The Good News: A large IRA is a wonderful retirement asset.
The Bad News: Without careful planning, it can also become a surprisingly expensive tax problem—for you, your spouse, and eventually your children.
If you’ve spent 30 or 40 years contributing to your IRA or 401(k), you’ve probably done a lot of things right. You’ve saved consistently, invested patiently, and taken advantage of tax-deferred growth.
Now, with retirement approaching, you may have $1 million, $2 million, or more in retirement accounts.
Congratulations. But those deferred taxes have been growing, and you may be looking at some potential tax problems.
The IRS hasn’t collected its share yet.
While deferral can be a powerful advantage, the decisions you make in the years immediately before and after retirement may determine how much of that money you actually keep.
Five Issues Worth Understanding
Additionally, here are five issues worth understanding related to Tax problems with large IRAs. Your withdrawals could push you into higher tax brackets. Tax problems with large IRAs can arise.
1. Traditional IRA withdrawals are generally taxed as ordinary income.
Once you begin taking required minimum distributions (RMDs), you may have less control over your taxable income than you expected – and, of course, you don’t know what tax brackets will look like at that time.
For someone with a substantial IRA, those distributions can become significant—particularly when combined with Social Security, pensions, investment income, or other retirement resources.
The result? You could find yourself paying higher taxes in retirement than you anticipated.
2. Your Medicare Premiums Could Increase
Many retirees are surprised to learn that Medicare premiums are tied to income.
Larger IRA withdrawals, including RMDs and Roth conversions, can trigger income-related adjustments to Medicare Part B and Part D premiums.
Even more frustrating, Medicare generally looks at income from two years earlier – something that ‘blindsides’ a lot of people.
That means a financial decision made today can affect your Medicare costs down the road.
3. Waiting Until RMDs Begin May Limit Your Options
For individuals born between 1951 and 1959, RMDs generally begin at age 73. For those born in 1960 or later, the starting age is 75.
The years between leaving work and beginning required distributions can offer valuable opportunities to manage future taxes. Unfortunately, many investors overlook this period.
However, they focus on investment returns while missing opportunities to coordinate withdrawals, Roth conversions, Social Security, and sources of income. Additionally, investing without planning is like building a house without a blueprint – the result may not look so good.
4. Your Children Could Inherit a Tax Problem
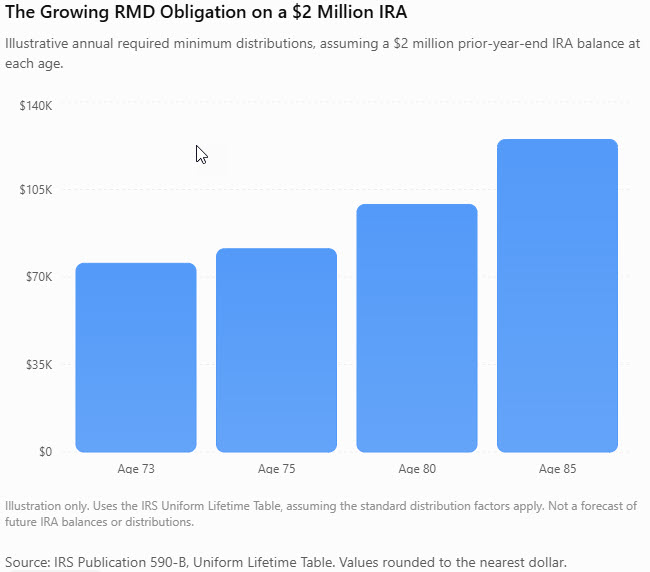
Leaving a substantial IRA to your children sounds like a generous gift. And it certainly can be.
But most adult children who inherit a traditional IRA must empty the account within 10 years.
Imagine your children inheriting a large IRA during their highest-earning years. Those inherited distributions could be added to already substantial salaries, creating an unwelcome tax burden.
A million-dollar inheritance may look considerably different after income taxes.
5. Your Estate Plan May Not Address the Tax Consequences
Having a living trust, updated will, and beneficiary designations are important. But estate planning and income-tax planning aren’t the same thing.
Who inherits your IRA, how beneficiaries are designated, and when distributions occur can materially affect the after-tax value of your legacy. A well-intended inheritance isn’t necessarily a tax-efficient inheritance. And, we’re not even talking about special needs beneficiaries – who will care for them, how will they manage? There’s a lot to consider and it’s too important to leave to uncle George who managed a gas station – and what if uncle George dies unexpectedly? But, I digress.
The Current Question: How Much of Your IRA Will You Actually Keep?
The objective isn’t to avoid taxes altogether. That’s generally unrealistic. It’s to understand where unnecessary taxes might arise and whether better coordination could help.
For households approaching retirement with substantial IRAs, investment management is only part of the picture. Retirement income, taxes, Medicare, and estate planning should work together.
A large IRA deserves a plan that’s every bit as thoughtful as the one that helped you accumulate it. Education comes first.
Begin with this Free Report: Retiring With a Big IRA?
If you’re approaching retirement with $1 million or more in retirement and investment assets, our complimentary report, Retiring With a Big IRA?, is a useful place to start.
It examines the often-overlooked tax pitfalls facing IRA owners and their heirs—and the planning considerations that deserve attention before important decisions become difficult to reverse.
[Download Your Free Report: Retiring With a Big IRA?]
And, or course, I’m here to help with independent, fiduciary financial planning for individuals and families locally in Simi Valley, Moorpark, Thousand Oaks, and surrounding Ventura County communities. Not local and still want help? We can do it all online, too – but, you probably already knew that.
This article is educational and is not individualized tax, legal, or investment advice. Rules and appropriate strategies depend on individual circumstances.
If you’d like some help, tell me your priorities. This will give us something to talk about.
Jim