Generated by All in One SEO Pro v5.0.1.1, this is an llms-full.txt file, used by LLMs to index the site.
# The Independent Financial Group
Retirement Planning and Wealth Management Solutions
## Posts
### [Blog](https://indfin.com/jim-blog/)
**Published:** October 28, 2014
**Author:** Jim Lorenzen
---
### [Don't Need a Financial Advisor?](https://indfin.com/dont-need-a-financial-advisor/)
**Published:** September 9, 2026
**Author:** Jim Lorenzen
**Excerpt:** Maybe having an independent fiduciary financial advisor is worth having anyway!
**Content:**
## Let’s begin with this
What about when you’re no longer around for your spouse? Who will step in to guide your spouse through the maze of the financial marketplace?
More importantly, a financial advisor can help keep your spouse from getting into trouble by falling for a good story.
After 30+ years as a financial advisor, I’ve witnessed enough mistakes (see my personal story below) including golfers checking their phones for stock moves on the course. It never dawns on them why Warren Buffett never has followed the stock market. Investing isn’t gambling, though many confuse the two.
That golfer wouldn’t be a good fit for most independent professionals who value smart clients. Back to taking care of your spouse and preparing for contingencies that matter.
One thing worth remembering: family members, friends, golf partners, and hairdressers are not held to a legal fiduciary standard. They aren’t regulated and likely lack the requisite knowledge or experience. This distinction matters when you consider who should guide your money.
Ask yourself: would you trust them to advise on your own life savings? Would anyone you know have the knowledge to do so confidently? Handing out free advice and taking responsibility for advice are very different things. In practice, a qualified financial advisor offers accountability and documented guidance.
Who would be best placed to choose your spouse’s advisor? You or your spouse? If it’s you, you’d better do it now – you can’t after you’re gone.
## Why an independent advisor matters
- **Objective stewardship:** Free from the biases that can accompany family dynamics or business relationships, an independent advisor prioritizes your goals and values.
- **Comprehensive coordination**: Independent advisors align legal documents, tax strategies, insurance needs, and investment decisions to create a coordinated and cohesive plan.
- **Continuity of care**: In the event of illness, incapacity, or death, an independent advisor can provide a clear, actionable roadmap for executors, heirs, and caregivers.
- **Reduced burden on your spouse:** A well-structured plan minimizes decision fatigue and ambiguity during difficult times – and reduce stress, as well.
## Key areas of focus for your spouse
- **Guardianship and succession**: Clear directives ensure that dependent family members are cared for according to your wishes.
- **Financial protection**: Adequate life and disability coverage, along with liquidity strategies, help cover ongoing expenses and obligations.
- **Estate and succession planning:** An independent advisor can help provide a thoughtful approach to coordinating other professionals with regard to wills, trusts, and tax considerations preserves wealth and minimizes conflicts.
- **Retirement and income continuity:** A plan for preserving income streams and essential spending helps sustain a secure lifestyle.
## How an independent advisor adds value
- **Fiduciary standard**: An independent registered investment advisor operates under a formal legal duty to act in your best interest, reducing conflicts of interest.
- **Personalization:** Strategies are tailored to your family’s unique situation, values, and financial realities.
- **Proactive planning**: They anticipate potential challenges and implement preventive measures rather than reacting after the fact. Some decisions regarding Social Security, tax planning for Roth conversions and IRMAA triggers regarding Medicare can often be irreversible. Investment decisions are made according to a formal written plan designed to meet current needs as well as long-term objectives.
- **Accessibility and clarity**: Complex concepts are explained in accessible terms, with documented decisions and timelines. The plan is kept current daily with a regular review schedule.
## Choosing the right advisor
- **Verify independence:** Confirm that the advisor does not have competing proprietary products that could bias recommendations.
- **Credentials and experience**: Look for fiduciary credentials, relevant certifications, and check the advisor’s background.
- **Transparent fees:** Seek clear, ongoing fee structures with no hidden charges.
- **The Big One** – Avoiding unregulated scam artists. There’s one thing all the scammers seem to have in common**: The lack of an independent custodian.** It’s one thing to pay a fee to an advisor – it’s something else entirely to write a check transferring your life savings to the advisor’s business account for him/her to invest for you. That’s a no-no. A legitimate advisor will never take possession of your funds.
## Practical steps to begin
How to begin working with a financial advisor.
1. [Inventory assets, liabilities, and ongoing obligations to understand the financial landscape.](https://indfin.com/wp-content/uploads/2026/08/IFG-Financial-Fitness-Checklist.pdf)
2. Identify primary and contingent guardianship needs and contingencies.
3. Draft or update essential documents: wills, trusts, durable powers of attorney, and healthcare directives.
4. Establish a communication plan for your spouse, executor, and key advisors.
5. [Schedule your first meeting](https://indfin.com/getting-started/)
6. [Begin planning](https://indfin.com/wp-content/uploads/2014/09/i110_First-Meeting-Agenda-2.pdf)
7. Schedule regular reviews to adapt the plan as circumstances change.
## Closing perspective
An independent advisor serves as a steady guardian of your spouse’s financial security and well-being when you are no longer around.
**Don’t wait. [Getting ducks lined-up is just the beginning](https://indfin.com/getting-started/).** Ideally, you both should have several years of the planning and review process under your belts long before your spouse is doing it all alone. When the time comes, your spouse will already know the drill – and what to avoid.
Through disciplined planning, clear documentation, and ongoing stewardship – they help ensure that your spouse is protected, informed, and capable of making informed decisions in your absence. A spouse who’s been through it all ahead of time isn’t likely to make the same mistakes others have made.
Ever watch “*American Greed*“? My dad once said, “If you think education is expensive, try ignorance.”
Jim
**My personal (short) story:**
My wife’s former husband passed away from cancer leaving her a substantial life insurance policy. He had handled everything and now she was left with a home and money to manage. She interviewed an independent advisor but felt more comfortable working with a big-name company. Unfortunately, she didn’t realize the independent advisor was the one who had access to the entire marketplace and had no production requirements to keep his desk at the firm, while the big-name firm’s advisor had different priorities.
The big-name firm’s advisor saw her coming, and placed 25% of her entire financial assets in a limited partnership and the rest in other high-commission products. In short, the advisor generated in excess of $90,000 worth of commissions in 90 days and provided no plan or guidance on management, or even on her spending habits. By the time I’d met her the damage had been done.
That was almost 30 years ago. If her former husband had been working with a independent fiduciary advisor to formulate and long-term plan and had her involved in a regular review process, the transition would have been seamless and she would most likely ended-up in a far better financial position.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [When to Claim Social Security? Here's a Guide!](https://indfin.com/when-to-claim-social-security-heres-a-guide/)
**Published:** August 19, 2026
**Author:** Jim Lorenzen
**Excerpt:** The Decision Is Bigger Than Age 62, 67, or 70.
**Content:**
Deciding when to Claim social security may be one of the most important retirement decisions you make. It is also one of the easiest to oversimplify.
The question is rarely just, **“Should I claim Social Security at 62, 67, or 70?”** The better question is:
However, when should I Claim social security based on my income needs, taxes, life expectancy, spouse, and overall retirement plan?
That is the Social Security elephant in the room.
**How Does Social Security Work?**
Social Security provides benefits to retired workers, certain spouses and dependents, disabled individuals, and survivors of deceased workers.
For retirees, benefits can generally begin as early as age 62. But claiming early permanently reduces your monthly benefit.
For someone born in 1960 or later:
- **Age 62:** approximately 70% of the full retirement benefit
- **Age 67:** 100% of the full retirement benefit
- **Age 70:** approximately 124% of the full retirement benefit
There is no additional benefit for delaying beyond age 70.
Suppose Tom is entitled to $3,000 per month at his full retirement age of 67. Roughly speaking, claiming at 62 could reduce that benefit to about $2,100. Waiting until age 70 could increase it to approximately $3,720.
That is a meaningful difference. But bigger is not automatically better.
**Should You claim Social Security at 62 or Wait?**
This is where retirement planning gets more interesting.
Someone who claims at 62 receives smaller checks but collects them for more years. Someone who waits receives fewer checks initially, but larger checks for the rest of his or her life.
A common way to compare the choices is with a **Social Security break-even age**.
Generally, the break-even point between claiming at 62 and waiting until full retirement age is somewhere around the late 70s. Comparing age 67 with age 70 often produces a break-even point in the early 80s.
But break-even analysis has limitations.
It does not automatically account for:
- Your health and longevity
- Your spouse’s Social Security benefit
- Survivor benefits
- Other retirement income
- IRA or 401(k) withdrawals
- Roth conversions
- Taxes on Social Security
- Medicare premiums
- Whether you need the money now
Retirement planning is a bit like golf: knowing the yardage matters, but it does not tell you which club to hit.
**Is It *Always* Better to Wait Until Age 70?**
No.
Delaying Social Security can be attractive, particularly for healthy retirees who expect to live a long time or for the higher-earning spouse in a married couple.
But claiming earlier may make sense if you need income, have health concerns, want to preserve other assets, or have circumstances that make waiting less valuable.
The mistake is assuming there is one “best age” for everyone. There isn’t.
**How Do Taxes Affect Social Security?**
Social Security should not be considered separately from the rest of your retirement income.
Your claiming decision can affect how much you withdraw from retirement accounts, when you recognize taxable income, whether Roth conversions make sense, and potentially what you pay for Medicare.
That is why a good Social Security strategy is usually part of a broader retirement-income and tax plan—not a decision made in isolation.
**So, When Should You File for Social Security?**
Before filing, ask yourself:
**How does this decision affect my lifetime income, my spouse, my taxes, and the rest of my retirement plan?**
Those questions matter far more than simply choosing between 62, 67, and 70.
To make the decision easier, check out **“The Social Security Elephant in the Room,”** a practical Social Security claiming guide that walks through the major considerations and includes a **simple decision flowchart you can complete in about five minutes.**
It will not magically predict how long you will live—if it could, I would probably charge considerably more than zero for it. But it can help you identify the questions worth answering **before** you make a Social Security decision that may affect your income for the rest of your life.
**Sign-up for the IFG newsletter** (if you don’t find it helpful, you can unsubscribe instantly at any time)**. When you sign-up you can [download the “The Social Security Elephant in the Room” guide](https://lp.constantcontactpages.com/sl/PTwNu4M/elephantintheroom), including the flow chart.**
**Get your [“Social Security Elephant in the Room” guide here!](https://lp.constantcontactpages.com/sl/PTwNu4M/elephantintheroom)**
You may also enjoy watching ***[“What Baby ](https://indfin.com/socialsecurity/)***Boomers***[ Need to Know”](https://indfin.com/socialsecurity/)***, as well. There’s also a lot of useful information on the [Social Security Administration’s website](http://www.ssa.gov/).
Enjoy!
Jim
Want help? Tell me [your priorities](https://indfin.com/retirement-priority-planning-review/), then [schedule an introductory call](https://go.oncehub.com/JimLorenzenCFP)!

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### ["Should I Rollover Your 401(k) to an IRA in Retirement?"](https://indfin.com/should-i-rollover-your-401k-to-an-ira-in-retirement/)
**Published:** August 10, 2026
**Author:** Jim Lorenzen
**Excerpt:** Years ago, those retiring didn’t ask many questions – rolling over their retirement accounts was virtually an automatic decision. Not anymore.
**Content:**
Common question today: Should I Roll Over My 401(k)? In fact, it is about more than where to put assets. Additionally, retirees are learning they have multiple options today. When approaching retirement, one major financial decision may be easy to overlook.
**Should I leave my money in my 401(k), or roll it over to an IRA?**
**Should I do a 401(k) rollover after retirement?**
**Should I leave my 401(k) with my old employer?**
**Should I just take a lump-sum distribution?**
For many retirees, including those who live in Simi Valley and Moorpark with high real estate prices, a 401(k) may represent one of their largest financial assets.
After 30 or 40 years of saving, the balance can easily reach hundreds of thousands—or several million—dollars. One million dollars ain’t what it used to be.
Simply asking ‘where’ to move the account isn’t enough now. During retirement, you’re in the decumulation stage of life – living off assets instead of simply accumulating. Now the decisions become more connected – and mistakes become more expensive.
So, should you roll?
**Rolling a 401(k) into an IRA can make sense, but it is not automatically the best choice. Before moving the money, compare your existing 401(k) with an IRA based on investment choices, costs, withdrawal flexibility, taxes, retirement income needs and several special rules you could lose by rolling over.**
Sounds complicated, I know. But an independent professional should have state-of-the-art software that can run an objective analysis for you.
**Why Retirees Roll Their 401(k)s Into IRAs**
The most common reasons tend to be **control** and **more choices**.
During your working years, your employer determines which investments are available inside the 401(k). That may be perfectly adequate while you are accumulating money. After all, during this stage taxes are deferred and you don’t have to worry withdrawals impacting tax brackets, Medicare premiums, or taxes on Social Security.
Retirement changes your job description
Now the portfolio may need to produce withdrawals, help manage taxes, maintain enough growth to keep up with inflation and coordinate with Social Security, pensions and other investments.
And, it’s often true that an IRA generally provides access to a much broader range of investments than the menu offered by a typical employer plan. It can also make it easier to coordinate or even consolidate several old retirement accounts under one investment and withdrawal strategy – that can simplify your life.
That flexibility can be valuable. But flexibility by itself is not a reason to roll over.
The better question is:
**What can the IRA accomplish that your current 401(k) cannot?**
If there isn’t a good answer, moving the account simply for the sake of moving it may accomplish very little.
**Should I leave my 401(k) with my old employer**
When Leaving Money in Your 401(k) May Be Better – Some 401(k) plans are excellent.
They may offer very low-cost institutional investments, attractive fixed-income or stable-value choices, convenient administration and other benefits that may be difficult to duplicate elsewhere. Maybe. But, today professionals have access to all these. In some cases the cost may be less; but even where it’s the same or more the question is what value you’re receiving for the difference in cost. An advisor who saves you thousands due to tax management may be worth more than the cost difference.
There are also several situations where moving too quickly can create problems.
For example, certain employees who separate from service during or after the year they turn 55 may qualify for an exception to the 10% additional tax on withdrawals from that employer’s retirement plan. That exception generally does not transfer with the money simply because you rolled the account into an IRA.
This can be especially important for someone retiring in their late 50s who expects to use retirement-plan money before age 59½.
Employer stock deserves attention as well.
If your 401(k) contains significantly appreciated company stock, special **net unrealized appreciation**, or NUA, tax treatment may be available in certain circumstances. Rolling the shares into an IRA without evaluating that opportunity first can eliminate the ability to use the special treatment. A professional can help design an NUA strategy that will avoid the tax traps a simple rollover would create.
That would be a rather expensive way to discover that not all rollovers are created equal and that professional help may be worth more than a simplistic look at fees.
**Don’t Look at the 401(k) in Isolation**
This is where rollover decisions become more interesting for households approaching retirement.
Employer stock deserves attention as well.
If your 401(k) contains significantly appreciated company stock, special **net unrealized appreciation**, or NUA, tax treatment may be available in certain circumstances. Rolling the shares into an IRA without evaluating that opportunity first can eliminate the ability to use the special treatment. A professional can help design an NUA strategy that will avoid the tax traps a simple rollover would create.
That would be a rather expensive way to discover that not all rollovers are created equal and that professional help may be worth more than a simplistic look at fees.
**Don’t Look at the 401(k) in Isolation**
This is where rollover decisions become more interesting for households approaching retirement.
Suppose you retire with:
- $1.5 million in a 401(k)
- $400,000 in taxable investments
- Social Security benefits beginning in a few years
- A pension
- A paid-off or nearly paid-off home
The question isn’t merely whether the IRA offers better investments. The real question is how that $1.5 million fits into your **retirement income and tax plan**.
- Should some withdrawals come from taxable investments first?
- Could Roth conversions make sense during the lower-income years immediately after retirement?
- How much should remain invested for long-term growth?
- How will future taxable retirement distributions interact with Social Security taxation and Medicare premiums?
Those decisions are connected. Treating the rollover as an isolated investment decision can miss the bigger opportunity.
**Should I Roll Over My Entire 401(k)?**
Not necessarily. Retirement decisions don’t always have to be all-or-nothing.
Depending on the rules of your employer plan, there may be circumstances where keeping part of the money in the plan while moving another portion elsewhere makes sense.
Your 401(k) may also contain different types of money—traditional pretax contributions, Roth contributions, employer contributions and possibly after-tax contributions.
Those distinctions matter.
IRS rules can allow pretax and after-tax portions of certain distributions to be directed to different destinations. For example, qualifying after-tax amounts may potentially be directed to a Roth IRA while pretax amounts go to a traditional IRA or another eligible retirement plan.
This is one reason I generally prefer to understand **what is actually inside the 401(k)** before deciding where it should go.
**If You Do Roll Over, Use the Right Method**
If the decision is made to move the account, a **direct rollover** is generally the cleanest approach. With a direct rollover, the retirement-plan assets are sent directly to the receiving IRA or retirement plan.
If instead the distribution is paid directly to you, an employer retirement plan generally must withhold 20% for federal income taxes. You normally have 60 days to complete an eligible rollover, and replacing the amount withheld may be necessary if you want the entire distribution treated as rolled over.
Why complicate things? There is rarely a prize for making this part more complicated than necessary.
**Five Questions to Ask Before Rolling Over a 401(k)**
Before moving the account, I would want answers to these questions:
1. What am I giving up by leaving my existing 401(k)?
2. What will the IRA allow me to do that the 401(k) doesn’t?
3. What will my total investment and advisory costs be under each choice?
4. Will I need access to this money during the first several years of retirement?
5. How does the rollover fit with my tax, Roth-conversion and retirement-income strategy?
For larger accounts, I would add a sixth:
**Is there employer stock, after-tax money or another special provision that needs to be evaluated before anything moves?**
That’s often where the expensive mistakes hide.
**Before you authorize the rollover**
- Do you own company stock?
- Are you retiring before 59½?
- Does the account contain after-tax contributions?
**So, Should You Roll Over Your 401(k) When You Retire?**
For many people, an IRA provides greater flexibility and can make it easier to coordinate investments, withdrawals and tax planning.
For others, leaving some or all of the money in the 401(k) is the better choice.
**The decision should come before the rollover—not afterward.**
Ready, fire, aim rarely leads to good outcomes. So, whether you’re someone local in Simi Valley or Moorpark – or anywhere else – who is approaching or in retirement and have accumulated a substantial 401(k), don’t begin by asking, “Where should I move the money?”
Begin with:
**“What do I need this money to do for me during retirement?”**
Once you answer that, the rollover decision usually becomes much clearer.
**Not Sure Which Direction Makes Sense?**
I’ve created **The 401(k) Rollover Decision Tree** to help you work through the major questions before deciding whether to leave your retirement savings in your employer’s plan or move them to an IRA.
It won’t make the decision for you. It will help you identify the issues worth looking at **before you make an irreversible or potentially costly move.**
**[Download The 401(k) Rollover Decision Tree ](https://lp.constantcontactpages.com/sl/dFjnEK7/RolloverDecisionTree)**
I hope you find it helpful. If I can be of help, [let me know](https://indfin.com/getting-started/)!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Rollovers
**Tags:** 401(k) rollovers, 401k decisions, retirement decisions, Retirement Planning
---
### [Where Should I Put My Money Before Retirement?](https://indfin.com/where-should-i-put-my-money-before-retirement/)
**Published:** July 21, 2026
**Author:** Jim Lorenzen
**Excerpt:** A Guide for Investors With $500,000 or More
**Content:**
Getting ready to retire? If you have $500,000 or more to invest, you may be asking a deceptively simple question:
**Where should I put my money?**
You may be wondering if it’s enough. At this stage, the answer is rarely one account, one investment or one magic product; but each dollar you add helps. But, as retirement gets closer, you’re probably also wondering where that NEXT dollar should go.
Should you stick it in your 401(k) knowing you’ll soon be taking taxable distributions? Should you put it in savings? Maybe you’re concerned about growth and feel you need a higher return!
Retirement planning is not a matter of finding the hottest investment or the highest interest rate. It is about deciding what each dollar needs to do—and when you may need it. That changes the conversation.
**Getting Your Ducks Lined Up: Start With the Job, Not the Investment**
Before choosing where to invest, think about what the money is supposed to accomplish.
Some money may need to cover expenses during the first few years of retirement. Some may be earmarked for emergencies, taxes, home repairs or health care. Other dollars may not be needed for ten or twenty years and can remain invested for growth.
Fear can be just as dangerous as recklessness. Putting all your eggs in one basket – even if it’s cash – can create problems that (like glaucoma) will likely come back to haunt you. Having the same number of pictures of presidents means little if you later can buy only half as much – money is worth only what it buys. Likewise, investing everything aggressively may produce higher long-term returns, but it can also expose you to uncomfortable losses just when withdrawals are beginning. Write this on your mirror: diversification is good.
The right approach usually involves balancing near-term stability with long-term growth.
**Retirement Changes the Rules**
During your working years, market declines may seem unpleasant, but you may want to change the way you think. You’re accumulating shares of ownership ‘on sale’. Wouldn’t you rather buy at low prices than buying high? When prices are down, the same dollar buys more – it’s about ***accumulating*** wealth, not gambling your way there.
Once retirement begins, withdrawals during market downturns can damage long-term plans. Selling investments after a sharp decline may leave fewer assets available to recover when markets improve.
This is why the years immediately before and after retirement deserve special attention. A portfolio that worked well while you were accumulating money may not be designed for distributing it.
The goal is not to eliminate risk. That is impossible. The goal is to avoid taking risks that are unnecessary or poorly timed.
**Do Not Ignore Taxes**
*Where* you hold your money can be just as important as what you own.
Many investors reach retirement with most of their savings inside traditional IRAs and 401(k)s. Those accounts offer valuable tax deferral, but withdrawals are generally taxable.
Large distributions can affect more than your federal tax bill. They may also increase the taxable portion of Social Security and raise Medicare premiums.
Meanwhile, taxable accounts, Roth accounts and cash reserves may offer different planning opportunities. The order in which you use these accounts can influence how long your money lasts and how much you keep after taxes.
This is why investment decisions should not be made separately from tax planning.
**Avoid the “One Big Move”**
People approaching retirement are often tempted to make one dramatic change: move everything to cash, buy one income product or transfer the entire portfolio into a new growth opportunity – This is seldom (okay, never) a good idea.
That may provide emotional relief, but retirement decisions are usually better handled as a series of coordinated steps.
You may need to address several questions (you’ve heard all this before, I’m sure):
- How much should remain available for near-term spending?
- How much market risk can you reasonably accept?
- Should part of your portfolio be repositioned for income?
- Are Roth conversions worth considering?
- Which account should fund your first retirement withdrawals?
- How will Social Security and required distributions affect the plan?
These questions are connected. Pulling one lever can move several others.
**Give Each Dollar a Purpose**
A practical retirement strategy starts by assigning priorities. Your next dollar might be best used to strengthen your emergency reserves, reduce debt, increase retirement contributions, fund a Roth account, build taxable savings or address an insurance need.
There is no universal answer because the right destination depends on your taxes, time horizon, income needs and overall financial position.
Think of it like planning a golf shot. The correct club depends on the distance, the lie, the hazards and where you want the next shot to be. Reaching for the driver every time is not a strategy. It is usually how the afternoon gets expensive.
**Get the Free Decision Tree**
To help simplify the process, download the free report:
**[Where Should My Next Dollar Go?](https://lp.constantcontactpages.com/sl/e9yrfgX/wheretoputmymoney)**
This practical decision tree is designed to help you evaluate where additional savings may have the greatest impact before retirement.
It will not replace a complete retirement plan, but it can help you ask better questions, avoid common missteps and make more deliberate decisions with the money you have worked hard to accumulate.
Before deciding where to put your money, make sure you know what you need that money to accomplish. [This guide](https://lp.constantcontactpages.com/sl/e9yrfgX/wheretoputmymoney) will help you decide where your next dollar should go.
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** Financial planning, investment decisions, Investment Strategy, retirement decisions
---
### [The Spousal IRA Rollover Mistake That Triggered a $100,000 Penalty.](https://indfin.com/the-spousal-ira-rollover-mistake-that-triggered-a-100000-penalty/)
**Published:** July 14, 2026
**Author:** Jim Lorenzen
**Excerpt:** Lucy inherited more than $2.5 million in IRA assets from her late husband, Bill. As a surviving spouse, she had several choices for handling the account.
**Content:**
**She chose to roll the full amount into an IRA in her own name.**
Not long afterward, Lucy withdrew $977,888. She reported the distribution as taxable income but did not include the 10% early-withdrawal penalty because she believed she still qualified for the exception available to beneficiaries. That was a rollover mistake.
**The IRS saw it differently.**
The case eventually reached the U.S. Tax Court, where her argument was rejected. The court explained:
*“Once \[Lucy\] chose to roll the funds over into her own IRA, she lost the ability to qualify for the exception from the 10-percent additional tax on early distributions. The funds became petitioner’s own and were no longer from her deceased husband’s IRA once petitioner rolled them over into her own IRA.”*
The result was a penalty of nearly $100,000, on top of the income tax she already owed. Big rollover mistake. It’s only one of [a number of decisions](https://indfin.com/retirementplanning/) retirees, and those planning for retirement, face.
**The problem was not necessarily the rollover itself.** It was the timing of the rollover and the loss of planning flexibility that came with it.
Surviving spouses have special options that other IRA beneficiaries do not. Those choices can affect access to the money, required distributions, future tax bills and whether withdrawals before age 59½ are subject to an additional penalty.
Once the wrong move is made, there may be no practical do-over.
This is where the “99% rule” may help bring some much-needed clarity. It is not a formal IRS rule, but rather a planning concept that can help surviving spouses think more carefully before moving an inherited IRA.
**Do you know the 99% rule?** You can [learn more about it here](https://indfin.com/wp-content/uploads/2026/07/The-99-Rule-for-Spousal-Beneficiairies-of-IRAs-2.pdf).
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Retirement, Rollovers
**Tags:** ira beneficiaries, ira rollovers, IRAs, spousal ira
---
### [Retiring With a Large IRA Comes with Tax Traps](https://indfin.com/retiring-with-a-large-ira-comes-with-tax-traps/)
**Published:** July 2, 2026
**Author:** Jim Lorenzen
**Excerpt:** You’ve worked and saved all your life and have built a large retirement nest-egg. And if inflation hasn’t been bad enough—a million dollars isn’t what it used to be— you now face other issues - tax traps!
**Content:**
**The good news:** You have a large 401(k) or IRA.
**The bad news:** You have a large 401(k) or IRA.
Retiring with a large IRA is a good problem, but it is still a problem and careful planning now is more complicated, making it even more important than it’s ever been before.
A large traditional IRA or 401(k) balance represents decades of discipline, and it’s proof that you did a lot of things right: you saved consistently, invested through market cycles, deferred gratification, and resisted the urge to treat every bonus like a personal stimulus package. You kept socking it away during market highs and lows. I wrote about retirement tax planning between work and RMDs. You can see that one [here](https://indfin.com/retirement-tax-planning-between-work-and-rmds/).
Life was simple during the working years– just keep saving and accumulating.
But retirement changes things. The decumulation stage is different – Uncle Sam is now at your door, and he comes with a lot of potential traps that can come as unwelcome surprises.
You’ll learn more about this and other important topics when you sign-up for my newsletter. Sign up today and you’ll [receive a copy of my special 10-page report](https://lp.constantcontactpages.com/sl/dFPRssD/BigIRATraps) on the tax traps that await those who retire with large IRAs. I think you’ll find this one worthwhile. Naturally, you can unsubscribe from my monthly letter at any time.
Enjoy!
Jim
You can also learn more about [how tax planning changes during retirement here!](https://lp.constantcontactpages.com/sl/dFPRssD/BigIRATraps)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Retirement, Retirement Income, Taxes
**Tags:** retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy
---
### [What Happens if the Market Falls Just After I Retire?](https://indfin.com/what-happens-if-the-market-falls-just-after-i-retire/)
**Published:** June 22, 2026
**Author:** Jim Lorenzen
**Excerpt:** A market drop right after retirement can be stressful, but it does not have to derail your plan. The key is managing withdrawals, reserves, taxes, and portfolio risk before trouble starts.
**Content:**
A market decline right after retirement can feel like terrible timing. You spend decades saving, finally step away from work, and then the market decides to throw a tantrum. Not ideal.
I recently read that by 2030, *every* baby boomer will be 65 or older. Health care expenses will continue rising along with many other age-related expenses. Nevertheless, a market drop early in retirement is not automatically a disaster. The real issue is whether your income plan is prepared for it.
When you are still working, market declines are uncomfortable but often manageable. In fact, you’re likely still contributing to your 401(k). Market dips mean you’re buying cheaper positions. And, you are not usually selling investments to pay the bills.
Retirement changes the math.
Once you start taking withdrawals – the decumulation phase – a market decline can become more serious because you may be selling investments when prices are down. That combination — falling markets plus portfolio withdrawals — is called sequence-of-returns risk.
**Why early retirement market declines matter**
Sequence-of-returns risk means *the order* of investment returns matters, not just the average return over time. And, it matters most when you’re in the withdrawal stage.
Two retirees can earn the same average return over a 25-year retirement, but if one experiences poor returns in the first few years while taking withdrawals, that retiree may face a much harder road because withdrawals taken during a downturn leave fewer dollars invested for the eventual recovery.
Imagine starting your golf round by hitting two balls into the water. You can still finish the round, but you’re having to make up for lost strokes first. Retirement works the same way. A rough start does not mean the plan is ruined, but it does mean the next moves matter. Unfortunately, fear usually leads to bad decisions.
There’s more to know about this risk. You can sign-up for my newsletter (which you can cancel at any time) and [receive a free report here](https://lp.constantcontactpages.com/sl/FpsJ2C9/sequenceofreturns) that discusses this issue in more detail.
**The biggest mistake: selling in panic**
When the market falls, the natural response is to “do something.”
Locking in losses isn’t a strategy, it’s a reaction. For retirees, the better question is not, “How do I avoid every downturn?” Bad question. You could put your money in a coffee can; but, then you’d lose purchasing power (inflation) – a sure loser.
The better question is:
**How do I manage risk? – avoid being forced to sell long-term investments at the wrong time?**
That is where planning and wealth management comes in.
**A retirement portfolio needs more than growth**
*The investment strategy that helped you build wealth may not be the same strategy needed to distribute wealth.*
After retirement, the portfolio has several jobs:
- Provide income
- Manage market risk
- Keep up with inflation
- Maintain flexibility
- Support tax-efficient withdrawals
- Preserve assets for later life or heirs
That requires a different kind of design. It’s trickier, too, because there are tax traps that can jump up and lead to bad (expensive) surprises.
A retiree should usually have some assets intended for near-term income needs, some for stability, and some for long-term growth.
*The goal is not to eliminate risk. The goal is to avoid depending on the stock market to behave nicely every single year. Markets are many things. Polite is not always one of them.*
**Cash reserves can buy time**
One way to reduce pressure during a downturn is to keep a reasonable reserve of cash or lower-volatility investments for near-term spending.
This does not mean stuffing years of expenses under the mattress. It means having enough accessible money so that routine withdrawals do not automatically require selling stocks during a bad market.
The right amount depends on Social Security, pensions, spending needs, portfolio size, risk tolerance, taxes, and other resources. Simple, huh?
For example, a retiree with strong Social Security income and modest withdrawals may need less in reserve than someone retiring early with high expenses and no pension.
Cash management is underrated. It’s not designed to produce exciting returns. Its job is to provide breathing room.
**Flexible spending helps protect the plan**
A retirement income plan should also identify which expenses are essential and which are flexible.
Essential expenses include housing, food, insurance, taxes, health care, and basic living costs. Flexible expenses may include travel, gifts, home improvements, new cars, or large discretionary purchases. A good plan prioritizes all these and automatically matches these various goals, in priority order, to your available resources with automatic updates.
That does not mean retirement has to become joyless; but sometimes peace of mind ranks higher.
**What should you do before retiring?**
The best time to prepare for a market decline is before it happens. Ready, fire, aim rarely works.
Before retiring, ask:
- How much will I need from the portfolio each year?
- What happens if the market drops 20% in my first two years?
- Which accounts will withdrawals come from?
- How much cash or short-term reserve should I keep?
- What expenses could I reduce temporarily?
- How will Social Security timing affect withdrawals?
- How will taxes influence the withdrawal strategy?
- When should the portfolio be rebalanced?
If your retirement plan cannot answer those questions, it may not be a plan yet. It may just be a spreadsheet with good intentions.
**Final thought**
A market decline just after retirement is one of the biggest risks retirees face, but it does not have to derail the plan.
The key is preparation: a thoughtful withdrawal strategy, appropriate reserves, tax-aware decisions, flexible spending, and a portfolio built for retirement income rather than just accumulation.
You cannot control when the market falls. But you can control whether your retirement income plan is ready for it.
That is the difference between reacting to every market headline and managing retirement with a steady hand.
**Typical Questions**
- What happens if the market drops right after I retire?
- Why are early retirement market losses so dangerous?
- What is sequence-of-returns risk?
- Should retirees sell stocks during a market downturn?
- How much cash should retirees keep for market declines?
- How can flexible spending protect a retirement plan?
- Can a market downturn create tax-planning opportunities?
- How should a retirement portfolio be built before retirement?
Those are all questions planning is intended to answer. [Don’t forget my free report](https://lp.constantcontactpages.com/sl/FpsJ2C9/sequenceofreturns). I think you’ll find it worthwhile.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Retirement Tax Planning Between Work and RMDs](https://indfin.com/retirement-tax-planning-between-work-and-rmds/)
**Published:** June 12, 2026
**Author:** Jim Lorenzen
**Excerpt:** For many retirees, the most valuable tax-planning years begin after the paychecks stop but before required minimum distributions begin.
**Content:**
This period is often overlooked, but for households with sizable IRAs, 401(k)s, brokerage accounts, and future Social Security benefits, can be one of the most important retirement tax planning windows of the entire retirement period.
Most people think retirement tax planning is mainly about April 15. Not true. Think of it as the quiet stretch between two busy intersections.
You may have retired from full-time work, so your taxable income may be lower than it has been in years. But required minimum distributions, Social Security, Medicare premiums, investment income, and future tax law changes may be lurking just down the road.
With proper planning, the retirement tax planning window can create opportunities. Ignored, it can close before you realize it was even open – and the results can be costly, maybe even irrevocable.
**What is the retirement tax window?**
The retirement tax window is the period after you stop working, or significantly reduce your earned income, *but before* required minimum distributions become substantial.
For many retirees, this may occur between ages 62 and 73. For others, the window may be shorter or longer depending on work, pensions, Social Security timing, investment income, and account balances.
During these years, taxable income may temporarily drop. That can create room to make strategic moves before income rises again later due to required minimum distributions (more on that in a minute) – and, of course, who knows what tax brackets will look like then?
This is especially important for retirees with large traditional IRA or 401(k) balances. Those accounts have not escaped taxes. They have only postponed them. Your statement may quote an account balance, but it’s not all your money. Eventually, Uncle Sam would like his turn at the buffet.
**Why required minimum distributions matter**
Required minimum distributions, often called RMDs, are mandatory withdrawals from many retirement accounts. Once they begin, they can increase taxable income whether you need the money or not.
That can create a domino effect.
Higher taxable income may increase federal taxes, of course; but, it may also cause more of your Social Security to be taxable. It may increase Medicare premiums. It may also reduce flexibility for future tax planning.
The larger your traditional retirement account balance, the more important this becomes. A retiree with a small IRA may not feel much pressure from RMDs. But, a retiree with $1 million, $2 million, or more in tax-deferred accounts may have a very different experience.
This is why waiting until RMDs begin may be like waiting until the ball is in the water before planning course management.
**Roth conversions: useful, but not automatic**
One of the most common strategies during this tax window is a Roth conversion.
A Roth conversion moves money from a traditional IRA or retirement account into a Roth IRA. The converted amount is generally taxable in the year of conversion. In exchange, future qualified Roth withdrawals may be tax-free, and Roth IRAs are not subject to lifetime RMDs for the original owner.
That can be powerful. But it is not automatically wise. The question is not simply, “Should I do a Roth conversion?”
The better question is: **How much should I convert this year, and what other costs could that conversion trigger?**
A thoughtful Roth conversion strategy looks at tax brackets, Medicare premiums, Social Security timing, future RMDs, cash flow needs, estate goals, and whether taxes can be paid from non-retirement assets.
Converting too little may waste a planning opportunity. Converting too much may create a tax bill that does not make sense. Note: IFG Newsletter subscribers can access a handy [Roth Conversion Decision Guide here](https://lp.constantcontactpages.com/sl/FlZLVgV).
This is where tax planning gets more like golf than checkers. Club selection matters.
**Capital gains also need attention**
Many retirees also have taxable brokerage accounts with appreciated investments. These accounts create their own planning opportunities.
In lower-income retirement years, it may make sense to harvest some capital gains, rebalance concentrated positions, or reposition investments more tax-efficiently. In some cases, capital gains may be taxed at a favorable rate, depending on total income.
But capital gains do not exist in a vacuum. Selling appreciated investments may affect taxable income, Medicare premiums, and the taxation of Social Security. It can also change future income from dividends and interest.
The right question is not, “Should we sell this investment?”
The right question is, “What does this sale do to the whole retirement income plan?”
**Social Security timing is an important part of the tax plan**
Social Security is often treated as a separate decision. It should not be.
Claiming Social Security early may reduce the amount you need to withdraw from investments in the short term. Delaying Social Security may increase future monthly benefits, especially for the higher-earning spouse. But delaying may also require larger portfolio withdrawals during the bridge years.
Those withdrawals may create taxable income. That taxable income may affect Roth conversion opportunities, capital gains planning, or Medicare premiums.
In other words, Social Security timing is not just an income decision. It is also a tax-planning decision.
For married couples, the survivor benefit adds another layer. The decision should not focus only on the first spouse to pass away. It should also consider the income picture for the surviving spouse, who may later file as a single taxpayer with less favorable (read: higher) tax brackets.
Yeah, it’s an unpleasant topic, but ignoring it does not make it go away. Retirement planning is not always fun, but neither is pretending math took the day off.
The fun continues:
**Medicare premiums can surprise retirees**
Many retirees are surprised to learn that higher income can increase Medicare Part B and Part D premiums through IRMAA, the income-related monthly adjustment amount.
Here’s a time-bomb: Medicare premiums are often based on income from *two years* earlier. That means income decisions at age 63 can affect Medicare costs at age 65.
This does not mean retirees should avoid Roth conversions, capital gains, or other income-producing strategies. Sometimes paying more tax or even higher Medicare premiums in one year may still be worth it over the long run.
But it should be intentional, not accidental.
A good plan looks before crossing the income threshold.
**The goal is coordination**
The biggest retirement tax planning failure is treating Roth conversions, Social Security, capital gains, and Medicare premiums as separate decisions.
They are connected.
A Roth conversion may affect Medicare premiums. Social Security timing may affect portfolio withdrawals. Portfolio withdrawals may affect capital gains planning. RMDs may affect future tax brackets. One decision can change the next.
Is planning beginning to look better to you?
For retirees with $1 million or more in retirement savings, this coordination can be especially valuable. The issue is not just growing the portfolio. It is managing how money comes out, how it is taxed, and how the plan holds together over time.
**What should retirees do during this window?**
A useful retirement tax review should ask:
- What will taxable income look like this year?
- How much room exists in the current tax bracket?
- Should part of an IRA be converted to a Roth?
- Should appreciated investments be sold or rebalanced?
- When should Social Security begin?
- Could Medicare premiums be affected two years from now?
- What might future RMDs look like?
- How would the surviving spouse be taxed later?
These questions are not about predicting the future perfectly. Stuff happens. The questions are more about making better decisions with the information available today.
**Final thought**
The years after retirement and before RMDs can be some of the most valuable planning years of your financial life. The paycheck may have stopped, but the planning should not.
**Financial planning and wealth management are interconnected and an ongoing process. Like medical and dental maintenance, it’s continuous**.
For many retirees, this is the time to take a careful look at Roth conversions, Social Security timing, investment gains, Medicare premiums, and future withdrawals before the decisions become less flexible.
Retirement tax planning is not about finding one magic move. It is about coordinating several smart moves in the right order.
**Frequently Asked Questions About the Retirement Tax Window**
**What is the retirement tax window?**
The retirement tax window is the period after you stop working, or significantly reduce your earned income*, but before* required minimum distributions become substantial. For many retirees, this may happen between retirement and their early 70s. During this period, taxable income may be lower, which can create opportunities for Roth conversions, capital gains planning, and more tax-efficient retirement withdrawals.
**Should I do Roth conversions before RMDs begin?**
Roth conversions before RMDs may make sense if you are in a lower tax bracket after retirement and expect higher taxable income later. Converting part of a traditional IRA or 401(k) to a Roth IRA can reduce future RMDs and create more tax flexibility. However, the conversion itself is taxable, so the amount should be planned carefully. Having an analysis done should be a normal part of your financial planning and wealth management process. [This decision guide should help](https://lp.constantcontactpages.com/sl/FlZLVgV).
**Can Roth conversions increase Medicare premiums?**
Yes. Roth conversions can increase Medicare premiums if the added taxable income pushes you above an IRMAA threshold. IRMAA stands for income-related monthly adjustment amount, and it can increase Medicare Part B and Part D premiums. Because Medicare generally looks at income from *two years* earlier, Roth conversions before and during Medicare years should be coordinated with the rest of your retirement income plan.
**Should I delay Social Security to do Roth conversions?**
Delaying Social Security may create room for Roth conversions because taxable income may be lower before benefits begin. This can be useful for retirees who want to reduce future RMDs or build more tax-free income for later. However, delaying Social Security also means relying more heavily on portfolio withdrawals during the bridge years, so the decision should be reviewed in context.
**Are capital gains part of retirement tax planning?**
Yes. Capital gains are an important part of retirement tax planning, especially for retirees with taxable brokerage accounts. In lower-income retirement years, it may make sense to sell appreciated investments, rebalance a portfolio, or reset cost basis. But capital gains can also affect taxes, Medicare premiums, and the taxation of Social Security, so they should not be reviewed in isolation. Actually, *nothing* in your plan should be reviewed in isolation.
**How do RMDs affect Social Security taxes?**
RMDs can increase taxable income, which may cause more of your Social Security benefits to be taxed at the federal level. For retirees with large traditional IRA or 401(k) balances, future RMDs may push income higher than expected. Planning before RMDs begin can help manage that risk and may provide more control over taxable income later.
**How can I reduce future RMD taxes?**
Future RMD taxes may be reduced through strategies such as partial Roth conversions, tax-efficient withdrawals, qualified charitable distributions after age 70½, and careful account sequencing. The best approach depends on your income, tax bracket, account mix, charitable goals, Medicare premium exposure, and long-term retirement income plan.
**Who benefits most from retirement tax-window planning?**
Retirement tax-window planning may be especially valuable for retirees with large traditional IRAs, 401(k)s, taxable investment accounts, pensions, or delayed Social Security benefits. It can also help married couples concerned about survivor taxes, future RMDs, Medicare premiums, and leaving assets to heirs more tax-efficiently.
If you’d like some help, [tell me your priorities](https://indfin.com/retirement-priority-planning-review/). This will give us something to [talk about](https://indfin.com/retirement-priority-planning-review/).
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Roth conversions, Taxes
**Tags:** retirement decisions, Retirement Planning, Retirement Strategy, tax management, tax planning
---
### [Is $2 Million Enough to Retire Comfortably in California?](https://indfin.com/is-2-million-enough-to-retire-comfortably-in-california/)
**Published:** June 8, 2026
**Author:** Jim Lorenzen
**Excerpt:** A $2 million portfolio may be enough to retire comfortably in California, but the answer depends on spending, taxes, Social Security, Medicare, housing, and how withdrawals are managed.
**Content:**
**The short answer**: Maybe – the consultant’s fallback answer.
It can be enough to retire comfortably in California — but it depends heavily on your spending: how you live, where you live, how your money is taxed, and how long it needs to last.
Two million dollars isn’t chump change; it’s a significant retirement portfolio. It can provide meaningful income, flexibility, and peace of mind. But California is not exactly the bargain aisle of retirement – surprise, I’m sure – and a portfolio that’s comfortable for one household may be strained in the one next door.
For many retirees age 62 and older, the real question isn’t, “Is $2 million enough?” The better question is:
***Can my $2 million portfolio, combined with Social Security and other income, support the lifestyle I want without creating unnecessary tax problems or running too much investment risk?***
Houses built without blueprints seldom turn out well. It should come as no surprise that planning for the financial future isn’t any different.
**How much income can a $2 million portfolio provide?**
A common starting point is to look at possible withdrawal rates.
For example, a $2 million portfolio could produce:
- **3% withdrawal rate:** $60,000 per year
- **3.5% withdrawal rate:** $70,000 per year
- **4% withdrawal rate:** $80,000 per year
That is *before* taxes and before considering Social Security, pensions, rental income, part-time work, or other sources of retirement income.
For a married couple with two Social Security benefits, the total retirement income picture may look quite different than the portfolio alone. A couple drawing $70,000 from investments and receiving another $50,000 to $70,000 from Social Security may have a very different retirement outlook than a single retiree relying almost entirely on portfolio withdrawals.
So, despite the financial media’s obsession for simple answers, the key is not choosing a magic withdrawal percentage. The key is understanding how all the pieces work together – and how Uncle Sam plays a role.
A retirement income plan should answer:
- How much do you need each month?
- Which accounts should income come from first?
- How much will be taxable?
- How will income change when Social Security starts?
- What happens when required minimum distributions begin?
- How will the plan respond to inflation, tax law and economic changes, market declines, or health care costs?
That is why “$2 million” is *only the beginning* of the conversation.
**Is $2 million enough to retire at 62 in California?**
Retiring at 62 is possible for some households with $2 million, but it requires more careful planning than retiring at 67 or 70.
Why? Because retiring at 62 likely means a longer retirement, fewer retirement contributions, earlier portfolio withdrawals, and a gap before Medicare begins at 65. It may also raise questions about when to claim Social Security.
Social Security retirement benefits can begin as early as age 62, but claiming early *permanently* reduces the monthly benefit – no do-overs. Waiting until full retirement age provides the full benefit, and delaying beyond full retirement age can increase the benefit up to age 70.
But, this doesn’t mean everyone should wait until 70. Health, family history, cash flow, survivor benefits, taxes, and portfolio withdrawals all matter. Did I mention planning is important? Anyway, for a 62-year-old retiree with a $2 million portfolio, Social Security timing should not be treated as a quick checkbox decision.
It is one of the largest financial decisions many retirees will ever make.
**California living costs can change the answer**
California retirement planning has an extra layer of complexity because living costs vary widely within the state.
A mortgage-free homeowner in Moorpark, Simi Valley, Thousand Oaks, or another inland community may have a very different situation than a retiree renting near the coast or carrying a large mortgage into retirement – not that Ventura County is inexpensive; but two households can both have $2 million and feel completely different financially.
Two households, the same age and income can have very different circumstances. Consider the difference between:
- A couple with no mortgage, modest property taxes, and reasonable spending
- A couple with a large mortgage, high travel expenses, and adult children needing help
- A single retiree renting in a high-cost area
- A household planning to relocate within California
- A household considering moving out of state later
Housing is often the swing factor.
If your home is paid off, $2 million may feel far more comfortable. If your monthly housing costs are high, that same $2 million may need to work much harder.
So, retirement rules of thumb can be misleading. They rarely account for real-life California expenses, especially housing, insurance, taxes, health care, and helping family. AI can mine the internet for information, but it isn’t to good at knowing what questions to ask – and often, that’s the missing key.
**Taxes matter more than many retirees expect**
Taxes can quietly change the retirement picture.
California does not tax Social Security benefits, which is helpful. But withdrawals from traditional IRAs, 401(k)s, pensions, and many other forms of retirement income may still be taxable. Federal taxes may also apply to Social Security, depending on your total income.
This becomes especially important for retirees with large tax-deferred accounts.
A household with $2 million mostly in a traditional IRA may not be in the same position as a household with $2 million spread among taxable accounts, Roth IRAs, and retirement accounts. And, even among taxable accounts, many hold investments that are highly inefficient from a tax standpoint.
The account mix – where and how assets are located – matters because every withdrawal may be treated differently.
For example:
- Traditional IRA and 401(k) withdrawals are generally taxable as ordinary income
- Roth IRA withdrawals may be tax-free if rules are met
- Taxable brokerage accounts may produce capital gains, dividends, and interest
- Social Security may be partly taxable at the federal level
- Required minimum distributions can increase taxable income later
- Many life insurance designs provide access to tax-free cash
This is where retirement income planning and tax planning meet. Sometimes they meet like two shopping carts in a crowded grocery aisle — awkwardly, unless someone is steering.
**Watch the Medicare premium trap**
For retirees age 62 and older, Medicare planning should begin before age 65.
Many retirees are surprised to learn that higher income can increase Medicare Part B and Part D premiums through IRMAA, the income-related monthly adjustment amount. IRMAA is generally based on income from *two years* earlier.
That means income decisions at 63 can affect Medicare premiums at 65. Income decisions at 64 can affect premiums at 66. It’s a tripwire that catches many retirees off-guard.
This does not mean retirees should avoid smart tax moves, such as Roth conversions, simply because of Medicare premiums. But it does mean the math should be coordinated.
A Roth conversion might reduce future required distributions, improve tax flexibility, and help heirs. But if the conversion pushes income over an IRMAA threshold, the retiree should know that before making the move.
The goal is not to avoid taxes at all costs. The goal is to avoid accidental costs.
**What could make $2 million comfortable?**
A $2 million retirement portfolio may be more likely to support a comfortable retirement if several of the following are true:
- You retire closer to full retirement age or later
- Your home is paid off or housing costs are manageable
- You have two Social Security benefits or a pension
- Your annual spending is reasonable relative to your assets
- Your investments are diversified
- You have a plan for withdrawals during market downturns
- You have tax flexibility across different account types
- You are not carrying major debt into retirement
- You have planned for health care and long-term care risks
In this situation, $2 million may provide a strong foundation.
It may allow for travel, family support, charitable giving, home improvements, and a comfortable lifestyle — assuming the spending level fits the plan.
**What could make $2 million feel tight?**
On the other hand, $2 million may be less comfortable if:
- You retire at 62 and need the portfolio to last 30-plus years
- You spend $150,000 or more per year
- You carry a large mortgage into retirement
- You live in a high-cost area of California
- Most of your savings are in tax-deferred accounts – that’s a whole new subject for another time.
- You claim Social Security early without reviewing the long-term impact
- You have concentrated stock positions
- You are supporting adult children or aging parents
- You have no plan for major health care or long-term care expenses
- You panic and sell investments during market downturns
None of these automatically means retirement will fail. But they do raise some concerns.
Retirement is not just about having enough money on day one. It is about keeping the plan on track through good markets, bad markets, tax law changes, health surprises, inflation, and the occasional financial curveball. No, Virginia, a one-time plan from two years ago won’t cut it. I probably forgot to mention planning is an ongoing process and, oh yes, it’s important.
**Two examples: same $2 million, different retirement**
**Example 1: The comfortable case**
A married couple retires at 66 with $2 million in investments. Their home is paid off. They expect combined Social Security income of about $60,000 per year. They spend about $110,000 annually before taxes.
They have a mix of IRA assets, taxable investments, and Roth accounts. They are willing to adjust travel spending during poor market years. They have reviewed Medicare premiums, tax brackets, and future required minimum distributions.
For this couple, $2 million may be enough to retire comfortably, especially if the portfolio is managed with a clear income and tax strategy. The overarching strategy is simple: don’t do anything dumb.
**Example 2: The tighter case**
Another couple retires at 62 with $2 million. They still have a mortgage. They spend $160,000 per year. Most of their savings are in traditional retirement accounts. They plan to delay Social Security until 70 but need larger portfolio withdrawals in the meantime.
They also want to help grandchildren with college costs and take several major trips in the first decade of retirement.
This couple may still be able to retire, but the plan needs much more testing under different economic, market, and legislative (read: tax) scenariios. They may need to adjust spending, reconsider retirement timing, review Social Security claiming strategies, or create a more tax-efficient withdrawal plan.
Same portfolio. Different answer.
**How long can $2 million last in retirement?**
Here we go again: it depends on withdrawals, taxes, investment returns, inflation, and life expectancy. Simple, eh?
A retiree withdrawing $60,000 per year from a $2 million portfolio is in a very different position than someone withdrawing $140,000 per year. The first household may have room for market volatility and inflation. The second may be putting more pressure on the portfolio, especially if retirement begins early. Portfolio pressure – especially if that household doesn’t have a roadmap – can lead to risk-taking. It seldom turns out good.
The early years of retirement are especially important because poor investment returns early in retirement can do more damage when withdrawals are being taken at the same time.
Simple example with simple numbers: The income need is $100. An investment drops from $1,000 to $800 just as income is taken, leaving $700. And, rebounds are tough. Just getting back to $900 (where it would have been with no drop in valuation), would require a 28.57% return!
So, should the retiree avoid stocks? No. Inflation is still a long-term risk. But the portfolio should be designed for the job it now has: supporting withdrawals, managing risk, and preserving long-term purchasing power. Diversification is more than just spreading money.
The investment strategy that helped build the portfolio may not be the same strategy needed to distribute it. [Learn more about retireme](https://lp.constantcontactpages.com/sl/2IaWQhU/RetirementInvestingReset)[nt portfolios here](https://lp.constantcontactpages.com/sl/2IaWQhU/RetirementInvestingReset).
**Questions to ask before retiring with $2 million**
Before deciding whether $2 million is enough, here are a few good questions:
1. How much do we actually spend each year?
2. How much of that spending is essential versus flexible?
3. When should we claim Social Security? – Don’t guess; get an analysis! It should be part of your plan. Did I mention that planning is important? Sometimes I forget.
4. Which accounts should we withdraw from first?
5. How much of our income will be taxable?
6. Could Roth conversions help before required distributions begin?
7. How would a market decline affect our income plan?
8. What happens if one spouse dies much earlier than the other? How does that change our income and tax picture?
9. How will health care and Medicare premiums fit into the plan?
10. Do we want to leave money to family or charity?
These questions are connected. Answering one often changes the answer to another.
That is why a retirement plan should not be built one decision at a time in separate little boxes.
**So, is $2 million enough?**
For many California retirees, $2 million can be enough to retire comfortably. But it is not a guarantee. The number matters, but the plan matters more. I probably forgot to mention that planning is important.
A good retirement plan should show how your income, taxes, investments, Social Security, Medicare, housing costs, and estate goals work together. It should also test what happens if markets decline, inflation remains stubborn, or one spouse lives much longer than expected.
And, by the way – something many people fail to grasp – your plan should be tied to (not just referenced for) your wealth management process. They should be linked with your plan values constantly updated. [You can learn more about retirement portfolios here](https://lp.constantcontactpages.com/sl/2IaWQhU/RetirementInvestingReset). But I digress.
The goal is not just to retire. The goal is to stay retired comfortably and confidently.
If you are age 62 or older and wondering whether your retirement savings are enough, this is the right time to get serious about the details. Not in a fearful way. In a practical way.
After all, $2 million – or any other amount – is too important to manage with guesswork, headlines, or a rule of thumb you found online while drinking coffee.
**Frequently Asked Questions**
**Is $2 million enough to retire at 62 in California?**
It may be, but retiring at 62 usually requires more careful planning. Your portfolio may need to last 30 years or longer, and you may need to bridge the gap before Medicare begins at 65. Social Security claiming decisions, taxes, health care, and housing costs all become very important.
**How much income can a $2 million retirement portfolio generate?**
A $2 million portfolio might support $60,000 to $80,000 in annual withdrawals using a 3% to 4% starting range. That amount is not guaranteed and should be adjusted for taxes, investment conditions, inflation, and other income sources such as Social Security or pensions.
**Does California tax retirement income?**
California does not tax Social Security benefits, but many other types of retirement income may be taxable, including traditional IRA withdrawals, 401(k) withdrawals, and pension income. Federal taxes may also apply. This makes tax planning especially important for retirees with large retirement accounts.
**Should I claim Social Security early if I have $2 million?**
Not necessarily. Claiming Social Security at 62 provides income sooner but permanently reduces the monthly benefit. Delaying may increase lifetime income, especially for a healthy retiree or married couple concerned about survivor income. The right answer depends on cash flow, taxes, health, and family circumstances.
**What is the biggest risk for someone retiring with $2 million?**
The biggest risk is not usually one single event. It is the combination of high withdrawals, poor market returns early in retirement, taxes, inflation, health care costs, and no coordinated plan. A strong retirement strategy should prepare for several risks at once.
**Final thought**
Retiring with $2 million in California is a strong starting point. But the real question is whether your retirement income plan is coordinated, tax-aware, and built around your actual life.
If you want a clearer answer, consider reviewing your retirement income strategy before making major decisions about Social Security, Roth conversions, withdrawals, or investment changes.
If you’d like some help, [tell me your priorities](https://indfin.com/retirement-priority-planning-review/). This will give us something to [talk about](https://go.oncehub.com/JimLorenzenCFP).
Jim
Tell me [your priorities](https://indfin.com/retirement-priority-planning-review/), then [schedule an introductory call](https://go.oncehub.com/JimLorenzenCFP)! You can [also subscribe to my newsletter.](https://visitor.r20.constantcontact.com/d.jsp?llr=fdk6idhab&p=oi&m=fdk6idhab&sit=icdtuhhgb&f=68947827-6cd6-46e6-a8a2-db365fc30f5c)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Retirement Income
**Tags:** Financial planning, Investment Strategy, managing risk, retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy
---
### [How Can Retirement Income Create a Tax Trap?](https://indfin.com/how-can-retirement-income-create-a-tax-trap/)
**Published:** May 11, 2026
**Author:** Jim Lorenzen
**Excerpt:** Tax planning should be an integral part of your financial plan
**Content:**
Retirement income withdrawals are loaded with surprises. You’re not accumulating anymore – that was the easy part. Decumulation is different. Whether you’re in pre-retirement, early retirement, middle or late retirement; what some people all the go-go years, go-slow years, or the no-go years, the withdrawal stage is different and filled with tax traps, some of which can result in life-long penalties.
**What is an example of a tax trap in retirement?**
Example: Take Bill (I made him up). He’s retired and single with a taxable income just over $58,000, which includes $45,000 in IRA income and $37,500 in Social Security benefits. As you can see, this puts him squarely in the 22% tax bracket with room to spare.
[](https://indfin.com/wp-content/uploads/2026/05/2026-Income-Tax-Brackets.jpg)He decides to tap his IRA for an extra $1,000 for a concert road trip. Adding $1,000 to his taxable income should keep him in the 22% bracket, so the additional tax on that extra $1,000 should be $220, right?
Nope. Bill will owe **$407** in taxes on that $1,000. That’s a **40.7% federal tax rate** on that additional money.
How can that happen?
Learn more about how [Tax Planning Changes During the Four Stages of Retirement.](https://indfin.com/retirementplanning/)
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Retirement Income, Taxes
**Tags:** Retirement Income, Retirement Planning, Retirement Strategy, tax planning, tax traps
---
### [Index Annuities: Useful or Unnecessary Complexity?](https://indfin.com/index-annuities-useful-or-unnecessary-complexity/)
**Published:** May 28, 2026
**Author:** Jim Lorenzen
**Excerpt:** The pitch for Index annuities can sound appealing.
**Content:**
Sure! Index annuities offer protection from market losses, some connection to stock market gains, tax deferral, and sometimes guaranteed lifetime income.
That combination gets attention, especially from retirees who are nervous about market volatility. And that concern is reasonable. Dropping from 100 to 80 represents a 20% loss; but, getting from 80 back to 100 requires a 25% gain!
Unfortunately, index annuities are often misunderstood. They are NOT:
- stock investments.
- a simple substitute for a diversified portfolio.
- “market upside with no downside,” even when the sales pitch makes them sound that way.
**An index annuity is an insurance contract that may provide protection and income, but usually at the cost of liquidity, flexibility, and upside potential.**
That does not make them bad. It makes them something worth understanding before buying, because they can be quite complex.
**What Is an Index Annuity?**
An index annuity is a fixed annuity issued by an insurance company. The return you get is what the insurance company credits. That credit is determined by a market index, such as the S&P 500.
But you are not directly invested in the S&P 500.
You generally do not:
- Own the stocks in the index
- Receive dividends from the index
- Get the full return of the index
- Have unlimited access to your money
Instead, your return is determined by a formula inside the contract. That formula may include:
- Caps on annual gains
- Participation rates
- Spreads or fees
- Surrender charges
- Income rider charges
- Withdrawal limits
- Contract rules that can change over time
This is where the details matter. The brochure may say “market-linked growth.” The contract may tell a more complicated story.
**The Good: What Index Annuities Can Do Well**
Index annuities may be useful for certain retirees or pre-retirees who want more protection and are willing to accept trade-offs.
Potential benefits include:
- **Principal protection from market losses:** Many index annuities protect your account from negative index returns.
- **Tax deferral:** Gains are not taxed until withdrawn.
- **Potential for modest growth:** You may receive some index-linked interest in positive years.
- **Lifetime income options:** Some contracts offer riders that can provide income for life.
- **Emotional comfort:** For some retirees, knowing part of their money is protected can make it easier to stay disciplined with the rest of their plan.
These are real benefits. They should not be dismissed.
But benefits are only half the story.
**The Trade-Offs: What You Give Up**
Annuities are contracts, and contracts come with rules. Common trade-offs include:
- **Limited upside:** If the market has a strong year, your gain may be capped.
- **Reduced liquidity:** Surrender charges may apply if you withdraw too much too soon.
- **Complexity:** It can be difficult to understand how returns are calculated.
- **Fees:** Optional income riders may add annual costs.
- **Ordinary income taxation:** Gains are generally taxed as ordinary income when withdrawn.
- **Inflation risk:** A fixed or limited income stream may not keep up with rising living costs.
- **Changing terms:** Some caps and crediting rates may be adjusted by the insurance company after the initial period.
This does not mean an annuity is automatically wrong. It means the product should have to earn its place in your retirement plan.
No financial product deserves a free ride just because the word “guaranteed” appears in bold print. Maybe the word “guaranteed” should be replaced with the words, “backed by”, because in the final analysis it’s simply a contract between you and a private insurer.
**Index Annuities Are Not Stock Replacements**
One of the biggest mistakes is comparing index annuities to stocks.
They should usually be compared to conservative tools, such as:
- CDs
- Treasury bills
- Treasury notes
- High-quality bonds – usually short to intermediate (1-10 year)
- Fixed annuities
- Bond ladders
- Cash reserve strategies
Why? Because **index annuities are designed more for protection than long-term growth**.
If an annuity has a 4% cap and the market rises 15%, you’ll receive only 4%. If the market falls, you’ll receive 0%. That may be a reasonable trade-off for conservative money, but it is not the same as investing in the market.
**The Income Base Confusion**
Many index annuities include income riders. These may show an “income base” growing at a guaranteed rate.
This is where confusion often begins. The income base is typically not real money you can withdraw. It is usually a calculation used to determine future guaranteed income.
Think of it like airline miles. Airline miles may help you get a flight, but they are not the same as cash in your bank account.
Before buying an annuity with an income rider, ask:
- What is my actual account value?
- What is my surrender value?
- What is the income base?
- What can I withdraw in cash?
- What income is guaranteed?
- What fees apply?
- What happens if I die early?
- What does my spouse receive?
If the answers are hard to explain, that is a warning sign.
**Are There Simpler Alternatives?**
I think so.
Depending on your goal, other strategies may accomplish similar objectives with less complexity.
If the goal is **safety**, alternatives may include:
- Treasury bills
- CDs
- Money market funds
- Short-term bond funds
- Individual high-quality bonds
If the goal is **retirement income**, alternatives may include:
- Delaying Social Security
- Coordinating pension choices
- Building a Treasury or CD ladder
- Creating a disciplined withdrawal plan
- Using dividends and interest as part of a broader strategy
If the goal is **longevity protection**, alternatives may include:
- Social Security timing analysis
- Partial annuitization
- A simpler immediate or deferred income annuity
- A more conservative portfolio withdrawal strategy
If the goal is **tax deferral (delay)**, you might consider
- Combining a tax-managed equity strategy with bond ladders designed to “guarantee” a return of principal.
- Advanced life insurance designs that might create a source of tax-free income in your later years.
Sometimes an annuity is the right tool. Sometimes it is an overbuilt solution to a problem that could be handled more simply.
All these solutions are simply tools in the toolbox that should be evaluated in terms of how well they fit into your comprehensive financial plan.
Keep it simple. Be careful about giving up liquidity. Keep an eye on costs.
**Q&A: Common Questions About Index Annuities**
**Are index annuities good for retirees?**
They can be, but only in the right situation. An index annuity may help retirees who value principal protection or guaranteed income. But it should be compared with simpler alternatives before buying. There might be tools and strategies that are less complex and more liquid.
**Can you lose money in an index annuity?**
Many index annuities protect against market losses, but that does not mean there is no risk. You may face surrender charges, limited returns, inflation risk, taxes, and reduced liquidity. If your return after inflation and taxes is zero, you’ve lost purchasing power.
**Are index annuities better than CDs or bonds?**
Not automatically. CDs and bonds are often simpler and more liquid. An index annuity may offer different benefits, such as tax deferral or lifetime income, but those benefits come with contract restrictions.
**Is the income base real money?**
Not likely. The income base is typically a calculation used to determine guaranteed income. It is not the same as your cash value.
**Should I buy an annuity for retirement income?**
Maybe. The decision depends on your income needs, tax situation, Social Security strategy, investment portfolio, liquidity needs, and comfort with guarantees. The annuity should solve a specific problem better than the alternatives. Important: Never put all your money into one idea. At best, it might be a good component in your overall plan, but not everything.
**Bottom Line**
Index annuities are not scams, and they are not magic. They are insurance contracts with benefits and trade-offs.
They may help provide protection, tax deferral, or lifetime income. But they can also add complexity, limit growth, reduce liquidity, and create tax issues later. No free lunch.
The objective question is simple:
**Does the annuity solve a real retirement problem better than a simpler alternative?**
That is the question worth answering before you buy.
If you are considering an index annuity, or already own one, it may be wise to have it reviewed as part of your full retirement plan. A good review should compare the annuity to other options, explain the contract in plain English, and help you decide whether the benefits are worth the trade-offs.
If you’re already invested in an older annuity, some of these older annuities have high cost structures and you may have very low or no surrender charges. You may or may not want to liquidate an older annuity because of tax reasons – that’s a separate discussion – but, there are low-cost, no-load alternatives available with no surrender charges which you can access with what’s called a 1035 exchange.
Look before you leap! Hope this helps. If you’d like some help, [you can begin here!](https://indfin.com/getting-started/)
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Annuities
**Tags:** Income Annuities, Retirement Annuities, Retirement Income
---
### [Social Security in 2026: 4 Themes (and What They Mean for Your Retirement Plan)](https://indfin.com/social-security-in-2026-4-themes-and-what-they-mean-for-your-retirement-plan/)
**Published:** January 19, 2026
**Author:** Jim Lorenzen
**Excerpt:** Social Security 2026 has issues. It isn’t “ending”—but four things are changing fast: Gen X is lining up with new questions, reform pressure is getting real, the “best” claiming age depends on your life (not just math), and dealing with the Social Security Administration can still be a time-suck. Here’s what to watch—and what to do
**Content:**
They say the only constant is change. It appears it’s still true. Here are four themes worth watching for Social Security in 2026, and what they mean:
**1) Gen X is getting to the starting gate**
Social Security in 2026 is facing an oncoming headwind: the *last* of the Baby Boomers turns 62 (the earliest age to start retirement benefits). Right behind them comes Gen X—now old enough to shift from “retirement is later” to “retirement is… wait, oops! It’s getting close!”
Gen X grew up assuming Social Security would be part of the plan, but with a healthy dose of skepticism. They’ve watched the economy stumble and recover more than once. (The National Bureau of Economic Research is the official scorekeeper for U.S. recession dates.) They’re also asking, “Will Social Security benefits be cut?”
**Why it matters:** Gen X questions are usually not just “When should I claim?” They’re more like:
- “Can we retire when we want, or when we have to?”
- “What happens if one of us stops working earlier?”
- “How do we cover healthcare before Medicare?”
- “What if one spouse outlives the other by 10–15 years?”
- “Will Social Security benefits be cut?
Social Security becomes the starting point for the *whole* retirement conversation—income, taxes, healthcare, survivor planning, and lifestyle. What’s the best age? 62, 67, or 70? You can [get a personalized report here](https://lp.constantcontactpages.com/sl/9Al940w).
**2) Social Security reform is moving from “someday” to “soon”**
Social Security isn’t vanishing. But the funding gap is real—and it’s getting close enough that lawmakers can’t keep punting forever. In fact, those members of the senate getting elected this year (1/3 of the senate) will have no choice but to deal with the problem. But, will Social Security benefits be cut?
According to the Social Security Trustees’ summary, the Old-Age and Survivors Insurance (OASI) Trust Fund is projected to pay full scheduled benefits until **2033**. After that, continuing income would cover about **77%** of scheduled benefits if Congress does nothing.
**What “77% payable” actually means**
If 77% is payable, that implies a shortfall of about 23%. That’s the “automatic cut” people worry about—because the system would only be able to pay what’s coming in.
Here’s the important planning point: **reform talk is not a great reason to panic-claim at 62.** It *is* a reason to pay attention and make decisions with your eyes open.
Brookings, for example, has put forward a “many small levers” approach—raising the taxable maximum so about **90% of wages** are covered again, plus other incremental changes aimed at restoring solvency.
As reform heats up, people will hear proposals that sound technical, like:
- raising the earnings cap (so more income is subject to payroll tax),
- changing how benefits grow for future retirees,
- tweaks that affect higher earners more than lower earners.
To judge any of it, people need the “rules of today” explained clearly—otherwise it’s just noise.
**3) Do the math first—then make the decision you can live with**
Some claiming decisions are like choosing a club: the “technically best” option on paper isn’t always the best one with real wind, real nerves, and real life.
Delaying benefits can increase guaranteed income later in life—when flexibility often shrinks and healthcare costs can rise. But waiting is not automatically “best” for everyone. Sometimes claiming earlier supports:
- an earlier retirement date,
- a spouse who needs income sooner,
- a health issue or family situation,
- or simply a plan that feels less stressful.
Also, many “optimal” scenarios are close calls. Sometimes the difference between choices is small enough that other priorities matter more—like getting income to one spouse earlier, or smoothing taxes across years.
**The best process is simple:**
1. run the numbers – and don’t forget [the impact of taxes](https://indfin.com/tax-planning-the-smart-way/).
2. then have the human conversation about tradeoffs. Begin doing some real [retirement income planning](https://indfin.com/retirementplanning/).
> [Retirement Income Planning](https://indfin.com/retirementplanning/)
**4) SSA service is better on paper than in real life**
SSA service metrics have improved in some areas, but the experience can still be frustrating—especially by phone. An SSA Office of the Inspector General report noted that the National 800 Number **Average Speed of Answer** peaked around **30 minutes in January 2025** and improved to **about 7 minutes in September 2025**.
**But there’s a catch** that matters to real humans: the same OIG report tracks **callback wait times**, which ran much longer—peaking at roughly **2 hours and 32 minutes in January 2025** and still around **about 1 hour and 2 minutes in September 2025**. Those requesting callbacks are counted as not having a wait time, which distorts the average. And major media reporting has continued to highlight long waits, dropped calls, and ongoing strain on the system.
**Practical takeaway:** assume you’ll do more self-service than you’d like.
**Quick checklist: what to do in 2026**
- **Create/use your “my Social Security” account** if you’re over 18 to track and review your earnings record.
- **Spot-check your plan as a couple**: spousal benefits, survivor benefits, and who claims first can matter a lot.
- **Treat reform headlines like weather reports**: worth checking, not worth panicking over.
- **Build extra time into anything involving SSA** (especially if you need humans, not just the website).
- **Run a claiming analysis inside the bigger plan** (taxes, healthcare timing, retirement date, spending needs).
2026 is a year to plan with your eyes open.
> Expect more questions from Gen X, louder reform headlines, and more people realizing Social Security decisions are personal—not automatic.
Run the numbers, then weigh the real-life tradeoffs. And if you need the SSA, give yourself extra time and patience.
Getting ready to retire? Learn about all the options that might be available to you. I’ve created a series of videos you may find helpful. Just pick the one(s) that are appropriate for you! [You can subscribe to my newsletter and access them here](https://lp.constantcontactpages.com/sl/oIwLnlJ). You might find my monthly letter helpful. If not, you can also unsubscribe instantly at any time.
**Questions frequently asked:**
**Will Social Security benefits be cut in 2033?**
If no changes are made, Trustees project that scheduled benefits could exceed available revenue after 2033, with about 77% payable from continuing income.
**Should I claim early because of reform uncertainty?**
Not automatically. The smarter move is to evaluate your options in context—health, spouse, taxes, work plans, and risk tolerance.
**Why are Social Security phone wait times still an issue?**
Hold times improved in 2025, but callback waits were still long, and service challenges remain widely reported.
I hope you found this helpful! Want help? Just [go to the Getting Started page!](https://indfin.com/getting-started/)
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Social Security, Taxes
**Tags:** social security, social security claiming, social security help, social security outlook, when to claim social security, Will Social Security be there for me
---
### [8 Social Security Topics to watch in 2026?](https://indfin.com/8-social-security-topics-to-watch-in-2026/)
**Published:** April 27, 2026
**Author:** Jim Lorenzen
**Excerpt:** Simi Valley, Moorpark, and Thousand Oaks are not inexpensive places to retire.
**Content:**
If you’re a Simi Valley or Moorpark pre-retiree or retired and trying to figure out the Social Security puzzle, the above video may be a good place to start. Here are eight Social Security topics to watch in 2026.
Are you a Baby-Boomer? You may [benefit from this one](https://indfin.com/socialsecurity/), too.
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Social Security, Taxes
**Tags:** social security, social security help, social security outlook
---
### [“How Do I Plan for Rising Prices? Is Inflation Changing the Rules?”](https://indfin.com/how-do-i-plan-for-rising-prices-is-inflation-changing-the-rules/)
**Published:** May 18, 2026
**Author:** Jim Lorenzen
**Excerpt:** Inflation is more than an economic headline. For retirees needing a rising income to keep pace with rising prices, it can quietly change the math of retirement.
**Content:**
Rising prices are frustrating during working years, but there are ways to adjust. Your income may increase or you may change jobs. If you’re a business owner, you might raise prices. There are fewer options in retirement. Your income may come from Social Security, pensions, investment withdrawals, cash, and savings. Some of those adjust for inflation. Many do not.
Rising prices mean a loss of purchasing power. Your money buys less. And, for a reitree facing rising health insurance and medical costs, paying more for food, energy, and other necessities can be worrisome. And, it doesn’t matter if you have $200,000 or $10 million. Lifestyles have a way of expanding to meet means – It’s all relative.
A retiree who needs $8,000 a month today – not unusual in Ventura County or anywhere else in California – may need much more later just to maintain the same lifestyle. At just 3.5% inflation for five years, that will retiree will need $9,500 per month, almost 19% more income, to buy the same things: nothing fancy. Same groceries. Same house. Same insurance. Same occasional dinner out where the menu now looks like it was priced by a hostage negotiator.
**The Lesson from the Late 1970s**
Many retirees remember the late 1970s and early 1980s, when inflation and interest rates were painfully high. Bank CDs, Treasury bonds, and savings accounts appeared to offer attractive returns. In those days people could earn double-digit interest.
That sounded wonderful—until you looked at what was really happening.
If you earned 12% but inflation was running near that level, your real return was much lower. After taxes, it could easily be negative. You had more dollars on paper, but those dollars bought less due to rising prices.
That is the part investors often miss.
So, a high interest rate is not the same as a high real return. What matters is what you keep after inflation and taxes. Retirement planning should focus on purchasing power, not just account statements.
**Why Retirees Feel Inflation More**
Retirees are especially exposed to inflation because they are usually withdrawing from their accounts rather than adding to them.
That creates a double challenge. If living costs rise, withdrawals need to rise too. If markets are weak at the same time, the portfolio is under pressure from both ends. You are taking more out while the account may be temporarily worth less.
That is how inflation can turn a decent retirement plan into a tighter one.
Where’s the safe haven? Cash feels safe, but using our 3.5% inflation example, our $8,000 monthly income will buy only $6,735 worth of goods and services in five years – and taxes are another subject.
TV commercials are always selling something. Angry Sandy is gone now, but there are people selling gold and they make it sound so safe. I feel better, don’t you?
The question is not, “How do I avoid all risk?” Well, as we’ve seen, cash is a *guaranteed* loser (no risk there). But, the truth is everything has some type of risk attached, even if only legislative risk (government changing the tax code).
**Historically, Stocks Have Performed Over Time, But They Are Not a Perfect Hedge**
Stocks are often described as a way to fight inflation. Over long periods, that can be true. Good companies may raise prices, grow profits, and help investors preserve purchasing power. Hey, it you like your breakfast cereal, you may want to be part owner of the company that makes it!
But stocks do not move neatly with inflation. They can fall when inflation rises. They can fall when interest rates rise. They can fall because investors get nervous and decide every stock suddenly has cooties.
Growth is good. But growth investments must be balanced against the need for stable income and near-term spending.
**Bonds Still Have a Job, But Expectations Matter**
Bonds have traditionally helped provide income and stability, but retirees need realistic expectations.
When inflation is high, a bond’s stated yield may not tell the whole story. A 5% yield does not help much if inflation is 6% and taxes take another bite. Ouch! The issue is not the number you see. It is what you keep.
This is why chasing yield has often proved dangerous. Higher-yielding investments usually come with higher risk. As I write this the 10-year Treasury is yielding around 4.6%. So, any investment touting a yield above 4.6% over the same period might be acceptable in moderation, but it is not a free lunch. To whatever degree it’s offering a greater return above 4.6% is the definition of risk you’re assuming. In retirement, “a little extra yield” can turn into “why is this thing down 20%?” faster than anyone enjoys.
**Social Security Is More Valuable Than Many People Realize**
One of the strongest inflation-fighting tools retirees have is Social Security – maybe the best annuity you didn’t know you bought – this one has cost-of-living adjustments (COLAs).
The COLAs are not perfect, and they may not fully match the rising costs retirees actually face, especially health care. But they are still valuable.
How much is a $3,000 monthly Social Security check worth? What bond would you have to buy to provide you with a $36,000 annual income. Even without the COLAs, it would take $782,608 in a 4.6% bond to produce the same income – but, the bond is redeemed at maturity while the Social Security income lasts for life! Now, add-in the COLAs and you really have something special.
This makes the claiming decision very important. Claiming early can make sense in some cases, but it permanently reduces the monthly benefit. Delaying can increase the benefit, and future inflation adjustments apply to that higher amount.
For married couples, this can also affect survivor income. The larger benefit may continue for the surviving spouse, which makes the timing decision even more important.
Social Security should not be treated like a quick checkbox. It is one of the most important retirement income decisions many people make. It should be an integral part of your planning. The wrong decisions can be costly – even permanent. [Learn more about what you need to know here.](https://indfin.com/socialsecurity/)
**Medicare and Taxes Can Shrink the Inflation Adjustment**
There is one catch.
Medicare Part B premiums are often deducted from Social Security payments. When Medicare premiums rise, they can reduce the net benefit of the Social Security cost-of-living adjustment.
Higher-income retirees may also face Medicare IRMAA surcharges. These can be triggered by Roth conversions, capital gains, large IRA withdrawals, or other income events. Oh! The IRMAA surcharge is triggered by your income TWO years ago! That’s the IRMAA tripwire. We have a kit you might like. [You can get it here.](https://lp.constantcontactpages.com/sl/M7nwT9y/IRMAATripwireKit)
That does not mean those moves are wrong. It means they need to be planned.
In retirement, one financial decision often affects three others. It is like golf: the shot you hit now determines whether the next one is from the fairway or behind a tree.
**What Retirees Should Do**
Inflation does not require panic. It requires discipline.
Retirees should review:
- How much they are withdrawing each year
- Whether their spending plan allows for rising costs
- How much cash they hold for near-term needs
- Whether the portfolio still has enough long-term growth
- Whether they are taking too much risk chasing income
- When to claim Social Security
- How taxes and Medicare premiums affect real income
The goal is not to predict inflation perfectly. Nobody does that consistently. The goal is to build a plan that can handle different conditions without forcing bad decisions.
**The Bottom Line**
Inflation is dangerous because it’s like glaucoma – it works quietly. It does not crash through the front door. It seeps in through groceries, insurance, taxes, utilities, repairs, and health care.
The late 1970s taught an important lesson: high stated returns do not mean much if inflation and taxes consume them. What matters is real purchasing power.
A sound retirement plan should account for that. It should include growth, stability, tax awareness, Social Security strategy, and spending flexibility.
Retirement income planning is not about getting the biggest number on a statement. It is about making sure your money keeps doing its job after inflation, taxes, and real life have taken their cut.
**FAQ: Retirement Planning and Inflation**
**How does inflation affect retirement planning?**
Inflation raises the cost of living and reduces purchasing power. Retirees may need larger withdrawals over time to maintain the same lifestyle.
**Why is inflation harder on retirees?**
Retirees often live on fixed or semi-fixed income and are usually withdrawing from investments rather than adding to them.
**Are stocks a good inflation hedge?**
Stocks can help over long periods, but they are not a perfect short-term inflation hedge. They can decline during inflationary periods.
**Does Social Security adjust for inflation?**
Yes. Social Security benefits may receive annual cost-of-living adjustments, which help retirees keep up with rising costs.
**What matters more: return or purchasing power?**
Purchasing power matters more. A high return can still be disappointing if inflation and taxes consume most of it.
If you’d like some help, [tell me your priorities](https://indfin.com/retirement-priority-planning-review/). This will give us something to [talk about](https://go.oncehub.com/JimLorenzenCFP).
Jim
Tell me [your priorities](https://indfin.com/retirement-priority-planning-review/), then [schedule an introductory call](https://go.oncehub.com/JimLorenzenCFP)! You can [also subscribe to my newsletter.](https://visitor.r20.constantcontact.com/d.jsp?llr=fdk6idhab&p=oi&m=fdk6idhab&sit=icdtuhhgb&f=68947827-6cd6-46e6-a8a2-db365fc30f5c)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Iran and the Ukraine - and Global Political Economics: A High-Level Overview.](https://indfin.com/iran-and-the-ukraine-and-global-political-economics-a-high-level-overview/)
**Published:** April 22, 2026
**Author:** Jim Lorenzen
**Excerpt:** It helps to see the whole chessboard
**Content:**
**A 30,000 Foot View**
The media dramatizing news events is nothing new. And, today, with so much happening in the Ukraine, the mid-east – both in Israel and the Iran conflict over the straits and other issues – and with NATO and balance of trade and defense issues, the news media has a plethora of stories. As usual, the media, in its desire to inform – coupled with ratings-driven entertainment – often neglects to educate. Stories often take a local slant – gas prices for example – and all the various stories are covered in isolation with little thought given to their interrelationship.
**First, A Backdrop**
To understand what’s driving the various interests (we’ll leave Iran’s theocratic motivation aside for now), it’s important to understand how money works on the global stage, as it affects the behaviors of NATO, Russia, the Ukraine, and Iran.
Obvious: the federal government is running annual deficits that accumulate as increased debt.
[](https://indfin.com/wp-content/uploads/2026/04/2026-Fed-Budget-1.jpg)Next, it’s important to recognize that the total amount of output (goods and services) a country produces constitutes its ultimate budget constraint. It’s large volumes of output – not large quantities of money (inflation) – that makes nations prosperous.
A country’s output is its gross domestic product (GDP): the market value of all final goods and services produced within a country’s borders over a given year. So, GDP is a nation’s output.
When one country wants to exchange its output for that of another, you have a trade deal. When the exchange is perfectly even in value, then both countries’ trade accounts are in balance.
When country A exports more than it imports from country B, country B runs a trade deficit. How does B pay the balance? It borrows money from country A to finance the difference. Country A is lending the money to allow B to purchase A’s excess production.
So, if a country imports products from another country without exporting anything, it could pay for those imports only by borrowing. The seller is financing the sale.
Back to square one: the long-term constraint on consumption and investment (components of GDP) is the amount of output that can be produced. GDP represents the ultimate budget constraint.
**A View From the Balcony**
The United States has a large debt problem. You can [see it in real time here](https://www.usdebtclock.org/). As you saw on the first slide, the U.S. spends more on debt interest than on national defense, at least as of the end of the first quarter. So, it’s no wonder those who do the spending want to see lower interest rates, since interest rates represent the price of money.
With the war with Iran, the Fed is facing a supply-shock tradeoff and may do little or nothing to lower rates. In addition, increased defense spending could raise deficits even further, which could mean higher longer-term Treasury yields, which could put pressure on stocks and long-term bonds. Why higher long-term Treasury yields? In a competitive marketplace, the government will have to pay higher interest rates to attract an investor to purchase long-term government debt. If the interest is high enough, the investor may sell a risky long-term stock holding to make the purchase.
Where else can the government go for money?
Tariffs are an option. Unfortunately, high penalizing tariffs don’t have a successful history. Without getting into the weeds, it’s worth remembering that trading partners represent more than competitive advantage economically (that’s a different topic); but those countries we trade with also provide defense landing bases, as well as overflight rights – areas which, in the past, have come in handy and, at other times because of tariffs, have come back to bite us.
Europe is purchasing Russia’s oil production, they want to see an end to the Iran conflict,which they hope will lead to lower oil prices. But, Europe has another incentive not to join the Iran fight. Their biggest worry is Russia. Russia depends on hard currency to finance its ambitions and it’s Russia’s oil exports that provides that financing. As long as oil prices are high, Russia runs a trade surplus. If those revenues were to dry up, they would – as President Reagan knew – likely implode.
And, there are those who know their history who see a potential repeat of the 1930s for eastern Europe when a previous “America First’ movement was preaching both isolationism and protectionism while Germany and Italy were promising greatness to their people mired in depression.
So, Russia has an economic interest in Iran *continuing* the conflict – indeed, continuing may be more important than winning – in order to finance their agenda for Ukraine and beyond. For them, it’s a continuing source of hard currency they need to advance their agenda. Remember the importance of GDP.
I remember it was during my first entry-level course in economics, the professor told the class that a basic understanding was important to being a good citizen.
It’s still true.
Jim
*Special thanks to JP Morgan for their assistance in providing the image for this post. IFG and JP Morgan are not affiliated.*

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Economy
**Tags:** economy
---
### [What's New for Social Security in 2026?](https://indfin.com/whats-new-for-social-security-in-2026/)
**Published:** April 14, 2026
**Author:** Jim Lorenzen
**Excerpt:** Take a look?
**Content:**
Grab a cup of coffee and take a look at the eight Social Security topics to watch in 2026.
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Social Security, Taxes
**Tags:** social security, social security help, social security outlook
---
### [Is Social Security in Danger?](https://indfin.com/is-social-security-in-danger/)
**Published:** April 6, 2026
**Author:** Jim Lorenzen
**Excerpt:** For many people, Social Security is looking less secure. Should they be worried?
**Content:**
The government recorded a deficit of approximately $1.78 trillion in 2025, while total debt surpassed $39 trillion, partially driven by high interest payments. Here’s the picture for 2026 including Social Security obligations.
[](https://indfin.com/wp-content/uploads/2026/04/2026-Fed-Budget.jpg)Meanwhile, total Social Security benefit payments for 2025 were about $1.6 trillion – and the Congressional Budget Office (CBO) projects the trust fund will be depleted in 2032. If this fund isn’t replenished, it’s estimated that only about 72% of promised benefits will be paid.
Social Security likely won’t go away; but, just as likely, there will be changes – possible gradual changes in benefits, taxes, and/or retirement ages.
This has prompted many investors to fill in the retirement income gap. No wonder those with a floor of income have more confidence in their retirements than those who don’t. Naturally, this confidence is a product of the relationship between the size of their asset base and spending levels.
That said, Social Security is unlikely to disappear. About 75% of benefits are funded by ongoing payroll taxes. It’s the other 25% that’s at issue.
Higher interest rates don’t directly fund or defund Social Security, but they do impact the broader financial picture since they impact trust fund interest. A good recommendation might be to build a retirement income plan stress tests multiple scenarios: lower Social Security income, higher healthcare costs, longer life expectancy, and market volatility.
If you’d like some help, [tell me your priorities](https://indfin.com/retirement-priority-planning-review/). This will give us something to [talk about](https://go.oncehub.com/JimLorenzenCFP).
Jim
*Thanks to JPMorgan for providing the above image. JPMorgan and The Independent Financial Group are not affiliated.*

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Social Security
**Tags:** social security, social security help, social security outlook, Will Social Security be there for me
---
### [Beware the Medicare Premium Surprise (IRMAA)](https://indfin.com/beware-the-medicare-premium-surprise-irmaa/)
**Published:** February 16, 2026
**Author:** Jim Lorenzen
**Excerpt:** The Tripwire that springs the trap two years later!
**Content:**
This one is created for executives near retirement to spot the income years that can raise Medicare Part B & D costs – The Medicare premium surprise that springs **two years later**!
**The IRMAA Tripwire Kit includes:**
- A plain-English IRMAA explanation tailored to executives “lumpy income”
- The **10 most common IRMAA tripwires** (bonus, RSUs, stock sales, severance, Roth conversions, etc.)
- A **two-year lookback planner** (so you know which tax year is “the scorecard”)
- **2026 Part B + Part D IRMAA tables** (with the official 2026 amounts)
- A **SSA-44 “income dropped after retirement” checklist** + links to the official forms/resources
If you’re one of those facing this issue, you can [sign-up to receive the IRMAA Tripwire Kit here.](https://lp.constantcontactpages.com/sl/M7nwT9y/IRMAATripwireKit)
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Medicare, Taxes
**Tags:** Medicare, tax management, tax planning, Tax reduction
---
### [Time for an Investment Strategy Reset?](https://indfin.com/time-for-an-investment-strategy-reset/)
**Published:** March 18, 2026
**Author:** Jim Lorenzen
**Excerpt:** Investment strategy was simple during working years: sock it away! If the market’s down, your deposits buy more and lower prices; if the market’s up, buy less at higher prices.
**Content:**
**The Shift from Growth to Income — How Investing Changes in Retirement**
Easy peasy.
Just keep doing it and the long term growth of the economy (and it’s markets) does the rest.
But, as retirement gets closer, and the conversation changes.
Now the question is not just, “How much can I grow this portfolio?” It becomes, “How can I make my money last while I’m taking income during turbulent markets while the tax laws can change at any time?”
That is a very different question.
Time for an investment strategy reset? Growth still matters, but losses become more meaningful when your drawing money out – and paying taxes, too.
Retirement is a different stage, with different risks, different tradeoffs, and different planning priorities – and all kinds of tax traps lurking as you take withdrawals, affecting Social Security, Medicare premiums, and a lot of other stuff.
*Note: a created a plain-English guide explains how thoughtful portfolios are often structured before retirement begins, and why a portfolio built for the accumulation years may need a fresh look as retirement approaches. You can [access it here](https://lp.constantcontactpages.com/sl/2IaWQhU/RetirementInvestingReset):*
**Why the old growth playbook often needs updating**
When you are still working, market downturns are easier to live with. They are not fun, but they are usually manageable because you are still earning, still saving, and still buying into the market as you go.
In retirement, the math gets trickier. Investment strategy becomes more important.
Once you begin taking money out of the portfolio, market losses can have a bigger impact. If you need withdrawals during a downturn, you may end up selling investments at depressed prices. That can reduce the portfolio’s ability to recover later. A bad stretch early in retirement can do more damage than the same bad stretch during your working years.
Example: if an account goes from 100 to 80 (we’ll keep it simple), that’s a 20% loss. To get back from 80 to 100 requires a 25% gain. If you’re drawing money from that account – say, taking it down to 75 after the drop, you’ll need a 33.3% gain to buy back that old 20% loss.
Scary thought?
At first, maybe; but, it does mean the portfolio should be built for a new reality. Retirement is not just about return. It is about return, timing, withdrawals, taxes, and resilience.
Put another way, the portfolio’s investment strategy now has to play offense and defense. It is no longer enough to swing for distance on every shot. At some point, retirement investing starts looking a lot more like course management than a driving range competition.
A game plan is important. [This is what the planning process looks like](https://indfin.com/retirementplanning/).
**Growth still matters in retirement**
A common mistake is assuming that retirement means you no longer need growth. Money buried in a coffee can still loses 2-3% every year in purchasing power – money is worth only what it buys.
Retirement can last 25 or 30 years, sometimes longer. A 62-year-old retiring today may need a portfolio that still works well into their 80s or 90s. That’s a lot of inflation and tax law change. There’s also the issue of rising healthcare costs and the needs of a surviving spouse.
So the real investment strategy shift is not from growth to no growth – It is from growth-only thinking to a more balanced approach that combines growth, stability, coordinating income, tax issues, and flexibility.
A retirement portfolio often needs to do at least four things well:
- Enough growth to help preserve purchasing power over time.
- Enough stability so you are not forced to sell growth assets at the worst possible moment.
- Ability to support a practical withdrawal strategy.
- It must be tax-efficient.
No wonder financial planning is so important. A sound investment strategy is based on a sound plan.
My dad once told me, “If you think education is expensive, try ignorance.”
**The shift from growth to income is not as simple as it sounds**
Over the years, I’ve noticed that more people are hurt by their behavior than their investments. Failing to plan is one flaw. Too often, “income” turns into “chasing yield.” That’s an investment strategy flying blind, without a plan.
That can mean loading up on dividend stocks, stretching for high-yield bonds, concentrating in REITs, or buying whatever happens to be paying the fattest distribution this week. The problem is that income by itself does not tell you much about risk.
A stock yielding 5 percent can still fall 25 percent.
A bond fund can lose value when rates rise. Did I say “can”? Change that to DOES. When interest rates rise, existing bonds do lose value and the reason Is simple: no one will buy an existing bond in the marketplace when newer bonds pay more interest. The only way to sell the existing bond is to reduce the price to compensate for the difference in income.
It’s not rocket science.
A portfolio packed with income investments can still be poorly diversified, more volatile than expected, or tax-inefficient.
Income is useful. Yield-chasing is not a retirement strategy.
The better question is not, “How much does this investment pay?” The better question is, “What role does this investment play inside the portfolio; how does it fit with my investment strategy, and what risks come with it?”
That framing tends to lead to better decisions. It is less exciting than hunting for the next shiny income idea, but exciting is overrated in retirement investing. Warren Buffett once said, “If you think investing is fun, you’re doing something wrong.”
So much for those trading options commercials.
**A retirement portfolio should be built by job, not by label**
So is it about “aggressive” or “conservative.” Labels don’t tell you much. A better approach is to think about what each part of the portfolio is supposed to do.
Near-term spending needs are different from intermediate-term support. And, longer-term growth is needed to address inflation and support spending far down the road.
No golfer would not use a driver on every shot just because it goes the farthest. And you would not use a putter from 150 yards just because it feels safe. Different tools have different jobs. A good retirement portfolio works the same way. The financial course you need to maneuver has its own set of hazards.
**The real risks in retirement are broader than market volatility**
When people talk about investment risk, they usually mean stock market risk. That matters, of course, but for retirees the real risks are broader.
One risk is withdrawing from the portfolio during a weak market.
Another is becoming too conservative too early and failing to keep up with inflation.
Another is concentration risk, such as having too much in one stock, one sector, or one style of investment.
And then there is tax risk, which gets ignored far too often.
A portfolio can look perfectly fine on paper and still create avoidable tax problems once distributions begin.
Do you have a large IRA? Large required minimum distributions can affect Social Security taxation and your Medicare premiums. poorly timed capital gains and lack of coordination across account types can all reduce what you actually get to keep. And you thought planning fees were expensive….
**Tax management becomes part of the investment strategy**
Your 401(k) or IRA is a kind of partnership. You and Uncle Sam both have a claim on the assets – except Uncle Sam isn’t a friendly business partner. He gets to decide how much of your money he can take – and you have no say. Some partner.
This is where many do-it-yourself investors get blindsided. They may have solid investments, but no clear plan for which accounts to tap first, how withdrawals affect tax brackets, or how future required distributions could shape the picture later. Okay, I won’t say a plan would help with this (but it would).
Consider this: two households with the same net worth can have very different retirement outcomes depending on where the money is held and how it is withdrawn. Traditional IRAs, Roth accounts, and taxable brokerage accounts do not behave the same way. Neither do the tax consequences tied to them.
So, a retirement-ready portfolio is built on a planned investment strategy more than an asset allocation chart. It should reflect how the accounts are organized, how withdrawals will likely happen, and where tax surprises may be waiting around the corner.
But, this doesn’t mean every investor needs a complicated investment strategy with seventeen moving parts and a spreadsheet that looks like it was built by NASA.
But it does mean taxes deserve a seat at the table.
**Is there a “best” portfolio for retirement?**
No.
That is a little like asking what the best club is on a golf course. It depends on the shot, the distance, the wind, the lie, and whether you are trying to save par or saving an 8. Either way, blaming the earth’s rotation doesn’t help.
The better question is: what investment strategy portfolio structure fits your actual life?
A couple with strong pension income and modest spending needs may be able to take more investment risk than a household depending heavily requiring large portfolio withdrawals. Someone with most of their money in tax-deferred accounts may need to think differently than someone with substantial after-tax savings. A pre-retiree five years out may need a different setup than a widow in her late seventies who is already drawing income.
That is why model portfolios can be useful educational tools, but they are not magic answers. They can help illustrate tradeoffs. They can show how different mixes handle growth, income, and risk. But they still need to be matched to a real person, with real goals, real taxes, and real spending needs.
**What should pre-retirees be doing now?**
It depends (consultant’s answer). A35-year old is still a pre-retiree – and should be planning. But, for most, if retirement is still a few years away, there’s no time like the present.
This may include reviewing how much risk the portfolio is actually taking, identifying concentrated positions, improving diversification, thinking through future withdrawal needs, and making sure the tax picture is not being ignored. Oh, yes, don’t get married to company stock just because you’re loyal. Manage your money like it’s a business – it is – and don’t get emotional. Ask any former Lucent employee.
A portfolio that worked beautifully during peak earning years may not be built for the transition into retirement income. That does not mean it is broken. It just means the game has changed, and the strategy may need to change with it.
**The bottom line**
Retirement investing is not about abandoning growth and hiding in income investments. It is about building a portfolio that can do more than one job well.
You still need growth. You also need stability, flexibility, and tax awareness. You need a plan for withdrawals. You need to understand the risks of chasing yield. And you need an investment strategy that fits the life the portfolio is meant to support.
That is the real shift from growth to income. Not a dramatic all-or-nothing move. More like a smart reset.
And for pre-retirees and retirees with serious assets, it is one of the most important changes to get right.
As retirement gets closer, the investment conversation usually changes.
The focus is no longer just on growth. It often becomes a balancing act between growth, income, risk, flexibility, and taxes.
That is why I created ***Model Portfolios for Pre-Retirees: Balancing Risk, Income, and Tax Surprises.***
This plain-English guide explains how thoughtful portfolios are often structured before retirement begins, and why a portfolio built for the accumulation years may need a fresh look as retirement approaches.
You can [access it here](https://lp.constantcontactpages.com/sl/2IaWQhU/RetirementInvestingReset):
---
**FAQ Section**
**What is the biggest investment change in retirement?**
The biggest change is that your portfolio often shifts from being primarily focused on growth to supporting withdrawals, managing risk, and helping provide sustainable income while still keeping up with inflation.
**Should retirees move most of their money into income investments?**
Not automatically. Income matters, but chasing yield can create new risks. A retirement portfolio usually still needs growth, diversification, and tax awareness rather than just higher payouts.
**Why does investment risk feel different in retirement?**
Because losses can hurt more when you are taking withdrawals. Selling investments during a downturn can reduce the portfolio’s ability to recover, especially in the early years of retirement.
**Does growth still matter after retirement?**
Yes. Retirement can last decades, and inflation continues to erode purchasing power. Most retirees still need some long-term growth in the portfolio.
**How do taxes affect retirement investing?**
Taxes can affect how much of your retirement income you keep. The type of account, timing of withdrawals, capital gains, required distributions, Social Security taxation, and Medicare premiums can all make a difference.
**Are model portfolios helpful for pre-retirees?**
Yes, as educational tools. They can help illustrate tradeoffs between growth, income, and risk. But they should not be treated as one-size-fits-all solutions.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Can AI Really Tell You If You’re Ready to Retire?](https://indfin.com/can-ai-really-tell-you-if-youre-ready-to-retire/)
**Published:** March 10, 2026
**Author:** Jim Lorenzen
**Excerpt:** AI can produce retirement answers in seconds. What it often misses are the blind spots that matter most: taxes, timing, risk, and real-life trade-offs, and there's something else....
**Content:**
**For many, especially those getting close to retirement decision time, money isn’t just about numbers –** it becomes emotional. For some, the accompanying stress can be paralyzing. Robots, AI, and software don’t understand – people do.
**Fast answers are easy. Thoughtful answers can be quite different**. AI can be fast – and useful – when used with the right purpose in mind. Without that, it often misses are the blind spots around taxes, timing, risk, and real-life decision-making.
If you are getting serious about retirement, AI can seem like a gift. Ask a chatbot whether you can retire at 62, when to claim Social Security, whether Roth conversions make sense, or how much you can safely spend each year, and you will get an answer almost instantly. Nothing wrong with that. Simple. Quick. That’s the attraction.
**It doesn’t reveal the problem:** AI looks for answers. Good retirement planning asks questions – It’s about looking for blind spots.
**Blind spots matter** – especially for those with significant assets approaching retirement. Fast answers are convenient; but they also can contain financial time bombs that can go off years later when tax brackets could look quite different.
When I first broke – some might say descended – into this line of work, the internet was in its infancy. Most everyone around me was a stockbroker and, in those days, the stockbroker was the source of information for clients seeking help (cable tv did have ‘top 10 fund manager’ entertainment lineups); however, today information is everywhere, bordering on information overload – more than a sane person wants to sort through. Stockbrokers have all but disappeared and fee-based financial planning has moved to the forefront as a profession whose main function now is informed guidance.
So, the real challenge is knowing which advice actually applies to your life, where the hidden tax traps are, and which decisions could quietly cost you money and/or flexibility later.
**AI can be helpful. It just cannot replace judgment.**
To be fair, AI does some things well.
It can explain retirement concepts in plain English. It can help you understand the [retirement planning process](https://indfin.com/ifgplanningprocess/), [Social Security](https://indfin.com/socialsecurity/), Medicare, Roth conversions, [withdrawal strategies](https://indfin.com/retirementplanning/), and [general investment principles](https://indfin.com/wp-content/uploads/2014/09/i307_RPT-Understanding-Investment-Returns.pdf). It can organize questions, summarize options, and make complicated topics feel less intimidating. That has real value.
For someone in the early stages of planning, AI can be a useful tool for getting oriented. It can help you ask smarter questions. It can help you sort through the noise and get a rough lay of the land. Good information – but information is not education.
An old professor once told me: education isn’t the mere acquisition of knowledge. the true measure of education is the ability to ask good questions.
So, accumulated information can be helpful; but, the true value is knowing what you don’t know – and knowing the value of questions.
So it follows: a real retirement plan is more than a list of answers. The right questions, however, can result in a coordinated strategy for income, taxes, investments, risk, and real-life decisions. It needs to reflect how you actually live, what you want your money to do, and what could go wrong if your assumptions are off.
Response is nice; but it’s not the same as perspective.
**Retirement planning is about the questions you did not think to ask.**
AI is designed to answer the question you put in front of it. That sounds useful, and sometimes it is. But retirement planning is rarely decided by one question alone.
You might ask, “Can I retire this year?” AI may take your account balances, a spending estimate, and an assumed rate of return and give you a neat answer. But did anyone ask whether your spending number is realistic for the first ten years of retirement, when travel, family support, and health care costs may all shift?
- Did anyone ask whether one spouse feels ready and the other is not quite there yet?
- Did anyone notice that retiring this year might create a valuable window for lower-taxes before required withdrawals begin?
- Did anyone test what happens if the market struggles early in retirement while you are drawing income from the portfolio?
It’s more about questions than fast answers. The reason is simple: good planning is not just about solving the visible problem. It is about spotting the one hiding in the rough before it costs you a stroke.
**Where AI often falls short**
For affluent pre-retirees, the biggest risks usually do not come from a lack of information. They come from incomplete questioning.
**AI only knows what you tell it. (remember GIGO?)**
If you leave something out, the answer you get can be off by quite a bit yet still sound polished and authoritative.
Maybe you forgot to mention company stock, rental income, a pension option, a large future expense, support for family members, or health concerns that may affect retirement spending. Maybe your estimate of what retirement will cost is more optimistic than realistic.
AI will still produce an answer, but that does not make the answer complete. Oh, yes, and by the way there’s something else to consider:
**AI is not accountable.**
This part gets overlooked. No regulatory requirements or oversight. AI simply mines the internet for information, which might be dated.
Retirement is not a multiple-choice quiz. Close enough is not especially comforting when the decision affects the next 20 or 30 years of your life.
**AI struggles with gray-area decisions.**
Some retirement questions are not purely mathematical.
- Should you retire now or work two more years?
- Should you delay [Social Security decisions](https://indfin.com/socialsecurity/) or claim sooner?
- Should you spend from taxable assets first or convert to Roth while income is temporarily lower?
- Should you pay off the mortgage or keep more liquidity?
- Should you give more to children now, fund charitable goals, or preserve flexibility?
Judgment calls all – involving taxes, family priorities, lifestyle goals, health, market risk, and peace of mind. The mathematically “best” answer may not always the best answer for your life.
**The blind spots that matter most**
For households with $1 million or more in investable assets, and depending on spending habits, retirement planning can be less about “Can I retire?” and more about “How do I retire well?” That is where blind spots can do the most damage.
**Tax blind spots**
This is one of the biggest planning issues for affluent retirees.
Two households can retire with similar portfolios and end up with very different after-tax results depending on how they draw income, manage gains, time Roth conversions, coordinate Social Security, and handle future required distributions. Example: The IRMAA lookback period is two years. Do you know what that is or what it might mean to your particular situation? AI probably won’t either.
A simple projection might show that the plan works. A good retirement plan asks whether the plan works efficiently. That is a different conversation. Because in retirement, what matters is not just what you have. It is what you get to keep.
That is why [tax ](https://indfin.com/rmds-the-retirement-tax-bill-most-people-dont-see-coming/)[planning in retirement](https://indfin.com/rmds-the-retirement-tax-bill-most-people-dont-see-coming/) deserves just as much attention as investment performance.
**Timing blind spots**
Timing matters more than many people realize. Retiring one year earlier may create a planning opportunity, or it may close one.
- Claiming Social Security too early may reduce future flexibility. The wrong strategy may penalize your spouse.
- Delaying certain moves may increase lifetime taxes.
- Pulling too much from investments during a weak market can create avoidable strain.
While AI can describe these ideas, it often does a weaker job of tying them together in a way that reflects your specific timing, assets, and goals.
**Behavior blind spots**
Even a strong plan can fail if it is not realistic for the people trying to follow it. That’s why it must be YOUR plan – not AI’s or an advisor’s (did I say that?).
Some investors say they can tolerate market declines until the market actually declines. Some couples seem aligned until one wants to spend freely and the other wants to put a padlock on the checkbook. Some retirees say they will cut spending later if needed, only to discover that “later” is harder than it sounded.
This is where human judgment – and plan stress-testing – matters.
A good advisor does not just build a plan that works in theory. A good advisor helps build one you can actually live with when turmoil happens – and it will.
**Where AI fits in**
AI is not the villain here. It is a tool. Used properly, it can help you learn, organize your questions, compare broad options, and prepare for a more productive planning conversation with your advisor – did I mention I’m available?
Think of AI like a rangefinder on the golf course. Helpful? Very. But it still does not know your swing, the wind, the lie, or whether you are feeling suspiciously confident about carrying the water. It also doesn’t know your back is sore and your golf balls have a mind of their own.
Useful tool. Terrible replacement for judgment.
**What independent fiduciary advice adds**
A fiduciary advisor should bring something more valuable than information: independent judgment in your best interest.
That means helping you answer questions like:
- Can your portfolio support your lifestyle without taking more risk than necessary?
- What is the most tax-efficient way to create retirement income?
- How should Social Security fit into the larger plan?
- What risks could hurt the surviving spouse if ignored?
- How should your investment strategy evolve as you move from building wealth to drawing from it?
- What opportunities exist now that may not exist five years from now?
That is where real planning lives.
For pre-retirees and recent retirees who want [independent guidance](https://indfin.com/your-advisor-jim-lorenzen-cfp-aif/), this matters. You want someone sitting on your side of the table, helping you see around corners, not steering you toward a product or a canned solution.
**The better question**
The better question is not, “Can AI tell me if I’m ready to retire?”
The better question is: What might AI miss about my retirement decision?
That question usually leads somewhere more useful.
Because the biggest retirement mistakes are often not obvious. [They hide in taxes](https://indfin.com/investment-philosophy/), timing, assumptions, behavior, and life changes. They hide in the places that do not fit neatly into a prompt box.
**Final thought**
AI can help you start the conversation. It can explain the basics and help you think more clearly about retirement.
But when the goal is to retire with confidence, reduce avoidable mistakes, and make smart decisions about income, taxes, and risk, AI alone is not enough. Good retirement planning is not about collecting answers. It is about asking questions – uncovering blind spots, weighing trade-offs, and building a strategy that fits your life.
If you have spent decades building wealth, this is the time to make sure your plan holds up where it matters most.
**Ready to take the next step?**
If you want an independent second opinion on whether your retirement plan is truly ready, visit my [Getting Started page](https://indfin.com/getting-started/). You will see how the process works, what to expect, and how to begin a thoughtful review of your retirement, tax, and income planning decisions.
**FAQ Section**
### **Can AI tell me if I’m ready to retire?**
AI can help with general retirement questions, projections, and education. But it cannot fully account for personal judgment, tax strategy, timing decisions, family dynamics, and real-life trade-offs.
**Is AI useful for retirement planning?**
Yes. AI can be useful for learning basic concepts, organizing questions, and comparing broad strategies. It works best as a tool to support planning, not as a replacement for personal advice.
**What does a fiduciary advisor add that AI cannot?**
A fiduciary advisor can ask the right questions – AI doesn’t do that – and provide personalized guidance, identify blind spots, coordinate tax and retirement income decisions, and help build a plan that reflects your goals, values, and real-life circumstances.
**Why do taxes matter so much in retirement planning?**
[Taxes can have a major impact](https://indfin.com/investment-philosophy/) on how much income you actually keep in retirement. Withdrawal order, Roth conversions, capital gains, Social Security timing, and required distributions can all affect long-term results.
**When should I get a second opinion on my retirement plan?**
A second opinion can be helpful if you are within a few years of retirement, recently retired, unsure whether your current plan is tax-efficient, or simply want independent guidance before making major decisions. It’s important to determine [your priorities](https://indfin.com/retirement-priority-planning-review/) (don’t worry – no sensitive information is needed and I won’t see your input unless you say it’s okay).
[Let me know](https://indfin.com/getting-started/ "Getting Started with IFG.") if I can be of help.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** AI - Artificial Intelligence, Retirement
**Tags:** Financial planning, retirement decisions, Retirement Planning, Retirement Strategy
---
### [RMDs: The Retirement Tax Bill Most People Don’t See Coming](https://indfin.com/rmds-the-retirement-tax-bill-most-people-dont-see-coming/)
**Published:** February 3, 2026
**Author:** Jim Lorenzen
**Excerpt:** Retirement planning isn’t just about how much you’ve saved—it’s about not getting clobbered with excess taxes later. Managing RMDs is key!
**Content:**
**RMDs Got a Makeover. Your Retirement Tax Plan Should Too.**
With SECURE Act 2.0 changing the RMD timeline, many pre-retirees and new retirees now have a longer runway before required withdrawals begin. That extra time can be valuable, but it can also concentrate taxable income later. A few common-sense adjustments now can help you avoid unpleasant surprises later.
**How do taxes have an impact on retirement?**
Let’s say you have one dollar. And let’s say you were able to double that dollar every year for twenty years. If you didn’t have to pay any taxes on the money, how much would you have at the end of that period? Answer: $1,048,576
Now, let’s say you have that exact same scenario, however, you had to pay 15% taxes. How much would you have at the end of that 20-year period? Answer: $220,513
Do you know what tax bracket you are in? Chances are it’s more like 25% and not 15%. If so, you would have $72,570 at the end of that 20-year period.
In summary:
Taxable at 25% = $72, 570
Taxable at 15% = $220,513
Tax Free at 0% = $1,048,576
If you’re a pre-retiree or newly retired, here’s the not-so-fun truth: **taxes often take more of your lifetime savings than people expect.** RMDs are one of the biggest reasons. If you start early enough, you may even be able to enjoy a tax-free retirement! You [can learn more about that here.](https://lp.constantcontactpages.com/sl/Jo4IAaT/4StepsTaxFreeRetirement)
SECURE Act 2.0 changed the timing of required minimum distributions (RMDs). That sounds like good news—because it can be. But the “delay” can also set you up for **larger forced withdrawals later**, which can mean **higher taxes** and **less flexibility** at the exact time you want more control.
**What changed under SECURE Act 2.0**
The starting age for RMDs moved:
- **Age 73** for people born **1951–1959**
- **Age 75** for people born **1960 or later**
So yes—you may have more time before RMDs kick in. But that extra time can also allow your tax-deferred accounts (traditional IRAs and 401(k)s) to grow larger. And larger accounts often lead to… you guessed it… **larger taxable RMDs**.
**Why “later RMDs” can backfire**
When RMDs start later, the withdrawals can be more concentrated. That can create income spikes that ripple through your entire plan.
Here’s what those spikes can affect:
- **Your tax bracket** (obviously)
- **How much of your Social Security becomes taxable**
- **Medicare premium surcharges (IRMAA)** if income crosses certain thresholds
- **Your ability to do tax-smart moves later** because the “room” in lower brackets is gone
In plain English: delaying RMDs can feel like postponing a bill… only to get a bigger bill later.
**Why this matters even more heading into 2026**
After a strong market stretch, many retirees are entering 2026 with retirement **account balances that are meaningfully higher than they expected** a few years ago.
That’s great—until the IRS starts forcing larger withdrawals. Remember, tax-deferred really means tax-delayed – at who knows what brackets will be in place when the time comes.
A simple example shows the idea:
- A **$1,000,000** retirement account at the end of 2023
- Earning **15% annually** (hypothetical) and taking required withdrawals along the way
- Could grow to roughly **$1.33 million** by the end of 2025
Now here’s the part people miss: the RMD isn’t growing a little — it can grow a lot! In your example, it jumps from roughly **$40,650** to **$60,748** over that period.
And that’s just one $1M account. Plenty of households have multiple accounts, plus pensions, plus Social Security.
That’s how taxes quietly become one of the biggest “expenses” in retirement.
**The real goal of RMD planning**
A lot of people treat RMD planning like a math problem: “What’s the minimum I have to take?”
That’s step one. But it’s not the strategy. *‘Minimum’* probably shouldn’t be your focus.
**Good RMD planning is about shaping taxable income over time**—so you don’t create big spikes later that lead to higher taxes and higher Medicare costs.
Or said another way: it’s not about how long you can avoid withdrawals. It’s about avoiding the retirement version of a triple-bogey that can ruin the entire 18-hole score: one big year that creates damage across multiple areas and for life!
**Common-sense ways to reduce future RMD pain**
The best solutions aren’t flashy. They’re mostly about timing and coordination.
Some examples that often help (depending on your situation):
- **Roth conversions in lower-income years** (partial, staged, intentional—not “all in”)
- **Using taxable accounts earlier** in retirement to reduce future tax-deferred balances
- **Coordinating withdrawals across account types** (taxable / tax-deferred / Roth) so income stays steadier
- **Planning around Social Security and pensions** so RMDs don’t pile on top
Done right, these steps can reduce future RMDs and smooth out taxes over your retirement years—usually the difference between “manageable” and “why is my tax bill doing that?”
**Pro tip**; **RMD planning is not about delaying distributions as long as possible.**
It’s about preventing taxable-income spikes that trigger higher taxes (including on Social Security) and Medicare surcharges.
You don’t need hero shots. You need fewer unforced errors.
**So, taxes matter.**
The amazing thing about it is that virtually anyone, if they begin early enough, can strategize a tax-free retirement.
There’s information about this, as well as a lot of other topics, in my monthly newsletter. And, new subscribers will receive a copy of ***4 Steps to a Tax Free Retirement.*** There’s no obligation, of course – no one will be calling you – and you can cancel at any time. [You can get your copy by subscribing here](https://lp.constantcontactpages.com/sl/Jo4IAaT/4StepsTaxFreeRetirement).
Tell me [your priorities](https://indfin.com/retirement-priority-planning-review/), then [schedule an introductory call](https://go.oncehub.com/JimLorenzenCFP)! You can [also subscribe to my newsletter.](https://lp.constantcontactpages.com/sl/Jo4IAaT/4StepsTaxFreeRetirement)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Retirement, SECURE Act, Taxes
**Tags:** retirement decisions, retirement mistakes, RMDs, tax planning
---
### [Can AI Tell Me When I Can Retire?](https://indfin.com/can-ai-tell-me-when-i-can-retire/)
**Published:** December 8, 2025
**Author:** Jim Lorenzen
**Excerpt:** It’s a typical question posed to AI. The simple answer is it cannot, by itself, answer the big one people are asking more often: Can AI Tell Me When I Can Retire?
**Content:**
Why not? Artificial intelligence (AI) must have some value, so let’s unpack it.
**Why people are asking AI if they’re ready to retire**
If you’ve typed something like “Can I retire with $1.2 million?” into an AI tool or calculator, you’re not alone. It’s fast, it’s anonymous, and it feels “smart.” In a world where AI can pass exams and write code, it’s tempting to think it can give you a clean yes/no on retirement.
But, can AI tell me when I can retire?
But retirement is not a math quiz. It’s closer to playing a long, unfamiliar golf course in the wind. Course management matters.
- The yardage matters, of course;
- The club you pick matters, naturally;
- But so do the trees, the bunkers you *don’t* see, and whether you tend to yank your driver out-of-bounds when you’re tense or nervous.
AI is very good at the yardage. It’s not so good at reading the wind in your life.
**What AI is actually pretty good at**
Let’s give AI its due. Used wisely, it can be a very helpful assistant in retirement planning:
**1. Crunching numbers quickly**
AI and online tools can help you:
- Build rough retirement projections
- Compare Social Security claiming ages
- Estimate how long a portfolio *might* last under different return assumptions
- See the impact of saving a bit more or spending a bit less
If you give it decent inputs, it can give you a reasonable set of ballpark scenarios.
**2. Explaining concepts in plain language**
AI can be good at turning jargon into English:
- What’s a required minimum distribution (RMD)?
- How does Medicare enrollment work?
- What’s the difference between Roth and traditional?
It can help you get educated so you’re not walking into a meeting with an advisor totally cold.
**3. Organizing information**
You can ask AI to:
- Summarize your 401(k) options
- Draft a list of questions to ask a financial planner
- Help you compare pros and cons of working part-time in retirement
Think of it as a solid research assistant that never gets tired and doesn’t roll its eyes at “one more question.” Used this way, AI is genuinely useful.
The trouble starts when people go from “this helps me think” to “this will decide for me.”
**Where AI falls down on “Am I ready to retire?”**
Here’s where the wheels start to wobble.
**1. It doesn’t really know *you***
AI doesn’t see:
- Your spouse’s health worries
- Your life expectancy, as well as your spouse’s
- Your financial and tax situation impacting the outcomes of your decisions ten to twenty years in the future
- Your risk capacity vs your risk tolerance – your tendency to panic and sell when markets get ugly
- The way you’ll feel watching your portfolio swing when you no longer have a paycheck
Two couples with the *exact* same numbers might need totally different answers:
- One sleeps fine with market volatility.
- One lies awake if the market drops 5%.
- One has a distribution strategy based on a twenty-year plan
- One makes an irrevocable decision based on something posted on the web.
AI can’t reliably measure your emotional risk tolerance or your “sleep-at-night” score. It also can’t provide insightful guidance when relevant information is missing.
**2. It’s only as good as the inputs (and most people guess)**
Retirement projections depend on things like:
- Future spending (most people underestimate lifestyle costs)
- Longevity (you might live to 75… or 95+)
- Health care costs
- Taxes, which change and vary by state – and can change drastically over time
- Investment returns, which are never a smooth straight line
- Inflation, which can change over decades – something few stress-test
Most people plug in rough guesses:
“Yeah, we’ll spend about what we do now.”
“Let’s assume 7% returns every year.”
AI will happily calculate based on those guesses, but it can’t tell you if they’re realistic or dangerous. No news there: “Garbage in, garbage out”.
**3. It doesn’t see the landmines**
AI can explain tax rules. It’s more likely to miss how they interact with *your* situation, such as:
- Triggering higher Medicare premiums (IRMAA)
- Accidentally bumping you into a higher tax bracket with big Roth conversions
- Timing Social Security with pensions and spousal benefits
- Coordinating withdrawals from IRAs, Roths, taxable accounts, and employer plans in a tax-smart order
It can give you “generic best practices.”
It struggles with, “Given your mix of accounts, your ages, your state, and your goals, here’s the smarter way to draw down.”
**4. It doesn’t take responsibility**
If AI tells you, “Yes, you’re on track,” and it turns out you weren’t… who’s accountable? No one.
A qualified human advisor, especially a fiduciary, has skin in the game. His/her name, license, and reputation. No one can predict the future, but a fiduciary advisor knows how to plan for the things we don’t know and help keep your plan on-track.
**How a fiduciary advisor adds value where AI can’t**
So if AI does the math, what’s left for a human? Quite a bit.
**1. Turning “numbers” into “a life you can live”**
A fiduciary advisor’s real job is **not** to impress you with charts. It’s **to translate**:
- “You have $1.3 million, Social Security at 67, and maybe a part-time job”
into
- “You can retire next year if you’re comfortable spending $X per month, taking two trips a year instead of four, and maybe downsizing the house in 10 years.”
The point is it’s not purely math. It’s judgment, trade-offs, and prioritizing what actually matters to *you*. And, happily, I’ve seen clients who actually have greater freedom than they thought – they actually could spend more, if they wanted to.
**2. Challenging your blind spots**
Everyone has blind spots:
- “We’ll definitely spend less in retirement.” (A common false assumption, especially in retirement’s early go-go years.)
- “I’ll just work a little longer if I need to.” (Health or layoffs may disagree – stuff happens)
- “My kids won’t need help.” (Then grandkids show up and college costs start.)
AI does not have decades of experience working with real people in the real world. AI is not going to look you in the eye and say, “That assumption may be a bit optimistic. Let’s re-work some worst-case assumptions and see how it looks.”
A fiduciary advisor will.
**3. Coach you through bad markets**
This is a big one.
The math says: “Stay invested. Don’t sell low.” Human nature says: “Get me out of this right now.” In a brutal bear market, AI can spit out all the right words about staying the course. It cannot take your phone call when you’re staring at a 20–30% drop and wondering if you’ve just ruined retirement.
Side note: I must have a lot of smart clients. During the 2008-9 market melt-down (remember that one?), my phone never rang; but then, every client’s plan had been through stress-testing and weren’t surprised by the event or worried about it’s impact on their future.
A good advisor:
- Helps you keep your plan current and provides education.
- Prepares stress-tested temporary declines into your plan as well as what they *actually* mean for your long-term odds
- Helps you keep your plan current with measured adjustments instead of emotional lurches
My experience is that more people are hurt by their behavior than by their investments. That behavior gap is where a lot of lifetime return is gained or lost.
**4. *Integrating* all the moving parts**
AI answers questions one at a time:
- “Should I take Social Security at 62 or 70?”
- “Should I do a Roth conversion?”
- “Should I pay off my mortgage?”
AI can provide information; but a fiduciary advisor stitches all of those together into one coordinated tax-optimized strategy, based on your unique financial situation. For example:
- Maybe you delay Social Security, draw from IRAs first, and do partial Roth conversions between 62 and 70 to reduce future RMDs and taxes on your surviving spouse.
- Maybe you don’t pay off the mortgage yet because your liquidity and tax situation argue for a slower pay-down.
AI can outline the options. The advisor helps you choose and sequence them intelligently.
**5. Updating the plan as life happens**
Retirement isn’t “set it and forget it.” Things change:
- Markets
- Tax law
- Inflation
- Health
- Family dynamics
- Your own goals
AI will answer whatever you ask in the moment. Can AI Tell Me When Can I Retire? As you may have guessed by now, it does fall short.
A fiduciary advisor might say, “Your portfolio’s up, RMDs start next year, and tax law is always subject to change, based on the government’s debt. Let’s take a look at a few scenarios to see what options are available to you.
That ongoing monitoring and proactive adjustment is the ongoing real value.
**How to use AI *and* an advisor together (instead of either/or)**
The smart move isn’t “AI or human.” It’s “AI + the right human.”
Here’s a practical way to combine them:
1. **Use AI to get educated.**
Learn the basics: how Social Security works, what RMDs are, how different withdrawal strategies compare in theory. Note: your advisor may have a treasure-trove of informative articles available – just ask!
2. **Use AI to draft your questions.**
Show up to a fiduciary advisor with a sharper list:
- “Can we stress-test retiring at 64 instead of 67?”
- “If we do Roth conversions, how do we avoid pushing Medicare premiums up?”
- “What’s our plan if we hit a bad market in the first five years?”
3. **Let the advisor stress-test and customize.**
Ask them to:
- Challenge your assumptions
- Run worst-case and not-so-rosy scenarios
- Explain the trade-offs in plain English
4. **Ask how they get paid and whether they’re a fiduciary 100% of the time.**
It’s been almost a cliché – advisors love to yak about being a fiduciary. Here’s where the rubber meets the road and you can find out if it’s real or just a lot of talk. Ask your advisor:
**“Are you willing to put your fiduciary status in writing –** **stating that you are a fiduciary for all your services, whether for financial planning or investment selection?”** Note: I furnish this to all clients.
AI can help you feel prepared. A true fiduciary advisor helps you feel confident.
**The bottom line**
AI is a powerful tool. It can:
- Speed up the math
- Explain complex topics
- Help you organize your thoughts
But it cannot:
- Truly know your fears, habits, and goals
- Take responsibility for the plan
- Coach you through real-world stress
- Integrate taxes, investments, family, and law into one coherent strategy tailored to *you*
So, can AI really tell you if you’re ready to retire? On its own, no. It can give you a first draft.
A qualified fiduciary advisor helps you turn that draft into a plan you can actually live with, through good markets and bad.[ **Learn about IFG!**](https://indfin.com/video-library-2/)
I hope this helps.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** AI - Artificial Intelligence, Investing, Planning, Retirement, Retirement Income, Taxes
**Tags:** AI, Financial planning, Investment Strategy, retirement decisions, Retirement Planning, Retirement Strategy
---
### [What a Million Dollar Retirement Really Buys](https://indfin.com/what-a-million-dollar-retirement-really-buys/)
**Published:** December 1, 2025
**Author:** Jim Lorenzen
**Excerpt:** Think a million dollars guarantees an easy retirement? See what a $1M portfolio really buys today, how far it goes in real life, and why your plan matters more than the number.
**Content:**
Short answer: A million dollar portfolio buys you options, flexibility, and a serious shot at a comfortable retirement. **It does not buy a lifetime “set it and forget it” fantasy.**
If you think of retirement as a long par 5, a seven-figure portfolio means you’re safely in the middle of the fairway. Nice drive. But how you play the next shots still decides the score. And, don’t forget, in golf the game is played from 100 yards in. That’s where strokes are most often lost – and, it can happen in retirement, too.
What a Million Dollar Retirement Really Buys? This post will walk through:
- What a million dollar retirement portfolio actually translates to in income
- What a seven-figure retirement really feels like day-to-day
- How far $1M goes in a place like Simi Valley or Moorpark, CA
- Why AI tools and online calculators don’t tell the whole story
- Practical next steps if you’re a $1M+ investor
**What Does a $1M+ Portfolio Actually Mean in Retirement?**
Let’s translate a million dollars into something more useful: **spendable income.**
A common starting point in retirement research is withdrawing around **3–4% per year**, then adjusting over time. It’s not a promise, just a reasonable planning yardage. It’s good to get yardage (and wind direction) before pulling a club.
Roughly:
- On **$1,000,000**, 3–4% is about **$30,000–$40,000 per year**
- On **$2,000,000**, 3–4% is about **$60,000–$80,000 per year**
Now add **Social Security**, which for many couples can be another **$40,000–$60,000+** combined. That puts you in a realistic range of:
- About **$70,000–$100,000+ per year** with a $1M portfolio
- About **$100,000–$140,000+ per year** with a $2M portfolio
That’s before we talk about taxes, healthcare, housing and debt, and how long you and your spouse might live. Don’t forget inflation – we’ll be getting to that.
So when you ask, **“Is $1 million enough to retire comfortably today?”**, the honest answer is: It can be—but it depends heavily on what life you expect that money to support. Remember, Elvis made millions but spent more.
**Four Things a $1M+ Retirement Really Buys**
**1. Options, Not Guarantees**
The real value of a seven-figure portfolio is **choice**. With a $1M+ portfolio:
- You *can* retire, but maybe not at the Instagram version of retirement
- You *can* scale back or change careers instead of grinding full-time
- You *can* choose how much investment risk to take, instead of gambling just to “catch up”
This is what **real life retirement with a 1 million dollar portfolio** looks like: You get to design your lifestyle intentionally, instead of having it dictated to you. It’s options, not a guarantee that you never have to think about money again.
**2. Flexibility When Life Doesn’t Go to Plan**
Your $1M+ portfolio does more than fund travel and dinners out. It buys **flexibility** when life surprises you:
- Helping adult kids or grandkids during a tough season
- Covering a big medical expense without blowing up your plan
- Replacing a roof, car, or HVAC system without panic
- Pivoting from “full retirement” to “semi-retirement” on your terms
Without assets, these are crises. With assets, they’re problems that can be managed.
**3. A Cushion Against Inflation, Taxes, and Market Risk**
Think of it this way: inflation is the slow leak in the retirement tires. Taxes are the potholes. Markets are the weather.
A $1M+ portfolio gives you more tools to handle all three:
- You can mix taxable, tax-deferred, and tax-free accounts and use tax-smart withdrawal strategies for $1M+ retirees instead of just yanking money from the same account every year
- You can stay invested in a way that has a decent chance to keep up with inflation, instead of hiding entirely in cash
- You can hold some reserves and safer assets to reduce the impact of bad markets early on
One under-appreciated issue here is sequence of returns risk in retirement income. If markets are ugly in your first 5–10 years of retirement, the damage can be much worse than the same downturn later on. That’s why how you invest and withdraw in those early years matters a lot more than people think. Remember, it’s the last 100 yards that can kill a game plan.
**4. The Ability to Design a Legacy, Not Just Leave Leftovers**
Once your own lifetime income needs are reasonably covered, you can start designing a legacy with a $1M retirement portfolio instead of just hoping there’s something left over.
That might mean:
- Leaving money to kids or grandkids with guardrails, not just a lump sum
- Supporting charities or causes you care about in a tax-efficient way
- Reducing the odds of family conflict and delays by getting the structure right
With no plan, even a large estate can turn into a mess. With a plan, you can live well *and* leave well.
**What a $1M+ Portfolio Does *Not* Automatically Buy**
Okay, maybe it’s time to pop a few myths.
**1. It Does Not Buy “Never Worry About Money Again”**
When I was a kid, being a millionaire meant something. Now, even with a seven-figure portfolio, you still need to:
- Make choices about lifestyle and spending
- Decide how much volatility you can actually handle
- Monitor your plan and adjust when markets, taxes, or life change
If you achieve a $1M+ portfolio and assume you never have to think about this again, you’re almost assuredly setting yourself up for an unwelcome surprise.
**2. It Does Not Buy Protection from Every Market Storm**
We can’t control the weather. If your internal plan sounds like “We’ll just earn 8–10% every year, withdraw 5%, and we’re good.” …that’s not a plan. That’s a wish.
Markets are lumpy. Some decades are generous. Some are flat. Some are ugly.
Your withdrawal rate, investment strategy, and risk management matter **more** when you’re retired than when you’re working, because you’re pulling money out while the market is bouncing around. It’s what’s called sequence-of-returns risk.
You’re not trying to win a driving contest here. You’re trying to make sure you have enough golf balls to finish the round. Remember, the game is played inside 100 yards (it’s worth repeating).
**3. It Does Not Buy Unlimited Healthcare or Long-Term Care**
Medicare is **not** free. Long-term care is definitely not free.
Even with a $1M+ portfolio, you still have to plan for:
- Medicare premiums and possible income-based surcharges
- Supplemental coverage and out-of-pocket costs
- The possibility that one of you might need assisted living, memory care, or in-home care for several years
Your assets give you more **options** to handle these costs, but if you ignore them entirely, they can still derail an otherwise solid plan.
**4. It Does Not Buy Unlimited Help for Adult Children**
This is a quiet one, but important.
Helping adult children with down payments, business ideas, or debt can be a great gift. But if your $1M+ portfolio quietly becomes a family ATM with no boundaries, it’s easy to over-give while you’re still feeling “young and fine” and regret it later.
Your portfolio gives you the **ability** to help. It doesn’t obligate you to say yes to everything. Oh, yes, I almost forgot: golf courses tend to place most hazards inside 100 yards – that’s where they are in retirement, too.
**How Far Does $1M Really Go in Simi Valley and Moorpark, CA?**
The question isn’t just **“What a $1 million retirement really buys?”** It’s **“What does that $1M buy where I actually live?”**
Same numbers, different zip code, very different result.
In a higher-cost area like **Simi Valley or Moorpark, CA**:
- Housing, property taxes, and general cost of living are higher than many parts of the country
- A $1M portfolio plus Social Security might support a **comfortable** lifestyle, but with some trade-offs on travel, cars, or gifting
- The question **“Is $1 million enough to retire in California?”** is really about the *version* of retirement you want
In a lower-cost state, that same $1M might fund:
- A more relaxed lifestyle with more “extras”
- Potentially earlier retirement or more time off work
- Less monthly pressure, especially if housing costs are lower
The portfolio is the club in your hand. The cost of living is the course you’re playing. You might shoot par—but each course, each hole, will require a different strategy – and there’s more than one way to hit each club. It helps to know where the hazards are.
**Retirement Planning in the Age of AI**
We’re now in a world where you can:
- Ask an AI chatbot, “Can AI tell you if 1 million is enough to retire?”
- Use an AI retirement calculator vs human advisor comparison tool
- Plug your numbers into a dozen free online calculators in one afternoon
All of that is fine—as long as you understand the limitations. One challenge is knowing all the questions to ask. Sometimes, it’s the unasked question that creates the biggest problems.
AI and calculators are strong at doing math, projecting scenarios, and showing you a range of outcomes
Where they are weak:
- Knowing how you actually behave when markets drop 25%
- Understanding how you and your spouse *really* feel about risk and spending
- Judging whether you’ll actually move, downsize, or keep working part-time
- Balancing money decisions with family dynamics and health issues
In other words, retirement planning in the age of AI is less about getting a robust calculator – those are everywhere – and more about stress-testing your real life:
- Translating a seven-figure portfolio into monthly income that fits how you live now
- Adjusting for inflation, taxes, and nasty market sequences
- Updating the plan as your life evolves
AI is a tool. It’s not a retirement strategy. Think of it as a club; but it won’t keep you out of the hazard. A good caddy may be more valuable.
**If You’re in the $1M+ Club, Here’s What to Do Next**
If you have—or are approaching—a seven-figure nest egg and you’re within about 10 years of retirement (or already there), here’s a practical playbook.
**1. Know Your Real Lifestyle Number**
Not the “back of the napkin” guess. The real number.
- What does it cost, after tax, to live your version of a good life for a year?
- What changes if you travel a bit less… or a bit more?
- What if you paid off the mortgage or downsized?
- What if the markets have a melt-down the month after you retire?
- What if inflation doubles in your second decade of retirement?
Knowing the questions and ‘gaming out’ the scenarios is step one in **translating a seven-figure portfolio into monthly income** you can actually live on.
**2. Map Your Income Sources**
Put it all on one page:
- Social Security (for each spouse, and when you plan to claim)
- Any pension or rental income
- Expected portfolio withdrawals
This is the foundation of **retirement planning for $1M+ investors**—seeing how all the pieces work together, not just staring at account balances.
**3. Stress-Test Your Plan**
Run “what if” questions:
- What if markets are flat or ugly for the first 10 years?
- What if inflation is higher than we’re used to?
- What if one of you lives to 95+?
This is how you stress test your retirement plan before life does it for you.
**4. Get Intentional About Taxes**
For a $1M+ retiree, taxes can quietly become one of the biggest lifetime expenses.
Questions worth answering:
- Which accounts do you tap first—and why?
- Does a Roth conversion strategy make sense for your situation, or not? Have you run the numbers?
- Should you claim Social Security early and preserve your IRA assets? – or, should you draw down your IRA and wait to claim Social Security? Have you run the numbers factoring in returns and inflation adjustments?
- How will Required Minimum Distributions impact taxes on Social Security in your tax bracket? How about your Medicare premiums?
The goal is simple: more of your money stays with you and your family instead of drifting away in unnecessary tax.
**5. Clarify Your Legacy and “Enough” Number**
Two big questions:
1. How much do you legitimately need to feel secure for life?
2. Beyond that, what impact do you want your money to have—for family, charity, or both?
Once you’re clear on those, designing your legacy becomes much easier and far less emotional.
**Curious What *Your* $1M+ Retirement Really Buys?**
Online calculators and AI tools can give you quick numbers. What they can’t do is tell you what a seven-figure retirement will actually feel like in your real life, in your real city, with your real trade-offs.
If you’d like a clear, plain-English look at:
- How much income your $1M+ portfolio could reasonably support
- How far it’s likely to go in Simi Valley, Moorpark, or elsewhere in California
- The key risks that could knock your plan off track—and how to manage them
…then it may be worth having a real conversation. [Learn about IFG](https://indfin.com/video-library-2/)! Subscribe to my newsletter!
You can [get started here](https://indfin.com/getting-started/)!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Inflation, IRAs, Planning, Retirement, Retirement Income
**Tags:** Financial planning, Investment Strategy, managing risk, Reducing Risk, retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy
---
### [What the New Tax Bill Could Mean to You.](https://indfin.com/what-the-new-tax-bill-could-mean-to-you/)
**Published:** November 17, 2025
**Author:** Jim Lorenzen
**Excerpt:** Curious? Well here's a brief overview of the new tax bill.
**Content:**
No weeds, just an overview that will help you list the items you may want to discuss with your financial advisor and tax professional.
Here’s a ‘handout’ you can use, too.
[OBBB-Handout-081425](https://indfin.com/wp-content/uploads/2025/11/OBBB-Handout-081425.pdf)[Download](https://indfin.com/wp-content/uploads/2025/11/OBBB-Handout-081425.pdf)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Should I Do a 401(k) to IRA rollover? ](https://indfin.com/should-i-do-a-401k-to-ira-rollover/)
**Published:** November 10, 2025
**Author:** Jim Lorenzen
**Excerpt:** Here are some rules to check Before You decide.
**Content:**
**What Is a 401(k) to IRA Rollover?**
When you leave a job or retire, whether here in Simi Valley, Moorpark or anywhere else, you have a decision to make with that old 401(k). One popular option is a 401(k) to IRA rollover, where you move your balance from the employer plan into an individual retirement account (IRA).
On paper, it’s simple: open an IRA, tell the 401(k) provider to send the money over, done. In real life, there are rules that can help—or hurt—your taxes, creditor protection, flexibility for heirs, and access to your money.
The question isn’t “*Can* I roll over?” It’s: “*Should* I roll over my 401(k) to an IRA, or *should* I stay put?” Especially if this is money you’re counting on to fund your retirement.
**Should I Roll Over My 401(k) to an IRA or Stay in My 401(k)?**
You really have six – yes, SIX! – options available to you when you leave an employer.
Rolling everything into an IRA can simplify life and make it easier to manage your retirement income plan in Simi Valley or Moorpark, but it’s not automatically better.
To learn more about all six options, you might like these short videos which address each option:
1. [Leave your money in your current plan](https://vimeo.com/919700051/7b737bab00?share=copy)
2. [Move your money to your new employer’s plan](https://vimeo.com/920114129/0c2b47679f?share=copy)
3. [Roll your money into an IRA](https://vimeo.com/920143551/d626474dc1?share=copy)
4. [Take a lump-sum distribution of all your money](https://vimeo.com/920518130/bc3869cfd0?share=copy)
5. [Convert plan assets to a Roth IRA](https://vimeo.com/920533438/7ec240929c?share=copy)
6. [Make an in-plan Roth conversion](https://vimeo.com/920545311/9ac36bd94d?share=copy)
Before you move a dollar, walk through the following rules.
**401(k) vs IRA Creditor Protection**
Most employer 401(k) plans are covered by ERISA, which generally provides strong protection from creditors and lawsuits. In many cases, that money is off-limits to general creditors.
IRAs are different:
- In bankruptcy, rollover IRAs get unlimited protection and contributory IRAs get a large federal protection cap (adjusted for inflation).
- Outside bankruptcy, IRA protection depends on California law (and/or the state where you live). Some states protect IRAs fully; others cap protection or use vague “reasonably necessary” language.
If you’re a physician, business owner, again, whether in Simi Valley, Moorpark, or anywhere else where lawsuits are a real risk, 401(k) vs IRA creditor protection *may* be a big reason to leave at least some money in the plan.
This is a “talk to your attorney” item, not a guess.
**Early Withdrawal Rules at 55 vs 59½**
Take money out before 59½, and the IRS usually adds a 10% penalty on top of income tax—unless you qualify for an exception.
Some key exceptions are 401(k)-only:
- Age 55 separation-from-service rule (or age 50 for certain public safety employees): if you leave your job in or after the year you turn 55, that specific 401(k) may allow penalty-free withdrawals.
- Certain distributions under a Qualified Domestic Relations Order (QDRO).
Some exceptions are IRA-only:
- Qualified higher-education expenses
- Qualified first-time homebuyer expenses (up to $10,000 lifetime)
- Health insurance premiums while unemployed
If you’re planning to retire between 55 and 59½ and may need that money, rolling everything to an IRA could cost you the age-55 break. On the other hand, if your bigger needs are education costs, a first home, or unemployment health premiums, an IRA may be more helpful.
**Inherited 401(k) vs Inherited IRA Flexibility**
Both inherited 401(k) accounts and inherited IRA accounts are subject to IRS required minimum distribution (RMD) rules for beneficiaries. The difference is how much extra restriction the plan adds.
Many 401(k)s:
- Offer limited payout options
- Impose deadlines that can force a lump sum more quickly than the tax rules require
IRAs generally follow the IRS inherited IRA rules without extra plan-level deadlines. For non-spouse beneficiaries (adult children, for example), an inherited IRA often gives more time and more control over how and when to take taxable distributions.
If you want your kids or other heirs to have flexibility (and not be forced into a big tax bill in year one), review your current plan’s beneficiary rules and consider whether an IRA might be a better long-term home.
**RMDs and the 401(k) Still-Working Exception**
Under current 401(k) to IRA rollover rules 2025, most people must start RMDs from traditional IRAs and most 401(k)s at age 73 (with the age scheduled to increase for younger cohorts).
But 401(k)s have a wrinkle. Your plan may let you delay RMDs from that current 401(k) until you retire.
- If you’re still working for the company sponsoring the 401(k),
- And you own less than 5% of that company,
IRAs do not get this “still-working” exception. You must start RMDs from traditional IRAs at your required age whether you’re working or not.
If you plan to keep working into your 70s and want to delay RMDs as long as possible, that’s a point in favor of keeping money in the current employer’s 401(k) instead of rolling everything to an IRA.
**What Happens to Company Stock in a 401(k) Rollover?**
If your 401(k) holds employer stock, rolling it to an IRA can quietly destroy a valuable tax break called Net Unrealized Appreciation (NUA).
Very simply:
- With a qualifying distribution, you may be able to take employer stock out of the 401(k) in kind.
- You pay ordinary income tax only on the cost basis.
- The gain inside the plan (the NUA) is taxed later at long-term capital gains rates—often lower than your income rate.
If you roll that company stock into an IRA, the NUA opportunity is gone; everything gets taxed as ordinary income when it eventually comes out of the IRA.
If you have a lot of company stock with big gains, don’t touch a 401(k) to IRA rollover until you’ve run the NUA math and looked at how it fits into your broader retirement plan. This report might prove helpful.
[i303\_Best and Worst IRA Rollover Decisions](https://indfin.com/wp-content/uploads/2025/11/i303_Best-and-Worst-IRA-Rollover-Decisions.pdf)[Download](https://indfin.com/wp-content/uploads/2025/11/i303_Best-and-Worst-IRA-Rollover-Decisions.pdf)
**401(k) Loans, Fees, and Investment Options**
Living in Simi Valley or Moorpark can be expensive. Your retirement dollars have to stretch through retirement at California prices. How you handle loans, fees, and investment choices matters.
**401(k) loans (401(k)-only feature)**
IRAs don’t allow loans. Some 401(k)s do. If you leave with an outstanding 401(k) loan, you’ll usually have a short window to repay it. If you don’t, the unpaid balance is treated as a taxable distribution and may be penalized.
If you’re in a fragile cash situation, losing access to 401(k) loans is a factor to consider before you roll everything out.
**401(k) vs IRA fees and advice**
Some large 401(k) plans have:
- Access to very low-cost institutional share classes
- Minimal account fees
- But only generic tools and call-center “advice”
IRAs can be:
- Extremely inexpensive if properly designed. Costs can be important; but value is critical.
- More expensive if you hire a fiduciary advisor—but in that case, the fee is paying for personalized planning and investment management, including Social Security planning, tax strategies, and more almost always unavailable within a 401(k) plan – not just a list of funds. And, as money is later withdrawn to taxable status, the difference between tax-managed and non-tax-managed investing can be substantial.
[](https://indfin.com/wp-content/uploads/2025/11/Impact_of_taxes.png)Also, the financial planning component can help avoid mistakes that can be costly and some irreversible. Like my dad once said, “Some people know the cost of everything and the value of nothing.” Don’t be one of them.
The proper comparison isn’t “free vs not free”; it’s total cost vs value received, especially when you’re making retirement decisions that affect the next 20–30 years. This checklist may help.
[i308a\_IRA Rollover Checklist](https://indfin.com/wp-content/uploads/2025/11/i308a_IRA-Rollover-Checklist.pdf)[Download](https://indfin.com/wp-content/uploads/2025/11/i308a_IRA-Rollover-Checklist.pdf)
**401(k) vs IRA investment options**
Most 401(k)s offer a limited menu: a few mutual funds and target-date funds. IRAs open up:
- Individual stocks and bonds
- ETFs and a wide range of mutual funds
- Sometimes additional asset types, if appropriate
If you want more control over asset mix, tax efficiency, or coordination across multiple accounts (spouse’s plan, old 403(b), etc.), that broader IRA toolkit is a real advantage.
Here’s some information on tax efficiency.
[i106\_Investment Services Team Suite of Services](https://indfin.com/wp-content/uploads/2025/11/i106_Investment-Services-Team-Suite-of-Services.pdf)[Download](https://indfin.com/wp-content/uploads/2025/11/i106_Investment-Services-Team-Suite-of-Services.pdf)
**Quick 401(k) to IRA Rollover Comparison and Your Personal Assessment**
Before you decide to roll over your 401(k) to an IRA, ask:
- How important is 401(k) vs IRA creditor protection for my situation?
- Will I need access to this money between 55 and 59½?
- What rules will my beneficiaries face if they inherit this account?
- Do I hold highly appreciated company stock, and have I reviewed NUA options?
- Am I likely to keep working past RMD age, and does my 401(k) offer the still-working exception?
- Do I rely on 401(k) loans today—or might I?
- How do fees, advice, and investment options in my 401(k) compare with a good IRA solution?
You might find this comparison chart helpful. You can also perform your own suitability assessment.
[](https://indfin.com/wp-content/uploads/2025/11/401K-v-IRA.jpg)[i105b\_Rollover Checklist Worksheet Assessment](https://indfin.com/wp-content/uploads/2025/11/i105b_Rollover-Checklist-Worksheet-Assessment.pdf)[Download](https://indfin.com/wp-content/uploads/2025/11/i105b_Rollover-Checklist-Worksheet-Assessment.pdf)
If you do roll over, use a direct trustee-to-trustee 401(k) to IRA rollover so the money never passes through your hands and you avoid unnecessary withholding and timing traps.
**401(k) to IRA Rollover FAQs for Simi Valley and Moorpark Residents**
**Is a 401(k) to IRA rollover always a good idea?**
No. Nothing is ALWAYS a good idea. It’s often a good idea for investment flexibility and consolidation, but you can give up useful 401(k) features like stronger creditor protection, early-access rules, the still-working RMD exception, or NUA opportunities on company stock.
That’s why you walk through the above points and assessment above before you decide. You may also want to [talk with a fiduciary advisor](https://indfin.com/getting-started/).
**Will I owe tax when I roll over my 401(k) to an IRA?**
If you roll a traditional 401(k) to a traditional IRA via direct rollover, you usually don’t owe tax at the time of the rollover. Roll to a Roth IRA, and you’re doing a taxable conversion.
**How do I avoid mistakes rolling over my 401(k) to an IRA?**
- Use a direct rollover, not a check payable to you.
- Don’t ignore company stock if it has big gains.
- Coordinate with your tax and retirement income plan, not just the plan’s paperwork.
Again, you have **SIX options** available to you when you retire. All of them are discussed in six individual videos I recorded – just pick the one(s) that are most appropriate for you.
1. [Leave your money in your current plan](https://vimeo.com/919700051/7b737bab00?share=copy)
2. [Move your money to your new employer’s plan](https://vimeo.com/920114129/0c2b47679f?share=copy)
3. [Roll your money into an IRA](https://vimeo.com/920143551/d626474dc1?share=copy)
4. [Take a lump-sum distribution of all your money](https://vimeo.com/920518130/bc3869cfd0?share=copy)
5. [Convert plan assets to a Roth IRA](https://vimeo.com/920533438/7ec240929c?share=copy)
6. [Make an in-plan Roth conversion](https://vimeo.com/920545311/9ac36bd94d?share=copy)
**Ready for a 401(k) Rollover Analysis?** – This is a no-charge analysis for qualified residents in Simi Valley or Moorpark?
If you’re looking at a 401(k) to IRA rollover, you don’t have to sort through all of this alone. A careful, side-by-side review of your 401(k) versus an IRA can help you:
- Protect more of what you’ve built
- Avoid avoidable taxes and penalties
- Turn your retirement accounts into a coordinated income plan
If you’d like a second opinion before you move your life savings, you can start here:
Get Started:
****
That’s where we begin the conversation about whether rolling over your 401(k) is actually in your best interest—or whether staying put (for now) makes more sense.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Retirement, Rollovers
**Tags:** 401(k) rollovers, company plan rollover, IRA rollover, ira rollovers, rollover mistakes
---
### [How to Retire in an Inflationary World](https://indfin.com/how-to-retire-in-an-inflationary-world/)
**Published:** October 28, 2025
**Author:** Jim Lorenzen
**Excerpt:** Think of treating inflation like a tough par-4 in a crosswind. You can’t control the wind— but you can control your stance, balance, club and shot selection.
**Content:**
And you can manage the course. You may not make eagle, or even a birdie, but you can keep a big number off the card. Figuring out how to retire in an inflationary world can be tricky.
**The problem—simply**
Prices don’t rise evenly. Groceries, healthcare, and home insurance may sprint while travel or electronics stroll. Headline inflation is ~3% year over year, but the mix matters—especially for retirees who spend more on healthcare[. Bureau of Labor Statistics ](https://www.bls.gov/news.release/cpi.nr0.htm?utm_)
Utilities, insurance, and groceries can vary zip-to-zip (93021, 93063, 93065, 91360. *Your lifestyle*—not a headline CPI number—should drive your plan. If you want to know how to retire in an inflationary world, you first have to know what’s ahead.
**What’s changing in 2026 that affects retirees and those planning retirement**
- **Social Security:** Benefits rise **2.8%** in January 2026 (SSI adjusts 12/31/25). Helpful, but not a free lunch. [Reuters+1](https://www.reuters.com/world/us/us-retirees-receive-28-social-security-increase-2026-2025-10-24/?utm_). And, don’t forget, a portion may be taxable, depending on your provisional income. To calculate your provisional income, you combine the following:
- Your Adjusted Gross Income (AGI), before considering Social Security benefits.
- Any tax-exempt interest income.
- Half (50%) of your total Social Security benefits for the year.
- **Medicare (projections):** Early estimates point to a higher **Part B premium** and deductible in 2026; IRMAA brackets also tend to drift up. Translation: some or all of your COLA may get eaten by premiums unless you plan for it.
- **Real yields & inflation hedges:** The 10-year **TIPS real yield** sits around **~1.7%**, meaning you can lock in positive after-inflation income—something retirees didn’t have for most of the 2010s. [FRED+1](https://fred.stlouisfed.org/series/DFII10?utm_) Again, don’t forget the impact of taxes.
- **I Bonds:** Expect mid-single-digit composite rates around resets; good for safety reserves but subject to purchase limits and holding rules. [TreasuryDirect+1](https://www.treasurydirect.gov/savings-bonds/i-bonds/i-bonds-interest-rates/?utm_)
**Game Plan**
1. **Right-size your cash**
Keep 6–12 months of baseline withdrawals in cash-like reserves so you’re not forced to sell when markets are grumpy. Anything beyond that should have a job: T-bills, CDs, short Treasuries, or TIPS ladders. Positive real yields mean your “safe” money doesn’t have to lose to inflation by default. [FRED](https://fred.stlouisfed.org/series/DFII10?utm_)
2. **Build an inflation-aware income ladder**
Match the next 5–10 years of expected withdrawals with a ladder of high-quality bonds/Treasuries (including **TIPS** in the near and mid-rungs). This reduces the “sequence-of-returns” hit while giving cost-of-living ballast. (Yes, we’re deliberately avoiding that overused phrase you told me never to say.)
3. **Own businesses that can raise prices**
Broad, low-cost equity exposure (U.S. and international) lets you participate when companies pass along higher costs. Favor quality: strong balance sheets, durable margins, and consistent free cash flow. This is your long-iron (I went to hybrids some time ago)—less flashy than a driver but key to reaching the green.
4. **Use TIPS where they actually fit**
TIPS adjust principal with CPI and pay a real yield—use them in tax-deferred accounts when possible to avoid phantom-income headaches. As real yields rise, TIPS become a more compelling core bond holding rather than a niche hedge. [U.S. Department of the Treasury](https://home.treasury.gov/resource-center/data-chart-center/interest-rates/TextView?field_tdr_date_value_month=202204.&type=daily_treasury_real_yield_curve&utm_)
5. **Tax-smart withdrawal ordering**
Coordinate withdrawals to manage **tax brackets**, **IRMAA** surcharges, and **Social Security** taxation. Don’t let a big capital gain or large IRA pull nudge you into higher Medicare premiums two years later. (Yes, that two-year look-back for IRMAA still bites.) [medicareresources.org](https://www.medicareresources.org/faqs/what-kind-of-medicare-benefit-changes-can-i-expect-this-year/?utm_)
6. **Plan around your COLA**
A 2.8% Social Security bump is helpful, but local costs (Ventura County property insurance, utilities, dining) may run hotter in a given year. Don’t mentally spend the COLA before you see your Medicare letter.
7. **Revisit insurance and debt**
Re-shop homeowners and auto coverage annually. Consider paying down high-rate debt; keep low, fixed-rate mortgages if they’re truly cheap after taxes.
8. **Guardrails and reality checks**
Use an inflation-aware spending rule with “raise/freeze” guardrails. When markets win, give yourself a raise; when they don’t, hold flat. Quarterly check-ins beat annual surprises.
Want to know how to retire in an inflationary world? It would help to have an **Inflation Survival Playbook?** You can **[get one here](https://lp.constantcontactpages.com/sl/bi3B0sC/inflationsurvivalplaybook).**
**Common myths? Maybe, maybe not.**
- **“Bonds always lose to inflation.”** Not always, but close. Most analysis you see, even from the government, doesn’t factor in federal and state taxes. [FRED](https://fred.stlouisfed.org/series/DFII10?utm_) provides a general view, but doesn’t tell the whole story.
- **“COLA covers the rising cost of retirement.”** Sometimes, but Medicare and taxes can erode it. [AP News+1](https://apnews.com/article/0be15d5f1285cd1b774a8f5c59167b90?utm_)
- **“I Bonds are the one-stop inflation hedge.”** Great tool, small annual limits and lock-ups; they complement, not replace, a plan[. TreasuryDirect](https://www.treasurydirect.gov/savings-bonds/i-bonds/i-bonds-interest-rates/?utm_)
**What this looks like in practice (one example)**
- Years 1–3 expenses: high-yield cash/T-bills.
- Years 4–10: ladder of Treasuries/TIPS aligned to your spending calendar.
- Years 11+: globally diversified stocks and intermediate bonds for growth and stability.
- Annual tax map: bracket management + Roth conversions in opportunistic windows; IRMAA watch two years ahead. [medicareresources.org](https://www.medicareresources.org/faqs/what-kind-of-medicare-benefit-changes-can-i-expect-this-year/?utm_)
---
**FAQ**
**Is inflation still a big deal if CPI is around 3%?**
Yes. You are not an index. Your personal inflation rate can be higher—especially with healthcare and insurance. [Bureau of Labor Statistics](https://www.bls.gov/news.release/cpi.nr0.htm?utm_)
[](https://indfin.com/wp-content/uploads/2025/10/Inflation_Present-value.png)**Should I delay Social Security to fight inflation?**
Delaying raises the base benefit (and all future COLAs compound on a larger base). That’s often powerful longevity insurance—but it must fit taxes and cash-flow.
**Are TIPS better than regular Treasuries now?**
If you want explicit inflation protection and like locking in a real yield near ~1.7%, TIPS can be attractive as part of the bond sleeve; but only a part. Remember, that 1.7% doesn’t look so good in a taxable account, but it can be a good risk management component.
And, don’t forget to get your copy of the [**Inflation Survival Playbook.**](https://lp.constantcontactpages.com/sl/bi3B0sC/inflationsurvivalplaybook)
**Get an Inflation Check-Up!**
Tell me [your priorities](https://indfin.com/retirement-priority-planning-review/), then [schedule an introductory call](https://go.oncehub.com/JimLorenzenCFP)! You can [also subscribe to my newsletter.](https://visitor.r20.constantcontact.com/d.jsp?llr=fdk6idhab&p=oi&m=fdk6idhab&sit=icdtuhhgb&f=68947827-6cd6-46e6-a8a2-db365fc30f5c)
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Inflation, Retirement, Retirement Income
**Tags:** Inflation, Investment Strategy, Retirement Income
---
### [Should I take social security at 62 or 70? The Real Math for Simi Valley and Moorpark.](https://indfin.com/should-i-take-social-security-at-62-or-70-the-real-math-for-simi-valley-and-moorpark/)
**Published:** October 20, 2025
**Author:** Jim Lorenzen
**Excerpt:** Short answer up front: if you’re healthy and can afford to wait, 70 usually wins on lifetime dollars; if cash flow is tight or your health isn’t great, earlier can make sense.
**Content:**
“Should I take social security at 62 or 70?”
“What happens if I take social security while working?”
“Does waiting increase spousal benefit?”
“Do i lose money if I claim early then stop?”
**All questions good financial plans answer**; but, many people have trouble getting started. The first step in playing the course is selecting the right tee box.
**The three tee boxes (what you actually get)**
- **62 (earliest):** Your monthly check is **reduced permanently**. For those with full retirement age (FRA) 67 (born 1960+), claiming at 62 pays **~70%** of your FRA amount. That reduction is applied monthly using SSA’s formula (5/9 of 1% for the first 36 months early, 5/12 of 1% for additional months). [Social Security](https://www.ssa.gov/benefits/retirement/planner/1960-delay.html?utm_)
- **67 (FRA):** You get **100%** of your “primary insurance amount” (PIA). [Social Security](https://www.ssa.gov/benefits/retirement/planner/agereduction.html?utm_)
- **70 (latest):** You earn **delayed retirement credits**—about **+8% per year** after FRA—up to age 70. If FRA is 67, starting at 70 pays **~124%** of your FRA amount. Benefits don’t grow past 70. [Social Security](https://www.ssa.gov/benefits/retirement/planner/1960-delay.html?utm)
**Example:** If your FRA (age 67) benefit is **$3,000**:
- At 62 ≈ **$2,100** (~70%).
- At 67 = **$3,000** (100%).
- At 70 ≈ **$3,720** (~124%). [Social Security](https://www.ssa.gov/benefits/retirement/planner/1960.html?utm_)
**“But I’m still working—does that change things?”**
If you claim **before** FRA **and** you earn above the annual earnings-test limit, Social Security may **withhold** benefits for now and **recalculate** your payment higher at FRA; those withheld dollars aren’t lost. Once you hit FRA, there’s **[no earnings test](https://www.ssa.gov/policy/docs/program-explainers/retirement-earnings-test.html?utm)**. [](https://www.ssa.gov/policy/docs/program-explainers/retirement-earnings-test.html?utm_source=chatgpt.com)
**[The real math: breakeven and risk](https://lp.constantcontactpages.com/sl/9Al940w)**
Think of 62 vs. 70 like choosing driver vs. 5-iron. Driver gets money on the scorecard sooner; 5-iron (waiting) aims for a higher lifetime total.
- **Breakeven math (illustrative):** Using the example above, you’ll collect more, per month, if you wait. The tradeoff is the **eight years** of smaller checks you pass up from 62–70. Typical breakeven for 62 vs. 70 lands in the **late 70s to around 80**, depending on COLAs, taxes, investment returns, and whether you keep working. (Exact age is specific to your numbers; we run this precisely for clients.)
- **Longevity risk:** If you live into your 80s and 90s, the **higher lifetime benefit** from delaying is powerful insurance against outliving savings.
- **Sequence-of-returns risk:** Waiting can reduce the need to sell investments in a down market because your **eventual** check is bigger.
- **Inflation:** COLAs apply to whatever you lock in. A bigger base (by delaying) means bigger dollar COLAs over time.
**Spousal and survivor stakes (don’t ignore this)**
- **Spousal benefits** can be up to **50% of the worker’s FRA benefit** (reduced if claimed early). Delaying the **worker’s** own benefit **doesn’t** increase the spouse’s *spousal* benefit beyond that 50% cap. [Social Security](https://www.ssa.gov/oact/quickcalc/spouse.html?utm_)
- **Survivor benefits** are different: if the higher-earning spouse delays and locks in a larger benefit, the **surviving spouse** can later receive **up to 100%** of that higher amount at survivor FRA. In plain English: delaying by the higher earner can materially boost what the widow(er) keeps for life. [Social Security](https://www.ssa.gov/pubs/EN-05-10084.pdf?utm_)
**Taxes and cash-flow (the part nobody loves, but matters)**
- Benefits can be **taxable** depending on your other income; coordinating IRA withdrawals, Roth conversions, and the start of Social Security can lower lifetime taxes. (Strategy, not slogans.)
- If you claim **before** FRA while working and cross the earnings-test limit, expect withholdings and later **recalculation upward** at FRA; plan cash flow accordingly. [Social Security](https://www.ssa.gov/policy/docs/program-explainers/retirement-earnings-test.html?utm_)
**“Should I take social security at 62 or 70? “**
Here’s quick decision framework (Moorpark & Simi Valley edition). Use this as a common-sense yardage book—then we run the exact numbers with your data.
**Lean toward 70 if most of these are true:**
- You’re in **good health** with a long-lived family history.
- You have **ample savings** or wages to cover spending until 70.
- You’re the **higher earner** in the household (bigger survivor benefit later).
- You prefer **longevity insurance** (bigger inflation-adjusted check for life).
**Lean toward 67 (FRA) if:**
- You want to keep working **without** the earnings test.
- Cash flow is fine after 67 but tight before then.
- You’re indifferent on breakeven but want simplicity and flexibility.
**Consider 62 if:**
- **Health** suggests a shorter life expectancy.
- You **need cash flow now** and other options are costly or unwise.
- Your **spouse** is the **higher earner** and will delay, protecting the survivor benefit.
**Common pitfalls to avoid**
- **“Claim early, invest the difference”** without accounting for volatility, taxes, and behavior—nice on a whiteboard, messy in real life. These “strategies” seldom work.
- **Ignoring survivors.** If you’re the higher earner, delaying often protects your spouse’s lifetime income.
- **Earnings test surprises.** If you claim before FRA and keep working, plan for withholdings and a later adjustment. It’s not a penalty, but it will affect cash flow.
- **Waiting past 70.** There’s **no increase** after 70. Don’t leave money in the clubhouse.
**Bottom line**
“Should I take social security at 62 or 70?”
If you have the health, savings, and patience, **age 70** generally produces the highest lifetime and survivor value. If you need the income or your health argues otherwise, **62 or 67** can be perfectly rational. The best choice is the one that wins on **after-tax, after-risk, family-aware** dollars.
**Here’s a special offer for residents of Simi Valley, Moorpark** **and Thousand Oaks.**
**What’s YOUR break-even age between 62 and 70?** Want your breakeven, survivor, and after-tax comparison in writing? [I’ll prepare a personalized report for you ](https://lp.constantcontactpages.com/sl/9Al940w)with your exact figures including an analysis.
If you’re in **93021, 93065, 93063, or 91360**, Want some answers? Want to kick the tires?
I’ll run your personalized Social Security timing PDF analysis using a calculator that **even computes COLAs and their impact** – **something even SSA doesn’t provide.**
**[Your personalized report:](https://lp.constantcontactpages.com/sl/9Al940w)**
- Will run through all possible claiming scenarios, whether you’re single, divorced, married, widowed – even for families with minor or disabled adult children
- Shows detailed breakdown of lifetime benefits under virtually any scenario.
- Incorporates cost-of-living adjustments – again, the SSA doesn’t provide this – they’re helpful (and overworked), but they’re not in the business of either providing predictions or financial planning.
- Shows first-year survivor income
- Is updated for the Social Security Fairness Act signed into law January 5, 2025
Report shows the benefit estimate based on the age when you claim Social Security. Each scenario shows both the benefit stream and cumulative benefits over your life expectancy.
**All that’s needed is each spouse’s birthdate and primary insurance amount.** The PIA can be obtained by opening an account at [ssa.gov/myaccount](https://www.savvysocialsecurity.com/LinkTrack.aspx?u=http%3a%2f%2fwww.ssa.gov%2fmyaccount). I think you’ll find the site quite helpful. You can contact the SSA for your statement, but phone waits can be long.
IFG doesn’t sell investments – so there’s no selling; just help.[ Let me know if I can help you](https://lp.constantcontactpages.com/sl/9Al940w).
Jim
Some additional information on what’s new with Social Security can be found on the [IFG website](https://indfin.com/socialsecurity/).

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement, Social Security
**Tags:** retirement decisions, Retirement Strategy, social security, social security claiming, when to claim social security
---
### [A Roth Conversion Strategy is One Way to Pay Less Tax in Retirement. There are others!](https://indfin.com/a-roth-conversion-strategy-is-one-way-to-pay-less-tax-in-retirement-there-are-others/)
**Published:** October 13, 2025
**Author:** Jim Lorenzen
**Excerpt:** Here’s the bottom line: you can’t control the tax code, but you can control how (and when) you show income. Smart moves—timed right—can lower your lifetime tax bill in retirement.
**Content:**
Here is a plain-English playbook with Roth conversion strategy and other local angles for Simi Valley and Moorpark, California residents.
**1) Know what’s actually taxed—and what isn’t**
- **Social Security:** California doesn’t tax Social Security at all. The **federal** government might tax up to 85% of your benefit depending on your income (“combined income” formula). [State of California Franchise Tax Board+2IRS+2](https://www.ftb.ca.gov/file/personal/income-types/social-security.html)
- **Capital gains:** California taxes *all* capital gains as ordinary income—no lower “long-term” rate at the state level. (Federal still has 0/15/20% brackets.) [State of California](https://www.ftb.ca.gov/file/personal/income-types/capital-gains-and-losses.html)[ ](https://www.ftb.ca.gov/file/personal/income-types/capital-gains-and-losses.html)[Franchise Tax Board](https://www.ftb.ca.gov/file/personal/income-types/capital-gains-and-losses.html).
- **Municipal bonds:** Interest from **California** munis is generally exempt from **California** income tax; interest from other states’ munis is usually taxable in CA. [Legal Information Institute](https://www.law.cornell.edu/regulations/california/18-CCR-24271-e?utm_).
**2) Sequence withdrawals to manage tax brackets**
Think of your retirement income like selecting clubs on a par-5: use the right club at the right time.
- **Early years (pre-RMD, post-retirement):** Often ideal for drawing from pre-tax IRAs up to the top of a target bracket, then filling the gap with taxable accounts. This can reduce future Required Minimum Distributions (RMDs) and IRMAA surcharges (more on those below).
- **RMD timing:** Under current law, RMDs start at **age 73** (75 if born in 1960 or later). You can delay the *first* RMD to April 1 of the following year—but that can force two RMDs in one calendar year.
**3) Use Roth conversions intentionally (not randomly)**
It’s good to have a well-planned Roth conversion strategy. Converting slices of a traditional IRA to a Roth in lower-income years can be powerful:
- You prepay tax at known (and potentially lower) rates, reduce future RMDs, and create a pot of tax-free income later.
- With several individual provisions scheduled to change after **2025**, many households are modeling conversions in 2025 while rates are still under current rules. (Details are policy-dependent; the nonpartisan CRS summary is a good reference on scheduled expirations.) [Congress](https://www.congress.gov/crs-product/R47846?utm_)[.gov](https://www.congress.gov/crs-product/R47846?utm_)
Are you considering a Roth conversion? I have a ‘decision tree’ roadmap that can help you through the process. [**You can get it here.**](https://lp.constantcontactpages.com/sl/H8w6Mxf/Rothconversiondecisions)
**4) Watch the “stealth taxes”: IRMAA + NIIT**
- **Medicare IRMAA (Parts B & D):** Two years after your income shows up on your tax return, Medicare can tack on an income-related surcharge. For **2025**, the standard Part B premium is **$185/month**; surcharges begin for 2023 MAGI above **$106,000 (single)** or **$212,000 (joint)** and scale by tier. [CM](https://www.cms.gov/newsroom/fact-sheets/2025-medicare-parts-b-premiums-and-deductibles?utm_)[S](https://www.cms.gov/newsroom/fact-sheets/2025-medicare-parts-b-premiums-and-deductibles?utm_). There’s more on this, and other tax traps, in my video library. See the very first video at [https://indfin.com/video-library](https://indfin.com/video-library/)[/](https://indfin.com/video-library/)
- **Net Investment Income Tax (NIIT):** High earners may owe an extra **3.8%** on investment income once MAGI exceeds **$200k single / $250k joint**. Planning levers include capital-gain timing, tax-loss harvesting, and asset location.
**5) Give smarter: Qualified Charitable Distributions (QCDs)**
If you’re **70½ or older**, you can send money directly from an IRA to a qualified charity. It **never hits your adjusted gross income (AGI)**, and it **can** satisfy RMDs once you’re subject to them.
- For **2025**, the QCD limit is **$108,000** per person (indexed).
**6) Place assets in the right accounts (asset location)**
- Keep **tax-inefficient** income producers (bond funds throwing off ordinary income, REIT funds) in **tax-deferred** accounts when possible.
- Keep **tax-efficient** or growth-oriented assets (broad equity ETFs) in taxable or Roth accounts, which is where having a well-planned Roth conversion strategy can be helpful. Especially for residents of high tax states like California.
**7) Capital gains: harvest with intent**
- Coordinate gains with low-income years; consider realizing gains up to the top of a federal 0%/15% bracket when it fits the plan.
- Remember: California will tax those gains at ordinary rates even if they’re long-term. [State of California Franchise Tax Board](https://www.ftb.ca.gov/file/personal/income-types/capital-gains-and-losses.html)
**8) Property-tax relief when you move (Prop 19)**
Many retirees downsize or “right-size.” Under **Prop 19**, Californians **55+** can transfer their **Proposition 13** assessed value to a replacement home **anywhere in the state**, up to **three times** (subject to rules and timing). That can keep property taxes in check even if you relocate within or around Simi Valley/Moorpark. [California State Board of Equalization](https://www.boe.ca.gov/pdf/pub800-3.pdf?utm_)
**9) Local realities: Simi Valley & Moorpark**
- **No state tax on Social Security** is a genuine win for local retirees; the trade-off is **state tax on capital gains** and most retirement distributions. If a big IRA or stock sale is in your future, plan ahead.
- **Considering bonds?** Again, a Ventura County or California muni fund can reduce your state bill versus an out-of-state muni fund; but I’m not a fan of bond funds in taxable accounts.. The reason is simple: there’s no maturity date and therefore no predictability.
**10) A simple order of play (example)**
This is an illustration, not advice—but it’s the kind of flow many Simi Valley/Moorpark retirees use:
1. In years before RMDs, **fill up** a chosen federal bracket (say, the 22% or 24% band) with IRA withdrawals or Roth conversions [(don’t forget this decision tree roadmap)](https://lp.constantcontactpages.com/sl/H8w6Mxf/Rothconversiondecisions).
2. Use **taxable accounts** for the remainder, tapping principal (which isn’t taxed) and qualified dividends/capital gains (federally lower rates).
3. Once RMDs start, you may want to consider **QCDs** to keep AGI—and IRMAA—down. That’s a case-by-case consideration, however.
---
**Frequently used reference numbers (as of 2025)**
[Important-Numbers-2025](https://indfin.com/wp-content/uploads/2025/10/Important-Numbers-2025.pdf)[Download](https://indfin.com/wp-content/uploads/2025/10/Important-Numbers-2025.pdf)
**What to do next (practical, no-nonsense)**
- **Map your income by year** (age 60–85) to see where conversions, RMDs, and Social Security overlap—and where IRMAA cliffs lurk.
- **Decide a target bracket** to fill annually with IRA withdrawals or conversions.
- **Charitable?** Set up QCDs before RMD season.
- **Moving locally?** Check Prop 19 timing rules *before* you list or buy.
If you’re within five years of retirement—or already retired in Simi Valley or Moorpark—let’s build a year-by-year tax strategy that puts more of your money in your pocket, not Sacramento or Washington. (No gimmicks. Just smart asset arrangement, sequencing and timing.)
Here’s where to [Get Started with IFG!](https://indfin.com/getting-started/)
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Will My Retirement Savings Last?](https://indfin.com/will-my-retirement-savings-last/)
**Published:** September 30, 2025
**Author:** Jim Lorenzen
**Excerpt:** The #1 Question That Keeps People Awake at Night. How to make retirement savings last.
After more than 30 years of helping families navigate retirement, the most common question isn’t about stocks, bonds, or the next hot investment tip. It’s simpler...
**Content:**
**Some tips from a Fiduciary Advisor in Simi Valley & Moorpark**
**“Will my retirement savings last?”**
We’re so used to working and saving – socking money away. The idea of income stopping and starting to drain assets – making your retirement savings last for maybe thirty years is a scary thought, whether you live in Simi Valley, Moorpark, or Beverly Hills – it’s all relative.
Whether you’re on the verge of retirement locally in Simi Valley or Moorpark, or planning, like some of my clients have, to retire in another state, making your retirement savings last has likely become a priority.
**Why This Question Matters More Than Ever**
When my father retired a few decades ago, life expectancy was shorter, pensions were more common, and interest rates were sky-high compared to today. In short, the math was easier. No one had to become his/her own actuary.
Times have changed. Fast forward to today:
- **People are living longer.** Many healthy 65-year-olds can easily expect to live into their 90s. That’s 30 years of withdrawals, inflation, and tax law changes. And, you know, of course, the government is here to help you….
- **Pensions are rare**. Companies’ financial officers managed the assets. Now, with IRAs, 401(k)s, and investment accounts, you now need to manage investments and withdrawals yourself. Now, you’re an actuary! Despite all the financial entertainment gurus (whatever happened to ‘Angry Sandy’) and their systems, they don’t bear any responsibility when things go wrong.
- **Markets are volatile**. Stocks, bonds, and interest rates swing more dramatically, making planning tricky. It bring sequence of returns risk (more later).
- **Healthcare costs are higher**. It’s simple economics really: an aging Baby Boomer population and longer lives are driving demand, even as the number of doctors seems to be declining. A 65-year-old couple retiring today may spend $300,000+ on healthcare over their lifetime.
Put all that together, and it’s no wonder the question of “will I run out?” feels like staring down a 200-yard shot over water with a breeze in your face. Maybe a ‘financial caddy’ can help manage the course.
**The Four Key Drivers of “Money That Lasts”**
**1. Spending Needs and Lifestyle**
The quickest way to sink the ship isn’t bad investments—it’s overspending. Retirees often underestimate what they’ll actually spend, especially in the **first decade** when they’re traveling, spoiling grandkids, and finally checking off bucket-list items. Even just eating out can add up.
**Tip: Run the numbers realistically**. If your monthly budget assumes you’ll suddenly spend half as much as you did while working, you may be setting yourself up for disappointment. Remember, you now have more time on your hands. Of course, some people work in retirement – consulting, or starting a little part-time business; but, those can drain money, too. Planning must always come before execution.
**2. Withdrawal Strategy**
How you take money out of your accounts matters as much as how you invested it. Different accounts are taxed differently, and the order of withdrawals can dramatically affect how lo*ng* retirement savings lasts.
For example:
- Withdraw from taxable accounts first? Your IRAs may keep growing (but future RMDs could be massive).
- Withdraw from IRAs first? You might trigger higher taxes earlier but reduce future tax traps.
There’s no one-size-fits-all answer but having a tax-smart withdrawal plan can extend a portfolio’s life by years.
**3. Market Sequence Risk**
I could easily do an entire presentation on this one. You might like [a paper I wrote](https://indfin.com/wp-content/uploads/2014/09/i307_RPT-Understanding-Investment-Returns.pdf) on investment returns. Markets don’t move in a straight line. If you retire into a downturn and need to sell investments while prices are low, it can dig a hole your portfolio never recovers from.
That’s why I often recommend having a cash reserve or short-term bonds covering expenses not covered by any ‘automatic’ income (Social Security, etc.) for (?) years. It depends on many factors, of course. It’s your buffer against selling stocks when they’re down.
**4. Taxes and Healthcare**
Two silent partners in your retirement: Uncle Sam and the healthcare system. Imagine having a business partner who can unilaterally decide how much money s/he can take out of your business – and change his or her mind at any time while you have no say. Would you take on a partner like that? Well, you have one.
- **Taxes:** Required Minimum Distributions (RMDs), Social Security taxation, Medicare surcharges (IRMAA)—these can add up quickly if you’re not proactive. And, the size of your RMDs affect the others.
- **Healthcare:** Medicare covers a lot, but not everything. Long-term care, assisted living, or memory care can be a six-figure expense. We’re living longer, which makes all these more likely – and more expensive. Smart kids may want to buy protection for their parents just too protect their inheritance!
Good planning doesn’t ignore these—it accounts for them early.
**Why “Safe” Isn’t Always Safe**
The ‘safety’ myth. Many pre-retirees tell me they want to move everything into “safe” investments at retirement. CDs, bonds, cash. The problem? Inflation doesn’t stop when you retire, and these options have never provided a long-term solution after inflation and taxes.
Imagine you need $100,000 a year today. At just 3% inflation, you’ll need over $240,000 in 25 years to buy the same goods and services. To put it another way, your purchasing power will end up being less than $48,000 in today’s money. Money is worth only what it buys. If your investments don’t outpace inflation, “safe” really means a sure loss. This isn’t a good way to make retirement savings last.
**Lessons From 30+ Years in the Trenches**
- You’re not managing money; you’re managing risks – you just do it with money. In addition to market risk, there’s inflation risk, legislative (tax) risk, interest rate risk, economic risk, longevity risk, and a few others. And, none of them are going away.
- No one regrets being prepared. However, many have regretted their behavior. Standing at the mirror with a pair of pliers to fix a tooth ache isn’t a good idea. Smart people get professional help for both their physical and financial health.
- It’s not about chasing returns or picking hot stocks. Turn off the ‘talking heads’ (MTV in suits). It’s about managing risk, costs, and taxes while building a steady income stream you can rely on. It’s also about taking steps to secure your later years.
- Location (sometimes) matters. Costs in Simi Valley and Moorpark aren’t the same as in Chicago, San Francisco or Manhattan. However, I remember when Florida was considered inexpensive. Even with no state income tax, Florida isn’t as inexpensive as it used to be: eastern Baby Boomers moving south have driven up real estate costs substantially since the old days.
When I had an office in Winter Park (Orlando), almost everything cost the same as in California – except real estate. But, now, even that is approaching California numbers, depending on which areas you’re comparing in either state. Your plan should reflect the reality of living here, even if you intend to move. You’d be surprised how many people move away – then move back. The grass isn’t always greener.
**What You Can Do Now**
If you’re on the edge of retirement, here are practical steps to start today:
1. **Get a realistic budget.** Include healthcare, travel, taxes, and “fun money.”
2. **Stress-test your plan**. Ask: what happens if markets drop 20% in the first 3 years? It takes a 25% gain to buy back a 20% loss.
3. **Review account types**. Know how IRAs, Roths, and your other accounts interact.
4. **Plan Social Security carefully.** Don’t just grab it at 62—run the numbers. Better yet, have a professionally created analysis done for you. Don’t expect advice from Social Security. They’re helpful, but they don’t do projections or give advice.
5. **Talk to a fiduciary advisor.** This is your life savings. Get advice from someone legally bound to put your interests first.
Cue shameless self-promotion: It would help if the advisor you choose is a *CERTIFIED FINANCIAL PLANNER® professional and an Accredited Investment Fiduciary®*
**Bringing It Home**
Here’s the truth: there’s no way to eliminate risk – but it can be managed. You *can* build a strategy that stacks the odds in your favor, provides income you won’t outlive, and gives you the confidence to enjoy the years ahead.
I’ve been doing this for over three decades, and if there’s one thing I know, it’s this: the earlier you plan, the more choices you have. Unfortunately, the young watch Kramer – entertainment is more fun – and most wait to long… sometimes until the last minute which leaves fewer options and creates more stress.
**Next Step: Get the Full Picture**
If you found this helpful, you’ll want to check out my exclusive video series addressing retirement. It addresses many of the issues we’ve discussed, as well as the decisions and options new retirees face. You’ll also be signed-up to receive my newsletter, which I think you’ll find helpful. You can, of course, unsubscribe instantly at any time.
\[[Click here to access the video series and start planning smarter](https://lp.constantcontactpages.com/sl/oIwLnlJ).\]
**Final Thought:**
The question isn’t just “Will my money last?”—it’s “What can I do today to make sure it does?” You’ve worked too hard to leave that answer up to chance.
**Frequently Asked Questions About Retirement Savings**
1. **How much do I really need to retire in Simi Valley or Moorpark?**
It depends on your lifestyle – true no matter where you live. Some families are comfortable on $80,000 a year, others want $150,000+. Housing, healthcare, and travel plans all matter. A fiduciary advisor can help you run the numbers realistically instead of guessing.
2. **What’s the biggest risk to my retirement savings?**
It’s not usually a market crash — it’s spending too much, too soon, or paying more tax than necessary. Sequence of returns (retiring into a down market) can also be a hidden danger if you don’t have a cash buffer.
3. **Should I take Social Security early or wait until 70?**
If you need the income, taking it earlier makes sense. But for many healthy pre-retirees, waiting boosts lifetime benefits significantly. The right answer depends on your health, portfolio size, and tax picture. Get a professionally prepared analysis. It’ll be worth it. Mistakes in claiming can be irreversible and costly.
4. **How do taxes affect retirement income?**
More than most people think. Withdrawals from IRAs and 401(k)s are taxable, Social Security can be taxed up to 85%, and large RMDs can push you into higher brackets, impacting Social Security taxation and your Medicare premiums. Smart withdrawal strategies can save tens of thousands over time.
5. **How can I make sure I don’t run out of money?**
The key is planning. That means: setting a sustainable withdrawal rate, keeping a balanced portfolio, accounting for inflation and healthcare, and reviewing annually. Retirement isn’t a “set it and forget it” stage — it’s active management.
Concerned about the impact of future interest rate moves on your long-term plans? Why not do this: Tell me [your priorities](https://indfin.com/retirement-priority-planning-review/), then [schedule an introductory call](https://go.oncehub.com/JimLorenzenCFP)!
If you haven’t done so already, you can [also subscribe to my newsletter.](https://visitor.r20.constantcontact.com/d.jsp?llr=fdk6idhab&p=oi&m=fdk6idhab&sit=icdtuhhgb&f=68947827-6cd6-46e6-a8a2-db365fc30f5c)
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [How Does a Fed Rate Cut Affect Long-Term Investors?](https://indfin.com/how-does-a-fed-rate-cut-affect-long-term-investors/)
**Published:** September 22, 2025
**Author:** Jim Lorenzen
**Excerpt:** On September 17, 2025, the Federal Reserve trimmed its benchmark rate by 25 basis points. This was the first fed rate cut since Dec 2024.
**Content:**
**Understanding the Fed Rate Cut vs. Market Rates**
Despite all the political grandstanding about the Fed chairman and his influence for a Fed rate cut, the Feb board is comprised of seven members who all have an equal vote – the chairman is just one of the seven – and there’s an 8th member politicians don’t discuss: the market. Will get into that.
This recent Fed action, no different from the others, directly changes ***only*** the overnight bank-to-bank borrowing rate. Most of our personal loan, CD, and mortgage rates are set by markets. As the AP News explains, the Fed “doesn’t directly set” mortgage rates; instead mortgages generally follow the 10-year Treasury yield [apnews.com](https://apnews.com/article/mortgage-rates-housing-federal-reserve-rate-cut-9351815c29cea1e27b531dec88d3e4da#:~:text=Mortgage%20rates%20generally%20follow%20the,guide%20to%20pricing%20home%20loans).
In other words, longer-term consumer rates depend on bond market demand, economic growth and inflation expectations – not the Fed funds rate, let alone any one member of the board. Even last year, a Fed cut “doesn’t necessarily mean mortgage rates will keep declining” [apnews.com](https://apnews.com/article/mortgage-rates-housing-federal-reserve-rate-cut-9351815c29cea1e27b531dec88d3e4da#:~:text=Like%20last%20year%2C%20the%20Fed%E2%80%99s,bank%20signals%20more%20cuts%20ahead). In short: a 0.25% Fed cut sends a signal about short-term credit, but it *won’t* instantly cut your mortgage or CD rates. So, the ‘8th member’ may not sit in at the board meetings – but is no less a factor.
**Key Point: *The Fed controls ONLY the very short end of interest rates. Your mortgage, CD, and bond ladder are driven by the market. So, you don’t need to swing at every pitch. If you have a professionally prepared formal plan, it’s likely been stress-tested.***
**Bonds: What Retirees Need to Know**
Bond investors often worry when Fed policy changes, especially investing for income in the face of a fed rate cut. **Here’s the good news:** if you own short-to-intermediate bonds and plan to hold them to maturity, your income stays the same – just one of the factors that influenced the decision to move client bond positions from funds and ETFs to individual holdings – particularly in taxable accounts – earlier this year.
Individual bonds, unlike funds, have a maturity date. As Kiplinger notes, “hold to maturity, and you get all of your principal back”[kiplinger.com](https://www.kiplinger.com/investing/bonds/bonds-pay-in-good-and-bad-times#:~:text=Important%3A%20The%20value%20of%20Treasuries,rates%20fall%2C%20value%20goes%20up).
So even if bond prices wobble, your final payout doesn’t change (assuming no default). In fact, existing bonds with higher coupons rise in value when yields fall [kiplinger.com](https://www.kiplinger.com/investing/bonds/bonds-pay-in-good-and-bad-times#:~:text=Important%3A%20The%20value%20of%20Treasuries,rates%20fall%2C%20value%20goes%20up)[kiplinger.com](https://www.kiplinger.com/retirement/retirement-planning/retirees-make-these-financial-before-the-fed-cuts-rates#:~:text=,price%20to%20rise%2C%E2%80%9D%20he%20explains). If the Fed cut pushes some yields down, those high-coupon bonds become *more* attractive. As one adviser explains, “when rates drop, bonds…with higher coupons become more attractive, causing their price to rise… intermediate- to long-term bonds tend to perform well” [kiplinger.com](https://www.kiplinger.com/retirement/retirement-planning/retirees-make-these-financial-before-the-fed-cuts-rates#:~:text=,price%20to%20rise%2C%E2%80%9D%20he%20explains).
On the flip side, longer-term yields are set by the market. A Fed rate cut has minimal impact here. Right now inflation and growth expectations are *still* above the Fed’s 2% goal – even if arbitrary – so medium/long rates have stayed relatively high. Vanguard economists warn that “long-term yields are shaped not just by near-term Fed policy, but also by expectations about future rates”[corporate.vanguard.com](https://corporate.vanguard.com/content/corporatesite/us/en/corp/vemo/looking-beyond-fed-rate-cut.html#:~:text=Second%E2%80%94and%20more%20importantly%E2%80%94many%20sectors%20would,duration%20bonds).
For example, U.S. Bank found that after the last Fed rate cut, long-term Treasury yields *actually rose* as the market grew more optimistic about the economy [usbank.com](https://www.usbank.com/investing/financial-perspectives/market-news/interest-rates-affect-bonds.html#:~:text=situation%20for%20an%20extended%20period,S). That means newly issued bonds might not yield much less after a cut, and older bonds may fall in price if yields go up.
**Key point:** If you hold bonds to maturity, rate swings only affect the *current market price – the price you’d receive only if you sold –* not your ultimate return [kiplinger.com](https://www.kiplinger.com/investing/bonds/bonds-pay-in-good-and-bad-times#:~:text=Important%3A%20The%20value%20of%20Treasuries,rates%20fall%2C%20value%20goes%20up)[usbank.com](https://www.usbank.com/investing/financial-perspectives/market-news/interest-rates-affect-bonds.html#:~:text=Bond%20prices%20move%20in%20an,doesn%E2%80%99t%20default%20on%20its%20obligations). (In fact, bond prices move inversely with yields: lower yields = higher price, and vice versa [usbank.com](https://www.usbank.com/investing/financial-perspectives/market-news/interest-rates-affect-bonds.html#:~:text=Bond%20prices%20move%20in%20an,doesn%E2%80%99t%20default%20on%20its%20obligations).)
One smart approach adopted by my clients is to **ladder your bonds**: buy a series of maturities so that if rates do fall, you still have some bonds locked in at higher rates, and if rates rise, short-term bonds come due sooner to reinvest at those higher rates [kiplinger.com](https://www.kiplinger.com/investing/bonds/bonds-pay-in-good-and-bad-times#:~:text=Since%20interest%20rate%20trends%20are,to%20reinvest%20at%20higher%20rates). This strategy smooths out the impact of rate moves over time.
**Stocks and Other Assets**
When the Fed cuts, stock valuations often improve because discount rates fall. Analysts note that a rate cut reduces the hurdle rate on future earnings, especially boosting growth stocks. For example, BlackRock’s iShares team observes that “discount rates fall when the Fed cuts, which benefits growth stocks, especially in technology” [ishares.com](https://www.ishares.com/us/insights/fed-rate-cut-and-your-portfolio#:~:text=Second%2C%20U,areas%20most%20likely%20to%20benefit).
Similarly, one advisor notes that lower rates let companies borrow more cheaply and invest in growth, so “it’s important to own stocks when interest rates are declining” [kiplinger.com](https://www.kiplinger.com/retirement/retirement-planning/retirees-make-these-financial-before-the-fed-cuts-rates#:~:text=As%20he%20explains%2C%20when%20rates,%E2%80%9D). In practical terms, a balanced retiree portfolio can include some high-quality, dividend-paying stocks to capture this effect. Remember, however, most companies capital borrowing isn’t short term, so a Fed rate cut would have minimal impact. Corporate CEOs and CFOs are more concerned with supply chain costs and the rates determined more by market forces.
However, remember the reason for the cut: often the Fed eases rates due to economic softness. Many companies aren’t hiring right now, still trying to digest the impact of tariffs. In a weakening economy, stocks can still be volatile. That’s why experts emphasize a balanced, diversified portfolio.
Instead of chasing the latest Fed rate cut – or any other move – it might be better to focus on *stability*: keep a mix of bonds (for income and safety) and stocks (for growth). The allocation percentages depend on many factors that are components of your financial plan.
Trying to time interest rate move may not be as wise as looking at your portfolio holistically and make sure it’s well-balanced and designed to withstand market fluctuations. In short, don’t overhaul your strategy just because of one Fed decision. When driving, see what’s down the road.
**Practical Takeaways for Retirees – and those planning for retirement:**
1. **Your bonds still pay their fixed coupons.** If you bought a bond yielding, say, 5%, that payment doesn’t change. A Fed cut won’t reduce what you get if you hold to maturity [kiplinger.com](https://www.kiplinger.com/investing/bonds/bonds-pay-in-good-and-bad-times#:~:text=Important%3A%20The%20value%20of%20Treasuries,rates%20fall%2C%20value%20goes%20up). It may make your bond’s market price higher (if yields fall), but only your sale price changes — not the interest you earned. Don’t sell and your bonds mature at face value.
2. **New bonds may yield less.** Future bonds or CDs could come with slightly lower rates if the Fed is easing. That’s why Kiplinger suggests keeping some cash and short bonds ready: “Many \[high-yield savings\] are still paying 4% or more. For funds beyond three months, U.S. Treasuries and short-term CDs are the preferred route” even with Fed changes [kiplinger.com](https://www.kiplinger.com/retirement/retirement-planning/retirees-make-these-financial-before-the-fed-cuts-rates#:~:text=%E2%80%9CIn%20the%20next%20one%20to,%E2%80%9D). In other words, lock in high short-term rates now and reinvest as needed, rather than rushing into ultra-long bonds.
3. **Intermediate yields depend on the economy.** Just because the Fed cut 25 bps doesn’t force the 5- or 10-year yield down by the same amount. If investors think inflation will stick or the economy holds up, medium-term yields could stay steady or even rise [usbank.com](https://www.usbank.com/investing/financial-perspectives/market-news/interest-rates-affect-bonds.html#:~:text=situation%20for%20an%20extended%20period,S)[corporate.vanguard.com](https://corporate.vanguard.com/content/corporatesite/us/en/corp/vemo/looking-beyond-fed-rate-cut.html#:~:text=Second%E2%80%94and%20more%20importantly%E2%80%94many%20sectors%20would,duration%20bonds). Watch inflation and fiscal news; those shape longer rates more than a single Fed move.
4. **Ladder and diversify.** If you own individual bonds, keep laddering maturities. That way, some bonds will mature sooner (to reinvest if rates rise) while others lock in current yields. Also balance bond holdings with some equity exposure. Quality stocks or dividend ETFs can help offset low bond yields over the years, especially as Fed cuts often favor equities [kiplinger.com](https://www.kiplinger.com/retirement/retirement-planning/retirees-make-these-financial-before-the-fed-cuts-rates#:~:text=As%20he%20explains%2C%20when%20rates,%E2%80%9D).
5. **Stick to your plan.** Ultimately, the best strategy is a portfolio designed to *weather any rate environment*. As one expert says, “focus on building a portfolio that will hold up in any rate environment, not just the one making headlines” [kiplinger.com](https://www.kiplinger.com/retirement/retirement-planning/retirees-make-these-financial-before-the-fed-cuts-rates#:~:text=%E2%80%9CAt%20this%20point%2C%20we%20don%27t,%E2%80%9D). Avoid knee-jerk moves. Use the Fed news as a prompt to review your goals, but not as a signal to chase flashy returns. Long-term focus and consistency will serve retirees better than trying to outguess each rate decision [kiplinger.com](https://www.kiplinger.com/retirement/retirement-planning/retirees-make-these-financial-before-the-fed-cuts-rates#:~:text=,designed%20to%20withstand%20market%20fluctuations).
**[Get our easy Interest Rate Survival Guide](https://lp.constantcontactpages.com/sl/xUWBwt8/interestratesuvivalguide).**
**Bottom line:** A 25bp Fed rate cut mainly eases short-term bank funding costs; it doesn’t magically drop your mortgage or CD rates, which follow market yields [apnews.com](https://apnews.com/article/mortgage-rates-housing-federal-reserve-rate-cut-9351815c29cea1e27b531dec88d3e4da#:~:text=Mortgage%20rates%20generally%20follow%20the,guide%20to%20pricing%20home%20loans). For retirees with bonds held to maturity, your income stream stays reliable. It’s something to keep in mind as as future Fed rate cuts may occur later this year.
If yields do edge lower, your existing bonds are worth more today (you can sell for a gain if needed). Keep a comfortable cash buffer, hold a bond ladder, and maintain a diversified mix of stocks and bonds. By focusing on long-term stability rather than the latest Fed headline, your retirement portfolio can stay on track through rate cuts or hikes alike [kiplinger.com](https://www.kiplinger.com/retirement/retirement-planning/retirees-make-these-financial-before-the-fed-cuts-rates#:~:text=,designed%20to%20withstand%20market%20fluctuations)[kiplinger.com](https://www.kiplinger.com/retirement/retirement-planning/retirees-make-these-financial-before-the-fed-cuts-rates#:~:text=%E2%80%9CAt%20this%20point%2C%20we%20don%27t,%E2%80%9D).
**Remember:** This is information, not advice. Advice is what comes after a formal needs-analysis. Concerned about the impact of future interest rate moves on your long-term plans? Why not do this: Tell me [your priorities](https://indfin.com/retirement-priority-planning-review/), then [schedule an introductory call](https://go.oncehub.com/JimLorenzenCFP)!
If you haven’t done so already, you can [also subscribe to my newsletter.](https://visitor.r20.constantcontact.com/d.jsp?llr=fdk6idhab&p=oi&m=fdk6idhab&sit=icdtuhhgb&f=68947827-6cd6-46e6-a8a2-db365fc30f5c)
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Economy, Inflation
**Tags:** Interest rates, retirement decisions, Retirement Income, Retirement Planning
---
### [The OBBBA: A Tightrope Walk Moon Boots](https://indfin.com/the-obbba-a-tightrope-walk-moon-boots/)
**Published:** September 15, 2025
**Author:** Jim Lorenzen
**Excerpt:** Living in Moorpark, Simi Valley, or anywhere in Ventura County can make us feel like the OBBBA spending bill’s impact is a thousand miles away in Washington.
**Content:**
But here’s the thing: the OBBBA’s impact is going to show up in many investors’ portfolios, healthcare costs, and maybe even the taxes their kids and grandkids pay. In other words—people shouldn’t tune this one out.
Washington recently dropped a new acronym on us—the “OBBBA”—and, like most things coming out of Congress, it’s equal parts bold, messy, and expensive. On paper, it looks like a roadmap for the next decade of federal spending. In reality, it’s a juggling act with flaming torches, and taxpayers are the ones standing in the front row.
**Clear Shifts in Federal Spending Priorities**
The OBBBA doesn’t nibble around the edges—it redirects hundreds of billions of dollars in ways that will reshape entire industries and government safety nets for years to come.
- **Border security & defense**: Roughly $170 billion for the border and $150 billion for defense. That’s a clear signal: national security is still the top shelf priority. Defense contractors and anyone making drones, ships, or steel fences are smiling.
- **Healthcare, food, and energy cuts**: Medicaid, SNAP, and clean energy programs take a beating. States will be left scrambling to fill the gaps, rural hospitals may face cutbacks or even closures, and clean energy companies that were counting on momentum from the Inflation Reduction Act just had the rug pulled out. The Center for Climate and Energy Solutions estimates as many as 1.7 million clean energy jobs could disappear.
The winners here are fossil fuel producers and defense manufacturers. The losers? Families relying on safety nets, rural healthcare systems, and an entire clean energy job sector that just went from federal darling to afterthought.
**Fiscal Fallout: Deficits, Debt, and Downgrades**
**Here’s the part that makes the bond market twitch**: the OBBBA comes with a $3.3 trillion deficit increase over the next decade—closer to $4 trillion once you account for interest costs. The debt ceiling gets bumped up by $5 trillion, which means debt-to-GDP could hit 124%–130% by 2034. For perspective, that’s higher than the U.S. hit after WWII.
Even the ratings agencies are starting to frown. Moody’s has already downgraded U.S. credit once, and with interest payments eating a bigger slice of the pie, more downgrades are possible. Higher deficits plus higher yields is like putting a heavy golf bag on a wobbly cart—eventually something gives.
Here’s the visual (thanks to J.P. Morgan Asset Management): Federal Deficit and Net Interest as a Share of GDP, 1973–2034
*The chart makes it clear: under the OBBBA, deficits stay above 6% of GDP after 2028, while interest costs keep climbing.*
[](https://indfin.com/wp-content/uploads/2025/09/Fed-Deficit-Innterest-Pmts.png)**Conflicting Economic Forces**
The OBBBA is a bit of a paradox—it’s like pressing the gas and the brakes at the same time.
- **Short-term sugar high**: Corporate tax breaks and bonus depreciation are now permanent. Businesses may boost investment, and consumers could spend a little more when tax relief kicks in around 2026.
- **Long-term drag**: Higher tariffs and tighter immigration policies will shrink the labor supply, raise costs, and keep inflation stubborn. That forces the Fed to hold rates higher for longer.
- **Household squeeze**: With less federal support for healthcare, food, and education, many families will find their new tax break evaporating under higher out-of-pocket bills.
The net effect? A bigger deficit, persistent inflation pressures, and a Federal Reserve stuck with fewer levers to pull when the next crisis hits.
**Market Implications**
This is where it matters for portfolios. The OBBBA reshuffles the deck for investors:
- **Potential bright spots:** Defense, traditional energy, technology, and manufacturing. These are the sectors catching the tailwinds of new incentives and redirected federal dollars.
- **Likely headwinds**: Healthcare providers (especially those tied to Medicaid) and consumer staples (as households tighten budgets). Clean energy, once a golden child, will likely face turbulence.
- **Broader positioning:** U.S. large-cap growth is expensive. This could be a moment to diversify into international equities, value stocks, and sectors that benefit directly from government incentives.
Treasury yields are likely to stay elevated, so bond investors should prepare for a “new normal” of higher financing costs. Equities may get a boost from tax relief, but the persistent inflation risk is like sand in the gears—it keeps everything grinding just a little harder.
**The Bottom Line**
The OBBBA is a double-edged sword: permanent corporate tax breaks and bonus depreciation could spark fresh business investment, but the deficit expansion and inflationary pressures will keep rates higher, limit the Fed’s flexibility, and raise borrowing costs across the economy. Company CEOs and CFOs are holding off on hiring, faced with potentially higher borrowing costs coupled with unanswered inflation questions, while the Fed is dealing with it’s inflation mandate.
Think of it this way: Washington handed out a round of drinks at the bar—but they stuck it all on the national credit card with a sky-high APR.
**Takeaway Checklist for Advisors & Investors in Ventura County**
If you’re nearing retirement, whether you live in Moorpark, Simi Valley, or anywhere else in the U.S., here’s what this means for your financial game plan:
- If you have a professionally-prepared formal financial plan, be cautious about making drastic changes. Elections have a way of changing priorities and investors investing based on headlines seldom win.
- Higher rates may be around for awhile. This, of course, favors investors with short-to-intermediate bond ladders: bond values matter little as they will mature at face value if held to maturity – and should be replaced with higher yields.
- Stress-test your retirement plan. Make sure your income strategy holds up in a higher inflation, higher rate world.
In short: this isn’t about panic—it’s about positioning. The OBBBA rewired the federal playbook, and that means smart investors should be reviewing their plans for stress-testing and asset positioning*. \[Note: IFG clients recently completed a review and repositioning; so if you’re an IFG client, you’re all set.\]*
Here’s an OBBBA comparison guide you can download:
[2025\_OBBBA Comparison Guide](https://indfin.com/wp-content/uploads/2025/09/2025_OBBBA-Comparison-Guide.pdf)[Download](https://indfin.com/wp-content/uploads/2025/09/2025_OBBBA-Comparison-Guide.pdf)
**Sources:**
- J.P. Morgan Asset Management. “What’s in the One Big Beautiful Bill Act?.” July 15, 2025.
- J.P. Morgan Asset Management. “OBBBA and the Cold-Hot-Cold Forecast.” July 14, 2025.
- PwC Health Research Institute. “Impact of the OBBBA on the U.S. Health System.” July 2025.
- J.P. Morgan Asset Management. “One Big Beautiful Bill Act: What Retirement Savers Need to Know.” July 2025.
- Thomson Reuters. “Impact of the One Big Beautiful Bill Act.” July 2025.
- Bryce Engelland. “Economic & Global Trade Impact of the One Big Beautiful Bill Act.” Thomson Reuters. July 17, 2025.
Tell me [your priorities](https://indfin.com/retirement-priority-planning-review/), then [schedule an introductory call](https://go.oncehub.com/JimLorenzenCFP)! You can [also subscribe to my newsletter.](https://visitor.r20.constantcontact.com/d.jsp?llr=fdk6idhab&p=oi&m=fdk6idhab&sit=icdtuhhgb&f=68947827-6cd6-46e6-a8a2-db365fc30f5c)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Retirement Planning, Unplugged: How to Stop Losing Sleep Over Money, Markets, and the IRS.](https://indfin.com/retirement-planning-unplugged-how-to-stop-losing-sleep-over-money-markets-and-the-irs/)
**Published:** September 8, 2025
**Author:** Jim Lorenzen
**Excerpt:** Retirement planning can be like trying to juggle sharp objects. One mistake could have lasting consequences; so, maybe it’s better to wait ‘til tomorrow.
**Content:**
Retirement planning decisions are often accompanied by legitimate fears: running out of money; deciding when to pack it in; and deciphering the alphabet soup of IRS rules (RMDs, Social Security claiming; how to manage a nest-egg so money can last over several decades. How do we coordinate all that? anyone? … anyone? ….. Buehler? Buehler?……Buehler?
Retirement planning can be complicated – Let’s break it down into plain English. I’ll try to keep it light to help the medicine go down. By the time you finish this, you may have the framework to reduce worrying, hopefully start planning, and maybe even sleeping better at night. Stress comes from not having answers – or even a plan. So, it shouldn’t be hard to guess how to limit stress.
There are three basic fears many pre-retirees face:
**Fear #1: Running Out of Money**
This is the big one. According to a recent study, nearly three-quarters of pre-retirees worry about this and 60% feel overwhelmed by all the decisions. And, believe it or not, even those considered wealthy have the same concerns simply because their living standard consumes more of their liquid wealth.
If retirement were golf, this is a 200-yard water hazard smack in the middle of the fairway. Nobody wants to outlive their income. The good news? You don’t have to.
A smart retirement income plan isn’t about living on a strict budget that feels like you’re back in college eating ramen noodles. It’s about creating different streams of income that can last. The usual contributors:
- **Social Security**: Your base paycheck for life. The longer you wait to claim (up to age 70), the bigger the check. Those thinking of retiring earlier usually worry about whether they should claim early (to avoid tapping their retirement plan), or whether to wait on claiming and tap into their retirement plan early. And, there [are issues many miss](https://indfin.com/why-claiming-social-security-at-age-70-could-be-a-smart-move-but-heres-what-most-people-miss/). Naturally, Uncle Sam’s take on al this becomes an issue, too.
- **Pensions** (if you’re one of the lucky ones still holding a golden ticket): Steady, predictable income. Few people have this option these days; but, outside of government pensions, I don’t know of a single private company plan that offers cost of living increases. That means that whatever the size of your pension income, it will buy 29% less in just ten years if inflation averages 3.5%. To put that into dollars, it means $5,000 will purchase only $3,544 worth of goods and services. And, of course, it’s taxable. Do you know what tax rates will be?
- **Investment accounts**: The flexible players. This is where your 401(k), IRA, and brokerage accounts come in. The problem, [as I’ve discussed before](https://indfin.com/ira-beneficiary-rules-for-children-are-different/), is the SECURE Act – which does more to secure the government than your heirs. Children or grandchildren inheriting any of these accounts will have to liquidate them in ten years. Do the math: what age will they likely be? Will they be in their highest earning years? Add these inheritances to their income and Uncle Sam might well have a big pay day!
The trick is having a strategy for the location of assets that combines these sources in a way that provides both stability and flexibility. Your golf bag has 14 clubs. One club won’t do the job. And, it helps to have a game plan. Same goes for retirement. A portfolio balanced for both growth and income gives you shots at the green while strategizing for taxes still keeping you out of the sand traps.
**Fear #2: When to Retire (a.k.a. “Is Now a Bad Time?”)**
Inflation is like that playing partner who talks during your backswing— always annoying, distracting, and showing up uninvited. Add in market volatility, and no wonder people are pushing off retirement. “Waiting until things settle down” never (NEVER) works. Recent surveys show nearly a quarter of pre-retirees are delaying retirement simply because they don’t feel confident. Problem is they’ll *never* feel confident.
Here’s the truth: **there’s never a “perfect” time to retire**. Waiting for the market to settle down is like waiting for Southern California rush hour traffic to magically disappear—it’s not happening. The stock market is *always* somewhere between slightly jittery and downright dramatic. If it was predictable, *everyone* would be wealthy and there would be nothing special about Warren Buffett.
Instead, the decision of *when* to retire comes down to one thing: does your plan work in bad times as well as good? Have you back-tested it against the crash of 1987, the melt-down of 2008-9? The Great Depression? Knowing your downside exposure can help you tweak your strategy and reduce anxiety when (not ‘if’) bad things happen.
*“The only thing that surprises me is that we are surprised when surprise happens.”*
*– Donald Rumsfeld, former Secretary of Defense, Known and Unknown.*
A retirement strategy that succeeds only if inflation drops or the market soars is like a golf swing that works only if the wind is blowing at exactly 7 mph from the west. Still waiting.
So how do you retire in uncertain times? By building resilience and a small measure of predictability into your retirement planning. You want your plan to address concerns and help reduce downside surprises:
- **Inflation protection**: Investments for long-term growth so your income keeps pace with rising costs over time.
- **Cash reserves**: Keeping a cushion so you don’t have to sell investments at a bad time.
- **Flexibility**: Knowing what expenses are fixed and what can be adjusted if needed.
- **Tax optimization**: Locating assets in a way that preserve value for you and your family, instead of Uncle Sam – see below.
To put it simply: you don’t retire when the economy looks calm—you retire when your plan is sturdy enough to laugh at the economy’s mood swings.
**Fear #3: The IRS Rulebook (a.k.a. “I Need a Decoder Ring”)**
Required Minimum Distributions (RMDs) and tax rules around withdrawals make most people’s heads spin. It’s like being handed the rulebook to cricket—like that helps.
Here’s the cheat sheet:
- **RMDs**: The IRS requires you to start pulling money out of tax-deferred accounts (like traditional IRAs and 401(k)s) starting in your early 70s. Required minimum distributions are required because they want their tax revenue, whether you need the money or not.
- **Taxes**: Withdrawals from these accounts count as income, which can bump you into higher tax brackets. It can also affect how much of your Social Security is taxable and even increase Medicare premiums. And, as noted earlier, children and grandchildren inheriting have to liquidate their inherited IRAs in ten years. Anyone want to guess what tax rates will be ten years after they inherit? Anyone? Buehler? Buehler? ….. Buehler? Hmmm.
- **Strategy matters**: Without planning, you could end up paying more in taxes during retirement than when you were working. I would spend time explaining this, but you’ve endured enough.
Roth conversions, careful timing of withdrawals, and smart tax planning can turn a potential disaster into an opportunity. It’s good to have a caddie – experience and guidance can often make a difference. Be the ball.
**Why These Three Fears Are Connected**
Running out of money, knowing when to retire, and understanding withdrawals aren’t separate issues. They’re three sides of the same triangle (I say that because a coin has only two sides).
Your income plan, your retirement date, and your tax strategy all influence one another. For example:
- Retire too early without inflation protection, and you risk outliving your money. I’ve never seen anyone list this as a goal.
- Delay Social Security too long without a solid income bridge, and you stress cash flow. It’s good to run alternate scenarios.
- Ignore tax planning, and you hand over too much to Uncle Sam, draining your nest egg faster. He’s a partner in your retirement – and some partner: he writes the rules unilaterally and you have to live with his decisions.
Good retirement planning doesn’t treat these in silos—it brings them together. Done right, your retirement income lasts longer, your timing feels less like a gamble, and you pay fewer taxes over your lifetime. Hmmm. Tough decision.
**The Bottom Line**
Retirement doesn’t have to be a constant panic attack. The antidote to fear is a plan: one that blends dependable income, cushions against inflation, and choreographs withdrawals in a tax-smart way. With that in place, you can spend less time stressing over IRS acronyms and market headlines, and more time focusing on what really matters—like lowering your golf handicap, spoiling the grandkids, or finally learning how to make sourdough bread.
**Ready to Retire? Ask Yourself These 5 Questions**
Here’s your quick checklist. If you can answer “yes” to these, you’re on solid footing:
1. Do I know how much I need each month? How about ten or fifteen years from now —and will I have reliable income sources to cover it?
2. Have I stress-tested my plan for inflation and market downturns? How about under a different tax regime after ten or fifteen years of inflation?
3. Do I know the best time for me to claim Social Security?
4. Do I have a tax strategy for my withdrawals and RMDs? Do I have a strategy for transferring these assets to my children and/or grandchildren without the ten-year RMD requirement and with little or no tax issues?
5. Have I thought about the non-financial side of retirement—what I’ll do with my time? What will you do and is this factored into your current plan?
If you don’t feel fully confident about your answers, it’s not the end of the world. You’ve already made progress just identifying some key issues! How do you eat an elephant? One bite at a time. Here’s how to get started: [get started](https://indfin.com/getting-started/).
Enjoy!
Jim
Tell me [your priorities](https://indfin.com/retirement-priority-planning-review/), then [schedule an introductory call](https://go.oncehub.com/JimLorenzenCFP)! You can [also subscribe to my newsletter.](https://visitor.r20.constantcontact.com/d.jsp?llr=fdk6idhab&p=oi&m=fdk6idhab&sit=icdtuhhgb&f=68947827-6cd6-46e6-a8a2-db365fc30f5c)
**Here are some checklists you might find helpful:**
[SS\_What-Issues-Should-I-Consider-With-My-Social-Security-Retirement-Benefits-2025](https://indfin.com/wp-content/uploads/2025/09/SS_What-Issues-Should-I-Consider-With-My-Social-Security-Retirement-Benefits-2025.pdf)[Download](https://indfin.com/wp-content/uploads/2025/09/SS_What-Issues-Should-I-Consider-With-My-Social-Security-Retirement-Benefits-2025.pdf)
[Retirement\_What-Issues-Should-I-Consider-Before-I-Retire-2025](https://indfin.com/wp-content/uploads/2025/09/Retirement_What-Issues-Should-I-Consider-Before-I-Retire-2025.pdf)[Download](https://indfin.com/wp-content/uploads/2025/09/Retirement_What-Issues-Should-I-Consider-Before-I-Retire-2025.pdf)
[Recession\_What-Issues-Should-I-Consider-During-A-Recession-Or-Market-Correction-2025](https://indfin.com/wp-content/uploads/2025/09/Recession_What-Issues-Should-I-Consider-During-A-Recession-Or-Market-Correction-2025.pdf)[Download](https://indfin.com/wp-content/uploads/2025/09/Recession_What-Issues-Should-I-Consider-During-A-Recession-Or-Market-Correction-2025.pdf)
[Invest\_What-Issues-Should-I-Consider-When-Reviewing-My-Investments-2025](https://indfin.com/wp-content/uploads/2025/09/Invest_What-Issues-Should-I-Consider-When-Reviewing-My-Investments-2025.pdf)[Download](https://indfin.com/wp-content/uploads/2025/09/Invest_What-Issues-Should-I-Consider-When-Reviewing-My-Investments-2025.pdf)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [The SECURE Act Has Changed Inheritance Rules.](https://indfin.com/the-secure-act-has-changed-inheritance-rules/)
**Published:** September 2, 2025
**Author:** Jim Lorenzen
**Excerpt:** If your IRA or 401(k) money will be inherited by your children or grandchildren (or any nonspouse), they have to drain the account within 10 years.
**Content:**
**Do the math**: what age will they likely be? Will they be in their highest earning (tax liability) years? The SECURE Act may secure the government; but it has made traditional retirement saving vehicles less than attractive options for either retirement or asset transfer. *(Note: you can [subscribe to ](https://lp.constantcontactpages.com/sl/3hChtqP/SECUREActIssues)[the IFG newsletter](https://lp.constantcontactpages.com/sl/3hChtqP/SECUREActIssues) and learn more about SECURE Act and other issues worth knowing*).
Non-spouse beneficiaries face decisions; here are a few:
[IRA\_Traditional\_Inherited\_Non Spouse – How-Must-I-Take-Distributions](https://indfin.com/wp-content/uploads/2025/09/IRA_Traditional_Inherited_Non-Spouse-How-Must-I-Take-Distributions-2.pdf)[Download](https://indfin.com/wp-content/uploads/2025/09/IRA_Traditional_Inherited_Non-Spouse-How-Must-I-Take-Distributions-2.pdf)
**Remember, every dollar withdrawn is taxed as income.** For wealthy families, the account could also face estate taxes – do you know what the law will be when this happens? And, don’t forget, some states have their own estate taxes.That double hit can strip away a big chunk of value—fast.
Wealth replacement trusts are often used by people who want their heirs to receive the full value of assets that would otherwise shrink due to estate taxes or charitable gifts. They’re especially useful for large retirement accounts, which, as I indicated, are some of the least efficient assets to leave to children or other nonspouse heirs. Estate tax exemptions are high now; but, that could change in future years – the government does like to spend and give away money for votes.
**The Estate Tax Solution: An Irrevocable Life Insurance Trust (ILIT)**
Many high-net-worth families use an ILIT to offset those tax losses. Here’s how it typically works:
- You take annual withdrawals from your IRA or retirement plan.
- Part of that withdrawal covers the taxes due.
- The rest funds life insurance premiums inside the ILIT.
- As long as those gifts stay under the annual gift-tax exclusion, no gift tax applies.
**Why It Works**
An ILIT can be surprisingly efficient. Benefits include:
- **Shrinks the estate each year.** Retirement account balances go down, which helps reduce future estate taxes. Keep in mind—federal exemptions are high now, but states often have their own estate tax rules.
- **Tax-neutral withdrawals.** The withdrawal pays for both the life insurance premium and the income tax due. Example: If the annual premium is $180,000 and you’re in a 24% tax bracket, withdrawing about $236,800 covers both the tax bill and the premium—without dipping into other assets.
- **Gift-tax friendly.** If structured properly, the after-tax dollars sent to the ILIT can qualify for the annual gift-tax exclusion. For couples, gift-splitting doubles the benefit.
- **Estate tax protection.** The ILIT itself is outside your estate, so the life insurance death benefit won’t add to your estate tax exposure.
- **Tax-free death benefit.** The ILIT receives the insurance proceeds tax free. Those funds can cover estate taxes and administration costs or provide liquidity for heirs.
- **Flexible distributions.** Beneficiaries can receive proceeds tax free, either as cash or as property purchased by the trust.
In short, wealth replacement trusts—funded through an ILIT—can turn a tax-inefficient asset (like a retirement account) into a tax-efficient legacy for your family.
**Not concerned about estate taxes?**
The SECURE Act is still a major issue for most everyone; and cash value permanent insurance is becoming a much more attractive option to leaving an IRA or other tax-deferred vehicle to children or grandchildren. The advantages are obvious: advanced designs can provide for enhanced cash buildup – money you can use while you’re alive, tax-free when you want it.
Also, there are no RMDs for you and no 10-year rule – and your children and grandchildren can inherit tax free money. It’s little wonder people are changing the way they think about how they locate retirement assets. Maybe you should, too.
Tell me [your priorities](https://indfin.com/retirement-priority-planning-review/), then [schedule an introductory call](https://go.oncehub.com/JimLorenzenCFP)! You can [also subscribe to my newsletter.](https://visitor.r20.constantcontact.com/d.jsp?llr=fdk6idhab&p=oi&m=fdk6idhab&sit=icdtuhhgb&f=68947827-6cd6-46e6-a8a2-db365fc30f5c)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [How to Handle Cognitive Decline Transferring Financial Control](https://indfin.com/how-to-handle-cognitive-decline-transferring-financial-control/)
**Published:** August 25, 2025
**Author:** Jim Lorenzen
**Excerpt:** Cognitive decline? What? I don’t remember forgetting anything…
**Content:**
The Baby Boomers are officially in retirement territory. The same folks who once packed Woodstock and watched Mary Richards toss her hat in the air are now seeing their old idols pitch walk-in tubs and prescription drugs on TV.
They’ve built serious wealth—remember when $50,000 a year felt huge and a $1 million nest egg meant you were set for life? Not so much anymore. Money is worth only what it buys – and $1 million is worth about $35,000 to $40,000 a year, unless you want to run out of money early.
Inflation has a way of moving the goalposts. But there’s another risk that doesn’t get as much attention: the mental slip-ups that come with age. Money mistakes due to cognitive decline can be just as damaging as a bear market. So the smart move is to plan ahead.
**Protecting Your Money from Cognitive Decline**
**Step 1: Pick the right person.**
A spouse is the obvious choice, but since they’re likely close to the same age, it’s good to have a backup. You want someone trustworthy, organized, and good with money. It’s fine to split the duties—one handles bills, another oversees investments.
**Step 2: Organize your financial life.**
Make a list of your accounts, assets, debts, and income sources. Write down your recurring bills and subscriptions. Yes, keep a secure list of passwords. And please—simplify. Do you really need 14 different accounts scattered all over? Help your future advocate by decluttering.
**Step 3: Start the conversation.**
This doesn’t have to be dramatic. A simple:
*“I respect how you’ve handled your finances, and I’d like your help if I ever can’t manage mine.”*
Reassure them you’re fine now. You’re just putting guardrails in place.
**Step 4: Spell out your wishes.**
Walk your advocate through your finances, explain what matters most, and put it in writing.
**Step 5: Make it official.**
Your advocate can’t just walk into the bank and start moving money around. You need a legal financial power of attorney (POA). Remember, it ends at your death—at that point, your executor takes over.
**Step 6: Hand off gradually.**
Signs of cognitive decline that signal it might be time: forgetting bills, making strange investment requests, or falling for too-good-to-be-true offers. Sometimes the signs are subtle, so write down in advance what should trigger the transition.
**The Hard Part: Knowing When to Let Go**
Here’s the truth: most people don’t suddenly lose capacity from a stroke or Alzheimer’s. More often, cognitive decline begins as a slow drip—missed bills, odd purchases, or questionable “friends” who are really scammers. And because the decline is gradual, people don’t always realize they’re slipping. That’s why elder scams are so common.
The risk isn’t just **whether** you give someone power of attorney—it’s **when** they actually step in. Too often, families wait until real damage has been done. Boston College research shows the average estimate of that damage is 18% of wealth. That’s not pocket change.
To make matters worse, people with high confidence and strong financial skills are often hit hardest—they don’t notice their decline, keep managing money themselves, and take bigger risks.
And don’t be surprised if your bank makes this harder. Many institutions want you to sign their own POA forms, not just the one your lawyer drafted. (You’re welcome.)
**Spotting Trouble Early**
Sometimes a financial advisor sees the warning signs of cognitive decline before family does—missed meetings, odd withdrawal requests, or “unique investment opportunities.” But you don’t want it to get to that point. Better to have the conversation while things are calm.
Signs to watch for (courtesy of Mayo Clinic):
- Forgetting things more often
- Missing appointments or social events
- Losing your train of thought or following a conversation
- Struggling with directions in familiar places
- Declining judgment (bad financial or personal decisions)
- Family and friends noticing changes before you do
These aren’t accusations—they’re just red flags worth discussing.
**Making the Transition Smoother**
This doesn’t have to be an all-or-nothing shift. Many families start with “oversight” rather than full takeover. Maybe your adult child shadows you, double-checks bills, or monitors accounts. Over time, as comfort and need increase, they step into the driver’s seat. Here’s a quick **Family Guide to Generational Planning.**
[IFG\_Family Guide to Generational Planning](https://indfin.com/wp-content/uploads/2025/08/IFG_Family-Guide-to-Generational-Planning.pdf)[Download](https://indfin.com/wp-content/uploads/2025/08/IFG_Family-Guide-to-Generational-Planning.pdf)
It’s like handing over the car keys on a long road trip—you don’t just throw them to someone at 70 mph. You switch drivers at a rest stop. Same with finances: gradual, intentional, and safe. Naturally, it’s good to have a plan. Here’s a **Generational Planning Checklist** you might find helpful.
---
[IFG\_Generational Planning Checklist](https://indfin.com/wp-content/uploads/2025/08/IFG_Generational-Planning-Checklist.pdf)[Download](https://indfin.com/wp-content/uploads/2025/08/IFG_Generational-Planning-Checklist.pdf)
**Takeaway:**
Cognitive decline isn’t rare, it isn’t personal, and it isn’t a reason to panic. The best defense is to face it head-on, set up the right people and paperwork, and make the transition gradual. That way, your money stays protected—and you stay in control of how the handoff happens.
You can read more about **Intergenerational Transfers here.**
[IFG\_Intergenerational Transfers](https://indfin.com/wp-content/uploads/2025/08/IFG_Intergenerational-Transfers.pdf)[Download](https://indfin.com/wp-content/uploads/2025/08/IFG_Intergenerational-Transfers.pdf)
Is your financial house in order? Would you like some help?
[Tell me your priorities](https://indfin.com/retirement-priority-planning-review/)! Then….
[Schedule your introductory call](https://go.oncehub.com/JimLorenzenCFP)!
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues, Health, Inheritance, Planning
**Tags:** Alzheimers, cognitive decline, Dementia, generational planning
---
### [Don’t Miss Your Roth Conversion Window](https://indfin.com/dont-miss-your-roth-conversion-window/)
**Published:** August 18, 2025
**Author:** Jim Lorenzen
**Excerpt:** If you’ve built a large retirement nest egg, you’ve also built a large tax problem.
**Content:**
Why consider a Roth conversion? Simple: For decades, the playbook was simple: defer taxes as long as possible, let your IRA grow, and only take money out when the government makes you do it.
That worked when tax rates were high and deferral gave you a big edge. It’s different now – with historically low tax brackets, the SECURE Act changing inheritance rules, and Washington’s spending tab climbing higher every day—that old “delay, delay, delay” playbook just may very well backfire for many unsuspecting investors… and especially their beneficiaries, usually their children.
As a practicing fiduciary financial advisor serving Moorpark, Simi Valley, and Ventura County, I’ve seen this issue come up often for affluent pre-retirees. Instead of asking, *“What’s the minimum I have to take out?”* the smarter question may be, *“What’s the maximum advantage I can get while the Roth conversion window is still open?”*
**The SECURE Act Changed the Rules of the Game**
Passed in late 2019, the **SECURE Act** reshaped retirement planning in two big ways:
1. **RMDs now start later.** You get an extra 18 months before Required Minimum Distributions kick in. Nice, but not game-changing.
- For those born in 1950 or earlier: Your RMDs began at age 72 (or 70 1/2 if you reached that age prior to 2020).
- For those born between 1951 and 1959: Your RMDs begin at age 73.
- For those born in 1960 or later: Your RMDs will begin at age 75.
2. **The stretch IRA is gone.** Your children now have only 10 years to drain an inherited IRA. And if they inherit during their peak earning years? Those withdrawals pile on top of their income, potentially pushing them into punishing tax brackets. [You might like my video about this.](https://vimeo.com/948781448/7f4e6bf795?&login=true#_=_)
In plain English: what used to be a gift of lifetime income can now be a gift of lifetime tax headaches – especially for your heirs.
**Why “Minimum” Thinking Can Be Costly**
The government calls it a *required minimum distribution*. Minimum, as in: do the least. But “minimum” thinking may be costing families millions in avoidable taxes, whether they live in Simi Valley, Moorpark, or anywhere else.
Here’s why:
- **Taxes are on sale.** Federal brackets are at historic lows. Yes, I know, the tax laws were made ‘permanent’. That’s Washington, D.C. talk for no expiration date; but, the truth is ‘permanent’ means ‘until congress changes the law.
- **Waiting means less control.** Once RMDs start, you don’t get to choose how much to withdraw—the IRS decides.
- **Your heirs inherit the tax mess.** A $2 million IRA could grow to over $3 million in ten years even at an annual 5% growth rate – and force your kids to add $200,000 per year in taxable income on top of their salaries. What will the tax brackets be in ten years? Don’t know? We’re not gambling with house money.
**The Power of a Roth Conversion**
A **Roth conversion** lets you move money from your pre-tax IRA into a Roth IRA. You’ll pay the tax bill now, at today’s known rates, and from then on the money grows and comes out tax-free.
Why it matters:
- **Tax-free growth for life.** Once converted, you’ve locked in future tax freedom.
- **Flexibility in retirement.** Roth withdrawals don’t inflate your taxable income or Medicare premiums.
- **A cleaner legacy.** Your heirs still have to withdraw within 10 years, but Roth dollars come out tax-free. That’s a far better gift than a tax-loaded IRA.
**Two hypothetical examples:**
**Case 1: John and Susan, age 62, Moorpark.**
They retire with $2 million in IRAs and modest income from part-time consulting. With 10 years before RMDs, they convert $150,000 per year into a Roth, staying within the 24% bracket. They pay taxes separately from a brokerage account. By age 72, they’ve shifted $1.5 million into Roth, cut their RMDs dramatically, and set up their kids for tax-free inheritance.
**Case 2: Mike, age 72, Simi Valley.**
Mike delayed withdrawals, followed the “minimum” strategy, and now RMDs push him into higher brackets. His Medicare premiums rise. When he passes, his kids inherit a $1 million IRA and a giant tax problem—they must drain it in 10 years, paying taxes on this increased income on top of their six-figure salaries.
Both followed the rules. Only one family avoided the trap.
**Who Should Consider Roth Conversion Planning?** [Here’s a decision tree to help](https://indfin.com/wp-content/uploads/2025/08/2024_Should-I-Consider-Doing-A-Roth-Conversion.pdf).
This strategy isn’t one-size-fits-all, but it may be ideal if:
- You expect tax rates to rise.
- You’re in a lower bracket now than you will be later.
- You can pay conversion taxes from non-IRA money.
- You want to leave tax-free assets to your heirs.
- You’re in the “gap years”—retired but not yet 72.
I’ve found Roth conversions especially valuable for affluent pre-retirees with $1M+ portfolios who want control over their future tax bill.
**Timing Is Everything**
The window won’t stay open forever. Today’s lower tax brackets expire after 2025. Once RMDs begin, your flexibility shrinks. And if Congress raises rates sooner, the deal gets worse.
Taxes are “On Sale” That’s why the next few years may be your best chance to convert strategically.
**The Bottom Line**
The SECURE Act closed the door on some old retirement strategies but opened a wider door for proactive tax planning. A well-timed Roth conversion can reduce your lifetime taxes, give you more flexibility in retirement, and leave your kids a cleaner, tax-free legacy.
The Roth conversion window is open. The question is: will you take advantage before it closes?
Would you like some help? [Tell me a little about your situation](https://indfin.com/retirement-priority-planning-review/) (no sensitive info required). Then, [schedule your introductory call!](https://go.oncehub.com/JimLorenzenCFP)
No time like the present!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Inheritance, IRAs, Roth conversions, SECURE Act, Taxes
**Tags:** Roth conversions, Roth IRA, tax law changes, tax planning, Tax-Free Retirement Income
---
### [Who is Your Trust’s Successor Trustee? Family or Friend?](https://indfin.com/who-is-your-trusts-successor-trustee-family-or-friend/)
**Published:** August 11, 2025
**Author:** Jim Lorenzen
**Excerpt:** Most people hand the successor trustee job to a family member. It feels right… until it goes wrong.
**Content:**
[](https://indfin.com/wp-content/uploads/2025/08/Man-Pondering.png)When most people set up a trust, they name a family member or friend as the successor trustee. It feels natural — you trust them, you know them. But that doesn’t automatically make them the right choice.
Being a trustee is a big job. Before you make it official, ask yourself:
- **Do they have the skills?** A trustee isn’t just a name on paper. They’re responsible for complex trust administration, detailed record-keeping, and understanding tax and trust laws.
- **Will they keep up with changing laws?** Trust law varies by state, and it’s usually based on where the trustee lives — not the beneficiary. State taxes and asset protection rules may come into play.
- **Can they stay objective?** Family relationships change. Even close bonds can strain over time, and personal agendas can get in the way.
- **What if they’re no longer around?** If your trustee dies or becomes incapacitated, who steps in? Will that person be as trustworthy? Will they be around for the life of your trust?
- **Are they financially stable?** If your trustee faces personal financial trouble, that could create unnecessary risks.
**Why a Corporate Trustee Might Make Sense**
Instead of relying on a family member, you could name a corporate trustee — a bank or independent trust company licensed to handle trusts. Their job is straightforward: carry out the instructions in your trust and manage assets in line with your wishes.
**Advantages of a corporate trustee:**
- A full-time team trained in trust administration, tax rules, and record-keeping.
- No family politics — decisions are objective and by the book.
- They don’t “expire” — a corporate trustee can serve for multiple generations.
- They’re financially stable, regulated, insured, and legally bound to act as a fiduciary.
**Keeping Checks and Balances in Place**
If you’re picturing a faceless institution holding all the cards, here’s where smart structure comes in. The right setup creates firewalls between your trustee, your money, and your beneficiaries.
Think of it like a well-coached football team:
- **Your Advisor = Quarterback**
Your independent, *CERTIFIED FINANCIAL PLANNER*® professional helps design the playbook, chooses the players, and makes sure everyone sticks to the game plan.
- **Independent Custodian**
Your trust’s assets are held with a custodian your advisor selects — and neither the advisor nor the corporate trustee can dip into the funds outside of the trust’s rules.
- **Independent Management**
Investments are managed using best practices, with transparency and regulatory oversight.
- **Corporate Trustee**
Distributes income or assets strictly according to the trust’s instructions and state laws.
Some families even choose corporate trustees in states with trust-friendly laws, like Nevada — no state income tax, strong asset protection, and trusts that can last up to 365 years. That means wealth can grow across multiple generations without being taxed each time it changes hands.
**The Bottom Line**
Choosing the right trustee isn’t just about who you trust today — it’s about protecting your wishes, your beneficiaries, and your legacy for decades (or centuries) to come.
No trust? What should you be considering? Here’s your roadmap.
[Should-I-Consider-A-Trust](https://indfin.com/wp-content/uploads/2025/08/Should-I-Consider-A-Trust.pdf)[Download](https://indfin.com/wp-content/uploads/2025/08/Should-I-Consider-A-Trust.pdf)**If you’re already a trust beneficiary**, take a closer look at your current setup.
Do you know who your trustee is? Are you paying more in taxes than necessary? You might benefit from a more efficient, independent structure. Are assets independently managed or under the same roof?
I**f you’d like your trust reviewed, let me know.** I’ll get it done for you. Maybe I can help you! Tell me [your priorities](https://indfin.com/retirement-priority-planning-review/), then [schedule an introductory call](https://go.oncehub.com/JimLorenzenCFP)! You can [also subscribe to my newsletter.](https://visitor.r20.constantcontact.com/d.jsp?llr=fdk6idhab&p=oi&m=fdk6idhab&sit=icdtuhhgb&f=68947827-6cd6-46e6-a8a2-db365fc30f5c)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Planning for a Special Needs Child's Future](https://indfin.com/planning-for-a-special-needs-childs-future/)
**Published:** August 4, 2025
**Author:** Jim Lorenzen
**Excerpt:** Today, nearly 57 million Americans have disabilities, according to the U.S. Census Bureau Reports issued July 25th. About half of them will require costly care throughout their lifetimes. Unfortunately, few parents are fully aware of all the risks they’re taking by not making special provisions for their special needs child.
**Content:**
Disabilities seem so common today. It seems almost every family is faced with the challenges of helping a child with special needs. Unfortunately, few parents are fully aware of all the risks they’re taking by not making special provisions for their special needs child.
**By inheriting his/her share of the parents’ assets, the child will *forever* be disqualified from receiving government benefits** like group housing, vocational training, and Medicaid or Medi-Cal. The fact is only by structuring the child’s inheritance as a special needs trust can the parents be sure their child will have both the necessary resources and the needed government benefits – for the remainder of his/her life.
**Today, nearly 57 million Americans have disabilities,** according to the U.S. Census Bureau Reports issued July 25th. About half of them will require costly care throughout their lifetimes.
A special needs trust can provide income for disabled beneficiaries’ future medical expenses, while maintaining eligibility for Supplemental Security Income (SSI), Medicaid, and other government benefits.
While 69% of families say they’re very concerned about providing lifetime care for their dependents with special needs, only around 12% have set up a special needs trust.
**Providing income can be tricky.** Government benefits phase out at very low levels. For example, SSI is available to individuals with less than $2,000 in assets – yes, you read that correctly – or couples with less than $3,000! Families who give their disabled relatives assets, either while alive or as part of their estates, can easily also make sure the child is no longer eligible for benefits.
**Some issues to consider:**
- If you named a family member to act as a trustee to administer the trust: what happens if something should happen to your trustee after you’re gone. Who steps in then? Is their a void – or a new trustee who is unqualified, or worse, untrustworthy?
- How will you fund the trust to provide the necessary assets to provide needed income for your child? What if something happens to you before the trust can be fully funded? Or, is this a gamble you’re willing to take with your child’s future?
- Who will manage the trust to help ensure the assets will be arranged responsibly? Will uncle Joe or aunt Betty be making it up as they go along – or worse – be watching Cramer for stock tips?
**Administration**: you want a qualified trustee to administer trust provisions – one that is independent, regulated, is legally required to function as a fiduciary, and – important – doesn’t die. Read on.
**Asset custody**: custody should be independent of administration. The assets reside should reside at an independent third party custodian. The trustee can administer the trust provisions, but the trustee does not have possession of the trust assets.
**Asset management**: asset management should be independent of administration and custody. Asset management is provided by an independent third party registered investment advisor, also regulated and legally required to function as a fiduciary. The advisor does not have access to the beneficiaries’ funds which reside at an independent custodian which can disburse funds only in compliance with the trustee’s instructions which are subject to regulatory oversight and fiduciary liability. It would also help if the investment advisor is *a CERTIFIED FINANCIAL PLANNER®* professional.
**Quick review: common pitfalls to avoid**
**1. The wrong trustee**
It’s common to name a relative as trustee, but what if they pass away or are unable to serve? Worse—what if they mean well but aren’t equipped to handle the legal, tax, and benefit rules?
**2. Underfunding the trust**
If you die before the trust is funded—or fund it too little—it may not cover your loved one’s lifetime needs. This isn’t something to “figure out later.”
**3. Amateur money management**
Aunt Betty and Uncle Joe might be wonderful people, but investing trust assets based on TV stock tips isn’t a sound plan.
**Steps to start planning**
Here are some steps you can take to protect your children:
- **Name a guardian**: Do this before your special needs child reaches adulthood so this person can continue to make decisions after the child reaches age 21. Most families also name a successor guardian, often a sibling, to take on these responsibilities after the parents pass away.
- **Write a will**: The will should name a successor guardian for the disabled child, in addition to providing for distribution of the estate.
- **Decide where your child will live** after you’re gone: the child will need housing and care.
- **Identify a trustee**: The trustee will be in charge of managing and distributing assets held in the trust. A corporate trustee can ensure that distributions cannot be considered as income to the beneficiary and conform to public benefit programs and laws. Solutions like direct bill-pay, credit cards, debit cards, and budgets can be set up to ensure the beneficiaries’ needs are met.
- **Funding**: begin setting aside money. Do you have a plan make sure the trust is fully funded? Even moderately wealthy families can benefit- and funding can come from a variety of sources. How much will you need to fully fund a trust to meet your special needs child’s requirements for life at different inflation rates?
- **Write a letter of intent:** A Letter of Intent (LOI) provides critical caregiving instructions to future guardians, trustees, and advocates of a special needs beneficiary.
- **Set up a special needs trust:** these specialized vehicles provide the mechanism for meeting the disabled beneficiaries’ supplemental expenses. Where will your trust be cited? You may want to avoid a high-tax state.
**How to eat an elephant: one bite at a time.**
Would you like an independent and qualified personal ‘quarterback’ to coordinate all the various service components and make sure it’s integrated into your personal plan? This is a landscape where professional navigation can be a big help.
Maybe I can help you! Tell me [your priorities](https://indfin.com/retirement-priority-planning-review/), then [schedule an introductory call](https://go.oncehub.com/JimLorenzenCFP)! You can [also subscribe to my newsletter.](https://visitor.r20.constantcontact.com/d.jsp?llr=fdk6idhab&p=oi&m=fdk6idhab&sit=icdtuhhgb&f=68947827-6cd6-46e6-a8a2-db365fc30f5c)
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Special needs
**Tags:** special needs, special needs trusts
---
### [Is the “Trump Account” a Good Deal?](https://indfin.com/is-the-trump-account-a-good-deal/)
**Published:** July 29, 2025
**Author:** Jim Lorenzen
**Excerpt:** Short answer: Not really. Middle to high income families may not feel it’s worth the headaches and low income families may see little benefit.
**Content:**
You’ve probably seen the Trump Account headlines: “Every newborn gets $1,000!” “Family members can add $5,000 a year!” Sounds like a game-changer, right?
In theory, the so-called “Trump Account” is meant to help close the wealth gap by giving every U.S. citizen born between January 1, 2025, and December 31, 2028, a head start — automatically creating a savings account with a $1,000 government deposit. Families can contribute more over time, and the money grows tax-deferred.
But once you look under the hood, the deal loses its shine. Let’s put on our financial hats.
**Is there a Catch?**
Yup. A few big ones. Like many Washington programs, the Trump Account has some drawbacks:
- **Withdrawals are taxed.** Even if the money is used for “approved” purposes like college, a first home, or starting a business, it’s still taxed at capital gains rates. No tax-free ride like a 529 plan.
- **Strict limits on access.** Your child can take out only half the money at age 18. The other half is locked up until they turn 31.
- **Penalties are harsh.** Use the money for anything not on the approved list, and you’re looking at a 10% penalty *plus* regular income tax.
- **Complex rules.** Just like many government-run programs, the fine print is long, confusing, and easy to trip over.
For middle- and upper-income families, the Trump Account hoops may not be worth jumping through. For lower-income families, the $1,000 seed money may sound appealing — but if they can’t afford to keep contributing, that small balance might be eaten up by fees or inflation before it ever amounts to much.
**Are There Better Options?**
Yes, Virginia, and they already exist. If you want real flexibility and tax advantages, here’s what’s already on the menu:
- **529 College Savings Plans:** Tax-free growth, tax-free withdrawals for education, and much more control over what the money can be used for – tuition, books, computers, even some room and board.
- **Custodial Roth IRA:** If your child has earned income, this is one of the best long-term vehicles out there. Contributions grow tax-free and money can be withdrawn for retirement, education, and even a first-time home purchase without penalties.
- **Cash Value Life Insurance (the smart kind):** For parents who want long-term, tax-advantaged flexibility and protection, some permanent life insurance strategies offer living benefits, self-completion, and no government strings attached.
**Bottom Line**
The Trump Account may have good intentions; but, typical of many government programs, it comes with complex rules, limited flexibility, and penalties that can wipe out any benefit for those who need it most.
The political headlines may look good – like no tax on tips, etc., it attracts votes – but a Trump Account doesn’t appear to solve any real problems beyond attracting voters. It’s too bad politicians don’t have to take a fiduciary oath.
Here’s a breakdown on the ‘big beautiful bill’ that was signed into law on July 4, 2025.
[OBBB-IFG\_Client-071025](https://indfin.com/wp-content/uploads/2025/07/OBBB-IFG_Client-071025.pdf)[Download](https://indfin.com/wp-content/uploads/2025/07/OBBB-IFG_Client-071025.pdf)
Hope this has been helpful.
Jim
Would you like a professional financial guide?
1. Tell me [your priorities](https://indfin.com/retirement-priority-planning-review/), then
2. [schedule an introductory call](https://go.oncehub.com/JimLorenzenCFP)!
You can [also subscribe to my](https://visitor.r20.constantcontact.com/d.jsp?llr=fdk6idhab&p=oi&m=fdk6idhab&sit=icdtuhhgb&f=68947827-6cd6-46e6-a8a2-db365fc30f5c)[ ](https://visitor.r20.constantcontact.com/d.jsp?llr=fdk6idhab&p=oi&m=fdk6idhab&sit=icdtuhhgb&f=68947827-6cd6-46e6-a8a2-db365fc30f5c)[newsletter.](https://visitor.r20.constantcontact.com/d.jsp?llr=fdk6idhab&p=oi&m=fdk6idhab&sit=icdtuhhgb&f=68947827-6cd6-46e6-a8a2-db365fc30f5c)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues, IFG Viewpoint & Outlook, Investing, Roth conversions, Taxes
**Tags:** Investment Strategy, tax law changes, tax planning, Tax reduction
---
### [7 Retirement Mistakes Pre-Retirees Need to Avoid.](https://indfin.com/7-retirement-mistakes-pre-retirees-need-to-avoid/)
**Published:** July 22, 2025
**Author:** Jim Lorenzen
**Excerpt:** If you’re within 5-10 years of retirement and have built a portfolio north of $1 million, congratulations—you’ve done the hard part. Now, it's about avoiding retirement mistakes.
**Content:**
But as you approach the retirement “decision phase,” the stakes change. Retirement mistakes can cost real money.
Suddenly, the questions become more about *withdrawal strategies*, *tax traps*, and *income coordination*. The wrong decision means retirement mistakes that could cost you tens—or hundreds—of thousands of dollars over time.
This is the phase where many financially successful people begin to look for expert, **fiduciary advice**—not because they can’t do it themselves, but because they don’t want to risk a misstep they can’t undo.
**Here are 7 Common Retirement Mistakes You Still Have Time to Avoid:**
**1. Claiming Social Security Too Early**
For high earners, delaying to age 70 can be a powerful way to hedge longevity risk. But timing matters—especially for couples. Once you file, there’s no do-over.
**2. Missing the Roth Conversion Window**
If you retire before RMDs begin, those “gap years” can be ideal for converting portions of your IRA to a Roth at low tax brackets. Most miss this.
**3. Ignoring Medicare Surcharges (IRMAA)**
Take too much income in retirement and your Medicare premiums can spike—often unexpectedly. A coordinated withdrawal strategy can help you stay below costly thresholds.
**4. Overlooking Tax Diversification**
It’s not just about how much you have—it’s about where you hold it. A tax-smart withdrawal strategy from IRAs, Roths, and taxable accounts can lower your lifetime tax bill significantly.
**5. Assuming the 4% Rule Applies to Everyone**
A cookie-cutter withdrawal rule doesn’t account for market volatility, required minimum distributions, or variable spending needs. You need a plan built around your lifestyle, not a rule of thumb.
**6. Holding Too Much Cash or Too Much Risk**
Some investors stay too conservative for too long. Others don’t realize how exposed they are to sequence-of-return risk. Retirement often requires a recalibrated investment plan.
**7. Thinking Estate Planning is Just for the Ultra-Wealthy**
Without the right structure, your heirs could face unnecessary taxes or delays. The SECURE Act changed how IRAs are inherited—your current plan may be outdated.
**Start with a checklist that covers the issues you need to consider BEFORE making decisions!**
Everyone needs a roadmap. You might want to consider getting my monthly letter. When you subscribe, I’ll send you a pre-retirement checklist that outlines the issues you need to consider before making decisions.
**[Get your pre-retirement issues to consider checklist here!](https://lp.constantcontactpages.com/sl/mpEDtqP/retirementchecklist)**
**Why Work with a Fiduciary Advisor?**
A **fiduciary financial advisor** is legally obligated to put your interests first—unlike many brokers or salespeople at large institutions – and – (shameless self-promotion, I know) an independent fiduciary who is also a *CERTIFIED FINANCIAL PLANNER*® professional is a good place to look.
If you’re approaching retirement and wondering how to:
- Minimize taxes on your IRA withdrawals
- Create consistent income that lasts
- Protect your legacy and stay in control
- Avoid permanent mistakes with Social Security or Medicare
…the odds are excellent I can help. If YOU would like some help, tell me [your priorities](https://indfin.com/retirement-priority-planning-review/), then [schedule an introductory call](https://go.oncehub.com/JimLorenzenCFP)!
(End of shameless self-promotion). Thanks.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Planning, Retirement, Retirement Income, Rollovers, Social Security
**Tags:** retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy
---
### [Do You Have a Mid-Year Financial Planning Strategy for Investors and Fiduciary Advisors.](https://indfin.com/mid-year_fiduciary_review/)
**Published:** July 1, 2025
**Author:** Jim Lorenzen
**Excerpt:** Whether you live locally in Moorpark, Simi Valley, or anywhere else, you may want to consider having a trusted fiduciary financial advisor help with your mid-year review, as you may see.
**Content:**
If you’re approaching retirement—or already enjoying it—this halfway point in the year is a good time to step back and reassess your financial strategy. With continued market volatility, the possibility of future tax changes, and inflation still affecting everything from healthcare to housing, now is the time for investors, working with a fiduciary advisor, to take action.
Below are what I consider nine essential mid-year strategies—across investments, risk management, retirement planning, and estate matters—to help ensure your financial plan stays on course in 2025 and beyond.
**1. Review Your Investments—And Know What’s Coming**
Are your investment accounts working toward your retirement goals—or against them? Do you have a formal family financial ‘business’ plan? Are your investments aligned with the plan and has your plan been ‘stress-tested’ for worst-case scenarios?
**Why It Matters**
If you’ve built up large balances in your traditional IRAs or 401(k)s, you could be setting yourself up for large Required Minimum Distributions (RMDs) later in life. These are taxable and can push you into a higher tax bracket, raise your Medicare premiums, and even cause more of your Social Security to be taxed.
A fiduciary advisor can help you:
- Rebalance your portfolio to match your current risk tolerance and goals.
- Evaluate whether it’s time to make Roth conversions, especially while markets are volatile and taxes appear to be ‘on sale’.
- Determine if your current allocation is too concentrated in any one sector or asset class. Owning two or three different growth funds isn’t diversification, it’s duplication.
**Tip for 2025:**
Take advantage of enhanced catch-up contribution limits if you’re age 50 or older. It’s one of the best ways to build your retirement nest egg while reducing your taxable income.
**2. Manage Risk Proactively—Not Emotionally**
Most investors worry about losing money—but few have a detailed strategy for how to avoid it. If your portfolio drops 20%, you’ll need a 25% gain just to get back to where you started.
**Key Questions to Ask:**
- Is your current asset allocation too aggressive—or too conservative—for your goals? Are your goals quantified with amounts and dates? Have they been integrated into your projected returns and tax brackets?
- Do you have a written plan for how to respond to future downturns?
- Have you stress-tested your portfolio for rising interest rates or continued inflation?
**3. Rethink the Retirement “Spending Phase”**
Most of your financial life has probably been about saving and accumulating. But the **distribution phase**—when you start living off your investments—is completely different. And much more complicated.
**Mid-Year Priorities:**
- Review your spending patterns and look for opportunities to reduce waste.
- Determine your success probability of achieving your goals based on all market and economic data inputs.
- Build buffers for rising costs, like healthcare, tuition for grandchildren, or supporting aging parents.
- Make sure you have at least 6–12 months of expenses in an emergency fund.
- Talk to your advisor about setting up a line of credit or HELOC as a backup.
- Recalculate your retirement income needs based on current market conditions, projected inflation and tax assumptions.
**4. Take Advantage of Roth Opportunities**
Roth IRAs and Roth 401(k)s offer tax-free growth and withdrawals, which can be extremely valuable in retirement—especially if future tax rates rise.
If markets are down, converting traditional IRA assets into Roth now means you’ll pay taxes on a lower value—and any future growth can happen tax-free.
If you’re employed and your company offers a Roth 401(k) option, it might be worth considering whether future tax-free income is worth more than today’s tax deduction.
**5. Reevaluate Your Insurance Coverage**
Insurance often gets overlooked in mid-year planning—but gaps in your coverage can expose your entire financial plan to unnecessary risk.
**Things to Review:**
- **Life insurance**: Do your policies reflect your current needs? How do the living benefits fit into your retirement plan?
- **Long-term care (LTC)**: Have you planned for it? Costs are rising quickly.
- **Disability coverage**: If you’re still working, how would you replace income if you couldn’t work?
- **Home and liability**: Rising real estate values are happening virtually everywhere, not just in Moorpark and Simi Valley. This could mean you may now be underinsured.
- **Earthquake and flood insurance**: If you live in Southern California, these aren’t optional—they’re essential, though admittedly, it may be difficult to get.
**6. Plan Now for Healthcare Inflation**
Healthcare is one of the biggest wildcards in retirement. It’s not just about premiums—it’s about out-of-pocket costs, prescriptions, and long-term care.
**Consider these actions:**
- You may want to plan for 6% to 8% annual increases in healthcare costs during early retirement.
- Review Medicare options before you turn 65—mistakes here can be permanent.
- Consider a Health Savings Account (HSA) if you’re still working and eligible. It’s triple tax-advantaged.
These costs can quickly derail even well-funded retirement plans. It would be wise to get ahead of them now.
**7. Refresh Your Estate Plan**
Life changes. So should your estate documents.
**Mid-Year Estate Planning Checklist:**
- Do your wills and trusts still reflect your wishes?
- Are your executors and trustees up-to-date—and prepared for their roles?
- Have you reviewed beneficiaries on retirement accounts, annuities, and insurance?
- Is asset titling correct (individual vs. joint ownership, trust title, etc.)?
- Are your powers of attorney and healthcare directives current?
In California and other high tax states, probate can be costly and time-consuming, especially if your estate is not properly titled or your documents are out of date. A small investment in time now can save your loved ones months—or years—of headaches later.
**8. Use Smart Gifting and Wealth Transfer Strategies**
Want to help your kids, grandkids, or favorite causes while minimizing taxes? 2025 presents a narrow window of opportunity to transfer wealth efficiently.
**What You Can Do Now:**
- The annual gift tax exclusion is $19,000 per person in 2025— it might be wise to use it.
- Consider gifting depressed assets now into trusts to remove future appreciation from your estate.
- Explore donor-advised funds (DAFs) or charitable trusts to combine tax benefits with giving.
- Start involving your children or heirs in your financial vision—this fosters trust and reduces future conflicts.
You don’t need to be ultra-wealthy to benefit from smart estate planning. Many families in Simi Valley and Moorpark are surprised how much wealth they’ve built—and how vulnerable it is to unnecessary taxes.
**9. Make Charitable Giving More Efficient**
If you’re planning to give, do it wisely. Mid-year is a great time to review charitable strategies with tax implications.
**How to Give Smarter:**
- Use Qualified Charitable Distributions (QCDs) if you’re over age 70½. You can gift up to $108,000 directly from your IRA, tax-free.
- A one-time QCD of $54,000 can be directed to a charitable gift annuity or trust in 2025.
- Donate appreciated stocks or funds instead of writing checks—avoid capital gains and take a deduction.
- Bunch donations into a single year to maximize itemized deductions.
These strategies are especially effective for retirees with large IRAs or taxable portfolios who want to make a difference without increasing their tax bill.
**Final Thoughts: Take Control at the Halfway Point**
Whether you’re retired or getting close, this is not the time to put your finances on autopilot. A mid-year checkup is essential—and having a financial advisor by your side – one who will accept fiduciary status in writing – ensures that all strategies are designed in your best interest.
You don’t have to live near Moorpark or Simi Valley to get help – though I do enjoy office visits. I can be of help wherever you are.
Mid-year planning can put you back in control—and help you finish the year with greater clarity and peace of mind. Use this checklist below!
**This year, take the opportunity to:**
- Reduce taxes
- Improve income security
- Minimize risk
- Protect your legacy
[IFG\_MidYear Checklist](https://indfin.com/wp-content/uploads/2025/06/IFG_MidYear-Checklist-1.pdf)[Download](https://indfin.com/wp-content/uploads/2025/06/IFG_MidYear-Checklist-1.pdf)
You can [learn more ](http://www.indfin.com/video-library-2/)[about my practice](http://www.indfin.com/video-library-2/) or subscribe to my newsletter, [on my website](http://www.indfin.com/).
Let me know if I can help!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Inflation Pressures, Retirement, and Woulda-Coulda-Shoulda](https://indfin.com/inflation-pressures-retirement-and-woulda-coulda-shoulda/)
**Published:** June 23, 2025
**Author:** Jim Lorenzen
**Excerpt:** While the Fed continues to target a 2.0% inflation rate, headwinds in the form of inflation pressures from worker shortages, tariffs, and foreign conflicts are coming at a time as America approaches a historic demographic milestone - a record number of individuals turning 65 this year.
**Content:**
The confidence many hold in their retirement plans is beginning to show signs of strain. A recent Fidelity study highlights how rising inflation and health care costs are further impacting the economic picture and reshaping retirement expectations. All these issues are triggering widespread financial unease among many pre-retirees and current retirees alike.
**Confidence Slipping Amid Cost Concerns**
Although two-thirds of Americans approaching retirement age are still expressing confidence in their ability to retire comfortably, that figure has declined by seven percentage points in just one year.
What’s happening? The downward shift reflects growing anxiety about impacting retirement planning timelines and savings strategies. Rising costs just compound the problem.
Current retirees aren’t immune. A striking 70% report that the rising cost of living has significantly eroded their retirement savings. This erosion is most apparent in essential categories such as housing, food, and especially health care — a sector that continues to outpace general inflation.
**Health Care: A Mounting Concern**
Health care expenses remain one of the most daunting line items for retirees. The average retiree can now expect to spend more than $165,000 on health care over the course of retirement, a 5% increase from just one year ago. That figure does not include the cost of long-term care, which can push total out-of-pocket expenses even higher.
This concern isn’t lost on pre-retirees. Many are revising their savings targets upward and exploring supplemental coverage options to hedge against future uncertainties. Health care inflation, in particular, is compelling many Americans to revisit, revise, and build more flexible financial plans that can be stress-tested and adjusted for medical volatility over a retirement horizon that now often stretches 25 to 30 years or more.
**Retirees Say: Start Early, Save Often**
For those already in retirement, hindsight offers a clear message to younger generations: begin saving as early as possible. Two-thirds of retirees surveyed said their top piece of advice would be to start retirement savings sooner, even if only in small amounts. Nearly 40% admitted they would have begun saving earlier if given a second chance, and about one in five said they would have more proactively planned for inflation and future costs.
This sentiment echoes a broader theme: retirement planning and saving isn’t a one-time event. It’s a lifelong process that requires ongoing adjustments based on economic conditions, health changes, and personal goals.
**Shifting Toward Self-Reliance**
Another key finding from the study is the growing sense among pre-retirees that they will need to shoulder more of the retirement burden than previous generations. More than 60% of those not yet retired doubt their savings will last throughout retirement, largely due to fears that Social Security may not be fully funded in the decades ahead. You may be interested in [my video about Social Security](https://vimeo.com/1094788429/8c3e5bd345?ts=0&share=copy) in 2025 that also addresses the outlook for the Social Security trust fund.
---
**Key Takeaways:**
1. **Reassess Inflation Assumptions:** Traditional retirement projections often underestimate the long-term impact of inflation. Investors and their advisors should stress-test their plans under higher inflation scenarios.
2. **Prioritize Health Care Planning:** With costs rising faster than expected, advance planning is critical.
3. **Emphasize Early Engagement:** Consistent, early contributions—even in small amounts—can compound meaningfully over time and provide greater flexibility in later years.
4. **Strengthen Retirement Income Streams:** With future Social Security uncertainty, retirees should build strategies that combine guaranteed income and investment-based withdrawals.
Retirement success today requires a dynamic, proactive approach that accounts for longevity, rising costs, and evolving risks. Those who prepare with these factors in mind will be far better positioned to preserve both their wealth and their peace of mind.
Learn more! Subscribe to my newsletter – you can do it on the right side-bar of this page.
If you’d like some help with your planning from a fiducairy, I invite you to [learn more about IFG](https://indfin.com/video-library-2/)!

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [From Growth to Efficiency and a Fiduciary Standard: Tax-Smart Investors Focus on More than Performance.](https://indfin.com/from-growth-to-efficiency-and-a-fiduciary-standard-tax-smart-investors-focus-on-more-than-performance/)
**Published:** June 19, 2025
**Author:** Jim Lorenzen
**Excerpt:** Back in the 1990s, taxes and fiduciary standards weren't talked about. The financial headlines were dominated by star fund managers and double-digit growth stories. Financial talk shows and glossy magazines alike obsessed over who was “beating the market.” The mantra was simple: accumulate assets. That was the measure of success.
**Content:**
I recall hearing a local independent broker—back when I had an office in Orlando—promising “15% returns with no risk of principal” on the radio. Dubious? Absolutely. But it was a time when many investors took the bait, hungry for growth, often with little understanding of the fine print. It was also a time before the rise of fiduciary standards and long-term, tax-aware planning.
**Information Abounds—But So Does Noise**
Today’s investors, whether close to my office in Simi Valley or Moorpark, or across the U.S, are far more informed. The internet has created an unprecedented level of access to financial content. But while knowledge is more available, clarity isn’t always. Anyone can understand what’s being said—but knowing what’s ***not*** being said is a different skill altogether. A professor I once had said, “Education isn’t all about what you know; it’s about knowing what questions to ask.”
**The Shift: From Growth to Income and Tax Efficiency**
What’s changed most is not just access to information—but investor priorities. For those approaching or already in retirement, the focus has shifted from growth at all costs to sustainable income, tax-efficient withdrawals, and coordinated asset planning.
The old approach of accumulating mutual funds and hoping for the best was okay for the ‘sock-it-away’ approach. Today’s well-designed financial plans prioritize income consistency and tax-smart withdrawals—especially critical in high-cost areas.
**Why Mutual Funds Can Be a Tax Trap**
We’re talking about taxable accounts now, not retirement accounts (though they, too, can have hidden traps – but that’s another subject). Let’s say you buy into a mutual fund that holds a stock like XYZ. You join when XYZ is trading at $40.
But the fund bought XYZ at $10 and recently sold it for $50. Here’s the catch: even though you never benefited from the early gains, you’re still on the hook for your share of the fund’s full $40 per-share gain. That’s a tax liability for growth you never experienced—that’s because YOU didn’t own the XYZ stock – the mutual fund was the owner. And, as a shareholder of the fund, you share in the fund’s tax liability for that sale.
**The Rise of ETFs and the Push for Efficiency**
Exchange-Traded Funds (ETFs) addressed some of these issues. They trade like individual stocks, have lower expense ratios, and are generally more tax-efficient due to lower turnover. However, while ETFs are a step up, they still aren’t inherently tax-managed.
**From Accounts to Households: A Better Way Forward**
More sophisticated investors and their advisors have moved toward structures like Unified Managed Accounts (UMAs) and Unified Managed Households (UMHs). These aren’t just investment accounts—they’re comprehensive strategies designed to:
- Optimize tax management across multiple accounts
- Harvest losses and gains strategically
- Coordinate withdrawals with Social Security, pensions, and other income
- Ensure the plan fits the household’s overall goals and risk tolerance
The evolution from planning vs. product approach, and account-based thinking to household-level coordination is a game-changer. Whether you’re near me in the Moorpark, Simi Valley area, or anywhere else – I’ve worked with clients from California to Florida – seeking smarter wealth planning and a fiduciary standard, this approach can add truly meaningful value over time—potentially funding a vacation, a vehicle, or simply offering peace of mind.
**Final Thoughts**
If your current plan is still rooted in accumulation-only thinking, it might be time to revisit your strategy with a fiduciary advisor who specializes in holistic, tax-aware planning. Smart investing isn’t just about what you earn—it’s about what you keep. And the best planning, of course, starts early.
Here’s a tax-smart checklist you can use! And, while you’re at it, subscribe to my newsletter! Use the tab on the right (I recently published a one-page overview of the House version of the tax bill now being debated in the Senate).
[Tax-Smart Financial Planning Checklist](https://indfin.com/wp-content/uploads/2025/06/Tax-Smart-Financial-Planning-Checklist-1.pdf)[Download](https://indfin.com/wp-content/uploads/2025/06/Tax-Smart-Financial-Planning-Checklist-1.pdf)
Would you like some help? Start here!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Why Claiming Social Security at Age 70 Could Be a Smart Move—But Here’s What Most People Miss](https://indfin.com/why-claiming-social-security-at-age-70-could-be-a-smart-move-but-heres-what-most-people-miss/)
**Published:** June 5, 2025
**Author:** Jim Lorenzen
**Excerpt:** What most people don’t realize: There are some important details about how and when these delayed credits are actually added to your benefit.
**Content:**
Social Security claiming can be confusing. Many people know that if you wait until age 70 to start collecting Social Security benefits, you can lock in a higher monthly check—thanks to something called **Delayed Retirement Credits (DRCs)**. For every year you wait beyond your Full Retirement Age (FRA) (which is usually around 66 or 67), your benefit increases by about 8%—all the way up to age 70.
This increase can be a big win, especially for higher earners and those with longer life expectancies. That’s why many smart retirees choose to delay claiming —even if they stop working before 70.
Using tools like IFG’s Savvy Social Security Planning Calculators, [we can show exactly how much you stand to gain](http://view.vzaar.com/11305923/player), including the effect on spousal and survivor benefits.
But here’s what most people don’t realize: There are some important details about *how and when* these delayed credits are actually added to your benefit.
**The Math Behind the 8% Increase**
When financial professionals say you get “8% more per year” by delaying Social Security, they’re simplifying the math. Here’s what’s really going on:
- DRCs are credited monthly—at 5/9 of 1% per month (which equals 8% per year).
- These credits apply to the months between your Full Retirement Age and when you start collecting.
Let’s say your Primary Insurance Amount (PIA) is $3,000 (this is your benefit at FRA), and your FRA is age 67. If you wait until 70 to claim, you’ll get $3,000 × 1.24 = $3,720 per month, not including cost-of-living adjustments (COLAs).
That 24% increase is from 3 full years of delayed credits (8% x 3 years). Important: Delayed credits are *not* compounded. You earn a simple increase of 8% per year.
**Timing Really Matters**
If you apply at age 70 (or up to 3 months before), all your delayed credits will be fully included in your first check. But if you file *before* 70—even just by a few months—things work differently.
Let’s look at an example:
Bob has a PIA of $3,000 and plans to wait until 70, but changes his mind and files at age 68, in July. His first Social Security check (in August) won’t include *all* his delayed credits yet.
Here’s why:
- Social Security only adds delayed credits once a year, in January.
- When Bob files, his benefit will include only the DRCs earned *up through the previous year*. So he gets $3,000 × 1.08 = $3,240 per month
That’s only one year of delayed credits. The six months he earned in the current year (January–June) will be added later—next January.
At that point, Bob’s benefit will increase again to $3,360 per month, plus he’ll get a lump sum of $240 for the retroactive increase.
COLA adjustments and income-based changes (if he’s still working) are calculated separately and automatically.
**The Bottom Line: Know the Rules Before You Claim**
If you’re looking to maximize your Social Security benefits, it’s critical to understand not just *how much* you’ll get—but *when* and *how* it’s calculated. The timing of your filing can affect more than just your monthly check—it can impact lifetime income, spousal benefits, and retirement income planning.
The Social Security Administration has automated most of these adjustments, but that doesn’t mean your strategy should be left to guesswork.
**Want Help Deciding When to Claim?**
**Social Security optimization** and tax-managed retirement income planning is my specialty. If you’re between the ages of 55 and 70 and want to make a smart, tax-efficient choice about your benefits, [let’s begin!](https://indfin.com/getting-started/)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Five Sneaky Tax Traps - and How You Can Dodge Them!](https://indfin.com/five-sneaky-tax-traps-and-how-you-can-dodge-them/)
**Published:** May 27, 2025
**Author:** Jim Lorenzen
**Excerpt:** Congratulations—you’ve built up a healthy retirement nest egg, maybe even a couple million bucks in a traditional IRA. Cue the applause! No worry about tax traps now! But as you reach retirement and start thinking about how to spend it (or pass it on), Uncle Sam is waiting with a few surprise moves that could mess with your plans. These are the tax traps.
**Content:**
**Let’s start with a brain teaser:**
• Bill is retired and has taxable income of $48,988 this currently puts him at the l[](https://indfin.com/wp-content/uploads/2025/05/Brackets-2024.png)ow end of the 22% tax bracket.
• Includes $40,000 in IRA income
• Plus $37,500 in Social Security benefits
• He taps his IRA for an extra $1,000 – he wants to go on a road trip to see Pee Wee Herman in concert.
You’d think that $1,000 from his IRA would increase his income by only $1,000 and he’d stay in the 22% tax bracket. Tax on the withdrawal would be $220, right?
Nope. The tax on that $1,000 withdrawal would come to $407! – a 40.7% tax rate! He didn’t see a tax trap.
How did this happen? Stay tuned…. you’ll see. (or, if you can’t wait, [subscribe to my newsletter and see the video here!](https://lp.constantcontactpages.com/sl/ATzXy6x) If you subscribe, don’t worry, you can unsubscribe instantly at any time).
**Let’s first begin by breaking down five sneaky tax traps that could trip you up**—and what you might be able to do about them before it’s too late.
**1. Required Minimum Distributions (RMDs):** The IRS Wants Its Cut, Like Clockwork
Once you hit age 73 (or 75, depending on your birth year), the IRS forces you to start taking money out of your retirement account whether you need it or not. These Required Minimum Distributions (RMDs) are calculated based on your account size and your age, and they only grow over time.
At 73, you might have to take out around 4% of your account. By 85, it’s over 6%. Add that to your Social Security income, and suddenly you’re in a higher tax bracket than expected—possibly paying more in taxes than you did while working full-time!
**What to do**: Start planning your withdrawals before you turn 70. A good tax strategy now can save you big later.
**2. Tax Cuts and Jobs Act (TCJA) Is on the Chopping Block**
The 2017 TCJA brought historically low tax rates—and those rates are scheduled to expire at the end of 2025. If Congress doesn’t step in, tax brackets will go up, and estate tax exemptions will shrink dramatically.
Let’s say you and your spouse earn $300,000. Right now, you’re taxed at 24%. After 2025? That jumps to 33%. Ouch.
**What to do:** Stay on top of legislation, and position your income and estate wisely. Tax-smart moves now (like Roth conversions or charitable giving strategies) could be lifesavers later.
**3. The Widow Penalty: Losing a Spouse Can Raise Your Taxes**
Here’s a curveball most people don’t see coming: once a spouse passes away, the survivor typically files taxes as “single” instead of “married filing jointly.” That switch can push the surviving spouse into a higher tax bracket—despite having nearly the same income.
And it’s not just income taxes. Medicare IRMAA surcharges (extra premiums for higher-income earners) can also spike, just because one spouse is gone.
**What to do**: Consider strategies like Roth conversions while both spouses are still alive and in a lower joint bracket. And make sure your estate plan anticipates this unfortunate tax twist.
**4. Leaving a Big IRA to the Kids Isn’t as Sweet as It Sounds**
Thanks to the SECURE Act (passed in 2019), your kids can no longer stretch out IRA withdrawals over their lifetimes. Now they have just 10 years to empty the account—and starting in 2025, most will have to take annual RMDs during that 10-year window too.
If your kids are in their peak earning years, this inheritance could push them into much higher tax brackets. So instead of your legacy being a gift, it might feel like a tax trap.
**What to do**: Spend down your traditional IRA gradually, or consider converting to a Roth IRA while your rates are low. Trusts, charitable planning, and other legacy strategies can also help.
**5. Estate Planning: The Rules Are Changing, Fast**
Estate tax law is like fashion—trends change quickly and not always for the better. The current estate tax exemption ($13.99 million per person) is generous, but it’s set to get cut in half after 2025 unless Congress acts.
Meanwhile, popular estate planning tactics are under attack. And if your total assets are around $6 million or more, the risk of your estate facing a hefty tax bill is real.
**What to do:** Get proactive. Talk to an estate planning expert now. Build flexibility into your plan. And don’t wait until Congress makes a move—by then, your options could be gone.
**Taxes in Retirement Aren’t Just a Nuisance—They’re a Strategy Game**
You’ve spent your life earning, saving, and building wealth. Don’t let retirement taxes turn your victory lap into a detour. With smart planning and timely advice, you can keep more of your hard-earned money—and leave a better legacy for the people you love.
**Pro tip:** Always check with a qualified tax pro before making big moves. The IRS doesn’t play favorites.
These aren’t the only tax traps! The distribution phase of retirement is very different from the accumulation phase. Accumulation was just saving as much as you could and everyone recommended tax-deferred (tax delayed) vehicles. Decumulation isn’t so simple. Tax planning changes through the four phases of retirement! And, you need to know how that happens!
**Okay, back to our brain-teaser!**
How did Bill’s $1,000 IRA withdrawal cause him to pay $407 in taxes? The spending phase (decumulation) is different from the accumulation phase. Those days were simpler: You worked, saved, and grew your money. Not so simple now, as Bill soon learns.
And, you may be surprised to learn how tax planning changes throughout retirement – and just how many tax traps there are!
**Grab some coffee!** You’ll not only learn the answer to our brain teaser – you’ll also learn about more tax traps in How Tax Planning Changes during the Four Stages of Retirement! [Get started here](https://lp.constantcontactpages.com/sl/ATzXy6x)!
Enjoy!
Jim
Here are some additional retirement resources you may like:
My retirement planning page:
A paper on Understanding Diversification: [https://indfin.com/wp-content/uploads/2014/09/i306\_Understanding-The-Diversification-Puzzle.pdf](https://indfin.com/wp-content/uploads/2014/09/i306_Understanding-The-Diversification-Puzzle.pdf)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
**Tags:** Retirement Income, Retirement Planning, tax management, tax planning
---
### [How To Disinherit Your Unnamed Beneficiary - the I.R.S.](https://indfin.com/disinherttheirs/)
**Published:** October 10, 2019
**Author:** Jim Lorenzen
**Excerpt:** RMDs can present a tax trap for the unwary. Here's a 4-point checklist to help you avoid the pitfalls.
**Content:**
[](https://indfin.com/wp-content/uploads/2017/10/Older-man-with-cash_gettyimages.jpg) *Getty Images***Jim Lorenzen, CFP®, AIF®**
In my last post, I revealed that virtually everyone with a 402(k), IRA, or even an annuity has an unnamed beneficiary who may get the lion’s share of the money you’ve worked so hard to get. If you haven’t read it, you can [find it here.](https://indfin.com/hiddenbeneficiary/)
That post showed you how you could offset that inheritance and give more money to your kids. This post will show you how you can disinherit this unnamed beneficiary altogether – at least from the above-mentioned accounts.
I used a hypothetical example of someone who had three kids living in a high tax state like California and a $600,000 IRA. If the kids are two-income households and successful, they could be paying 40% to the state and federal governments for the money they end-up taking from the inherited IRA.
$600,000 divided by 3 kids = $200,000 per kid. At 40%, each kid would be paying $80,000 in taxes, realizing $120,000 after tax. The state and federal governments would therefore receive $80,000 x 3 kids = $240,000 – this would be DOUBLE what each kid would end-up with!
What if you could disinherit the government altogether?
You guessed it: There’s only ONE tool I’ve found that can do this, if combined with the right strategy.
In my last post, I talked about using a life insurance policy and the children using the tax-free death benefit to pay the taxes, keeping their IRA inheritance in-tact. This time we do it differently.
Starting with the same $600,000 IRA, we purchase a $600,000 survivorship life insurance policy (it pays after the last of two spouses dies). This time, however, instead of using the death benefit to pay the taxes, the death benefit goes to the children tax-free.
The strategy:
1. Name a tax-exempt charity as beneficiary of your IRA.
2. Purchase a life insurance policy for full estimated IRA value (we’ll use $600,000).
3. At death, the charity receives the IRA proceeds tax-free.
4. Your kids receive the $600,000 ($200,000 each) tax-free.
5. The state and federal governments get zero.
Your kids received $80,000 more than the $120,000 they would have received, a 70% increase using our hypothetical tax bracket – that’s $240,000 went to them instead of the government, who got nothing.
How much did the life insurance cost? That depends on the policy and the company, but I think it’s less than $240,000, ya think?
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Life Insurance, Planning, Retirement, Taxes
**Tags:** Financial planning, retirement mistakes, Retirement Planning
---
### [Retirement Planning and The Hidden Risk No One Talks About](https://indfin.com/retirement-planning-and-the-hidden-risk-no-one-talks-about/)
**Published:** April 2, 2013
**Author:** Jim Lorenzen
**Excerpt:** Retirement plannning doesn't seem as easy as it used to be. During the 1990s, everyone assumed that markets only went up and double-digit returns were accepted by many as normal.
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017c37fc6922970b-320wi.jpg)Now, reality has set in. With lower returns and a poor(er) economy, many facing[retirement](https://en.wikipedia.org/wiki/Retirement "Retirement")are now worried. They’re worried about running out of money in retirement. It’s called longevity risk.
**But, there are other risks also affecting seniors and those planning retirement many don’t even suspect – these are risks no one is talking about.**
When I was a kid, everyone wanted to live a LONG life; today, many are afraid of living too long! This phenomenon may be occurring because (1) many in my parent’s generation had defined benefit pensions – an income they couldn’t outlive, something most of us don’t have these days – and (2) we’re living longer – the definition of ‘old’ is different today.
When you couple this new ‘longevity risk’ with the fact we’ve cured many of the diseases that, back in the old days, used to kill us, many of us are now living long enough that not only has health care become a real issue, so has personal care!
Sure, it’s old news: People are worried about running out of their money. But wait, as they say on those tv commercials, there’s more:
Have you ever noticed that wheneverthere’s a problem facing the marketplace, financial product providers magically appear, anxious to create solutions they can package and market to the public. Often, however, the public has to be careful, because sometimes the packaging and presentation, which may meet all required disclosure rules, often makes NO attempt to educate the buyer on the hidden external issues that can heavily impact their decision-making.
Here’s a simple example:While the product distributors often use “average[annual return](https://en.wikipedia.org/wiki/Annual_percentage_yield "Annual percentage yield")” in their demonstrations and illustrations to sell their solutions, many, if not most, individual investors fail to recognize that returns never seem to come in ‘on average’. Not only are they different every year, they*compound,*as well*.* Not only do gains compound, so do the losses; and, that’s important, especially for seniors who are living off their life savings. But, while the “average annual return” calculation can mask some problems, there’s yet another one.
It’s a hidden risk that comes into play for those taking income withdrawals from their retirement savings, as gains and losses are being compounded – a hidden risk that few investors know about – simply because they are the risks no one ever talks about.
**This hidden risk primarily impacts those who are close-to and planning their retirement**. If you fit that description, and are depending on your investment portfolio to provide a significant portion of your retirement income, I think you’ll find what you learn in our report,***[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk%20 "Hidden Risk Report")***, to be very enlightening.
Enjoy!
Jim
———————
Report:***The Hidden Risk No One Talks About***. You can[register and download here](https://tinyurl.com/TheHiddenRisk "Hidden Risk Report").
Subscribe to our E-Zine:[IFG Insights](https://tinyurl.com/IFGInsights "IFG Insights")!
Follow Jim on Twitter: @jimlorenzen
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Facebook](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
———————
***Jim Lorenzen is a[CERTIFIED FINANCIAL PLANNER](https://en.wikipedia.org/wiki/Certified_Financial_Planner "What is a CFP?")®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,****a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [IRA Beneficiary Rules for Children are Different. ](https://indfin.com/ira-beneficiary-rules-for-children-are-different/)
**Published:** May 6, 2025
**Author:** Jim Lorenzen
**Excerpt:** You’ve just inherited an IRA from someone not your spouse… usually a parent. Guess what! Your rules are different.
**Content:**
Yes, when it comes to inherited IRAs, non-spouse beneficiaries – usually children – face a very different set of rules than spouses. Yes, IRA beneficiary rules for children ARE different.
Navigating these rules incorrectly—especially when moving inherited retirement assets—can result in the permanent loss of tax-deferred status and an unexpected tax bill. Ouch.
**Why It Matters: The High Cost of Mistakes**
Non-spouse beneficiaries who move inherited IRAs using improper methods risk turning what should be a tax-deferred transfer into a fully taxable event. This is more than a paperwork error—it’s a potentially irreversible mistake that accelerates taxable income and undermines long-term financial planning.
**Note:** While this article uses the term “IRA” throughout, the rules also apply to inherited employer-sponsored retirement plans, such as 401(k)s and 403(b)s.
---
**Who Qualifies as a Non-Spouse Beneficiary?**
Under the IRS Final RMD (Required Minimum Distribution) Regulations, a **non-spouse beneficiary** is any “designated beneficiary who is not a spouse.” There are three key classifications:
**1. Designated Beneficiary**
This includes individuals named as beneficiaries and certain **see-through trusts** (trusts that meet specific IRS requirements). Legal counsel is essential to determine whether a trust qualifies.
**2. Eligible Designated Beneficiary**
These are designated beneficiaries who meet one of the following criteria at the time of the IRA owner’s death:
- Surviving minor child of the IRA owner
- Disabled or chronically ill individual
- Individual not more than 10 years younger than the IRA owner
*Spouses are treated under a separate set of rules and are not covered in this discussion.*
**3. Non-Designated Beneficiary**
Entities such as estates, charities, and non-qualifying trusts fall into this category. Their distribution rules are less favorable and more rigid.
Note: A beneficiary can be designated and still be ineligible for the stretch – and that’s where most non-spouse beneficiaries (children) are. You might find [this video](https://vimeo.com/948781448/7f4e6bf795?share=copy "SECURE Act 2.0 - Death of the Stretch") helpful.
🔑 **Key Date to Remember:** Beneficiary classification is finalized on **September 30 of the year following the IRA owner’s death**—especially important when multiple beneficiaries are involved.
---
**Portability Options: Transfers vs. Rollovers**
Non-spouse beneficiaries must understand the correct way to move inherited assets. There are **three key portability methods**:
**✅ Trustee-to-Trustee Transfers (Nonreportable)**
- Tax-free and nonreportable
- Must be between same-type accounts (e.g., inherited traditional IRA to inherited traditional IRA)
- Beneficiary name and relationship must remain consistent
**❌ 60-Day Rollovers (Not Allowed for Inherited IRAs)**
- Non-spouse beneficiaries are **not permitted** to use 60-day rollovers
- Doing so will result in a fully taxable distribution
**✅ Direct Rollovers (From Employer Plans Only)**
- Permitted **only from inherited employer-sponsored retirement plans**
- Must be directed to a properly titled **inherited IRA**
- Reportable, but tax-deferred if staying within same account type (traditional to traditional, Roth to Roth)
---
**Transfer & Rollover Rules by Beneficiary Type**
[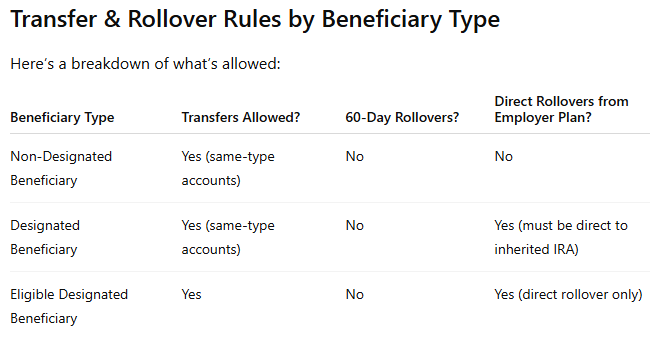](https://indfin.com/wp-content/uploads/2025/05/Transfer-Rollovers-by-Type.png)⚠️ **Important:** The receiving and delivering accounts must always be beneficiary accounts titled in the name of the deceased and the beneficiary (e.g., *Jane Smith IRA FBO Carol Smith, Beneficiary*).
---
**Direct Rollover Scenarios: What’s Taxable and What’s Not**
[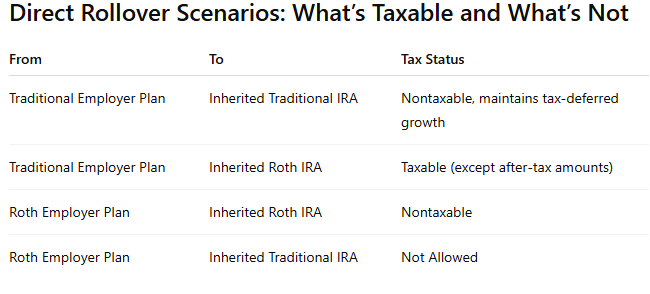](https://indfin.com/wp-content/uploads/2025/05/Direct-Rollover-Scenarios.png)📌 **Reminder:** All **RMDs must be taken before** executing a direct rollover to avoid compliance penalties. For more details, see our post: *Avoid RMD Shortfalls on Inherited IRAs: 5 Top Life Expectancy Rules*.
---
**Avoiding Common Pitfalls**
One of the most frequent (and costly) errors is attempting a rollover that is not permitted—such as trying to use a 60-day rollover from an inherited IRA. This misstep not only triggers full taxation but can eliminate the ability to spread distributions over a 10-year period under the SECURE Act’s rules.
For example, a designated beneficiary under the 10-year rule who mistakenly performs a rollover may be required to recognize the **entire distributed amount as income** in the year of the distribution.
---
**Final Thought: Consult an Expert**
Inherited IRA rules for non-spouse beneficiaries are complex and unforgiving. Working with a qualified financial advisor or tax professional is essential to:
- Identify the correct type of beneficiary classification
- Choose the appropriate method of transfer or rollover
- Maintain tax-deferred growth and minimize tax liability
When in doubt, ask before you act—because when it comes to inherited retirement accounts, the cost of getting it wrong is high. [Knowing about the SECURE Act 2.0](https://indfin.com/how-the-secure-act-changes-retirement-planning/ "SECURE Act 2.0") would be helpful, too.
---
It’s a maze of rules, I know. Would you like an easy-to-follow roadmap you can use? We have a flowchart summarizing the options for a non-spouse IRA beneficiary. [ Just tell me where to send it](https://lp.constantcontactpages.com/sl/8iYWYlN "Non-Spouse IRA Beneficiary Roadmap")!
Enjoy!
Jim
Would you like to get started with your planning? **[Here’s where to start!](https://indfin.com/getting-started/ "Getting Started with Jim at IFG")**

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [How To Do a 401(k) Rollover.](https://indfin.com/how-to-do-a-401k-rollover/)
**Published:** April 17, 2025
**Author:** Jim Lorenzen
**Excerpt:** If you’ve changed jobs or are getting ready to retire, don’t leave your old retirement account behind. Rolling over your employer-sponsored plan—like a 401(k) or 403(b)—into an IRA or new employer’s plan keeps your money growing tax-deferred and gives you more control over your investments.
**Content:**
**Nuts and Bolts: How to do a Rollover of Your Employer Retirement Plan the Right Way**
Let’s walk through a few considerations:
[](https://indfin.com/wp-content/uploads/2025/04/Home_Office_Man_Smiling_At_Desk-1.jpg)- The difference between direct and indirect rollovers
- How to roll over to a new employer’s plan or an IRA
- Tax pitfalls to avoid
- When to consider a special rollover IRA
Let’s get started.
**✅ What Is a Rollover?**
A retirement plan rollover moves your retirement savings from one account to another—without triggering taxes or penalties (if done right).
There are **two main types**: direct and indirect.
- **Direct Rollover** – The safest option. Your funds go straight from your old account to a new one. Bang, done.
- **Indirect Rollover** – You receive the money first, then must deposit it elsewhere within 60 days. This one has some pitfalls.
**Believe it or not, you have 6 options**! Worthwhile suggestion: You can learn more about your options in [this series of ](https://indfin.com/video-library/)[videos](https://indfin.com/video-library/). Pick the one(s) that applies to you!
**🔄 Direct Rollovers: The Smartest Move**
🏢 Rollover to a New Employer’s Plan
[](https://indfin.com/wp-content/uploads/2025/04/Checking_off_boxes.png)Thinking about consolidating your old 401(k) with your new employer’s plan?
Here’s what to do:
1. Choose “direct rollover” on your old plan’s distribution form.
2. Contact your new plan’s administrator to ensure they accept rollovers.
3. Your old plan will:
- Wire the funds, or
- Send a check payable to your new plan for deposit.
Pro Tip: Consolidating makes it easier to track your savings and manage your investments.
🏦 Rollover to an IRA
Prefer more control or better investment choices? An IRA rollover might be for you.
Steps:
1. Open an IRA or use an existing one.
2. Provide your account info to your old plan.
3. Your plan administrator will:
- Transfer the funds directly, or
- Issue a check payable to your IRA.
See the [5 things you can do with an IRA you can’t do with a 401(k)](https://indfin.com/wp-content/uploads/2022/05/5-Things-You-Can-Do-with-an-IRA-You-Cant-With-401k.pdf).
**⚠️ Indirect (60-Day) Rollovers: Use With Caution**
An indirect rollover means the funds are sent to you first—you then have 60 days to complete the rollover to avoid taxes and penalties.
[](https://indfin.com/wp-content/uploads/2025/04/Calendar_with_pins_001.png)Here’s the catch:
- Your employer must withhold 20% for taxes. If you want to roll over the full amount, you’ll need to replace that 20% out of pocket.
- If you miss the 60-day window, the IRS considers it a distribution—which means income taxes and possibly a 10% early withdrawal penalty.
Unless you need temporary access to the cash, a direct rollover is the safer option.
Rollovers can contain some irreversible pitfalls. You want to avoid the [Fatal Rollover](https://indfin.com/wp-content/uploads/2019/06/i308b_The-Fatal-Rollover-Oversight.pdf)[ ](https://indfin.com/wp-content/uploads/2019/06/i308b_The-Fatal-Rollover-Oversight.pdf)[Oversight](https://indfin.com/wp-content/uploads/2019/06/i308b_The-Fatal-Rollover-Oversight.pdf).
**🚫 Not Everything Can Be Rolled Over**
Some distributions aren’t eligible:
- Hardship withdrawals
- Required Minimum Distributions (RMDs)
- Substantially equal periodic payments
- Corrective distributions
If you inherited an account and you’re not the spouse, you have only one option: roll the funds into an inherited IRA via direct transfer.
🔐 Do You Need a Special “Rollover IRA”?
Not required, but sometimes helpful. A Rollover IRA (aka conduit IRA) is typically used when:
- You may want to move funds back into an employer plan later.
- You want stronger bankruptcy protection, since rolled-over employer funds often receive better federal protection.
You can always move funds from a Rollover IRA to a Traditional IRA later.
🆘 Missed the 60-Day Deadline? You May Qualify for a Waiver
If illness, natural disaster, or another issue prevented you from completing a rollover in time, the IRS offers three ways to get a waiver:
1. Automatic waiver
2. Self-certification
3. Private letter ruling
A tax professional can guide you through the right path.
📊 Special Note: Employer Stock & Net Unrealized Appreciation (NUA)
[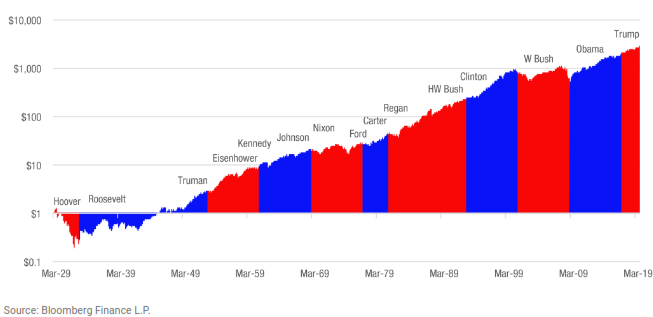](https://indfin.com/wp-content/uploads/2025/04/Growth-of-1-invested-in-the-SP_1929-2019.png)If you receive highly appreciated company stock in your distribution, consult a tax advisor before rolling it into an IRA. You might qualify for Net Unrealized Appreciation (NUA) tax treatment—potentially saving thousands in taxes. Need help? That’s what advisors are for!
💬 Final Thoughts: Don’t Go It Alone
Rolling over your retirement account is a smart move—but the process can be tricky. In most cases, a direct rollover to an IRA offers the best mix of flexibility, control, and tax protection.
🎯 Your Next Steps:
- Review your plan’s distribution options
- Decide whether to use an IRA or your new employer’s plan
- Talk to a financial advisor or rollover specialist
📣 Need Help?
[Get your planning started today!](https://indfin.com/getting-started/)
Don’t forget to bookmark this guide and share it with anyone who’s changing jobs or retiring soon.
Jim
Concerned about inflation and Social Security? The Center for Retirement Research at Boston College published a report on ***The Impact of inflation on Social Security Benefits****.* You can [access it here](https://indfin.com/wp-content/uploads/2021/10/Impact-of-Inflation-on-Benefits_BostonCollege.pdf).
If you’re worried about the future for Social Security? See this 13-minute video at

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [How to Plan for a Tax Free Retirement](https://indfin.com/how-to-plan-for-a-tax-free-retirement/)
**Published:** April 4, 2025
**Author:** Jim Lorenzen
**Excerpt:** The Big Picture:
For years, baby boomers drove the housing market, and much of the economy, as they moved into their first homes, began raising families, and moved-up to larger homes finally ending-up in the “McMansions” we’re all familiar with today. The boomers are now older—they’re no longer moving up. In fact, they’re just beginning to “decumulate” and downsize.
**Content:**
Meanwhile, the Federal government is running a record debt—and, it’s worse than the numbers you hear on the news. I’ll get to that and your tax free retirement chances soon; but, for now, it’s worth recognizing one simple fact: The government needs money—and that means increased income tax rates are probably on the horizon.
The problem for boomers is right under their noses: They’ve been deferring taxes for decades on the “seed money” they’ve been using to fund their 401(k) plans. Now, just when the government needs money the most, these same boomers are poised to withdraw a large harvest—and pay taxes on the tax rates in effect from this time forward.
**There are three reasons taxes will likely rise:**
1\. **The Federal Debt**
Despite recent reductions in the annual deficit (upper right), the deficits continue to accumulate and are projected to climb. As you can see the debt has continued to increase
[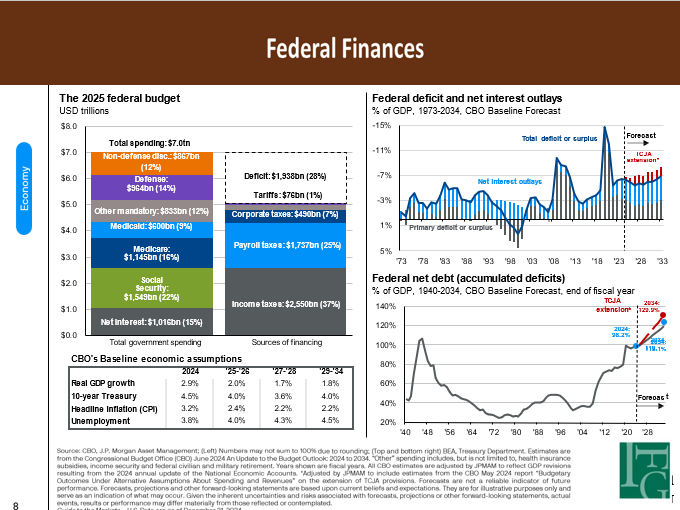](https://indfin.com/wp-content/uploads/2025/04/Federal-Finances.png)What’s more, the government doesn’t use recognized accounting standards. As I mentioned, it’s worse than you might think: only current year obligations are used.
Example, if you purchased a $50,000 car, you would expect to enter a $50,000 liability on your balance sheet. The government does it differently, entering only the total of the current year’s payments.
Don’t you wish you could build your balance sheet the same way?
Suppose you had only to list your current year’s mortgage payments on the liability side of your balance sheet, instead of the total outstanding mortgage obligation. That should tell you something about the federal debt figure you see on the news.
As I write this, the federal debt more than doubled, from $9 trillion to more than $18 trillion in just seven years. In other words, we’ve added more debt in seven years than the United States accumulated over its entire history before March of 2008. And the real debt, using accepted bookkeeping standards, was estimated to be more like $87 trillion – and that was back in 2012!
*\[Source: [http://townhall.com/tipsheet/guybenson/2012/11/28/americas\_true\_national\_debt\_87\_trillion](http://townhall.com/tipsheet/guybenson/2012/11/28/americas_true_national_debt_87_trillion)\]*
2\. **Reduced Federal Income Tax Revenues**
While unemployment has been heading down, the raw numbers don’t tell the whole story. Those finding work seem to be taking lower-paying or part-time jobs. They’re working, but for less and/or with fewer hours.
Wage growth remained below its 40-year average for almost 30 years and has been trending downward since the melt-down with only a recent turn to the upside. However, that recent upturn appears weaker
than prior upturns going back to the late 1980s.
Wages remaining below their 40-year average resulted in less income tax revenue for federal coffers.
3\. **Current Income Tax Rates are Historically Low**
Marginal tax rates haven’t been this low since the early 1930s. During much of the 1940s, 50s, and 60s, the top marginal income tax rates were over 90%.
As income tax rates have declined since the 1960s, Congress has taken away deductions. Now that rates are historically low and the debt has virtually doubled just since 2009, many have little doubt taxes are headed back up, especially since the Feds are taking in less tax revenue. Few expect a reinstatement of the deductions that used to be available.
**The picture is clear.**
Since the government needs money to repay its debt – and the huge chunk of untaxed money sits on the verge of being taxed – there seems to be little doubt, given our current historically low rates, that these rates will remain in-place indefinitely – political winds do shift from administration to administration.
**Now, consider this**:
If an investor does a great job, focusing on *accumulating* retirement assets, and the portfolio’s stocks, bonds, mutual funds, REITs, SPDRs, ETFs and other taxable retirement assets are doing well, this person has *even more tax exposure*. Larger tax-deferred accounts mean larger required minimum distributions. Those larger taxable distributions affect how Social Security is taxed… and also impacts Medicare premiums.
Strong performance is good, of course; but couldn’t this client arrange things so that his investments can still perform well and his partner, Uncle Sam, does less ‘relieving’?
**What happens to the tax-deferred bucket when our professional retires?**
Simple: All those tax-deferred assets become taxable. As you can see distributions go into the taxable bucket. They never make it into the tax-advantaged bucket where distributions are income-tax free!
**What’s really happening? You’re likely in a bad business partnership:**
> > Uncle Sam is YOUR partner in your retirement plan—and he gets a cut of whatever you take out.
> Your partner can change his share at any time; he has the ONLY vote on his share.
> Your partner is deep in debt due to overspending and needs money.
> Your partner is still spending and will likely need more money over the next thirty years
This isn’t a partnership anyone would choose for their own private business; but here we are.
**Traditional Retirement Solutions**
This is the way most Americans have approached retirement. Everything after the tax-deferred bucket is funded with after-tax dollars. You pay the I.R.S. and can use what’s left to invest in stocks, bonds, mutual funds, etc., in the next bucket.
The tax-deferred bucket has restrictions, of course, so that the I.R.S. can get some of your money before reaching the taxable bucket. There are no restrictions on this bucket, but it does leak taxes, as you can see.
The third bucket is the tax-advantaged bucket, which would include, for example, municipal bonds and Roth IRAs. While there is no limit on how much can be invested in municipal bonds, there are contribution limits for Roth IRAs. But, this bucket has one huge advantage: All income distributions are tax-free!
The key to strategizing a tax-free retirement is to use all three buckets in an intelligent way. A tax-free retirement is possible.
[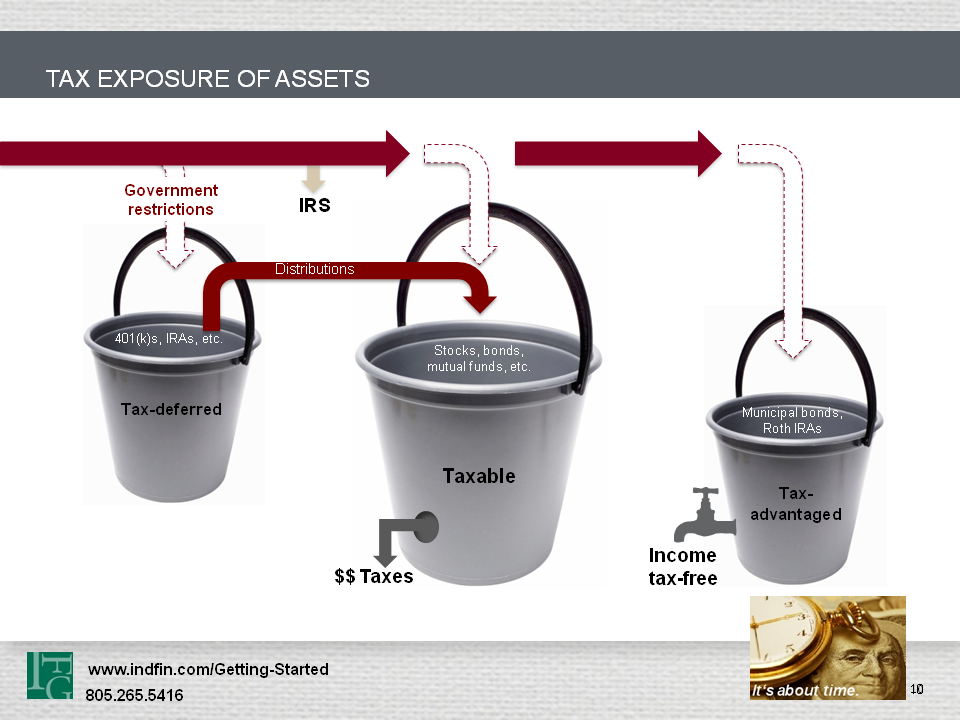](https://indfin.com/wp-content/uploads/2025/04/Tax-Exposure-of-Assets.png)**Can EVERYONE achieve a tax-free retirement?**
**Unfortunately no.** For example, if you receive pension income that would put you over the provisional income threshold after your standard deduction and personal exemption, you’re stuck. You won’t be able to have a tax-free retirement; but you can certainly improve your tax picture by reducing your exposure to both taxes and potential tax-law changes.
There are four stages of retirement – and tax planning does change during these stages. If you’re a ‘learner’, grab some coffee and enjoy this [45-minute video](https://vimeo.com/818413909/03eda87040?turnstile=0.k99IIYK8bxdzmZg0rxIefVMoXUVUwKWKlNlex5OCv4Hg5hkIBV73ZiFxMZ5JjwE-jwo7uRnGQEiQOLqSAMoeKPXUgrdlD01DkLfXLWWGTrscwTzimvxYul5YUuzogCPhgqv_FHHf2Ll3pkWxWfrZAeprouUXIHzUYKkH8yFC4A9W5Vl18p1Cd1e5Gty-jWJjQe_c1avv2IEN-yIy_F3TTgstsZVpWAehghItZZwqSlkbqbFEuwhysJQRX9KhXt-c-iVeRqEVBmBpva1TBausWTVYSXg3ppF0S8xM4EaN6DaAbtSj8zAREftcjGl3Z3o9oDzUPG8EHx25jrHyspeGQzm1m9xhTyA6QslU7FDgchZhy4Ic2S9kWRLeE7aNSEIbE7yW6ldc8hCWPVPxNMZkglP1oXowbsmMBuirQYXMIGxSySERz16G8RGHAjPGCAJv4VKCeqD39HLiOZP3s5A_SdjqAJknC3GGh1B575BGIsV0mwICYqleB7qZaK0mjYWc4H48xh4UgWfCH5_DTgWOXl6OFTAKsehE1VgYknRKlQ2w-zzz6vuXtPItNMe6RM3eX2SZZxwUH8x7wmBLSw3jzvJL61Kv7rIkR-cuj0jQhhZ-vHyhwQ_1nA16fMnB7pzeXSXRfC_hW10TpK86491jGjdcJ5z67avPOAeLpfWwZWsAbbH_o3UnqNjVZi6I-nwOE77fBAH4BmWqKE3R6diaalyPUbUTqerzqogg1os5RgH4Kp_afRRdgHbeljh48Sjx5UzW6j5WVxJjaXYGuBzYiuWoe1AAfHZ9s37m1WnDR4xtubnPK5Jy7mQPh6h7UWA4ip5nMLWij1NUhgW0bQLdBw.pPXd0f5XyYf8zGIknue6jQ.e64c98697c1da9abe55876a3cb06ae52fad1d7104022e7a6b8072a11a38c891c "How Tax Planning Changes During the Four Stages of Retirement") on ***How Tax Planning Changes During the Four Stages of Retirement.***
**Can YOU achieve a tax-free retirement?**
The odds might be very good you can; but, that would require some analysis. There’s [more information](https://indfin.com/tax-planning-the-smart-way/ "More information on retirement and taxes.") on my website
You also might be interested in our report, ***[4 Steps to a Tax-Free Retirement.](https://lp.constantcontactpages.com/sl/1nfZSzD/4StepsTaxFreeRetirement)***
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Retirement Income, Taxes
---
### [Are You " On-Track " to a Successful Retirement?](https://indfin.com/are-you-on-track-to-a-successful-retirement/)
**Published:** September 9, 2015
**Author:** Jim Lorenzen
**Content:**
**Jim Lorenzen, CFP®, AIF®**
Retirement successmaynot be as easy to achieve as many think.I attended a conference and heard one speaker relay a story about one company’s 401(k) enrollment meeting where 100% – yes, everyone – said they wanted to enroll in the company’s 401(k) plan. They all were going through the materials and even choosing allocations they felt were appropriate – and all them were excited about starting to save for their retirement!
Would you like to guess how many actually followed through and actually participated? 3%.
That’s right; only three in one hundred actually did it.
Education didn’t seem to help, at least in that particular case, despite all the glowing post-meeting comments. Benjamin Graham, the ‘dean’ of value investing who taught Warren Buffett at Columbia University, once said that behavior, more than investment choices, represent the largest impediment to financial success for most Americans; and the data seems to bear that out. Poor savings habits, poor investor performance due to behavior, and paralysis often due to too many choices create roadblocks many have trouble overcoming.
Maybe the best gauge of investor success (or failure) might be whether they are ‘on track’ to a successful retirement, which some define as replacing 75% of preretirementincome at age 67.
According to onestudy – I think it was conducted by Mass Mutual – revealed that *only 15%* of American workers are ‘on track’. Even without my HP12-C, it’s obvious it obvious then that 85% are not.
It’s not rocket science. It’s about three simple components: time, savings rates, and return.But, time is the only component that constantly declines; and, as it does, it creates pressure on the other two to outperform. That’s when mistakes are likely to happen.
When procrastination behavior reduces the available time,most ofthe pressure then falls on investment return, simplybecause most people feel limitedregarding how much they can save.
This may be why some people reach a point where they begin making the risky choices they soon live to regret. Investment mistakes can be committed by anyone – I even once met a CPA who didn’t know the difference between gain and yield.
But then, you wouldn’t want me doing your taxes, either.
Many people make mistakes, when it comes to retirement. In fact, many, if not most, retirement planning is doomed to failure. If you’d like to learn more about why, I’ve created a report on that very subject and you can get it free right here.
[](https://indfin.com/)Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
**Tags:** Retirement Income, Retirement Planning
---
### [Annuity Income May Contain a Hidden Surprise](https://indfin.com/annuity-income-may-contain-a-hidden-surprise/)
**Published:** August 24, 2016
**Author:** Jim Lorenzen
**Content:**
Jim Lorenzen CFP® AIF®Jim Lorenzen, CFP®, AIF®
Annuity income may feel secure; but, is it really? Once you realize that money is worth only what it can purchase, the effects of inflation become woefully clear.
Suppose your annuity will provide you with $50,000 in annual income through retirement. It sounds good, but does it provide for cost-of-living increases? If not, those payments will likely be worth less each year. Assuming a 3% inflation rate, your $50,000 will represent only about $48,500 of purchasing power in today’s dollars in the second year. In the tenth year, your purchasing power would be around $37,200 in today’s dollars; and, in the 20thyear, it would be around $27,700!
The pattern is clear: Your purchasing power would be declining each year. If you purchased the annuity in order to preserve lifestyle security, you may be very disappointed.
Remember, there are different kinds of annuities:
- Immediate
- Deferred
- Indexed
- Variable
All have their own bells & whistles and all have their own set of characteristics and costs, sometimes not so obvious. And, the chances are excellent you’re paying extra for any add-on benefits that may appear free. Often, you may be able to replicate those same benefits with less cost through some basic and prudent financial planning. Just remember NOTHING is ever the answer for ALL your money. Diversification isn’t about money; it’s about risk. And, there are more risks than one you should be considering. Also remember….
When something sounds too good to be true… well, you know the rest. If you’d like to learn more about income annuities, I’ve prepared an Income Annuity Primer for you. It’s free when you subscribe to IFG Insights. If you’re not happy with Insights you can always cancel; but, I think you’ll like both the primer and the ezine. You can get the primer here.
[](https://indfin.com/)
Enjoy!
Jim
———
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk)(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist)(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights)to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
***Jim Lorenzen**is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
**Tags:** Annuity, Annuity income, Guaranteed Income, Income Annuities, Retirement Annuities, Retirement Income
---
### [Why Do Individual Investors Seem to Always Lag Behind Market Returns?](https://indfin.com/whyindividualinvestorslagbehind/)
**Published:** February 19, 2018
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017c384ba1fa970b-320wi.jpg)Jim Lorenzen, CFP®, AIF®**
**A recent study by Morningstar**, a leading mutual fund research firm, compared mutual fund returns with the gains individual investors actually received. The study found that investor returns typically lagged fund returns. The reason: Investors tended to move cash in and out as markets would rise and fall, often buying high and selling low.[\[1\]](#_ftn1)
The study covered 10 years through the end of 2012, and found that funds posted an average annualized return of 7.05%, compared with a 6.1% average return realized by investors. (The returns factor in all stock and bond funds that Morningstar tracks. Investor returns are weighted based on asset owes into and out of all share classes of open-end mutual funds tracked by Morningstar. \[To learn more on why many individual investors have trouble reaching goals, see your report, *Why Most Financial Planning Will Probably Fail.*
Although a gap of a single percentage point may not seem like a big difference, it can make a significant impact over the long term, thanks to compounding. In fact, a hypothetical $10,000 investment returning an average of 7.05% annually would produce a total of $19,856 over 10 years compared with $18,078 for an average annual return of 6.1% over the same period. Over 30 years, the gap becomes even wider: $78,286 for the 7.05% return vs. $59,082 for the 6.1% return.[\[2\]](#_ftn2)
[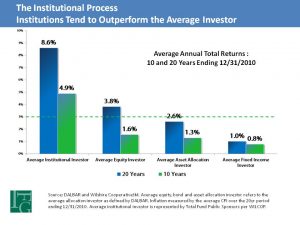](https://indfin.com/wp-content/uploads/2017/05/Institutional-Investors-vs-Avg-Indiv-Investor.jpg)The findings in the Morningstar study are apparently no fluke. Similar findings were discovered in a study by Dalbar back in 2010 (see graph).
What’s the reason for this? While I have admittedly not conducted a back-tested analysis on this, I do have what could be considered an informed opinion. It’s investor behavior – to be sure not a ground-breaking epiphany.
When investors buy in good markets and sell in bad ones, they generally lose – no news there. What is worth consideration is something Warren Buffett said years ago: If you think investing is fun, you’re doing something wrong. Real investing is boring; what you see on tv is financial porn. However, if you’re investing properly, you will virtually always be buying low and selling high.
Why? It’s as simple as having a properly constructed portfolio, designed to implement your formal financial plan, and adhering to a disciplined rebalancing process. Not all financial plans are sound, however. See our report.
**Rebalancing is key**. Regardless of your rebalancing schedule,[\[3\]](#_ftn3) it helps ensure you will be selling high and buying low. Important: Rebalancing does not guarantee gains nor does it guarantee against loss; but, it sure beats trying to ‘call’ markets.
Let’s use a simple hypothetical example using a simple stock and bond portfolio. If your financial plan indicates the best balance for you is 60% bond and 40% stocks and your investment portfolio is valued at $500,000, you’d be allocating $300,000 to bonds and $200,000 to stocks.
Using easy to grasp numbers, let’s assume that when it’s time to rebalance, based on a schedule you and your advisor have chosen, your bonds have lost 10% in value, due to rising interest rates while your stocks have gained 20%.
Your bonds are now valued at $270,000 (down by $30,000) and your stocks are now valued at $240,000 (up by $40,000). Your total portfolio is now valued at $510,000. Not bad, but our schedule says it’s time to rebalance and we do believe in investment discipline.
40% of $510,000 would indicate a stock allocation of $204,000; but the current value of that portfolio is $240,000 due to the run-up. That means trimming our stock exposure by $36,000 – we’re automatically “selling high”.
Our bond portfolio, now valued at $270,000 is down $30,000 due to rising interest rates. At a 60% allocation, we should have $306,000 (60% of $510,000) in bonds. Obviously, that’s where the $36,000 from our stock sales will go. We’re “buying low” into a rising interest rate market.
In the real world, portfolios aren’t quite so elementary. There are investment styles within each asset class and there are sectors within each style. It can get rather sophisticated, but technology helps.
You may have heard it a thousand times; it still bears repeating: It begins with a plan. If you don’t have one, you’re lost – and if you think you have your plan in your head, your heirs will be helpless, even if you aren’t already.
[\[1\]](#_ftnref1) Russel Kinnel, “Mind the Gap: Why Investors Lag Funds,” Morningstar, February 4, 2013.
[\[2\]](#_ftnref2) Results are for illustrative purposes only and in no way represent the actual results of a specific investment.
[\[3\]](#_ftnref3) Transaction costs and tax implications should not be ignored.
As I noted earlier, many plans will likely fail. See our report. Hope you find this helpful.
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** Financial planning, life insurance, Reducing Risk, term insurance, term insurance vs permanent
---
### [Will My Annuity Income Really Increase?](https://indfin.com/will-my-annuity-income-really-increase/)
**Published:** December 13, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/11/Piecing-Retirement-Puzzle-Path.png)**Jim Lorenzen, CFP®, AIF****®**
Annuities can play a valuable role in a retirement portfolio; but, often they’re somewhat oversold.
**Should equity-indexed annuities serve as a substitute for stocks?**
Short answer: No. And, when making historical performance comparisons, you’d be better off comparing them to CDs and traditional fixed annuities. An equity-indexed annuity is nothing more than an interest-bearing IOU from an insurance company paying an unpredictable interest rate each year… anywhere from 0% up to the “cap”, which these days can be around 4-5%. So, do the math: if you get the maximum cap in two out of three years – let’s assume 5% – and zero in every third year, you’re averaging 3.33%. It’s up to you to decide whether that’s a good return. It is tax-deferred until withdrawn, but you also have a liquidity issue.
As I said, in some cases, they can make sense for a portion of a bond portfolio because of downside guarantees from the insurance company; but, you should also see if another alternative might make more sense.
**“My annuity Living Benefit is guaranteed to return 5-10% each year!”**
Not likely (translation: No). Too often, people look at the ‘income benefit base’ in the paperwork and assume (because they see a dollar sign in front of the number) they’re looking at real money. Not so.
Think of the income benefit base as “sky miles” – it’s a number that’s used to calculate the amount of income that will be generated and has nothing – zero – to do with the return on the policy itself.
Technically, many, if not most, annuity offerings state that if the account value ever exceeds the income benefit base, the purchaser will receive a ‘step-up’ in income. Realistically, however, it’s not likely (translate: won’t happen) these days, considering the spreads and cap rates the insurance companies are using. As long as living benefit income is calculated on the income base vs. the account value, you shouldn’t expect anything beyond what’s guaranteed on the first day of the policy.
If you’re considering purchasing an annuity, there are seven things you should consider ahead of time. You might find this short report worthwhile.
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement
**Tags:** Inflation, Retirement Annuities, Retirement Income, Retirement Strategy
---
### [Who's Looking Out for YOU?](https://indfin.com/whos-looking-out-for-you/)
**Published:** September 18, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01b8d06b519e970c-320wi1.jpg)
**Your candidates likely reside in three camps:**
Not all advisors are alike; and it’s worth knowing how to tell them apart.
While the overwhelming majority of investment and financial advisors are honest, reputable, qualified, and provide quality work for loyal clients, those who are looking for a potential advisor do face a daunting task. It isn’t easy.
Some are simply pushing high-commissioned products trying to “build production” because they have to meet a quota to keep their desks. Others, also chasing commissions, are simply hawking annuities – indeed, some brokerages specialize in annuities and buy tv advertising touting the benefits (without disclosing the drawbacks) – all the viewer hears is “our clients don’t lose money”.
So, who’s who? And, how do you recognize the standard of care you desire?
- Some are licensed for investments, some for insurance, and some for both.
- Some are captive (they work for a known, well-established firm), and some are independent. Among the independents are both solo practitioners and practice ensembles with several advisors.
- Some are brokers (commission-earning registered representatives), some are Registered Investment Advisors (RIAs) who are compensated by fees; some are hybrids (registered representatives who are also associated with an RIA firm and can accept either form of compensation.
**The Legal Requirements**
Here is where “the rubber meets the road” – it may be the most crucial issue.
A broker is held to a “suitability” standard. This doesn’t mean many brokers don’t operate at a higher standard and, indeed, many do; but, this is the legal requirement. An RIA must adhere to a fiduciary standard. Here’s what all that means:
**The Suitability Standard**
There must be a reasonable basis to believe that the recommendation is suitable for the customer, based on information obtained through reasonable diligence to obtain the customer’s investment profile.
**The Fiduciary Standard**
All decisions made for a client must place the interests of the client ahead of his/her own at all times;.
For example, a broker can make a decision based on which recommendation pays the highest commission and still be within the legal standard, as long as the recommendation is suitable. The RIA, however, must place the client’s interests first, ahead of his/her own.
Brokers are regulated by FINRA; RIAs are overseen by the SEC (if assets being managed exceed $100 million) or their individual state. Brokers must obtain and maintain a Series 7 general securities license and pass a Series 63 state exam. RIAs must pass a Series 65 exam, although in some states certain designations are accepted in lieu of the exam. California requires that RIAs must have passed the Series 7, as well.
**The Hybrid Model**
A registered representative (broker) may also be affiliated with an RIA firm, which is often the case where investments are sold – just look on the business card to see if you see something like, “*Securities offered (or provided) through XYZ Securities*“. If so, the firm is a broker-dealer for your registered representative. And, as I said, the firm is also an RIA and the rep is an RIA associate.
This allows the rep to provide planning while wearing his/her RIA hat, observing the fiduciary standard; however, when it comes time to make investment recommendations, the rep is then able to put on the registered representative hat, which means the fiduciary standard no longer applies and the suitability standard takes over. The client is seldom aware of the switch. Even when making recommendations under the suitability standard, the hybrid can accept fees, generally asset-based, for some assets while earning commissions on others.
**Insurance**
Many Registered Reps, RIAs, and hybrid advisors are also licensed for insurance. It’s also true than some aren’t. It really depends on the type of services they wish to provide for their clients. My own career path followed this route:
1. Captive registered representative in a major national firm, where I was also licensed for life and health insurance. Compensation was pretty much all commissions in those days.
2. Independence: I opened my own office as an independent registered representative offering securities through an independent broker-dealer. I maintained my life and health insurance license. When the broker-dealer became an RIA, I became associated and began offering institutional managers to my clients on a fee basis. Compensation evolved toward fees as I began converting existing clients and discontinued commissioned sales. I did maintain my life and health insurance licenses.
3. Independent RIA: I became an RIA and dropped by broker-dealer association, which meant going 100% fee-only for all investment related business. In order to be “pure” fee-only, I dropped my life and health insurance licenses. I operated this way for about five years. There’s more information [about my practice](https://indfin.com/all-about-ifg/ "About IFG") on my site.
I reacquired my life insurance license last year not long after a client I’d referred out to a life agent said to me: “Let me get this straight. Are you telling me you think they’ll do a better job for me than you will?” Since insurance plays such an integral role in estate planning and financial security, I decided it belonged back in my core offering; however, since ongoing management oversight isn’t generally an issue, I was comfortable receiving commission rather than fee compensation (I guess I should point out that whenever an insurance product is needed that includes investment components requiring ongoing management oversight, only no-load products are used and compensation is by fees only. Health insurance is something I feel more comfortable referring to a health insurance specialist.[\[1\]](file://notebook/documents/LAPTOP%20DESKTOP/INVESTMENT%20ADVISORY/MARKETING/BLOG-EZINE-NL%20PREP/Who%27s%20Looking%20Out%20for%20You.docx#_ftn1)
[](file://notebook/documents/LAPTOP%20DESKTOP/INVESTMENT%20ADVISORY/MARKETING/BLOG-EZINE-NL%20PREP/Who%27s%20Looking%20Out%20for%20You.docx#_ftn1)**How to Protect Yourself**
Ask the prospective advisor to answer the following in writing, then date and sign:
1. Are you held to a fiduciary standard in all dealings with me and my financial affairs? Will you acknowledge that status in writing?
2. Do you provide full service, comprehensive financial planning services as well as investment advisory services?
3. If you provide full service, comprehensive financial planning services, are these services performed by individuals that have obtained the Certified Financial Planner (CFP®) certification?|
It should be noted that some well-qualified, quality advisors do excellent work but work in firms (a captive relationship) that are dually-licensed (broker-dealers and RIAs) that will not allow their registered reps to sign such a document for fear of the obvious liability it might create. This may not be a reflection on the representative, but it does help identify the culture or environment you could be working within.
**Conflicts of Interest**
These are always required to be disclosed. And, while some firms tout the claim they have no interest conflicts, this is seldom, if ever, true. Personally, I think we all have conflicts and I have yet to see any advisor, including myself, who doesn’t.
- **Commissions**: Higher vs. lower commissions
- **Fees:** Depends on the form of the fees structure
- Asset based – A recommendation to pay-off the house reduces the assets under management and the advisor’s compensation.
- Hourly – Padding hours worked increases the advisor’s income
- Flat fee – Reducing the time spent, and maybe quality, increases profitability
Of course, there is a ‘flip side’ to all of this. The existence of commissions, for example, allow smaller investors to access professional advice they otherwise wouldn’t pay for – though many smaller investors are comfortable using “magic box” online solutions. Commissions also may inhibit frequent trading or changes, which seldom help.
Likewise, asset-based fees do provide an incentive for the advisor to limit risk in larger client portfolios, since the advisor’s income suffers when the portfolio value suffers.
Hourly or flat fees, while they sound good, can have a negative influence. Many people will refrain from seeking advice or help simply to avoid a fee. I have seen cases where a $500 savings resulted in a $100,000 mistake.
Maneuvering the maze isn’t easy and can be confusing; and many other well-meaning and excellent advisors will surely have their own thoughts on this; but, this may help get you started.
Jim
---
[\[1\]](file://notebook/documents/LAPTOP%20DESKTOP/INVESTMENT%20ADVISORY/MARKETING/BLOG-EZINE-NL%20PREP/Who%27s%20Looking%20Out%20for%20You.docx#_ftnref1) I’ve always been skeptical of professionals who hold a laundry-list of credentials and licenses. It’s been my experience that many of the credentials often turn out worthless and the licenses meaningless, since there would be just too much ongoing required reading to really stay knowledgeable.
**RESOURCES:**
**Visit** [**Jim’s Social Security Learning Center**](https://www.jlorenzen.sswise.com/ "Social Security Learning Center")
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Conversation Checklist") (does not require registration)
[Subscribe to IFG Insights ](https://tinyurl.com/IFGInsights "Subscribe to IFG Insights")
[The IFG Website](https://indfin.com/ "IFG Website")
IFG’s [Financial Resources website](https://finsecurity.com/Lorenzen "IFG Financial Resources Website").
Follow Jim on Twitter: @JimLorenzen
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [ROLLOVER DECISIONS - THE BEST AND THE WORST](https://indfin.com/therolloverdecision/)
**Published:** June 13, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/09/iStock_64047885_SMALL.jpg)Jim Lorenzen, CFP®, AIF®**
**Bad decisions = bad consequences = big costs!**
As you may have seen or heard me say many times, it’s not wise to act first and plan later; yet, that’s exactly what I’ve seen people do time and again over the last twenty-five years. As you can imagine, I’ve seen a few mistakes. That applies to rollover decisions, as well as other decisions regarding 401(k) and other retirement account assets.
You might enjoy seeing a short video on one big mistake many people make – and you can also get access to some additional resources and a rollover checklist I think you’ll find useful. You can find it all here.
There’s a right way and wrong way to do a rollover, if you should do one at all. Let’s quickly capsulize – there’s more to know, so you should consult with appropriate tax and legal advisors before acting. Here are the six best and worst rollover decisions people make:
**The Best**
1. ******[](https://indfin.com/wp-content/uploads/2016/11/Tax-Burden-Scale.png)Leave money in the qualified plan if retiring between ages 55 and 59½ and distributions are required.******Since there is no penalty on withdrawals from a qualified plan after attainment of age 55 and separation from service (age 50 for qualified public safety employees), distributions are more liberal than if funds are rolled to an IRA.Once funds are rolled to an IRA, there is generally a penalty for withdrawals prior to age 59½. Therefore, it’s best for people who need money from their retirement account in this age bracket to leave the money as is, in their company retirement plan.Often, people who have already completed their rollover are younger than age 59½ and need a distribution. In these cases, they can use rule 72(t) to avoid penalties. When they do this, it’s best to split the IRA into pieces for maximum benefit.Each IRA stands on its own, which means that taking 72(t) distributions from one account has no effect on the others. Therefore, if one IRA produces more income than is needed when placed on 72(t) distributions, you could split the IRA into more than one account, and use one of the smaller accounts to make your withdrawals. I am not a CPA or an attorney; so, check with the appropriate advisors.And in the future, if you need more income, you could begin equal distributions from another account as well. This could provide greater flexibility in meeting your immediate and future income requirements if under age 59½.
2. ******Make optimal use of creditor protection******Some IRA owners and financial advisors think that the recent changes to the federal bankruptcy rules automatically protect IRAs. That is not true. For creditor protection purposes, an individual would be wise to leave his funds in his qualified plan because ERISA gives complete creditor protection to qualified plans (note that one person qualified plans do not receive the protection–there needs to be at least one “real” employee in the plan). If the individual does roll over his qualified plan into an IRA, it is optimal to leave these funds in a separate rollover IRA, because the protection that the funds had under ERISA will follow the funds into the rollover IRA.
3. ******[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73de5d743970d-320wi2.jpg)Re-Check Your Beneficiaries******A company retirement plan (a qualified plan) is governed by the ERISA rules. And those rules state that you must name your spouse as a beneficiary or get spousal consent to name another person. The same rules do not apply to IRAs.**Remember this all important rule**–whoever you name as beneficiaries on your IRA account will inherit your IRA. Your will or living trust has no control over your IRA, so make sure your IRA beneficiaries are exactly as you desire.
**The Worst**
1. ****Get a check from the company****Of course, this is just foolish. The company must withhold 20% from the payment, so that a person with a $100,000 account will have $20,000 withheld, and will receive a check for $80,000. In order to complete a tax-free rollover, the taxpayer must deposit that $80,000 in an IRA plus $20,000 from their pocket to complete a tax-free $100,000 rollover.The taxpayer may eventually get the $20,000 withheld as a tax refund the following year, but that will not help their cash flow, as they need to complete their IRA rollover within 60 days of receiving the check from their qualified plan.The bottom line is that people should never touch their qualified funds. The only sensible way to move funds is a direct transfer from the qualified plan to the IRA custodian and avoid withholding.
2. ******Rollover company stock******Shares of employer stock get special tax treatment, and in many cases, it may be fine to ignore this special status and roll the shares to an IRA. This would be true when the amount of employer stock is small, or the basis of the shares is high relative to the current market value.However, if you have large amounts of shares or low basis, it might be a very costly mistake not to use the Net Unrealized Appreciation (NUA) Rules.[\[1\]](#_ftn1) If your company retirement account includes highly appreciated company stock, one option is to withdraw the stock, pay tax on it now, and roll the balance of the plan assets to an IRA. This way you will pay no current tax on the Net Unrealized Appreciation (NUA), or on the amount rolled over to the IRA. The only tax you pay now would be on the cost of the stock (the basis) when acquired by the plan.By the way, if you withdraw the stock and are under 55 years old, you have to pay a 10% penalty (the penalty is applied only to the amount that is taxable).For more information on NUA, get our complete report on the ***Six Best and Worst IRA Rollover Decisions***. You can do that here.
[Click here for your report!](https://indfin.leadpages.co/leadbox/147676173f72a2%3A12a1899aa346dc/5672463165816832/)
[\[1\]](#_ftnref1) IRS Publication 575
3. **Rollover after-tax dollars**Sometimes, qualified plan accounts contain after-tax dollars. At the time of rollover, it is preferable to remove these after-tax dollars, and not roll them to an IRA. That way, if the account owner chooses to use the after-tax dollars, he will have total liquidity to do so.You can take out all of the after-tax contributions, tax-free, before rolling the qualified plan dollars to an IRA. You also have the option to rollover pre-tax and after-tax funds from a qualified plan to an IRA and allow all the money to continue to grow tax-deferred.The big question is, “will you need the money soon?” If so, it probably will not pay to rollover the after-tax money to an IRA, because once you roll over after-tax money to an IRA, you cannot withdraw it tax-free. The after-tax funds become part of the IRA, and any withdrawals from the IRA are subject to the “Pro Rata Rule.”
Don’t forget the video, resources and checklist, which you can access here. And, don’t forget the report!
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement, Taxes
**Tags:** investment returns, Investment Strategy, managing risk, Reducing Risk, retirement decisions, Retirement Income
---
### [The Road to Retirement = 4 Simple Steps](https://indfin.com/the-road-to-retirement-4-simple-steps/)
**Published:** June 22, 2016
**Author:** Jim Lorenzen
**Content:**
*iStock Images*Jim Lorenzen, CFP®, AIF®
When I was young, my father once advised, “Jim, just save 10-cents out of every dollar you ever earn and you’ll never have to worry about money the rest of your life.”
He always was smarter than I’ll ever be. He was also right. But, while I listened, I didn’t follow his advice, which puts me right with most of America.
Behavioral finance is a young science that uses psychology to understand irrational thinking. DALBAR has been studying investor behavior for over thirty years and concludes that investors can be their own worst enemy. They usually make bad decisions at critical points. Example: During October, 2008, equity investors lost 24.21% while the S&P Index lost 16.8%. *\[Source: Investment Advisor, June 2016\]*
Behavioral finance suggests investors remember losses more vividly than gains, even if the gains are greater!
Last March was the seventh anniversary of the bull market – the third longest rally in history. Yet many have failed to realize much of the rebound due to their of buying back when the market was low. Many may also believe that we’re in a Fed-fueled market, anyway; but, that’s another discussion.
Sometimes, the value of an advisor is in saving the client more than his or her fee on the downside. After all, much of what investors need to do is more related to behavior than investment prowess.
Like my dad’s advice, the steps to a successful retirement aren’t simplistic; but, they are simple.
I created a short report, ***4 Simple Steps to a Comfortable Retirement***. It’s not earth-shaking, but for many I’m sure it will be well worth reading.
I hope you’ll find it both informative and helpful.
You can access it here.
Enjoy!
Jim
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** Financial Security, Retirement Planning, Retirement Strategy
---
### [Should You Buy TERM Insurance and INVEST the Difference?](https://indfin.com/termandinvest/)
**Published:** February 5, 2018
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2017/10/Older-man-with-cash_gettyimages.jpg)*Getty Images***Jim Lorenzen, CFP®, AIF®**
**BUY TERM INSURANCE! INVEST THE DIFFERENCE!** That’s the mantra that’s been preached (mostly by tv gurus selling their DVDs) since the 1970 (they were selling tape cassettes back then) and even before.
It seems logical: You buy term insurance and get pure protection with insurance dollars while you invest remaining dollars for retirement or other needs.
It even sounds catchy: *Buy term insurance and invest the difference.* That’s what your dad did, and grandpa before him. Of course, they may not have majored in economics or finance.
Does the old “buy term” maxim they’ve been preaching really hold up under real number-crunching analysis?
Well, here’s an analysis using numbers you might find interesting. While not exhaustive, it certainly will shed some worthwhile light worthy of discussion. You can access it here.
Hope you find this helpful.
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Life Insurance, Planning, Retirement
**Tags:** Financial planning, life insurance, Reducing Risk, term insurance, term insurance vs permanent
---
### [The Top 5 Myths of Retirement Planning](https://indfin.com/5myths/)
**Published:** June 14, 2017
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/06/iStock_44633966_SMALL.jpg)iStock Images**Jim Lorenzen, CFP®, AIF®**
I came across this video on the Five Myths of Retirement – It’s by Northwestern Mutual. I have no relationship with them; however, it’s an excellent educational video and I thought you might find it interesting.
We know that many retirement expenses are guaranteed; but, how of the income required to meet those expenses is also guaranteed? If having a guaranteed income floor is important to you, we have another educational video you might enjoy viewing.
If you would liketo see it, grab a cup of coffee – it’s about 20-minutes long – and you’ll learn about a process for arranging assets that may be eye-opening,you can do so by clicking here.
**Your Roadmap?**
This educational video depicts an eye-opening strategy. The specific financial tools used to implement this strategy will be different for each individual, depending on specific needs and desires; but, it is a strategy that could put retirement on ‘auto-pilot’. Keep in mind, this is but one strategy for addressing retirement income needs. There are others. The one that’s right for you would depend on your plan
The plan comes first. We don’t do “ready-fire-aim”.
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement
**Tags:** investment returns, Investment Strategy, managing risk, Reducing Risk
---
### [Is the 4% Rule Still Valid?](https://indfin.com/4percentrule/)
**Published:** June 19, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/09/pic1.png)Jim Lorenzen, CFP®, AIF®**
Ever hear about the 4% Rule? It’s about safe withdrawal rates for retirement income. If you’ve been following my pontifications over the years,you probably recognize this;but, if the rule is unfamiliar to you, here’s a brief description.
The 4% rule was the result of some back-testing and research by a financial advisor named William Bengen. The objective was to identify a ‘safe’ withdrawal rate for retirement income that would answer the question, “How much can I safely withdraw from my portfolio without having to worry about running out of money?”
His results were published in 1994 and identified 4% as the withdrawal rate that would provide an 80% success probability over a 30-year period, regardless of market conditions.
Of course, it’s a probability based on back-testing. The problem investors face is that inflation, which has been historically low for some time now, could rear it’s ugly head and impact withdrawals significantly. So, we’re still dealing in probabilities.
Let’s look at a hypothetical example:
[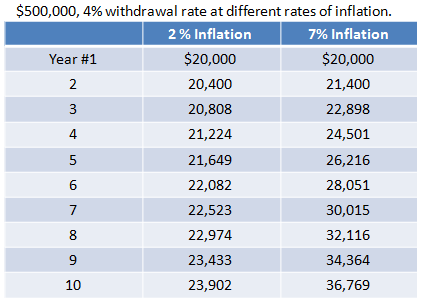](https://indfin.com/wp-content/uploads/2017/06/500K_4WD_DiffInflationRates.png)
**The ending annual expensesusing a 7% inflation rate is 53.8% higher than if inflation remains at 2% for the entire decade.** Is 7% an unreasonable figure? If you’re old enough be be concerned about outliving your money – or your income – you know it’s very reasonable. Remember the double-digit inflation of the late 1970s?
What does that do to our probabilities discussion? GIGO.
Planning is as much about what we don’t know as what we know. It’s about testing and stress-testing our assumptions.
For many, the real question is not whether money will last – it doesn’t do much good to have some money if that money won’t produce the income you need to maintain your desired lifestyle – it’s whether you will have the inflation-adjusted income you will need.
**Key question: Are you comfortable dealing with probabilities or guarantees?** The strategy that’s right for you will be different depending on your answer.
We know that many retirement expenses are guaranteed; but, how of the income required to meet those expenses is also guaranteed? If having a guaranteed income floor is important to you, we have an educational video you might enjoy viewing.
If you would liketo see it, grab a cup of coffee – it’s about 20-minutes long – and you’ll learn about a process for arranging assets that may be eye-opening,you can do so by clicking here.
**Your Roadmap?**
This educational video depicts an eye-opening strategy. The specific financial tools used to implement this strategy will be different for each individual, depending on specific needs and desires; but, it is a strategy that could put retirement on ‘auto-pilot’. Keep in mind, this is but one strategy for addressing retirement income needs. There are others. The one that’s right for you would depend on your plan
The plan comes first. We don’t do “ready-fire-aim”.
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Inflation, Investing, Planning, Retirement
**Tags:** investment returns, Investment Strategy, managing risk, Reducing Risk
---
### [What Business Owners Need Most!](https://indfin.com/whatbusinessownersneedmost/)
**Published:** October 2, 2017
**Author:** Jim Lorenzen
**Content:**
**[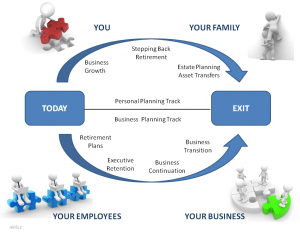](https://indfin.com/wp-content/uploads/2017/09/i605c1_BO_Lifecycle_slide_201611.png)Jim Lorenzen, CFP®, AIF®**
Business owners spend long hours for many years trying to build their dream. For many, their business represents 70%, 80%, even 90% of their net worth! It’s not unusual to have everything tied-up in their business ownership.
In essence, they have everything riding on one stock – something they’d never do with any other stock, even if the company was run by the greatest CEO on earth.
Their business is the source of their income, including salary and bonuses, as well as the source of all their benefits, including retirement funding and health insurance.
Business owners spend 110% of their energy on trying to grow their business; yet, if you ask them how they’ve planned their exit, you’ll often get a blank stare. Some say they plan to work ’til they drop; others say they’ll sell it, sure that it will be an attractive purchase.
How many will exit their business? Answer: 100% – either head first or feet first. Either way, how will the business be monetized?
**Many don’t know what their business is worth.**
I personally know one person who built a small but very successful restaurant chain that enjoyed excellent sales – until he unexpectedly (and rather quickly, unfortunately) contracted terminal cancer and died. The restaurants soon all went into receivership and were either liquidated or taken-over for pennies on the dollar – the family left with only his life insurance proceeds.
[](https://indfin.com/wp-content/uploads/2017/09/meetingtable.jpg)
**Many have no idea how they will exit.**
It didn’t have to happen that way. He had key people in-place; but, he didn’t know how to plan business continuity. He also could have created a funding mechanism for his family to monetize all he’d worked for (in addition to his life insurance), but he hadn’t done that, either.
He, like many successful business owners running established businesses, didn’t even know what his business value, let alone have a mechanism in place to convert his asset into liquid dollars…. something he could have enjoyed even if he’d lived.
[](https://indfin.com/wp-content/uploads/2017/10/i601d_How-To-Establish-Business-Value_Cover-Image.png)He probably didn’t want to spend the money on a formal appraisal; but, he didn’t have to do that, either – informal valuations for retirement and exit planning could have met his needs. \[You can learn more about business valuation in our free report, which you canaccess here. If you would like a copy, we’ll also make sure you receive other relevant information from time to time.\]
How about the business with multiple ownership? If/whensomething happens to one of them, do the others want to have the surviving spouse as a partner – maybe an equal partner – even though they may make little or no contribution to business success?
What if there’s a divorce? What if one simply decides to ‘hang it up’? What if one files for bankruptcy? Without the right mechanisms in place, the other owner(s) could be facing litigation or liquidation.
**Many don’t know the solutions that are available.**
He might have felt he didn’t want to siphon off dollars from cash flow that could be otherwise used to grow his businesses; but, there are mechanisms that can mitigate that concern, as well.
[](https://indfin.com/wp-content/uploads/2017/09/iStock_000004694200-Goal-ThinkBig.jpg)
Successful owners of established businesses can be busy – often too busy to pay attention to the very issues they see as their ultimate objective in the first place.
I can empathize. Years ago I built a publishing business. Publishing weeklies combines the functions advertising, sales, production, manufacturing, distribution, credit and collections. Front to back, it entails virtually every business function you can think of, including deadlines and resource management.
I had a general manager named Nick who came up ‘through the ranks’ and became very capable at running the entire organization, allowing me to pursue other initiatives. I ended-up selling my businesses on the open market; but, had I known, I could have actually sold the whole thing to Nick – probably for more money even though he didn’t have much money. Simply by putting the right mechanisms in place early, I could have had a ready-made buyer in place… and one who not only knew the business, but knew the customers – and one that wouldn’t have made the bankers nervous.
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Business Owners, Executive Compensation, Planning, Retirement
**Tags:** business owners, business owners retirement, selling closely-held business, Selling your business
---
### [The REAL Cost of Luxury](https://indfin.com/the-real-cost-of-luxury/)
**Published:** April 18, 2024
**Author:** Jim Lorenzen
**Excerpt:** When most people buy things, they see only the price tag; but that doesn’t reveal the REAL cost, especially when it comes to luxury items. The real cost of luxury can be more than they realize.
**Content:**
Take automobiles. I’m in California – a place where many have bought into the myth that you are what you drive. A car is a necessity; but, it can be a luxury, too. And, the real cost of luxury can be more than expected.
Let’s use a simple example (I’m good at simple): You have the choice between a $25,000 car and a more luxurious $50,000 car. Let’s assume you have sufficient income and good size savings, so you can afford either one. In fact, you don’t even have to finance your purchase – you can pay cash!
One variable, of course, is your age: how long until you have to retire. Why is that important? Let’s see.
Let’s assume you have 20 years left before retirement and you can afford the $50,000 car. You buy it. How much did you spend? Now we get into time-value of money and how much that money could have earned elsewhere. Since you opted for the $50,000 car instead of the $25,000 car, the difference in spend is $25,000 (you do need a car, so it’s the difference between necessity and luxury).
If that additional $25,000 had been invested at earned a long-term average annual return of 6% in a balanced portfolio, it would have grown to $80,178 (for simplicities sake, I’m ignoring taxes and expenses in this example).
Suppose you bought a new luxury car every five years. The next $25,000 expenditure invested the same way would have grown for 15 years to just under $60,000. The third car growing for ten years would have grown to over $44,000. You get the idea: these three cars cost about $184,000 extra of retirement money because of the desire for luxury.
$184,000 over 20 years may not seem like the end of the world; and, at 2.5% inflation, it is worth just over $112,000 in today’s purchasing power. But, when you realize that the car may not be the only luxury purchase you make over a twenty year period, all those dimes and pennies can add up.
I’m sure I’m not the only financial advisor whose most successful clients are driving older cars, not throwing money at depreciating assets. A good lesson for our kids and grandchildren, too.
Are you planning your future? You can [begin your journey here](https://indfin.com/).
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Should You Buy Term Insurance and Invest the Difference?](https://indfin.com/termanalysis/)
**Published:** March 22, 2017
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/01/Female_Mgr_Responsible_Concern.jpg)*iStock Images***Jim Lorenzen, CFP®, AIF®**
I first heard this mantra in the 1970s. It resurfaced again in the ’80s and again in the 90s. Funny thing is it’s only the guru’s selling CDs and DVDs – people who are neither registered, regulated, or even have a single client – who keep promoting it.
**Nevertheless, it does sound good! Would it work.** I thought you might like to see an independent analysis that even gives term insurance a head start! What if you could buy $500,000 of term insurance for only $1 a year! Silly, I know, but, the analytics are interesting – and worth understanding.
I think you’ll find it interesting. You can access it here.
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Life Insurance, Planning, Retirement
**Tags:** life insurance, life insurance decsions, term insurance vs permanent
---
### [Taxes in Retirement: A Potential Time-Bomb for Many!](https://indfin.com/taxes-in-retirement-a-potential-time-bomb-for-many/)
**Published:** April 6, 2016
**Author:** Jim Lorenzen
**Content:**
Jim Lorenzen, CFP®, AIF®
**No one knows what taxes will be like in the coming years;** but, with a debt that’s rising dramatically and an ageing baby-boomer population moving ever-increasing numbers into retirement, this is a collision that isn’t hard to predict.
For retirees, it’s like being in business with a partner who has the ONLY vote on how[](https://indfin.com/a-zero-percent-return-can-be-powerful/istock_unclesamliftingwallet_medium/)much of the company gross s/he gets to take. And your partner gets it BEFORE you get to pay the overhead with whatever s/he decides should be left.
Not good.
Is it possible to completely eliminate Uncle Sam as a partner? I think so. So do many others, including retirement guru, Ed Slott, who many of you may have seen on PBS and who is also a practicing CPA.
But, is it possible for everyone? Maybe not; but, almost everyone can mitigate taxes dramatically and many can likely eliminate them completely.
Think about THAT! Wouldn’t it be nice if you lived through retirement without paying income taxes, regardless of what tax law changes Congress made? Do the math: That could really add up!
**First, a dose of reality:**
- If you’re retiring now, a tax-free retirement isn’t going to happen. There are no ‘quick-fixes’, but you can take steps to reduce future taxes, and keep more of your own money. Everyone’s situation is different, but it’s worth pursuing.
- If you’re more than ten years away from taking retirement income from your retirement plans (you must begin taking required minimum distributions around the time you turn age 70-1/2), then a tax-free retirement may be very realistic!
How do you begin your journey to a possible tax-free retirement? You might want to begin by reviewing this 12-page outline, ***4 Steps to a Tax-Free Retirement***.

This will help you understand your situation, provide a framework for your decision-making, and hopefully get you started on your journey.
You can get your copy by clicking here.
Enjoy!
Jim
————————
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-based registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Taxes
**Tags:** Retirement Income, Retirement Planning, Tax-Free Retirement Income
---
### [Getting Ready to Take a RMD? Here's a 4-Point Checklist.](https://indfin.com/rmdchecklist/)
**Published:** September 26, 2019
**Author:** Jim Lorenzen
**Excerpt:** RMDs can present a tax trap for the unwary. Here's a 4-point checklist to help you avoid the pitfalls.
**Content:**
**[](https://indfin.com/wp-content/uploads/2017/05/Coffee_with_RMD_Pencil.png)Jim Lorenzen, CFP®, AIF®**
Remember the 1990s? That was when every business channel had multiple programs with business gurus picking and ranking mutual funds. It was a time when many mutual fund managers were becoming the ‘rock stars’ of financial meda. Everyone wanted to know what Peter Lynch, Bill Gross, and others were buying, selling, and saying.
If you were one of those following all those shows back then, you were no doubt thinking about your financial future. And, if you were born in the years following 1946, chances are you’re a ‘baby boomer’ – a term we’re all familiar with by now.
I read somewhere that there are 65,000 boomers turning age 65 every year! And, those turning 70-1/2 have hit a big landmark: It’s the year – actually it’s up until April 1st of the following year – Uncle Sam begins sticking his hand into your retirement account – after all, he is your partner; and, depending on your combined state and federal tax-bracket, his ownership share can be pretty significant, depending on the state you live in. Yes, that’s when you must begin taking required minimum distributions (RMDs).
By the way, if you do wait until April 1st of the following year, you’ll have to take TWO distributions in that year – one for the year you turned 70-1/2 and one for the current year. Naturally, taking two distributions could put you in a higher tax bracket; but, Uncle Sam won’t complain about that.
So, now that you’ve been advised of one trap that’s easy to fall into, what are some of the others? You might want to give these concerns some thought – worth discussing with your tax advisor, as well as your financial advisor.
1. **Not all retirement accounts are alike.**
- IRA withdrawals, other than Roth IRAs, must be taken by December 31st of each year – and it doesn’t matter if you’re working or not (don’t forget, there is a first year exemption as noted earlier).
- 401(k) and 403(b) withdrawals can be deferred past age 70-1/2 provided you’re still working, you don’t own more than 5% of the company, and your employer’s plan allows this.
- As noted, Roth IRAs have no RMD requirements. Important: If you’re in a Roth 401(k), those accounts are treated the same as other non-Roth accounts. The key here is to roll that balance into a Roth IRA where there will be no RMDs or taxation on withdrawals.
2. [](https://indfin.com/wp-content/uploads/2014/09/Fotolia_5386670-DontSkipDetails.jpg)*Fotila Images***Get the amount right!**
The amount of your total RMD is based on the *total value of all of your IRA balances requiring an RMD as of December 31st of the prior year*. You can take your RMD from one account or split it any or all of the others. Important: This doesn’t apply to 401(k)s or other defined contribution (DC) plans… they have to be calculated separately and the appropriate withdrawals taken separately.
3. **Remember: It’s not all yours!**
You have a business partner in your 401(k), IRA, and/or any other tax-deferred plan: Uncle Sam owns part of your withdrawal. How much depends on your tax bracket – and he can change the rules without your consent any time he wants. Some partner. Chances are you will face either a full or partial tax, depending on how your IRA was funded – deductible or non-deductible contributions. Important: The onus is on you, not the IRS or your IRA custodian, to keep track of those numbers. Chances are your plan at work was funded with pretax money, making the entire RMD taxable at whatever your current rate is; and, as mentioned earlier, it’s possible your RMDs could put you in a higher tax bracket.
It’s all about provisional income and what sources of income are counted. The amount that’s above the threshold for your standard deduction and personal exemptions are counted. By the way – here’s something few people think about: While municipal bond interest may be tax-free, it IS counted as provisional income, which could raise your overall taxes, including how much tax you will pay on Social Security income. Talk to your tax advisor.
4. **[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a511e3d0c5970c-320wi.jpg)Watch the calendar.**If you fail to take it by December 31st of each year – even if you make a miscalculation on the amount and withdraw too little – the IRS may hit you with an excise tax of up to 50% of the amount you should have withdrawn! Oh, yes, you still have to take the distribution and pay tax on it, too! There have been occasions when the IRS has waived this penalty – floods, pestilence, bad advice, etc.
Remember to talk with your tax advisor. I am not a CPA or an attorney (and I don’t play one on tv); but, of course, these are issues that come up in retirement planning and wealth management quite often.
Happy retirement!
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Investing, Planning, Retirement, Taxes
**Tags:** Financial planning, Reducing Risk, retirement mistakes, Retirement Planning, Retirement Strategy
---
### [Can You REDUCE Risk by ADDING Risk?](https://indfin.com/can-you-reduce-risk-by-adding-risk/)
**Published:** May 4, 2016
**Author:** Jim Lorenzen
**Content:**
Jim Lorenzen, CFP®, AIF®
Does ‘adding’ a riskier position to a portfolio actually REDUCE the total portfolio risk?
The fact is many investors are often their own worst enemy. The media gurus – usually selling their own DVD sets – have succeeded in focusing on fees and expenses (something they’re correct in doing) to the exclusion of any possible value (something they’ve been successful in doing to the point of dereliction). The unfortunate result has been many portfolios that are scattered vs. diversified (as this Morningstar chart depicts) and too conservative to the point of being risky.
But, risk is a concern! However, it is often possible to reduce risk by actually adding a riskier position. The key lies in understanding investment correlation.
You might find this short report helpful; just click on the button below.
[Adding Risk Report](https://indfin.leadpages.co/leadbox/14327a573f72a2%3A12a1899aa346dc/5747976207073280/)
Enjoy,
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning
**Tags:** Investment Strategy, Reducing Risk, Retirement Planning, Retirement Strategy
---
### [A Zero Percent Return Can Be Powerful!](https://indfin.com/a-zero-percent-return-can-be-powerful/)
**Published:** March 2, 2016
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/how-much-should-you-be-saving/6a017c332c5ecb970b0192ac05f306970d-320wi/)The financial landscape is known for its complexity;** and the plethora of confusing financial products – not to mention the alphabet soup of designations and certifications – can present a daunting task for any normal person to unravel. And, every time the market changes, the product vendors come out with another solution.
When you add to all this the media gurus who want you to buy their DVD packages instead of ‘throwing away’ a penny per dollar for professional advice – and who can blame anyone for listening when anyone with a license to sell can legally call themselves a ‘financial planner’ – it’s a situation that would make most sane people want to throw up their hands and run to live in the forest.
Of course, consumers do have their share of responsibility for taking the easy route – relying on television gurus and consumer magazines trying to sell circulation – rather than actually laying out money for more academically-oriented educational material or investing in qualified advice.
So, at the risk of appearing as simplistic as the media gurus, I thought I’d just provide some simple mathematical insights. I hope you might find this somewhat helpful.
**Buying back losses is difficult.**
It takes about a 43% return to buy-back a 30% loss. If an investment suffers a 30% loss, dropping from 100 to 70 for example, it would take a 42.9% return just to get back to even (30/70 = 0.4286).
Realizing that, limiting downside exposure can be quite helpful. For example, take a look at this hypothetical scenario below. Portfolio A is invested in our hypothetical market and Portfolio B is managed for limiting downside risk (also purely hypothetical). While our fictitious manager captured only 80% of the upside (never beating the market), s/he was still able to ‘beatthe market’ long term by limiting downside capture to only 70%.
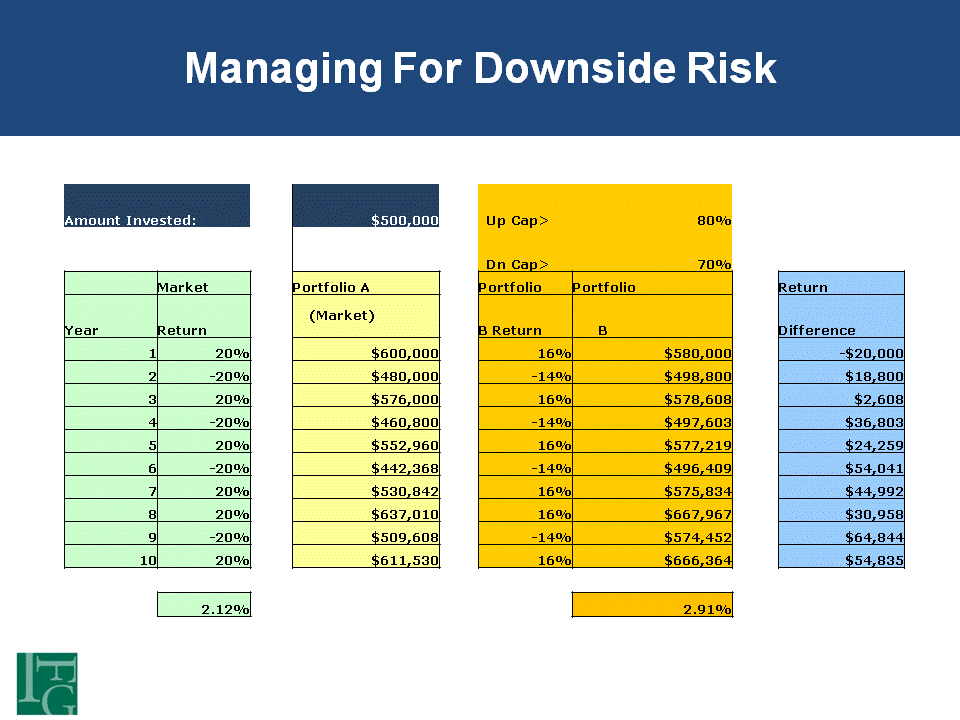
It’s all hypothetical theory, of course, but it does demonstrate a principle: Limiting downside loss can be more powerful than upside capture, particularly since most managers do not outperform the market and virtually none consistently outperform the market long term.
Television gurus make a big deal out the fact managers can’t beat indexes, but it’s a false argument. An index is not a measure of what YOU need to do. Your GOALS are what’s important, and whether you’re on track.
Indexes do not have expenses and they also don’t pay taxes. If your house went up in value perfectly tracking an index, would you have tied the index? Of course not. An index doesn’t have annual expenses like interest expense on your mortgage, maintenance, repairs, insurance, and property taxes. If you add those expenses and then compute the return you’d need to ‘tie’ the market, you might be astounded – that’s bigger than `surprised’, but I digress.
**What if you could *eliminate* the downside?**
Let’s suppose you could, hypothetically, never lose money with a trade-off than you would have a limit on how much you could achieve as a return each year? What would *that* look like?
Let’s suppose you would never lose – if the market lost 5%, your return would be 0%, i.e., no loss, and in exchange you could never make more than 10%. How would you fare?
Let’s start by taking a look at what was probably the worst ten-year period in history: The period from 1929-1938 – the crash and Great Depression.
**[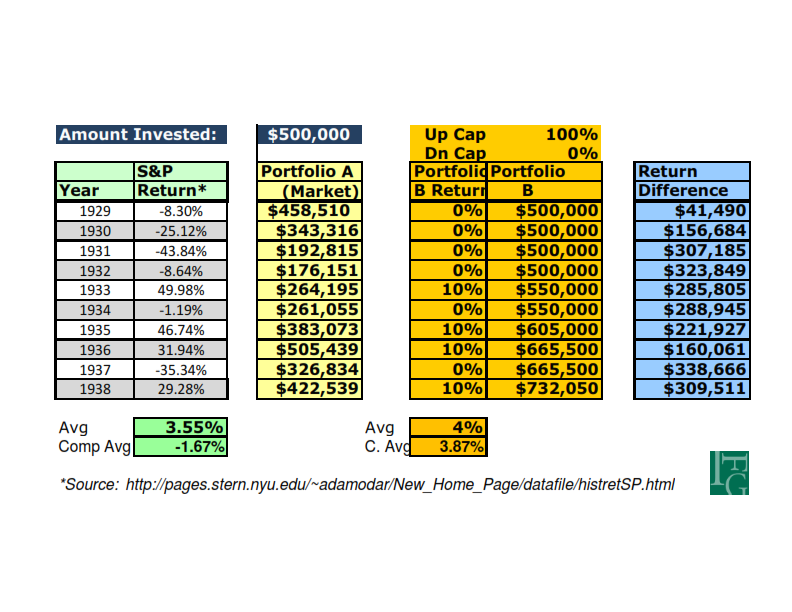](https://indfin.com/a-zero-percent-return-can-be-powerful/managing-downside_sp29-38-vs-no-loss-w-cap_001/)** Portfolio A, if it had remained invested throughout the entire period, would have seen a $500,000 portfolio reduced to $422,539.[\[i\]](#_edn1) As you can see, our hypothetical ‘no-loss’ but capped at 10% portfolios would have grown to $732,050. But, what’s interesting are the percentages!
Many companies love to use ‘average’ (arithmetic) returns, which simply add-up all the annual returns and divide by the number of periods, in this case, 10. Looking at a simple average, we can see the difference is only 0.45%. But, this isn’t the return percentage you want to see.
The average annual compounded (geometric) returns are more telling. Those returns tell you what actually happened to the investor! As you can see, the compounded return for the period was -1.67% per year for the ‘market’ investor, and 3.87% for our hypothetical Portfolio B – a spread of 5.54%!
**A little more food for thought**
All your life you’ve been told to ‘max-out’ your 401(k). Should you?
Well, up to your employer’s match, it can make some sense; but,, how about unmatched money?
Suppose you invest $5,000 a year for 30 years (total of $150,000) and average a 6.5% return. Your total at the end would be about $463,000, depending on timing of your deposits. But, while your statement may show $463,000, much of it will belong to Uncle Sam.
[](https://indfin.com/a-zero-percent-return-can-be-powerful/istock_unclesamliftingwallet_medium/)**How much?** It depends on what the tax laws are during your retirement. If you withdraw $50,000 each year of retirement and are in a 30% tax-bracket, you’ll pay $15,000 in taxes each year. In ten years, you will have paid $150,000 in taxes; but, the chances of your retirement lasting 20 years or longer is probably very good, which means $300,000+ in taxes. And, if you’re like many who live three decades in retirement, you could be facing more than $450,000 in taxes!
But, wait! Your 401(k) had only $463,000 to begin with! Welcome to longevity risk… and that’s if the tax laws don’t change – good luck.
Another option: Instead of paying taxes on “the harvest” as we did above, you pay taxes on “the seed”. We’ll use the same example: $150,000 invested over 30 years earning 6.5%. If you pay taxes on the money as you earn it over 30 years, your total taxes paid by the end, using the same 30% tax bracket, now come to only $45,000! Big difference, ya’ think?
Your $3,500 annual investment (after taxes) would, depending on the timing of your deposits, would probably grow to around $322,000 – again using the same 6.5% average annual return.
Whether or not you pay any capital gains on realized gains, during the period or at withdrawal, will depend on
(a) the tax laws at the time, and, more importantly,
(b) how the money is arranged and held until retirement.
There are people who do pursue a tax-free retirement strategy. If you’re interested, you can learn more about that in a one-hour on-demand webinar I’ve recorded, which you can access here. I think you’ll find it eye-opening, if not helpful.
James Lorenzen, CFP®, AIF®
[***\[i\]***](#_ednref1) *This does not include any expenses or taxes (indexes don’t pay either) and you cannot buy an index anyway. You can only purchase shares of an index mutual fund or an exchange –traded fund (ETF).*

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
---
### [RETHINKING PRIORITIES? SOME THOUGHTS FOR 2016](https://indfin.com/2016-priorities/)
**Published:** February 9, 2016
**Author:** Jim Lorenzen
**Content:**
Jim Lorenzen, CFP®, AIF®
**The key to pursuing longer-term financial goals, such as retirement and education funding, is to have a well-thought-out plan that assigns actual dollar amounts to each goal — and a timetable for getting there.**
Financial resolutions are only as good as your follow-through. Here are some planning considerations for the three key stages of your financial life — accumulation, preservation, and transfer.
**Rethinking your financial priorities? Here’s some food for thought for all of your goals:**
Financial resolutions are only as good as your follow-through. Here are some planning considerations for the three key stages of your financial life — accumulation, preservation, and transfer.
These same resolutions often fall prey to the same procrastination that hinders personal aspirations. Yet current volatility in the financial markets along with other unsettling factors such as the impending presidential election and widespread geopolitical unrest may have led investors to pause, rethink their financial situations, and set new expectations for the future.
Resolutions typically fall into one of three financial “life stages” — accumulation, preservation, or transfer of wealth. In order to establish action plans for these phases, you need to examine opportunities, identify challenges, and add a dose of reality to your planning efforts.
**Accumulating Assets[](https://indfin.com/bad-advice-repeated-becomes-accepted-knowledge/istock_000003860264-femaleleader/)**
The key to pursuing longer-term financial goals, such as retirement and education funding, is to have a well-thought-out plan that assigns actual dollar amounts to each goal — and a timetable for getting there. On this score, many investors are falling well short of the mark.
For instance, research compiled by the Employee Benefit Research Institute (EBRI) indicates that a sizeable percentage of workers say they have virtually no money in savings and investments.\* Specifically, among workers who provided this type of information, 57% reported that the total value of their household’s savings and investments, excluding the value of their primary home and any defined benefit plans, is less than $25,000. This includes 28% who say they have less than $1,000 in savings.\*
If you find yourself behind in your accumulation efforts for major life expenses, such as retirement, don’t despair. There are many opportunities to jump-start your savings campaign.
- Make the most of employer-sponsored plans. For participants in 401(k)s, 403(b)s, and 457 plans, the contribution limit stands at $18,000 for 2016 with an additional $6,000 in catch-up contributions allowed for those who are 50 or older.
- Maximize IRA contributions. In 2016, you can contribute up to $5,500 to a traditional or Roth IRA (or split that amount between the two types of accounts). Add another $1,000 to that total if you are making catch-up contributions.
[](https://indfin.com/fia/6a017c332c5ecb970b01a73dd6f67e970d-320wi-2/)iStock Images**Preserving Assets**
Holding on to your assets requires a disciplined, long-term view. Most people plan for a retirement to span 25-plus years, but evaluate their portfolios’ performance over the last quarter. Particularly in volatile market environments, investors tend to move in and out of positions too quickly, potentially causing them to sell low, buy high, and abandon asset allocation fundamentals.
Short-term declines are inevitable and may tempt the most grounded investor to make impulsive investment choices. That is why maintaining an investment policy statement that reflects your long-term horizon is essential. Such a statement should reflect your current investment expectations as well as address the tax consequences of your portfolio.
For instance, many investors tend to hold on to a stock because of a low basis without evaluating what it may be costing them in missed opportunities (i.e., building a more diversified portfolio). Alternatively, investors need to be mindful of the tax cost associated with buying and selling securities. Tax efficiency is important in asset preservation, so speak to your tax advisor now about your 2016 strategy, particularly if you plan to rebalance your portfolio.
**Transferring Assets**
[](https://indfin.com/common-misconceptions-about-the-unlimited-marital-deduction/senior-couple-meeting-with-agent/)Fotilla ImagesTo leave the legacy that you envision requires significant advance planning. Questions regarding how much you want to leave to loved ones, how long your bequest will last, and how much will be eroded by taxes are difficult to address. But planning converts uncertainty into real opportunities to make a difference.
When crafting your estate plan, be sure that documents are written to be flexible and easily adapted to changing circumstances. For instance, if balances on investment accounts decline, you may need to rethink — and restate — your intentions, perhaps even change beneficiary designations to reflect changing market dynamics.
**IFG Notes:**
[Not everyone agrees](https://indfin.com/time-to-rethink-401k)with conventional wisdom regarding the 401(k). There might be other options, particularly for those who areconcerned about future tax hikesand still have more than ten years before they begin drawing retirement income.
Don’t let procrastination get the better of your best-laid plans. Make 2016 the year you get serious about saving. Are you on track?
You can find some tools on the[IFG Resources website](https://tinyurl.com/IFGWorksheets), which is different from The IFG main site, which you can find [here.](https://indfin.com/)You might check-out the Home Page, too, for even more resources.
[](https://indfin.com/variable-annuities-have-you-looked-under-the-hood/6a017c332c5ecb970b01a5116fb332970c-320wi-3/)Jim Lorenzen CFP® AIF®[Let me know if I can be of help!](https://www.meetme.so/JimLorenzenCFP)
Jim
\*Employee Benefit Research Institute, 2015Retirement Confidence Survey, April 2015.2Asset allocation does not assure a profit or protect against a loss.
*Because of the possibility of human or mechanical error by Wealth Management Systems Inc. or its sources, neither Wealth Management Systems Inc. nor its sources guarantees the accuracy, adequacy, completeness or availability of any information and is not responsible for any errors or omissions or for the results obtained from the use of such information. In no event shall Wealth Management Systems Inc. be liable for any indirect, special or consequential damages in connection with subscriber’s or others’ use of the content.© 2016 Wealth Management Systems Inc. All rights reserved.*

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Estate, Retirement, Taxes
---
### [WOMEN STILL FACE FINANCIAL CHALLENGES](https://indfin.com/women-still-face-financial-challenges/)
**Published:** January 11, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/01/Female_Mgr_Responsible_Concern.jpg)iStock ImagesEven though women live longer than men, yet 80% take their Social Security at age 62 when it provides the least benefit! That choice also reduces their cost-of-living increases because they started with a smaller income. When you compound the lost income over a lifetime, it’s a bunch of bucks.
There’s a hidden whammy in there, too. It’s often the woman that becomes the irreplaceable caregiver. When they have children, many reduce their schedule and income resulting in fewer Social Security credits. They’re also the ones who often leave the workforce to care for disabled or elderly parents.
According to a recent study, women were found to be short of retirement goals to a much greater degree than men. The math indicates they need to save 26% more just to get even!
Maybe the question shouldn’t be whether you want to get rich. Maybe it should be whether you’d rather have a guarantee that you’d never be poor!
Much retirement planning is flawed. If you’d like to learn why, you might enjoy this webinar I created some time ago.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues, Retirement
---
### [Women May Be More Serious Than Men About Planning!](https://indfin.com/women-may-be-more-serious-than-men-about-planning/)
**Published:** January 15, 2013
**Author:** Jim Lorenzen
**Content:**
Could it be?
Apparently, according to the 2012 Fidelity Millionaire Outlook Study. They found a rather large gap between what women and men look for in planning their financial futures.
For example, according to the study, women were more than TWICE as likely as men to be interested in hollistic financial planning to meet a specific lifestyle or goal. Men, apparently, are more interested in investment return.
Not too surprising, really. The last time you were out with a group of people, wasn’t it usually the men talking about what stocks were doing well? Women never seem to talk about that. Their conversations tend to be more private… and about more serious issues.
The study also concluded that women were also more likely than men to seek financial advice. No surprise. Men never ask for directions.
The study had one other conclusion: Women also tended to be about TWICE as loyal than men as clients for advisors. Again, not surprising. Aren’t men the ones ‘chasing returns’ when women tend to be more serious long-term planners?
————-
Additional Resources:
[A Financial Coversation Checklist ](https://indfin.com/financial-conversation-checklist)for you and your spouse.
[Why Retirement Planning Often Fails](https://indfin.com/why-retirement-planning-can-often-fail)
——————–
*Jim Lorenzen is a Certified Financial Planner® and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of* [*The Independent Financial Group*](https://indfin.com/)*, a fee-only registered investment advisor with clients located in New York, Florida, and California. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
Additional IFG Links:
- Twitter; @JimLorenzen
- Jim’s MoneyBlog
- IFG on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp)
- IFG on [Facebook](https://www.facebook.com/IFGAdvisory)
*IFG does not sell products, earn commissions, or accept any third-party compensation or incentives of any description.* IFG does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional. The Independent Financial Group does not sell financial products or securities and nothing contained herein is an offer or recommendation to purchase any security or the services of any person or organization.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Will YOUR Money Last?](https://indfin.com/will-your-money-last/)
**Published:** June 10, 2015
**Author:** Jim Lorenzen
**Content:**
Jim Lorenzen, CFP®, AIF®
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a3fd0c994a970b-320wi.jpg)When I first entered the advisory business in the early 1990s, financial entertainment television was a new phenomenon. All the tv gurus were being interviewed regularly and talking heads discussed which funds were likely to do best in the coming months.
The ‘baby-boomers’ were in the accumulation mode and the mantra was “buy term and invest the difference”. Few did it, though. They acquired their insurance through work and they invested as long as the market when up. When the inevitable market pull-backs occurred, they often got out and sat on the sidelines as professionals went in to grab the bargains.
The boomers are older now. Accumulation is no longer the priority; now, it’s safety – and many are avoiding the market altogether. Understandable, but problematic, when you consider that the stock market is THE all-time heavyweight champion of inflation hedges.
Inflation, of course, measures what things cost; and the market is comprised of all those companies that sell all those things to us. Those dots are easy to connect, even for me.
**Storm Clouds are Gathering**
Many people may be blindsided, according to retirement expert Ed Slott, who also happens to be a CPA, and David M. Walker, former U.S. Comptroller General. As they point out along with author David McKnight in “The Power of Zero”, the bottom line is this: The Government is in debt and needs money. Most Americans will once again be caught on the wrong end when the dog wags his tail.\\
Demographics and realities tell the story:
- The boomers were accumulating and Uncle Sam convinced them to put money into their 401(k)s, IRAs, and other tax-deferred accounts. They avoided taxes on the ‘seed’ so Uncle Sam could reap the harvest. If tax rates never change, no problem; but, with a license to spend, higher taxes seem bound to follow.
- The Government has been running up debt. Just 7 years ago, the 219-years of accumulated national debt totalled $9 trillion. Now, it’s over $18 trillion – doubling in 7 years – and there’s more: The government counts *only the current year’s outlay* as debt, not the total outstanding obligations. Don’t you wish *you* could do that?
- The boomers will begin drawing on their now-taxable retirement accounts just when Uncle Sam will need more revenue to fund federal obligations. It has to come from somewhere. Successful people are the ones in the cross-hairs.
- Uncle Sam is a partner in every boomer’s retirement plan – a partner with the SOLE vote on how much of the plan he gets to take to fund his promises. The boomer-partner has no vote. A boomer with a $500,000 IRA might have $125,000 in embedded taxes today and could have $250,000 or more in embedded taxes tomorrow – no one knows, but Uncle Sam has the only vote.
So, for many boomers, the issue of longevity risk is very real; and particularly so for their spouses as boomers wrestle with making sure they’re provided for if something should happen to them.
It’s something I’ve witnessed in my own family. My dad died at 94, but my mom lived to age 99… a full eight years after my dad passed away… and she needed full-time care the entire time he was no longer around.
**Industry Responses**
[](https://indfin.com/wp-content/uploads/2015/10/daycare_preschool_kids.jpg)Picture from my first industry conferenceWhen I attended industry conferences in the early days, all the sessions seemed to be about “adding alpha” (manager value-added) and the efficient frontier (risk mitigation).
Today, increasingly, conferences, webinars, and trade publications are addressing the issue of longevity risk and sustainable withdrawal rates. The academics are running models with back-testing to aid planners and others who serve clients facing these real-world issues.
Traditionally, most advisors counseled clients to use the 4% rule: Maintain an optimized portfolio mix and withdraw 4% of your initial balance annually, taking cost of living increases each year the market experiences a gain.
The April 2015 issue of the *Journal of Financial Planning*[\[1\]](#_ftn1) featured an in-depth study by Wade Pfau, Ph.D, CFA, addressing this issue testing three different strategies:
1. The SPIA strategy: Buy a joint/100% survivor’s life-only single premium immediate annuity.
2. Buy a ladder of bonds maturing over the next 30 years.
3. Buy a ladder of bonds maturing over the next 20 years and purchase a deferred income annuity (DIA) that will continue the same income level and trend in years 21 and beyond.
Dr. Pfau detailed how eachstrategy had its own advantages and disadvantages, as one would expect since we’ve never seen anything that’s perfect. For example,
\#1 sacrifices some liquidity but also eliminates both market and longevity risk.
\#2 can provide inflation protection by laddering TIPS (Treasury inflation-protected securities), however there is no longevity risk protection beyond 30 years.
\#3 is actually fairly attractive and seems to provide the highest sustainable withdrawal rate, despite giving up liquidity on about 25% of assets; but, the trade-off is still inflation risk since no company currently offers a DIA that provides inflation protection for the initial payout made in the future. The planner would have to do some ‘reverse engineering’ to come up with an estimate of what funding would be required to provide an inflation-adjusted initial payment. The downside is that it might require funding at a level requiring less liquidity than desired or an inaccurate result.
The models I’ve seen in this and other studies would suggest that sustainable withdrawal rates must inherently be conservative to allow for the spending rate to work. While the three strategies above may support spending rates between 3.65-4.03% in the back-tested models cited, sustainable spending rates for those not willing to give up liquidity, i.e., in traditional investment portfolio, are more likely to be in the 2.35%-3.51% range, the latter being considered aggressive.
While there are a number of sophisticated strategies available to individual investors, they often require abandoning long-held, well-ingrained beliefs in order to achieve the long-term goals that matter.
Jim
If you’d like to view my 30-minute webinar, *Why Most Retirement Planning Will Probably Fail*, you can do so[ here](https://attendee.gotowebinar.com/recording/3582652353068760321); our you can go here for more information.
[\[1\]](#_ftnref1) *The Costs of Retirement with Different Income Tools*, Wade Pfau, Ph.D., CFA, professor of retirement income at The American College. Published by the Financial Planning Association.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
---
### [Will You Work Past Full Retirement Age?](https://indfin.com/will-you-work-past-full-retirement-age/)
**Published:** March 27, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a3fcd21456970b-320wi.jpg)**The Great Recession has many older Americans considering the prospects of staying in the workforce past their normal retirement again. But, working past your normal retirement age is not a new phenomenon.**
The Great Recession has many older Americans considering the prospects of staying in the workforce past their normal retirement; but working past your normal retirement age is not a new necessity.
According to the Social Security Administration, more than 30% of individuals between the ages of 70 and 74 reported income from earnings in 2010, the latest year data are available. Among a younger age group, those between 65 and 69, nearly 49% had income from a job.1
Some remain employed for personal reasons, such as a desire for stimulation and social contact; others still want a regular paycheck. Whatever the reason, the decision to continue working into your senior years could potentially have a positive impact on your financial future.
Working later in life may permit you to continue adding to your retirement savings and delay making withdrawals. For example, if you earn enough to forgo Social Security benefits until after your full retirement age, your eventual benefit will increase by between 5.5% and 8% per year for each year that you wait, depending on the year of your birth. You can determine your full retirement age at the Social Security Web site or by calling the Social Security Administration at1-800-772-1213.
**Adding to Your Nest Egg**
Depending on the circumstances of your career, working could also enable you to continue adding to your retirement nest egg. If you have access to an employer-sponsored retirement plan, you may be able to make contributions and continue building retirement assets. If not, consider whether you can fund an IRA. Just remember that after age 70 1/2, you will be required to make withdrawals, known as required minimum distributions (RMDs), from traditional 401(k)s and traditional IRAs. RMDs are not required from Roth IRAs and Roth 401(k)s.
Even if you do not have access to a retirement account, continuing to earn income may help you to delay tapping your personal assets for living expenses, which could help your portfolio last longer in the years to come. Whatever your decision, be sure to apply for Medicare at age 65. In certain circumstances, medical insurance might cost more if you delay your application.
Work doesn’t have to be a chore. You may find opportunities to work part time, on a seasonal basis, or capitalize on a personal interest that you didn’t have time to pursue earlier in life.
*1Source: Social Security Administration,Income of the Population 55 or Older, 2010,March 2012 (latest available).*
*Because of the possibility of human or mechanical error by Wealth Management Systems Inc. or its sources, neither Wealth Management Systems Inc. nor its sources guarantees the accuracy, adequacy, completeness or availability of any information and is not responsible for any errors or omissions or for the results obtained from the use of such information. In no event shall Wealth Management Systems Inc. be liable for any indirect, special or consequential damages in connection with subscriber’s or others’ use of the content. © 2014 Wealth Management Systems Inc. All rights reserved*.
**Resist Emotional Decision-Making**
It pays to have a plan; but, to get one you need a proven process.
First, sit down with your spouse and have a talk. You might find [this checklist](https://indfin.com/financial-conversation-checklist) helpful. Need some educational input? Take a look at these free [Life Guides](https://tinyurl.com/IFGLifeGuides) and [worksheets](https://tinyurl.com/IFGWorksheets).
And, don’t forget Social Security planning. The wrong claiming strategy could conceivably cost hundreds of thousands of dollars! You can learn more on the IFG [Social Security Strategies website](https://tinyurl.com/SocialSecurityStrategies).
Of course, you [can talk with me](https://tinyurl.com/IFGIntroCall).
Enjoy!
Jim
***ADDITIONAL RESOURCES:***
**Arrange a brief15-minute introductiory phone call with Jim Lorenzen, CFP®, AIF®** [**here**](https://tinyurl.com/IFGIntroCall)**.**
**Social Security** – The wrong claiming strategy could conceivably cost hundreds of thousands of dollars! Knowledge is more than power; it’s real money. You can learn how to [get to the right strategy](https://tinyurl.com/SocialSecurityStrategies) with the right planning.
**College Planning and Funding Strategies** – Just like with the airlines, there are often two prices people pay for the same education: The price paid by the informed and the price paid by the uninformed. What are the projected four-year costs for the college your student desires? How much scholarship money will your student qualify for? You can see a short video, *“A Lesson in Paying for College”,* and download a free report, “*Insider Strategies and Secrets to Reducing your College Costs.”* You can learn more on the [IFG College Funding site](https://www.ifgcollegefunding.com/).
**Financial Planning and Investing:**
IFG Report: Understanding Mutual Funds
IFG Report: The Hidden Risk No One Talks About (Registration required)
Begin the discussion with your spouse with this [Financial Converstion Checklist](https://indfin.com/financial-conversation-checklist). (No registration required)
Facing financial decisions but feel you need to do some homework first? You might benefit from looking through our free [Life Guides](https://tinyurl.com/IFGLifeGuides) and using some [financial worksheets](https://tinyurl.com/IFGWorksheets)!
Visit the[IFG Website](https://indfin.com/)!
Follow Jim on Twitter: [@jimlorenzen](https://twitter.com/JimLorenzen) and also on [Jim’s MoneyBlog](https://www.jimsmoneyblog.com/)
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp)
IFG on [Facebook](https://www.facebook.com/IFGAdvisory)
Become an IFG client! [Schedule your 15-minute introductory phone call here](https://www.timetrade.com/book/F7ZPS)!
———————
Jim Lorenzen is a[ *CERTIFIED FINANCIAL PLANNER®*](https://en.wikipedia.org/wiki/Certified_Financial_Planner) professional and An Accredited Investment Fiduciary® in his 21st year of private practice.
The Independent Financial Group is a fee-only registered investment advisor with clients located across the U.S. He is also licensed for insurance as an independent agent under California license 0C00742.Jim can be reached at 805.265.5416 or (from outside California) at 800.257.6659.
**Interested in becoming an IFG client?** Why play phone-tag? You can easily [schedule your 15-minute introductoryphone call!](https://www.timetrade.com/book/F7ZPS)
The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Why Install an Executive Compensation Plan?](https://indfin.com/why-install-an-executive-compensation-plan/)
**Published:** January 21, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019b050bdff4970d-320wi.jpg)Simple. Quite often qualified plan contributions, even at the limits, will be inadequate to meet the retirement income needs of highly compensated employees.
Executives at companies with 401(k) plans actually often find they’re severely limited by plan limits as to how much they can contribute; and, that severely limits their ability to achieve the necessary levels of retirement income to continue their pre-retirement standard of living, even when coupled with Social Security.
For example, it’s not uncommon to find that a typical wage earner will achieve about 60-80% of final compensation from a combination of Social Security and qualified plan distributions. But, a highly-compensated executive (HCE) may only achieve retirement income of about 10-30% of final compensation.
**Will Your Top Executives Exercise “Free Agency”?**
It’s no secret: It can take years to find or develop the executive talent needed to build the business to the next level. Not only is executive talent is hard to come by, it is even more difficult to replace when it walks out the door.
What keeps a key executive? There are many reasons, of course; but, a strong monetary incentive package is likely a bedrock requirement. People tend to stay where they feel appreciated and appropriately rewarded. Structured incentive plans can help keep key executives in place and motivate them to higher levels of performance.
But non-qualified deferred compensation plans aren’t right for every business. There’s more to learn about executive compensation; and you canfind an introduction here.
Enjoy!
Jim
**RESOURCES:**
IFG Report:The Hidden Risk No One Talks About(registration required)
A Financial Conversation Checklist(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights)to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
The[Joint Committee on Taxation](https://www.jct.gov/resources.html)
**Become an IFG client!**Don’t play phone-tag; schedule your 15-minute introductory phone call using[this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,****a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### ["When the Market Goes Up, You Make Money! When the market goes down, you don't lose!"](https://indfin.com/when-the-market-goes-up-you-make-money-when-the-market-goes-down-you-dont-lose/)
**Published:** October 9, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/09/Fotolia_5386670-DontSkipDetails.jpg)*Fotila Images*###### Jim Lorenzen, CFP®, AIF®
Sound familiar? If so, it’s because you saw all those television commercials selling safety to a frightened public. After all, all those daily market gyrations are scary to an aging boomer population who’ve spent most of their adult lives getting their financial education from television gurus, talking heads, and financial (entertainment) magazines.
When in doubt, hide. Buy gold, buy silver, buy guarantees! Maybe all risk will go away. Maybe. Maybe not.
Being conservative when inflation and interest rates have nowhere to go but up is probably a smart idea. The question is, where does conservative leave off and ignorance take over?
What are those commercials really selling? Equity-indexed annuities (EIAs). Without getting to far into the weeds, EIAs are basically insurance company IOUs. Your money is not invested in the stock market. It’s loaned to an insurance company. The insurance company puts the money in its general account and invests in a conservative portfolio, made-up mostly of bonds.
How do they tie returns to the stock market when the company has invested in bonds? You can getmy 3-1/2 page report here!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
**Tags:** Retirement Income, Retirement Planning, Retirement Strategy
---
### [Variable Annuities - Have You Looked "Under the Hood"?](https://indfin.com/variable-annuities-have-you-looked-under-the-hood/)
**Published:** November 26, 2013
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi2.jpg)Investors often purchase annuities without really understanding what they bought, usually because the sometimes over-hyped guarantees sound so good their eyes tend to glaze over.
Variable annuities differ from fixed annuities in that assets are invested in mutual funds.
Think of a Reese’s cup. Peanut butter inside are the mutual funds; the chocolate coating is the insurance wrapper… which brings up the point: There are some differences from investing in mutual funds directly:
- Investments grow tax deferred – the insurance wrapper buys tax-deferral
- There is a death benefit which typically protects what you’ve put in
- You can elect periodic payments for the rest of your life at retirement – or the life of your spouse, which helps protect against longevity risk.
I won’t go into the nuts and bolts here; the SEC offers an[excellent overview](https://www.sec.gov/investor/pubs/varannty.htm "SEC Overview of Variable Annuities")of variable annuities and you can access it here.
But, here are a few things you should know.
While variable annuities do allow assets to grow tax-deferred, that deferral feature comes at a price – and it can be a rather stiff one. That insurance wrapper, according to the SEC, can typically be around 1.25%… and this is in addition to the mutual fund charges, some of which are well-hidden. You can learn more about what you need to know about mutual funds here.
There are also administrative fees. While these fees can be small, they should be flat fees, not percentage fees; after all, if it costs $X to process a transaction, why should the cost of processing increase just because your account balance increased?
There are also add-on charges for any riders you elect. When added to the underlying fund expenses, it can look something like this:
**Typical Annual Fees for Variable Annuities:**
Mortality and Expense Risk (insurance wrapper)1.25%1Administrative Fees0.15%2Optional Guaranteed Minimum Death Benefit Rider0.61%2Optional Guaranteed Lifetime Withdrawal Benefit Rider1.03%2Fund Expenses for Underlying Funds in Variable Annuity0.94%2**Total Cost** **3.98%** *1Securites and Exchange commission,[Variable Annuities: What you should know.](https://www.sec.gov/investor/pubs/varannty.htm "SEC Overview of Variable Annuities")*
*2Insured Retirement Institute, 2011 IRI Fact Book (Washington, DC: IRI, 2011), 36-38, 56.*
However, as I mentioned, mutual funds have additional hidden expenses beyond the quoted annual expense ratio we’re all familiar with. When you factor those in – and our report will explain how you can come up with a reasonable estimate for yours – you’ll see something pretty clearly: It may take a lot of years of tax deferral to “buy back” all the costs you’ve accumulated in your variable annuity.
Nevertheless, variable annuities can be worthwhile for the right investor who is already maxing-out more traditional retirement options, i.e., 401(k)s, IRAs, etc. They key, of course, is to buy smart.
If your advisor is a Registered Investment Advisor, chances are good s/he can help you select a quality no-load3variable annuity that uses low-cost funds and has fixed-dollar admin fees.
Remember, no one can control the markets; but we can try to control costs and taxes.
Jim
3Surrender charges generally occur when a company has to recoup commissions advanced to the salesperson. No-load generally means no commissions and therefore no surrender charges.
—-
RESOURCES:
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk)(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist)(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights)to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,****a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Top College Planning and Funding Mistakes](https://indfin.com/top-college-planning-and-funding-mistakes/)
**Published:** April 10, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5118d6207970c-320wi1.jpg)**Did you know it’s possible for a grandparent to gift $10,000 to a grandchild for a college education and end up costing the family up to $7,000 in financial aid? That’s a lot of money to pay for a $3,000 benefit.**
**Did you know how some wealthy families end-up paying a lot less for college than the rest of us?**
Many, if not most, people make numerous mistakes when it comes to planning for college.
- **They assume they won’t qualify for aid** – often untrue, even for people making $175K a year.
- **Waiting until the last minute** – rushing often leads to costly mistakes.
- **Applying to colleges they like,** based on rankings, without considering ‘best fit’
- **Picking the wrong schools** – often limits the opportunity for merit money. I’ve heard the divorce rate in the U.S. is around 50%. College choices are often made emotionally, as well.
- **Assuming all aid is the same** – the fact is some schools are better endowed than others, which means not all aid is equal. A $60K school may actually be a better choice than a $40K school!
- **Not understanding the aid formulas** – knowing what’s included and what isn’t in qualifying for federal aid can make a huge difference in how much comes out of pocket. How your assets are arranged is important.
- **Not applying for aid at all** – probably the #1 mistake – parents should file forms no matter what. If you don’t file, the college may feel there’s no need for merit money. Even if you have a high income and substantial assets, filing the forms will show the college your ability to pay, and discounts to those who can demonstrate payment ability are not uncommon. The forms are actually the ‘means’ to the best deal. In fact, many merit scholarships actually require financial aid forms.
- **Responding to college offers too soon** – knowing how to leverage offers to achieve additional merit money or discounts can result in substantial savings (note: the IFG/CFS Client Care Center has deep experience in evaluating offers, as well as leveraging them).
- **Forgoing professional help** – My dad once told me, “Some people know the cost of everything and the value ofprofessional help nothing.” Mistakes are usually more costly than doing it right the first time.
IFG has partnered with Collegiate Funding Solutions (CFS) to help clients receive independent, objective help navigating the college funding and admissions maze. You can learn more about it on the [IFGCollegeFunding website. ](https://www.ifgcollegefunding.com/)There, you can:
- Download a free and informative report, *“Insider Strategies and Secrets to Reducing Your College Costs”*
- See a short video, *““A Lesson in Paying for College”.*
- Learn how much scholarship money your student qualifies for;
- Subscribe to the CFS award-winning e-newsletter and stay informed about important college planning, funding, and admissions information
- See college-specific projected four-year costs – for virtually any college your student(s) wish to attend
- Arrange to receive a quick diagnosis of your specific situation – a valuable and important step to getting it right.
- There’s even a college planning primer on the planning and financial aid landscape.
If you have a high school student wondering about navigating the maze, even as you’re wondering how you can make it happen financially without jeopardizing your retirement or amassing a huge debt, there’s little time to waste.
Jim
***ADDITIONAL RESOURCES:***
**College Planning and Funding Strategies** – Just like with the airlines, there are often two prices people pay for the same education: The price paid by the informed and the price paid by the uninformed. What are the projected four-year costs for the college your student desires? How much scholarship money will your student qualify for? You can see a short video, *“A Lesson in Paying for College”,* and download a free report, “*Insider Strategies and Secrets to Reducing your College Costs.”* You can learn more on the [IFG College Funding site](https://www.ifgcollegefunding.com/).
**Retirement Income Planning**– The wrong Social Security claiming strategy could conceivably cost hundreds of thousands of dollars and have a dramatic impact on your other retirement assets! Knowledge is more than power; it’s real money. You can learn how to [get to the right strategy](https://tinyurl.com/SocialSecurityStrategies) with the right planning.
**Arrange a brief15-minute introductory phone call with Jim Lorenzen, CFP®, AIF®** [**here**](https://tinyurl.com/IFGIntroCall)**.**
**Financial Planning and Investing:**
IFG Report: Understanding Mutual Funds
IFG Report: The Hidden Risk No One Talks About (Registration required)
Begin the discussion with your spouse with this [Financial Converstion Checklist](https://indfin.com/financial-conversation-checklist). (No registration required)
Facing financial decisions but feel you need to do some homework first? You might benefit from looking through our free [Life Guides](https://tinyurl.com/IFGLifeGuides) and using some [financial worksheets](https://tinyurl.com/IFGWorksheets)!
Visit the[IFG Website](https://indfin.com/)!
Follow Jim on Twitter: [@jimlorenzen](https://twitter.com/JimLorenzen)and also [Jim’s MoneyBlog](https://www.jimsmoneyblog.com/)
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp)
IFG on [Facebook](https://www.facebook.com/IFGAdvisory)
Become an IFG client! [Schedule your 15-minute introductory phone call here](https://www.timetrade.com/book/F7ZPS)!
———————
Jim Lorenzen is a[ *CERTIFIED FINANCIAL PLANNER®*](https://en.wikipedia.org/wiki/Certified_Financial_Planner) professional and An Accredited Investment Fiduciary® in his 21st year of private practice.
The Independent Financial Group is a fee-only registered investment advisor with clients located across the U.S. He is also licensed for insurance as an independent agent under California license 0C00742.Jim can be reached at 805.265.5416 or (from outside California) at 800.257.6659.
**Interested in becoming an IFG client?** Why play phone-tag? You can easily [schedule your 15-minute introductoryphone call!](https://www.timetrade.com/book/F7ZPS)
The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [To Roth or Not to Roth - Should You Do a Conversion?](https://indfin.com/to-roth-or-not-to-roth-should-you-do-a-conversion/)
**Published:** July 8, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi1.jpg)
**Jim Lorenzen, CFP®, AIF®**
Steven Elwell, a CFP® practitioner in Amherst, NY recently wrote a nice piece for NerdWallet on this subject.
In his piece, he mentions five situations that might suggest a conversion would be a good move:
1. You are in a low tax bracket
2. You don’t need the money and plan to leave it to your kids
3. When your investments are down (did you do it in 2008?)
4. When you believe tax rates will go up
5. You want to reduce the value of your estate for income tax purposes.
If you’d like to read Steve’s article, you can access it here.
The points worth noting in particular – my own opinion – are #1 and #4.
Tax brackets are historically low. There was once a time when the highest marginal bracket was 90% before the early 60’s, when President Kennedy began to initiate cuts. As you can see from the chart below, the general trend has been down for some time, although it’s also worth noting a lot of deductions have disappeared along the way.

While top marginal tax rates have declined, it’s also true that the Government is still spending your money – usually favoring whatever groups will help them get re-elected – I know, I’m a cynic. Nevertheless, as I take great pains to avoid any mention of Greece, the government keeps spending. While those in office take pains to point out the annual deficits have been in decline, the fact is those deficits still add to the existing debt.
There is a difference between the reported national debt and the REAL debt. The reported national debt is now over $18 trillion; but the real debt is very different.

The government engages in different accounting than the rest of us. If you purchase a car with nothing down, for example, you would have to list the entire outstanding balance as debt on your balance sheet. Not so with the government; only the current year’s payments are counted as debt. Result: While the government reports $18 trillion, Townhall.com estimated the debt at $87 trillion – and that was in 2012!
Not long ago I did a webinar entitled*How To Plan for an Income Tax-Free Retirement.* A number of those who attended, and a few who couldn’t make it, have asked me if I had a written report they could download. I’ve created an updated version outliining this strategy, which is really most worthwhile for those who are successful and most likely between ages 35-55. Those between 55 and 60 may still benefit. You can learn more here.
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Life Insurance, Retirement, Uncategorized
---
### [The Insurance Illustration Landscape is changing](https://indfin.com/the-insurance-illustration-landscape-is-changing/)
**Published:** February 22, 2016
**Author:** Jim Lorenzen
**Content:**
**Should You Believe Insurance Company Illustrations?**
[](https://indfin.com/the-investment-philosophy/symbolbild-zahlen/)*Fotila Images***Jim Lorenzen, CFP®, AIF®**
Just in case you haven’t heard, Genworth has decided to suspend life insurance and annuity sales. This decision will leave many agents and their client with questions on where to turn and how to get protected.
Insurance companies seldom discontinue a business segment when it’s either profitable or if they haven’t overextended themselves. Remember Executive Life?
Before Executive Life of New York went under, they had over 50% of their portfolio invested in less than investment grade ‘junk’ bonds, despite the fact that in June 1987, the New York legislature had mandated that insurance companies licensed to business in that state were to limit their general portfolios to no more than a 20% allocation to such bonds. Remember, there are no guarantees; there are only guarantors. *\[Source: The New Insurance Investment Advisor, Ben G. Baldwin, McGraw-Hill 2002, p. 37.\].*
A qualified advisor would/should have looked “under the hood” at the company’s investment asset allocation and quickly realized it wouldn’t be used in a client’s portfolio; so, why would anyone use it to back their retirement or legacy planning? Unfortunately, as all too often happens, insurance companies can take ill-advised risk in order to promote unrealistic return rates to pump-up sales.
Life insurance illustrations have had, for more years than I can count, a well-deserved reputation for less than transparent and amazingly inaccurate projections of what the policyholder could expect in future years. The unfortunate result is that one of the most amazing financial products on earth – and life insurance does far more than most people even suspect – has suffered from a plethora of negative bias, both in and outside the media universe, and virtually all of it wrong.
**A regulatory solution?**
A recent regulatory change recently took affect that limits the growth rate an insurance company can use in its illustrations to a maximum that’s based on the company’s current ‘cap’ rate applied to an average rate history going back over 50 years. The key is that the company can use its *current* cap – which actually can function as an incentive to keep the caps high, maybe even unrealistically.
This could mean – and what many unsuspecting consumers may not realize – that it may also act as an incentive to take on additional risk in the company’s underlying general account investment portfolio. Insurance company actuaries are good at manipulating numerous ‘moving parts’ that can make attractive caps look better than they really are. Does a company offering a 13% cap on an indexed product really perform better than one offering only a 10% cap? According to some extensive back-testing I’ve seen, it doesn’t seem to be the case – expenses often play a more important role
One major problem for the typical insurance consumer is the inability to tell one company from another. While many truly professional and credentialed independent agents do make an effort to represent only “investment-grade” companies, there are those who will represent the highest commission, which can often lead to selling substandard products for companies that appear to be substantial. An agent who is also an investment advisor can be a benefit for the buyer.
**[](https://indfin.com/a-market-high-should-you-jump-in/6a017c332c5ecb970b017c384ba1fa970b-320wi/)What many don’t know**
Most of the well-known rating agencies you may be familiar with are actually paid by the insurance companies they rate! Little wonder many insurance companies that failed actually had good ratings when they went under.
Have you noticed that virtually all insurance companies tout ratings from the same rating agencies in their promotional materials? Few, if any, however, tout their rating from Weiss, maybe because Weiss doesn’t get paid by the companies they rate – their revenues come solely from subscriber revenue (kind of like *Consumer Reports*).
For example, according to the September 2002 Insurance Forum, of 1221 life and health companies rated by Weiss, only 3.9% of companies made it into the ‘A’ category. Compare that with the 54.9% rated ‘A’ by Standard and Poor’s. At Moody’s, 90% of their list made it to ‘A’ that year. A.M. Best gave ‘A’ to 56.3% of the companies they rated. *\[Source: The New Insurance Investment Advisor, Ben G. Baldwin, McGraw-Hill 2002, p. 405.\].*
By the way, Companies with ratings in the A or B brackets from Weiss are considered secure, while some of the other rating agencies will give B and even A bracket ratings to companies considered vulnerable.
Recently, indexed universal life (IUL) policies have become quite popular – both among agents and their clients. The reasons are many, but two big attractions are (1) transparency – virtually no hidden moving parts. These products are easy to understand; and (2) low cost – insurance costs are basically like term policies. Admin costs are also low and, as noted, everything, including costs, is transparent, including performance going forward.
Does that mean the illustrations can be believed? No, but for different reasons. To understand the reasons why illustrations can be misleading and how to know you’re comparing apples with apples, it’s important to know how these policies work.
First a caveat: This is not an exhaustive text on IUL products and there’s a lot more to know than is being discussed here. This is simply a quick overview highlighting the stand-out characteristics.
**[](https://indfin.com/a-quick-estate-planning-checklist/6a017c332c5ecb970b01901bb7b3ed970b-320wi/)IUL basics**
IULs are often, but not always, designed as financial tools for maximum cash accumulation in a tax-advantaged vehicle. In these cases, the death benefit is often a secondary consideration; however, it’s the life insurance that buys the tax benefits – and, for many, these benefits far outweigh the cost of insurance, which is typically priced like term insurance.
Unlike most insurance buyers who want the most insurance for the least amount of money, these buyers want to buy the minimum amount of insurance for the maximum amount of premium they can put in (yes, there’s a limit). This is because after the minimum insurance is purchased and expenses are covered, the rest goes into a cash accumulation account; and in an IUL, it can be tied to an index with much higher caps than are usually available in an annuity.
The cash accumulation account accumulates tax-deferred, but can be accessed for retirement income later as tax-free loans. How fast does the cash accumulate? Interest is credited to the account based on the performance of an outside index. While there are often many choices, most people tend to choose the S&P 500 index.
To keep this simple, I’ll just quickly cover the simplest approach: Let’s suppose our policyholder purchased an IUL policy using the S&P 500 index as the crediting option. The policy might offer 100% participation in the index’s upside moves up to a ‘cap’ during a crediting period, typically one year. For example, if the index rises 8% by the policy’s 1-year anniversary date, the policyholder participates 100% in that move and receives the full 8%, provided the ‘cap’ is higher. If the index rose by 25% and the policy ‘cap’ was 11%, the policyholder would realize a credit of 11%.
So, on a 1-year, 100% participation with a 11% cap, a 25% rise in the index means the policyholder would receive 11%, i.e., 100% of the increase up to the cap. That amount would be credited on the policy’s anniversary date
The next crediting would take place on the policyholder’s second anniversary. Note: It doesn’t matter what happens between anniversaries – only the value ON the anniversary date counts, nothing else.
The good news is that if the stock market index has a drop, the policy loses nothing. The amount credited is 0. No gain, but no loss, either. Another nice thing is that, in our example above, after the 12% gain is achieved, it’s locked-in. That’s the new floor and that money can’t be lost.
To understand how beneficial a ‘no-loss’ concept is, it’s worth remembering that while a drop from 100 to 80 represents a 20% loss, to get back to 100 from 80 requires a 25% gain (20 points up from 80 is 20/80 = 25%).
How can the insurance company, investing in a conservative bond portfolio do this? It’s simple. Again, I’ll oversimplify with rounded numbers just to make the concept easier. Premium money received by the insurance company might be invested 95% in bonds, and 5% in stock options. If the market goes down, the options expire; if the market goes up, they execute the options and, of course, the cap on the policy limits their exposure. So, the pricing of options, as well as the length, impact costs.
Important: The policyholder is not invested in the market or the options. The index is only a ‘ruler’ to measure how much the insurance company will credit. It’s the insurance company’s investment account that is doing the investing, not the policyholder.
**Returns and Illustrations**
Can the policyholder really receive stock market-like returns? Not likely. The caps limit the upside, and while there is no downside, down years representing no gain will sometimes occur. So, positioning IULs as a stock substitute is probably not the best strategy. I would look for returns that are more bond-like – maybe a little better – which means, it’s the bond portion of your portfolio that you’re really dealing with.
And, here’s where illustrations can be a bit misleading.
If one company is offering a 12% cap and another company is offering an 11% cap, but both are showing you an illustration using a 7% crediting rate, saying that the S&P average over all their back-tested periods indicates that 7% is conservative, are you really seeing an apples-to-apples comparison?
Now that new regulations limit the cap that can be illustrated – remember, however, it’s based on the ‘current’ cap rates for each company applied to historical data, placing an incentive for the company to keep current rates high – it’s probably better to simply ‘level the playing field’.
First, the company: How have they treated policyholders in the past when they’ve reduced or increased their caps? Did existing policyholders receive the same treatment as new policyholders? Believe it or not, not all insurance companies treat their existing policyholders the way they treat their new ones.
Secondly, a decrease in a cap rate isn’t all bad. Responsible insurers are custodians for client assets and need to act responsibly, rather than chase risky investments to meet caps they can’t pay. However, a decrease in the cap also can affect your outcome.
Take a look at the chart below. Noticea 7% illustrated rate for a 12% cap IUL has had a 79.5% chance historically of meeting its projections, based on a 20-year probability study of the S&P 500 at various cap and crediting rates. If the cap is 11%, the probability is reduced to 60.7%.
[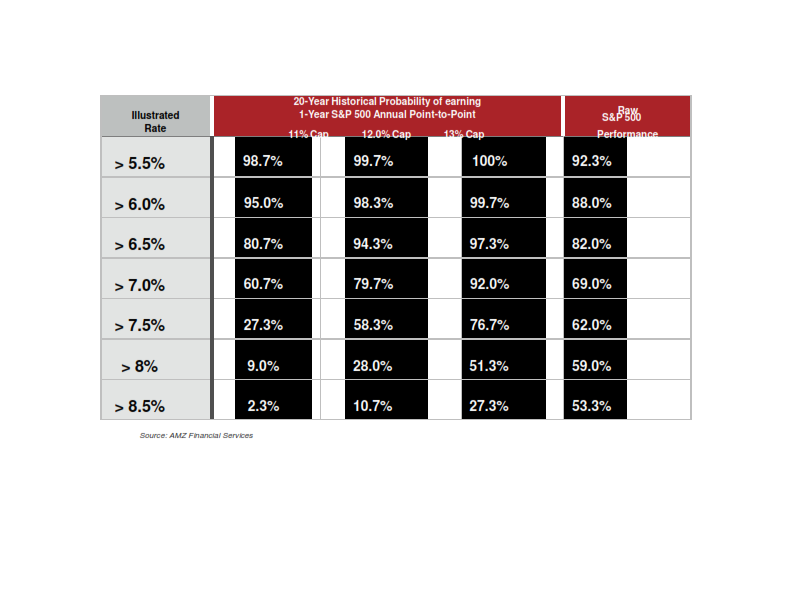](https://indfin.com/hiddeninsurancesecrets/iul-crediting-rates_001/)
The new regulations stress average results; but, it provides little comfort to know that your own retirement results have a 50-50 chance of being better or worse.
This has less to do with the insurance company than it does with expectations. It’s important to know, when you’re buying, what you can reasonably expect; and, often, it may not be what you’ve been promised with a rosy illustration. High quality companies providing investment-grade products will tend to be conservative in their projections – and a good advisor will educate clients on realistic outcomes.
Key Point: An illustration for a policy with an 11% cap but using only a 6% crediting rate may not look as rosy as the 7% illustration, but the odds of the company delivering on its promise rises to 95%. This means, it’s virtually certain your policy will perform this well or better. The 7% illustration will look so much better at the point of sale, but it also has almost a 40% probability of doing worse than promised.
So, when comparing companies, wouldn’t it make more sense to have them all illustrated at 6%? By doing so, you could see how they perform on a level playing field with a higher success probability. You can compare high probability outcomes and, more importantly, a basis for comparing costs, as long as the policies being compared have the same features, riders, etc.
**The Real Benefits**
If someone begins utilizing these benefits early, say in their 40s or 50s, the retirement benefits can be substantial. As a matter of fact, it’s a retirement strategy being used by 85% of Fortune 500 CEOs and many members of Congress in order to create a tax-free retirement. Other proponents of this strategy include retirement and IRA expert Ed Slott, who is also a CPA, and David M. Walker, former US Comptroller General *\[Source: The Power of Zero, David McKnight\].*
I’ve created a report on this concept. You might find it interesting. You’ll receive it free by going here. If you’d rather take the time (about an hour) and view the webinar with all the slides, you can do that here.
Enjoy!.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues, Life Insurance, Retirement, Taxes
---
### [RMD’s: A Quick 4-Tip Checklist for Baby Boomers](https://indfin.com/rmds-a-quick-4-tip-checklist-for-baby-boomers-2/)
**Published:** June 15, 2016
**Author:** Jim Lorenzen
**Content:**

**James Lorenzen, CFP®, AIF®**
Remember the 1990s? That was when every business channel had multiple programs with business gurus picking and ranking mutual funds. It was a time when many mutual fund managers were becoming the ‘rock stars’ of financial meda. Everyone wanted to know what Peter Lynch, Bill Gross, and others were buying, selling, and saying.
If you were one of those following all those shows back then, you were no doubt thinking about your financial future. And, if you were born in the years following 1946, chances are you’re a ‘baby boomer’ – a term we’re all familiar with by now.
I read somewhere that there are 65,000 boomers turning age 65 every year! And, those turning 70-1/2 have hit a big landmark: It’s the year – actually it’s up until April 1st of the following year – Uncle Sam begins sticking his hand into your retirement account – after all, he is your partner; and, depending on your combined state and federal tax-bracket, his ownership share can be pretty significant, depending on the state you live in. Yes, that’s when you must begin taking required minimum distributions (RMDs).
**By the way, if you do wait until April 1st of the following year, you’ll have to take TWO distributions in that year** – one for the year you turned 70-1/2 and one for the current year. Naturally, taking two distributions could put you in a higher tax bracket; but, Uncle Sam won’t complain about that.
So, now that you’ve been advised of one trap that’s easy to fall into, what are some of the others? You might want to give these concerns some thought – worth discussing with your tax advisor, as well as your financial advisor.
1. **Not all retirement accounts are alike.**
- IRA withdrawals, other than Roth IRAs, must be taken by December 31st of each year – and it doesn’t matter if you’re working or not (don’t forget, there is a first year exemption as noted earlier).
- 401(k) and 403(b) withdrawals can be deferred past age 70-1/2 provided you’re still working, you don’t own more than 5% of the company, and your employer’s plan allows this.
- As noted, Roth IRAs have no RMD requirements. Important: If you’re in a Roth 401(k), those accounts are treated the same as other non-Roth accounts. The key here is to roll that balance into a Roth IRA where there will be no RMDs or taxation on withdrawals.
2. **Get the amount right!**The amount of your total RMD is based on the *total value of all of your IRA balances requiring an RMD as of December 31st of the prior year*. You can take your RMD from one account or split it any or all of the others. Important: This doesn’t apply to 401(k)s or other defined contribution (DC) plans… they have to be calculated separately and the appropriate withdrawals taken separately.
3. **Remember: It’s not all yours!**
You have a business partner in your 401(k), IRA, and/or any other tax-deferred plan: Uncle Sam owns part of your withdrawal. How much depends on your tax bracket – and he can change the rules without your consent any time he wants. Some partner. Chances are you will face either a full or partial tax, depending on how your IRA was funded – deductible or non-deductible contributions. Important: The onus is on you, not the IRS or your IRA custodian, to keep track of those numbers. Chances are your plan at work was funded with pretax money, making the entire RMD taxable at whatever your current rate is; and, as mentioned earlier, it’s possible your RMDs could put you in a higher tax bracket.
*Fotilla Images*It’s all about provisional income and what sources of income are counted. The amount that’s above the threshold for your standard deduction and personal exemptions are counted. By the way – here’s something few people think about: While municipal bond interest may be tax-free, it IS counted as provisional income, which could raise your overall taxes, including how much tax you will pay on Social Security income. I have a LifeGuideabout ***Retirement and Social Security*** available here. Also, be sure to talk to your tax advisor.
4. **Watch the calendar.**If you fail to take it by December 31st of each year – even if you make a miscalculation on the amount and withdraw too little – the IRS may hit you with an excise tax of up to 50% of the amount you should have withdrawn! Oh, yes, you still have to take the distribution and pay tax on it, too! There have been occasions when the IRS has waived this penalty – floods, pestilence, bad advice, etc.
Remember to talk with your tax advisor. I am not a CPA or an attorney; but, of course, these are issues that come up in retirement planning and wealth management quite often, so this can serve as a starting point in your discussions.
Jim
RESOURCES:
LifeGuide download: ***Retirement and Social Security***
***Thinking About Retirement*** + ***Retirement Priority Review*** > Download page
————–
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an Accredited Investment Fiduciary® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of **The Independent Financial Group**, a Registered Investment Advisor providing retirement planning and investment advisory services on a fee-only basis. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriately licensed professional. All images used in this communication are in public domain unless otherwise noted.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement, Taxes
**Tags:** Required Minimum Distributions, Retirement Income, Retirement Planning, Retirement Strategy, RMDs, Taxes in retirement
---
### [Econ. 101-Supply and Demand - and Longevity Credits](https://indfin.com/longevity-credits/)
**Published:** June 24, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi3.jpg)Jim Lorenzen CFP® AIF®Jim Lorenzen, CFP®, AIF®
**More and more boomers are beginning to approach retirement.**
No news there; but something’s been happening – and continues to happen – that can negatively impact people who waited hoping to get a better deal regarding their retirement income. It’s little wonder that so many retirement plans are in jeopardy.
You see, immediate income annuity sales totaled $9.7 billion last year – a 17% spike. My guess is, as the boomer retirement bubble really begins to hit, that number will be much higher.
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b0192ac851ba2970d-320wi.jpg)It’s Economics 101: Supply and Demand.** As more and more boomers purchase annuities to cover their basic expenses in retirement, this demand coupled with increasing life expectancies, will likely have a dramatic effect on payout rates for future purchasers.
According to an excellent article by Tom Henga, writing in the June issue of *Retirement* *Advisor,* a Society of Actuaries (SOA) committee released the final report of RP-2014 mortality tables in October and those tables reveal a consistent trend, which if it continues for the next 14 years, means in 2028 life expectancy might rise to 88.6 years for males aged 65, and 91.2 years for females the same age.
So what?
According to Mr. Henga, these updated mortality tables will require insurance companies to lower their payout rates in order to properly reflect longer life spans. His logic is easy to understand and the math isn’t hard to do.
The trend increasing life expectancies – along with the consumer demand for guaranteed income solutions – could very well result in annuity payout rates going from 14 percent to 10 percent, from 9 percent to 7 percent, and from 7 percent to 5 percent. It’s about longevity credits. As demand increases, something has to give.
People who’ve been avoiding annuities now because of today’s low interest rates may find themselves wishing later that they had understood the situation. As Mr. Henga points out, income annuities are not an interest-rate play; they’re a longevity credit play.
Most people have no idea how annuities work or why the insurance companies can provide such high cash flows in a low interest rate environment. The key is longevity credits, i.e., mortality credits. It’s what separates annuities from investments.
When new mortality tables reflect increased aging, chances are better than good that insurance company payout rates will be reduced because of the adjustment in mortality credits. And, chances are, due to the factors cited above, we may be seeing the highest longevity credits we may ever see the rest of our lives…. And many of these adjustments may very well occur in the next 12 months!
[](https://indfin.com/wp-content/uploads/2014/09/its-about-time.jpg)Longevity credits aren’t unlimited. It’s the life insurance on the books that provides the built-in hedge to lifetime annuity sales. As people live longer and the demand for credits increases, the pool of available credits decreases. Econ. 101: This will affect pricing of annuity products in the future.
Boomers, of course, are becoming more preoccupied with covering 100% of their non-discretionary, basic retirement needs, and using other investments to address inflation and discretionary spending. Those who secure their annuities earlier in their planning can lock-in these longevity credits early.
Tom Henga likens it to fishing in a fully-stocked pond, as opposed to a pond with a limited supply of fish.
Income annuities come in all shapes and sizes, of course, and the long list of insurance carriers selling them each offer a variety of designs, each with their own bells and whistles. They can be complex products; but, they can also have simple, easy to understand designs. It’s important, however, to avoid the tendency of grabbing the best-looking shiny thing that may have other problems embedded.
Annuities, as mentioned earlier, are gaining in importance however; and they may be worth a look now, more than ever, because of the Econ. 101 issues cited above.
Retirement planning can be a little tricky. In fact, I believe – and many experts agree with me – that most retirement plans will probably fail. I’ve even created a special report that explains why. I think you may find it interesting. You can access it here.
Hope it helps!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Retirement
---
### [Do You Have A Greedy Business Partner - Even if you don't own a business.](https://indfin.com/greedypartnerblog/)
**Published:** March 8, 2017
**Author:** Jim Lorenzen
**Content:**
**Jim Lorenzen, CFP®, AIF®**
**If you work, you have a business partner, even if you don’t own a business. And, this partner isn’t like most others.**
**[](https://indfin.com/wp-content/uploads/2017/03/i319_Do-You-Have-A-Greedy-Business-Partner_001.png)**The problem is your partner in the business of life gets to decide how much of your revenue he wants to take… and you have no vote. In fact, he can – and will – change his mind at any time at any time, including during your retirement years.
What can you do? You might find this special report helpful.
You can [access it here](https://indfin.com/greedypartner/).
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement, Taxes
**Tags:** Retirement Income, secure retirement, Tax-Free Retirement Income, Taxes in retirement
---
### [SEEKING OPTIMAL RETIREMENT INCOME](https://indfin.com/seeking-optimal-retirement-income/)
**Published:** February 12, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/all-about-ifg/business-concept/)*Fotilla Images****James Lorenzen, CFP®, AIF®***
For years we’ve heard about “The 4% Rule”. Of course, that’s when the markets seemed to be going up all the time. In recent years, due to low interest rates and increased market volatility introducing everyone to sequence-of-returns risk, – I even did a webinar on this topic – many advisors have dialed back the 4% withdrawal rate to 3.5%
**Testing with annuities**
A Journal paper in December 2001 by Mark Warshawsky and co-authors John Ameriks and Bob Veres introduced the use of immediate annuities into the retirement discussion. In his current contribution, Warschawsky examines the use of immediate annuities combined with a fixed withdrawal percentage from a total-return portfolio. The conclusions [\[1\]](#_ftn1) were:
- The 4% rule tends to fail when utilized for extended periods, i.e., 30 years, whereas immediate annuities provide continual cash flow, regardless of market or economic
- A 3.5% or less is often more appropriate than 4% (for obvious reasons).
- When incorporating an immediate annuity at age 70, the annual payout almost always exceeds the 4% rule and does not risk full income or running out of money – in essence it’s purchasing an unending cash flow that, testing shows, exceeds the 4% rate.
Immediate annuities offer many advantages, but they likely not suitable for those with impaired longevity, liquidity needs, and adequate pension income. If you like to learn more, you can access the Income Annuity Primer.
**Testing with insurance**
Wade Pfau, in a paper commissioned by OneAmerica, addresses this issue in three scenarios:
1. Investments combined with term life insurance
2. Investments, joint and 100% survivor annuity, and term insurance
3. Investments, single life annuity, and whole life insurance[\[2\]](#_ftn2)
He compared these three approaches for 35 year-old and 50 year-old couples. Without getting into the weeds, I just say his study found a “substantive evidence that an integrated approach with investments, whole life insurance, and income annuities provide more efficient retirement outcomes than relying on investments alone.” It’s not an either/or decision.
Withdrawal strategies vary beyond what’s been discussed here, of course, which is why professional help can be very important and the difference of even hundreds of thousands of dollars.
It pays to do your homework and have a good guide.
——————–
**Interested in becoming an IFG client?** Why play phone-tag? You can easily schedule your introductory call [right here](https://www.meetme.so/JimLorenzenCFP)!
[](#_ftnref1)
\[1\]*Journal of Financial Planning*, January 2016
\[2\] ibid
*Jim Lorenzen is a[*CERTIFIED FINANCIAL PLANNER®*](https://en.wikipedia.org/wiki/Certified_Financial_Planner)*professional and An Accredited Investment Fiduciary® serving private clients since 1991. Opinions expressed are those of the author and do not represent the opinions of IFG any IFG affiliate or associated entity.The Independent Financial Group is a fee-only registered investment advisor with clients located across the U.S. He is also licensed for insurance as an independent agent under California license 0C00742.Jim can be reached at 805.265.5416 or (from outside California) at 800.257.6659.The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.**
[](#_ftnref2)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Life Insurance, Retirement
---
### [Rollover Mistakes Could Be Irrevocable!](https://indfin.com/rollover-mistakes-could-be-irrevocable/)
**Published:** June 29, 2016
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019b00066606970c-320wi.jpg)Jim Lorenzen, CFP®, AIF®**
According to Cerulli Associates, rollovers from 401(k)s and other retirement plans will cause IRA assets to reach $12 trillion by 2020, and according to retirement expert, Ed Slott, CPA, fully 99% of advisors – never mind the general public; good luck – know next-to-nothing about the rollover/distribution side of the business.[\[1\]](#_ftn1)
It’s worth understanding that every time IRA or 401(k) money is touched, it’s a gamble for those who don’t know what they’re doing. Mr. Slott says it’s like an eggshell – he’s good at metaphors – break it, and it’s over. He’s right.
Few people realize that if they make a mistake on the rollover, they could lose the IRA entirely – and it’s irrevocable!
A number of years ago, I wrote a report, *Six Best and Worst IRA Rollover Decisions*, which is available on the IFG website. One of the mistakes I mentioned was in not recognizingthat some peoplemaybeshouldn’t do a rollover at all!
Why? First, you have to understand what a rollover is – as the well as the difference between a rollover and an custodian-to-custodian transfer. A rollover happens when money has been withdrawn from a 401(k) and deposited into an IRA. When that happens, the client is required to do the necessary withholding, pay the tax and wait for a refund the following year. A transfer of the account directly between custodians avoids that problem; but, there’s a potentially bigger one.
**Here’s an example scenario**: If a rollover has been previously rolled over in the past 12 months, the entire account now becomes taxable, and there’s no fix to correct the error. Someone with a $500,000 or $1 million (or any other size) IRA could be in for a big shock. Taxes will be due at their new rate – this withdrawal likely puts them in a new bracket – and the money left is no longer tax-deferred!
A direct transfer would have avoided this problem.
**Keep Up with New Rules**
A lot of seniors have CDs and IRAs at banks. Last year, you could do one rollover per year for each of your IRA accounts. No more. Now, the law is one rollover per year for ALL IRA accounts – and that includes Roth IRAs. Two rollovers means that one of them will be no good.
**Inherited IRAs**
Here’s where mistakes can, and do, happen far too often; because the rules are different – and stiffer.
Did you know a non-spouse beneficiary can NOT do a rollover? A child who inherits a parent’s IRA must be careful. Often , because the child wants to access the money right away, an attorney will sometimes put the child’s name on it. When that happens, that’s the end of the account. It just became a taxable distribution – check with your tax advisor. It should have been set up as a properly titled and inherited IRA. Putting the money into the beneficiary’s IRA is a terrible mistake.
**Beneficiary Designation**
Too often, problems happen because people fill-out the beneficiary forms and forget them – never reviewing them. Failure to do this only puts off the day when siblings get “lawyered-up” because the investor didn’t understand the true meaning of the distribution designations.
There’s more to know, of course; but, hopefully this will get you thinking… and doing your homework before making mistakes that can’t be changed. Working with a professional who’s been down the path before can’t hurt, either.[](https://indfin.com/wp-content/uploads/2016/06/4-Simple-Steps-Post_001.png)
I did create a short piece not long ago, *Four Steps to a Comfortable Retirement*. You might find it worthwhile.
Enjoy!
Jim
---
*Jim Lorenzen is a*[ *CERTIFIED FINANCIAL PLANNER®*](https://en.wikipedia.org/wiki/Certified_Financial_Planner) *professional and An Accredited Investment Fiduciary® serving private clients since 1991. Opinions expressed are those of the author and do not represent the opinions of IFG any IFG affiliate or associated entity.The Independent Financial Group is a registered investment advisor with clients located across the U.S. He is also licensed for insurance as an independent agent under California license 0C00742.Jim can be reached at 805.265.5416 or (from outside California) at 800.257.6659.The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.*
[***\[1\]***](#_ftnref1) *401kSpecialistmag.com, Issue 2 1015.*

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement, Taxes
**Tags:** retirement mistakes, Retirement Planning, rollover mistakes
---
### [Retirement Webinar Announcement: This Saturday, October 1st](https://indfin.com/retirementwebinarannouncement/)
**Published:** September 26, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/06/iStock_62491112_XXXLARGE.jpg)*iStock Images***I’ll be conducting a retirement webinar this comingSaturday, October 1st.**
**Who would benefit**: “Baby Boomers” planning for or nearing retirement and desiring to put a plan in place.
You can learn more about the webinar and register here.
When you register, you’ll automatically be signed-up to receive our weekly ezine and, as a bonus, you’ll also receive a retirement income planning tool you can use to help get your own ‘ducks lined up’. I think you’ll find it quite useful.
Jim
---
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients providing retirement planning and wealth management services since 1991. Jim is Founding Principal of The Independent Financial Group, a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement
**Tags:** retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy, retirement webinar
---
### [There's More than One Path to Retirement Security](https://indfin.com/retirementsecuritychoices/)
**Published:** August 29, 2017
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/06/iStock_44633966_SMALL.jpg)iStock Images**Jim Lorenzen, CFP®, AIF®**
#### People often think investment strategies for retirement security involve a either/or choices, i.e, risky stocks or savings as a zero-sum choice, or active vs. passive investing as an either/or choice; Believe it or not, there’s more than one path to retirement security. Sometimes (often) they can be blended.
**Active vs. Passive**
[](https://indfin.com/wp-content/uploads/2017/05/i317a_Cl_Active-vs-Passive-Investing_Vanguard_001.png)For example, low-cost passive investments are attractive simply because it’s widely believed that active managers can’t beat their relevant indexes’ average return on a consistent basis.
That’s probably true, however the argument often ignores the downside protection active management can offer – something index investing doesn’t provide, and something important to investors for retirement security.
Does that mean there’s only one path to financial security… that active is better? No – it’s just different. Sometimes, the extra fee an active manager charges can be worth far more than the alternative downside exposure. Vanguard has created a client education piece about active and index investing that you might find helpful. You can download it [here](https://indfin.com/wp-content/uploads/2017/05/i317a_Cl_Active-vs-Passive-Investing_Vanguard.pdf).
**Active Institutional Management**
Investors with smaller accounts often achieve diversification by investing in mutual funds. While these investors can benefit from the diversification they offer, those with larger accounts can be penalized. The reason is simple: Mutual fund costs don’t scale.
For example, if you have $50,000 invested in a mutual fund that carries a 1.25% expense ratio (just to pick a number), you’re paying $625 a year in annual expenses. Not too bad. But, suppose your investment is $500,000 and you have a basket of mutual funds and all charge about the same 1.25%. Your annual expenses would now total $6,250 per year.
Fund expenses don’t go down as the asset level increases. 1.25%, in our example, would stay 1.25%, regardless of how much your account increases in value. And, those aren’t the only expenses! You can learn about the other hidden expenses in another report, ***Understanding Mutual Funds***, which you can also download instantly, [right here](https://indfin.com/wp-content/uploads/2017/05/i309_WP-Understanding_Mutual_Fund_Landscape.pdf).
**Institutional money managers** – at least all those I use – have fully disclosed fees; but, furthermore, their fee percentage actually declines as the investor’s asset level grows. They can also provide tax-managed benefits not available in mutual funds.
Institutional managers seem to do far better than the individual investor. As you can see from this independent Dalbar study, individual investors didn’t even come close- and the time period for the study included the famous ‘meltdown’ of 2008.
[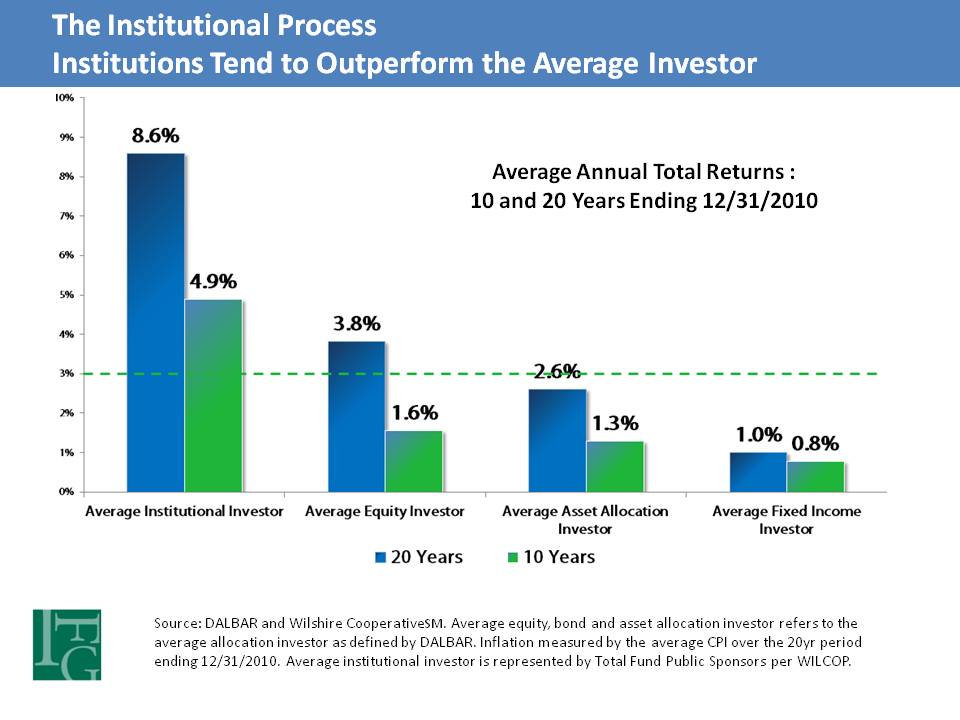](https://indfin.com/wp-content/uploads/2017/05/Institutional-Investors-vs-Avg-Indiv-Investor.jpg)
[](https://indfin.com/wp-content/uploads/2017/05/i208_Manager-Screening-and-Selection-Process_001.png)The selection process for institutional managers, of course, is important, if not critical.
If you’d like to see the process I have been usinghere at IFG, you can [get it here.](https://indfin.com/wp-content/uploads/2017/05/i208_Manager-Screening-and-Selection-Process.pdf)
Of course, it’s not an either/or proposition: Blending active institutional management with passive indexes can be quite effective.
**It begins with a philosophy.**
[](https://indfin.com/wp-content/uploads/2014/09/Key_Success.png)Do you know your investment philosophy? By the way, “I don’t want to lose money” is not a philosophy; it’s a wish. A philosophy goes deeper – it’s the roadmap that helps you as you go through the investment/manager selection process. IFG’s can be accessed immediately[here](https://indfin.com/wp-content/uploads/2017/05/i206_Investment-Philosophy.pdf).
**Managing the Downside.**
There’s a tv commercial sponsored by a mutual fund/insurance complex that asks the question, “**Do you know your number?**”
While it’s a good question, it doesn’t go far enough. **The real question may not be how much you have, but how long it will last!** After all, that’s the key to almost everyone’s definition of retirement security.
**Longevity risk – “Will I run out of money?”**
This is the key issue for most Americans; even those with $1,000,000+ who want to maintain their standard of living, let alone the vast majority of Americans who have less. You might enjoy getting our Money or Income report when you sign-up for the IFG ezine (you can always unsubscribe later). You can get the report here.
What’s right for you is likely no one strategy, but a blend of this – and other strategies not even covered here – that best fits your particular needs and desires.
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** investment returns, Investment Strategy, managing risk, Reducing Risk
---
### [What if Retirement Plan Statements Stated the Facts?](https://indfin.com/what-if-retirement-plan-statements-stated-the-facts/)
**Published:** September 21, 2016
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2016/02/iStock_UncleSamLiftingWallet_Medium.jpg)The next time you open your 401(k) or IRA statement and see your current balance, it might be worth remembering it isn’t true. The balance, you see, isn’t all yours!**
Remember how many times you’ve heard the phrase*tax deferred*? You’ll avoid taxes only as long as you leave the money untouched; of course, by age 70-1/2 or thereabouts you’re going to have to take some money out, whether you like it or not, because Uncle Sam wants his cut.
Then, the truth hits: You’ve been growing money for Uncle Sam, too!
If you’re in a combined state and federal income tax bracket of 33%, it means only 66% of the balance you see on your statement is really yours – or ever will be.
For example, if your tax-deferred retirement plan statement indicates you have $500,000, remember it’s illusory. Your tax bracket will [](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73dd6e411970d-320wi.jpg)determine how much Uncle Sam will get – and Uncle Sam is not only the one who ‘writes the rules’, he also determines when he wants to do it.
If your combined state and federal tax bracket is 30%, for example, Uncle Sam’s balance in your account is $150,000. Your balance is $350,000 – unless Uncle Sam changes his mind about your bracket.
So, the next time you look at your tax-deferred balance, you might want to whack-off Uncle Sam’s cut and enter the remaining balance on your own balance sheet – it will probably be a closer representation of what you really own when all the dust settles.
There are some steps you can take to reduce or potentially eliminate income tax in retirement, if you’re prepared to do what it takes today.
You have to ask yourself:
- With an aging population demanding services, do I feel confident Uncle Sam won’t raise taxes in the future on those who’ve worked and saved?
- With the “official” national debt over $19 trillion – and the real debt more like $89 trillion – do I feel confident Uncle Sam will simply manage better and keep taxes where they are on those who’ve worked and saved?
If you feel good about trusting their management of your money over the next thirty years, you may even be content with your tax status moving forward. If not, you may want to begin exploring your options.
[](https://indfin.com/wp-content/uploads/2016/04/IFGi_4-Steps-to-a-Tax-Free-Retirement_001.png)Here’s a short report you might find interesting as a first step in your process.
You can access it here. I hope you find it helpful.
Jim
——————————
**RESOURCES:**
**[Subscribe](https://tinyurl.com/IFGInsights)to IFG’s Ezine: IFG Insightsat**
Visit the [IFG Website](https://indfin.com)!
***Jim Lorenzen**is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement, Taxes
**Tags:** Retirement tax strategies, Tax reduction, Tax-Free Retirement Income
---
### [Someone Predicts a Market Drop of 20%! So What?](https://indfin.com/someone-predicts-a-market-drop-of-20-so-what/)
**Published:** January 5, 2024
**Author:** Jim Lorenzen
**Excerpt:** It depends on how much you have invested in the market. If you're a conservative retiree, should you care?
**Content:**
Maybe. Maybe not. Suppose you have 40% of your portfolio invested in stocks – assuming your holding represent “the market” being predicted – and the rest of your money is in bonds and cash.
Assuming your bonds and cash remain at the same value, how much impact will a 20% market drop affect you? Simple math: 40% drops by 20%: 40 x .20 = 8%. So, if the prediction comes to pass and the rest of your portfolio stays the same, you would experience at 8% decline in your assets.
Of course, this is all hypothetical theory. In the real world, it’s a little different. First, bonds seldom stay the same. If interest rates drop, the value of existing bonds will increase. The reverse is true if interest rates increase.
And cash? Well, it’s worth only what it will purchase; so, if inflation averages 3% in a year, the value of cash has declined by 3%.
So, nothing happens in a vacuum. And, what a ‘market’ move means to you depends on how other components react. If you have a solid, stress-tested financial plan, the ‘white noise’ of media predictions, so often chased by those who don’t know any better, can just go in one ear and out the other. If you don’t have a plan, you can get one started securely here.
And, remember what Warren Buffett once said: he never met anyone who could predict the market.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [SBA Small Business Week Begins April 30th](https://indfin.com/smallbusinesswebinars/)
**Published:** April 25, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/09/Internet_Image_Global_Waves.jpg)Jim Lorenzen, CFP®, AIF®**
##### Small business webinars will be available the week of April 30th to help celebrate Small Business Week.
SBA Secretary Linda McMahon announced this on the SBA website:
The countdown to [National Small Business Week](https://links.govdelivery.com:80/track?type=click&enid=ZWFzPTEmbWFpbGluZ2lkPTIwMTcwNDIzLjcyNjAwMDQxJm1lc3NhZ2VpZD1NREItUFJELUJVTC0yMDE3MDQyMy43MjYwMDA0MSZkYXRhYmFzZWlkPTEwMDEmc2VyaWFsPTE3MTM0MzcwJmVtYWlsaWQ9aW5mb0BpbmRmaW4uY29tJnVzZXJpZD1pbmZvQGluZGZpbi5jb20mZmw9JmV4dHJhPU11bHRpdmFyaWF0ZUlkPSYmJg==&&&101&&&https://www.sba.gov/blogs/get-ready-national-small-business-week?utm_medium=email&utm_source=govdelivery) (NSBW) is on! NSBW (April 30th – May 6th) is an annual event hosted by the U.S. Small Business Administration to recognize the nation’s top small businesses, entrepreneurs, small business advocates and champions, and will feature a series of small business webinars.
These small business webinars cover a wide variety of topics:
**The U.S. Economic Outlook and Its Impact on Small Businesses**
Presented by Visa
May 2, 2017 | 2:00-3:00 pm ET
Register [here](https://links.govdelivery.com:80/track?type=click&enid=ZWFzPTEmbWFpbGluZ2lkPTIwMTcwNDIzLjcyNjAwMDQxJm1lc3NhZ2VpZD1NREItUFJELUJVTC0yMDE3MDQyMy43MjYwMDA0MSZkYXRhYmFzZWlkPTEwMDEmc2VyaWFsPTE3MTM0MzcwJmVtYWlsaWQ9aW5mb0BpbmRmaW4uY29tJnVzZXJpZD1pbmZvQGluZGZpbi5jb20mZmw9JmV4dHJhPU11bHRpdmFyaWF0ZUlkPSYmJg==&&&102&&&https://cc.readytalk.com/registration/?utm_medium=email&utm_source=govdelivery#/?meeting=kq61i7knmzxb&campaign=91jrfdtyov2)
**5 Fabulous Habits of Local Business Champions**
Presented by YP
May 3, 2017 | 2:00-3:00 pm ET
Register [here](https://links.govdelivery.com:80/track?type=click&enid=ZWFzPTEmbWFpbGluZ2lkPTIwMTcwNDIzLjcyNjAwMDQxJm1lc3NhZ2VpZD1NREItUFJELUJVTC0yMDE3MDQyMy43MjYwMDA0MSZkYXRhYmFzZWlkPTEwMDEmc2VyaWFsPTE3MTM0MzcwJmVtYWlsaWQ9aW5mb0BpbmRmaW4uY29tJnVzZXJpZD1pbmZvQGluZGZpbi5jb20mZmw9JmV4dHJhPU11bHRpdmFyaWF0ZUlkPSYmJg==&&&103&&&https://cc.readytalk.com/registration/?utm_medium=email&utm_source=govdelivery#/?meeting=15u3wsfhcnhk&campaign=sft38grdkaqm)
**Grow Your Business Online**
Presented by Google
May 3, 2017
4:00-5:00 pm ET
[Register here](https://links.govdelivery.com:80/track?type=click&enid=ZWFzPTEmbWFpbGluZ2lkPTIwMTcwNDIzLjcyNjAwMDQxJm1lc3NhZ2VpZD1NREItUFJELUJVTC0yMDE3MDQyMy43MjYwMDA0MSZkYXRhYmFzZWlkPTEwMDEmc2VyaWFsPTE3MTM0MzcwJmVtYWlsaWQ9aW5mb0BpbmRmaW4uY29tJnVzZXJpZD1pbmZvQGluZGZpbi5jb20mZmw9JmV4dHJhPU11bHRpdmFyaWF0ZUlkPSYmJg==&&&104&&&https://cc.readytalk.com/r/gjkbtesqmzvb&eom?utm_medium=email&utm_source=govdelivery)
**The Future of Small Business Innovation**
Presented by Salesforce
May 4, 2017
2:30-3:30 pm ET
[Register here](https://links.govdelivery.com:80/track?type=click&enid=ZWFzPTEmbWFpbGluZ2lkPTIwMTcwNDIzLjcyNjAwMDQxJm1lc3NhZ2VpZD1NREItUFJELUJVTC0yMDE3MDQyMy43MjYwMDA0MSZkYXRhYmFzZWlkPTEwMDEmc2VyaWFsPTE3MTM0MzcwJmVtYWlsaWQ9aW5mb0BpbmRmaW4uY29tJnVzZXJpZD1pbmZvQGluZGZpbi5jb20mZmw9JmV4dHJhPU11bHRpdmFyaWF0ZUlkPSYmJg==&&&105&&&https://www.salesforce.com/events/esmb/sba-innovation-webcast/?utm_medium=email&utm_source=govdelivery)
**How to Write Your Email Content in 15 Minutes or Less**
Presented by Constant Contact
May 4, 2017 | 3:30-4:30 pm ET
Register[ here](https://links.govdelivery.com:80/track?type=click&enid=ZWFzPTEmbWFpbGluZ2lkPTIwMTcwNDIzLjcyNjAwMDQxJm1lc3NhZ2VpZD1NREItUFJELUJVTC0yMDE3MDQyMy43MjYwMDA0MSZkYXRhYmFzZWlkPTEwMDEmc2VyaWFsPTE3MTM0MzcwJmVtYWlsaWQ9aW5mb0BpbmRmaW4uY29tJnVzZXJpZD1pbmZvQGluZGZpbi5jb20mZmw9JmV4dHJhPU11bHRpdmFyaWF0ZUlkPSYmJg==&&&106&&&https://cc.readytalk.com/registration/?utm_medium=email&utm_source=govdelivery#/?meeting=w7h2t3nfs4p3&campaign=4u348rhqap5d)
**Find the Hidden Money in America**
Presented by Chase
May 4, 2017 | 5:00-6:00 pm ET
Register [here](https://links.govdelivery.com:80/track?type=click&enid=ZWFzPTEmbWFpbGluZ2lkPTIwMTcwNDIzLjcyNjAwMDQxJm1lc3NhZ2VpZD1NREItUFJELUJVTC0yMDE3MDQyMy43MjYwMDA0MSZkYXRhYmFzZWlkPTEwMDEmc2VyaWFsPTE3MTM0MzcwJmVtYWlsaWQ9aW5mb0BpbmRmaW4uY29tJnVzZXJpZD1pbmZvQGluZGZpbi5jb20mZmw9JmV4dHJhPU11bHRpdmFyaWF0ZUlkPSYmJg==&&&107&&&https://cc.readytalk.com/registration/?utm_medium=email&utm_source=govdelivery#/?meeting=v0iioflv4wvh&campaign=mmcrl3tbysfa)
IFG has also created a report, “***How to Establish Business Value***” – information that can be useful for evaluating the impact of major purchases on business value going forward. You can get it here.
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Business Owners
**Tags:** business decisions, business owners, management
---
### [SELLING YOUR BUSINESS? This may be the best kept secret you'll need.](https://indfin.com/selling-your-business-this-may-be-the-best-kept-secret-youll-need/)
**Published:** January 24, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2016/11/Fotolia_4812344-DB-wDollarSign.jpg)Jim Lorenzen, CFP®, AIF®**
Ever heard of a “One-Way Buy-Sell” arrangement? Don’t feel bad. Few people have. I know when I was in publishing I hadn’t heard of it, either. I wish I had.
Here’s the tease: How to sell your business – in advance, at a price you want, and secure the funding, too!
Most businesses are sold on some form of the installment plan; for closely-held businesses, the ‘all cash’ buyer is virtually a misnomer. The problem with the installment plan is obvious: What if the business should suffer reversals during the buyout period? Do you really want to come out of retirement to save the business and go through another sale all over again?
[](https://indfin.com/wp-content/uploads/2017/01/i806a_One-Way-Buy-Sell-Agreements_001.png)The One-Way Buy-Out arrangement not only addresses all the issues cited above, it also protects against reversals and can secure your retirement, as well as the security of employees and family if something should happen to you before you get your ducks lined up.
Want to learn more? You can get my report here!
Enjoy,
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Business Owners, Retirement
**Tags:** business owners, business owners retirement, selling closely-held business, Selling your business
---
### [RMDs - A Quick 4-Tip Checklist for Baby Boomers](https://indfin.com/rmds-a-quick-4-tip-checklist-for-baby-boomers/)
**Published:** May 11, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/higher-tax-rates-for-trusts/6a017c332c5ecb970b01910219a734970c-320wi/)**Jim Lorenzen, CFP®, AIF****®**
Remember the 1990s? That was when every business channel had multiple programs with business gurus picking and ranking mutual funds. It was a time when many mutual fund managers were becoming the ‘rock stars’ of financial meda. Everyone wanted to know what Peter Lynch, Bill Gross, and others were buying, selling, and saying.
If you were one of those following all those shows back then, you were no doubt thinking about your financial future. And, if you were born in the years following 1946, chances are you’re a ‘baby boomer’ – a term we’re all familiar with by now.
I read somewhere that there are 65,000 boomers turning age 65 every year! And, those turning 70-1/2 have hit a big landmark: It’s the year – actually it’s up until April 1st of the following year – Uncle Sam begins sticking his hand into your retirement account – after all, he is your partner; and, depending on your combined state and federal tax-bracket, his ownership share can be pretty significant, depending on the state you live in. Yes, that’s when you must begin taking required minimum distributions (RMDs).
By the way, if you do wait until April 1st of the following year, you’ll have to take TWO distributions in that year – one for the year you turned 70-1/2 and one for the current year. Naturally, taking two distributions could put you in a higher tax bracket; but, Uncle Sam won’t complain about that.
[](https://indfin.com/common-misconceptions-about-the-unlimited-marital-deduction/senior-couple-meeting-with-agent/) *Fotilla Images*So, now that you’ve been advised of one trap that’s easy to fall into, what are some of the others? You might want to give these concerns some thought – worth discussing with your tax advisor, as well as your financial advisor.
Here are four tips to think about:
****Not all retirement accounts are alike.****
IRA withdrawals, other than Roth IRAs, must be taken by December 31st of each year – and it doesn’t matter if you’re working or not (don’t forget, there is a first year exemption as noted earlier).
401(k) and 403(b) withdrawals can be deferred past age 70-1/2 provided you’re still working, you don’t own more than 5% of the company, and your employer’s plan allows this.
As noted, Roth IRAs have no RMD requirements. However, if you’re in a Roth 401(k), those accounts are treated the same as other non-Roth accounts. The key here is to roll that balance into a Roth IRA where there will be no RMDs or taxation on withdrawals.
**The amount of your total RMD is based on the total value of all of your IRA balances requiring an RMD as of December 31st of the prior year.**
You can take your RMD from one account or split it any or all of the others. By the way, this doesn’t apply to 401(k)s or other defined contribution (DC) plans… they have to be calculated separately and the appropriate withdrawals taken separately.
**Uncle Sam owns part of your withdrawal.**
How much depends on the year and he can change the rules without your consent. Chances are you will face either a full or partial tax, depending on how your IRA was funded – deductible or non-deductible contributions. And, the onus is on you, not the IRS or your IRA custodian, to keep track of those numbers. Chances are your DC plan at work was funded with pretax money, making the entire RMD taxable at whatever your current rate is; and, as mentioned earlier, it’s possible your RMDs could put you in a higher tax bracket.
It’s all about provisional income and what sources of income are counted. The amount that’s above the threshold for your standard deduction and personal exemptions are counted.By the way – here’s something few people think about: While municipal bond interest may be tax-free, it IS counted as provisional income, which could raise your overall taxes. Talk to your tax advisor.
**Don’t miss taking your RMD**.
If you fail to take it by December 31st of each year – even if you make a miscalculation on the amount and withdraw too little – the IRS may hit you with an excise tax of up to 50% of the amount you should have withdrawn! Oh, yes, you still have to take the distribution and pay tax on it, too! There have been occasions when the IRS has waived this penalty – floods, pestilence, bad advice, etc.
Remember to talk with your tax advisor. I am not a CPA or an attorney; but, of course, these are issues that come up in retirement planning and wealth management quite often.
I’ll be doing a webinar on retirement planning for income on May 28th. We’ll have more information on that soon. I’ve also created a reportentitled, *TheFive Biggest Risks to Your Retirement.*You can get it here.
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. Images contained herein are public domain images and do not depict IFG clients or anyone affiliated with IFG unless otherwise noted. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Taxes
**Tags:** IRAs, Retirement Planning, Retirement Strategy
---
### [Should You Invest in Real Estate?](https://indfin.com/should-you-invest-in-real-estate/)
**Published:** May 9, 2013
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017eeab50e0a970d-320wi.jpg)Hey, they ain’t making anymore of it!**
Unlike the dollar, the government can’t print real estate; so, I’ve been a long proponent of real estate investing. But, then, I’m also a proponent for investing in stocks. I also like commodities. What do they all have in common? They all have had their ups and downs.
There have been times when people have made money – or been hurt – in all of them. That’s why we diversify. You see, you don’t diversify investments; you diversify risk!
Because the real estate market is composed of non-interchangeable, unique, illiquid properties, it might be considered as less efficient than the stock and bond markets; but, that inefficiency is probably what creates*exploitable opportunities*for skilled investors. But, because each investment is unique and non-liquid, it’s important that real estate investments be adequately diversified.
You can diversify your real estate portfolio by having ownership interests in different types of real estate, such as:
- Office buildings
- Residential apartment complexes
- Shopping centers
And, you can diversify geographically, as well.
Want to buy an apartment building? You can, but you might consider this: You wouldn’t be purchasing an `investment’ as much as you’d really be buying a full-time business. If you tie all your money up in that one business, you’re putting all your eggs in one basket, hoping the equity will be there when the day comes you actually need it. In essence, it’s like putting all your money in one company’s stock!
As recent history has shown, that can be problematic. Equity real estate investment trusts (REITs) can provide an alternative method to provide real estate diversification. Equity REITsare publicly traded operating companies that own and manage real estate properties. Similar to mutual funds, equity REITs serve as a conduit for earnings on investments and avoid corporate taxation by meeting certain investment and income distribution requirements.
One of the reasons many investors include REITsin their portfolios as a diversification tool is because they’ve offered long-term total returns comparable to the stock market – dividend income has been a major portion of that return – and equity REITs have had a relatively low correlation with both the U.S. bond and stock markets. There are also some non-traded REITs that can offer relatively consistent income streams for those willing to sacrifice liquidity on that portion of their assets.
How big of a role should real estate play in your portfolio? That’s something you should discuss with your advisor, preferably one who provides planning and investment advisory services on a fee-only basis. Making blind purchases can be risky financially; and they can be even more risky if you’re just buying from a salesman.
But, don’t fall prey to common misconceptions many investors have: Thinking their home is a real estate investment – it isn’t, it’s shelter, and you’ll always need to have one. Just like owning rental real estate directly isn’t so much an investment as it is a business. You can live off the business, but you won’t retire on it – you’ll have to sell it to retire, just like any other business.
The key is the plan: If you don’t have a formal, written financial plan for your future, you really don’t know how much real estate – or what kind – you should have. And, getting older without a plan is never a good idea.
Jim
—————
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk "Hidden Risk Report")(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Financial Conversation Checklist")(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights "IFG Insights")to IFG’s Ezine:[IFG Insights](https://tinyurl.com/IFGInsights%20 "IFG Insights")
[The IFG Website](https://indfin.com/ "IFG site")
Follow Jim on Twitter: @jimlorenzen
[Jim Lorenzen on LinkedIn](https://www.linkedin.com/in/jimlorenzencfp%20 "Jim on LinkedIn")
IFG on[Facebook](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
———————
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,****a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Should You Retire or Keep On Working?](https://indfin.com/should-you-retire-or-keep-on-working/)
**Published:** June 24, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a3fd223cfa970b-320wi.jpg)Politicians, journalists, and lawyers never retire – at least, it seems that way. Arnold Palmer was once asked when he would retire and he said, “Retire to what?”
I can understand that. I took a stab at it myself some years ago – I even moved to Florida, bought a home on a golf course, and played golf for about three years when it hit me: I wanted to get `back in the game’. I realized I missed actually having something to do – and I wanted something to do that would actually have significance. That was 23 years ago. My ‘retirement’ has become a true second career. By the way, that’s not my office pictured – this one’s too neat.
Oh, yes, let’s not forget the effect the Great Recession had on many people. About that time, I was glad I was working! And, many others contemplating retirement began re-evaluating their future plans, as well. Working past normal retirement age is not a new necessity. According to the Social Security Administration, more than 30% of individuals between the ages of 70 and 74 reported income from earnings in 2010, the latest year data are available. Among a younger age group, those between 65 and 69, nearly 49% had income from a job. \[*Source: Social Security Administration,Income of the Population 55 or Older, 2010,March 2012 (latest available).\]*
There are good reasons to stay productive: You can start with health, both physical and mental; but, it’s also true that, as long as you CAN work, it simply makes sense – every dollar that comes from the outside isn’t draining your nest-egg. And, if you can work in some form of self-employment, you can even exercise some degree of control over your schedule!
There’s another benefit: If you earn enough to forgo Social Security benefits until after your full retirement age, your eventual benefit will increase by between 5.5% and 8% per year for each year that you wait, depending on the year of your birth – that’s more than double the inflation rate!. You can determine your full retirement age at the Social Security Web site ([www.ssa.gov](https://www.ssa.gov/ "SS Admin Site")) or by calling the Social Security Administration at1-800-772-1213.
One client once told me, “I’ll never live long enough to get all the money back I gave up!” I reminded him that if he was dead, he didn’t have a problem. It’s living too long that creates the problems – and you’ve heard of Murphy’s Law.
**Seeing Money Grow is Good.**
Depending on the your circumstances, working longer could also enable you to continue adding to your retirement nest egg, either through an employer-sponsored retirement plan or an IRA, or, if your self-employed, some other tax-deferred means. Remember however that after age 70 1/2, you will be required to make withdrawals, known as required minimum distributions (RMDs), from traditional 401(k)s and traditional IRAs. RMDs are not required from Roth IRAs and Roth 401(k)s.
By the way, whether you retire or not, don’t forget to apply for Medicare at age 65. In certain circumstances, medical insurance might cost more if you delay your application.
And, don’t overlook part-time, seasonal, or temporary opportunities – all of which can provide excellent opportunities for staying in the game.
Jim
**RESOURCES:**
**Visit[Jim’s Social Security Learning Center](https://www.jlorenzen.sswise.com/ "Social Security Learning Center")**
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Conversation Checklist")(does not require registration)
[Subscribe to IFG Insights](https://tinyurl.com/IFGInsights "Subscribe to IFG Insights")
[The IFG Website](https://indfin.com/ "IFG Website")
IFG’s[Financial Resources website](https://finsecurity.com/Lorenzen "IFG Financial Resources Website").
Follow Jim on Twitter: @JimLorenzen
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
**Become an IFG client!**Don’t play phone-tag; schedule your 15-minute introductory phone call using[this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,**a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Like the S&P 500 Index?](https://indfin.com/sp500/)
**Published:** October 12, 2020
**Author:** Jim Lorenzen
**Excerpt:** Like indexing? Like the S&P? You can get an index fund! Sounds good. Let's face it, most (virtually all) investment management companies fail to beat the S&P index on a consistent basis. We all know that.
**Content:**
#### Maybe you should look under the hood.
[](https://indfin.com/wp-content/uploads/2016/11/Dollar-Sign-and-characters-surrounding.png)
**Jim Lorenzen, CFP®, AIF®**
Like indexing? Like the S&P? You can get an index fund! Sounds good. Let’s face it, most (virtually all) investment management companies fail to beat the S&P index on a consistent basis. We all know that.
There’s a good reason for it: An index doesn’t have expenses while, in the real world, all assets have a cost of ownership – expenses – attached.
If your home is worth $500,000 and your local housing market, including your home, increased by 10%, your home and the market would become worth $550,000. Did you tie the housing index? Of course not. You had to pay property taxes, homeowner’s insurance, maintenance and repair costs, mortgage interest, maybe even HOA and other costs that are required. Sometime, just for fun, add up all your annual costs and see what your annual expense ratio is (total costs of ownership divided by your home’s current value). You might be surprised, but I digress.
Expenses aside, how about using a fund replicating the S&P index (that’s as close as you’ll get)? Let’s look under the hood.
According to Craig L. Israelsen, PhD, an Executive-in-Residence in the Personal Financial Planning program in the Woodbury School of Business at Utah Valley University, if all holdings in the index were weighted equally, each company holding would have a fixed weight of about 0.20% in the index. However, the holdings aren’t weighted equally; their weighted according to their market capitalization. This means that roughly 42% of the assets in a market cap-weighted S&P index are held in just 25 of the 500 stocks – another way of saying that the largest 5% of stocks represent over 40% of the allocation.
The practical implication of all this: half the stocks in the market cap-weighted S&P index have very little impact on performance.
When tech goes up, the cap-weighted S&P index looks good. When tech takes a nose-dive, not so good.
Is that good for baby-boomers now guarding their serious money for retirement? Saving a point or two on investment expenses may not be the key issue for this group. Wealth preservation and maintaining purchasing power for the long term may be more important.
Maybe there’s a better way to achieve long-term goals than riding the index roller coaster.
Jim
————————————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** Financial planning, Investment mistakes, investment planning, investment returns
---
### [Financial Planning for Special Needs Children is Different!](https://indfin.com/specialneeds/)
**Published:** December 9, 2019
**Author:** Jim Lorenzen
**Excerpt:** According to Financial Planning magazine, more than 5% of school-age children are diagnosed with a disability of some type
**Content:**
****[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019104976c39970c-320wi.jpg)Few families aren’t touched by this issue.****
According to Financial Planning magazine, more than 5% of school-age children are diagnosed with a disability of some type – seeing, hearing, talking, walking, or thinking; and, planning for their future can not only be complex, but demanding. Indeed, many parents feel overwhelmed!
What makes it so difficult is that the planning isn’t only for the parents – it’s also for after the parents and caregivers are long-gone, which can be another 30 to 50 years!
So, financial planning must last for at least two lifetimes when special needs children are involved.
The issues are many, and often difficult to talk about. Will the child have a shortened life-span? Will the child be capable of living and working independently? Will they be able to handle money? Someone who can’t make change in their 40s will find it virtually impossible to reconcile a check book.
The families struggle, too. Medical, therapeutic, and emergency health care issues can deplete a bank account quickly; and, often, families neglect their own retirement plans in an effort to help. Younger couples facing these issues really need to begin their planning early – for more than just themselves. How will special needs children be provided for? Who will administer it all after the parents are gone? What investment mix is required?
Many planners will often recommend that families facing these issues begin by setting-up a third-party special-needs trust – and, it should go without saying that an experienced lawyer is a must. The reason this type of trust is recommended is because the assets in these trusts aren’t counted toward the disabled person’s eligibility cap for Medicaid benefits; but there are rules on how the money can be used – cash, for example, is bad because if the trustee gives the beneficiary cash, that cash counts against their benefits dollar for dollar, according to Dennis Sandoval, an estate planning attorney in Riverside, California.
Some families are wealthy enough to fund trusts while they’re still alive; but, others can accomplish the same thing with life insurance, often a second-to-die policy that pays out after the second parent’s death because the premiums are less. Term insurance can make sense if the child is expected to die before the parent.
Quite often, a family establishing a trust will want to name a family member as trustee; but, many advisors think this may not be a good idea since most lack the financial acumen to handle a trust’s administration. Besides, what if your family trustee dies? What then? Who takes over? Can the child function in an adult world, even after reaching age 50?
A better option might be to use a third-party trust company for administration and a qualified advisor to oversee the management of the assets. Trust companies don’t die and are bound by regulatory oversight. Quite often, an experienced advisor can help parents access an independent third-party trust company – without a conflict of interest or hidden compensation – and be better equipped to balance immediate needs against the long-term goal of ensuring that there is enough money to last throughout the disabled person’s life.
Jim
—————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
*Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues, Planning, Special needs
---
### [The Stretch IRA is Gone. Now What?](https://indfin.com/stretchalternatives/)
**Published:** February 8, 2020
**Author:** Jim Lorenzen
**Excerpt:** The SECURE Act has changed the game, especially for parents who were planning on leaving substantial nest-eggs to their kids, with the elimination of Stretch IRAs. Uncle Sam may be the biggest beneficiary.
**Content:**
**There are three alternatives you can use!**
**Jim Lorenzen, CFP®, AIF®**
The SECURE Act has changed the game. I discussed the things you need to know in a [previous post](https://indfin.com/secureact/); but maybe the biggest game-changer, especially for parents who were planning on leaving substantial nest-eggs to their kids, is the elimination of Stretch IRAs. The big unexpected inheritor just might be Uncle Sam.
Before the SECURE Act, the child could take required minimum distributions (RMDs) based on his/her own life expectancy. Theoretically, if they inherited early, the RMD would be so small they could actually continue growing the nest egg in perpetuity – even grandchildren could benefit! No more. Now, the inherited IRA has to be liquidated in *ten* years.
The odds are most boomers will die when their children are in their peak earning years. So, an inherited $500,000 IRA can create some tax problems! An inheriting child in their 50s, who before the SECURE Act may have taken RMDs in the neighborhood of $17,000, will now be required to take a first RMD of $50,000…. and that’s in addition to their income during their peak earning years. Add to that the double-whammy that the current tax law sunsets in 2026 and the old 2017 tax brackets come back into effect, and you have a perfect storm – I won’t depress you with the outlook for tax legislation in view of the current national debt.
The elimination of the stretch IRA is expected to add $15.7 billion to the federal budget over the next ten years as baby boomers begin the pass away.
As you can imagine, this has tremendous estate planning ramifications for those wishing to pass-on wealth to their heirs. Now that the stretch is gone, here are three you may want to consider.
- **Roth Conversions**: This is an obvious one. Traditional IRAs may be tax-deferred, but they really should be called “tax-postponed”… until tax brackets are higher (remember the national debt and politician’s desires to spend tax dollars to gain reelection). If state inheritance taxes are an issue, a conversion could reduce the size of the estate and reduce tax exposure, too. A conversion may not be the right move for everyone. There are current tax bracket shift issues that should be considered.
- **Life Insurance**: Death benefits are generally tax-free, i.e., not included in the beneficiary’s income. Use distributions from the IRA to pay the policy and bingo – money goes to the kids and by-passes Uncle Sam. Depending on age and insurability, there are even advanced designs that could provide with tax-free income during retirement, as well. It’s not your father’s – or grandfather’s – life insurance anymore. It has become the ‘swiss army knife’ of financial tools.
- **Charitable Remainder Trusts (CRTs)**: Use your IRA to fund a CRT. This allows parents to create an income stream for their children with part of the IRA while the rest goes to charity. While the CRT can grow assets tax-free, the kids do pay tax on the income withdrawn. There are two types: an annuity trust and a remainder trust. The first distributes a fixed annuity and doesn’t allow future contributions; the second distributes a fixed percentage of the initial assets and allows for continued contributions.
Naturally, you should discuss anything you’re considering with your financial, tax, and legal advisors before making any moves. It pays to plan.
Jim
—————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Charitable Giving, Family Issues, Life Insurance, Planning, Retirement
**Tags:** charitable giving, trusts, wealth replacement
---
### [No RMDs for 2020!](https://indfin.com/roth-ira/)
**Published:** August 14, 2020
**Author:** Jim Lorenzen
**Excerpt:** Required minimum distributions (RMDs) have been eliminated for 2020 due to the COVID-19 pandemic; but, you just might want to consider taking a distribution anyway. Why?
**Content:**
#### But, you may want to take IRA withdrawals anyway. The reason is simple: Taxes are On Sale!
[](https://indfin.com/wp-content/uploads/2020/08/HM_Taxes.png)**Jim Lorenzen, CFP®, AIF®**
Required minimum distributions (RMDs) have been eliminated for 2020 due to the COVID-19 pandemic; but, you just might want to consider taking a distribution anyway. Why?
**Taxes are on sale!**
**The dirty little secret is that all that money in your IRA isn’t yours**, unless you have so many deductions or credits that you can zero out all your income – not likely. We have a tendency to look at our statement’s IRA balance and think all that money is ours. It isn’t . At some point, Uncle Sam will take a chunk of it. It will happen when you begin withdrawing it. So, the only question is *at what rate*?
**Few people are aware that the current tax laws is set to expire – it ‘sunsets’ – on December 31,2025**, about 5 years from now (that allows for tax increases without anyone in Congress having to vote for it, though many would happily do it earlier anyway).
So, you can take your IRA money now at ‘sale prices’ or take it later at higher prices. Why would you want to do that (besides the obvious)?
**The SECURE Act has eliminated the stretch IRA.** This means your heirs could have a big problem when you and your spouse pass away. Odds are it will happen when your kids are in their peak earning years; want to guess what taxes might look like then? When they inherit your IRA(s), they will be required fully liquidate those IRAs by the end of the 10th year – ouch! Big tax bite.
**What can you do?** Begin withdrawing your IRA money while taxes [](https://indfin.com/wp-content/uploads/2020/08/Roth_checked_vs_IRA_unchecked.png)are on sale over the next five years and do a Roth conversion on the money each year. You’ll pay taxes now at ‘sale prices’ and the money will grow inside the Roth IRAs tax-free. Now, there’s no RMDs. And, when the time comes, your kids will have to liquidate by the end of the 10th year – but the money will be tax free!
**There’s a hidden benefit** for you, too: Taxable income is used to determine what percentage of your Social Security is deemed taxable; it’s also used to determine Medicare premiums. The less money you have in your traditional IRAs, the less the RMDs – and the less taxable income you have. Hmmm.
If you have a comprehensive financial plan, a Roth conversion analysis should be a normal part of your planning process. The savings over the life of your plan, and to your kids, could be substantial. There are a number of issues to be considered, age, possible penalties, etc., so be sure to talk with your financial advisor. Don’t have one? See below!
**Is there a subject you would like to learn more about?** Let me know in just 1 minute! [You can do it here](https://www.surveymonkey.com/r/RB5PFZG).
Jim
————————————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Annuities, IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, Retirement tax strategies, Roth conversions, Roth IRA, Tax reduction
---
### [The SECURE Act Is A Financial Planning "Game Changer".](https://indfin.com/secure-act-game-changer/)
**Published:** February 26, 2020
**Author:** Jim Lorenzen
**Excerpt:** This major change will bring in $15.7 billion in tax revenue by 2029, according to the joint committee on taxation in their report on the bill, H.R. 1994. And, guess whose money they want? Yes, yours.
**Content:**
**And, there are implications many have missed.**
**Jim Lorenzen, CFP®, AIF®**
**Why did congress pass The SECURE Act?**
Simple. This major change will bring in $15.7 billion in tax revenue by 2029, according to the joint committee on taxation in their report on the bill, H.R. 1994. And, guess whose money they want? Yes, yours.
The administration, of course, is looking for ways to address the debt by raising revenue without actually talking much about the debt. They’re even kicking the can down the road on taxes, talking about making the current tax-cuts “permanent” – as if Washington had ever passed a permanent tax bill; it’s “Washington-speak”. The current tax law is set to “sunset”, i.e., expire in 2026, taking us all back to the pre-2017 tax rates. Permanency would be achieved by removing the sunset date. So far, so good; but, if you’re one of those planning for the next two decades, you should be thinking about what the next ten congressional elections might bring.
**The Stretch IRA is all but eliminated.** Under the old law, an heir could inherit an IRA and stretch the RMDs over his/her life expectancy. Okay, considering the inheritance will probably take place during their peak earning years. So, a $17,000 RMD on a $500,000 IRA (purely hypothetical) won’t make much difference. However, under The SECURE Act the inheritor must liquidate the IRA by the 10th year. There’s NO RMD REQUIREMENT, so, the heir could let the IRA grow until the last year–but, then would be required to withdraw ALL funds in one year–talk about playing roulette with what the tax laws will be when the entire balance is added to that year’s income for calculating the tax bill. Alternatively, the heir could take a 10% yearly distribution, for example. But, in our example, that would add $50,000 each year to taxable income during what would likely be the heir’s peak earning years!
For the owner of a traditional IRA, remember that RMDs are considered in two other areas: (1) how much of Social Security income will be subject to taxation, and (2) as income for determining your Medicare Part B premiums. Oh, yes, high income in retirement means higher Part B premiums.
It’s a good time, especially for those with substantial incomes, to do some planning.
Jim
—————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues, Life Insurance, Planning, Retirement, SECURE Act
**Tags:** retirement decisions, Retirement Planning, Retirement Strategy, Retirement tax strategies, SECURE Act
---
### [What You Should Know About The SECURE Act!](https://indfin.com/secureact/)
**Published:** January 20, 2020
**Author:** Jim Lorenzen
**Excerpt:** The SECURE Act contains quite a few changes that impact both individuals and business owners.
**Content:**
**Effective January 1, 2020**
**Jim Lorenzen, CFP®, AIF®**
******The SECURE Act contains quite a few changes that impact both individuals and business owners.****** **Two Key Changes For Individuals:**
**70-1/2 is out.**
New Law Raises Age for RMDs from 70½ to 72: Under the Setting Every Community Up for Retirement Enhancement (SECURE) Act of 2019, if you turn 70½ years old on or after January 1, 2020, you are eligible for the law’s changes and generally must begin taking RMDs by April 1 of the year following the year that you turn age 72.
People who turned 70½ years old in 2019 are not eligible for the law’s changes and generally must begin withdrawing money by April 1, 2020
[](https://indfin.com/wp-content/uploads/2020/01/RMD_Changes_under_SECURE_Act.png)
You can use the RMD calculator from FINRA [here](https://tools.finra.org/rmd/).
**No more “Stretch IRA” (for most).**
It’s eliminated for most beneficiaries of Traditional and Roth IRAs whose owners pass away in 2020 or later (Note: previous rules still apply to certain beneficiaries and to all inherited IRAs whose owners passed away before 2020). **There are no mandatory annual distributions, but the entire inherited Traditional or Roth IRA balance must be withdrawn by the end of the tenth year.**
There are some exclusions as well as other changes – talk with your financial or tax advisor.
**Business Owners**
There are a number of key changes for business owners, including
- Expanded access to annuities within retirement plans in order to help retirees establish their own “pension” plans.
- Retirement plan statements will be required to include a lifetime income disclosure at least once during any 12-month period
- Multiple-Employer plan rules relaxed – this allows a number of unrelated businesses to set-up a plan with one provider/administrator in an effort to reduce costs – this will help small businesses most.
Of course, there’s more; but, this should give you an idea of why it will pay to work closely with your financial and tax advisors.
Have a great 2020!
Jim
—————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Business Owners, Planning, Retirement, Taxes
---
### [Target Date Funds - An Easy Answer?](https://indfin.com/target-date-funds-an-easy-answer/)
**Published:** September 19, 2013
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019aff2c9b18970d-320wi.jpg)The problem with easy answers is that easy answers aren’t always the best.** The investment industry has many product manufacturers eager to pounce on any rising investor concern with a convenient prepackaged answer that seems to solve their most pressing problem.
Many 401(k) participants seeking an easy way to pick the funds that will let them retire on a given date have jumped on[target-date funds](https://en.wikipedia.org/wiki/Target_date_fund "Target date fund")(TDFs) as the answer. These funds became available to investors as a qualified investment alternative under the[Pension Protection Act of 2006](https://en.wikipedia.org/wiki/Pension_Protection_Act_of_2006 "Pension Protection Act of 2006"); but, since the market losses of 2008, many have been wondering just how predictable achieving a successful retirement can be using TDFs.
What if, in 2008, you had been in a TDF with a target date of 2010 – just two years away? According to[Ibbotson](https://corporate.morningstar.com/us/documents/q4ibbotsontargetreport/maturityreportq42008.pdf "Ibbotson_TDF"), your losses could have ranged from -3.5% to -41.3%, depending on which 2010 TDF you chose.
When you think about it, a TDF isn’t much more than a “balanced fund” – I love that term; no one knows what it means – that is supposed to be continually rebalanced to a lower risk allocation as you approach retirement. But, if that’s all it is, why not just simply create your own allocation – using professional help or some sophisticated planning software, of course – and rebalance as you go through your periodic investment reviews?
Those approaching retirement often have substantial investments in TDFs. They may want to evaluate the suitability of their stock allocations. While many studies have indicated that stock allocations toward the higher end of the range offered in TDFs provide better retirement outcomes, many may be concerned about short-term volatility, giving them a ride they may not enjoy. Meanwhile, the decreasing equity allocations over the course of retirement, while it may feel comforting, doesn’t appear to improve retirement outcomes.
Those investors may find fixed annuities might serve as bond substitutes and also reduce the risk of outliving one’s savings. Substituting fixed annuities for bonds can reduce overall volatility and thereby support higher stock allocations without undue risk of failure.
Remember, characteristics such as age, marital status, required withdrawal rate, and other sources of income such as Social Security must factor into what works best in individual cases.
Jim
—————-
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk)(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist)(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights)to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
*Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [The Secret To Saving Money on Health Insurance: Buy Smart!](https://indfin.com/the-secret-to-saving-money-on-health-insurance-buy-smart/)
**Published:** September 12, 2013
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b0192ac851ba2970d-320wi.jpg)While politicians continue to debate health care, many people are worried about how to afford it.**
Health insurance has been a hot topic ever since costs began rising faster than inflation – certainly long before the debate began over the Healthcare Reform Act, now referred to as Obama-Care. Today, as our population ages and health care costs continue to rise, more of us are wondering how to separate fact from fiction as the insurers continue to jockey for position in the marketplace.
This environment has lead to the creation of some myths, according to industry experts, that have left many consumers somewhat confused.
To sort out fact from fiction, I asked Brad Burch, District Manager of [Health Plans 4 Less](https://www.healthplans4less.com/), based in [Simi Valley, California](https://www.simivalley.org/ "Simi Valley, California"), to help clear-up some of the confusion and misconceptions. Brad and I are both members of The Simi Valley chapter of Business Network International (BNI), so I’m familiar with his work.
When it comes to saving money, Brad says it’s mostly about knowing HOW to buy. Most insurance products are bloated; and, sometimes, people are sold bells and whistles they really don’t need. It’s about smart buying and many people are simply overpaying.
**A Good Place to Start**
For example, according to Brad, a good starting place for savings is in avoiding the low co-pay trap. Low co-pays virtually always result in higher premiums; but those high premiums will almost always outweigh the difference in doctor visit charges. And, now with the new health care reform provisions in-place, all plans now cover your annual preventative care doctors visit for every member of your family.
**A Factor Few Consider**
Brad pointed out another misconception: Many people believe their plan will cover all their medical bills once the deductibles and co-insurance has been met. The reality is that besides the deductibles and co-insurance, which is typically between $4,000 and $7,000 out-of-pocket, there are other costs few people consider. For example, if someone were to have a prolonged illness like cancer, s/he can be out of work for months. Few people consider how their bills will get paid. The doctors and hospitals may be covered, but they can still go broke fighting the illness.
According to a Harvard Business School study, the number one reason for bankruptcy in America (55% of all bankruptcies) is people being out of work for extended periods due to a critical illness – believing that their health plan was enough.
**The Solution: Smart Purchasing**
Is the Government program the answer to all these problems? Maybe. Maybe not. The Healthcare Reform Act isn’t designed to be free or even close to 100% coverage.
While many will argue the eventual cost, the math is pretty simple: When you add 30 million people to the rolls and include coverage for pre-existing conditions for them, as well as everyone already in the marketplace, you’ve increased demand for services.
When there’s no expansion of the supply of new doctors – indeed, some are leaving or [changing their business models](https://archive.constantcontact.com/fs133/1107137833061/archive/1114250352956.html) – it becomes simple economics. Increased demand with static supply equals higher prices; and, as noted earlier, there’s still the lost wages issue many never address.
But, health insurance is expensive, isn’t it? Well, it depends on how you look at it. Bankruptcy is expensive, too! Not having it can prove financially disastrous.
Brad says, it’s all about knowing how to buy. The problem is many people simply overpay because they don’t know how to buy it! Health insurers love to sell us all kinds of ‘bells and whistles’ they say we need when we really don’t.
It pays to do your homework, and talk to an expert.
Jim
———————————
***Resources***
Health Plans for Less: [https://www.healthplans4less.com/](https://www.healthplans4less.com/ "HealthPlans4Less");
Brad Burch: (805) 876-4193
\[Note: IFG and HealthPlans4Less are notaffiliated and noreferral compensation agreement exists to provide a referral incentive.\]
IFG Report: [The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk) (registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist) (does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights) to IFG’s Ezine: IFG Insights
**Interested in becoming an IFG client?** Why play phone tag? [Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule your introductory call with Jim!") your 15-minute introductory phone call!
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on [Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Thinking of an indexed annuity? Why not just build your own?](https://indfin.com/thinking-of-an-indexed-annuity-why-not-just-build-your-own/)
**Published:** June 27, 2013
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019103500289970c-320wi.jpg)You’ve heard the annuity pitch. It says you can*participate*in market gains while being protected against loss! But do you really need to buy an annuity to do that?
To paraphrase Warren Buffett, theremay bejust too many mouths to feed between the investor and the investment; and all those mouths cost money.
Insurance companies don’t have a special market to invest in. They have to access the same markets you do; so, why pay them to do what you can do yourself?
This is a nifty little strategy I learned when I first entered the investment business more than two decades ago. In all fairness, there may be one reason to purchase an annuity, but I’ll get to that later. For now, here’s how you can create your own.
Let’s say you’d like to invest $100,000 for ten years. You’re willing to pursue a strategy that allows you to invest some of it in the market, but you want a guarantee that ten years from now, you won’t have a loss.
So, first, as I write this, the 10-year U.S. Treasury is yielding 2.19%.[You can check current rates now](https://www.treasury.gov/resource-center/data-chart-center/interest-rates/Pages/TextView.aspx?data=yield "Treasury Rates").
What amount do you have to invest in 10-year Treasuries today at 2.19% so that the bonds will mature at $100,000 ten years from now? According to my trusty HP-12C, it’s $80,522– I won’t bore you with the pennies. We’ll put the remaining $19,478 into stocks or something that replicates an index, like an S&P 500 Index fund or ETF (you can’t invest in an index itself).
Of course,*anything*can happen in the stock market. Here are three hypothetical outcomes – the real world is bound to be different (it always is):
1. **You lose half your money**. You get $9’739 back from your stocks and $100,000 from your treasury for a total of $109,738. Not very good, but at least you have your money with a little profit.
2. **Your stocks go nowhere.** You end-up with $100,000 from your Treasury and $19,478 in stocks: Total: $119,478 . Still not great, but you did average 1.8% per year on your money.
3. **Your stocks go up**.Let’s assume 9% a year – an assumption everyone on the planet thought reasonable until the `meltdown’ of 2008 destroyed all the averages. At that hypothetical rate – not unreasonable, but who can predict? – you’d end-up with $46,111 in stocks to add to your $100,000 in maturing Treasuries. Total: $146,111 –an average annual compounded return of 3.86% on the total portfolio.
Not bad, considering you’ve eliminated your risk of loss!
“But Jim”, you say, “Annuities are tax-deferred!”
Yes,they are. But, when you take your money out, it’s taxed at ordinary income tax rates! Stock dividends get favorable tax treatment. Not only that, but if you die first, the cost-basis is stepped-up for your heirs so they don’t pay tax on all previous gains. And, if you need your money earlier, there are no surrender charges!
How about the insurance company guarantee? I like the Treasury `guarantee’ better – I use quotes only because the word `guarantee’ doesn’t appear anywhere on a Treasury or any other government note, bill, or bond. The wording is, `backed by the full faith and credit of….’. Nevertheless, it’s a better guarantee. We’re not Greece, yet. Remember, an annuity is basically an insurance company’s I.O.U.
The strategy and figures discussed above do not take into account taxes or inflation – the latter being the huge, hidden tax ignored by too many people. So, you shouldn’t pursue this, or any other, strategy without discussing this with your advisor first.
**Why would someone want to buy an annuity when they could just do it on their own?**
The insurance company will stick with the ten-year plan. Often the investor won’t.Manyinvestors often lack the discipline to stick with it a long-term process, especially if other more appealing-sounding alternatives grab their attention, particulary as surrender charges reach lower levels.
The drawback: Investors shouldn’t purchase anything unless you know how it fits-in with an overall plan! When it comes to comparing strategies, it’s the after-tax and after-inflation dollars – when the money isneeded – that counts.
Plan wisely!
Jim
**RESOURCES:**
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist)(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights)to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/ "The Independent Financial Group")
Follow Jim on Twitter:[https://twitter.com/JimLorenzen](https://twitter.com/JimLorenzen "Jim on Twitter")
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")[https://www.linkedin.com/in/jimlorenzencfp](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen on LinkedIn")
IFG on[Face book](https://www.facebook.com/IFGAdvisory "The Independent Financial Group on Facebook")
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,****a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Think Giving To Charity Steals From Your Heirs?](https://indfin.com/wealthreplacement/)
**Published:** February 3, 2020
**Author:** Jim Lorenzen
**Excerpt:** Giving to charity doesn't have to mean your kids get less. You might be able to make everyone happy... except Uncle Sam.
**Content:**
**Here’s a possible solution!**
**Jim Lorenzen, CFP®, AIF®**
Giving to charity can create significant tax advantages. Many people use real estate and securities to gain these advantages.
If you were to SELL an appreciated asset, the gain would be subject to capital gains tax. However, by donating the appreciated asset to a charity, however, you can receive an income tax deduction equal to the fair market value of the asset and pay no capital gains tax on the increased value.
**Example:** Alan purchased $25,000 of publicly-traded stock several years ago. That stock is now worth $100,000. If he sells the stock, he must pay capital gains tax on the $75,000 gain. However, Alan can donate the stock to a qualified charity and, in turn, receive a $100,000 charitable income tax deduction. When the charity then sells the stock, no capital gains tax is due on the appreciation.
This may create a problem, however. When Alan made this gift to charity, his family is deprived of those assets that they might otherwise have received.
**Potential solution:** In order to replace the value of the assets transferred to a charity, the Alan establishes a second trust – an irrevocable life insurance trust – and the trustee acquires life insurance on Alan’s life in an amount equal to the value of the charitable gift. Using the charitable deduction income tax savings and any annual cash flow from a charitable trust or charitable gift annuity, Alan makes gifts to the irrevocable life insurance trust that are then used to pay the life insurance policy premiums. At Alan’s death, the life insurance proceeds generally pass to the his heirs free of income tax and estate tax, replacing the value of the assets that were given to the charity. Not bad!
—————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Charitable Giving, Family Issues, Life Insurance, Planning, Retirement
**Tags:** charitable giving, trusts, wealth replacement
---
### [What (Many) Life Insurance Agents Won't Tell You.](https://indfin.com/what-many-life-insurance-agents-wont-tell-you/)
**Published:** April 15, 2015
**Author:** Jim Lorenzen
**Content:**
Jim Lorenzen, CFP®, AIF®
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017c37fc6922970b-320wi.jpg)First, let me state up-front that I AM a big believer in the power of life insurance, especially when designed as a financial tool using an “investment-grade” company in order to execute a larger financial plan.**
The fact is life insurance can do things for you – while you’re alive – that no other financial vehicle can do.
And, although being licensed myself as a California independent agent, there are a few things anyone considering a life insurance purchase should remember:
- **Be wary of a packaged solution.**Participating whole life and Indexed Universal Life can be designed as a financial tool to meet retirement income needs\*, but only as a component of a larger strategy, i.e., to supplement other income strategies.
- **Don’t believe beautiful illustrations**. Identifying an investment-grade insurance company means understanding the company’s own investment portfolio (this might be where an agent who is not only a certified financial planner, but also a Registered Investment Advisor, might come in handy).Before Executive Life of New York went under, they had over 50% of their portfolio invested in less than investment grade ‘junk’ bonds, despite the fact that in June 1987, the New York legislature had mandated that insurance companies licensed to business in that state were to limit their general portfolios to no more than a 20% allocation to such bonds. Remember, there are no guarantees; there are only guarantors.*\[Source: The New Insurance Investment Advisor, Ben G. Baldwin, McGraw-Hill 2002, p. 37.\].* When screening companies for my clients, I like to see what the company promised ten years ago vs. what their clients are actually experiencing today. Quality companies today generally create conservative projections, many using a 7% default rate. I usually ask them to use 6.5%. It’s not as pretty, I know; but, the probability of an unpleasant surprise drops dramatically.
- **Most of the well-known rating agencies we’re familiar with are actually paid by the insurance companies they rate.** Little wonder many insurance companies that failed during the big ‘melt-down’ actually had good ratings when they went under.While I do check all those agencies, my ‘go-to’ is Weiss, which receives no money from the insurance companies they rate; they’re paid by customers who access their ratings. Like Consumer Reports, their supported by subscribers, not advertisers.Their ratings are called ‘safety ratings’ and they seem to be a little more stringent. For example, according to the September 2002 Insurance Forum, of 1,221 life and health companies rated by Weiss, only 3.9% of companies made it into the ‘A’ category. Compare that with the 54.9% rated ‘A’ by Standard and Poor’s. At Moody’s, 90% of their list made it to ‘A’ that year. A.M. Best gave ‘A’ to 56.3% of the companies they rated. With Weiss, a B or B+ rating can still be regarded as a strong company.
- **Company strength is more than assets.** It’s about liabilities and the investment portfolio, too.Remember, insurance benefits, including claims and/or loans you may use for income, are paid from the general investment portfolio of the company – money that came from deposits required to provide pure insurance protection. So your safety is as good as the safety of the insurance company’s investment portfolio. Again, being able to understand the company’s investment portfolio – and history – is critical.
Hope this helps!
Jim
\* I’ll be conducting a webinar (my first) on this topic on April 22nd and 25th. You’ll likely hear more about it next week.
\*\* Today, many quality companies are using 7% as their default for creating illustrations. While I feel 7% can be considered a responsible, conservative figure, I personally like to use 6.5%. It won’t look as rosy, I know; but, you have a higher probability of never facing an unpleasant surprise.
————-
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20)!
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Life Insurance
---
### [What's So Great About a Rollover?](https://indfin.com/whats-so-great-about-a-rollover/)
**Published:** March 20, 2014
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73dd6f67e970d-320wi.jpg)Itdepends on how you do it!**
Changing or leaving a job can be a tumultuous experience. Even under the best of circumstances, making a career move requires a series of tough decisions, not the least of which is what to do with the funds in your old employer-sponsored retirement plan.
Some people choose to roll over these funds into an Individual Retirement Account, and for good reason. More than 25% of all retirement assets in the U.S. are held in IRAs, and more than 50% of traditional IRA owners funded all or part of their IRAs with a rollover.¹,²
Generally, you have three choices when it comes to handling the money in a former employer’s retirement account.
- You can cash out of the account. However, if you choose to cash out, you will be required to pay ordinary income tax on the balance plus a 10% early withdrawal penalty if you are under age 59½.
- You may be able to leave the funds in your old plan. But some plans have rules and restrictions regarding the money in the account.
- You can roll the money into an IRA. Why do so many people choose an IRA rollover? Here are a few of the major benefits:
Rollovers may preserve the tax-favored status of your retirement money. As long as your money is moved through a direct “trustee-to trustee” transfer, you can avoid a taxable event.³ In a traditional IRA, your retirement savings will have the opportunity to grow tax-deferred until you begin taking distributions in retirement.
An IRA rollover may open up your investment choices. When you stick with your former employer’s retirement plan, you are typically limited to the investments offered by the plan. With an IRA, you may have a much broader range of choices, giving you greater control over how your assets are allocated.
Rollovers can make it easier to stay organized and maintain control. Some people change jobs several times during the course of their careers, leaving a trail of employer-sponsored retirement plans in their wake. By rolling these various accounts into a single IRA, you might make the process of managing the funds, rebalancing your portfolio, and adjusting your asset allocation easier.
An IRA rollover may make sense whether you’re leaving one job for another or retiring altogether. But how your assets should be allocated within the IRA will depend on your time horizon, risk tolerance and financial goals.
IRA rollovers shouldn’t be taken lightly. You may benefit from a report I created some time back entitled, “*[Six Best Worst IRA Rollover and Decisions](https://tinyurl.com/IRARolloverDecisions)*“.
Enjoy,
Jim
*1.2012 Investment Company Factbook*
*2.Distributions from traditional IRA and most other employer-sponsored retirement plans are taxed as ordinary income and, if taken before age 59½, may be subject to a 10% federal income tax penalty. Generally, once you reach age 70½, you must begin taking required minimum distributions.*
*3.The information in this material is not intended as tax advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult a tax professional for specific information regarding your individual situation*.
*The content is developed from sources believed to be providing accurate information. The information in this material is not intended as tax or legal advice. It may not be used for the purpose of avoiding any federal tax penalties. Please consult legal or tax professionals for specific information regarding your individual situation. This material was developed and produced by FMG Suite to provide information on a topic that may be of interest. The opinions expressed and material provided are for general information, and should not be considered a solicitation for the purchase or sale of any security. Copyright 2013 FMG Suite.*
*—*
**RESOURCES:**
IFG Report: [The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk) (registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist) (does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights) to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
[The IFG Managing Life’s Risks Website](https://finsecurity.com/Lorenzen)
Follow Jim on Twitter:
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on [Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
The [Joint Committee on Taxation](https://www.jct.gov/resources.html)
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***[](https://indfin.com/wp-content/uploads/2014/03/6a017c332c5ecb970b01a51174caed970c-120wi.jpg)Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,**a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
[](https://indfin.com/wp-content/uploads/2014/03/6a017c332c5ecb970b01a51174cbb0970c-120wi.jpg)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Losing A Spouse Can Be Expensive...](https://indfin.com/widowstax/)
**Published:** January 6, 2020
**Author:** Jim Lorenzen
**Excerpt:** Few people think about this – and I wish I could be the smart guy that thought of this for this post, but I wasn’t . It’s something called the widow’s penalty tax; it affects the surviving spouse.
**Content:**
****[](https://indfin.com/wp-content/uploads/2016/10/Checkbook-Pen.jpg)… you could get hit with the widow’s penalty tax!****
Few people think about this – and I wish I could be the smart guy that thought of this for this post, but I wasn’t[\[i\]](#_edn1). It’s something called the widow’s penalty tax; it affects the surviving spouse.After a spouse’s death, the survivor usually goes from a joint return to filing as a single filer, usually resulting in an increase in the survivor’s tax bracket. This happens because often the survivor’s income can be almost as much as they were filing when using a joint return – Bingo! – a large tax bill. One advisor’s client went from a 24% bracket (filing jointly) to a 32% bracket as the survivor[\[ii\]](#_edn2)**How to protect yourself?**
A series of partial IRA conversions (to Roth IRAs) over several years, keeping the amounts low enough not to change your tax bracket, can help. Do this after age 59-1/2 but before taking Social Security benefits. The distributions will avoid the 10% penalty and, at the same time, take advantage of the low joint rate. By the way, it’s worth mentioning that the current tax law, which has lower brackets than prior law, sunsets in 2026, meaning brackets are set to return to their previous higher rates. Another benefit: the conversions will reduce your taxable income when you are forced to begin your required minimum distributions (RMDs) after age 70-1/2.
Good idea, huh?
Jim
```
[i] Donald Jay Korn, Financial Planning, August 2019
[ii] Bob Morrison, founder of Downing Street Wealth Management in Greenwood Village, Co., cited in the same article.
```
—————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
*Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues, Planning, Taxes
---
### [Worried About Living Too Long?](https://indfin.com/worried-about-living-too-long/)
**Published:** March 26, 2013
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017ee9006b18970d-120wi-1.jpg)Longevity risk**is getting a lot of attention these days, particularly with many of us living in the ‘sandwich generation’ – taking care of both elderly parents as well as grown children who’ve moved back in with their parents. As someone experiencing this first hand, I can tell you it’s an expensive proposition – particularly taking care of aging parents.
Now, a few companies are stepping up with insurance products to address longevity concerns…[longevity insurance](https://en.wikipedia.org/wiki/Longevity_insurance "Longevity insurance"). It’s called ‘longevity insurance’ because it’s basically protecting you if you live longer by allowing you to make a payment now for a large flow of income in your later years.
One company offers a”deferred income annuity”. From what I’ve read, it apparently now accounts for 35% of their overall income annuity sales from their agents. A recent[Wall Street Journal article](https://online.wsj.com/article/SB10001424052970204571404577253853314354494.html "WSJ - Longevity Insurance")on this product points out that, like animmediate income annuity, a longevity policy allows purchasers to convert a lump sum into a pension-like stream of income for life.
Other companies offer variations of this product, and each insurer has its own guidelines. It’s important to compare because start dates can vary widely.
**There’s one thing you shouldn’t forget, however: Inflation.**
We’re all living longer and inflation is sneaky. You may not think you or your spouse will live in retirement for 30 years, but what if you’re wrong? Odds are one, or both of, you will! Remember, the cost of a postage stamp, a convenient government barometer, was 20-cents in 1983. So, what may sound like a good income today may not be so good in future years. My dad retired in 1974. What was a considered a good income backthen wasn’t so hot during his last decade 1995-2005. While he did fine, that wasn’t true of many of his contemporaries.
The key: You have to do the math. You haveto have a plan. And, you should startearly.
**It’s about time.**
*[](https://jimlorenzen.typepad.com/.a/6a017c332c5ecb970b017ee9006d09970d-pi)*
**Additional IFG Links:**
Follow Jim on Twitter: @jimlorenzen
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Facebook](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
———————
***Jim Lorenzen is a[CERTIFIED FINANCIAL PLANNER](https://en.wikipedia.org/wiki/Certified_Financial_Planner "CFP")®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of[The Independent Financial Group](https://indfin.com/),**a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not providelegal or tax advice and nothing contained herein should be construed as securitiesor investment advice, nor an opinion regarding the appropriateness of anyinvestment to the individual reader. Thegeneral information provided should not be acted upon without obtainingspecific legal, tax, and investment advice from an appropriate licensedprofessional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [You Just Received an Inheritance? So did Uncle Sam!](https://indfin.com/you-just-received-an-inheritance-so-did-uncle-sam/)
**Published:** June 26, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a3fd22455b970b-320wi.jpg)
***The only difference between a taxidermist and a tax collector is that the taxidermist only takes your skin.***
***– Mark Twain***
Don’t try to keep your inheritance a secret from the IRS by sending them an email. There are other ways you might consider for reducing your tax exposure:
**Tax-managed mutual funds.** There are really only two ways these vehicles can attempt tax-efficiency – low turnover or offsetting gains with losses. It’s an option, but frankly not one of my favorites.
**Municipal bonds or municipal bond funds.** The interest on municipal bonds is usually exempt from federal taxes – and sometimes taxes at the state and local level, too. The higher your income tax bracket, the more you may benefit from owning “munis.”1; but, you need to do some math to compare taxable vs. tax-free yields. For example, someone in the 28% federal tax bracket would need to earn 4% % on a municipal bond to realize the same after-tax income as a 5.55% corporate bond would provide. There’s more, though: Financial stability. There are some California cities issuing bonds you may not want to buy.
**Consider tax-advantaged strategies.** While you can contribute up to $5,500 annually to an IRA plus an additional $1,000 per year if you’re over age 50 (for the 2014 tax year), and while IRAs offer tax deferral — you pay no taxes on earnings until withdrawal — and may provide tax deductions2 , they may be of limited help dealing with a large inheritance. It just might be that institutional money management with a tax-optimized strategy may make more sense; but, there are a lot of factors at play. That’s one conversation you need to have with your advisor.
**Take advantage of loss/gain tax rules.** Actually, this is akin the prior point. If you hold an investment for a year, you’ll be eligible for capital gains tax treatment – usually less than paying income tax rates, up to 39.6%, which would apply if you sell sooner. The same capital gains rate also applies for dividend income.3 As for positions with losses, sell by December 31 and deduct up to $3,000 in investment losses from that year’s tax return. Any excess losses can be carried over to future years and used to offset capital gains.
Some of this may sound simple; but, it’s not simplistic. And, you should get professional tax and investing advice before making any moves. Don’t rely on this, or any other, post for tax or investment advice. That’s best done first-hand with someone who knows you and your situation.
Jim
Notes:
1Income may be subject to the alternative minimum tax. Capital gains, if any, are subject to taxes.
2Withdrawals before age 59½ are subject to a penalty tax. Each type of IRA has respective income limits as well as deductibility rules.
3Lower rates apply for long-term capital gains and dividends for taxpayers who are in lower tax brackets. An additional 3.8% Medicare tax may also apply.
**RESOURCES:**
**Visit[Jim’s Social Security Learning Center](https://www.jlorenzen.sswise.com/ "Social Security Learning Center")**
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Conversation Checklist")(does not require registration)
[Subscribe to IFG Insights](https://tinyurl.com/IFGInsights "Subscribe to IFG Insights")
[The IFG Website](https://indfin.com/ "IFG Website")
IFG’s[Financial Resources website](https://finsecurity.com/Lorenzen "IFG Financial Resources Website").
Follow Jim on Twitter: @JimLorenzen
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
**Become an IFG client!**Don’t play phone-tag; schedule your 15-minute introductory phone call using[this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,****a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Your Doctor's Business Model May Change Soon](https://indfin.com/your-doctors-business-model-may-change-soon/)
**Published:** August 15, 2013
**Author:** Jim Lorenzen
**Content:**
**Many doctors are overworked and making less. Now, with Medicare reimbursement revenue being cut, new business models may be on the way.**
As medical costs have risen, insurance companies have taken steps to reduce their exposure, putting a cap on a physician’s income. At the same time, doctors have seen their costs rise without caps, i.e., rent, utilities, medical and office supplies, wages for office staff, and, of course, insurance costs, including malpractice.
It was only a few years ago my own doctor – I’m on my second one now, but I’ll get to that – sent a letter to all his patients, me included, that he was leaving the practice of medicine. He was tired of working day and night while watching his margins get thinner and thinner. There just weren’t any more hours in the day and it was no longer worth it to him. He took an administrative position with a medical facility in another state.
His practice was taken over by my current physician who, on more than one occasion over the past several years, has confided to me the following:
- He works from 7 a.m. to almost 10 p.m. most days.
- He hasn’t had dinner with his family in so long he can’t remember the last time
- His children don’t know him – I’m sure it’s just a figure of speech, but it makes the point.
About six months ago, he flew a ‘trial balloon’ past me: He was thinking his business model. He could no longer continue working day and night trying to serve 1,000+ patients. It’s too hard to spend quality time with that many people for less and less money. He wanted a business model that would allow him to reduce his patient load, increasing the time he could spend with each, and at the same time be able to make a decent living while getting back to a normal life style – who can blame him?
The model was simple: Limit his patient load to 400-600 who are willing to pay an $1,800 annual retainer, which could be paid monthly, quarterly, or annually. It doesn’t affect any insurance or anything else; but, it does give the patient easier access for quality care – same day or next-day appointments, less-to-no waiting, more time with the physician, a pro-active wellness program instead of diagnose and treat, 24-hour physician access, personal client websites and easy access to health records, and more, including screenings, physicals, etc.
Last week, during a routine checkup, he announced he’s making the change effective in October. His membership practice is being coordinated by [MDVIP](https://www.mdvip.com/), an organization that provides administrative, as well as additional medical resources support.
This is likely the trend we’re about to see in the medical industry, as well as others. Even many independent Registered Investment Advisory (RIA) practices across the U.S. have now instituted financial planning retainer programs to offset the reduced margins resulting from the fee compression pressures that have forced minimum account size requirements to move higher.
If your doctor hasn’t said anything to you, yet, he soon might. Thought you’d like to know.
Jim
—————
**RESOURCES:**
IFG Report: [The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk) (registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist) (does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights) to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on [Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
**Interested in becoming an IFG client?** Why play phone tag? [Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!") your 15-minute introductory phone call!
*Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of* [*The Independent Financial Group*](https://indfin.com/)*, a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Retirement Planning Dilemma](https://indfin.com/retirement-planning-dilemma/)
**Published:** July 29, 2014
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73df22bdd970d-320wi.jpg)Retirement planning is becoming increasingly difficult for many pre-retirees**; and it’s virtually ignored among the young – so, what else is new? Expectations may a part, but there’s more.
One cause of the problem, of course, rests with advisors themselves. According to Phoenix Marketing International, only one-third of all households feel that financial firms look out for their best interests.
Can you blame them? Many, if not most, in the brokerage industry have been fighting a move to hold their reps to the same standard as [registered investment advisors](https://en.wikipedia.org/wiki/Registered_Investment_Advisor "Registered Investment Advisor") (RIAs). Their reps, who most of us refer to as ‘brokers’ – it’s really the firm that’s the broker, but I digress – operate under a ‘suitability’ standard; and, their recommendations are merely “incidental” to the product sale, not really advice. That’s quite different from the fiduciary standard required of all RIAs which mandates that the client’s best interest must be the sole consideration and any recommendation is considered advice. That’s about as far into the weeds as I dare go – I’m not an attorney and I don’t even play one on tv. And, it was just recently that congress voted down the fiduciary standard being extended to broker-dealers – I’ll leave it to you to figure out why.
There’s another converging force in this perfect storm leading to retirement insecurity: According to a well-written article by Mark Tibergien in this month’s *Investment Advisor*, only 14 states require a high school course in personal economics. He further states that even in those states where the course is offered (as an elective), the schools are having difficulty finding both qualified teachers who can teach the material and students interested enough to sign-up.
This isn’t new. Mr. Tibergien points out that almost half of the adults who do closely monitor their finances say they learned about personal finance from their parents or at home.
The problem exists partly because of the media, too. I actually re-tweeted a post a few weeks ago with advice from a financial writer about how to pick an advisor. One of the top criteria was to check for the advisor’s investment track-record against the market indexes. Did the advisor constantly outperform? Huh? My re-tweet contained a caveat for older investors.
People read this stuff and blindly follow this rather dubious advice, never stopping to think that one advisor may serve young investors, while another my specialize in older investors more concerned about wealth preservation, a strategy designed to protect against downside exposure while they’re drawing income. These clients have minimal market exposure and, indeed, don’t want to even try beating it. Still, some people in their 50’s and 60s, especially those who’ve done insufficient planning in the past, may see this ‘compare performance’ advice is logical, even if uneducated. Do the writer really think my 85-year-old should be chasing market performance?
Let’s face it. Managing money is something everyone thinks they can do, even without formal education, training, experience, or sophisticated tools, simply because we’ve been making, and handling, money all our lives! We’ve made big decisions (cars, homes, vacations) and we’re not eating dog food! Never mind we can’t calculate the time-value of money or dollar-weighted returns. Never mind that [Monte Carlo simulation](https://en.wikipedia.org/wiki/Monte_Carlo_method "Monte Carlo method") sounds more like a casino than the calculation of outcome probabilities. We’re still doing fine and nothing’s broken so far.
Unfortunately, too many will reach their second (and third) decade of retirement in financial distress, and thinking no one could have done it any better. They’ll never know. No one taught them.
Jim
——
**Visit** [**Jim’s Social Security Learning Center**](https://www.jlorenzen.sswise.com/ "Social Security Learning Center")
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Conversation Checklist") (does not require registration)
[Subscribe to IFG Insights ](https://tinyurl.com/IFGInsights "Subscribe to IFG Insights")
[The IFG Website](https://indfin.com/ "IFG Website")
IFG’s [Financial Resources website](https://finsecurity.com/Lorenzen "IFG Financial Resources Website").
Follow Jim on Twitter: @JimLorenzen
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of* [*The Independent Financial Group*](https://indfin.com/)*, a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Retirement Planning and The Fiduciary Standard](https://indfin.com/retirement-planning-and-the-fiduciary-standard/)
**Published:** July 11, 2013
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01901dd12617970b-320wi.jpg)“Will your interest be placed first?”**
There are lots of good brokers and investment advisors, but it’s up to you to ensure your interest is protected. Although there are no guarantees, one way of mitigating the risk of conflicting advice is to**have your financial advisor sign the ProspectiveClient Disclosure Form**developed by the Center for Fiduciary Studies. You can[Download PROSPECTIVE CLIENT DISCLOSURE FORM](https://jimlorenzen.typepad.com/files/prospective-client-disclosure-form-1.pdf)here.
**Planning your retirement?**
I often include tidbits from*Money Magazine*and the recent “[Six Secrets of Retirement](https://money.cnn.com/2013/02/18/retirement/investments-stocks-funds.moneymag/index.html "Money Magazine's 6 Secrets to a Successful Retirement")” is a story worth reading!
**Is it Getting Late?**
Back in the late 1990s I would visit my retired parents in Florida every year. I could see they were beginning to decline, and my wife and I both invited them to come to California to live with us. They, of course, wanted to remain independent. I remember telling them, “Don’t wait until you can’t before you have to.” While I guided my father’s investments and told him what to do, (i.e., meet with a local estate planning attorney, etc.), I didn’t want him to feel I was being pushy. Dad was ahighly intelligent and had been a highly successful electrical engineer, so I thought he was doing the right things. He wasn’t – and when the time came, I ended-up having to ‘sort-it-all-out’ in the midst of dealing with his lung cancer and mom’s Alzheimer’s while selling their home and orchestrating their move to our home in California.
Why am I telling you this? If you haven’t “had the talk” with your parents, you can never start too soon.
**Want to know how?**
Financial writer Jack Tatar wrote an excellent book,”***Having The Talk***“; I heartily recommend it, and you can purchase it in paperback on Amazon, as well as through most book sellers.
Enjoy!
Jim
————-
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk)(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist)(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights)to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,****a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Retirement Planning and Medicaid Maneuvers](https://indfin.com/retirement-planning-and-medicaid-maneuvers/)
**Published:** August 5, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a3fd3741a4970b-320wi.jpg)
**Show me a retirement problem and I’ll show you someone with a planning solution packaged to solve it.**
Unfortunately, too many people jump at great sounding packaged solutions without doing their homework.
In recent years, Medicaid Planning has taken center stage, particularly in the insurance community. And, it’s no surprise. Many people are concerned about having enough money to live on and the idea of spending down all of their assets to pay for long-term care. Many will establish certain types of entities like trusts, give cash gifts to children, spend money on exempt assets or engage in other legal financial maneuvers.
There’s no end to the ideas floating around; but, it’s important to be sure the financial activities these people, usually boomers, are considering are legal, in addition to being smart. But, even when using perfectly legal activities, they still may compromise or delay some of their potential benefits from Medicaid.
Medicaid has something called “the look-back period”. What that means is you’ll have to disclose, on the application required to collect Medicaid benefits, answers to extensive questions about your financial assets going back from three to five years. Medicaid will “look back” to see whether assets had been illegally sheltered in order for the applicant to qualify for coverage.
No surprise. Legal moves are permitted; however, transfers that took place during that look-back period will be scrutinized. Even if they are deemed legal, they may incur some penalties. For example, if you apply for Medicaid and had made an asset transfer (a gift, transfer into a trust, or other large transaction) within the look-back period, it may not necessarily disqualify you from receiving benefits, but it may delay the date when nursing home benefits begin. Home care benefits are not affected by the look-back period. There are many strategies for legally moving assets and timing the submission of a Medicaid application.
Best advice, talk with your estate planning attorney before making a move. If s/he suggests a strategy you like, then it might be time to bring in a qualified financial advisor for the implementation stage.
Jim
—-
**RESOURCES:**
**Visit** [**Jim’s Social Security Learning Center**](https://www.jlorenzen.sswise.com/ "Social Security Learning Center")
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Conversation Checklist") (does not require registration)
[Subscribe to IFG Insights ](https://tinyurl.com/IFGInsights "Subscribe to IFG Insights")
[The IFG Website](https://indfin.com/ "IFG Website")
IFG’s [Financial Resources website](https://finsecurity.com/Lorenzen "IFG Financial Resources Website").
Follow Jim on Twitter: @JimLorenzen
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of* [*The Independent Financial Group*](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
– See more at: https://www.jimsmoneyblog.com/2014/08/retirement-planning-and-medicaid-maneuvers.html#sthash.hqy8mUJ9.dpuf

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Retirement Planning and Denial](https://indfin.com/retirement-planning-and-denial/)
**Published:** August 7, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73df3aa85970d-320wi.jpg)
Are boomers in denial when it comes to retirement planning? While we’ve covered the state of financial illiteracy previously, denial is also all to rampant.
Take a look at the following. I want to state up-front that I didn’t write the two paragraphs and I’m embarrassed to say I don’t know or remember where I found it – so my apologies to whoever it might be that I’m plagerizing; but, I thought you might find it interesting.
*About 15 years ago, it was reported that as a generation boomers had tended to avoid discussions and planning for their demise and avoided much long-term planning. However, there has been a growing dialogue on how to manage aging and end of life issues as the generation ages. In particular, many argued that Baby Boomers were in a state of denial regarding their own aging and death, thus leaving an undue economic burden on their children for their retirement and care.*
*One book, written by Colorado doctor Terry Grossman, titled, The Baby Boomers’ Guide to Living Forever, proposes how baby boomers might avoid death. On page 3 of the book, Grossman writes, and not ironically: As an official member of the Baby Boomer Generation, I really and truly do not believe that it was intended for us to die. Death, if and when it occurs, clearly will represent a mistake of some kind.*
Interesting, huh?
Jim
**RESOURCES:**
**Visit** [**Jim’s Social Security Learning Center**](https://www.jlorenzen.sswise.com/ "Social Security Learning Center")
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Conversation Checklist") (does not require registration)
[Subscribe to IFG Insights ](https://tinyurl.com/IFGInsights "Subscribe to IFG Insights")
[The IFG Website](https://indfin.com/ "IFG Website")
IFG’s [Financial Resources website](https://finsecurity.com/Lorenzen "IFG Financial Resources Website").
Follow Jim on Twitter: @JimLorenzen
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Would You Build A House Without a Blueprint?](https://indfin.com/planningincrisis/)
**Published:** May 4, 2020
**Author:** Jim Lorenzen
**Excerpt:** If you're receiving Social Security, Pension, or other guaranteed income, you may want to rethink how your nest-egg is arranged for long-term inflation risk.
**Content:**
I wouldn’t. I also wouldn’t be driving in a strange city without a GPS.
**[](https://indfin.com/wp-content/uploads/2019/10/Fotolia_3956379-Overwhelmed.jpg)Jim Lorenzen, CFP®, AIF®**
It looks like the COVID-19 issue is going to be with us for awhile; the U.S. is still seeing over 25,000 new cases each day and some medical experts think we’re in a two-year process, which makes some sense considering the time it takes to get a vaccine into mass distribution, as well as getting the public to embrace it the way they did the polio vaccine in the 1950s.
Congress, of course, has been passing relief measures which, among some, are raising concerns about the national debt which now stands around at 100% of GDP while unemployment payments in excess of normal wages are creating a disincentive for some Americans to return to work until August, when those benefits are due to expire.
We’e in, of course, an ‘event-driven’ bear market which some would call a structural bear in that it is the result of a government-induced forced shut-down. Given that about 70% of our economy is driven by the consumer and no one knows when they will feel safe enough to work, shop, travel, and go to sporting events (a $12-billion industry) – not to mention the achievement of mass innoculation; some experts believe that the bear could last as long as 42 months.
Whenever economic crisis occurs – and it has on numerous occasions throughout history – the lesson comes home that building a financial house without a blueprint makes for bad construction and a poor outcome. That blueprint, of course, is a financial plan that serves as the foundation for an investment process – and a process is not a group of transactions. Today, of course, those who’ve done it the right way are seeing the value, and the power, of having a model to follow and stay within.
If you have a plan, make sure you keep it updated. If not, maybe it’s time to begin one. If you’d like some help, you can [begin your process here](https://indfin.com/getting-started/).
Jim
————————————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, investment planning, Investment Strategy, managing risk, Reducing Risk
---
### [News and Markets Make You Worry?](https://indfin.com/news-and-markets-make-you-worry/)
**Published:** March 18, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi3.jpg)Jim Lorenzen CFP® AIF®When I first entered this business back in 1990, most people were watching financial tv shows – virtually all of which were covering mutual funds in those days. It seemed everyone wanted to buy mutual funds!
In a way, it made sense. In those days, the large baby-boom demographic bubble was largely made-up of people who were accumulating and in their peak earning years. Now, however, the story is different.
Growth with some risk seemed okay. Retirement was still a long ways off. But, today, the story has changed. Baby-boomers are getting closer to retirement and other issues are more important: Security and predictability.
If those issues are important to you, you may enjoy readingour[IFGi\_Report\_Let’s Review](https://indfin.com/wp-content/uploads/2015/03/IFGi_Report_Lets-Review.pdf)that may help put things in perspective for you. Enjoy!
Jim
———————-
**[Learn more about IFG here!](https://indfin.com/video-library-2/ "Jim Lorenzen talks about the IFG Difference")**
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20)!
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Are the Markets On Their Way Back?](https://indfin.com/newmarkets/)
**Published:** April 20, 2020
**Author:** Jim Lorenzen
**Excerpt:** Increased debt, the worry of a debt spiral, low yields, and future taxes - all make a solid plan more important than ever. Unfortunately, too many put it off until the're "confident', but they never get there.
**Content:**
Markets always do; but strategies in the future will have to be different.
[](https://indfin.com/wp-content/uploads/2014/09/iStock_62491112_XXXLARGE.jpg)iStock Images**Jim Lorenzen, CFP®, AIF®**
Maybe. You might think so.
While the S&P was down 10.5% year-to-date as of Friday, it’s still UP 1.1% for the last 12 months while foreign stocks actually lost 13.1%. Who’d a thunk it? And, the real surprise is the NASDAQ index of small stocks, down only 3.3% for the year and actually UP 9.3% for the last 12 months as of Friday’s close[\[i\]](#_edn1). The 10-year Treasury has gained 17.9% as the yield plummeted to just 0.65%[\[ii\]](#_edn2).
The core consumer price index (CPI) is holding at 2.1%[\[iii\]](#_edn3); but, as we see huge stimulus spending driving up the debt, the inevitable result may be too much money chasing too few goods and services, thus driving up inflation – an argument to get the economy moving again in order to drive up production while increasing the job numbers and sources of revenue. Debt as a percentage of the GDP will be the key figure to watch.
A key worry is a debt spiral. Treasury secretary Mnuchin is already trying to fund the growing budget deficit – the $2.2 trillion stimulus package is the largest ever passed. John Briggs, head of strategy for the Americas at Natwest Markets, thinks the sheer amount of debt coming is really a war-time sort of funding.
The government has been selling short-term debt (Treasury bills that mature in one year or less) virtually as fast as possible – and more is coming.
The fiscal 2020 deficit – a deficit that needs to be funded somehow – will be four times as large as last year’s $3.8 trillion – almost 19% of GDP, according to the Committee for a Responsible Federal Budget, a non-partisan group. Few on ‘the hill’ see a need for caution right now, given the threat of the virus, but there is little doubt corrective action will be on the horizon.
Economists at JPMorgan Chase & Company say GDP will shrink an annualized 40% in the second quarter, according to a feature in Bloomberg News. That, of course, means a huge amount of debt is coming in the second quarter.
Having a solid formal financial plan with the right allocation is now more important than ever. The markets will come back, but because of the CARES Act and the SECURE Act – and added market volatility – the strategies that used to work are now changing.
Jim
*\[i\] Source: MacroBond Financial AB. S&P 500 is represented by the S&P 500 Index, DJIA is represented by the Dow Jones Industrial Average, NASDAQ is represented by the NASDAQ Composite Index, Foreign Stocks are represented by the MSCI EAFE Index and Emerging Markets are represented by the MSCI Emerging Markets Index. Sectors based on S&P 500 Index sector indexes. You cannot purchase an index.*
*\[ii\] Source: MacroBond Financial AB, Morningstar Inc., Bloomberg LP. 10-Yr Treasury is represented by the MacroBond 10-Year Treasury Bond Index.*
*\[iii\] Source: MacroBond Financial AB, Federal Reserve (Fed Funds Rate), US Department of Labor (Inflation and Unemployment) and US Bureau of Economic Analysis (GDP).*
——-
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Economy, IFG Viewpoint & Outlook, Inflation, Investing, Planning, SECURE Act
**Tags:** Coronavirus, Financial planning, investment planning, Investment Strategy, Taxes in retirement
---
### [Market Crisis in Perspective](https://indfin.com/marketperspective/)
**Published:** March 10, 2020
**Author:** Jim Lorenzen
**Excerpt:** It's good to have some perspective.
**Content:**
**A Picture is worth…. you know.**
**Jim Lorenzen, CFP®, AIF®**
**Is the media overplaying the stock market pullback?**
No more than usual. This has all happened before – just different story lines. Take a look at the following charts from JP Morgan:
[](https://indfin.com/wp-content/uploads/2020/03/Stock_Market_and_Crisis_since_1900.png)
How long do these downturns last?
[](https://indfin.com/wp-content/uploads/2020/03/Bear_Markets_and_Subsequent_Bull_Runs.png)
Last week someone asked me (some people think all advisors are stockbrokers) whether he should be in or out of the market.
Jim
—————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** investment planning, Investment Strategy, retirement decisions, Retirement Planning, Retirement Strategy, understanding investment returns
---
### [March 2015 IFG Viewpoint & Outlook](https://indfin.com/march-2015-ifg-viewpoint-outlook/)
**Published:** March 5, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2015/03/IFG-2015-March_001.png)
Here’s IFG’s March 2015 Viewpoint and Outlook.
It should serve as a “heads up” for those of you over age 50, for whom retirement planning is becoming an issue.
Just click on[IFG 2015 March](https://indfin.com/wp-content/uploads/2015/03/IFG-2015-March.pdf).
Enjoy!
Jim
—————-
You can find some useful Life Guides and Worksheets [here](https://finsecurity.com/Lorenzen "IFG Resource Center").
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook
---
### [Make Your Own Pension](https://indfin.com/make-your-own-pension/)
**Published:** August 12, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73df22bdd970d-320wi.jpg)Jim Lorenzen, CFP®, AIF®
Wouldn’t it be comforting to know you’re retirement is assured? An income you can’t outlive does have appeal. People who retire from the government have a steady income stream. They don’t have to manage portfolio withdrawals with actuarial precision in a world where change is a constant.
It’s no wonder that a Towers Watson survey found that retirees relying on pension or rental income are less anxious than those living off investments. Of course, those living off rental income aren’t really retired – they’re in the real estate rental business; but, that’s another story.
People can pay cash for a retirement income, however. According to a story in the current issue of Money[\[i\]](#_edn1), a 65-year old man can buy a $500 monthly income for life with $100,000. It’s called an immediate fixed annuity. Heck, that’s $6,000 a year! It is taxable, but it’s also likely more than your investments pay on an after-tax basis, even if you were to take it all in capital gains.
If you have some expenses that are guaranteed to be there forever, add them up and see how much they come to each year. Subtract the amount you receive from Social Security, and the remaining gap is the amount of guaranteed income you may want to consider purchasing.
Of course, you don’t have to buy all of it. You may want to buy a portion of it, to start out, if getting comfortable with the idea is a challenge. You can also purchase immediate annuities from more than one insurance company.
While immediate fixed annuities can provide a guaranteed income for life, the income is taxable; but, that’s what happens if you wait until retirement to buy one.
If you begin planning early – in your 40s and 50s, even up to age 60 – you might be able to arrange for an income tax-free retirement income and never have to worry about what the politicians will do to your taxes again. According to David McKnight’s book, *The Power of Zero*, endorsed by CPA Ed Slott, it’s a strategy being used by 85% of Fortune 500 CEOs and many members of Congress.
I’ve written a report about it that’s free for those who would like to receive our ezine, IFG Insights. You can get the report here.
[](https://indfin.com/taxfreeretirementreport%20)
Enjoy!
Jim
[\[i\]](#_ednref1) “*Don’t Shortchange Your Retirement*” by Donna Rosato, Money.com, August 2015.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
**Tags:** Guaranteed Income, Income Annuities, Retirement Annuities, Retirement Income, Retirement Strategy
---
### [Looking to Sell Your Business?](https://indfin.com/looking-to-sell-your-business/)
**Published:** April 9, 2013
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017c384a4369970b-320wi.jpg)Do you know the true value of your business?**Business valuation isn’t as easy as assigning a multiple, and finding a buyer isn’t as easy as placing an ad.
Selling your business isn’t easy. If I had to take a guess, I’d be willing to bet that 90% of all business owners have never sold a business before; and most, if not all, of them have more than 80% of their net worth tied-up in their own businesses. When you think about it, it’s scary.
More than thirty-five years ago, I launched a weekly publication with little more than a typewriter – ask your father – and a bottle of ‘white-out’. With a combination of luck and a lot of hard work, I was able to sell it six years later to a buyer who had just left his position with a local daily paper.
I was lucky. There was a industry-savvy buyer with money, locally, just as I was ready to sell. This rarely happens, of course, but I also had done a few things right along the way that made the business worth buying… it had value.
How do you know the true value of your business? The only time you’ll know for sure is AFTER the sale, because the true value is only what a buyer is willing to pay. Reality: The ‘asking price’ is meaningless.
But, before you spend between $5,000 and $25,000 or more on a certified valuation, you may want to just go through this checklist:
1. **Can your business operate without you?**If not, you don’t own a business, you own your job. A true business keeps operating, and making money, even if you’re sick or on an extended vacation. To have value, the business shouldn’t need you. Early in my publishing career, I had read Robert Townshend’s*Up the Organization*; That’s when I knew how important this was.
2. **Do you have documented operating systems in place?**If you’re away (see #1) and a team member leaves, can your business continue functioning with a replacement? Do you have a “how to” manual for each business function? I was lucky I had worked for a company that had a great manual, and I had worked on the rewrite; so, I duplicated those efforts in my own business.
3. **Are your revenue sources diversified?**You don’t want a huge chunk of your revenue coming from a single customer; if they leave your business may cease to exist! Our publications focused on the ‘bread & butter’ advertisers, which turned out to be a winning idea.
4. **Does your business have a recurring revenue stream?**Does this recurring revenue account for 10% of revenue or 95%? That makes a difference. Subscriptions are better than re-orders. Is the recurring revenue tied to a personal relationship or something less dependent (see #1)? A buyer will expect those revenues to continue. In our case,a large number of”bread & butter” advertisers and a few big names that comprised less than 10% of total revenue were ALL under long-term contracts. We had NO one-time ads. Our buyer couldn’t believe it! What’s more, we had zero delinquency and no collection problems.
5. **Do you have a solid management team?**The keys here are stability and spirit. A serious buyer will see good management as an asset. An owner who has a non-qualified deferred compensation program in place will likely have motivated team members who will want to continue working so that their accounts will vest every year. My publications didn’t have a deferred comp plan, largely because I knew nothing about them at the time and no one ever approached me about it. If I had known, you can bet I would have put one in place.
6. **Are your financials clear and easy to understand?**Typically, many small business owners try to “run everything through the business” to grab every possible deduction they can find. Can a plumber really deduct a cruise because he mentioned “clogged drains” to another passenger? When an owner runs a lot of personal expenses through the business, it sends the wrong signal, even if they can be ‘backed-out’ for the buyer. If the business is really “clean”, you shouldn’t have to “clean-up” the financials. While I could deduct more than many other businesses, since we could publish restaurant reviews and travel sections, etc., I made sure to keep the expenses legitimate and the books clean. This impressed our buyer – and his advisors. Nothing had to be “backed out”.
7. **What is your cash-flow trajectory?**Cash flow is what’s left after everything and everyone has been paid. Is your cash flow improving or declining? What are the causes? This was something we measured constantly. While we were growing, I could see the growth was beginning to show signs of weariness after six years. When we sold in 1984, it turned out to be a good time as other competiing media were beginning to take hold. Tracking this trajectory is what gave us the ‘heads-up’ that changes were in the wind.
Seven tips seems to be a good number; no one ever seems to make a list of eight; but, if I were to add one more, it would be this:
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01901c238330970b-320wi.jpg)Own your distribution.**If you have solid, long-term contracts in place or have vertically integrated this function, your business has far greater value than the business that’s dependent upon, or at the mercy of, some outside entity. Obviously, if you’re in retail, this translates into location considerations. This is why many publications use the U.S. Mail, contracted delivery, or their own carriers. Those publications have greater value than the ones dependent on the courtesy of a local store to allow their presence.
**Here’s something you may not know:** Many, if not most, businesses never do find an outside buyer.. The truth is cash buyers are not only hard to find, they seldom exist, at least in the small business landscape. The idea that someone will write a check for the selling price is largely a fairy tale. Outside buyers, when they can even be found, will often purchase on a myriad of terms.
It should be no surprise that business transfers most often occur involving the owner’s family members and/or employees; but, a sale to family members or employees doesn’t just happen overnight. The business owner who sees his/her business as ultimately an equity that can be traded for a secure future, will be planning the move years – even ten – in advance, and usually with a team of competent financial, legal, and tax advice. Those who think they’ll have no problem finding a buyer just may be in for a sad surprise.
—————-
**[Subscribe to IFG Insights](https://tinyurl.com/IFGInsights "IFG Ezine Sign-Up")**
Follow Jim on Twitter: @jimlorenzen
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Facebook](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
———————
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/ "IFG")***,****a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Julie Andrews Turns 79! ... and does it with a sense of humor.](https://indfin.com/julie-andrews-turns-79-and-does-it-with-a-sense-of-humor/)
**Published:** April 1, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi3.jpg)
**James Lorenzen, CFP®, AIF®**
This was sent to us by one of my wife’s friends; I thought you might enjoy it.
To commemorate her 79th birthday , actress/vocalist, Julie Andrews made a special appearance at Manhattan ‘s Radio City Music Hall for a benefit. One of the musical numbers she performed was *‘My Favorite Things’* from the legendary movie*‘Sound Of Music’*. *Here are the lyrics she used:*
(If you sing it, it’s even funnier.)
Botox and nose drops and needles for knitting,
Walkers and handrails and new dental fittings,
Bundles of magazines tied up in string,
These are a few of my favorite things.
*Cadillacs and cataracts, hearing aids and glasses,
Polident and Fixodent and false teeth in glasses,
Pacemakers, golf carts and porches with swings,
These are a few of my favorite things.*
When the pipes leak, When the bones creak,
When the knees go bad,
I simply remember my favorite things,
And then I don’t feel so bad.
*Hot tea and crumpets and corn pads for bunions,
No spicy hot food or food cooked with onions,
Bathrobes and heating pads and hot meals they bring,
These are a few of my favorite things.*
Back pain, confused brains and no need for sinnin’,
Thin bones and fractures and hair that is thinnin’,
And we won’t mention our short shrunken frames,
When we remember our favorite things.
When the joints ache, When the hips break,
When the eyes grow dim,,
*Then I remember the great life I’ve had,*
*And then I don’t feel so bad.*
(I’m told Ms. Andrews received a standing ovation from the crowd
that lasted over four minutes and repeated encores. )
———————-
**RESOURCES:**
**What’s it like to work with IFG? See “**[The IFG Difference](https://indfin.com/video-library-2/)!”
**How much risk is in YOUR current portfolio? Do you know** [YOUR “risk number”](https://pro.riskalyze.com/embed/e2caceca86722d4b959d)**?**
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist) (does not require registration)
[Subscribe to IFG Insights ](https://tinyurl.com/IFGInsights)
[The IFG Website](https://indfin.com/)
IFG’s [Financial Resources website](https://finsecurity.com/Lorenzen).
Follow Jim on Twitter: @JimLorenzen
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp)
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20)!
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Is Owning Your Home ALWAYS the Best Idea?](https://indfin.com/is-owning-your-home-always-the-best-idea/)
**Published:** June 13, 2013
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01901c23af2a970b-320wi.jpg)That’s what we’ve always been told! But, how many of us have ever really run the numbers? A recent case from indicates what most of us already know: Most people don’t understand cash flow.
An article by Jim Grote, CFP®, in this month’s Financial Planning relates the story of a 54-year old single woman, a homeowner, who intends to retire at age 66. The question: What would happen if she sold her home in 2016 and rented a similar home in the neighborhood? Since people are living longer and it’s wise to be conservative, a life expectancy of 100 was used.
The numbers: If she were to sell her home at an estimated future value of $892,000 in 2016, her mortgage of $392,000 would be paid off, leaving net proceeds of $491,000, after adjusting for incidentals. She would also not be paying out $17,000 a year for homeowner’s expenses such as taxes, homeowners insurance, repairs, maintenance, capital improvements, some utilities, and landscaping.
She would be paying $30,000 annually (before inflation) in rental payments, with everything else remaining the same, including a $2 million investment portfolio.
The cash-flow analysis result: If she sold her home in 2016, she would die with portfolio assets of somewhere around $1.5 million. If she keeps her home, she runs out of cash at age 95 (equity in her home would be passed-on to her heirs). Quite a difference.
There may be other time-bombs in the wings. The same cash flow crunch may be awaiting those in residential investment properties.
Too often, people assume what’s right based on conventional thinking without having really run a sophisticated “what if” financial analysis.
The takeaway: If you’re wondering, it’s worth investigating. Now is always better than later.
Jim
——————
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://digioh.com/em/6318/5225/66272hevvs?demail=$SUBSCRIBER.EMAIL$%20 "Hidden Risk Report")(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "IFG Financial Conversation Checklist")(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights "IFG Insights")to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/ "IFG Website")
Follow Jim on Twitter: @jimlorenzen
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn profile")
IFG on[Facebook](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
———————
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,****a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [IRS Creates a Coronavirus Site](https://indfin.com/irscoronavirus/)
**Published:** March 18, 2020
**Author:** Jim Lorenzen
**Excerpt:** IRS Coronavirus resoures
**Content:**
**Jim Lorenzen, CFP®, AIF®**
You can find it [here](https://www.irs.gov/coronavirus).
——-
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Taxes
**Tags:** Coronavirus
---
### [The Investment Model And It's Amazing Hidden Powers.](https://indfin.com/investmentmodel/)
**Published:** May 18, 2020
**Author:** Jim Lorenzen
**Excerpt:** Few understand the power of the investment allocation model, even in - especially in - times of crisis; but the power can be great when tied to a long-range financial plan.
**Content:**
#### Few understand the power of the investment allocation model, even in – especially in – times of crisis; but the power can be great when tied to a long-range financial plan.
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017eea826334970d-320wi.jpg)iStock Images**Jim Lorenzen, CFP®, AIF®**
I can almost guarantee that not many people fully realize the power of an investment model as a means to fulfill a long-range financial plan, even in – or especially in – times of crisis.
The chances of a V-shaped recovery appear to be slim; not just because of the chances of a new spike in the pandemic due to possible premature reopening of the economy, it’s more about how market recoveries generally occur; yet, the power of the investment model remains unknown to many.
Many people intuitively believe that a 20% loss can be recaptured with a 20% gain; but, of course it’s not true. If you start out with $100, a 20% loss takes you down to $80. But, to get back to $100, you need to see your $80 grow by 25% ($20 ÷ $80). So, knowing that it takes a 25% gain to buy back a 20% loss, it’s easy to see why recoveries generally take longer than the original decline.
When we suffer declines in the market, it can be tempting for some people to sell on the way down in an attempt to cut their losses. The problem, of course is that calling the ‘bottom’ is difficult, because recoveries seldom occur in a straight line. Next thing they know, the recovery happened and they missed the rebound forcing them to buy back in at a new high. As you can see from this chart, a simple buy-and-hold philosophy would have been much easier without forcing them to become a market genius. After all, if Warren Buffett can’t time markets – and he says he can’t – than, why should we try?
[](https://indfin.com/wp-content/uploads/2020/05/MarketTiming_Right51Percent.png)
##### **That’s where the power of the investment allocation model comes in.**
Those who’ve been smart enough to build their financial future with a blueprint tend to have a framework for fulfilling their long-range strategic plan. On the investment side of their planning, the foundation is an customized asset allocation. What few realize is that that allocation has an automatic buy low/sell high mechanism that comes built-in!
Let’s look at a simplified example:
Since we talking about stocks more than bonds, let’s use an example of a simple growth-oriented allocation that’s comprised of 70% stocks and 30% bonds, with the majority of the stocks in the domestic U.S. market (represented here using the S&P index) and a lesser amount in foreign stocks (represented here using a Europe, Asia, and Far East index).
[](https://indfin.com/wp-content/uploads/2020/05/Sample_Allocation.png)
**Let’s assume our hypothetical investor has $500,000 invested.** To make it simple, basic stock-bond allocation would look like this:
Stocks: $350,000 = 70%
Bonds: $150,000 = 30%
Total: $500,000 = 100%
**Now, let’s suppose stocks drop by 20%** (we’ll pretend bonds stay the same). Our new allocation would look something like this:
Stocks: $280,000 = 65%
Bonds: $150,000 = 35%
Total: $430,000 = 100%
Stocks are now underweighted by 5% and bonds are now overweighted 5%. The great thing about models is that they can, and usually are, rebalanced on some type of schedule or according to some built-in protocol. To get back to our original allocation, money will have to be reallocated from bonds into stocks – the rebalancing ensures that we’re now buying low.
**In order to get stocks back to their 70% weighting**, we’ll need to bring the stock total to $301,000 ($430,000 x 70%). That will require moving $21,000 from bonds ($301,000 – $280,000). So, our rebalanced allocation is now:
Stocks: $301,000 = 70%
Bonds: $129,000 = 30%
Total: $430,000 = 100%
**Now, over time, the stock market finally recovers the 25% needed** to get back to where it was. That 25% gain in stocks adds $75,250 to stock value:
Stocks: $376,250 = 74%
Bonds: $129,000 = 26%
Total: $505,250 = 100%
Notice, we didn’t just get back to where we were before, we actually made money! We ‘beat the market’? How did that happen? The market returned to where it was but we ended-up ahead!
##### Rebalancing the investment model allowed us to buy low and sell high without being a market genius!
Now, of course, this is a over-simplified hypothetical (you can’t buy an index and I’ve ignored things like the time-frame involved, taxes, inflation, and a lot of other stuff), but, the concept is no less valid.
Oh, yes, rebalancing again now, getting us back to our original allocation, now means that we’re `selling high’ as the 4% overweighted stock money is now repositioned back to bonds until next time.
Not bad, eh?
Jim
————————————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, investment planning, Investment Strategy, managing risk, Reducing Risk
---
### [Investment Returns Can Be Misleading.](https://indfin.com/investment-returns-can-be-misleading/)
**Published:** July 6, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/06/iStock_44633966_SMALL.jpg)Jim Lorenzen, CFP®, AIF®
This sign represents the off-ramp many pre-retirees are seeking; but, there are usually many unforeseen detours before getting there; and, too often, far too many unpleasant road closings after finding it.
Example: Average annual (arithmetic) returns tend to reflect how an investment has performed, while it’scompound (geometric) return may be more indicative of how the investor actually fared; but, that’s only part of the story. In the real world, most portfolios have cash flows.
During our working years, we’re adding money to our investment nest egg; but, at retirement we begin taking money FROM our investments. This presents a very different dynamic when a down market hits and we’re reducing our assets via withdrawals, too – and, it can change the probabilities of success going forward.
*Understanding Investment Returns*just might help pre-retirees, as well as those already retired, to better grapple with the sometimes confusing overwhelming data provided by financial product distributors who can sometimes make it into a shell-game.
You can get yours here.
Enjoy.
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Retirement
---
### [How to Exit Your Business, Provide for Your Retirement, Turn the Business Over to your Kids, and Still Give Money To Charity!](https://indfin.com/how-to-exit-your-business-provide-for-your-retirement-turn-the-business-over-to-your-kids-and-still-give-money-to-charity/)
**Published:** January 28, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019b050c4fec970d-320wi.jpg)Yousay you own a successful C-corporation with excess cash and you’d like to retire and turn it over to your children and still give money to charity?
You don’t have to be Warren Buffett or Bill Gates to utilize sophisticated financial strategies to achieve your goals. Many are available to everyone; but, not everyone is aware they exist or how to use them.
There’s a way.
Consider this strategy1used by many successful business owners to achieve goals you may share:
1. Transfer a small amount of stock equally to your children by using your annual exclusion and, if necessary, part of your gift tax exemption.
2. Contribute the balance of your stock to a charitable remainder trust (CRT)\* – you will be the non-charitable beneficiary.
3. Once the transfer is completed, the corporation makes a general offer to all shareholders to redeem the outstanding stock at a specified price. The independent trustee of the CRT agrees to sell the stock to the company at the offered price. The corporation, using loans, retained earnings, or using other strategies, purchases the stock that now becomes ‘treasury stock’.
What’s happened?
- Your children are the only remaining stockholders in the corporation and have full control.
- The CRT now has cash instead of stock. The trustee can invest the cash in a diversified portfolio to provide a lifetime of annuity or other income to you and your spouse.
- There will be no immediate capital gain tax on the sale of the stock because it was sold by the CRT.
- After you and your spouse are deceased, the remaining funds in the CRT will pass to your family foundation or another qualified charity you chose.
- And, you’ll get a charitable tax deduction for a portion of the value of the stock you gave to the CRT.
Not bad. But, as they say, don’t try this at home. Be sure to meet with your financial, tax, and legal advisors to map out evaluate this strategy to make sure it’s right for you.
Jim
*\*A charitable remainder trust is an irrevocable strategy that allows a deduction for the gift to the CRT since the asses will ultimately benefit a qualified charity. The donor(s) may live off the income the assets provide and upon death, the rest goes to the charity. Life insurance is often used to replace the value of assets donated because it allows the replaced assets’ value to be more equitably divided and, properly structured, the death benefits are generally tax-free.*
1I first saw this strategy outlined in*GIVING,*by Robert Esperti, Renno Peterson, and Lemuel Bargeron in an Esperti Peterson Institute book published by Quantum Press, LLC, 2003.
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk)(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist)(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights)to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
The[Joint Committee on Taxation](https://www.jct.gov/resources.html)
**Become an IFG client!**Don’t play phone-tag; schedule your 15-minute introductory phone call using[this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,**a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Hidden Secrets of Insurance Company Promises](https://indfin.com/hiddeninsurancesecrets/)
**Published:** August 3, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73dd6e411970d-320wi.jpg)Jim Lorenzen, CFP®, AIF®
Life insurance illustrations have had, for more years than I can count, a well-deserved reputation for less than transparent and amazingly inaccurate projections of what the policyholder could expect in future years. Typical whole life policies had a lot going on “under the hood” and virtually invisible to the buyer.
One major problem for the typical insurance consumer is the inability to tell one company from another. While many truly professional and credentialed independent agents do make an effort to represent only “investment-grade” companies, there are far too many others who will represent the highest commission, which can often lead to selling substandard products for companies that appear to be substantial. An agent who is also an investment advisor can be a benefit for the buyer.
Here’s an example: Before Executive Life of New York went under, they had over 50% of their portfolio invested in less than investment grade ‘junk’ bonds, despite the fact that in June 1987, the New York legislature had mandated that insurance companies licensed to business in that state were to limit their general portfolios to no more than a 20% allocation to such bonds.
Remember, there are no guarantees; there are only guarantors. \[Source: The New Insurance Investment Advisor, Ben G. Baldwin, McGraw-Hill 2002, p. 37.\]. A good advisor would look at that allocation and realize it was one he would never recommend for a client; so, why would anyone use it to back their legacy planning?
**Here’s what most people don’t know:** Most of the well-known rating agencies we’re familiar with are actually paid by the insurance companies they rate! Little wonder many insurance companies that failed actually had good ratings when they went under.
Have you noticed that virtually all insurance companies tout ratings from the same rating agencies in their promotional materials? Few, if any, however, tout their rating from Weiss, maybe because Weiss doesn’t get paid by the companies they rate – their revenues come solely from subscriber revenue (kind of like Consumer Reports).
For example, according to the September 2002 Insurance Forum, of 1221 life and health companies rated by Weiss, only 3.9% of companies made it into the ‘A’ category. Compare that with the 54.9% rated ‘A’ by Standard and Poor’s. At Moody’s, 90% of their list made it to ‘A’ that year. A.M. Best gave ‘A’ to 56.3% of the companies they rated.
By the way, Companies with ratings in the A or B brackets from Weiss are considered secure, while some of the other rating agencies will give B and even A bracket ratings to companies considered vulnerable.
Recently, indexed universal life (IUL) policies have become quite popular – both among agents and their clients. The reasons are many, but two big attractions are (1) transparency – virtually no hidden moving parts. These products are easy to understand; and (2) low cost – insurance costs are basically like term policies. Admin costs are also low and, as noted, everything, including costs, is transparent, including performance going forward.
Does that mean the illustrations can be believed? No, but for different reasons. To understand the reasons why illustrations can be misleading and how to know you’re comparing apples with apples, it’s important to know how these policies work.
First a caveat: This is not an exhaustive text on IUL products and there’s a lot more to know than is being discussed here. This is simply a quick overview highlighting the stand-out characteristics.
**Quick IUL Overview**
IULs are often, but not always, designed as financial tools for maximum cash accumulation in a tax-advantaged vehicle. In these cases, the death benefit is often a secondary consideration; however, it’s the life insurance that buys the tax benefits – and, for many, these benefits far outweigh the cost of insurance, which is typically priced like term insurance.
These buyers want to buy the minimum amount of insurance for the maximum amount of premium they can put in (there’s a limit). This is because after the minimum insurance is purchased and expenses are covered, the rest goes into a cash accumulation account.
The cash accumulation account accumulates tax-deferred, but can be accessed as tax-free loans. How fast does the cash accumulate? Interest is credited to the account based on the performance of an outside index. While there are often many choices, most people tend to choose the S&P 500 index.
To keep this simple, I’ll just quickly cover the simplest approach: Let’s suppose our policyholder purchased an IUL policy using the S&P 500 index as the crediting option. The policy might offer 100% participation in the index’s upside moves up to a ‘cap’ during a crediting period, typically one year.
For example, if the index rises 8% by the policy’s 1-year anniversary date, the policyholder participates 100% in that move and receives the full 8%. If the index rose by 25%, the policyholder would receive whatever the ‘cap’ is.
So, on a 1-year, 100% participation with a 12% cap, a 25% rise in the index means the policyholder would receive 12%, i.e., 100% of the increase up to the cap. That amount would be credited on the policy’s anniversary date.
The next crediting would take place on the policyholder’s second anniversary.
Note: It doesn’t matter what happens between anniversaries – only the value ON the anniversary date counts, nothing else.
The good news is that if the stock market index has a drop, the policy loses nothing. The amount credited is 0. No gain, but no loss, either. Another nice thing is that, in our example above, after the 12% gain is achieved, it’s locked-in. That’s the new floor and that money can’t be lost.
How can the insurance company, investing in a conservative bond portfolio do this? It’s simple. Again, I’ll oversimplify with rounded numbers just to make the concept easier. Premium money received might be invested 95% in bonds, and 5% in stock options. If the market goes down, the options expire; if the market goes up, they execute the options and, of course, the cap on the policy limits their exposure.
Important: The policyholder is not invested in the market or the options. The index is only a ‘ruler’ to measure how much the insurance company will credit. It’s the insurance company’s investment account that is doing the investing, not the policyholder.
**Returns and Illustrations**
Can the policyholder receive stock market-like returns? Not likely. The caps limit the upside, and while there is no downside, down years representing no gain will sometimes occur. So, positioning IULs as a stock substitute is probably not the best strategy. I would look for returns that are more bond-line, maybe a little better, which means, it’s the bond portion of your portfolio that you’re really dealing with.
And, here’s where illustrations can be a bit misleading.
If one company is offering a 12% cap and another company is offering an 11% cap, but both are showing you an illustration using a 7% crediting rate, saying that the S&P average over all their back-tested periods indicates that 7% is conservative, are you really seeing an apples-to-apples comparison?
Maybe. Maybe not. It depends.
First, the company: How have they treated policyholders in the past when they’ve reduced or increased their caps? Did existing policyholders receive the same treatment as new policyholders?
Secondly, a decrease in a cap rate isn’t all bad. Responsible insurers are custodians for client assets and need to act responsibly, rather than chase risky investments to meet caps they can’t pay. However, a decrease in the cap also can affect your outcome.
As you can see from this chart below- I apologize if it’s a bit difficult to read -a 7% illustration for a 12% cap IUL has a 79.5% chance of meeting its projections, based on a 20-year historical probability study of the S&P 500 at various cap and crediting rates. If the cap is 11%, the probability is reduced to 60.7%.
[](https://indfin.com/wp-content/uploads/2015/08/IUL-Crediting-Rates_0011.png)
This has less to do with the insurance company than it does with expectations. It’s important to know, when you’re buying, what you can reasonably expect; and, often, it may not be what you’ve been promised with a rosy illustration. High quality companies providing investment-grade products will tend to be conservative in their projections – and a good advisor will educate clients on realistic outcomes.
Note: An illustration for a policy with an 11% cap but using only a 6% crediting rate may not look as rosy as the 7% illustration, but the odds of the company delivering on its promise rises to 95%. This means, it’s virtually certain your policy will perform this well or better. The 7% illustration will look so much better at the point of sale, but it also has almost a 40% probability of doing worse than promised.
**The Real Benefits**
If someone begins utilizing these benefits early, say in their 40s or 50s, the benefits can be substantial. As a matter of fact, it’s a strategy being used by 85% of Fortune 500 CEOs and many members of Congress in order to create a tax-free retirement. Other proponents of this strategy include retirement and IRA expert Ed Slott, who is also a CPA, and David M. Walker, former US Comptroller General *\[Source: The Power of Zero, David McKnight\].*
I’ve created a report on this concept. You might find it interesting. You’ll receive it free by going here. If you’d rather take the time (about an hour) and view the webinar with all the slides, you can do that here.
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Life Insurance, Retirement
**Tags:** Retirement Income, Retirement Planning, Retirement Strategy
---
### [A Guaranteed Income for Life?](https://indfin.com/guaranteedincomeforlife/)
**Published:** July 27, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/09/Laptop_w_Income4Life_Model_on_Screen.png)Jim Lorenzen, CFP®, AIF®**
In a previous post I talked about how everyone now has to be his/her own actuary, if they want to create a guaranteed income for life.
I’ve even provided a 20-minute educational video on how it’s possible to actually create a guaranteed income for life. I think you’ll find it helpful; grab a cup of coffee and you can register to take a look.
While I’m at it, here’sa link to areport that takes a deeper look at a a ‘hybrid’ scenario manyinvestors might find attractive. I think you’ll find the report interesting, if not eye-opening. You can access it here.
How does one GUARANTEE an income for life? Well, there’s only ONE way to guarantee that outcome: An annuity. NO OTHER FINANCIAL TOOL WILL DO THIS.
Oh, yes, they do get bad press (what doesn’t?). The real problem, though is the confusion around the different types of annuities that exists.
1. Variable annuities
2. Equity-indexed annuities
3. Fixed annuities – can be either immediate or deferred
Options #1 and 2 can be problematic. They are often loaded with excess costs, moving parts, and restrictions.
Option #3 is generally more straightforward. It’s more of an I.O.U. with the insurance company. You pay them; they pay you.
[](https://indfin.com/wp-content/uploads/2017/06/FA_Sample_Payouts_201706.png)Here are some sample payout examples. Take the first one: the payout represents a 6.54% payout; and as you can see, the payouts do increase with age.
There’s a trade-off, however, the money is not just illiquid – it’s gone! You are essentially ***buying*** an income stream for life! You’re paying cash for a secure retirement.
So, should you do that with all your money? Probably not. It should not be an ‘all or nothing’ strategy. That’s why I think you’ll find this report on a hybrid strategy helpful.
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP) Just pick a time convenient for you.
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Inflation, Investing, Planning, Retirement
**Tags:** investment returns, Investment Strategy, managing risk, Reducing Risk
---
### [Don't Confuse Loaning With Owning.](https://indfin.com/dont-confuse-loaning-with-owning/)
**Published:** May 7, 2013
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73d6e4d94970d-320wi.jpg)The Investment decisions we make aren’t*always*about investing, after all.**
Your cousin Willie calls you and tells you he’s going to open a taco stand in Beirut – there’s little competition there – and he needs another $10,000 to make it happen; so, he’s asking you to make him a loan and he’ll pay you 10% interest on a quarterly basis.
**Are you an investor or a creditor?**
If you said creditor, congratulations! You made a loan. You didn’t make an investment.
Ever hear someone tell you they’ve “invested” in a bond, fixed annuity, or bank CD? Just remember cousin Willie.
- When you buy a bond, you’re making a loan to a government entity or a corporation. They are giving you their I.O.U. – their bond – and paying you interest for your money.
- When you “buy” a bank CD, you’re really making a loan to the bank. Of course, they’ll re-loan the money at a higher rate and profit from the spread; but, for you, it’s a loan, nevertheless. You could call it a bank “bond”.
- Insurance companies make loans, too. They’re called fixed annuities. You’re basically loaning money to an insurance company and they’re giving you an I.O.U. for repayment at some fixed rate of interest.
- Equity-indexed annuities are fixed annuities, too. The fixed rate is re-set periodically according to the terms of the annuity you purchased; but, it’s still an insurance company I.O.U. It just has a fixed rate that can be adjusted.
- Immediate annuities: It’s a contract. You give your money to an insurance company and they promise you a fixed income for life. In most cases, when you die, they keep what’s left. Again, it’s not ownership; but, this one’s not necessarily a loan either. In this case, you’re transferring your cash from your account onto the insurance company’s balance sheet; and your future income is tied to the health of the insurance company.
You see, other than hoarding – putting money under the mattress – there are only two things you can do with money: Own or loan. But, not all ownership transactions are investments.
- When you buy a taco at Willie’s stand, you’re consuming, not investing.
- When you buy a new car, chances are excellent it will depreciate. There’s an outside chance it become a collector’s classic someday; but not likely. The slight chance of gain makes this an investment – probably a bad one. You could call this a guaranteed loss investment.
- When you buy precious metals, they could go up or down. Your purchase may be based on speculation, but it’s still investing.
- When you buy ownership in real estate or even shares of ownership in established and successful companies with an eye to the future, you’re investing. Both could go up or down, as we’ve seen for decades; but, that’s what makes it “investing”. This type of investing, however, would seem less speculative if done prudently.
Before you make financial decisions, it’s probably a good idea to sit down with a CFP®professional; but, even before you do that, you and your spouse should talk things over first. You can use the**Financial Conversation Checklist**in the Resources section below. After you’ve talked things over, sit down with your advisor and go through the checklist again.
Hope this helps!
——————————————–
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk "Hidden Risk Report")(registration required)
[A Financial](https://indfin.com/financial-conversation-checklist "Financial Conversation Checklist")Conversation Checklist(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights "IFG Insights")to IFG’s Ezine:[IFG Insights](https://tinyurl.com/IFGInsights%20 "IFG Insights")
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter: @jimlorenzen
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp%20 "Jim on LinkedIn")
IFG on[Facebook](https://www.facebook.com/IFGAdvisory%20 "IFG on Facebook")
———————
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,****a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Retirement and Income Taxes](https://indfin.com/retirement-and-income-taxes/)
**Published:** June 16, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2016/11/Tax-Burden-Scale.png)Jim Lorenzen, CFP®, AIF®**
Who better to talk about taxes in retirement and income taxes than a CPA? You may be familiar with Ed Slott from his frequent appearances on PBS. One of the very few gurus who actually is the real deal: A CPA who is recognized even inside the financial profession as an expert – he even teaches CFP Board-approved continuing education classes.
Mr. Slott does have a unique ability to present financial topics in an easy-to-understand, entertaining way. One of the hot topics right now is protecting retirement income from taxation. The topic is hot primarily because of two issues: Longevity risk (outliving our money) and taxation risk (the government debt is huge and the outlook over the next two decades, when we’ll need money the most, is that taxes are bound to rise).
I think you’ll find this video interesting.
If you’d like a report on how you might be able to create a tax-free retirement, you canget it here.
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
Enjoy the video and report!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Inflation, Investing, Planning, Retirement
**Tags:** investment returns, Investment Strategy, managing risk, Reducing Risk
---
### [The Provisional Income Trap](https://indfin.com/provisionaltrap/)
**Published:** July 25, 2017
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/02/iStock_UncleSamLiftingWallet_Medium.jpg)… and what it means to your retirement income – particularly your Social Security taxation in retirement.
**Jim Lorenzen, CFP®, AIF®**
**Most people believe** that municipal bond interest is tax-free and won’t affect taxation on their retirement income. Well, it is, I guess; but, there are tax ramifications few people have heard about. It’s called “provisional income”.
Huh?
There are categories of income which, when added up, determine how much provisional income you’ve received in a given year. And, during retirement, when you’re likely receiving Social Security income, the amount of provisional income you receive determines just how much you’ll pay in taxes on your Social Security Income.
[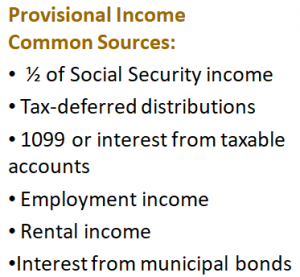](https://indfin.com/wp-content/uploads/2017/07/Provisional_Income_Sources.png)As you can see, when adding up your provisional income, it begins with 50% of your Social Security income. Then they add in all distributions from tax-deferred accounts. If you’re in retirement, that includes money you’re taking from your 401(k) or IRAs (except distributions from a Roth IRA, which are generally tax-free, and any money you’ve taken from a properly-structured permanent life insurance policy (withdrawals up to your cost-basis and policy loans). And, as you can see, municipal bond interest is counted.
Once you’ve added up all your provisional income, how much do you owe in taxes? Well, it depends. Here are the provisional income thresholds.
[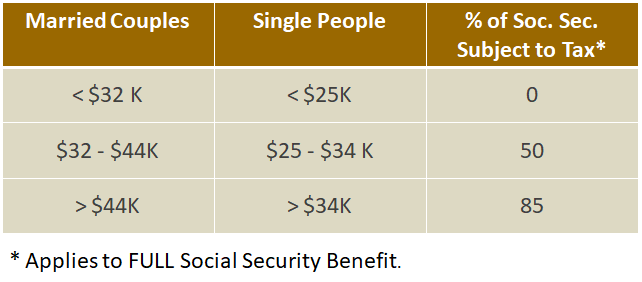](https://indfin.com/wp-content/uploads/2017/07/Provisional_Income_Threshholds.png)
If you’re a married couple and your provisional income is below $32,000 for the tax year, you will pay no txes on your Social Security income. If your income is over $44,000, however, then 85% of your Social Security income will be taxable. The whole idea was part of a package passed back in the 1980s to save Social Security. One thing they didn’t do: index it for inflation.
So, as your 401(k) grows and your assets grow–more importantly, as inflation continues through the years and it will require greater withdrawals for you to live in retirement–the greater the likelihood you’ll be paying taxes on your Social Security. It doesn’t take much to get past $44,000 in retirement.
Let’s take a quick look at an example: Fred and Wilma. They have $30,000 in combined Social Security income and also take $40,000 annually from their IRAs, giving them a $70,000 income in retirement.
[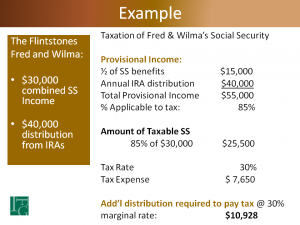](https://indfin.com/wp-content/uploads/2017/07/Fred-Wilma-1.png)
For computing their provisional income, only half of their Social Security income is used. Added to their IRA distributions, they have $55,000 in provisional income, meaning that 85% of their Social Security income ($25,500) is taxable at their tax rate. If they’re paying taxes at 30%, their tax bill will be $7,650.
But if they need the entire $70,000 they’ve taken as income, they’ll have to take an additional distribution just to pay the tax bill, and, oh yes, it’s taxable, too.
But, Fred and Wilma have another problem they’re likely completely unaware of. There’s a ticking time-bomb growing inside their 401(k). It’s growing.
**How can that be bad?** Well, it isn’t, of course, but it might come at a huge price. If history has taught us anything, it’s that governments exist to get re-elected and they help insure than through spending which never seems to get undone. Our nation’s huge debt is growing and the money to pay the bills will have to come from somewhere–and it won’t come from people with no money. With an ageing demographic bubble moving into the decumulation stage and wanting more services, particularly health care, the long-term outlook for taxes can’t be too encouraging. Let’s get back to Fred and Wilma:
[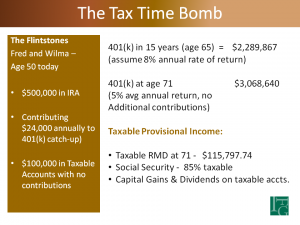](https://indfin.com/wp-content/uploads/2017/07/Fred-Wilma-2.png)If Fred’s 401(k) continues to grow at an 8% average annual rate until he’s 65, he’ll have a balance of over $2 million! And, at age 71, when he’ll be required to take required minimum distributions (RMDs), his balance will be over $3 million–requiring RMDs of over $115,000 annually.
Fred and Wilma will be paying a lot of taxes.
And, as mentioned earlier, the long-term outlook for taxes isn’t likely very good. Just take a look at the differences from 2012 to 2017.
[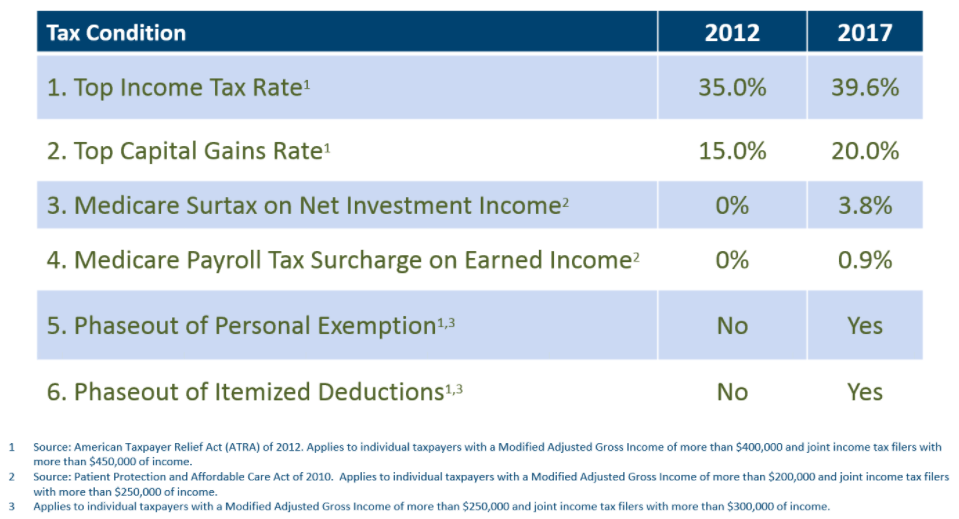](https://indfin.com/wp-content/uploads/2017/07/Uncertain_Tax_Environment_in_Retirement.png)
How can Fred and Wilma mitigate, and maybe eliminate, their income tax payments in retirement?
Under current tax law, each has a personal exemption of $4,050, so they have $8,100 incombined personal exemptions. They also have their deductions. If they’re using the standard deduction, they’ll have $12,700 too, giving them a total of $20,800 in exemptions and deductions. So, their key is to keep their taxable income below $20,800. All income above the standard deduction and personal exemption is subject to tax.
**[](https://indfin.com/wp-content/uploads/2016/06/4-Simple-Steps-Post_001.png)The good news** is that Fred and Wilma are still in their 50s and there’s plenty of time to plan. Working with their *Certified Financial Planner®*professional, they can begin “reverse –engineering” the placement of assets in a way they can still grow their nest-egg, but re-arrange their ‘tax buckets’ so Uncle Sam becomes less of a partner–or no partner at all, which would be the ideal making their tax-jockeying a moot issue. You can get our piece on *4 Steps to a Tax-Free Retirement.* I think you’ll like it.
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Inflation, Planning, Retirement, Taxes
**Tags:** investment returns, Investment Strategy, managing risk, Reducing Risk
---
### [Optimizing Retirement Income: Combine Actuarial Science with Investments.](https://indfin.com/optimizing-retirement-income-combine-actuarial-science-with-investments/)
**Published:** August 10, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/a-market-high-should-you-jump-in/6a017c332c5ecb970b017c384ba1fa970b-320wi/)You’ve probably heardabout “The 4% Rule” – it’s been an ‘accepted’ rule-of-thumb for years that a retiree could withdraw 4% of his or her initial retirement portfolio value each year (increasing for inflation only, not market returns) and could reasonably expect his or her retirement nest-egg to last.
Of course, that’s when the markets seemed to be going up all the time. In recent years, due to low interest rates and increased market volatility introducing everyone to sequence-of-returns risk, many advisors have dialed back the 4% withdrawal rate to 3.5%
It’s also lead to some back-testing within the industry to determine just what retirees can expect.
**Testing with annuities**
An FPA Journal paper back in December 2001 by Mark Warshawsky and co-authors John Ameriks and Bob Veres introduced the use of immediate annuities into the retirement discussion. In his current contribution, Warschawsky examines the use of immediate annuities combined with a fixed withdrawal percentage from a total-return portfolio. The conclusions [\[1\]](#_ftn1) were:
- The 4% rule tends to fail when utilized for extended periods, i.e., 30 years, whereas immediate annuities provide continual cash flow, regardless of market or economic
- A 3.5% or less is often more appropriate than 4% (for obvious reasons).
- When incorporating an immediate annuity at age 70, the annual payout almost always exceeds the 4% rule and does not risk full income or running out of money – in essence it’s purchasing an unending cash flow that, testing shows, exceeds the 4% rate.
Immediate annuities offer many advantages, but they likely not suitable for those with impaired longevity, liquidity needs, and adequate pension income. For those who face longevity risk with no pension income, creating a “floor” may make some sense, after all.
**Testing with insurance**
Industry thought-leader Wade Pfau, in a paper commissioned by OneAmerica, addresses this issue in three scenarios:
1. Investments combined with term life insurance
2. Investments, joint and 100% survivor annuity, and term insurance
3. Investments, single life annuity, and whole life insurance[\[2\]](#_ftn2)
He compared these three approaches for 35 year-old and 50 year-old couples. Without getting into the weeds, I just say his study found a “substantive evidence that an integrated approach with investments, whole life insurance, and income annuities provide more efficient retirement outcomes than relying on investments alone.” It’s not an either/or decision.
Withdrawal strategies vary beyond what’s been discussed here, of course, which is why professional help can be very important and the difference of even hundreds of thousands of dollars.
There are some things you should consider before purchasing an annuity. You can access my report here. Also,[ inflation](https://indfin.com/will-my-annuity-income-really-increase/) is also an issue worth considering.
It pays to do your homework and have a good guide. If I can be of help, feel fee to [get in touch](https://www.meetme.so/JimLorenzenCFP)!
Jim Lorenzen, CFP®, AIF®
—————————————-
*Jim Lorenzen is a*[ *CERTIFIED FINANCIAL PLANNER®*](https://en.wikipedia.org/wiki/Certified_Financial_Planner) *professional and An Accredited Investment Fiduciary® serving private clients since 1991. Opinions expressed are those of the author and do not represent the opinions of IFG any IFG affiliate or associated entity.The Independent Financial Group is a fee-only registered investment advisor with clients located across the U.S. He is also licensed for insurance as an independent agent under California license 0C00742.Jim can be reached at 805.265.5416 or (from outside California) at 800.257.6659.The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.*
**Interested in becoming an IFG client?** Why play phone-tag? You can easily [schedule your 15-minute introductoryphone call!](https://www.timetrade.com/book/F7ZPS)
\[1\] Journal of Financial Planning, January 2016
2 ibid
[](#_ftnref1)
[](#_ftnref2)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
**Tags:** Reducing Risk, Retirement Income, Retirement Planning, Retirement Strategy
---
### [The One-Way Buy-Sell](https://indfin.com/onewaybuysell/)
**Published:** January 13, 2020
**Author:** Jim Lorenzen
**Excerpt:** Typically, small business owners are the active managers of their businesses, are heavily invested in their businesses, and generally rely on a small number of important accounts and suppliers. Also, in most, if not all, cases no secondary market exists for easy valuation and quick disposition of ownership.
**Content:**
Maybe the best kept secret in business succession for family-owned businesses.
**[](https://indfin.com/wp-content/uploads/2016/11/Dollar-Sign-and-characters-surrounding.png)Jim Lorenzen, CFP®, AIF®**
******According to the U.S. Census Bureau’s “Statistics of U.S. Businesses”, more than five million firms employ fewer than 20 employees.******[](#_ednref1)
Typically, small business owners are the active managers of their businesses, are heavily invested in their businesses, and generally rely on a small number of important accounts and suppliers. Also, in most, if not all, cases no secondary market exists for easy valuation and quick disposition of ownership. Succession often depends on a successful transfer to a key employee or family member while preserving and securing the retirement of the original owner.
You can access my report here.
Enjoy!
Jim
```
```
—————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
*Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Business Owners, Business Succession
---
### [Market Opinions Everywhere; That's Why They're Meaningless.](https://indfin.com/market-opinions-everywhere-thats-why-theyre-meaningless/)
**Published:** April 11, 2013
**Author:** Jim Lorenzen
**Content:**
**Retirement planning isn’t about gambling; it’s about, well, *planning*.**
I noticed a recent Twitter post from *US News & World Report* entitled, *[9 Simple Ways To Quit Worrying About Retirement](https://money.usnews.com/money/blogs/On-Retirement/2013/03/28/9-simple-ways-to-worry-less-about-retirement?s_cid=rss:On-Retirement:9-simple-ways-to-worry-less-about-retirement&utm_source=twitterfeed&utm_medium=twitter "US News 9 Ways")*. It’s aimed at people in their 40’s and contains some excellent advice. If you’re in your 40’s – or know someone who is – you may want to look it over.
More people are worried about outliving their money than ever before, something I’ve [written about before](https://www.jimsmoneyblog.com/2013/03/worried-about-living-too-long.html "Longevity Risk") in this forum. And, with today’s 24-hour news cycle, the media is pressured to get more eyeballs to tune-in and stay-tuned for every earth-shaking, world-changing, all-important, and ultimately mind-numbing event.
I spent some time around the news business many years ago and the mantra in most newsrooms was indeed, “If it bleeds, it leads.” In other words, bad news sells. When you have 24-hours to fill, you find as much as you can. Of course, this doesn’t do much constructive for us viewers; it warps our sense of reality. Pretty soon, we begin thinking all future events are likely to be bad; so, we become desensitized.
It’s important to keep perspective. Despite the concerns I wrote about in [a recent post](https://www.jimsmoneyblog.com/2013/04/a-market-high-should-you-jump-in.html "Market Highs"), others, like *[The Economist](https://www.economist.com/blogs/schumpeter/2013/03/america%E2%80%99s-stockmarket "Economist")*, see the market as better than the alternatives. Indeed, recently Warren Buffett was chiming in with positive comments regarding his market outlook.
What many investors should realize, however, is that long term investment success isn’t about market timing. And, you [don’t have to beat the market](https://www.jimsmoneyblog.com/2013/03/how-to-underperform-the-market-and-still-beat-it.html "Managing the Downside") to outperform it!
As always, it’s about the plan… and *it’s about time*.
————
RESOURCES:
IFG Report: [The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk) (registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist) (does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights) to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter: @jimlorenzen
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on [Facebook](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
———————
***Jim Lorenzen is a [CERTIFIED FINANCIAL PLANNER](https://en.wikipedia.org/wiki/Certified_Financial_Planner "Certified Financial Planner")® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Is A Reverse Mortgage Right For You?](https://indfin.com/is-a-reverse-mortgage-right-for-you/)
**Published:** January 17, 2013
**Author:** Jim Lorenzen
**Content:**
You’ve seen the commercials with celebrities touting reverse mortgages; ever wonder what they are? Actually, they are just what they sound like: It’s a loan; but the lender pays you and they don’t get their money back until you (or the last surviving borrower) die, sell the home, or `permanently’ move out of it (usually for a year or more). You or your heirs keep the difference between the value of your home and what you owed on the loan.
Reverse mortgages aren’t for everyone. Consumer Reports, their booklet, *50 Steps to A Richer Retirement*, reports one study that found less than one percent of the people who would be eligible have signed up; but, these loans do allow many retirees to stay in their homes and get some of the accumulated equity out of it.
In most cases, you must own your home as your principal residence and usually be 62 or older. You also can’t have any other outstanding mortgages on your home unless you intend to use part of the proceeds to pay them off.
There are two types of reverse mortgages:
- The Home Equity Conversion Mortgage (HECM) is insured by the Federal Housing Administration (FHA) and governed by FHA rules concerning loan amounts, costs, and eligibility.
- Proprietary Reverse Mortgages are just what they sound like: They are proprietary reverse mortgage products offered by private lenders. These are generally more expensive than FHA insured mortgages, but they may also have higher loan limits – you need to do your homework on any increased benefits vs. costs.
**How they work.** Here’s a purely hypothetical and admittedly oversimplified example just to give you an idea of the reverse mortgage structure. The numbers aren’t as important here as the concept:
Suppose your home is worth $500,000. A reverse mortgage is basically a refinancing providing you cash for a portion of your equity. It’s only a ‘portion’ because the new lender needs to have a `cushion’ for repayment that comes from your equity. Confused?
Hypothetically, your reverse mortgage lender could lend, say, $350,000 on your home, less any pay-off required by your current mortgage holder. If none, you’d receive the $350,000 less other fees and expenses required to initiate the loan. Under this scenario, you’d go from $500,000 equity and no loan to a $350,000 (less fees, etc.) loan and about $150,000 in equity. You don’t have to make payments. The “payments” plus interest are now added to your loan balance, thereby reducing your equity, each month.
As you can see, your equity could be reduced to zero and your loan balance could eat up all your equity at some point in the future. It’s also possible that equity could grow at a faster pace than your loan balance; but, you intend to stay in your home forever, it may not be an issue, especially if you don’t intend to pass your home along to your heirs. You could, for example, replace the equity you wanted your heirs to receive with a life insurance policy and have the money pass tax-free.
**Watch your step!** Reverse mortgages can often come with high fees; so you need to do your homework and get **everything** spelled-out in writing. It would likely pay to have an objective third party, a CPA or CFP professional actually run the numbers for you.
For more information about reverse mortgage pros and cons, see the AARP website and the National Center for Home Equity Conversion.
Sites: [AARP – Reverse Mortages](https://search.aarp.org/browse?Ntt=Reverse%20Morgages); [www.reverse.org](https://www.reverse.org/)
Good luck!
——————-
*Jim Lorenzen is a Certified Financial Planner® and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of* [*The Independent Financial Group*](https://indfin.com/)*, a fee-only registered investment advisor with clients located in New York, Florida, and California. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
Additional IFG Links:
- Twitter; @JimLorenzen
- [Jim’s MoneyBlog](https://indfin.com/jim-blog/)
- IFG on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp)
- IFG on [Facebook](https://www.facebook.com/IFGAdvisory)
*IFG does not sell products, earn commissions, or accept any third-party compensation or incentives of any description.* IFG does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional. The Independent Financial Group does not sell financial products or securities and nothing contained herein is an offer or recommendation to purchase any security or the services of any person or organization.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [IRS Clarifies IRA Rollover Rule](https://indfin.com/irs-clarifies-ira-rollover-rule/)
**Published:** June 5, 2014
**Author:** Jim Lorenzen
**Content:**
This, courtesy of the Financial Planning Association (FPA), of which I am a member:
**A U.S. Tax Court ruling on IRA rollovers has the IRS changing its longstanding position.**
In January of this year the U.S. Tax Court ruled that the “once a year” IRA rollover rule applies to all of an individual’s IRAs, not to each separately. The court’s decision conflicts with a longstanding IRS position (as outlined in IRS Publication 590) that states the rule applies separately to each IRA owned, thus allowing multiple rollovers if taken from separate accounts during a 365-day period — as opposed to a calendar year period.
For its part, the IRS had not publicly indicated how it would handle the court’s decision until recently, when it announced that it would uphold the court’s decision and revise its rules and publications accordingly.
**Ruling Applies to Indirect Rollovers**
It should be noted that the rule applies only to indirect rollovers, in which the account holder initiates a distribution from an IRA and receives a check for the distributed amount which is deposited into his or her personal account. It is then up to the individual to redeposit the funds into the new IRA within the allotted 60-day period to avoid possible taxation and penalties on the amount distributed.
If individuals want to move money more frequently, they can still use the direct rollover approach — also known as a trustee-to-trustee rollover — anytime without regard for the new once-per-year rule. With a direct rollover, the money goes directly from the former IRA custodian/trustee to the new custodian without the account holder ever touching it. The Tax Court was clear in its ruling that individuals who have more than one IRA may make multiple direct rollovers from the trustee of one IRA to the trustee of another IRA without triggering the one-year limit. Other advantages of a direct rollover include simplicity and continued tax deferral on the full amount of the account holder’s retirement savings.
Both the court’s decision and the IRS’s ruling may have an impact in individual investors’ retirement planning decisions. To play it safe, consult with a qualified financial and/or tax advisor before making any IRA moves.
*Source: financial-planning.com, “IRS Issues IRA Rollover Warning,” April 10, 2014.*
*Because of the possibility of human or mechanical error by Wealth Management Systems Inc. or its sources, neither Wealth Management Systems Inc. nor its sources guarantees the accuracy, adequacy, completeness or availability of any information and is not responsible for any errors or omissions or for the results obtained from the use of such information. In no event shall Wealth Management Systems Inc. be liable for any indirect, special or consequential damages in connection with subscriber’s or others’ use of the content. © 2014 Wealth Management Systems Inc. All rights reserved.*
What are the Six Best and Worst IRA Rollover Decisions? You may want to [read this](https://tinyurl.com/IRARolloverDecisions%20 "Best and Worst IRA Rollover Decisions").
Enjoy,
Jim
Follow Jim on Twitter:
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on [Facebook](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,** a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Think You're Diversifying Investments? Not Really.](https://indfin.com/investment-diversification-and-reducing-investment-risk/)
**Published:** April 28, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b0192ac851ba2970d-320wi.jpg)Jim Lorenzen, CFP®, AIF®**
#### Investment diversification, reducing investment risk, may be one of the most misunderstood of investment principles. I’ve seen tv stock gurus tell you that owning three stocks in different industries passes forinvestment diversification, implying that risk is being reduced. I don’t think so; it’s just compounding investment concentration.
Believe it or not, you can’t possibly diversify-away market risk. Think about it; you could own every single stock contained in the S&P 500 Index and all you would have done is *duplicate* the market’s risk.
[](https://indfin.com/wp-content/uploads/2017/04/DiversificationVsDuplication.jpg)
I’ve also seen investors buy multiple mutual funds in an attempt to diversify; but, since everything they bought had to be “quality”, all they did was duplicate their holdings (portfolio A) instead of diversifying them (portfolio B) across multiple investment styles (growth/value, large/small, etc.).
Diversification, done properly, can smooth things out, as this simple example shows.
[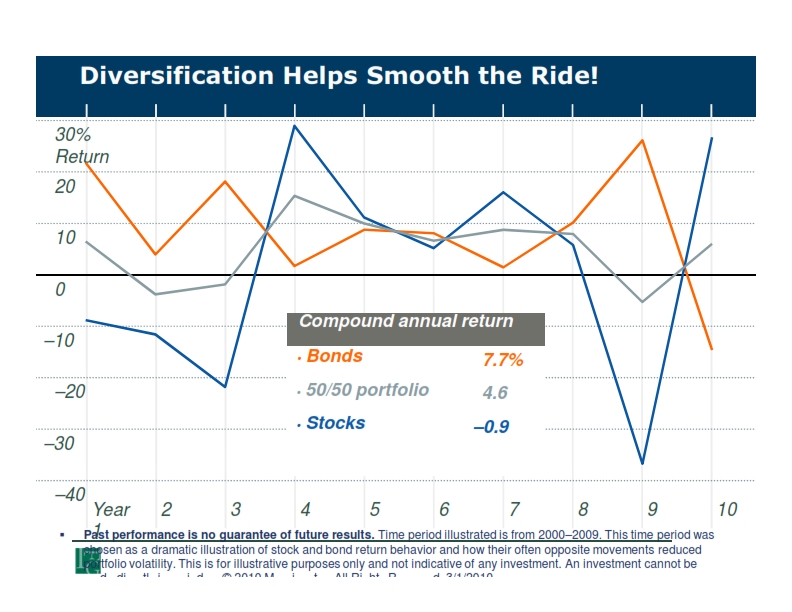](https://indfin.com/wp-content/uploads/2017/04/Diversification_SmoothTheRide.jpg)But, what stocks? Which bonds? Is buying a few enough? The answer, of course, is “it depends”; but, it’s worth noting that there are five basic asset classes (stocks, bonds, real estate, commodities, and cash) and within each there are multiple sectors. It’s also virtually impossible to know which will outperform all others in any given year. Yet, diversification among them can smooth the ride!
[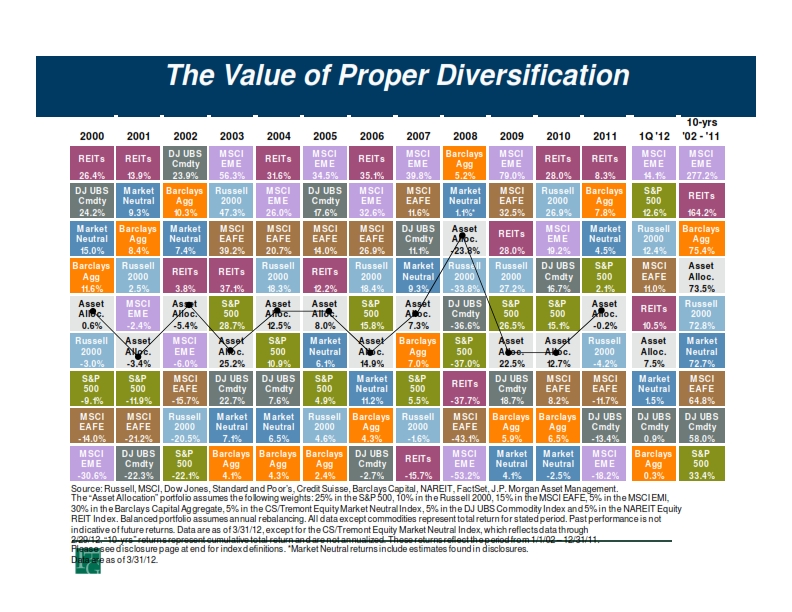](https://indfin.com/wp-content/uploads/2017/04/Diversification_Value.jpg)I’ve been telling clients for more than two decades now, “We’re not diversifying money. We’re diversifying risk; we just do it with money.”
So, how do we diversify risk? It’s all about something called correlation.
You can think of correlation as pistons in an engine: They all go up and down, but not necessarily at the same time. Their going up and down is what propels the machine, but you wouldn’t want your money on any one piston. If the engine were to stop, you’d have a 50/50 chance of being up or down! But, if your money was spread over all the cylinders, you’d still have a stable overall value regardless of when the engine shut down.
It doesn’t really work all that clearly in the real world of investing, of course; but the theory is no less valid. Here’s a chart the relative correlations among a number of classes and styles.
[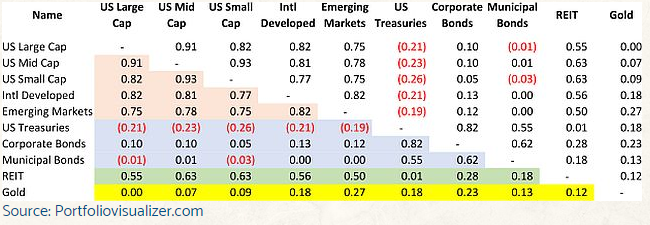](https://indfin.com/wp-content/uploads/2017/04/Asset_class_Correlations_2017-04-13.png)
Correlations don’t remain the same, even from day-to-day; so, they’re not in stone – they just give us a historical look at their relative movements, but the numbers will be different depending on the time-frames chosen.
[](https://indfin.com/wp-content/uploads/2017/04/i306_Understanding-The-Diversification-Puzzle_001.png)Diversification is all about correlation reduction in portfolios. I created a report on all this a while back called***Understanding the Diversification Puzzle.*** You might find it helpful and you can get it here.
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** investment returns, Investment Strategy, managing risk, Reducing Risk
---
### [Inflation, Stocks, and Computing Investment Returns](https://indfin.com/inflationandstocks/)
**Published:** April 11, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2016/11/Fotolia_4812344-DB-wDollarSign.jpg)Jim Lorenzen, CFP®, AIF®**
People are often either surprised to hear that stocks are probably the best inflation hedge they’ll ever find – or they really don’t understand why.
Those who intuitively believe it believe it’s simply because stock prices tend to rise over time; but, so do prices for other things, generally, including real estate. After all, as a long-term hedge, most real estate is a good inflation hedge, as well. It’s only real drawback, most believe, is the lack of liquidity it entails.
When my parents retired, the common practice was to simply “ladder” bond or CD maturities as many counted on rising interest rates to offset inflation. While inflation had averaged only 2% in te 1950s and 2.3% in the 1960s, all of a sudden climbed to 6.2% in 1973 and by 1974 had reaced 11%. Bonds, of course, paid higher rates to the holders, but after taxes, the income didn’t keep up with inflation.
From 1973 to 1982, inflation averaged 8.7%! A little math reveals that the purchasing power of bond income had declined 57% in just one decade; and, as many found out, they were living longer, too!
Enter the 1980s and a newfound interest in stocks, which continued into the 1990s and even into the 2000s. But why?
**The reason lies in a simple, basic premise:** stocks represent shares of ownership in businesses – businesses that sell goods and services in the marketplace. When you eat breakfast, everything you eat or drink was grown, packaged, distributed, and sold by a business. Everything we consume was sold by a business. The largest providers, distributors, and sellers are publicly held – the ownership shares are owned by people like you and me – and often in their 401(k) plans through their ownership of mutual fund shares, which are shares of ownership in investment companies which, in turn, buy shares in publicly held companies.
So, if prices go up, stocks go up. Is it that simple? Actually, there’s more to it.
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b0192ac05f306970d-320wi.jpg)iStock ImagesTake an (admittedly oversimplified) example of a company that generates $1 million in sales and $800,000 in expenses. Let’s assume the remaining $200,000 is paid out in dividends.
If inflation causes prices to double, sales rise to $2 million and expenses rise to $1.6 million, now creating $400,000 in dividends. Dividends have doubled, despite the fact that all margins have remained the same. That’s how stocks become an inflation hedge, with liquidity.
This is exactly what happened throughout the 1980s. The decade began with the S&P paying out around $7 in dividends, when the index paid out a 5.3% yield as it stood at $133. By 1990 it was paying out around $12.50 when the index was up to $340, for a 3.7% yield. As the yield went down, stock prices went up; yet, the investor saw cash flows rise from $7 to $12.50! This actually did better than inflation, which averaged 4.7% – up 58%.
Of course, dividends are not guaranteed and stocks have both business and market risk – a good reason why people relied on “blue-chip” stocks and a sound asset allocation process.
It’s also important to understand investment returns, including their measures (there’s more than one) and why most individual investors typically don’t do as well as institutional investors. If you’d like to learn more about this topic, you might want to see our report, which you can access here.
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Inflation, Investing, Planning, Retirement
**Tags:** calculating returns, Inflation, investment returns
---
### [Inflation Can Cause Financial Glaucoma](https://indfin.com/inflation-can-cause-financial-glaucoma/)
**Published:** October 10, 2013
**Author:** Jim Lorenzen
**Content:**
Remember when gas was 35-cents a gallon? You could fill a 10-gallon tank for $3.50! I know; I did – it was a small hatch-back. Heck, I even remember when Coca-Cola was 5-cents I think Grant was President, I forget – now it’s a buck something; talk about losing purchasing power.
When Reagan was president, a first-class postage stamp was 8-cents! The lesson is simple and as unchanging as a politician’s desire to get reelected: Every year everything will cost a little more than it did the year before because our money is worth less and therefore purchases less.
I once saw a 1955 LIFE magazine featuring a full-page ad from a big insurance company with the headline: ***“How To Retire in 30 Years n $500 a Month for Life!”*** But, $500 wouldn’t have bought much even in 1985.
Wealth cannot be measured by how many pictures of presidents we have in our wallets; but by what those pictures of presidents *will actually buy*.
There was a time not long ago when $2,000 a month was a good income; now it’s poverty level. I could go on, but you get the picture.
Unfortunately, too many of us (like sheep) chase the investment fad of the day, whether it’s flipping real estate or hoarding gold, silver, or anything else. I like seafood; but, it’s never the only thing on my plate. A balanced diet, in moderation, works day in and day out, regardless of the fads others chase.
It’s NOT “where” do you PUT your money “right now”. It’s HOW do you ARRANGE assets to plan for your FOREVER!
If you haven’t talked with a *[CERTIFIED FINANCIAL PLANNER](https://en.wikipedia.org/wiki/Certified_Financial_Planner "Certified Financial Planner")® lately, it might be your next best move.
Jim
**RESOURCES:**
IFG Report: [The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk) (registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist) (does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights) to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on [Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®** professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [MONEY OR INCOME: Which is most important to you?- Part 3](https://indfin.com/incomeormoney-3/)
**Published:** August 15, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/09/LTop_Maintain_Purchasing_Power.png)Jim Lorenzen, CFP®, AIF®**
**An income for life – a lifetime retirement income strategy is whatmost people want – but are they willing to do what’s required?**
For most, if not many, the idea of ‘bucketing’ money into categories – current needs, emergency needs, and future needs – is intuitive. An that’s the ‘secret’ behind having a retirement income for life! It’s not a secret, really; just a common sense strategy for creating a stress-free lifetime retirement income.
We don’t want to take money from one to fund another unless we’re absolutely FORCED to, which we seldom are – yet, that’s what a lifetime retirement income strategy demands.
This likely explains why people generally hate the idea of annuitization, even though retirees routinely say their biggest fear is running out of assets – aha! Assets! Not income?
I’ve known people who’re retired with generous pensions (with cost-of-living adjustments) from the federal government and lived [](https://indfin.com/wp-content/uploads/2017/05/lorenze-R5-019-8.jpg)amazing retirements, living on Florida waterfront property with boats outside their back doors, even though they had only a couple hundred thousand dollars in savings… and loving it. You couldn’t get them to trade those pensions for *anything*! It was predictable – it would never stop – and they had COLAs built-in!
But, the rest of society seemingly isn’t willing to make the liquidity trade. Research seems to back this up, finding that the size of liquid holdings is directly related to their sense of well-being and satisfaction. Apparently if they can’t achieve their need for future income until they meet their need for current assets, they feel cash-strapped – or they’ll choose retirement solutions that are inferior but psychologically more satisfying..
**Mental bucketing comes in two forms:**
- **Time segmentation**: Cash, bonds, and stocks are segmented according to time frames. Cash funding near term, laddering bonds for intermediate term and interest-rate risk, and stocks for long-term inflation-hedges.
- **Spending segmentation**: Using financial tools to put predictability into outlays – Using Social Security and immediate annuities to create an ‘income floor’ for meeting essential expenses, and using portfolio withdrawals throughout the entire retirement period to provide for discretionary expenses.
For many, however, the delineation between essential and discretionary expenses can be fuzzy. When people prioritize their goals, some will classify travel and cable tv as a need, while others will find few needs beyond food, shelter, transportation, medical expenses, etc. And, many neglect to think about the biggest outlay they’ll make during their entire retirement – the annual tax payment to the I.R.S.
**The most straightforward solution to longevity risk**
For most, the biggest risk is outliving their money. In short, it means running out of income. The straightforward solution is simple: Trading a portion of liquidity to pay cash for a lifetime income – and transferring longevity risk to an insurance company in exchange for an immediate annuity. For many, this is a tough sell because they aren’t willing to give up liquidity of current assets to secure a lifetime income, despite the fact all those retired federal retirees in Florida have been doing it for years – and loving it. And, also despite the fact that an immediate annuity solution is far superior to that of using a variable annuity with a guaranteed lifetime withdrawal benefit.[\[1\]](#_ftn1)
Not only that, retirees want the potential for an increasing standard of living, as well! Others may have additional legacy goals! Inflation-adjusted immediate annuities are available, but haven’t been too popular due to their lower initial payout
The Hybrid Time-Segmentationâ„¢ (HTS) solves many of the issues and may appeal to investors who need a greater degree of certainty for their income strategy.
[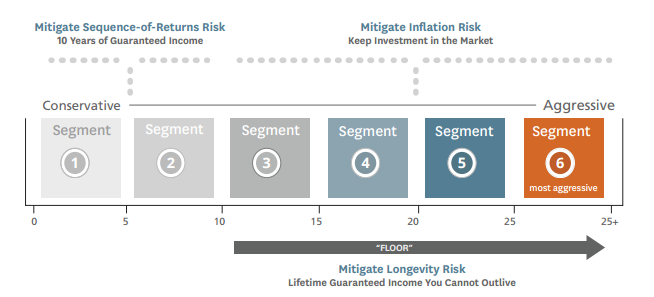](https://indfin.com/wp-content/uploads/2017/05/Allocation_Process.png)
The HTS strategy puts an ‘income floor’ under the segments – a floor that’s both predictable and expected to last a lifetime, while still preserving short-term liquidity needs and providing for long-term inflation concerns. For example, one popular approach is to use a portion of assets to purchase a ten-year deferred income annuity that provides a lifetime retirementincome beginning in year #11. In this way, an additional guaranteed income source is added providing an increased floor as the rest of the portfolio grows for future years.[\[2\]](#_ftn2) The entire strategy, of course, should coordinate liquidity, security, inflation-protection, and income needs.
[](https://indfin.com/wp-content/uploads/2014/09/iStock_73740177_SMALL.jpg)
If you’d like to learn more – and it’s worth doing – we have a twenty-minute educational video that explains this lifetime retirement income strategy. I think you’ll like it! Grab some coffee, sit back, and learn more here.
Enjoy!
Jim
[\[1\]](#_ftnref1) I must admit my own bias against variable annuities. To me, using the stock portion of a portfolio to purchase a variable annuity is only turning a potential capital gain into taxable income – something that’s made little sense to me, expenses aside.
[\[2\]](#_ftnref2) Using an ‘investment grade’ insurance company is more important, in my view, than simply grabbing for the best-sounding promise of a slick marketing campaign.
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** investment returns, Investment Strategy, managing risk, Reducing Risk, retirement decisions, Retirement Income
---
### [MONEY OR INCOME: Which is most important to you?- Part 2](https://indfin.com/incomeormoney-2/)
**Published:** August 8, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/09/iStock_64047885_SMALL.jpg)Jim Lorenzen, CFP®, AIF®**
Last week I asked which was most important to you:
**Never running out of money**
**Never running out of income**
Whether you’re building a house or your ‘financial house’, it begins with a plan – that’s common sense. Yet, I’ve seen more than a few people make major financial decisions BEFORE ever walking through my door for the first time: Ready, fire, aim.
I’ve seen them retire, make Social Security claiming decisions and even pension decisions… then seek out financial advice – moves that often put them behind the 8-ball before they start.
So, what are the hazards retirees face?
- **Being underfunded**. It’s not uncommon today for people to live thirty years in retirement – one good reason why so many are opting to continue working after their ‘formal’ retirement. It takes a lot of capital to fund thirty years of income after taxes and inflation – for two lives. The problem with this hazard is that it’s extremely difficult, if not impossible, for an advisor to change at the point of retirement.
- **Bad timing**. This is something we call ‘sequence of returns’ risk. To illustrate using simple numbers and ignoring taxes, imagine this scenario: You retire with $1 million and plan to withdraw 4% annually. That $40,000 combined with Social Security should meet your needs.
**If the market goes up** 20% and you withdraw 4%, you should have $1,160,000 after the first year. Allowing for a 3% inflation rate, you can withdraw $40,000 + inflation = $41,200 in your second year, which computes to 3.55% of the second year’s beginning balance. Not bad. If the market does that every year forever, you’re fine!
**What if the market goes down** 20% in the first year as you withdrew your $40,000 (4% of the original balance)? The market loss was $200,000 and you withdrew $40,000. At the end of year #1, you’re down $240,000 and your new balance is $760,000 at the beginning of year #2. And, of course, prices are higher – inflation has driven your living costs up by 3%! You’ll need to take $41,200 in the second year, just as in the first scenario above, but now it’s coming from a starting balance of $760,000, which means your withdrawals now represent 5.42% of assets. Another down year could be disasterous.
Diversification can help[\[1\]](#_ftn1). Diversification is all about using asset classes that have low correlation in their movements. Think of pistons in a car: If they all went up and down and down at the same time, where would they all be if the engine were to shut down? Oddly enough, you may not want a portfolio that contains investments that all go up – the opposite could happen, too!
- **Withdrawing too much too soon**.
Some people may simply not know how much they can, or should, withdraw. With longevity risk becoming greater with our medical advances, knowing how much we can withdraw presents a problem for many.
[](https://indfin.com/wp-content/uploads/2017/05/Coffee_with_RMD_Pencil.png)**How do you know how much you CAN withdraw and never run out of money?** The government has the answer! They even publish it! It’s the IRS required minimum distribution rules! Just plug your numbers into the calculator[\[2\]](#_ftn2) and that shows how much can be withdrawn! The RMD rules apply to all qualified plans, but not to Roth IRAs while the owner is alive, and can be used for other accounts as a guide to avoiding longevity risk.
**The good news**: RMD math virtually guarantees against running out of money within 45 years if the amount withdrawn is that calculated and no more. There’s a practical weakness in this method as a guide for annual income, as well: Remember our sample $1 million portfolio?
Practical: Withdraw 4% of the original account balance each year, adjusted for inflation, regardless of market returns, i.e., $40,000 base adjusted only for COLAs each year. Weakness: Could lead to early depletion of assets if there are continuous market declines.
Not practical: The RMD calculation is based on a percentage of the account value. If the market declines, the percentage could result in a declining income for one or more years.
**The bad news**: The RMD amount might be less than what’s needed to meet living expenses and, as noted, could even decline! So, asset allocation, using the RMD rules, does not affect portfolio survival; but it does affect how much the retiree might receive each year – an unpredictable income.
**How do we create a sustainable LIFETIME income?**
That’s our subject for next time.
[\[1\]](#_ftnref1) You might want to access our report, *Understanding the Diversification Puzzle.*
[\[2\]](#_ftnref2)
Enjoy!
Jim
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** investment returns, Investment Strategy, managing risk, Reducing Risk, retirement decisions, Retirement Income
---
### [If Inflation is Going Down, Why Don’t People Feel It?](https://indfin.com/if-inflation-is-going-down-why-dont-people-feel-it/)
**Published:** December 12, 2023
**Author:** Jim Lorenzen
**Excerpt:** Inflation deflates purchasing power. We all know that. After all, money is worth only what it buys.
**Content:**
**Not a news flash: inflation hurts; but not everyone has the same agenda.**
- Politicians are interested in popular support – they compete for ballots.
- The news media is interested in popular viewership – they compete for ratings
- Neither of them are concerned about educating the pubic and, unfortunately, the public at large often turns to their phones or flat screens for entertainment disguised as information.
Everyone wants to see prices go down – it means we can buy more! But, here’s what isn’t being told: declining prices is deflation. So what?
**A little history:**
Back around 1979-80 prices were rising (inflation) at a double-digit rate – as much as 15-17% annually. As a result, many people were engaging in ‘defensive buying’, i.e., buy now – it’ll only cost more later.
Deflation is taught us the opposite is also true. When prices are dropping, people stop buying because they think prices will go lower in the future. Unfortunately, when prices fall, so do paychecks as businesses can pay less for labor. Prices and paychecks may decrease, but debt doesn’t – welcome to the Great Depression. Not good. Prices falling means your house is worth less and other assets are depreciating, as well.
If a bank advertises 1% loans when prices fall by 5%, the real interest rate on that loan is 6%. Money is worth only what it will purchase.
So, why are we being told inflation is getting under control and people still feel pain? It’s the rate that’s declining, not the nominal dollars. If inflation used to be 8% and now the rate is down to 3%, that item you want to purchase still costs 3% more than last year – on top of all the previous price increases. And, salaries, etc., haven’t caught up yet. Simple.
**Is inflation good?**
A certain amount, yes, which is why the Fed has been targeting 2% for many years now through multiple administrations. Modest increases contribute to productivity and job growth.
For those of you who like reading about this stuff, you might check out *Basic Economics* by Thomas Sowell and *Naked Money* by Charles Wheelan. I also recommend *Boom and Bust* by William Quinn and John D. Turner – a global history of financial bubbles.
Will your long-term financial plan survive for the next twenty to thirty years? Start planning now! You can get started here.
Enjoy!

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [How Will Rising Interst Rates Affect Your Bond Values?](https://indfin.com/how-will-rising-interst-rates-affect-your-bond-values/)
**Published:** August 26, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a511dcc667970c-320wi.jpg)
Rising interest rates can have an effect on bond values. After all, if you’re holding a bond paying 2% and interest rates for comparable bonds rise to 3%, you’ll have trouble finding a buyer unless you’re willing to reduce the price of the bond to make up the difference.
In addition, a bond paying 2% for the next thirty years will be harder to sell than one that has only one year left. This means that, generally speaking, the longer the maturity the more the price will be affected by rising rates.
But, maturity measures only the time until principal is due – it doesn’t consider the coupon payments. Duration is a measure that incorporates both the magnitude of the principal and interest payments and the timing of those payments, as well. Think of duration as the weighted average time to receipt of both coupon and principal payments. For those of you familiar with time-value-of-money, the weights are the present value of each cash flow.
If you own bond funds, you can often find duration figures for the funds you own from a variety of commercially-available sources; and, that’s the data that will help you determine how much your bond values are likely to change in response to interest rate movements. Today, duration is expressed as modified duration (a math adjustment to more accurately reflect interest rate sensitivity).
Without getting too deep into the weeds of bond math, this formula will help you determine what price changes you can expect with a change of interest rates:
Price Change = (Duration) x ( – Yield Change)
For example, if you find your bond portfolio has a modified duration of 7.4 and market interest rose by 0.50% per year, the bond portfolio value could be expected to decline to around 3.7%. By the same token, if interest rates fell by 0.50%, you could expect the bond portfolio to add 3.7%. The higher the duration, the higher the interest rate sensitivity.\\
There are some limitations you should be aware of:
- Duration is useful over only a limited range of yield change
- Price changes due to changes in bond quality or changes in sectors aren’t considered
- Duration assumes the shape of the yield curves will remain unchanged – in the real world, they do change.
There’s more to know, of course. Talk to your advisor.
Jim
—-
**RESOURCES:**
**Visit** [**Jim’s Social Security Learning Center**](https://www.jlorenzen.sswise.com/ "Social Security Learning Center")
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Conversation Checklist") (does not require registration)
[Subscribe to IFG Insights ](https://tinyurl.com/IFGInsights "Subscribe to IFG Insights")
[The IFG Website](https://indfin.com/ "IFG Website")
IFG’s [Financial Resources website](https://finsecurity.com/Lorenzen "IFG Financial Resources Website").
Follow Jim on Twitter: @JimLorenzen
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Uncategorized
---
### [How to Get Money From An Illiquid Asset and Not Pay Uncle Sam](https://indfin.com/how-to-get-money-from-an-illiquid-asset-and-not-pay-uncle-sam/)
**Published:** May 21, 2013
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01901c236980970b-320wi.jpg)You own an illiquid asset (land, buildings, etc) and you’d like to sell; but, you don’t want to get hammered with capital gains taxes (now at 20% in 2013). That’s a situation many people find themselves in.
One solution worth discussing with your CFP®professional and an estate planning attorney is a charitable remainder trust (CRT).
Here’s the short version: You can gift the property into the trust. This lets you sell the building without paying taxes on the increased value and invest the sale money – all of it – into passive investments (stocks, bonds, mutual funds, ETFs, etc.), and take a large charitable deduction in the process, because the assets will ultimately go to charity; but, in the meantime, you can increase your cashflow.
Not bad: You’ve achieved a huge charitable deduction, sold your property and avoided taxes, increased your cash flow, and helped a charity!
But, what if you the money to go to your children? Simple: Use the money you saved on the taxes to purchase a life insurance policy. It wouldn’t be surprising to find that the amount they receive from the life insurance would be greater than the value of the property… and they’ll likely receive those proceeds tax-free!
As they say, don’t try this at home. Talk with your professionals about this.
Jim
———————–
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://digioh.com/em/6318/5225/66272hevvs?demail=$SUBSCRIBER.EMAIL$ "Hidden Risk Report")(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist)(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights "IFG Insights")to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/ "IFG Website")
Follow Jim on Twitter: @jimlorenzen
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn profile")
IFG on[Facebook](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
———————
***Jim Lorenzen is a[CERTIFIED FINANCIAL PLANNER](https://en.wikipedia.org/wiki/Certified_Financial_Planner "Certified Financial Planner")®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,****a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [How to Create A Risk-Free Investment Strategy.](https://indfin.com/how-to-create-a-risk-free-investment-strategy/)
**Published:** November 13, 2023
**Author:** Jim Lorenzen
**Excerpt:** So, you want to dive into the stock market without losing your sanity or, more importantly, your hard-earned cash? Here's a strategy that's not exactly 'rocket science' – Here’s a risk-free investment strategy that’s a ‘diet version’ of a financial plan. It surely doesn’t cover all the bases, but it's sure to spice up your next dinner party conversation.
**Content:**
Let’s imagine you’ve got $100,000 in your mattress, and you’re as risk-averse as Aunt Bee who wants only a risk-free investment. If your timeline is next Tuesday, you will forever be in your mattress. However, if you’re in it for the long haul, let’s say a solid 10 years, that’s different.
**Step #1** of the risk-free investment strategy: Secure that ‘I’m-serious-about-this’ vibe by investing $61,391 in a 10-year Treasury bond. Currently, the Treasury is yielding about 4.6%, so I’m going to use 5% in this example to keep things simple. Your financial calculator will do the math dance and reveal that $61,391 invested at 5% will mature at $100,000 in a decade. Voila! You’re getting your money back with interest – it’s like magic, but with more numbers.
**Step 2**: Now, with the remaining $38,609 still burning a hole in your pocket, let’s dip our toes into the stock market waters. No one knows what the market will do, but let’s throw caution to the wind and assume an 8% average annual return for the next 10 years. If pigs start flying, and that actually happens, you could end up with a sweet $83,353 from the stock portion. Ah ha! Your grand total return is $183,353, and the best part? No risk of losing sleep over your investments.
**Okay. Reality check**: Crunching the numbers reveals that your received a total return of 6.25% over the decade. But wait, maybe it’s not such a risk-free investment strategy after all. Taxes and inflation show up to the party, and suddenly your after-tax return, assuming 3% inflation and a 24% tax bracket, is doing a limbo dance at a mere 1.75%. And that’s if you’re in a state with no state income tax!
What was it we learned about a free lunch? Turns out, it might not be free, but at least it’s entertaining. If you’re guessing there’s a better way to reach your goals, you’re right. And, of course, it begins with a plan.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
**Tags:** Financial planning, Investment Strategy, managing risk, Reducing Risk, Retirement Planning
---
### [How to Buy or Lease Your Next Car!](https://indfin.com/how-to-buy-or-lease-your-next-car/)
**Published:** January 10, 2013
**Author:** Jim Lorenzen
**Content:**
Believe it or not, car buying isn’t as much of a hassle as it used to be – the reason is simple: There’s so much available information through internet sites.
If you’re looking at a new car, it’s now possible to see exactly what the dealer paid – and, I’m not talking about the ‘dealer’s invoice’; that’s a marketing ploy, as is the manufacturer’s suggested retail price (MSRP).
The thing to remember is that car dealers like ‘moving parts’ in a negotiation. The more moving parts there are, the more they can manipulate. Moving parts include:
- The price of the car
- Trade-in value
- Financing
- Fees and other add-ons
They’ll ask about whether you want to buy or lease and whether you have a trade-in.
**Whether you want to buy or lease, whether you have a trade-in or not**, you want to begin with this:
- It’s about the price, not the payments.
- You’re paying cash. If they ask about leasing, say “No, thanks.”
- You have no trade-in
You’ve just removed two of the moving parts. So, here are your steps along with my little story:
1. **Test-drive** the cars you’re interested in at various dealerships. They’ll ask you about your trade-in and whether you plan to lease or buy. Remember: No trade-in; you’re paying cash. If you like a car you driven, ask for the literature on the car, including the `trim line’.
2. **Do your homework**. *Consumer Reports* has an excellent car buying site, as well as a service, for both new and used cars. It’s worth paying for the reports on the cars you’re interested in. Once you’ve decided on a couple of candidates, it’s time to get your ducks lined-up. Whether you plan to lease or buy, you should know your credit score, which you can also find online. If you plan to finance, you might check out some local credit unions, your bank, or something like LendingTree.com and get *pre-qualified for your* loan. When you’re all ready with homework and financing completed, head back to the dealership(s). Take your homework with you.
3. **Re-Test, if necessary**. Need to test-drive again? Do
4. **Get Extra Fees in writing**. When the salesman asks you to sit down; remember negotiating isn’t about ‘winning’ or acting tough. It’s about helping him see your side; but begin with this:*“Before we begin talking about the car, can you give me an itemized list of the extra fees that will be added to the price?”* A reputable dealership will do it readily and easily. Mine was very cooperative. When I asked, he said said, “Sure!” and ran out of the room, returning in 30 seconds with a computer print-out. You can expect vehicle registration, license, etc.; but if `dealer prep’ charges are there, cross it off in front of him – they didn’t try to charge it in my case. You’ve just removed the last remaining moving part. Now, it’s about the cash price.
5. **The negotiation.** It’s amazing what objective third-party numbers can do to solidify your position. Now, remember, the dealership has to make money. They have overhead, payroll, etc., like any other business; but, once armed with the true cost the dealership pays, you’ll know about how much profit you can reasonably build-in. As I said, the *Consumer Reports*website will be helpful, here. Make your offer – of course, you’ll low-ball a little; but those third-party numbers and your transparency makes your case pretty compelling. And, of course, the salesman has no ‘moving parts’ to play with. **It’s strictly about the cash price**.
The last time I did this, the salesman was very nice; but, quick and adamant that he just couldn’t meet my price – big surprise.
I smiled and said, “I understand. You’re probably right! The car may indeed be worth more than this… I guess I’m simply negotiating for the wrong car!” I was packing my things as I said it. There was a $4,000 spread. But he insisted it was the right car, despite the fact I had done my homework on others.
Short version: He wanted to move that unit. The dealership came down $3,000, if they could handle the financing (he makes a commission on the financing, too). At the time I did this a little over a year ago, I had already put financing in place at a very low rate ; he came back and said he quoted a slightly lower rate with no prepay penalties, blah, blah, blah. That was fine with me. At that time, rates were SO low, it was questionable whether I should pay cash when I could use the money to add technology to my planning practice, since it would earn more there than I would be paying in interest.
Quick note: When you see 0% financing offers, the dealership is building the financing into the price knowing they can work with all the ‘moving parts’.
What if they don’t meet your price? You leave. After all, there are other cars and dealerships. Let him know, “I’m not saying `*no’* to you; I’m saying this isn’t the right car. Maybe there’s another! Maybe you have it! Want to go test-driving?” He didn’t.
- We’re done. Extra add-ons were eliminated early, the price was settled, and the prequalifying allowed me to negotiate the price I wanted.
1. If this were a lease deal, I would have worked it the same way. Once the price is established, I could have asked? “What would the residual value of a \_\_\_-month closed-end lease look like? Also, ‘What’s your lease factor?”
2. If I were doing a trade-in, that would come up after everything else is settled. “I’m glad we have a deal!” Then, I’d stare out the window at my car. “I’m not sure my niece really needs it – maybe she’d rather have the down payment for another car. How much do you think my car’s worth?” – you did your homework on that car, too. I actually gave my car to my brother-in-law.
3. The ‘business office’ stop should be a formality. The extra charges (vehicle registration, etc.,) have been previously disclosed and there’s no dealer prep. The price is set and the financing is in place. The ‘trade’ value, if any, comes off the price. The moving parts are done. My stop took four minutes.
You’ll find that reputable dealerships are easy to deal with because the amount of available information has actually made their job easier. When there’s transparency – everyone knows the real story – it’s easier to meet with mutual advantage. If they don’t want to share fees, etc. in front, it’s time to look elsewhere.
Jim
—————–
Jim Lorenzen, CFP*®*, AIF*®*
*Jim Lorenzen is a Certified Financial Planner® and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of* [*The Independent Financial Group*](https://indfin.com/)*, a fee-only registered investment advisor with clients located in New York, Florida, and California. IFG provides investment and fiduciary consulting to retirement plan sponsors, and retirement and wealth management services for individual investors.*
Additional IFG Links:
- Twitter; @JimLorenzen
- Jim’s MoneyBlog
- IFG on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp)
- IFG on [Facebook](https://www.facebook.com/IFGAdvisory)
*IFG does not sell products, earn commissions, or accept any third-party compensation or incentives of any description.* IFG does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional. The Independent Financial Group does not sell financial products or securities and nothing contained herein is an offer or recommendation to purchase any security or the services of any person or organization.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [How Much Should You Be Saving?](https://indfin.com/how-much-should-you-be-saving/)
**Published:** July 18, 2013
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b0192ac05f306970d-320wi.jpg)A recent survey by the Employee Benefit Research Institute reveals that 20% of respondents believe they should save 20% to 29% of their income for retirement.
That might be right.
For example, a 50-year old who makes $120,000 per year abd saving 20% or $2,000 per month will have $619,548.45 at age 67 (this includes a starting balance of $10,000.00 and a 4.25% annual rate of return).
What would saving 20% mean for you? You can find out with [this calculator](https://vsa.fsonline.com/pnuco/kje2/CompoundSavings.html "Savings Calculator").
```
---------------------
```
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as
securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [How Middle-Income Boomers Are Planning For Retirement](https://indfin.com/how-middle-income-boomers-are-planning-for-retirement/)
**Published:** September 28, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/06/iStock_67121241_SMALL.jpg)Conceptual one way signs on LifeJim Lorenzen, CFP®, AIF®
According to a survey conducted by Bankers Life Center for a Secure Retirement, middle income boomers aren’t paying much attention to planning for their old age.
Here are some of the results:
While 61% have taken at least one step in retirement planning, about only 1% havetaken all the steps.
Only 25% have calculated a monthly retirement goal – no information on what method they used – but only 12% have translated that into an account balance goal.
Only 9% have developed a formal, written plan (how this happened with only 1% having completed all the steps, noted above) is a little interesting.
Nevertheless, they still have some work to do, it appears. Maybe a good first step might be attending our retirement planning webinar this coming Saturday. They can learn more and register here.
---
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients providing retirement planning and wealth management services since 1991. Jim is Founding Principal of The Independent Financial Group, a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement
**Tags:** Retirement Planning, Retirement Strategy, retirement webinar
---
### [Higher Tax Rates for Trusts](https://indfin.com/higher-tax-rates-for-trusts/)
**Published:** May 30, 2013
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01910219a734970c-320wi.jpg)**The taxpayer relief act**– I love that name since tax rates went up – raised the top tax rates that trusts pay on income. So, for 2013, new rates apply when trust taxable income goes over $11,950. And, in case you didn’t know, the 3.8% Medicare contribution tax also applies to trust income above that figure.
Remember: Even though the tax law is supposed to be permanent, it means it will be permanent only until the next change.
Note: The income of these trusts is taxed to the trust creator, instead of the trust itself, allowing trust assets to grow without the tax burden, which allows more money to be distributed to trust beneficiaries later on. Of course, that means grantors of trusts previously set-up may not be as happy about the arrangement as they were originally. Few people really like giving more money to Washington.
Non-grantor trusts may be able to distribute income in a way that reduces a family’s total tax outlay, but doing so may inhibit future growth inside the trust.
Now may be a good time to talk with your tax professional and, of course, your estate planning attorney.
Jim
————
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://digioh.com/em/6318/5225/66272hevvs?demail=$SUBSCRIBER.EMAIL$ "Hidden Risk Report")(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Financial Conversation Checklist")(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights "IFG Insights")to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter: @jimlorenzen
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn profile")
IFG on[Facebook](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
———————
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,****a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Hidden Surrender Charges](https://indfin.com/hiddencharges/)
**Published:** September 14, 2020
**Author:** Jim Lorenzen
**Excerpt:** I don’t know anyone, certified financial planner professionals included, who is a fan of surrender charges; but, economically they are a fact of life for many products simply to make the offering available and viable for the investment or financial product provider.
**Content:**
#### You could be paying them without knowing it. It pays to do some math.
**[](https://indfin.com/wp-content/uploads/2016/10/Checkbook-Pen.jpg)Jim Lorenzen, CFP®, AIF®**
I don’t know anyone, certified financial planner professionals included, who is a fan of surrender charges; but, economically they are a fact of life for many products simply to make the offering available and viable for the investment or financial product provider.
For consumers, the surrender charge represents an obstacle that stands between them and having total liquidity–and the charge itself reduces the value of the product should that liquidity be required at some future date. Sometimes, however, consumers are already paying for the liquidity they desire even if they never need or use it!
**Hypothetical example**: Mary and John have $150,000 “just in case” money set-aside in savings. They have no particular purpose for it but they like knowing it’s there if they should need it. They’re not making much interest, of course, probably less than 2% – but they like the liquidity. They’ve heard about another investment that in all likelihood could help them achieve a 5% return, but it has a surrender charge–something they would like to avoid–so they’re staying with their savings account. In effect, due to the return difference, they’re paying 3% per year for their liquidity right now. In three years, they will have paid 9% – $13,500! In five years the liquidity/opportunity cost will be 15% – $22,500–even without growth.
Maybe the alternative might be a better bet–especially if other questions result in favorable answers: Is the tax treatment different? How much of the money is even subject to surrender charges and how much might be liquid without surrender charges? Does it make sense to pay 3% in opportunity cost up front for liquidity they may not even use–or does it make more sense to pay for it when it’s needed? And how much would it even be?
It pays to do the math and examine all alternatives.
Jim
————————————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Annuities, IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, Investment mistakes, investment planning, investment returns
---
### [HEALTH CARE COSTS MAY EAT HALF OF YOUR SOCIAL SECURITY INCOME](https://indfin.com/health-care-costs-may-eat-half-of-your-social-security-income/)
**Published:** July 27, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi2.jpg)**Jim Lorenzen, CFP®, AIF®**
The 2016 Retirement Health Care Costs Data Report recently released by Healthview Services found that health care costs are continuing to rise, as if any of us are surprised, of course.
According to Marlene Y. Satter, writing for BenefitsPro.com in the July 2016 issue of *Retirement Advisor*, a healthy person retiring in 2016 can expect to spend $288,400 in today’s dollars on lifetime Medicare Parts B, D, and supplemental insurance premiums.
There’s more. Ms. Satter indicates that Social Security isn’t going to be of much help, either:
- A 66-year-old retiring this year will need 57% of the Social Security to cover health care costs.
- A 44-year-old retiring in 10 years will need 88%.
- A 45-year-old couple will require 116%!
And, she says, it’s going to get worse! A 30-year-old female retiring at 65 can expect to pay $548,098… $118,632 more than a male the same age.
Wow.
What to do?
The simple truth for long-term investors is that nothing beats growth; but older investors may be tempted to grab any “sure thing” that comes down the path – thus the popularity of annuities, even at current low interest rates.
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019aff2c9b18970d-320wi.jpg)*Fotilla Images*But, before you leap, it’s worth doing some homework. You can begin with the Income Annuity Primer. It won’t tell you *everything* you need to know; but, it’s a start.
Naturally, the Social Security claiming decision can be a costly mistake if not made properly. We have a LifeGuide on retirement and Social Security you might like, as well. You can get it here.
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement
---
### [Have You Had "The Talk"?](https://indfin.com/have-you-had-the-talk/)
**Published:** September 26, 2013
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019aff2c523c970c-320wi.jpg)You know…. the one with your parents… or your children.**
Not yet? Procrastination is easy. It’s something you can always do later, right?
Maybe not.
This picture isn’t a stock photo; it’s of my wife and I with my parents after we brought them from Florida to California to live with us in 2005. This picture was taken for my mom’s 91st birthday (she’s 99 and still with us today). Thankfully, we had been planning the financial transition for some time. When the time came, all the ducks were lined-up.
Many haven’t done that, however. And, procrastination can cause problems. It’s worth being pro-active. You might want to read this[New York Times article](https://www.nytimes.com/2013/05/25/your-money/aging-parents-and-children-should-talk-about-finances.html?ref=your-money-email&nl=your-money&emc=edit_my_20130528&_r=3& "NY Times_The Talk").
Having the conversation can be difficult for some because of a number of perceived barriers. Some need to feel in control; others may feel the need to avoid possible confrontation.
Quite often a good financial planner can help by acting as a facilitator, helping determine what subjects the client may wish to cover and then providing a roadmap for discussion, possibly involving the family attorney and accountant – something your planner can coordinate.
Financial writer Dan Richards suggests some potential topics:
- Estate plan and any trusts
- Life insurance
- Long term care and other insurance
- Value of investments, assets and possessions
- How current investments are allocated
- Will
- Executors Power of attorney Location of documents
- Advanced health directive
- Funeral arrangements
- Special gifts
- Legacy
Having this discussion*before you need to*can make things a lot easier; and, having an outside facilitator can provide an independent framework and remove some of the barriers to discussion.
Jim
———————–
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk)(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist)(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights)to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
*Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Guarantees Against Loss Not A Panacea... but maybe still valuable.](https://indfin.com/guarantees-against-loss-not-a-panacea-but-maybe-still-valuable/)
**Published:** August 31, 2016
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01901dd12617970b-320wi.jpg)Jim Lorenzen, CFP®, AIF®**
**Active managers can’t beat their indexes consistently.**
**Who cares?**
During my 25+years of helping people navigate financial waters, I can honestly say I have never had a single client who cared about beating an index – any index – except inflation.
Pretty amazing since most media tend to focus on only two things: Active managers vs. a passive index and cost of ownership. Little, if anything, is ever said about the value provided. To them, apparently, value is ‘nil’.
Actually, our industry is at fault, as well. Look at our quarterly or annual reports. Performance is always measured against an index or some blend of indexes. Industry custodians don’t get it, either.
The ONLY index that REALLY counts is long-term performance measured as progress toward your personal goals, measured in probabilities. Probabilities, after all, are all we really have to work with since there are no guarantees in life. Even our money isn’t guaranteed; it’s “backed by the full faith and credit of….”
So, what approach offers the best chance of meeting your goals? As you might guess, there is no one right answer. The answer will depend on which approach is most appropriate for you.
**Managing the downside**
When active managers are chosen for a portion of a client’s portfolio, in most cases what the investor is really seeking are returns that outpace inflation while limiting downside risk.
Take a look at this purely hypothetical 10-year market environment. You’ll see our hypothetical market begins and ends with 20-point gains. There are six years of +20% and four years of -20%.
[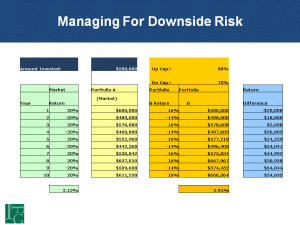](https://indfin.com/wp-content/uploads/2015/04/Image_Managing-for-Downside.gif)
Portfolio A begins with $500,000 and invests in that market. To keep things simple for illustrating this concept, we’ll ignore expenses and taxes. Those aside, you’ll note the average annual compound return and the ending value. The numbers aren’t important except for comparison with the next chart.
IHere’s a hypothetical portfolio that’s been managed for downside risk. Here our fictitious manager is very conservative, capturing only 80% of the upside of each up-market, and also very effective, capturing only 70% of the downside moves. Despite the fact this manager never beat the market on up years, outperforming by limiting losses in down years lead to an overall outperformance.
It’s a made-up scenario, I know, but it does illustrate a concept: Limiting the downside can be quite effective – maybe even more than trying to beat the market indexes and accepting big downside losses.
**What if we eliminate the downside altogether?**
Insurance companies market their equity-indexed annuities and equity-indexed universal life products with this guarantee. What if you could capture 100% of the upside up to a ‘cap’ of 12%, for example, and be guaranteed that you never lose money? You’ve seen the commercials.
Here’s the same hypothetical market return, this time compared to the strategy that eliminates downside risk! Wow! Looks good! Compare the ending values with our manager limiting losses in the prior example. Now, even if you factor in expenses and inflation, it would still look pretty good.
[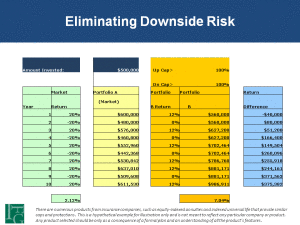](https://indfin.com/wp-content/uploads/2015/04/Image_Eliminiating-the-Downside.gif)
**But, does this method outperform in all markets?**
In this third chart, I’ve created another hypothetical series of market returns starting at -10% and moving all the way up to +35% over ten years. There are only two down years, yet despite that, this market return series outperformed the guaranteed return. In fact, our downside guaranteed portfolio came in $477,000 BELOW the ‘market’ portfolio.
You could create a million market return sequences and come up with a million different variations. The point is while these downside guarantees don’t necessarily mean you will make more money, they can provide a valuable ‘protected’ return.
[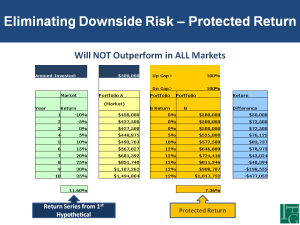](https://indfin.com/wp-content/uploads/2015/04/Image_Protected-Return.png)
Again, who cares? If the portfolio is advancing you to your goals, that should be all that counts.
**But, how do you position these guaranteed products in your portfolio?**
What asset-class should they be assigned to? Just because you may have participation with a stock index, do those assets get assigned to the stock portion of your allocation? If not, why not? And, how would you position them?
The answer might surprise you. Many retirement plans may fail. Some time ago I created a report on this subject – you might find it helpful. You can access it here.
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** Investment Strategy, retirement mistakes, Retirement Planning
---
### [Getting Ready to Change Jobs?](https://indfin.com/getting-ready-to-change-jobs/)
**Published:** March 7, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/should-investing-be-fun/6a017c332c5ecb970b017c37dfb72e970b-120wi/)*iStock images*There’s more to changing jobs than simply getting a (hopefully) higher salary. This “One Sheet” will provide you with a list of some additional issues you may want to consider. Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
---
### [Funding Retirement and College Costs, too? How?](https://indfin.com/funding-retirement-and-college-costs-too-how/)
**Published:** April 17, 2014
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5118d6207970c-320wi.jpg)Retirement planning and college funding are, for many parents, hopelessly connected**.
The reason is simple: Whatever is spent on college usually comes at the expense of a secure retirement.
Today, tuition, fees, room and board at a public four-year institution can total $31,700 for a single school year and around $41,000 at private schools – and we’re not talking about the top-tier ‘brand names’. Multiply that by a minimum of four years and the number of children a parent wants educated, and it’s a chunk of bucks.
Parents and students want to purchase the best education possible; and, of course, the colleges are marketing their product, competing for the right students.
**But, costs are rising dramatically**. A Fidelity study of recent graduates found that 70% are carrying personal debt averaging more than $35,000. I’m not sure who Fidelity was talking to; but many advisors report seeing students graduating with $60,000 to $80,000 in debt.
**There appears to be a disconnect.** The financial aid system isn’t designed to support the top-tier university system; it’s more designed for community college level funding.
Advisors have long known that comprehensive wealth management planning includes the typical components of college savings, investing, insurance, taxes, and estate gifting. Much of the planning for college, however, has traditionally centered on saving FOR college – not saving ON the cost of college.
For most, 529 plans are inadequately funded; and many parents are surprised to find that the subsidized Stafford loan program provides for a maximum of just $3,500! They may also qualify for a maximum of $2,000 in unsubsidized Stafford loans – and they may also find some help from the states; but, it still seems to many like small drops in a large bucket.
**Saving ON the cost of college requires a strategy.** But, to formulate one, it’s best to have a roadmap. For most, it requires more than simply adding up loans and scholarships.
**Failure to optimize a funding strategy can be expensive**. Think about it: When it comes to funding a college education, a $10,000 mistake doesn’t happen just once; it happens every year! Over four years – and many take four to six years due to transfers resulting from choosing the wrong school in the first place – that $10,000 mistake can become a $40,000 mistake… for a single child! Two kids? Three kids? The math is simple.
Because these mistakes can prove so costly, and potentially destroy many parent’s plans for retirement – an issue near and dear to our hearts – I’ve decided to allocate some resources to making a dedicated college funding service offering available to IFG clients, which fits with my philosophy of providing clients with custom-tailored solutions utilizing independent and objective service providers.
**A little news:** IFG has partnered with [Collegiate Funding Solutions](https://ccc.collegiatefundingsolutions.com/), which can provide clients with a dedicated Client Care Center, to help efficiently guide clients through the entire process. As you can probably guess, my work centers on the financial strategies side, and you can learn more about how we can help clients on the [IFG College Funding website](https://www.ifgcollegefunding.com/). There, you can:
- Download a free and informative report, ***“**Insider Strategies and Secrets to Reducing Your College Costs”***
- See a short video, ***“A Lesson in Paying for College”.***
- Learn how much scholarship money your student qualifies for;
- Subscribe to the CFS award-winning e-newsletter,***College Ed Xpress,*** and stay informed about important college planning, funding, and admissions information,
- **See college-specific projected four-year costs** – for virtually any college your student(s) wish to attend
- **Arrange to receive a quick diagnosis ofyour specific situation** – a valuable and important step to getting it right.
- There’s even **a college planning primer** on the planning and financial aid landscape.
If you have a high school student wondering about navigating the maze, even as you’re wondering how you can make it happen financially without jeopardizing your retirement or amassing a huge debt, there’s little time to waste.
Enjoy the site! I hope you find the information helpful.
Jim
***ADDITIONAL RESOURCES:***
**College Planning and Funding Strategies** – Just like with the airlines, there are often two prices people pay for the same education: The price paid by the informed and the price paid by the uninformed. What are the projected four-year costs for the college your student desires? How much scholarship money will your student qualify for? You can see a short video, *“A Lesson in Paying for College”,* and download a free report, “*Insider Strategies and Secrets to Reducing your College Costs.”* You can learn more on the [IFG College Funding site](https://www.ifgcollegefunding.com/).
**Retirement Income Planning**– The wrong Social Security claiming strategy could conceivably cost hundreds of thousands of dollars and have a dramatic impact on your other retirement assets! Knowledge is more than power; it’s real money. You can learn how to [get to the right strategy](https://tinyurl.com/SocialSecurityStrategies) with the right planning.
**Arrange a brief15-minute introductory phone call with Jim Lorenzen, CFP®, AIF®** [**here**](https://tinyurl.com/IFGIntroCall)**.**
**Financial Planning and Investing:**
IFG Report: Understanding Mutual Funds
IFG Report: The Hidden Risk No One Talks About (Registration required)
Begin the discussion with your spouse with this [Financial Converstion Checklist](https://indfin.com/financial-conversation-checklist). (No registration required)
Facing financial decisions but feel you need to do some homework first? You might benefit from looking through our free [Life Guides](https://tinyurl.com/IFGLifeGuides) and using some [financial worksheets](https://tinyurl.com/IFGWorksheets)!
Visit the[IFG Website](https://indfin.com/)!
Follow Jim on Twitter: [@jimlorenzen](https://twitter.com/JimLorenzen)and also [Jim’s MoneyBlog](https://www.jimsmoneyblog.com/)
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp)
IFG on [Facebook](https://www.facebook.com/IFGAdvisory)
Become an IFG client! [Schedule your 15-minute introductory phone call here](https://www.timetrade.com/book/F7ZPS)!
———————
Jim Lorenzen is a[ *CERTIFIED FINANCIAL PLANNER®*](https://en.wikipedia.org/wiki/Certified_Financial_Planner) professional and An Accredited Investment Fiduciary® in his 21st year of private practice.
The Independent Financial Group is a fee-only registered investment advisor with clients located across the U.S. He is also licensed for insurance as an independent agent under California license 0C00742.Jim can be reached at 805.265.5416 or (from outside California) at 800.257.6659.
**Interested in becoming an IFG client?** Why play phone-tag? You can easily [schedule your 15-minute introductoryphone call!](https://www.timetrade.com/book/F7ZPS)
The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Financial Literacy Soccer Game](https://indfin.com/financial-literacy-soccer-game/)
**Published:** July 22, 2014
**Author:** Jim Lorenzen
**Content:**
Financial planning, whether for retirement or anything else, can sometimes appear a little boring to many people. How much do most people really know about financial matters? You may know more than you think!
If you like soccer, you can have some fun while you test your financial literacy. I learned about this online game in one of the industry trade magazines and tried it out. You can play alone or with someone else.
It’s pretty easy to learn. [Give it a try](https://www.financialsoccer.com/play/ "Soccer Financial Literacy Game")! You might enjoy it!
Jim
**RESOURCES:**
**Visit** [**Jim’s Social Security Learning Center**](https://www.jlorenzen.sswise.com/ "Social Security Learning Center")[ ](https://www.typepad.com/site/blogs/6a017c332c5ecb970b017ee4d0333b970d/post/6a017c332c5ecb970b01a73ddd02ba970d/www.jlorenzen.sswise.com "Jim's Social Security Learning Center")
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Conversation Checklist") (does not require registration)
[Subscribe to IFG Insights ](https://tinyurl.com/IFGInsights "Subscribe to IFG Insights")
[The IFG Website ](https://indfin.com/ "IFG Website")
IFG’s [Financial Resources website](https://finsecurity.com/Lorenzen "IFG Financial Resources Website").
Follow Jim on Twitter: @JimLorenzen
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [How to Diversify Investments - As simple as a pie chart?](https://indfin.com/diversification/)
**Published:** July 11, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b0192ac851ba2970d-320wi.jpg)Jim Lorenzen, CFP®, AIF®**
#### Most of us want to learn how to diversify investments so we can reduce investment risk – but it may be one of the most misunderstood of investment principles. Too many think it’s about simply selecting the right pie chart.
I’ve even seen tv stock gurus tell you that owning three stocks in different industries passes forinvestment diversification, implying that risk is being reduced. I don’t think so; it’s just compounding investment concentration.
Believe it or not, you can’t possibly diversify-away market risk. Think about it; you could own every single stock contained in the S&P 500 Index and all you would have done is *duplicate* the market’s risk.
[](https://indfin.com/wp-content/uploads/2017/04/DiversificationVsDuplication.jpg)
I’ve also seen investors buy multiple mutual funds in an attempt to diversify; but, since everything they bought had to be “quality”, all they did was duplicate their holdings (portfolio A) instead of diversifying them (portfolio B) across multiple investment styles (growth/value, large/small, etc.).
Diversification, done properly, can smooth things out, as this simple example shows.
[](https://indfin.com/wp-content/uploads/2017/04/Diversification_SmoothTheRide.jpg)But, what stocks? Which bonds? Is buying a few enough? The answer, of course, is “it depends”; but, it’s worth noting that there are five basic asset classes (stocks, bonds, real estate, commodities, and cash) and within each there are multiple sectors. It’s also virtually impossible to know which will outperform all others in any given year. Yet, diversification among them can smooth the ride!
[](https://indfin.com/wp-content/uploads/2017/04/Diversification_Value.jpg)I’ve been telling clients for more than two decades now, “We’re not diversifying money. We’re diversifying risk; we just do it with money.”
So, how do we diversify risk? It’s all about something called correlation.
You can think of correlation as pistons in an engine: They all go up and down, but not necessarily at the same time. Their going up and down is what propels the machine, but you wouldn’t want your money on any one piston. If the engine were to stop, you’d have a 50/50 chance of being up or down! But, if your money was spread over all the cylinders, you’d still have a stable overall value regardless of when the engine shut down.
It doesn’t really work all that clearly in the real world of investing, of course; but the theory is no less valid. Here’s a chart the relative correlations among a number of classes and styles.
[](https://indfin.com/wp-content/uploads/2017/04/Asset_class_Correlations_2017-04-13.png)
Correlations don’t remain the same, even from day-to-day; so, they’re not in stone – they just give us a historical look at their relative movements, but the numbers will be different depending on the time-frames chosen.
[](https://indfin.com/wp-content/uploads/2017/04/i306_Understanding-The-Diversification-Puzzle_001.png)Diversification is all about correlation reduction in portfolios. I created a report on all this a while back called***Understanding the Diversification Puzzle.*** You might find it helpful and you can get it here.
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** investment returns, Investment Strategy, managing risk, Reducing Risk
---
### [Congress Turns to Roth accounts to Raise Revenue – Again.](https://indfin.com/congress-turns-to-roth-accounts-to-raise-revenue-again/)
**Published:** January 8, 2013
**Author:** Jim Lorenzen
**Content:**
Back in 2006 the government passed a law that took effect in 2010 lifting income restrictions on converting individual retirement accounts (IRAs). Now, there’s no limit on conversions nor a cap on the amount that can be shifted.
The budget deal that passed Congress on January 1st allows 401(k) participants to convert any money in their tax-deferred accounts to a Roth 401(k) account, provided the option is available in their plan, of course. This would allow the participants to withdraw money tax-free in retirement. The old law allowed participants to convert part of their money, with a number of restrictions. Basically, this new law is allowing participants to convert any money in their plan and it may encourage more employers to offer Roth 401(k) accounts.
According to the Joint Committee on Taxation, this change could raise as much as $12.2 billion in revenue over 10 years, helping to defray the cost of delaying spending cuts that had been set to take effect this month.
For some, this change could benefit those who have significant balances in their 401(k) accounts, the money to pay taxes from assets outside their 401(k) assets, and who have years of tax-free earnings ahead of them or their heirs.
Wealthy investors who want to leave their retirement accounts to heirs and younger savers are the ones who may benefit most… it allows them to pay taxes now for their kids!
Younger investors – the ones who’s 401(k) constitutes a small part of their net worth – may want to consider converting a portion or all of their 401(k)s now since they have more time in the future to recoup the initial tax outlay and to grow their money virtually tax-free.
Don’t plan on running out and doing this right away. Companies offering these plans are going to be looking for guidance from the Treasury Department before making amendments to their plans and, according to Bloomberg, only about 12% of plan sponsors offer and allow conversions to Roth 401(k) accounts.
**Points woth remembering**
The old law allowed taxpayers to choose whether to pay the tax all at once or split it over two years when converting. The new law has no such option.
When you do a conversion, you have to pay a tax. It’s best if you can pay them from assets outside your 401(k) plan in order to maintain the asset level in your retirement account.
Those at or near retirement with a 401(k) balance that constitutes a large portion of net worth needed for retirement years probably shouldn’t make a conversion..
Look out for “legislative risk” – Tax laws seem to change frequently; and while some feel the government will lower taxes in the future, others believe the ‘middle class’ will not be able to escape higher taxes as our national debt continues to increase. Diversification of legislative risk could be accomplished by partial conversions. Thinking about where you will retire is important, too. You may want to consider retiring to a state with no state income taxes – I have quite a few clients who’ve done just that!
—————
*Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® in his 21st year of private practice as Founding Principal of* [*The Independent Financial Group*](https://indfin.com/)*, a fee-only registered investment advisor with clients located in New York, Florida, and California. IFG provides investment and fiduciary consulting to retirement plan sponsors, and retirement and wealth management services for individual investors.*
Additional IFG Links:
- Twitter; @JimLorenzen
- Jim’s MoneyBlog
- IFG on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp)
- IFG on [Facebook](https://www.facebook.com/IFGAdvisory)
*IFG does not sell products, earn commissions, or accept any third-party compensation or incentives of any description.* IFG does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional. The Independent Financial Group does not sell financial products or securities and nothing contained herein is an offer or recommendation to purchase any security or the services of any person or organization.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Are You Recharging Your Batteries?](https://indfin.com/are-you-recharging-your-batteries/)
**Published:** August 22, 2013
**Author:** Jim Lorenzen
**Content:**
Many years ago, back during my days in publishing, I read an exchange between Jack Nicklaus and Lee Trevino – this was when Jack Nicklaus was dominating golf, much like Tiger did some years ago. Of course, we know today that Jack Nicklaus ended-up with 18 professional majors… more than Lee Trevino, Arnold Palmer, and Gary Player combined!In those days, Jack Nicklaus was known for playing a limited schedule of around 15 tournaments each year, while others were out there almost every week! Lee asked Jack if he had any idea how many tournaments he would have won if he’d actually played full-time like everyone else! Jack said he would have probably wouldn’t have won as many! He said he felt his success was due to the fact that when he played, his “tank was full”… he was never playing running on half-empty!
Jack had his life compartmentalized – evenly divided between family, his business, and golf. Whatever he was engaged in, his mind was never someplace else. Each could get full attention without distraction because he was always fresh.
While many others came to the course tired; he came rested and ready to play.
Many of you are heading-off to vacations about now. Enjoy!
Jim
—————
**RESOURCES:**
IFG Report: [The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk) (registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist) (does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights) to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on [Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
**Interested in becoming an IFG client?** Why play phone tag? [Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!") your 15-minute introductory phone call!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Another Wealthy Celebrity (apparently) Gets Bad Advice](https://indfin.com/another-wealthy-celebrity-apparently-gets-bad-advice/)
**Published:** July 25, 2013
**Author:** Jim Lorenzen
**Content:**
The heirs of actor James Gandolfini, best known for playing mobster Tony Soprano, aren’t likely to be too happy with his tax advisors.
The actor left 80% of his $70 million estate to relatives other than his wife, creating an estimated $30 million federal and New York tax bill.
You can read all about it [here](https://www.investmentnews.com/article/20130712/FREE/130719966?utm_source=indaily-20130712&utm_medium=in-newsletter&utm_campaign=investmentnews&utm_term=text "Gandolfini's heirs won't like this.").
Jim
—————
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [A Reverse Mortgage Quickie Primer](https://indfin.com/a-reverse-mortgage-quickie-primer/)
**Published:** May 1, 2014
**Author:** Jim Lorenzen
**Content:**
**Reverse mortgages can be worthwhile; but, there’s no free lunch. Here are some issues to review.**
A reverse mortgage is a loan against the value of your home that does not have to be paid back for as long as you live in the home. Simply put, a reverse mortgage converts some of the equity in your home into income. And, because it’s really loan proceeds you’re receiving, it’s free of income tax liability (be sure to talk with your tax advisor anyway).
**But, remember, there’s no free lunch, and there are issues you should consider:**
• Typically, a reverse mortgage must be a “first” mortgage, meaning that if you still owe money on your home, you must pay off the existing mortgage before you can get a reverse mortgage (note: an initial lump sum payment from a reverse mortgage can be used to pay off an existing mortgage).
• Keep in mind that, while you don’t have to repay a reverse mortgage for as long as you live in the house, the amount that ultimately has to be repaid does grow over time. So, your outstanding balance is growing each month – at a rate which may or may not keep pace with the home’s value or inflation. However…
• While the amount of debt grows over time, the reverse mortgage repayment cannot exceed the value of your home at the time it is ultimately sold.
• If you take out a reverse mortgage, you continue to own your home. This means that you continue to be responsible for expenses such as property taxes, hazard insurance and home maintenance and repair.
• Reverse mortgage proceeds may affect eligibility for assistance under state and federal programs.
• The upfront costs associated with a reverse mortgage, such as an origination fee, closing costs and mortgage insurance premium, can be significant. This means that a reverse mortgage may be expensive if the loan is repaid within a few years of closing. As a result, if you anticipate moving within a few years, you should explore another alternative, such as a home equity loan.
• Repayment of a reverse mortgage when your home is sold will mean less equity left to pass to your heirs.
Hope this helps!
Jim
—————————
***ADDITIONAL RESOURCES:***
**Retirement Income Planning**– The wrong Social Security claiming strategy could conceivably cost hundreds of thousands of dollars and have a dramatic impact on your other retirement assets! Knowledge is more than power; it’s real money. You can learn how to [get to the right strategy](https://tinyurl.com/SocialSecurityStrategies) with the right planning.
**Arrange a brief 15-minute introductory phone call with Jim Lorenzen, CFP®, AIF®** [**here**](https://tinyurl.com/IFGIntroCall)**.**
**College Planning and Funding Strategies** – Just like with the airlines, there are often two prices people pay for the same education: The price paid by the informed and the price paid by the uninformed. What are the projected four-year costs for the college your student desires? How much scholarship money will your student qualify for? You can see a short video, *“A Lesson in Paying for College”,* and download a free report, “*Insider Strategies and Secrets to Reducing your College Costs.”* You can learn more on the [IFG College Funding site](https://www.ifgcollegefunding.com/).
**Financial Planning and Investing:**
IFG Report: Understanding Mutual Funds
IFG Report: The Hidden Risk No One Talks About (Registration required)
Begin the discussion with your spouse with this [Financial Converstion Checklist](https://indfin.com/financial-conversation-checklist). (No registration required)
Facing financial decisions but feel you need to do some homework first? You might benefit from looking through our free [Life Guides](https://tinyurl.com/IFGLifeGuides) and using some [financial worksheets](https://tinyurl.com/IFGWorksheets)!
Visit the[IFG Website](https://indfin.com/)!
Follow Jim on Twitter: [@jimlorenzen](https://twitter.com/JimLorenzen) and also [Jim’s MoneyBlog](https://www.jimsmoneyblog.com/)
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp)
IFG on [Facebook](https://www.facebook.com/IFGAdvisory)
Become an IFG client! [Schedule your 15-minute introductory phone call here](https://www.timetrade.com/book/F7ZPS)!
———————
Jim Lorenzen is a[ *CERTIFIED FINANCIAL PLANNER®*](https://en.wikipedia.org/wiki/Certified_Financial_Planner) professional and An Accredited Investment Fiduciary® in his 21st year of private practice.
The Independent Financial Group is a fee-only registered investment advisor with clients located across the U.S. He is also licensed for insurance as an independent agent under California license 0C00742. Jim can be reached at 805.265.5416 or (from outside California) at 800.257.6659.
**Interested in becoming an IFG client?** Why play phone-tag? You can easily [schedule your 15-minute introductory phone call!](https://www.timetrade.com/book/F7ZPS)
The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Economy Maybe Not So Strong After All](https://indfin.com/economy-maybe-not-so-strong-after-all/)
**Published:** December 6, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/09/Fotolia_5386670-DontSkipDetails.jpg)*Fotila Images***Jim Lorenzen, CFP®, AIF****®**
The [new jobs report](https://www.bls.gov/ces/) shows 178,000 jobs were created last month – and much of the media has reported that number; however, there’s a number missing: All but 9,000 were part-time.
While unemployment has dropped from 5% to 4.6% over the past year, the participation rate has remained constant and those eligible workers not in the labor force has actually gone up, as [you can see](https://indfin.com/wp-content/uploads/2016/12/BLS-Nov-2016.pdf).
All of this, of course, seems to be forming a pattern occurring in an environment of[ increasing national debt.](https://www.usdebtclock.org/) If you want to give the politicians your own feedback on this, there are[ resources you can use](https://www.jct.gov/resources.html).
If you’re one of those trying to navigate retirement planning in the midst of all the media `white noise’ and financial uncertainty, it might help to have a roadmap. Maybe I can help. You can begin here.
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Economy, IFG Viewpoint & Outlook, Planning, Retirement
---
### [Does the 4% Rule Still Work?](https://indfin.com/does-the-4-rule-still-work/)
**Published:** February 27, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi.jpg)
Jim Lorenzen, CFP®, AIF®
Before you can take income from a nest-egg, you have to HAVE a nest-egg; but, getting there takes more than discipline – it takes MOTIVATION! What motivates YOU?
Here are some thoughts from The Financial Planning Association:
**Reality Check**
It used to be that Americans could count on a pension plus Social Security to get them through their Golden Years. But traditional pensions only account for an estimated 18% of the total aggregate income of today’s retirees, and Social Security accounts for only about 36%.1Alas, the responsibility for the bulk of your nest egg now rests with you.
As you begin thinking about a comfortable retirement, consider that by most estimates you’ll need at least 60% to 80% of your final working year’s income to maintain your lifestyle after retiring. And don’t forget that your annual income will need to increase each year — even during retirement — in order to keep up with inflation. At an average annual inflation rate of more than 3%, your cost of living would double every 24 years.
You’ll also have to consider the likelihood of increased medical costs and health insurance premiums as you grow older. The average cost of a year’s stay in a semi-private room in a nursing home, for instance, is now over $80,000 a year and could rise more than $130,000 per year by 2030, assuming an annual inflation rate of 3%.2
**Getting a Leg Up**
If this dose of reality makes you glum, cheer up — you have some allies. Investment vehicles, such as your employer-sponsored retirement plan and individual retirement accounts (IRAs), allow you to put off paying taxes on your earnings until you begin taking withdrawals, typically during retirement when you may be in a lower tax bracket.
Additionally, time can be an ally — or an enemy. Delaying the process of investing can significantly reduce your results. Consider this example: Jane begins investing $100 a month in her employer-sponsored retirement plan when she’s 25. Mark begins investing the same amount when he’s 35. Assuming an 8% annual rate of return compounded monthly, when Mark retires at 65, he’ll have $150,030. Jane will have $351,428.3
While this is only a hypothetical scenario and there are no guarantees any investment will provide the same results, you can see the remarkable difference starting early may make. But no matter what your age, contributing the maximum amount to your employer-sponsored retirement plan and IRA each year could help you achieve the comfortable retirement that each of us desires.
***Source/Disclaimer:***
*1Source: Social Security Administration, Fast Facts & Figures About Social Security, 2013.*
*2Source: Genworth Financial, Inc. and National Eldercare Referral Systems, LLC, Cost of Care Survey, 2013.*
*3Example is hypothetical and for illustrative purposes only. The hypothetical rates of return used do not reflect the deduction of fees and charges inherent to investing and the example does not represent the return of any actual investment. Your results will vary.*
*Because of the possibility of human or mechanical error by Wealth Management Systems Inc. or its sources, neither Wealth Management Systems Inc. nor its sources guarantees the accuracy, adequacy, completeness or availability of any information and is not responsible for any errors or omissions or for the results obtained from the use of such information. In no event shall Wealth Management Systems Inc. be liable for any indirect, special or consequential damages in connection with subscriber’s or others’ use of the content.*
*© 2014 Wealth Management Systems Inc. All rights reserved.*
**Click on this video!**
[](https://indfin.com/wp-content/uploads/2014/10/236-thumb.jpg)[**Retiring the 4% Rule**](https://www.fmgwebsites.com/jimlorenzen/resource-center/retirement/retiring-the-4-percent-rule)
A portfolio created with your long-term objectives in mind is crucial as you pursue your dream retirement.
**ADDITIONAL RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk)(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist)(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights)to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
[The IFG Managing Life’s Risks Website](https://finsecurity.com/Lorenzen)
Follow Jim on Twitter:
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
The[Joint Committee on Taxation](https://www.jct.gov/resources.html)
**Become an IFG client!**Don’t play phone-tag; schedule your 15-minute introductory phone call using[this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,**a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Do Your Investments Match Your Risk Profile?](https://indfin.com/do-your-investments-match-your-risk-profile/)
**Published:** November 19, 2013
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi3.jpg)Ask anyone. Most investors tend to associate risk with loss. But losing money can happen without market risk every day: Congress can raise taxes, inflation can reduce purchasing power, your spouse can beat you to the dresser in the morning.
Investment risk incorporates other risks and understanding them, along with the potential return associated with each one of them can help you determine whether your investments are appropriate for your situation.
Depending on the time frame, most would agree, I think, that stocks have historically been associated with the highest level of market risk — the potential that an investment may lose money in the short term. It’s also true that over the long term stocks have outperformed both bonds and cash investments.1This risk/return tradeoff may influence how you allocate your investments.
The bond market, of course has its own set of risks: Credit risk, the possibility that a bond issuer could default on interest and principal payments; and interest rate risk, the chance that rising interest rates could cause a bond’s price to fall, are both examples. Rising interest rates historically have influenced the prices of bonds more directly than stocks.1When short-term rates are on the rise, investors may sell older bonds that pay a lower rate of interest — causing their prices to fall — in favor of newly issued bonds that pay higher interest rates. On the plus side, bonds historically have exhibited less short-term volatility than stocks; but, you can see how market forces can operate.
Don’t overlook the importance of reviewing even cash investments, such as money market funds, from the vantage point of risk and return.1Although money market funds typically experience a low level of volatility, they may be subject to inflation risk — the possibility that their returns may not keep pace with the rate of inflation, like in our current environment where money market instruments aren’t much different from cash, from a yield point of view…. Okay for emergency funds you may need within the next year.
Risk management is really all about correlation. In an ideal world, all your investments would be diversified among assets that would move up and down in varying degrees – like the pistons in an engine. Two of them are always opposite and the rest vary in degrees of correlation in their movement. Too bad the world is never so ideal; but, we try. Reducing correlation has become more difficult over the years as the markets themselves seem to have become more correlated, which is why alternative approaches, like floating-rate strategies have seemingly started to find their way into more investors’ portfolios as rates have begun to rise.
Important to understand: You really can’t diversify away market risk. If you bought every stock in the market, you’d be diversified, for sure; but, you would have only*replicated*market risk, not reduced it.
Jim
1You know the speech: Past performance does not guarantee future results. Investment in a money market fund is neither insured nor guaranteed by the U.S. government, and there can be no guarantee that the fund will maintain a stable $1 share price. The fund’s yield will vary.
————
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk)(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist)(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights)to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
*Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Do You Know Your Social Security Options?](https://indfin.com/do-you-know-your-social-security-options/)
**Published:** July 8, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73de5d743970d-320wi.jpg)
TEN THOUSAND AMERICANS TURN AGE 65 EVERY DAY!
For some, making the decision to claim retirement benefits early may be right choice. But by claiming benefits early, millions of people could be losing out on tens-of-thousands, or even hundreds of thousands of dollars.
The Center for Disease Control and Prevention ([CDC](https://www.cdc.gov/aging/data/ "CDC")) tells us we’re living longer. But while “65” is synonymous with retirement, in terms of claiming Social Security benefits, age 65 has little meaning for almost three-quarters of us. The reason: Almost 75% choose to receive Social Security retirement benenfits BEFORE their [full retirement age](https://en.wikipedia.org/wiki/Retirement_Insurance_Benefits "Retirement Insurance Benefits").
Can you afford to wait? Or, is the appeal of claiming retirement benefits early just too strong? Knowing how Social Security works, and what you could be sacrificing, is information that can boost your retirement security for decades to come.
Today, many people are worried about outliving their money – and, well they should: We’re living longer!
In 1935, life expectancy in the U.S. was 61.7 years . By 2010 it had increased to 78.7 years\*.
Consider a married couple age 65. There’s a 50% chance that one spouse will live to age 92. And a one-in four chance that one spouse will live to age 97\*\*. As of December 2010\*\*\*, 5.8 million Social Security beneficiaries were at least age 85. Some were much older.
*\* [National Center for Health Statistics](https://en.wikipedia.org/wiki/National_Center_for_Health_Statistics "National Center for Health Statistics"), National Vital Statistics Reports*
*\*\* Annuity 20000 [Mortality Table](https://en.wikipedia.org/wiki/Life_table "Life table"), Society of Actuaries*
*\*\*\* Social Security Administration Facts and Figures About Social Security, 2011*
Unfortunately, many people tend to engage in short-term thinking; they believe – usually without investigation – that claiming benefits early is the best course. That may have been true for our parents; but it could be the wrong choice for you. Indeed, a mistake can cost hundreds of thousands of dollars!
If you feel that you are likely to live to age 80, or, 85, you should think carefully about delaying benefits until even after your full retirement age. This is because for every year that you wait beyond full retirement age, your monthly check will be increased by an additional 8%.
Waiting until age 70 means receiving 32% more retirement income versus age 66,and 75% more income compared to age 62. That’s $1,800 per month at age 62, versus $3,168 at age 70.
**There are a number of claiming strategies; but, no one strategy is right for everyone!**
I’ve created a little “mini” website containing videos and other info you might find helpful. You can locate it[here](https://tinyurl.com/IFGSSWise "Jim's Social Security Learning Center")!
Enjoy!
Jim
——————
**RESOURCES:**
**Visit** [**Jim’s Social Security Learning Center**](https://www.jlorenzen.sswise.com/ "Social Security Learning Center")
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Conversation Checklist") (does not require registration)
[Subscribe to IFG Insights ](https://tinyurl.com/IFGInsights "Subscribe to IFG Insights")
[The IFG Website](https://indfin.com/ "IFG Website")
IFG’s [Financial Resources website](https://finsecurity.com/Lorenzen "IFG Financial Resources Website").
Follow Jim on Twitter: @JimLorenzen
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Do You Know the 5 Biggest Risks To Your Retirement?](https://indfin.com/do-you-know-the-5-biggest-risks-to-your-retirement/)
**Published:** July 15, 2015
**Author:** Jim Lorenzen
**Content:**
Jim Lorenzen, CFP®, AIF®
**Do you know what your biggest retirement risks are?**
[](https://indfin.com/wp-content/uploads/2015/07/5-Biggest-Risks-to-Your-Retirement_ifgi_001.png)Many might think, after watching all the coverage about Greece, computer glitches on Wall Street, and stories about hackers, that it might be the financial markets; but, the fact is there have been all kinds of melt-downs over the years and some people’s plans were unaffected!
Those people, of course, tended to be the ones that had plans that anticipated the 5 Biggest Risks!
You can download this reporthere.
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
---
### [Beware: The COVID-19 Scammers are Loose.](https://indfin.com/covid-19-scammers/)
**Published:** April 6, 2020
**Author:** Jim Lorenzen
**Excerpt:** IRS Coronavirus resoures
**Content:**
You need to keep safe financially too!
**[](https://indfin.com/wp-content/uploads/2020/04/International_Stop_Sign_WebCD.png)Jim Lorenzen, CFP®, AIF®**
Here are some ways you can “social distance” yourself from these parasites:
“¢ Hang up on robocalls, and don’t press any numbers. You’ll get robo-calls selling fraudulent COVID-19 treatments and work-at-home schemes. Press a number to be removed from a list and you’ll likely get more calls because they sell the lists and any response simply validates the phone number.
“¢ Ignore online offers for vaccinations and unproven home test kits. You’ll see lots of internet posts pitching success stories – look for CDC clinical trials and hard data.
“¢ Ignore texts and emails about cash from the government. Don’t click on anything. Stimulus checks will be forthcoming, but, according to the FTC, anyone who tells you they can get you the money now is a scammer.
“¢ Do NOT respond to emails that claim to be from Centers for Disease Control and Prevention (CDC) or experts that claim they have information about the virus. Government agencies do not email. For the most up-to-date information about coronavirus, visit the websites of the CDC (my personal choice) or the World Health Organization (WHO).
“¢ Malware and phishing scams are on the uptick. Legitimate companies will never ask you to verify passwords or usernames via an email. Fraudsters will. Again: do not click on any links. Get the proper URLs independently.
“¢ Do you see misspelled words or grammatical mistakes? That’s a sure sign that the official-looking email originated from a suspicious source.
——-
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook
**Tags:** Coronavirus
---
### [Counting on Your Business To Finance Retirement?](https://indfin.com/counting-on-your-business-to-finance-retirement/)
**Published:** May 23, 2013
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01901c238330970b-320wi.jpg)Not so fast. It’s common for a 60-something business owner to count on finding a buyer, selling for an attractive figure, then live off the proceeds for the rest of his/her life. But, when you look at real-world cases, it often isn’t true.
The fact is most business owners soon learn they may not be able to afford retirement after all; and, it can affect those with companies worth $20 million as easily as the smaller business owner.
Some reasons involve the economy, credit, and changing industries; but, sometimes there’s another wrinkle: The owner was counting on supporting a pre-retirement lifestyle; and, often, that just isn’t the case.
But, as I indicated, there are other issues. Many businesses that realized huge gains fifteen or twenty years ago may now be looking at flattened growth curves, which means margins have been squeezed as costs have risen. And, regardless of the revenues and margins that may fit neatly into those purchase formulas so many accountants may like to use, the reality is that a company with a 20% growth rate might be worth three times more than a flat company to a financial buyer.
Note: Financial buyers buy for what a company is worth to their bottom line. Strategic buyers buy for what it can mean to their own company, i.e., maybe to remove a competitor or to vertically integrate their manufacturing or distribution chain, etc.
Most owners, of course, have never sold a business before and are emotionally attached to their companies – a situation that virtually always results in an inflated idea of what their business is worth. They tend to have this mental picture based on some multiple of revenues or earnings – a formula they read or heard was the ‘norm’ for their industry.
But, valuing a business can involve costs many owners don’t want to pay. But, success planning requires*advance*planning. Unfortunately, sometimes even the owners’ most trusted advisors are jealous of their relationships and can get in the way. I’ll never forget meeting with a owner and his CPA over lunch one day and the CPA said to me, “Tell me about your scheme.” I could tell immediately, the desire to preserve “go-to” status overrode the client’s best interest – and he couldn’t see it.
Finding a successor who can run the company well – who wants to take back a failure if it doesn’t work out? – isn’t easy. Often, the best are home-grown employees or employees brought in for that purpose at a later date.
Investment bankers may not be interested in looking at companies worth below $15 million; and, those that are will likely need to have a full-blown audit, as well as a well-rounded operating management team. An owners key people are just that: Key to the value – and future value – of a company. Too often, owners neglect the “golden handcuffs” that make their company attractive to a future buyer who will want reassurance that top people won’t leave.
The bottom line: If an owner of a successful company wants to attract outside investors, the company should hae the same good governance as a public company – and board should go beyond friends and family.
Jim
—————-
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk "Hidden Risk Report")(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Financial Coversation Checklist")(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights "IFG Insights")to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/ "IFG Website")
Follow Jim on Twitter: @jimlorenzen
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn profile")
IFG on[Facebook](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
———————
***Jim Lorenzen is a[CERTIFIED FINANCIAL PLANNER](https://en.wikipedia.org/wiki/Certified_Financial_Planner "Certified Financial Planner")®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,****a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Common Misconceptions About the Unlimited Marital Deduction](https://indfin.com/common-misconceptions-about-the-unlimited-marital-deduction/)
**Published:** February 11, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73d6e4d94970d-320wi.jpg)Did you know thatproperty transferred in excess of the unified credit equivalent will ultimately be subject to estate tax in the estate of the surviving spouse, meaning **that use of the unlimited marital deduction will NOT eliminate estate settlement costs?**
**The marital deduction eliminates both the federal estate and gift tax on transfers of property between spouses**, in effect treating them as one economic unit.
**The amount of propertransferredbetween them is unlimited**, meaning that a spouse can transfer all of his or her property to the other spouse, during lifetime or at death, and completely escape any federal estate or gift tax on this first transfer.**ty that can be Consider the following:**
- **At best**, the unlimited marital deduction will **POSTPONE** payment of the federal estate tax, **not ELIMINATE** it. If the estate of the surviving spouse exceeds the unified credit equivalent\*, federal estate tax will be payable at the second death. In fact, postponing payment of the tax may even result in a higher federal estate tax, if estate assets continue to grow.
- The unlimited marital deduction does not eliminate the need for estate liquidity to pay administrative costs, such as funeral expenses, probate costs, legal fees and final expenses.
The unlimited marital deduction is **NOT** available to:
- Surviving spouses;
- Single or divorced people or
- A married person who wants/needs to leave property to someone other than the spouse.
\**The 2010 Tax Relief Act provided for **“portability”** of the maximum estate tax unified credit between spouses if death occurred in 2011 or 2012. The American Taxpayer Relief Act of 2012 subsequently made the portability provision permanent. This means that a surviving spouse can elect to take advantage of any unused portion of the estate tax unified credit of a deceased spouse ($5 million as adjusted for inflation; $5,340,000 in 2014). As a result, with this election and careful estate planning, married couples can effectively shield up to at least $10 million (as adjusted for inflation) from the federal estate and gift tax without use of marital deduction planning techniques.*
**With proper advance planning, it may be possible to take full advantage of the marital deduction at both spouses’ deaths, reducing estate tax liability and increasing the size of the estate ultimately left to surviving family members.**
**Advance Directives**
Advance Directives are a way to “have your say” about the type of care you receive (or don’t receive) in the event you suffer a catastrophic medical event, such as a stroke or an accident, that leaves you unable to communicate your wishes. Every adult should plan ahead by completing an Advance Directive that specifies his or her personal preferences in regard to acceptable and unacceptable medical treatments. There are two types of Advance Directives:
**Living Will**
A Living Will states your preferences regarding the type of medical care you want to receive (or don’t want to receive) if you are incapacitated and cannot communicate. You specify the treatment you want to receive or not receive in different scenarios.
**Medical Power of Attorney**
Also known as a durable power of attorney for health care or a health care proxy, a Medical Power of Attorney names another person, such as your spouse, daughter or son, to make medical decisions for you if you are no longer able to make medical decisions for yourself, or you are unable to communicate your preferences.
Note that a Medical Power of Attorney is not the same as a Power of Attorney, which gives another person the authority to act on your behalf on matters you specify, such as handling your financial affairs.
**Important Points to Remember**
- Each state regulates Advance Directives differently. As a result, you may wish to involve an attorney in the preparation of your Advance Directive
- You can modify, update or cancel an Advance Directive at any time, in accordance with state law.
- If you spend a good deal of time in several states, you may want to have an Advance Directive for each state.
- Make sure that the person you name to act for you – your health care proxy – has current copies of your Advance Directive.
- Give a copy of your Advance Directive to your physician and, if appropriate, your long-term care facility.
You might want to consult with your tax professional.
Jim
—-
**RESOURCES:**
IFG Report: [The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk) (registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist) (does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights) to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on [Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
The [Joint Committee on Taxation](https://www.jct.gov/resources.html)
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,** a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [College Aid Fake "Advisors" Abound](https://indfin.com/college-aid-fake-advisors-abound/)
**Published:** June 20, 2013
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73d6e4d94970d-320wi.jpg)Last weekend I was going through my email in-box and found a company offering to supply me with a proven system for attracting new clients by selling an IMMEDIATE NEED, rather than a future one.
The immediate need target market is supposedly parents of high-school (college bound) kids who are seeking college aid!
It looked enticing. Every advisor would like to have new clients, particularly those who have a problem that a qualified advisor might be able to solve! Maybe I’ll look into this.
I went downstairs to turn-on the ball game and began flipping through the pages of one of the industry trade publications. There, in the back with all the other vendor display ads, was an ad from the same company, touting how much money the founder had made selling college aid solutions to a hungry market!
I’ve been in this business over 22 years; and there are two things I’ve learned:
1. The amount of hype attached to a financial solution is virtually always inversely proportional to its value.
2. It’s no coincidence that the higher the commission, the more likely it is the product should be avoided. Indeed, those high commissions, it seems, are a necessary incentive to for less educated salespeople to sell something that couldn’t be sold otherwise, which is why the hype (see #1) is necessary. Those reps and agents often possess impressive-sounding credentials that are recognized by no industry authority and usually even unregistered.
If you’re considering financial aid, you may want to visit – and read in its entirety –[this piece](https://money.cnn.com/2013/01/01/pf/college/college-aid.moneymag/index.html?iid=EL "College Aid - Don't Take the Bait!")from CNN Money.
Note: I’ve had some problems with this link; you may want totry pastingthis in your browser and try it there:
It could save you a lot of grief.
Jim
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk)(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist)(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights)to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,****a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Changing Jobs? You May Have an Important Decision to Make!](https://indfin.com/changing-jobs/)
**Published:** September 29, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi.jpg)Jim Lorenzen CFP®What to do with your money in an employer-sponsored retirement plan, such as a 401(k) plan?
Since these funds were originally intended to help provide financial security during retirement, you need to carefully evaluate which of the following options will best ensure that these assets remain available to contribute to a financially-secure retirement.
**Take the Funds:**You can withdraw the funds in a lump sum and do what you please with them. This is, however, rarely a good idea unless you need the funds for an emergency. Consider:
- A mandatory 20% federal income tax withholding will be subtracted from the lump sum you receive.
- You may have to pay additional federal (and possibly state) income tax on the lump sum distribution, depending on your tax bracket (and the distribution may put you in a higher bracket).
- Unless one of the exceptions is met, you may also have to pay a 10% premature distribution tax in addition to regular income tax.
- The funds will no longer benefit from the tax-deferred growth of a qualified retirement plan.
**Leave the Funds:**You can leave the funds in your previous employer’s retirement plan, where they will continue to grow on a tax-deferred basis. If you’re satisfied with the investment performance/options available, this may be a good alternative. Leaving the funds temporarily while you explore the various options open to you may also be a good alternative. (Note: If your vested balance in the retirement plan is $5,000 or less, you may be required to take a lump-sum distribution.)
**Roll the Funds Over:**You can take the funds from the plan and roll them over, either to your new employer’s retirement plan (assuming the plan accepts rollovers) or to a traditional IRA, where you have more control over investment decisions. This approach offers the advantages of preserving the funds for use in retirement, while enabling them to continue to grow on a tax-deferred basis.
**Why Taking a Lump-Sum Distribution May Be a Bad Idea:**
While a lump-sum distribution can be tempting, it can also cost you thousands of dollars in taxes, penalties and lost growth opportunities…money that will not be available for future use in retirement.
Let’s say that you have $100,000 in a retirement plan with a former employer, you’re under age 59-1/2 and you’re in the 28% federal income tax bracket.
**Taxes and penalties if you…****Roll the $100,000 into an IRA****Take a lump-sum distribution**20% mandatory withholding at the time of distribution$0$20,0008% additional income tax due at filing$0$8,00010% premature distribution penalty tax$0$10,000**Ending Balance:****$100,000****$62,000****Cost to Take the Funds Today:** **$38,000****Value of $38,000 in …****5 Years****10 Years****15 Years****20 Years**5% Return$48,499$61,898$78,999$100,8258% Return$55,834$82,039$120,542$177,11610% Return$61,199$98,562$158,735$255,645Before making any decisions, it’s best to get your ducks lined-up. You can begin by using our Retirement Planning Priority Review, which you can get here.
Enjoy!
Jim
###### NOTE:The above is a hypothetical example for illustration purposes only and assumes that one of the exceptions to the premature distribution penalty tax is not available. In addition to the federal taxes illustrated above, state tax may also be payable. This example is not indicative of any particular investment or performance and does not reflect the fees and expenses associated with any particular investment, which would reduce the performance shown above if they were included.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
---
### [Can You Pass The College Savings Test?](https://indfin.com/can-you-pass-the-college-savings-test/)
**Published:** April 3, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5118d6207970c-320wi3.jpg)
**Mantaining a sound investment strategy can help put your children on the road to a valuable four-year college degree.**
Did you know that on average, a college graduate earns over 80% more than someone with just a high-school diploma?1 That advantage, however, comes with a price tag. Currently, the annual cost of a four-year private college can top $30,000 for tuition, fees, and room and board, according to a 2013 report by the College Board. That’s a significant amount of money, but don’t despair. A sound investment strategy can help put your children on the road to a valuable four-year college degree.
When investing for any large financial objective, it’s best to start early and invest often. First, set your goal: Estimate how much you will need to accumulate for each child based on his or her age. Then, develop a plan and stick with it. Consider discussing the following guidelines with your financial advisor.
**Use an Age-Based Approach**
If you have time on your side (12 to 18 years), consider investing the majority of your college assets in stocks and equity mutual funds, as these investments have historically provided the greatest long-term growth potential (of course, past performance can’t guarantee future results). Make sure to consider the volatility involved with equity investing and your ability to ride out potential fluctuations.
As your time horizon nears, you’ll probably want to add or increase a fixed-income element to help balance risk. Also, consider teaching the college-bound student about investing — by encouraging that a portion of the money earned through part-time jobs be contributed to the college savings plan.
**Investigate Tools for Saving**
When investing for college, consider investing in a 529 college savings plan. These state-sponsored plans allow individuals to invest in predetermined, professionally managed investment pools. All earnings and distributions are tax free if used for qualified higher education expenses2 and residents of the sponsoring state may be eligible for a state tax deduction on contributions to the state’s 529 plan.
Lifetime contribution limits to 529 plans often exceed $200,000. In addition, you can contribute up to $14,000 annually or make a lump-sum contribution of $70,000 every five years — up to the plan’s lifetime contribution limit — without triggering gift taxes. Another plus: there are no income restrictions on contributors to a 529 plan.
Work with your financial advisor to devise a strategy and choose from among different investments to pursue a long-term financial goal, such as a child’s or grandchild’s college education.
1Source: U.S. Census Bureau, 2011. Based on lifetime earning figures.
2Nonqualified withdrawals are subject to a 10% federal penalty tax.
*Because of the possibility of human or mechanical error by Wealth Management Systems Inc. or its sources, neither Wealth Management Systems Inc. nor its sources guarantees the accuracy, adequacy, completeness or availability of any information and is not responsible for any errors or omissions or for the results obtained from the use of such information. In no event shall Wealth Management Systems Inc. be liable for any indirect, special or consequential damages in connection with subscriber’s or others’ use of the content. © 2014 Wealth Management Systems Inc. All rights reserved.*
If your child is now in his or her junior year in high school, it’s time to begin taking serious action. Remember, it’s never too soon! Here are a few resources I’ve put together you might find useful:
- Find out how much scholarship money your student qualifies for
- See a short video, “*A Lesson in Paying For College*“
- Download a free report: “*Insider Strategies and Secrets to Reducing Your College Costs*“
- A College Cost Calculator: Projected four-year costs for the specific college you want (go to the Introduction tab)
There’s also a College Planning Primer (Primer 101 and Financial Aid 101) and even a way for IFG to provide you with a diagnosis of your current situation!
Oh, yes, you can even subscribe to College Ed Xpress, our e-letter that will keep you informed about important college planning, funding, and admissions information.
It’s all on our new College Planning site! Enjoy!
Jim
—
***ADDITIONAL RESOURCES:***
**Arrange a brief15-minute introductiory phone call with Jim Lorenzen, CFP®, AIF®** [**here**](https://tinyurl.com/IFGIntroCall)**.**
**Social Security** – The wrong claiming strategy could conceivably cost hundreds of thousands of dollars! Knowledge is more than power; it’s real money. You can learn how to [get to the right strategy](https://tinyurl.com/SocialSecurityStrategies) with the right planning.
**College Planning and Funding Strategies** – Just like with the airlines, there are often two prices people pay for the same education: The price paid by the informed and the price paid by the uninformed. What are the projected four-year costs for the college your student desires? How much scholarship money will your student qualify for? You can see a short video, *“A Lesson in Paying for College”,* and download a free report, “*Insider Strategies and Secrets to Reducing your College Costs.”* You can learn more on the [IFG College Funding site](https://www.ifgcollegefunding.com/).
**Financial Planning and Investing:**
IFG Report: Understanding Mutual Funds
IFG Report: The Hidden Risk No One Talks About (Registration required)
Begin the discussion with your spouse with this [Financial Converstion Checklist](https://indfin.com/financial-conversation-checklist). (No registration required)
Facing financial decisions but feel you need to do some homework first? You might benefit from looking through our free [Life Guides](https://tinyurl.com/IFGLifeGuides) and using some [financial worksheets](https://tinyurl.com/IFGWorksheets)!
Visit the[IFG Website](https://indfin.com/)!
Follow Jim on Twitter: [@jimlorenzen](https://twitter.com/JimLorenzen) and also on [Jim’s MoneyBlog](https://www.jimsmoneyblog.com/)
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp)
IFG on [Facebook](https://www.facebook.com/IFGAdvisory)
Become an IFG client! [Schedule your 15-minute introductory phone call here](https://www.timetrade.com/book/F7ZPS)!
———————
Jim Lorenzen is a[ *CERTIFIED FINANCIAL PLANNER®*](https://en.wikipedia.org/wiki/Certified_Financial_Planner) professional and An Accredited Investment Fiduciary® in his 21st year of private practice.
The Independent Financial Group is a fee-only registered investment advisor with clients located across the U.S. He is also licensed for insurance as an independent agent under California license 0C00742.Jim can be reached at 805.265.5416 or (from outside California) at 800.257.6659.
**Interested in becoming an IFG client?** Why play phone-tag? You can easily [schedule your 15-minute introductoryphone call!](https://www.timetrade.com/book/F7ZPS)
The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Buying An Annuity? Keep it Simple!](https://indfin.com/buying-an-annuity-keep-it-simple/)
**Published:** August 17, 2016
**Author:** Jim Lorenzen
**Content:**
Jim Lorenzen, CFP®, AIF®
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b0192ac05f306970d-320wi.jpg)It isn’t uncommon for people to buy things they don’t need; and when it comes to annuities, it’s often no different, and it doesn’t help when (sometimes) an agent adds bells and whistles, in the form of elaborate policy riders, that the client will never use!
Today, because many baby-boomers are concerned about a lifetime income they can’t outlive, annuity recommendations often include a guaranteed minimum withdrawal benefit (GMWB) rider. The problem is that often it isn’t needed. Worse, the cost of the rider reduces the earnings potential for wealth accumulation by eating away at the interest clients would otherwise earn.
Rich Lane and Jeff Affronti, in the October 2015 issue of*National* *Underwriter,*cited an example of a buyer who purchased an annuity with $1 million in premium who paid more than $160,000 for this type of rider – and it ended-up being a benefit the client wasn’t even going to use! They pointed out that the example may be extreme; but, the point is no less valid: It’s a waste of money if it isn’t used.
In today’s low interest rates, it may not be the best choice to add an income rider over selecting the appropriate rate of return. The GMWB rider may sound great, but during the accumulation stage the focus should be on accumulation.
If income is needed down the road, a deferred annuity will allow the client to turn-on (annuitize) the income stream. If they need income now, simply purchase a single premium immediate annuity (SPIA) that allows instant access to funds that can be used to supplement Social Security. For a guaranteed income, it’s probably the highest payout for the money available today.
Deferred annuities have an income stream ‘built-in’ to the product – they all have a basic fundamental feature that allows the owner to elect an income stream on or before the maturity date – and it doesn’t cost a thing.
Something to bear in mind. You might find our *Income Annuity Primer* helpful.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement
**Tags:** Guaranteed Income, Retirement Annuities, Retirement Income
---
### [Business Valuation Matters](https://indfin.com/businessvaluationmatters/)
**Published:** November 13, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2017/09/meetingtable.jpg)Jim Lorenzen, CFP®, AIF®**
Business valuation matters! And, not just when you plan to sell. Few business owners realize that valuation ‘what-if’s’ can help determine the advisability of major purchases and investments, not to mention the implementation of pre-funded buy-sell arrangements. Yet, of the more than 200 million businesses in operation globally, fewer than 2 percent value themselves annually. Over the next 10 years, approximately 10 million businesses will change ownership, according to BizEquity, but 75 percent of small business owners don’t know what their business is worth.
Business owners often hold mistaken assumptions about their business’s value, he says; technology companies often overvalue themselves while retailers, manufacturers and professional firms don’t value themselves highly enough.
The lack of knowledge puts small and midsize business owners at particular riskbecause they are unaware of how to create the right capital structure for their business, what amount of insurance to buy or how to plan for a business transition into retirement. According to BizEquity, 50 percent of small businesses are uninsured andmore than three-quarters of business owners plan to fund 100 percent of their retirement through the sale of their business.
How do you establish business value? You might find our report helpful. You can learn more here.
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Business Owners, Planning, Retirement
**Tags:** business owners, business owners retirement, selling closely-held business, Selling your business
---
### [Business Valuation Methods - Which One is Right for You?](https://indfin.com/business-valuation-methods-which-one-is-right-for-you/)
**Published:** January 10, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2016/11/Fotolia_1594119-ReadyToShip.jpg)Jim Lorenzen, CFP®, AIF®**
Business valuation is something that most business owners don’t think about until they decide it’s time to sell.
Big mistake.
Business valuation can be a powerful planning tool!
- How willl this capital expenditure impact the value of my business?
- If my partner(s) pass away, how can I buy-out the partner(s) spouse(s) interest – they may know little about the business!
- If I want to leave the business to one of my children, how will I value that child’s inheritance to be fair to other children who may not want the business – and how will everything get funded?
You get the idea. Your imagination can come up with a lot of reasons for knowing how much a business is worth and how future decisions/events may impact it’s value.
Here’s another one: You’re key employee dies, or just leaves the business. When key employees are no longer on the scene, it’s an event that can impact supplier relationships (and terms), as well as banking relationships (and terms), not to mentions client or customer relationships.
But, valuations are expensive.
Are they? Formal appraisals for sales or mergers and acquisitions can seem expensive; but, informal valuations for planning purposes can be valuable, widely accepted, and far less expensive.
A blog post can’t cover all they types of business valuations; but, it can help in determining which of the move most-accepted methods may be right for you!
Maybe this little chart will help:
[](https://indfin.com/wp-content/uploads/2016/11/i601b_Businss-Valuation-Methods_slide.png)
If you’d like to see a **sample** business valuation report, just click on the button below:
[Click Here to get your Sample Business Valuation Report](https://indfin.leadpages.co/leadbox/1464bce73f72a2%3A12a1899aa346dc/5714142736416768/)
For more on business valuations, see our Business Valuation Report.
Hope this helps!
Jim
———–
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an Accredited Investment Fiduciary® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of **The Independent Financial Group**, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. He is also licensed for insurance as an independent agent under California license 0C00742. Jim’s background includes founding, building, and selling five successful businesses and international consulting. He has been the headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications, as well as scores of state, regional, and national conventions. Jim has also been heard on American Airlines’ Sky Radio on more than 19,000 flights and has been published in the Journal of Compensation and Benefits.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriately licensed professional. All images used in this communication are in public domain unless otherwise noted.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Business Owners, Planning, Retirement
**Tags:** business decisions, business owners, business value
---
### [Business Owners: Have you done tax bracket planning?](https://indfin.com/business-owners-have-you-done-tax-bracket-planning/)
**Published:** February 4, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a51162e90a970c-320wi.jpg)**Tax brackets have an impact on your choice of funding insurance solutions to meet the needs of closely-held corporations and their shareholders!**
**For example**, a corporation in the 15% tax bracket gets to keep 85 cents of every taxable dollar it makes, while an individual in the 35% tax bracket gets to keep only 65 cents of every taxable dollar he or she makes. Since**life insurance purchased to fund a buy-sell plan**must be paid for with after-tax dollars, it may make more sense to pay the premiums with 85 cent dollars as compared to 65 cent dollars.
**Impact of Tax Brackets on Buy-Sell Planning**- ***Lower bracket corporation***— If the corporation is in a lower tax bracket than the shareholders, a stock redemption buy-sell plan can be funded with enhanced dollars, since premiums are paid by the corporation.
- ***Higher bracket corporation***— If the corporation is in a higher tax bracket than the shareholders, a cross purchase buy-sell plan may be more cost effective since premiums are paid with enhanced dollars by each shareholder.
Conversely, the marginal tax brackets of the corporation and shareholder-employees can have an impact on the **total cost of a selective benefit plan.** Benefits provided to corporate employees on a selective basis generally are either tax-deductible by the corporation or are not currently taxable to the employee, but not both. **As a result, the relative impact of tax brackets should be considered in selecting a selective executive benefit plan that produces the most advantageous overall tax results.**
**Impact of Tax Brackets on Executive Benefit Planning**- ***Lower bracket corporation***— When the corporation is in a lower tax bracket, selective benefits that are non-deductible by the corporation and non-taxable to the shareholder-employee generally produce the better overall tax results.
- ***Higher bracket corporation***— When the corporation is in a higher tax bracket, selective benefits that involve tax-deductible corporate payments are generally more advantageous, even if taxable to shareholder-employees.
Jim
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk)(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist)(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights)to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
The[Joint Committee on Taxation](https://www.jct.gov/resources.html)
**Become an IFG client!**Don’t play phone-tag; schedule your 15-minute introductory phone call using[this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,**a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Three Tips for Building Family Wealth](https://indfin.com/buildingwealth/)
**Published:** July 6, 2020
**Author:** Jim Lorenzen
**Excerpt:** Most people work long hours for 30+ years trying to build wealth for themselves and their families. These three tips can make it a little easier.
**Content:**
#### There is more you can do, of course; but, these will get you on your way:
[](https://indfin.com/wp-content/uploads/2017/10/Older-man-with-cash_gettyimages.jpg)*Getty Images***Jim Lorenzen, CFP®, AIF®**
Most people work long hours for 30+ years trying to build wealth for themselves and their families – okay, it’s really for the vacation home and a nicer car, but the first part sounds better.
The truth is building family – inter-generational wealth – really isn’t that hard to do. If you REALLY want to do that, these simple steps will get you started.
1. **Choose your beneficiaries wisely when allocating inheritance money.** Leave tax-deferred accounts (IRAs and non-qualified annuities, for example) to younger family members. They’re likely in a lower tax bracket and have longer life expectancies for taking the required minimum distributions, which means the distributions will be smaller, as well. Highly appreciated assets are best left to beneficiaries in higher tax brackets as long as the cost-basis can be stepped up to the current price levels. This means wealthier recipients can sell the asset with little or no tax consequences. The high-income beneficiaries would most benefit from the tax-free benefits from life insurance policies. Life insurance is the most overlooked, yet one of the most valuable tools in the toolbox. Where else could you create an estate with the stroke of a pen?
2. **Don’t be too eager to drop older life insurance policies.** Some may wonder why keep the policy if they no longer need it. Those older policies may be paying an attractive interest rate, which is accumulating tax-deferred. Secondly, those small premiums may well be worth the much larger tax-free payoff down the road. How to tell? Start by dividing the premium into the death benefit. Got the answer? If you think you’ll pass away before that number (in years), you probably should keep paying. Remember, death benefits generally pass tax-free!
3. **Convert Grandpa’s IRA to a Roth IRA**. When grandpa passes away, his IRA assets will likely be passed down to children and grandchildren, which means they’ll have to begin taking taxable required minimum distributions (RMDs) – which means they’ll probably be taxed at a higher rate than grandpa would have paid on his own withdrawals (when grandpa passes away, the grandkids are probably in their peak earning years, paying higher taxes anyway. Why force them into a higher bracket still?). If grandpa converted some or all of his traditional IRAs to Roth IRAs while alive, this problem wouldn’t happen. Smart kids might want to encourage this and *even offer to pay the tax bill* on the conversion now!
Review your financial plan with your advisor? Don’t have an advisor or a plan? Hmmmm. See below.
Jim
————————————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Annuities, IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, investment planning, Investment Strategy, Retirement tax strategies, Tax reduction
---
### [Does "Bucket Investing" Achieve Goals or Destroy Wealth?](https://indfin.com/bucketinvesting/)
**Published:** September 28, 2020
**Author:** Jim Lorenzen
**Excerpt:** Does the ‘bucket’ approach to allocating assets to life goals make sense—or does it actually destroy wealth? Mentally, bucket investing is simply assigning money to ‘buckets’, i.e. goals
**Content:**
#### Many investors, and advisors, like it; but there are some experts who apparently aren’t too sure.
[](https://indfin.com/wp-content/uploads/2016/01/Female_Mgr_Responsible_Concern.jpg)*iStock Images***Jim Lorenzen, CFP®, AIF®**
Does the ‘bucket’ approach to allocating assets to life goals make sense–or does it actually destroy wealth? Mentally, bucket investing is simply assigning money to ‘buckets’, i.e. goals. Advisors utilizing this approach use a variety of buckets. Even some celebrated elite advisors have used this method. One uses a two bucket approach: Bucket #1 contains a five-year cash reserve and bucket #2 is then free to invest in longer-term investments, typically stocks, stock funds or exchange-traded funds (ETFs).
Many people find the approach appealing for several reasons:
- No need to wrestle with sequence-of-returns risk
- No need to worry about liquidating assets during a down market
- Comfort: It comports comfortably with the well-know behavioral bias of mental accounting. It’s easy to understand having a withdrawal account and a long-term investment account.
Javier Estrada, a professor of financial management at the IESE Business School in Barcelona, Spain conducted a research study, some time back, on the merits of the ‘bucket approach’ to investing for achieving long-term financial goals. His study included highly-detailed back-testing of both Monte Carlo and bucket strategies, back-tested over a variety of time periods and methodologies. His study uses\\d a risk-adjusted success (RAS) measurement–it’s defined as the ratio between the mean-expected value of outcomes and the standard deviation of outcomes
Are you asleep, yet?
Basically, he’s measuring downside risk-adjusted success–measuring only downside volatility–the dispersion of only failed outcomes as opposed to simply looking at the disparity of upside to downside outcomes.
Okay, enough of the weeds. His extensive research shows that while the bucket approach may have psychological benefits, it doesn’t perform so well when tested for the highest likelihood of success. It failed in all performance tests to provide enough money to cover the needed withdrawals. Estrada found that as he extended the number of years for withdrawals to occur, the worse the strategy became.
Reasons for the failure? Estrada explained: “Most implementations of the bucket approach… distribute funds from more aggressive buckets into more conservative buckets, but not the other way around. Put differently, although bucket strategies avoid selling low by withdrawing from bucket #1 after stocks performed badly, they do not take advantage of also buying low as static strategies do with rebalancing.”
The bucket approach is popular due chiefly to a lack of knowledge. Surrendering to the mental accounting bias allows investors to conveniently stop worrying. While increasing the amount of money allocated to bucket #1 might allow them to sleep better, it also increases the odds of running out of money.
Oops. Not good.
Jim
————————————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Annuities, Investing, Planning, Retirement
**Tags:** Financial planning, Investment mistakes, investment planning, investment returns
---
### [Best Paying Jobs and Best College Majors](https://indfin.com/best-paying-jobs-and-best-college-majors/)
**Published:** September 10, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01b8d06393d2970c-320wi.jpg)Most six figure jobs require an advanced degree, according to CareerCast, which created a report with data from the [Bureau of Labor Statistics](https://www.dol.gov/bls "Bureau of Labor Statistics").
I first learned of this in a piece by Michael Fischer, writing for ThinkAdvisor, an industry trade publication. I noticed `financial advisor’ didn’t appear on the list – someone must have seen the cars we drive.
The Top Ten are:
1. Surgeon
2. Physician
3. Psychiatrist
4. Orthodontist
5. Dentist
6. Petroleum Engineer
7. Air Traffic Controller
8. Pharmacist
9. Podiatrist
10. Attorney
But, what if you don’t want to get an advanced degree? In a piece by Dan Berman, which appeared last May in ThinkAdvisor, it became clear that the best undergraduate majors seem to be in engineering and science. He also noted that Child and Family Studies came in dead last. Based on a study of data collected from 1,000 universities, including graduates with bachelor’s degrees only (88% of schools had enrollment of more than 5,000), these are the top 30. Here’s Dan Berman’s list:
30 Best Paying College Majors (2014)
- Petroleum Engineer
- Chemical Engineer
- [Nuclear Engineer](https://en.wikipedia.org/wiki/Nuclear_engineering "Nuclear engineering")
- Computer Engineer
- [Electrical Engineer](https://en.wikipedia.org/wiki/Electrical_engineering "Electrical engineering")
- [Aerospace Engineer](https://en.wikipedia.org/wiki/Aerospace_engineering "Aerospace engineering")
- Materials Science & Engineering
- [Industrial Engineer](https://en.wikipedia.org/wiki/Industrial_engineering "Industrial engineering")
- [Mechanical Engineer](https://en.wikipedia.org/wiki/Mechanical_engineering "Mechanical engineering")
- Software Engineer
- Computer Science
- [Biomedical Engineer](https://en.wikipedia.org/wiki/Biomedical_engineering "Biomedical engineering")
- Actuarial Mathematics
- [Electrical Engineering Technology](https://en.wikipedia.org/wiki/Electrical_engineering_technology "Electrical engineering technology")
- Nursing
- Civil Engineering
- Mechanical Engineering Techonolgy
- Management Information Systems
- Physics
- (tie) [Supply Chain Management](https://en.wikipedia.org/wiki/Supply_chain_management "Supply chain management")
- (tie) Applied Mathematics
- Statistics
- Information Systems
- Construction Management
- (tie) Industrial Technology
- (tie) Computer Information Systems
- Occupational Health & Safety
- Economics
- Information Technology
- Mathematics
What were the worst majors, according to ThinkAdvisor? According to an article published in June, 2014, they were, beginning with the worst:
1. Child & Family Studies
2. Elementary Education
3. Exercise Science
4. Broadcast Journalism
5. Social Work
6. Animal Science
7. Special Education\\
8. Theology
9. (tie) Culinary Arts
10. (tie) Athletic Training
11. Religious Studies
12. Physical Education
13. (tie) Paralegal Studies
14. (tie) Recreational & Leisure Studies
15. Horticulture
16. Criminal Justice
17. Biblical Studies
18. (tie) Kinesiology
19. (tie) Drama
20. (tie) Hospitality & Tourism
21. (tie) Music
22. (tie) Public Health
23. (tie) Human Development
24. Interior Design
25. Art
26. (tie) Anthropology
27. (tie) Theatre
28. (tie) Photography
29. Psychology
30. Liberal Arts
Want your kids to do well financially? With the cost of college as high as it is these days, they might want to reevaluate majoring in Peruvian Art.
Jim
————
**RESOURCES:**
**Visit** [**Jim’s Social Security Learning Center**](https://www.jlorenzen.sswise.com/ "Social Security Learning Center")
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Conversation Checklist") (does not require registration)
[Subscribe to IFG Insights ](https://tinyurl.com/IFGInsights "Subscribe to IFG Insights")
[The IFG Website](https://indfin.com/ "IFG Website")
IFG’s [Financial Resources website](https://finsecurity.com/Lorenzen "IFG Financial Resources Website").
Follow Jim on Twitter: @JimLorenzen
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [BAD ADVICE REPEATED BECOMES ACCEPTED KNOWLEDGE](https://indfin.com/bad-advice-repeated-becomes-accepted-knowledge/)
**Published:** March 9, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01b8d06b519e970c-320wi1.jpg)We’ve seen it all our lives; and the older one gets, the more transparent it becomes. Some people simply don’t know what they’re talking about. Here are a few examples:
- **“Pay cash and you avoid paying interest.”** You’ve heard that one. Whether good or bad, it sounds simple enough. It’s apparent plausibility even leads us to believe it without even bothering to examine it, let alone test it.
**The truth: Everyone pays interest, including those who pay cash.** How?
The money you use to pay cash is unavailable to lend to others which would allow you to*earn*interest. $40,000 cash paid for a car is $1,200 every year in lost interest (hypothetical 3% rate) that money could have earned. That’s $6,000 over five years. True cost of the car: $46,000.
Some people may not think “opportunity cost” is worth worrying about; but, I doubt they’re among the wealthy. Warren Buffet may disagree with them.
Whether it would have earned more than it would have saved on the car purchase is another discussion, of course; but, the blind statement that it’s always better to pay cash is an example of financial pornography. It sounds good, so it must be true in all cases when, in fact, it may or may not be true in any given case.
- **“Investments should be compared on the basis of their average annual return.”**Really?
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017c384ba1fa970b-320wi.jpg)Average annual (arithmetic) return is different from average annual compounded (geometric) returns. Geometric returns measure how well an investor would have done. You might find [Understanding Investment Returns](https://indfin.com/wp-content/uploads/2015/03/IFGi_RPT-Understanding-Investment-Returns1.pdf)helpful.
- **“Buy term insurance and invest the difference.”**Really?
It sounds true because we want it to be true. The tv gurus tell us it’s cheaper. This one is usually advanced by some financial types who are usually selling something else: Other financial products – or gurus\[2\]selling CDs, DVDs, workbooks, seminars, etc.
> *Professional speakers know this basic axiom: If you tell people something they think they already know and perceive to be true, they will think you’re smart and follow your advice. Tell them something that flies in the face of their belief system, and it’s like getting someone to change religions. People tend to favor the advice that’s consistent with what they’ve always believed.*
>
> *– Anonymous*
**Ask yourself: Why is term insurance so cheap?**
First of all, you’re paying for “pure” protection; but, as you’ll see, the cost for pure protection is the same in a wide variety of policies. More significant, I think, are thestatistics from a study conducted by LIMRA\[3\]indicates that death benefits are paid out for only 1% of retail term insurance policies. The other 99% are dropped without value.
There’s very little risk in a 3-year term if your life expectancy is higher. And, when you renew, the rates will be higher, too. It’s like an apartment lease.\[4\] When the lease is up you renew at higher rates – but most of us like owning our houses. We like the predictability of no increases and we know it can be paid off by us or a buyer.
This is a no-brainer for the insurance companies; and, unfortunately, too many who find chase “shiny things” – things that sound cheap and therefore good.
The ‘term is cheaper’ argument has been disproven in numerous analytical models, but ignored by mostly tv gurus trying to sell their CDs and DVDs. The reason is simple: Their argument generally ignores cash-value buildup which can be accessed tax-free and usually based on policy designs created decades ago.
Many will argue that if you invest the difference, you won’t need the insurance later and won’t have to renew. How many people actually did this – or do? And, what happened to those who bought that idea in 1988 only to see their retirement accounts blow-up the day they retired in 2009?
Ask 10 35-year olds who believe the ‘buy-term-invest-the-difference argument if they’re doing it; then ask ten 60-year-olds who did it if they’re glad they did. I’ve never met a 70-year-old who wished s/he’d followed that advice – ever. Not one.[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73dd6e411970d-320wi.jpg)
This is a mantra that simply hasn’t worked since they began preaching it in the early 1970s – at least that’s when I first heard it.
**What the schools don’t teach\[5\]and the public doesn’t know: There are only two ways to pay for life insurance:**
- You can purchase off-the-shelf, retail, yearly renewable term life insurance and pay for it with after-tax income – a purchase of pure protection for a limited time; or
- you may rearrange assets to place investment funds with the insurance company, funds in excess of what is required for the yearly renewable term insurance.
So, what happens with the excess money that most people place with the company… money beyond what’s required for pure protection?The insurance company invests those extra funds on your behalf and earns a return that will not be subject to income tax. Sounds a little like a tax-deferred vehicle, doesn’t it?
The insurance company will then use a portion, or all, of this return to pay the annual mortality and expense charges required by your life insurance contract. You can choose to pay for life insurance with the pretax earnings on your investments inside the policy.\[6\] Oops! Now we’re not limited to a specific term. The policy can even become self-supporting!
Under the first method, retail term insurance, you would be paying for these same benefits with dollars that had been subject to taxation. Under the second, the inside buildup of excess dollars, above the cost of pure insurance, can be added-to with pre-tax buildup, grows tax-deferred, and, depending on the design, possibly be accessed later tax-free. Any purpose. No pre-59-1/2 penalties. No credit checks, no loan origination fees, no application process,and on-demand.
**In essence, all insurance is term insurance.** You pay for life insurance each year, whether you make the payment directly or have premium payments taken from earnings in the insurance company’s investment account (which you’re funding over and above the cost of pure insurance).
The question is how excess capital is treated and utilized once the cost of pure protection is covered. The uninitiatedsee it as a cost. Those who know understand it has uses as a financial vehicle for efficiently managing assets in excess of the insurance cost. Excess capital is managed in the insurance company’s general account in conservative investments (usually long-term bonds and mortgages) and the client receives tax-deferred treatment on those cash values.
[](https://indfin.com/wp-content/uploads/2015/03/YoungExecSmilingAtMeeting.jpg)One product, indexed universal life (IUL), in one form, marries the concepts of term insurance with an equity-indexed annuity. This allows the policy owner’s cash value to benefit from upside moves in the market while being protected against loss. How is that possible? The company uses a small portion of their investment account to buy options on an index, which they can exercise to take gains when available. This product is particularly popular with successful business owners.
- Receive market-like returns with no market risk.
- Never take a market loss
- Draw income in retirement tax-free
- Access to money at any age
- Provides a large income-tax-free lump sum payment to your family if you die prematurely
- Protected against judgments and lawsuits (in many states)
- Can give you an option to continue to make your savings contributions if you become disabled
- No 59-1/2 required minimum distributions
- Cost of insurance similar to pure term
Not bad. Your 401(k)s, IRAs nor the investments they hold – stocks, bonds, mutual funds, CDs, etc. – can do all that. If you can find something better, let me know. Many advisors, RIAs included, are now beginning to view IUL policies designed as financial tools not so much as substitutes for stocks in client portfolios, but for placement as part of a portfolios bond allocation. There are a number of reasons for this; but, the primary ones are:
- Safety – insurance company guarantees against loss – bonds won’t do that.
- Bond like returns – Despite the caps and floors, returns can be expected to look more like bond, rather than stock, returns – and likely even a little better – and with better tax treatment than is available even in tax-deferred vehicles.
- Advantages outlined in the previous list, including excess capital accumulation beyond what maturing bonds would likely provide.
- Business owners particularly like the fact that there are no funding limits other than those imposed by the insurance company and that prior year’s under-funding can be carried over, unlike traditional retirement plans.
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017c37fc6922970b-320wi.jpg)Maybe the guru’s don’t get it;but the people in Congress sure do.**
**It’s an issue congress has re-visited on more than one occasion since 1985 with some wanting to tax the inside buildup received by those who hold permanent, participating policies designed as a financial tool rather than pure term protection.**
Their argument is that even if a policy owner did surrender the policy during his or her lifetime and incurred ordinary income tax on the amount received in excess of the investment made, that policy owner has still received still reaped a substantial income tax benefit. This is because the tax basis in the policy includes a portion of the premium that had been used to pay the cost of life insurance for past periods. In other words, the cost of life insurance has become equivalent to a tax-deductible expense in these policies.
They’re arguing that comparable investment products are not tax-free or tax deferred.\[7\] Further, they argue that life insurance is not subject to significant limitations on the timing and amount of contributions (although greater limitations were imposed in 1988 under Modified Endowment rules) and that there are no required minimum distributions.\[8\]
**Interesting; don’t you think? Politicians in Washington, D.C. are able to present the benefits of life insurance so forcefully, whereas the insurance industry itself seems unable to communicate these benefits to the public without confusion, usually coming from self-anointed gurus.**
**Will Congress change the rules?** Probably. But, if history is any guide, people who bought policies with provisions Congress decided to change, required the changes going forward only. Policies already in force have generally been “grandfathered” so those policy owners would not be affected. The reason for this is simple: An insurance policy is a private contract between two parties and the law has been loath to interfere with lawful agreements between private parties. The lesson seems to be if you like it, you’d better do it before the politicians see it as a revenue source.
**Should you start using life insurance as an investment vehicle?** No. Even though advisors, as I stated earlier, are beginning to view some policies as part of an asset allocation, life insurance is still about life insurance – there must be a need for the death benefit – but, it does have some attractive tax and savings components that can help secure your life while you’re still alive, as indicated earlier. **Policy design is something you should discuss with your financial/insurance advisor.**
Unfortunately for the investing public, information isn’t education. And, financial entertainment seldom provides even good information. The investor is left on his own if not seeking qualified help.
Jim
——————
\[1\]Seemy report, [Understanding Investment Returns](https://indfin.com/wp-content/uploads/2015/03/IFGi_RPT-Understanding-Investment-Returns1.pdf)*.*
\[2\]Not all gurus are financial pornographers. A few are actually qualified: They’ve taken the rigorous coursework, passed the exams, have respected credentials, are regulated, practicing professionals. One example is Ed Slott, the IRA guru you often see on public television. A few others I won’t mention, with nationwide radio programs, have never taken any academic courses, achieved any credentials, or worked with a single client. They’re also unregulated. But, they do have free speech.
\[3\]Life Insurance Marketing Research Association
\[4\]Term insurance has it’s uses, particularly for temporary protection needs, i.e., a need that isn’t permanent.
\[5\]If the schools did teach it, it would interesting to see who they’d pick to teach the class and what their qualifications would be.
\[6\]The New Investment Life Insurance Advisor,Ben G. Baldwin, McGraw-Hill, 2002.
\[7\] IRAs, 401(k)s, 403(b)s are account types, not investments. Investments placed in these accounts grow tax-deferred until withdrawn, then taxed at the then-current income tax rates. So, someone in the 28% bracket, for example, can figure that 28% of the account balance really belongs to Uncle Sam. This is not necessarily the case inside a life insurance contract.
\[8\]It’s worth noting that the government is not a party to the contract. The policy is a private contract between the owner and the insurance company, giving the owner greater control.
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional. Images used in this post are public domain stock images and do not represent any IFG affiliate or client.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook
---
### [Are You Ready for Retirement?](https://indfin.com/are-you-ready-for-retirement/)
**Published:** March 6, 2014
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/174-thumb-1.jpg)Ready for Retirement?**
Are you ready for retirement? Here are five words you should consider.
Here’s some food-for-thought from the Financial Planning Association:
**Three Key Retirement Income Considerations**
Average life expectancy has risen steadily in the United States, so retirees and soon-to-be retirees need to ensure that they don’t tap their nest eggs too heavily.
There are two factors that can determine whether you’ll have a comfortable retirement: The amount of money you’ve saved and how quickly you spend that nest egg after you retire. The rate of annual withdrawals from personal savings and investments helps determine how long those assets will last and whether the assets may be able to generate a sustainable stream of income over the course of retirement. A number of factors will influence your choice of annual withdrawal rate. The following are three key considerations.
As you think about what your withdrawal rate should be, begin by considering your age and health. Although you can’t predict for certain how long you will live, you can make an estimate. However, it may not be wise to base your estimate on average life expectancy for your age and sex, particularly if you are healthy. The average life expectancy has risen steadily in the United States, reaching 78.2 years.¹
**Consideration 2: Inflation**
Inflation is the tendency for prices to increase over time. Keep in mind that inflation not only raises the future cost of goods and services, but also affects the value of assets set aside to meet those costs. To account for the impact of inflation, include an annual percentage increase in your retirement income plan.
How much inflation should you plan for? Although the rate varies from year to year, U.S. consumer price inflation has averaged under 3% over the past 30 years.2So, for long-term planning purposes, you may want to assume that inflation would average in the range of 3% to 4% a year. If, however, inflation flares up after you have retired, you may need to adjust your withdrawal rate to reflect the impact of higher inflation on both your expenses and investment returns. Also, once you retire you should assess your investment portfolio regularly to ensure that it continues to generate income that will at least keep pace with inflation.
**Consideration 3: Variability of Investment Returns**
When considering how much your investments may earn over the course of your retirement, you might think you could base assumptions on historical stock market averages, as you may have done when projecting how many years you needed to reach your retirement savings goal. But once you start taking income from your portfolio, you no longer have the luxury of time to recover from possible market losses, as retirees and near-retirees during this latest market downturn have experienced firsthand.
For example, if a portfolio worth $250,000 incurred successive annual declines of 12% and 7%, its value would be reduced to $204,600, and it would require a gain of nearly 23% the next year to restore its value to $250,000.3When a retiree’s need for annual withdrawals is added to poor performance, the result can be a much earlier depletion of assets than would have occurred if the portfolio returns had increased steadily. While it’s possible that your portfolio will not experience any losses and will even grow to generate more income than you expected, it’s safer to assume some setbacks will occur.
*Source/Disclaimer:*
*1Source: Center for Disease Control, March 2012 (based on 2009 data, latest available).*
*2Source: Bureau of Labor Statistics, January 2014.*
*3Example is hypothetical and for illustrative purposes only. Your results will vary.*
*Because of the possibility of human or mechanical error by Wealth Management Systems Inc. or its sources, neither Wealth Management Systems Inc. nor its sources guarantees the accuracy, adequacy, completeness or availability of any information and is not responsible for any errors or omissions or for the results obtained from the use of such information. In no event shall Wealth Management Systems Inc. be liable for any indirect, special or consequential damages in connection with subscriber’s or others’ use of the content.*
*© 2014 Wealth Management Systems Inc. All rights reserved.*
**ADDITIONAL RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk)(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist)(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights)to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
[The IFG Managing Life’s Risks Website](https://finsecurity.com/Lorenzen)
Follow Jim on Twitter:
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
The[Joint Committee on Taxation](https://www.jct.gov/resources.html)
**Become an IFG client!**Don’t play phone-tag; schedule your 15-minute introductory phone call using[this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,**a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Are You A Business Owner? Maybe You Should Know About Tax Bracket Planning!](https://indfin.com/are-you-a-business-owner-maybe-you-should-know-about-tax-bracket-planning/)
**Published:** February 13, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73d75677c970d-320wi.jpg)**Owners of closely-held businesses have long understood the value of insurance as a funding tool for executive retention, transition planning, and enhanced retirement benefits; but, tax-brackets can have a significant impact on those solutions!**
**For example**, a corporation in the 15% tax bracket gets to keep 85 cents of every taxable dollar it makes, while an individual in the 35% tax bracket gets to keep only 65 cents of every taxable dollar he or she makes. Since**life insurance purchased to fund a buy-sell plan**must be paid for with after-tax dollars, it may make more sense to pay the premiums with 85 cent dollars as compared to 65 cent dollars.
**Impact of Tax Brackets on Buy-Sell Planning**- ***Lower bracket corporation***— If the corporation is in a lower tax bracket than the shareholders, a stock redemption buy-sell plan can be funded with enhanced dollars, since premiums are paid by the corporation.
- ***Higher bracket corporation***— If the corporation is in a higher tax bracket than the shareholders, a cross purchase buy-sell plan may be more cost effective since premiums are paid with enhanced dollars by each shareholder.
Conversely, the marginal tax brackets of the corporation and shareholder-employees can have an impact on the total cost of a selective benefit plan. Benefits provided to corporate employees on a selective basis generally are either tax-deductible by the corporation or are not currently taxable to the employee, but not both. As a result, the relative impact of tax brackets should be considered in selecting a selective executive benefit plan that produces the most advantageous overall tax results.
**Impact of Tax Brackets on Executive Benefit Planning**- ***Lower bracket corporation***— When the corporation is in a lower tax bracket, selective benefits that are non-deductible by the corporation and non-taxable to the shareholder-employee generally produce the better overall tax results.
- ***Higher bracket corporation***— When the corporation is in a higher tax bracket, selective benefits that involve tax-deductible corporate payments are generally more advantageous, even if taxable to shareholder-employees.
**Misconceptions About the Unlimited Marital Deduction:**
**The marital deduction eliminates both the federal estate and gift tax on transfers of property between spouses**, in effect treating them as one economic unit.
**The amount of property that can be transferred between them is unlimited,** meaning that a spouse can transfer all of his or her property to the other spouse, during lifetime or at death, and completely escape any federal estate or gift tax on this first transfer.
However, property transferred in excess of the unified credit equivalent will ultimately be subject to estate tax in the estate of the surviving spouse, meaning that use of the unlimited marital deduction will **NOT** eliminate estate settlement costs.
**Consider the following:**
- **At best**, the unlimited marital deduction will**POSTPONE**payment of the federal estate tax,**not ELIMINATE**it. If the estate of the surviving spouse exceeds the unified credit equivalent(1), federal estate tax will be payable at the second death. In fact, postponing payment of the tax may even result in a higher federal estate tax, if estate assets continue to grow.
- The unlimited marital deduction does not eliminate the need for estate liquidity to pay administrative costs, such as funeral expenses, probate costs, legal fees and final expenses.
- The unlimited marital deduction is**NOT**available to:
\* Surviving spouses;
\* Single or divorced people; or
\* A married person who wants/needs to leave property to someone other than the spouse.
(1) The 2010 Tax Relief Act provided for**“portability”**of the maximum estate tax unified credit between spouses if death occurred in 2011 or 2012. The American Taxpayer Relief Act of 2012 subsequently made the portability provision permanent. This means that a surviving spouse can elect to take advantage of any unused portion of the estate tax unified credit of a deceased spouse ($5 million as adjusted for inflation; $5,340,000 in 2014). As a result, with this election and careful estate planning, married couples can effectively shield up to at least $10 million (as adjusted for inflation) from the federal estate and gift tax without use of marital deduction planning techniques.
**With proper advance planning, it may be possible to take full advantage of the marital deduction at both spouses’ deaths, reducing estate tax liability and increasing the size of the estate ultimately left to surviving family members.**
**Advance Directives**
Advance Directives are a way to “have your say” about the type of care you receive (or don’t receive) in the event you suffer a catastrophic medical event, such as a stroke or an accident, that leaves you unable to communicate your wishes. Every adult should plan ahead by completing an Advance Directive that specifies his or her personal preferences in regard to acceptable and unacceptable medical treatments. There are two types of Advance Directives:
**Living Will**
A Living Will states your preferences regarding the type of medical care you want to receive (or don’t want to receive) if you are incapacitated and cannot communicate. You specify the treatment you want to receive or not receive in different scenarios.
**Medical Power of Attorney**
Also known as a durable power of attorney for health care or a health care proxy, a Medical Power of Attorney names another person, such as your spouse, daughter or son, to make medical decisions for you if you are no longer able to make medical decisions for yourself, or you are unable to communicate your preferences.
Note that a Medical Power of Attorney is not the same as a Power of Attorney, which gives another person the authority to act on your behalf on matters you specify, such as handling your financial affairs.
**Important Points to Remember**
- Each state regulates Advance Directives differently. As a result, you may wish to involve an attorney in the preparation of your Advance Directive
- You can modify, update or cancel an Advance Directive at any time, in accordance with state law.
- If you spend a good deal of time in several states, you may want to have an Advance Directive for each state.
- Make sure that the person you name to act for you – your health care proxy – has current copies of your Advance Directive.
- Give a copy of your Advance Directive to your physician and, if appropriate, your long-term care facility.
You might find it worthwhile to consult with your tax professional as well as your attorney. And, of course, I’m available to help in any way I can.
Jim
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk)(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist)(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights)to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
The[Joint Committee on Taxation](https://www.jct.gov/resources.html)
**Become an IFG client!**Don’t play phone-tag; schedule your 15-minute introductory phone call using[this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,**a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Thinking of Buying An Annuity? Do Your Homework.](https://indfin.com/annuitychecklist/)
**Published:** January 22, 2018
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2016/11/Piecing-Retirement-Puzzle-Path.png)Jim Lorenzen, CFP®, AIF®**
**If you’re thinking of purchasing an annuity, here’s a report you might find helpful.**
I seldom use annuities for client portfolios; but, that doesn’t mean they’re bad. Any financial instrument will have it’s good and bad points; the question is really whether the instrument in question is appropriate for a particular client, and given that I take fiduciary status for my clients, it MUST be in a client’s best interest.
Television commercials abound – some advisors telling you they have annuity strategies no one else has (uh huh) and others telling you they’d rather die before they’d ever sell one (neglecting to either differentiate what annuities they’re talking about – variable and fixed annuities are two entirely different animals with virtually nothing in common – or to tell the viewer they’re not licensed to sell annuities to begin with). The truth is both types of commercials are misleading and tend to target those who don’t know what questions to ask – convenient.
If you’re considering purchasing an annuity, and I’m not recommending that you should, you might find this report about the things you should consider helpful. You can access it here.
Hope you find this helpful.
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Annuities, Investing, Planning, Retirement
**Tags:** Estate Planning, Financial planning, Reducing Risk
---
### [How Social Security and Pensions Might Impact How You Arrange Your Nest-Egg.](https://indfin.com/allocatingincome/)
**Published:** April 30, 2020
**Author:** Jim Lorenzen
**Excerpt:** If you're receiving Social Security, Pension, or other guaranteed income, you may want to rethink how your nest-egg is arranged for long-term inflation risk.
**Content:**
Few people think about this, but you might want to.
**[](https://indfin.com/wp-content/uploads/2017/05/lighthouse.jpg)Jim Lorenzen, CFP®, AIF®**
Everyone intuitively understands the need to have a balanced approach to meet retirement needs; however, it’s also important to address risk in light of the long term inflation risk.
**Let’s take a hypothetical example** using simple numbers. And, suppose after all the data gathering, goal setting, and risk assessments have been completed in the financial planning process, June and Ward Cleaver (yes, I am that old) have decided they feel comfortable with a portfolio that’s comprised of 60% bonds and cash and 40% in stocks.
June and Ward are retiring today after over thirty years of working and saving–they’ve done a lot of thing right–and have accumulated a nest-egg of $1 million. So, in our simple example, that would indicate their money should be arranged with $600,000 allocated to bonds and cash, and $400,000 to stocks. Simple.
But, suppose the two of them also have Social Security income–maybe even pension income, as well. This additional ongoing cash flow shouldn’t be ignored in constructing their allocation. Again, to keep numbers simple (I’m highly qualified for simple numbers). Let’s say Ward and June have an additional $30,000 in annual ongoing income to augment their savings.
What does that $30,000 annual income represent? How much would someone need to have invested to provide the same income?
Assuming a 4% annual withdrawal rate on assets – we’ll say that fits June and Ward’s situation – that $30,000 represents income on an additional $750,000 in assets… except these assets are illiquid: June and Ward can only take the income, they can’t ‘cash in’ the principal. It is like, in effect, an annuity, something some people use to simply ‘purchase’ a lifetime income. I’m not a big proponent, but they do have their place in some situations–but that’s another story.
Nevertheless, if we consider that $30,000 annual income as actually representing an additional asset, June and Ward really effectively have $1,750,000 in assets, $750,000 of which we’ll consider illiquid and providing an income of $30,000 at 4%, but it never runs out of money. If 60% of their total retirement ‘assets’ is to be allocated to bonds, their bond portfolio might now be $1,050,000 (60% of $1,750,000), $750,000 of which is already allocated and providing $30,000 in income.
That leaves $300,000 ($1,050,000 – $750,000) to be allocated to bonds from their nest-egg. This decreases their nest-egg bond and cash allocation from the original $600,000 to $300,000, and therefore raises their stock allocation from $400,000 to $700,000. If long-term inflation is an issue – and it is – then were June and Ward really risking being under-allocated to stocks?
The ‘guaranteed’ $30,000 cash flow, representing an illiquid asset, provides them with the ability, i.e., gives them the freedom, to still address short-term needs and objectives with $300,000, while allowing more money, $700,000) to address long-term inflation risk.
Historically, stocks have performed, simply because they represent the economic engine of the United States. And, it has never made sense to bet against the U.S.A. Pistons drive the engine and the engine provides forward movement.
Jim
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Annuities, Inflation, Investing, Planning
**Tags:** Financial planning, investment planning, Investment Strategy, managing risk, Reducing Risk, social security
---
### [Do Advisors Really Add Value?](https://indfin.com/advisorvalue/)
**Published:** February 14, 2017
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017c384ba1fa970b-320wi.jpg)
**Jim Lorenzen, CFP®, AIF®**
For years the media and others have debated the ultimate value of an advisor to the individual investor. Some believe they either under or outperform; others believe the value is more about providing a disciplined investment process; and, there are still others who believe the value lies in the planning and tax optimization process.
Vanguard – long a champion of the individual investor and low-cost investing – conducted their own study and actually came up with more than a conclusion; they came up with a number. You may find it interesting.
You can access it here.
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** Retirement Income, secure retirement, Tax-Free Retirement Income, Taxes in retirement
---
### [Adult Children Living at Home? Here are a few tips!](https://indfin.com/adult-children-living-at-home-here-are-a-few-tips/)
**Published:** March 25, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019aff2c523c970c-320wi.jpg)When I grew up – I was an only child – there was my mom, my dad, and me. When I graduated from college, I took my first job in central Illinois over 1,000 miles away from my parent’s home in Virginia.
I wasn’t unique. In those days, no one I knew – or even heard about – remained living at home once schooling was completed. Many even took summer jobs away from home. The world has changed.
According to a study in 2010 by researchers at Columbia University using the U.S. Current Population Survey, 52.8% of 18- to 24-year-olds were living at home, up from 47.3% in 1970. The study also showed that one-in-seven young adults is are entering their 20s with no pathway to financial and economic independence.1
One advantage of being an experienced (read: older) advisor is that, in many cases, I’ve actually lived many of the experiences I write about and help clients plan for: Caring for aging parents with Alzheimer’s (ten years), dealing with wealth transfer issues, and caring for adult children – and their children, too – are all things I can talk about from first-hand experience.
Many of the lessons include the financial impact of doing – or failing to do – the things that did, or could have, made a big difference in everyone’s lives.
For parents with live-in adult children,it can be trying; But, it can also be rewarding. Part of you truly enjoys having a lot of family all together – and grandchildren add a lot of life to a home. The flipside, of course, is that you know they need to learn independence; and, if there’s a free ride, there’s little incentive to leave the nest.
People dealing with special needs children face a myriad of other issues arise: What happens to them financially if something happens to the family’s main provider? Leaving a sizable death benefit may sound like enough; but, what if they can’t manage money? How will they budget, pay bills, or hold a job if they can’t handle basic math?
While we’re lucky – in our family, it’s surprisingly harmonious – there can be friction from time to time in any home, especially when financial issues are involved.
**Getting your financial ducks lined-Up.** Here are a few tips that help get the process moving in the right direction:
- **Track your expenditures**. You need to know where money is going. It’s not that hard, really. If you have even basic bookkeeping software, you can set-up spending categories. Here’s an abbreviated example of what some categories might look like. You’ll get the idea:
- - Home
- Mortgage
- Utilities
- Water
- Electricity
- Trash pickup
- Household
- Food
- Lawncare
- Auto
- Gas
- Ser vice
- Registration
- Repairs
- Insurance
- Recreation
- Dining out
- Special Events
- Vacation
- Day-trips
- Insurance
- Homeowners
- Life
- Health, Disability, Long-term-care
- Adult child’s name – share of out of pocket costs
- Food
- Food – special
- Water
- Electricity
- (add others as they arise)
Begin with a basic category list, then add others as you need them. Keeping receipts and entering them is easy. The biggest problem is your own inertia. If you’re used to not paying attention, it might be time to start.
- **Set-up your Accounts**: Household checking and a cash account for you and your spouse.
- **Paying their fair share.** If your adult child is working, s/he can share in the costs noted above; but, if not, they can still earn their way:
- - A job-search plan – with accountability meetings. If s/he had a job, they’d have those meetings there, wouldn’t they?
- Doing their share of household chores – no free ride.
- **Separate the individual costs.** Is your live-at-home son or daughter a finicky eater? Do they demand certain foods or sundries that you would not buy otherwise? See the ‘Food-Special’ category above. If you’re making the purchase, they go into that account. Otherwise, let them pay for those items themselves. They may quit drinking gourmet coffees at ridiculous prices.
Like everything else in life, it’s better when there’s a plan and a process. Once there’s a roadmap and process, everyone knows where they’re headed.
Enjoy
Jim
*1Source: Columbia University, National Center for Children in Poverty, “A Profile of Disconnected Young Adults in 2010,” December 2010 (latest available). Our thanks to Wealth Management Solutions, Inc., for this information.*
—————
***ADDITIONAL RESOURCES:***
**Arrange a brief15-minute introductiory phone call with Jim Lorenzen, CFP®, AIF®** [**here**](https://tinyurl.com/IFGIntroCall)**.**
IFG Report: Understanding Mutual Funds
IFG Report: The Hidden Risk No One Talks About (Registration required)
Begin the discussion with your spouse with this [Financial Converstion Checklist](https://indfin.com/financial-conversation-checklist). (No registration required)
Facing financial decisions but feel you need to do some homework first? You might benefit from looking through our free [Life Guides](https://tinyurl.com/IFGLifeGuides) and using some [financial worksheets](https://tinyurl.com/IFGWorksheets)!
Visit the[IFG Website](https://indfin.com/)!
Follow Jim on Twitter: [@jimlorenzen](https://twitter.com/JimLorenzen) and also on [Jim’s MoneyBlog](https://www.jimsmoneyblog.com/)
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp)
IFG on [Facebook](https://www.facebook.com/IFGAdvisory)
Become an IFG client! [Schedule your 15-minute introductory phone call here](https://www.timetrade.com/book/F7ZPS)!
———————
Jim Lorenzen is a[ *CERTIFIED FINANCIAL PLANNER®*](https://en.wikipedia.org/wiki/Certified_Financial_Planner) professional and An Accredited Investment Fiduciary® serving private clients since 1991. Opinions expressed are those of the author and do not represent the opinions of IFG any IFG affiliate or associated entity.
The Independent Financial Group is a fee-only registered investment advisor with clients located across the U.S. He is also licensed for insurance as an independent agent under California license 0C00742.Jim can be reached at 805.265.5416 or (from outside California) at 800.257.6659.
**Interested in becoming an IFG client?** Why play phone-tag? You can easily [schedule your 15-minute introductoryphone call!](https://www.timetrade.com/book/F7ZPS)
The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues
---
### [A Quick Estate Planning Checklist](https://indfin.com/a-quick-estate-planning-checklist/)
**Published:** May 14, 2013
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01901bb7b3ed970b-320wi.jpg)Here’s a quick checklist, courtesy of Kathleen McBride, Editor-in-Chief of*Wealth Channel, AdvisorOne*.
You may want to sit down with your estate-planning attorney and review it together.
1. Check your will and create a `revocable trust’ to avoid probate. Assets pass easily, much like under a will, but you can avoid the probate process. Make sure your will is placed inside the trust.
2. When you meet with your attorney, remember to set-up a review schedule. Current tax law never stays current.
3. Assets should be titled in the name of the revocable trust – that includes your home, car, investment accounts, and other property. Ask your attorney whether IRAs should be included since there are other factors to consider.
4. Make sure both the trust documentand will reference the new tax law.
5. You might want to make sure one or more people have a general power of attorney. If you get into a car accident, someone has to write checks.
6. Make sure you have a health care directive.
7. Discuss a limited power of appointment (LPA) with your attorney so that somebody who benefits from the trust can decide where it goes when they no longer need the income.
This is just a `heads-up’ checklist to discuss with your estate planning attorney. I am not an attorney and I didn’t even stay in a Holiday Inn Express. I did watch Perry Mason when I was a kid, but I’m not sure that counts.
Jim
—————-
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk "Hidden Risk Report")(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Financial Coversation Checklist")(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights "IFG Insights")to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter: @jimlorenzen
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Facebook](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
———————
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,****a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [A Market High!!!!! Should YOU Jump In?](https://indfin.com/a-market-high-should-you-jump-in/)
**Published:** April 4, 2013
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017c384ba4db970b-320wi.jpg)The market seemed to love the first quarter… as it’s loved many before. Does that mean the party will continue? It might be best to look at some underlying factors.
I, along with most other advisors, constantly caution people about trying to ‘time’ the markets. I personally don’t think anyone can do it with any consistency; and, even Warren Buffett says it’s a fools game – I guess he should know.
So the decision to sell, buy or wait based on market conditions, including the current one, is, according to experts, a fool’s game. I agree.
The issue isn’t whether we should be making market-based decisions; but how we make long-term career decisions, realizing that market climates, like the weather, will change. There are some things we do know, however:
- Interest rates are so low there’s only one direction left; it’s just that no one knows when or how fast.
- When interest rates rise, bond values go down. This isn’t an ‘if’; it’s a ‘when’. The first question, of course, will be when the Government will quit continuing to sell debt to finance new spending.
And, there are some other things we*should*know:
- Many company earnings and balance sheets have been bolstered by cutting costs (payroll) more than by increasing sales during a global recession.
- The government has been printing money, creating inflation, particularly in areas the government doesn’t count in its cost-of-living index (CPI-W, which measures wage inflation – a convenient measure during a recession when they want to reduce outlays to pension and Social Security recipients). This has the tendency to create inflation-fed stock market pricing, just as it creates it in grocery stores and gas pumps.
- When interest rates begin to rise, bond rates will follow suit – depressing bond prices, as stated earlier. When this happens, those holding bond mutual funds will see decreasing values; while those not in bonds or bond funds will begin to see them as a ‘safe haven’ offering a chance to buy higher yields at lower prices. Believe it or not, you CAN lose money in a bond fund; this comes as a surprise to many.
- When U.S. debt becomes less attractive globally, or the government cuts back on printing money to finance our growing debt, bond prices will begin to fall. It’s corresponding higher rates will likely siphon-off money from the stock market.
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017c384ba1fa970b-320wi.jpg)**Is the market overpriced?**
Some think not. Economist[Arthur Laffer](https://en.wikipedia.org/wiki/Arthur_Laffer "Arthur Laffer"), the architect of The[Laffer Curve](https://en.wikipedia.org/wiki/Laffer_curve "Laffer curve")and President Reagan’s ‘supply side’ approach to economics, recently stated in an interview that current corporate earnings actually justify higher prices if only there were less government intervention. While it could be true; it’s also easy to see the source of those profits, as I indicated earlier.
**So much for white noise.**
What has all this to do with your retirement within the next ten or twenty years? Probably less than zero.
It probably means just as much to you as the Cuban Missile Crisis, the attack on the Marine barracks in Beirut, the gas lines of the late ’70s, or the bank failures of the early ’80s meant to the retirees of today.
**Economies, like life, move on.**
There seems to be little doubt among most experts – a scary thought when too many agree and follow the “this-time-it’s-different” crowd – that the future will probably mean lower yields and returns than the historic averages we’ve grown accustomed to over the past few decades. The demographic trend of an aging population would seem to support this; but, it’s also true that that may be more of a domestic (U.S.) issue, while more companies are doing business globally than ever before. Caterpillar, after all, is selling equipment all over the world, including China, where the demand for roads is expected to grow exponentially over the next decade; and Caterpillar isn’t alone.
What does all this have to do with your retirement within the next ten or twenty years? Maybe something. You should talk to your advisor about what, if anything, that means to you.
- **Follow your written business**plan, investment plan, financial plan, survival roadmap, monetary guidebook, whatever you want to call it. It’s your ‘lighthouse’ in the storm – the one thing that is stationary when all else around you is in turmoil.
- **Avoid fads**. The world hasn’t really changed, despite the man-made economic events that have convinced us otherwise. The investment industry events a new theory every time the public has a new worry. Then, they manufacture a product utilizing the theory to address the worry. Many in the investment world believe that many long-accepted theories regarding risk-adjusted asset allocation strategies are now outmoded in ‘the new environment’ and new theories, with new products those theories sell, are the new way to address these new concerns. Unfortunately, many of these new solutions come at a high cost and, in the end, are likely to make little if any difference.
- **[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017ee9006d09970d-120wi.jpg)Think long-term**. Don’t react. Better: Turn-off the news. Most of it is really just entertainment anyway. Your long-term success will not be tied to how you reacted to a news story. The next time you hear about a Warren Buffett investment, remember that he had been negotiating a deal you’d never get access to and had been doing it for some time before the news media even learned about it. You and I were the last to know.
It’s about putting time on your side by following a long-term plan – something you and your advisor should be regularly reviewing.
————————–
*RESOURCES:*
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk "Hidden Risk Report")(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Financial Conversation Checklist")(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights "Subscribe to IFG Insights")to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/ "Begin Your Planning Now!")
Follow Jim on Twitter: @jimlorenzen
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Facebook](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
———————
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of***[***The Independent Financial Group***](https://indfin.com/)***,****a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using aproven planning processcoupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [A Lesson from the Banks](https://indfin.com/a-lesson-from-the-banks/)
**Published:** December 1, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73df22bdd970d-320wi.jpg)Jim Lorenzen, CFP®, AIF®
**I think many, if not most, professional advisors would agree that even 99% of”the affluent” make the same mistakes made by virtually every other American.**
Fact is, even “rich” people worry about running out of money because they live at a higher standard and have a larger ‘cash burn’.
But, many wealthy people know something others don’t.
**Programmed bias:** Since childhood, we’ve been taught the same things, which is why most of us tend to do the same things. Some people, however, were maybe lucky enough to be mentored or did a lot of non-traditional financial reading – reading outside the financial entertainment universe. Some learned from experience.
Whatever the reason, it seems that those who’ve achieved true wealth often were doing the kinds of things the rest of us either didn’t know about or were unwilling to do – it’s hard to go against everything we’ve been taught, which may bewhy, according to one figure I saw, **less than 7% of all Americans have amassed even $500,000 in investment assets.**.. and far fewer have achieved financial wealth in the millions.
**Myth: Debt is bad.** We’re all told to get out of debt and remain debt-free. The idea is that we’ll be safer and be able to sleep better at night. But, is that true?
**Reality: Destructive debt is bad**. ***Constructive* debt can be good!**
**Lessons from the banks**
All through American history, most people have come to see banks as corporate giants who’ve become rich off of the rest of us. Banks borrow money from consumers constantly. They do this by paying interest on savings accounts, CDs, and lines of credit.
Think about it. They make a *concerted effort* to borrow every single day – they even *buy advertising* to get people to lend them money! And, of course, you know why they do it. They lend the money out at higher rates and make their money on the margin.
No mystery there. It’s called arbitrage. Banks want a rate of return on the money they loan out.
Banks do it; why don’t the rest of us?
**Mistakes most Americans make**
Back in the late 1970’s, I read an interview with Jack Nicklaus, and I’ve never forgotten it. In addition to his golf winnings and endorsement money, he had a successful golf course design business \[he still has it and today he has more than 50 projects under development all over the world; in fact, over 80% of his business is now outside the United States\].
In that interview, he mentioned that he’d made some mistakes early in building his business – mistakes he was correcting. He said that in the early years he had all of his net worth tied-up in his business. He said it was only later he realized that this type of equity position didn’t have a rate of return.Business growth should arrive organically, not through loss of return.
From that point on, he used his business as *a vehicle* to generate cash flow (excess revenue after all taxes and expenses had been paid) and began to build his net worth *away* from his business where he could actually generate a rate of return.
**Common programmed bias**: We’ve been told: Pay-off your home! Own it free-and-clear. Some are taking a second look at this idea.
Now, I’m not suggesting you take out a second trust deed and put the money into the stock market, even for long-term growth. That’s probably not a good idea. Besides, your situation may involve another set of circumstances, needs, and objectives that this piece isn’t even addressing.
But, that doesn’t eliminate this as a valid financial strategic question:
- Is holding home equity really a good idea? Or,
- should we be doing what banks do?
After all, banks have a ton of liabilities on their balance sheet; yet, most banks are *completely solvent* and consider their operations debt-free!
Lesson: Debt and solvency aren’t mutually exclusive financial concepts. You can have debt – even a lot of debt – and still be solvent.
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73de5d743970d-320wi1.jpg)Consider this example:**
Let’s say you own a $500,000 home that has $250,000 worth of equity.
Your balance sheet would look something like this:
Assets: $500,000 home
Liabilities: $250,000 mortgage
Net Worth: $250,000
Point: Your equity will rise or fall with the housing market, but, there’s no real rate of return.
Even if your home appreciates 10% to $550,000, you would have $300,000 in equity – on paper; but, it’s not a return.
Now, ask yourself this: How accessible is it in an emergency? If you lose your job or become disabled, will you qualify for a loan – hard to do when you’re out of work – to access that equity then?
Maybe not. You’d have net worth, but no money. You could take a reverse mortgage; but, that takes time and expense. It’s also something very difficult, if at all possible, to undo.
**How about this?** What if you were to refinance or add a mortgage for your $250,000 in equity and *loaned* that money out?
Your balance sheet would look something like this
Assets: $500,000 house + $250,000 returning a fixed return
Liabilities: $500,000 house
Net Worth: $250,000
No difference in net worth, except you now have a fixed return, too! The return is taxable, and it must exceed the cost of the loan on an after-tax basis to be profitable; but, it’s doable if you can find one or more quality, i.e. “safe” or “secured”, borrowers that can pay a dependable and competitive return..
Now, what ifthe houseappreciates 10% just as before and your fixed return was just half that, at 5%, your balance sheet would look like this:
Assets: $550,000 house;$262,500 returning a fixed return (compounded)
Liabilities: $500,000
Net Worth: $312,500 – Now, that’s a $62,500 difference.
**You still have your equity. Except now it’s not IN your home; it’s BESIDE it.** And, if done correctly, that equity will be accessible without loan applications or even delay, as you will see.
Oh, yes; you may have noticed I didn’t mention taxes on the 5% return… that’s because you should be loaning your money in a tax-advantaged way… and at compound interest!
**If equity has no return “inside” the house; the key is to reposition it “beside” the house where it can earn a return and provide liquidity.**
The proper arrangement of assets can be very powerful.
**Interest:** Yes, you’d be paying interest on your mortgage – let’s assume it’s around 5%. That interest is tax deductible! At a combined state and federal income tax rate of 33%, you’d really be paying 3.34%. Now, if you can loan it out at a compound after-tax rate that’s higher, you’re a winner…. And if it’s tax-advantaged, you can really grow your future!
Where do you get the money to service the additional mortgage interest until you can deduct it?
Why not simply change your withholding exemptions on your paycheck?[\[ii\]](#_edn2)
**Do you stay in debt forever?**
**It’s worth repeating: You’re not eliminating your equity.** You’re just re-positioning it from your house and putting it into a kind of *side* account -onesitting “next to” your house; except thisside accountearns a rate of return.
Suppose some years from now your home is valued at $800,000 and it’s fully mortgaged; but, yourside accounthas $900,000 in it – very possible with both the power of compounding and using a tax-advantaged strategy – would you consider that mortgage *‘as good as paid-off’*?I certainly would, and then some.
That’s why banks consider themselves solvent even with liabilities on the books. If you have more money than needed *in your equity side-bucket*, you’re solvent, particularly if it’s accessible on a tax-advantaged basis.
**Who’s** ***really*** **in a safer position? Let’s compare.**
If you were doing this, how would your financial picture compare to your neighbor who’s doing what everyone else is doing?
Just two points tell an interesting story:
- If both of you lose your income, which one is able to access equity more easily for living costs or emergency expenses? Which one of you has true safety and liquidity? You have liquidity; your neighbor may not qualify for a loan.
- Which one is better protected against foreclosure? A bank will foreclose on a home with 100% equity faster than one with 100% debt… and it’s proportional at every degree in between. And, it doesn’t matter if your neighbor paid $50,000 toward the balance the week before! The monthly payment is still due and if not paid… well, you know.
**Your position? Just like the banks: You may have liabilities on the books; but, you’re not in debt.**
**Quick review**: Your money is (should be) in a position that’s secured, liquid, and offering a consistent, conservative, fixed rate of return. You can tap it for emergencies. Your bank has no incentive to foreclose. You want to pay off your house? You can (should be able to) do it in a heartbeat.
**Who’s in the better position?**
- **Your neighbor**: He believed everything he was taught by people – probably parents – who also followed the same formula. He may not be able to access a loan, savings could be diminishing, and his equity is tied-up, inaccessible without adding more debt or taking a reverse mortgage, which may not be advisable.
- **You** have all your equity… it’s justBESIDE your house, notIN it. The banks can’t touch it there, until you decide. You have instant access.
**You need a quality borrower: Who do you loan your money to?**
Your uncle Fred? Your neighbors? Do you run out and buy real estate notes? I don’t think so.They don’t satisfy the **4-point test**:
- **liquidity**
- **safety**
- **predictability**
- **tax-favored**
**Why not loan your equity to an investment-grade financial institution and receive a return?**
There are ways to design sound retirement strategies using well-known “investment grade” financial institutions that can provide the right platforms and designs required – provided – you’re not trying to ‘get rich’ overnight.
Note: You could loan money to large corporations and institutions by simply buying their bonds – a bond is simply an IOU that pays interest until the principal is returned at maturity – but, bonds wouldn’t satisfy the 4-point test. They’re liquid, but have to be sold on the open market, and likely at a loss in a rising interest rate environment. While they can provide safety and predictability, they’re not tax-favored since interest is generally taxed at regular income tax rates.[\[iii\]](#_edn3)
There are conservative strategic approaches to arranging financial assets that can not only address the issues cited above, but can also provide for a tax-advantaged retirement, as well.
**What are 85% of Fortune 500 CEOs doing, as well as many members of Congress?[**\[iv\]**](#_edn4)**
Many investment-grade financial institutions have offerings that meet the 4-point test; and the strategies used by so many CEOs and members of Congress are actually available to anyone.
Worth noting: If your objective is to build a side-fund that will accomplish the goals outlined above and also provide for a tax-free retirement, you can’t wait until you’re ready to retire. That simply won’t work. The retirement objective must be addressed much earlier – the earlier the better, but age 60 is about the limit. The reason is simple: It takes time to make the proper arrangement of assets and to build the tax-advantaged value you’ll need. As I said, it’s not a ‘get rich quick’ scheme; it’s a conservative strategy – conservative strategies always take longer – involving quality investment-grade institutions.
I’ve created a report that reveals what these people know about arranging assets so that they can not only plan for a tax-free retirement, but they also can arrange for a sizable side-fund that can be accessed tax-free. You’ll need to go through an opt-in page to access it. You can access that report here.
I think you’ll find it interesting and likely very helpful.
[\[i\]](#_ednref1) *The Power of Zero*, David McKnight. Acanthus Publishing, 2013.
[\[ii\]](#_ednref2) Be sure to discuss this with your tax advisor
[\[iii\]](#_ednref3) ibid
[\[iv\]](#_ednref4) See Footnote #1

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Life Insurance, Retirement
---
### [A "Heads-Up" for 2014](https://indfin.com/a-heads-up-for-2014/)
**Published:** January 10, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi1.jpg)Watch for mutual fund companies to begin touting their 5-year track-records in a race for new assets. That’s because the ‘market meltdown’ happened six years ago, so those numbers won’t show up in the five-year calculations. I don’t expect too many commercials touting ten-year returns since those would include the melt-down years.
Also worth thinking about: The market experience pretty decent gains during 2013… somewhere around 30%. Few expect that trend to continue and many, if not most analysts, expect more modest returns for 2014… in the neighborhood of mid-to-low single-digit returns. If that’s true, mutual fund investors may want to be careful. If the returns are as low as expected, many mutual fund managers may decide to lock-in their gains, and that may create a double-hit for mutual fund investors: Low returns combined with a high tax bill.
Jim
———-
Here’s a free report:Understanding The Mutual Fund Landscape.
You also might like:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk%20 "Hidden Risk Report").

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [The 401K Failure](https://indfin.com/401kfailure/)
**Published:** August 3, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/target-date-funds-an-easy-answer/6a017c332c5ecb970b019aff2c9b18970d-320wi/)*Fotilla Images***Are we in the midst of a 401(k) failure?** Some time ago,PBS aired an excellent program on retirement and how the various generation, including baby boomers, are being affected by their planning – or failure to plan.
It’s an hour-long program entitled, **“[When I’m 65](https://www.wi65.org/)“**. The program addresses savings rates, withdrawal rates, investment pitfalls, issues to address, pitfalls to avoid, and even the difference between advisors, including the fiduciary standard – what it means and why it’s different from the ‘suitability’ standard adopted by product sellers. It also discusses the recent legislation affecting the advisory industry and consumers and even addresses annuities – insurance-based productswidely misunderstood by much of the general public who tend to see things through an ‘either-or’ lens (for additional information on income annuities, you can access a ‘primer’ here).
This PBS program iswell worth watching. You may even want to forward it to someone who you think can benefit. You can see it[here](https://www.wi65.org/)– scroll down to the video.
There have beenquestions about the failure of the 401(k) system that have been discussed in the media from time to time since the 2008-9 market meltdown. This topic was addressed in a Frontline program some time ago and also well worth watching:
I addressed this issue myself in a webinar I recorded last year. It’s also about an hour long; so, for those of you who aren’t faint of heart, you can access it here. I think you might find it interesting, as well.
Hope you find all of this worthwhile and helpful.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Taxes
**Tags:** Reducing Risk, Retirement Planning, Retirement Strategy, Retirement tax strategies
---
### [Retirement and Social Security](https://indfin.com/2093-2/)
**Published:** May 25, 2016
**Author:** Jim Lorenzen
**Content:**
**Jim Lorenzen, CFP®, AIF****®**
It’s one thing to simply ‘maximize’ your Social Security, it’s another to know just how taxation and the future health care costs will impact your plans.
**Your planning solution should be able to:**
- Quickly provide estimated health care costs in retirement for individuals or couples.
- Incorporate Medicare Parts B and D, Medigap and out-of-pocket care expenses.
- Calculate the total lifetime cost of health care in current dollars.
- Provide a side-by-side comparison of your lifetime health care costs with projected Social Security benefits
- Create a full financial picture to addressyour best interests.
And, remember, Social Security is taxable income. You may be interested in this report, “***Retirement and Social Security***“.
Jim
See “[*The IFG Difference*](https://indfin.com/video-library-2/)”
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional. 
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
**Tags:** Retirement Planning, Retirement Strategy
---
### [](https://indfin.com/1990-2/)
**Published:** March 9, 2016
**Author:** Jim Lorenzen
**Content:**
Numerous studies have consistently shown than Americans are ill-prepared for retirement. 401(k)s have apparently failed to provide a solution.
You may be interested in seeing just how pervasive this issue has become.
If that weren’t enough, the increasing national debt coupled with increasing entitlement obligations has made it painfully obvious to many that their taxes just might go up during their retirement years – something unthinkable in the past.
So, what can be done? Many people are look for a different strategy involving a solution that eliminates both market risk and potential negative tax-law changes in the future. I’ve recorded a webinar – it’s about an hour long – that may provide some food for thought for many. I hope you enjoy it. You can register and access it here.
Enjoy,
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Life Insurance, Retirement, Taxes
---
### [The Future of Social Security](https://indfin.com/the-future-of-social-security/)
**Published:** March 17, 2025
**Author:** Jim Lorenzen
**Excerpt:** During his campaign, President Donald Trump pledged not to reduce Social Security benefits. He even proposed eliminating taxation on Social Security benefits, which would enable higher-income beneficiaries to retain more of their income.
**Content:**
A purely economic analysis seems to indicate this proposal does not seem to account for the financial consequences it could have on the Social Security Trust Fund; and other than a some feedback from the financial community, few seem to be engaging the discussion.
Social Security is the issue everyone wants to save; but some cures might cause even bigger problems. The elimination of this tax revenue stream is projected to accelerate the fund’s depletion by three years, expediting insolvency sooner than current projections suggest.
Despite these promises, the influence of Project 2025—a policy blueprint associated with conservative governance—on Trump’s Social Security policies remains uncertain. While Trump has publicly distanced himself from the initiative, many of his policies align with its recommendations. Notably, Project 2025 does not explicitly address Social Security, leaving uncertainty about how his administration will approach the program.
**Impact on Social Security Administration Operations**
One area that is expected to see significant change under the Trump administration is the operational efficiency of the Social Security Administration (SSA). The newly proposed Department of Government Efficiency (DOGE), spearheaded by Trump’s policy team, has identified SSA as a target for further cost-cutting measures. This is despite SSA’s reputation as one of the most efficiently managed government agencies.
Under the leadership of Commissioner Martin O’Malley, SSA made significant strides in improving efficiency. In 2024, productivity increased by 6.2%, even as the number of new beneficiaries surged. Despite these gains, SSA operates with its lowest staffing levels in 50 years. O’Malley implemented several improvements, including reducing average call wait times from 42 minutes to 12 minutes, streamlining procedures for overpayments and underpayments, and accelerating the processing of disability approvals.
Despite these advancements, Trump’s DOGE team has indicated plans to further scrutinize the agency’s operations, focusing on eliminating “waste, fraud, and abuse,” with an emphasis on ensuring that payments are directed only to rightful beneficiaries. The assertion is that these measures could save “hundreds of billions of dollars” without requiring changes to benefit formulas.
While these reforms are positioned as efficiency improvements, there is concern about their impact on service delivery. The departure of Commissioner O’Malley raises further uncertainty, as the President has nominated financial software executive and GOP donor Frank Bisignano to assume the role. Bisignano, known for his success in transforming large corporations, will be tasked with overseeing SSA’s continued commitment to service efficiency. However, there are concerns that further reductions in staffing and resources could result in longer wait times, increased errors in claims processing, and a decline in service quality.
The area most likely to experience disruptions is survivor benefits – something that requires manual processing rather than automated calculations. Any reductions in staffing or efficiency could lead to delays and complications for beneficiaries relying on these essential payments.
**The Social Security Trust Fund and Fiscal Challenges**
A major concern surrounding the President’s policies is the potential impact on the Social Security Trust Fund. An analysis by the Committee for a Responsible Federal Budget (CRFB) evaluated the implications of Trump’s proposals and found that they would significantly exacerbate Social Security’s financial shortfall.
According to the CRFB’s report, *What Would the Trump Campaign Plans Mean for Social Security?*, the following consequences could result from Trump’s proposals:
- Increase Social Security’s ten-year cash shortfall by $2.3 trillion through the fiscal year 2035.
- Advance the projected insolvency of the trust fund from 2034 to 2031, effectively reducing the timeline for corrective action by one-third.
- Lead to a 33% across-the-board benefit cut in 2035, up from the 23% cut projected under current law.
- Increase Social Security’s annual funding gap by approximately 50% in 2035, raising it from 3.6% to 4% of taxable payroll.
- Require either a one-third reduction in benefits or a 50% increase in revenue to restore 75-year solvency.
[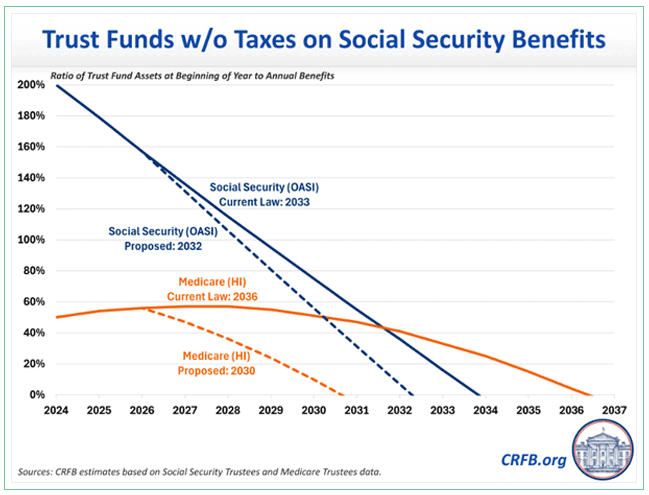](https://indfin.com/wp-content/uploads/2025/03/Trust-Funds-without-taxes-on-benefits.png)*A comparison of Social Security Trust Funds before and after proposed tax repeal***Trump’s Proposals and Their Fiscal Implications**
While the administration has pledged not to touch benefits, it appears the economic consequences of other policies could lead to some ripple-effect unintended consequences.
Several specific policy proposals put forth by the administration could further weaken the financial stability of Social Security due to impacts seldom discussed:
1. **Eliminating Taxation of Social Security Benefits**
- Currently, a portion of Social Security benefits are subject to taxation, and the revenue generated is used to help fund the program. Eliminating these taxes would remove a crucial funding source, accelerating the depletion of the trust fund.
2. **Ending Taxes on Overtime Pay and Tips**
- Trump’s proposal to exempt overtime pay and tipped wages from taxation would reduce payroll tax revenue, further limiting contributions to Social Security and Medicare trust funds.
3. **Imposing Large Tariffs on Imports**
- Tariff policies could lead to higher inflation, which would, in turn, increase the cost-of-living adjustments (COLAs) for Social Security beneficiaries. Higher inflation would put additional financial strain on the trust fund (surprise).
4. **Enhanced Border Security and Deportation of Unauthorized Immigrants**
- The removal of undocumented workers would reduce the number of individuals paying into the Social Security system, decreasing payroll tax revenue and exacerbating the program’s financial challenges.
**Effects on Medicare and Other Social Programs**
The financial instability of Social Security would also have significant implications for Medicare, which is partially administered by SSA. A separate CRFB analysis, published in July, focused on the potential impact of eliminating taxes on Social Security benefits. The findings indicated that this policy alone would accelerate the insolvency of Medicare’s Hospital Insurance (HI) Trust Fund by six years.
Given that Medicare and Social Security serve overlapping beneficiary populations, any financial strain on one program is likely to have cascading effects on the other. Increased pressure on these programs could lead to reductions in services, increased premiums, or policy changes that shift more costs onto beneficiaries.
**Conclusion**
While President-elect Trump has pledged not to cut Social Security benefits, his proposed policies could have significant long-term consequences for the program’s financial stability. The elimination of taxation on Social Security benefits, changes to payroll tax structures, and other proposed economic measures could hasten the insolvency of the Social Security Trust Fund, leading to substantial benefit cuts in the future, despite how good they sound.
The operational efficiency of SSA is another area of concern. Despite notable improvements under Commissioner O’Malley, the Trump administration’s plans to further streamline the agency could negatively impact customer service, leading to longer wait times and increased administrative challenges—particularly for individuals applying for survivor benefits.
As policymakers and beneficiaries alike evaluate the future of Social Security under the Trump administration, it is essential to consider both the short-term benefits of proposed tax cuts and the long-term sustainability of the program. Ensuring the financial health of Social Security will require a balanced approach that safeguards the needs of current and future beneficiaries while addressing funding challenges through responsible fiscal policy.
Did I say ‘responsible fiscal policy’? Wouldn’t that be a nice change…..
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Tariffs, Trade Wars and the Cost of Guacamole](https://indfin.com/tariffs-trade-wars-and-the-cost-of-guacamole/)
**Published:** March 12, 2025
**Author:** Jim Lorenzen
**Excerpt:** Rise of avocados is a powerful lesson in understanding how markets evolve
**Content:**
Avocados have transformed from a niche fruit into a staple of the American diet, reflecting broader economic and trade dynamics, including tariffs. For investors and consumers alike, the avocado economy serves as a compelling case study in supply, demand, and globalization.
**A 10,000-Year-Old Superfood**
Avocados have been part of human diets for over 10,000 years. Early civilizations in present-day Mexico and Central America selectively cultivated them to enhance their size, richness, and resilience. Today, avocados are a dietary staple for millions of Americans, prized for their creamy texture, high nutritional value, and versatility.
However, this wasn’t always the case. In the 1970s, the average American consumed less than a pound of avocados per year, hardly a target for tariffs. By the 1990s, that figure had barely doubled. Then, thanks to strategic marketing, shifting consumer preferences, and favorable trade policies, avocado consumption surged – quadrupling since the early 2000s to over nine pounds per person annually.
**Why Mexico Rules the Avocado Market**
With nearly 3 billion pounds of avocados consumed in the U.S. each year, domestic growers cannot meet demand. That’s where Mexico comes in. Today, nearly 90% of avocados eaten in the U.S. originate from Mexico, whose climate allows for year-round harvesting.
This dominance stems from several key factors:
- **Ideal Climate & Growing Conditions** – Mexico’s Michoacán region, the heart of the avocado industry, has optimal weather and volcanic soil that enable continuous production.
- **Trade Agreements & Market Access** – The North American Free Trade Agreement (NAFTA), later replaced by the U.S.-Mexico-Canada Agreement (USMCA), facilitated a steady flow of avocado imports into the U.S.
- **Marketing & Cultural Influence** – Aggressive marketing campaigns, particularly those linked to major events like the Super Bowl, turned avocados into a cultural phenomenon and an American dietary essential.
**Tariffs, Trade Wars, and the Cost of Guacamole**
Despite the avocado’s success, the trade is not immune to political and economic headwinds. Tariffs and trade tensions have introduced price volatility. When the Trump administration threatened tariffs on Mexican imports, businesses faced a dilemma: absorb the additional costs or pass them on to consumers. Even when tariffs were postponed, the mere possibility of disruption underscored how dependent the U.S. has become on Mexico for its avocado supply.
For investors, this dependency raises important considerations. Shifts in trade policy, climate-related supply chain risks, and evolving consumer demand all influence avocado pricing – and, by extension, the profitability of food, agriculture, and distribution companies.
**Lessons for Investors: The Avocado Economy in Action**
The rise of the avocado offers broader investment insights:
**Consumer Trends Drive Markets** – The surge in avocado consumption highlights how shifting dietary habits fuel market demand. Investors who anticipate such trends – whether in food, technology, or energy – can capitalize on emerging opportunities.
**Supply Chain Vulnerabilities Matter** – The U.S. depends on Mexico for avocados much as it relies on specific regions for semiconductor chips or rare earth minerals. This underscores the importance of diversification and contingency planning in business and investing. No wonder CEOs are concerned about where to commit capital. No wonder investors are seeking safe havens.
**Trade Policies Shape Business Strategy** – Uncertainty in tariffs and trade regulations directly affects costs and supply chains. Investors should monitor geopolitical developments that impact key industries.
**From Toast to Trade: The Bigger Picture**
Avocados are more than just a trendy food. They embody the intersection of agriculture, international trade, and consumer behavior. Whether or not tariffs return and despite fluctuations in supply, one thing is certain – Americans aren’t giving up their guacamole anytime soon.
For investors, that’s a powerful lesson in understanding how markets evolve over time.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
**Tags:** economy, Tariffs, Trade wars
---
### ["How Can I Increase My Social Security Benefit?"](https://indfin.com/how-can-i-increase-my-social-security-benefit/)
**Published:** February 27, 2025
**Author:** Jim Lorenzen
**Excerpt:** Not so long ago, baby boomers viewed Social Security as a retirement program for old folks. High-earning boomers felt that Social Security didn’t apply to them because the monthly checks were small, and they believed the system wouldn’t be around when they retired.
**Content:**
The question most asked by Baby Boomers ask. Here are some answers:
Now the tide has shifted. Nearly all boomers have embraced Social Security, and they’re on a mission to get the most out of the system. Maximizing your benefits has become a national obsession, even—especially—among high-earners.
A boomer who has earned the benefit maximum throughout his career and who claims at full retirement age (67 for those born after 1959) will receive a monthly benefit of approximately $3,600. If he plays his cards right, he could receive even more.
So, how do you play your cards right today?
One of the most frequently asked questions by boomers is: “How can I increase my Social Security benefit?” There are three ways to do it.
[Here’s how!](https://hmlink.co/ZRJ)
You can also learn more about Social Security planning[ here.](https://indfin.com/socialsecurity/)
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Bad Tax Planning begins when you believe your 401(k)/IRA statements.](https://indfin.com/bad-tax-planning-believing-your-retirement-statements/)
**Published:** February 18, 2025
**Author:** Jim Lorenzen
**Excerpt:** If you have $500,000 in your 401(k) or IRA, it’s not really $500.000. That's a tax planning mistake most people make going right out of the gate. If you’re married and filing jointly, it’s more likely you could have $325,000 (35% tax bracket) or just $315,000 (37% tax bracket).
**Content:**
Tax deferred should read ‘tax delayed’. Do you know what taxes will be when you’re 73/75 and required by the I.R.S. to take distributions? Would you like to [take a guess](https://www.usdebtclock.org/)? Good tax planning begins with thinking ahead.
It’s not only highly likely your accounts (and therefore your RMDs) will be much larger, but the tax rates may be much higher, too. And, of course, all this will impact the tax rates on your Social Security benefits – and those brackets aren’t adjusted for inflation; so, inflation alone will push many into higher Social Security tax brackets.
[](https://indfin.com/wp-content/uploads/2025/02/iStock_UncleSamLiftingWallet_Medium.jpg)Oh yes, tax planning can’t ignore Medicare. Medicare premiums are impacted, too. Have you met IRMAA?
IRMAA stands for “Income-Related Monthly Adjustment Amount.” The emphasis is on “income” because it is a monthly tiered surcharge (again, a kind of tax) that is tacked on to people’s Medicare Parts B and D premiums. But it only happens if you have income over $103,000 for single filers and $206,000 for married couples filing a joint return. Let’s take a look at what this means in action.
Take George and Martha. This hypothetical couple are a high-earning married couple, and both are Medicare Part B and D participants. Point worth remembering: IRMAA surcharges *affect income from two years prior*, and this couple was on track for $322,000 of modified adjusted gross income, or MAGI.
But on December 1, George decided to sell a stock he bought for $10,000 back in 2007. He sold the stock for $11,000. The resulting $1,000 of gain was taxed at the 15% long-term capital gains rate, plus an additional 3.8% net investment income surtax for a total federal tax bill of 18.8%. (That 3.8% net investment income surtax is another tax that comes into play when your MAGI exceeds $200,000 for singles and $250,000 for married couples.)
So, George and Martha owe $188 of tax on the gain from their sale of the stock, right – 18.8% of $1,000.
Nope.
They’re in for a surprise. You can [read the whole story here.](https://indfin.com/tax-planning-the-smart-way/)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
**Tags:** Retirement Planning, tax management, tax planning, Tax reduction
---
### [DOGE Wants to "Streamline" Social Security - That will be interesting.](https://indfin.com/social-security-streamlined/)
**Published:** February 10, 2025
**Author:** Jim Lorenzen
**Excerpt:** The three largest expenses in the federal budget are Social Security/Medicare, interest on the debt, and defense.
**Content:**
Streamlining Social Security?
As I indicated in [my previous post](https://indfin.com/no-more-zero-interest-rates/), there’s a good budgetary reason the administration wants lower interest rates, – the dirty secret is that it allows for more spending – but back to DOGE.
President Trump has been doing all he can to keep his campaign promises. There were three that stand out:
1. He promised not to touch Social Security or Medicare (which continually add to the deficit)
2. He promised to increase our defenses (additional spending)
3. He promised to cut spending (however, he wants an increase in the debt limit)
Problem is, all three of these largest categories are major contributors to our deficits, and therefore, our debt.
So, where can the administration cut? Agriculture? Don’t bet on it. Now, we’re back to efficiency.
Musk says, when it comes to Social Security/Medicare, he’s interested in rooting out fraud and elicit payments. Problem is SSA staffing levels are now at a 50-year low (have you tried to call them lately?) and the baby boomers are just now beginning to apply. Automated systems are good, but the processing of survivor benefits, to name just one, do require human intervention. Problem is that the entire federal labor force represents only a tiny portion of our nation’s annual deficit.
Why does this matter? Politics aside, your financial planning should take into account that future Social Security benefits – those after 2035 – may not look the way they look today. Congress has a poor record when it comes to courage.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [No More Zero Interest Rates!](https://indfin.com/no-more-zero-interest-rates/)
**Published:** February 5, 2025
**Author:** Jim Lorenzen
**Excerpt:** The Fed's zero interest-rate policy (ZIRP) resulted in printing money. Quantitative easing (QE) seemed to work as the stock market saw it's longest bull market in history.
**Content:**
ZIRP ended in 2022. Now, the Fed’s balance sheet is at $7 trillion – $6 trillion more than the $1 trillion historical average.
If interest rates rise, it could lead to a ‘debt spiral’ – servicing the interest on our $36 trillion dollar debt (which is [constantly rising](https://www.usdebtclock.org/)) by “monetizing” – which means borrowing even more.
[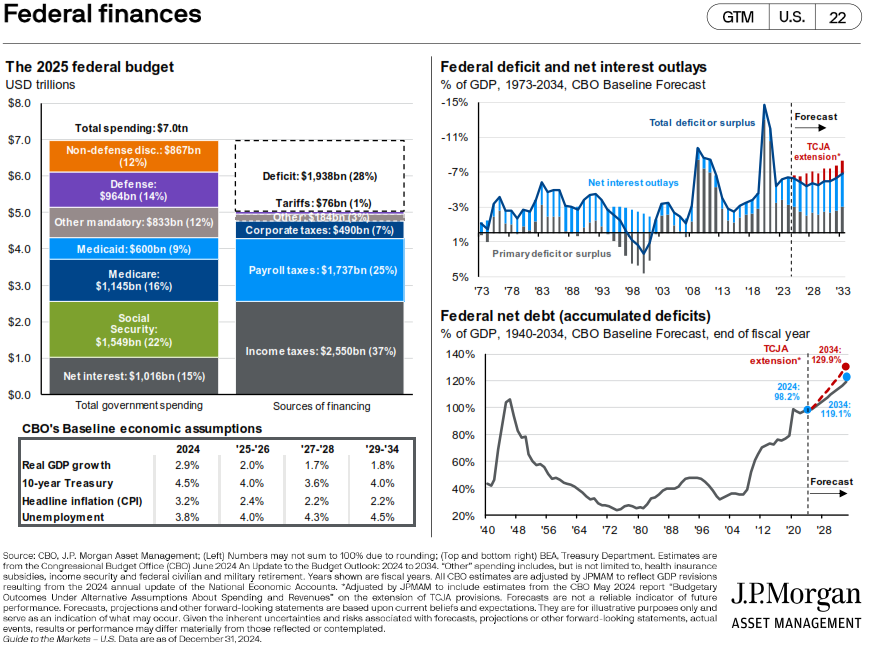](https://indfin.com/wp-content/uploads/2025/02/Fed-Finances-2025-Jan.png)Interest payments are already our government’s third highest expense – even higher than defense. And, if interest rates rise above 5%, interest on the debt will become the government’s single largest expense.
Inflation complicates things. No surprise. Politician’s promises seem to always come with price tags, while most of the talk about reorganization will face problems on Capitol Hill – every expenditure has a constituency and they are, after all, in the re-election business.
Be careful what you wish for.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Happy Thanksgiving: Should you be thankful for the electoral college?](https://indfin.com/happy-thanksgiving-should-you-be-thankful-for-the-electoral-college/)
**Published:** November 21, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/09/Time_Is_Money.jpg)
**Jim Lorenzen, CFP®, AIF®**
You’re probably wondering, “What does the electoral college debate have to do with Thanksgiving? Nothing.
It maybe has more to do with being thankful for our founding fathers’ wisdom. And, I’m not talking about this past election, but the reasons why the electoral college was created for all elections we’ve had and will have in the future. Those who say it’s `outdated’ probably don’t understand why it was created – and why eliminating it will likely never happen.
As an amateur historian – an un-ranked/low-rank/no-rank amateur, at that – I’ve found that learning about these things can be quite interesting, which shows you how much excitement I have in my life.
I won’t get into the weeds on this, lest your eyes begin to glaze over; however, I will give you the names of a couple books, should you find you’d like to learn more.
Even as far back as the Constitution Convention in 1787, race and class warfare was alive and well in America; indeed, the Constitution itself can be, and has been, viewed by some as a racist document, but that’s another story. Slavery was the elephant in the room no one wanted to talk about since, at that time, the object was to keep the southern states on-board as the northern states were striving for unity in the separation from English rule.
The divisions were complicated: Northern mercantile vs southern agriculture economies – large states vs. small states, etc. So, regional and cultural differences not only divided many, but also made them in many ways interdependent. As was also true then, the population centers, such as they were in those days, tended to be clustered around Boston, Philadelphia, and New York. The rest of the population was spread-out throughout the colonies in rural areas, including the agricultural south.
In the convention, small states didn’t want to be dictated to by the large; and were concerned that regional influences could dominate national interest, so a system of ‘electors’ was created to ensure that smaller states could still have a voice in the democracy.
The system was based on state representation. Each state would receive one elector for each senator (2 from each state), and one elector for each member of the House. Each house member would come from a congressional district, the number of districts being determined by the state’s population. No state would have less than 3 electors (Rhode Island’s 1 district + 2 senators), but only population growth would limit the larger states, albeit there was a moderation factor: the limit of 1 elector for each of the two senators.
As I said, this is a short version.
[](https://indfin.com/wp-content/uploads/2014/10/6a00d83451c82369e201b8d0769f84970c-600wi.jpg)Still, even today, no one regional area can dominate national election results; and, this latest election is just the most recent example (there have been others throughout our history) that demonstrates exactly what the founders had in mind.
Below is a county-by-county map of the recent Presidential election results. While it doesn’t reflect the degree of victory for each county (landslide vs. squeeker), it does provide a broad picture of the larger regional support patterns.
As you can see, Democrats did well in densely populated regions like the California coast, the Miami-Dade area in Florida, and New England. Hence, Mrs. Clinton won more popular votes than did Mr. Trump because of the high concentration population centers placed in only a few regions – the exact issue the founders in the Philadelphia State House that summer were trying to moderate.
If there had been no electoral college to moderate regional influence in this past election, the people in Ohio, Indiana, Michigan, Wisconsin, Oklahoma, Iowa, Kansas, Missouri, Nebraska, and many other states would have had – and maybe would never have – a voice in the electoral process.
Indeed, the electoral college was the reason both presidential candidates spent time in Nevada. Without the electoral system, they would have ignored the state completely. Bottom line: Every regionshould have an impact on a national election that decides a national leadership. A few areas should not decide the government for the whole simply because they have high population clusters.

*Source\_ The Washington Post*
While James Wilson of Pennsylvania proposed the elector system, it was James Madison, known as the father of the Constitution, who noted that a system mediated through electors, rather than direct voting, would balance regional interests better as population grew and became more centralized. Indeed, James Mason argued that the people could not be trusted! With the electoral college the smaller states, particularly those in the South who wanted to protect slavery, were glad to see that New York and Philadelphia wouldn’t dominate national politics to the exclusion of the interests of the minority. They didn’t talk about slavery much though. As I said, it was the elephant in the room no one really wanted to address – the result being a violent split that took another seventy-three years to ignite.
The founding fathers argued all summer in 1787 and the result was a Constitution that today, 229 years later, is the **oldest, still-functioning Constitution in the world!** Not France, not Greece, not England, not Spain – no country in the world has a constitution in effect that’s older than ours. Amazing, huh?
A few possible reasons:
- It’s intentional ambiguity, which allows for interpretation as times change, although many strict constructionists may not consider that a good thing. However, when Secretary of the Treasury Alexander Hamilton wanted to create the first national bank in the Washington Administration, it was Thomas Jefferson (later the first Democrat) who opposed it because that power wasn’t granted to the president in the Constitution.
- The amendment process, which allows for changes in the Constitution, even with the high hurdles, that can originate from the people through their elected representatives.
- The willingness of our elected officials to recognize the Constitution as the supreme law. Many world leaders have chosen to ignore theirs in the past. Here, we’ve seen one President resign and, even in this most recent rancorous election, we’re seeing a smooth transition – maybe except in the media (they have to fill a lot of time) and in the streets, where many who demonstrate knowlittle about the process they hate so much.
If you’re interested in learning more about the Constitution, here are a couple of good books you might enjoy:
*The Summer of 1787*, David O. Stewart
*America’s Constitution*, Akhil Reed Amar
If you’re an American history lover like me, you’ll find both of these enjoyable holiday reading.
Maybe I should have saved this post for the 4th of July!
Enjoy!
Jim
Jim Lorenzen, CFP®, AIF®
The Independent Financial Group
A Registered Investment Advisor
805-265-5416
[https://indfin.com](https://indfin.com/)
If you’d like to Get Started with IFG, you can [begin here](https://indfin.com/getting-started/)!
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of The Independent Financial Group. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
**Tags:** electoral college, Thanksgiving
---
### [Retirement Income Knowledge Less Than Believed](https://indfin.com/retirementincomeknowledge/)
**Published:** March 10, 2019
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/09/Time_Is_Money.jpg)Jim Lorenzen, CFP®, AIF®**There’s seems to be a huge gap between perceived retirement income knowledge (how much people really know) and the knowledge people actually possess.
That appears to be the conclusion one can draw from the results of the American College’s National Retirement Income Survey. The survey used questions commonly used to gauge financial literacy and the results of the quiz were pretty poor. The mean retirement income literacy score was 47%… only 26% of older Americans passed the literacy quiz in 2017.
While only 12% of those with the lowest levels of wealth ($100,000 to $199,000) passed the quiz, the passing rate for those with $1.5 million or more in wealth was only 50%!
If you would like to take the American College’s Retirement Income Literacy Survey for yourself and read the full report on the national survey results, you can [do it here](https://retirement.theamericancollege.edu/research/2017-ricp-retirement-income-literacy-survey).
Enjoy!
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Estate, Family Issues, Life Insurance, Planning, Retirement
**Tags:** Financial planning, life insurance, Reducing Risk, term insurance, term insurance vs permanent
---
### [Should You Graduate From Mutual Funds?](https://indfin.com/mutual-funds/)
**Published:** December 10, 2018
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/01/Female_Mgr_Responsible_Concern.jpg)*iStock Images*
**Jim Lorenzen, CFP®, AIF®**
It’s probably a safe assumption that most individual investors began their investment programs with mutual funds and have built their 401(k)s, IRAs, and/or taxable accounts with mutual funds ever since.
While those mutual funds may have been appropriate for them in those early days, are they appropriate today?
If you’re one of those who’s built your retirement portfolio with mutual funds over the years and now have more than $500,000 invested in your long-term nest-egg, you may want to consider how much you may be losing to factors that have little to do with “the market”. It begins with the **Four Pillars of Investment Success.**
[](https://indfin.com/wp-content/uploads/2014/09/philosophy1.jpg)
For this post, we’ll talk about the bottom-left pillar, particularly as it relates to cost.
By now, most people are aware of the difference between ‘load’ and ‘no-load’ mutual funds. Loads are basically sales charges that pay compensation to the selling registered representative of a broker -dealer. They’re not necessarily bad. A small investor can seldom be economically serviced by a fee-based registered investment advisor and this economic model provides that investor access to help that otherwise may not be available. Either way, those charges aren’t hidden; they’re disclosed. Here are some additional charges worth discussing:
**Annual expense ratio**
This is also disclosed in a mutual fund’s prospectus. For example, assume a growth mutual fund has an expense ratio of 1.40%. You’ll find it disclosed; but here’s what that 1.4% doesn’t include:
**Turnover**.Turnover is an important factor in determining a fund’s true costs. You see, turnover impacts other costs, as you’ll soon see.
**Transaction/trading costs**:When a fund manager makes a trade on an exchange, that trade incurs a commission – just like *your own* trade would – and the fund manager receives a `confirm’ reflecting the net proceeds of the trade AFTER commissions have been taken… the same kind of ‘confirm’ you would receive. They report the NET proceeds *after* the cost of the trade.
Look on your most recent mutual fund statement – any fund. Do you see trading costs or any other fees or expenses disclosed on the statement… anywhere? You might think it’s all in the annual expense ratio; but think again. Transaction costs are NOT included in the fund’s annual expense ratio!
In the book, *Bogle on Mutual Funds*, the former Vanguard Fund chairman estimated trading costs generally average 0.6% I don’t know the real number, so for illustration, I’ll use his. If hypothetically a fund’s turnover is 120% – check the prospectus for your fund’s turnover – here’s what it means in calculating expenses:Trading Costs (use a low-end figure) x Turnover = Total trading costs. So, 0.6% x 2.2 = 1.32%.
Why use the 2.2 factor for a 120% turnover? Simple: You have to *establish* a position in a security before you can turn it over; and, that’s true for each security in the portfolio. The entire portfolio is established, then 120% is `turned over’ in a year. If you used 1.2, you’d be computing only a 20% turnover, far from what’s really happening. So, trading cost times turnover gives us 1.32% in trading costs, to add to the fund’s annual expense ratio to get combined annual expenses plus trading costs.
According to *Morningstar*, the typical equity fund has annual expenses of 1.4% annually. If we use that figure for illustration – remember to look at your own funds’ prospectuses to see what applies to you – 1.32% + 1.40% = 2.72% in annual costs.
**Market impact costs**: When you or I sell 100 shares of a security, it doesn’t really impact the price. But, when an institution buys or sells huge blocks of a security, the price can be affected. How much? Market impact costs can range between 0.15-0.25%. And, of course, you would apply that figure to turnover, too. We’ll use the lower number for our hypothetical illustration.0.15% x 2.2 = 0.33%. So our hypothetical fund with a 1.4% annual expense ratio that experiences a 120% annual turnover could actually be costing the shareholder 3.03% annually.
Annual Expense Ratio 1.40%
Turnover 2.2 x 0.6% 1.32%
Market Impact Costs 2.2 x 0.15% 0.33%
**Total** **3.05%**
This means, according to this calculation of our fictitious fund – the one we assumed had an annual expense ratio of 1.40% – the total real annual expenses to the shareholder are actually 3.05%, more than twice the annual expense ratio reflected in the prospectus; and those additional costs are nowhere to be found on the statement.
Okay, you now know what to look for. Pull out your statements and prospectuses and do your own math. You may have to make a guess for market impact and trading costs, or you can use Mr. Bogle’s – you probably won’t be far off.
Here’s another point worth remembering. Using our hypothetical fund example, if you’re paying 3% all-in for a $100,000 investment, you’re paying about $3,000 per year; but, the percentages don’t drop as your assets increase! If you have a $1 million dollar portfolio, you’re now paying $30,000 per year – and, that’s just for the fund!
As I said at the outset, if your portfolio is over $500,000, there’s probably a better way to get responsible management, a good investment allocation, and even professional guidance – all for less than you may be paying simply to be in mutual funds now.
You may want to check into it. Naturally, I’d be happy to help.
Jim
If you have $500,000 or more and are looking for an independent fiduciary advisor, you can [get started here](https://indfin.com/getting-started/).
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** Financial planning, life insurance, Reducing Risk, term insurance, term insurance vs permanent
---
### [Five Times When An Annuity Makes Sense](https://indfin.com/five-times-when-an-annuity-makes-sense/)
**Published:** May 27, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®My recent blog posts, as well as on this platform, discussed the advantages of arranging assets early – ten years or more before retirement – to lay the groundwork for an income-tax free retirement. Many experts believe it’s time to dump the stock-market-based approach in favor of an insured retirement solution – see ***[Time To Rethink the 401(k)](https://indfin.com/time-to-rethink-401k)*.**
Planning for an income tax-free retirement is very doable for many people, though not everyone, to be sure. I’ve even posted **[a recorded webinar](https://attendee.gotowebinar.com/recording/1183711495198713857)** on this subject (Note: It’s about an hour long; so get some coffee and get comfortable).
Then there’s the Obama administration’s Green Book, which I discussed last week, detailing budget and tax proposals for the coming year. It leaves little doubt, if there was ever any, that the government will be looking at all types of retirement vehicles (401(k)s, IRAs, Roth IRAs, etc.) – vehicles the government created, regulates, and is therefore in a position to write the rules. You can **[see that post here](https://indfin.com/are-you-a-target-in-the-green-book/).**
Of course, there are other insured solutions, designed to address the issue of longevity risk – we do seem to be living longer; and, some are worried that their money won’t last as long as they will.
Last week, Rich Lane of Magellan Financial outlined five reasons annuities can make sense, especially for financially conservative investors who want to build and protect their assets. He was talking about fixed annuities (which is good – I must admit I am not a great fan of variable annuities; but, that’s another story.
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a3fd41160b970b-320wi.jpg)Those who remember losing money back in the economic downturn are often interested in a vehicle that has a guaranteed minimum rate of return – something few alternatives offer; and that’s one of the reasons why the fixed annuities industry is seeing strong sales growth.
Fixed deferred annuities can provide a predictable future with flexible payout options that offer a guaranteed income stream, and those earnings aren’t taxed until the funds are withdrawn. In effect, they are treated as a source of income, just like a pension. So you can think of it as your own “pension” that you fund yourself.
A deferred indexed annuity – a fixed annuity with an interest crediting rate that’s linked to an outside market index of some type – can be “turned on” before or after retirement to create a liquid stream of income. When you think about it, how many investments do you know of – other than a fixed annuity – that can provide a predictable and guaranteed stream of income?
Banks? Maybe. But, during the Great Depression, banks across the country closed. Insurance companies thrived (risk management is their business). Bonds? Maybe. But, governments seem to habitually spend beyond their means and you face interest rate risk when it’s time to reinvest at maturity. Bond ladders can reduce this risk; but, few people in their second decade of retirement want to spend their time tracking the bond markets.
Here are Rich Lane’s five reasons an annuity might make sense for you:
1. **Safety:** Fixed annuities can ensure that if anything should happen to you, your surviving spouse has a source of continued income in place. This can help in case of a catastrophic illness or if there should ever be a need to enter a nursing home.
2. **Liquidity**: Today’s challenging economy has heightened interest in liquidity. Many hesitate to make long-term financial commitments without flexibility and access to funds – even if it means creating an income stream should they need it.
3. **Tax deferral**: The tax benefits of fixed annuities are important to many. Because earnings will not be taxed until withdrawals are made or regular distributions start, annuity owners can benefit from triple compounding: earning interest on principal, interest on interest, and interest on tax savings.
4. **Control:** Another appealing aspect of fixed annuities is the ability to choose a predictable income stream. Lifetime income options provide clients with the control of selecting payments that are guaranteed to continue for life.
5. **Wealth transfer:** Financially-conscious investors tend to be keenly focused on what happens to their money after they pass away. Annuities can bypass a lot of red-tape and provide greater control over outcomes.
It’s worth remembering that no investment, vehicle, or strategy will be right for everyone; and no investment or vehicle should be regarded as “the answer” to all your needs. Creating a retirement strategy is more like assembling a puzzle. There are always trade-offs. The key is not to get blinded by single issues; it’s really about finding the mix of solutions that create a master strategy for accomplishing your prioritized goals.
Do you know how much risk is embedded in your current investment and retirement portfolio? If you’d like to find out your risk number, you can begin[here](https://tinyurl.com/RiskNumber).
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
---
### [Here's Your Important Document Checklist!](https://indfin.com/document-checklist/)
**Published:** January 8, 2018
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/09/iStock_64047885_SMALL.jpg)Jim Lorenzen, CFP®, AIF®****A fiduciary advisor is good to have; but, YOU are a kind of fiduciary, too!**
Your family depends on you, which means you have the responsibilities a fiduciary would have. Step one, of course, is knowing where your important documents are.
Here’s a checklist to help you get your ducks lined up.
[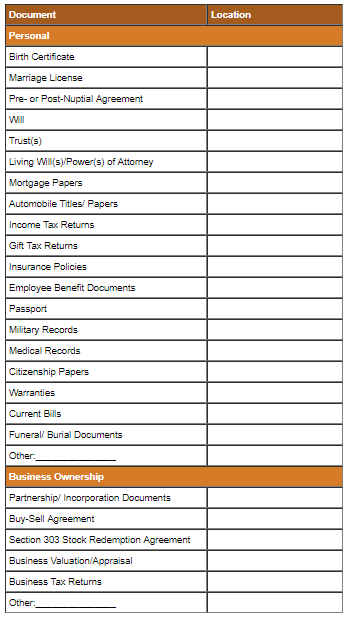](https://indfin.com/wp-content/uploads/2018/01/Document_Checklist.png)
Hope you find this helpful.
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Estate, Family Issues, Investing, Life Insurance, Planning, Retirement
**Tags:** Estate Planning, Financial planning, Reducing Risk
---
### [How Will Rising Interest Rates Affect Stocks?](https://indfin.com/risingratesandstocks/)
**Published:** March 5, 2018
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/09/iStock_62491112_XXXLARGE.jpg)*iStock Images*
**Jim Lorenzen, CFP®, AIF®**
… and what do rising interest rates (and inflation) mean to your long-term success?
Maybe less than you think… or is it maybe more than you think.
We don’t really know, do we? Planning isn’t about what we know; if it were, we’d all just go with our guts and get rich! Planning is about what we don’t know.
But we do have indicators. Past performance is no guarantee the future will repeat – we know that; but, maybe – just maybe – it can provide a little idea of how markets have reacted to rising interest rates in the past. Here’s a chart from Bloomberg; I apologize for the fuzziness.
As you can see (I hope) since March of 1971, there have been 21 periods of rising interest rates. Of those 21 periods, the S&P declined only 5 times and the largest decline was around 5.5%. Comforting? Well, good reading anyway.[](https://indfin.com/wp-content/uploads/2018/02/IFG_SP500_Duriing_Rate_Hikes.png)
The problem, of course, is we’re dealing with real money and real people’s lives.
It pays to have a ‘back-up’ in your financial plan that can help ensure there’s a ‘late life income’ even if everything else falls victim to the incompetency of elected officials who’ve become self-anointed economic experts.
For that reason, I thought you might enjoy a report I’ve put together about how to create a ‘late life income’ by adding another component to your investment diversification strategy.
I think you might enjoy it -it’s based on an actual case study. You can [access your Late Life Income report here](https://indfin.com/latelifeincome).
Enjoy!
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Life Insurance, Planning, Retirement
**Tags:** Financial planning, life insurance, Reducing Risk, term insurance, term insurance vs permanent
---
### [Interested in Charitable Giving? You May Want a Wealth Replacement Trust!](https://indfin.com/wealthreplacementtrust/)
**Published:** March 19, 2018
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2016/11/Solution-Puzzle-Piece-2.png)Jim Lorenzen, CFP®, AIF®**Charitable giving is a way you can truly leave a legacy beyond our own family; However, believe it or not, few among what many would call the ‘mass affluent’ ever give much thought to charitable giving. Often, they simply feel they don’t have enough money; however, many of these same people are often sitting on highly appreciated assets such as real estate.
What many fail to realize is there can be significant tax advantages in charitable giving. When money is tied up in real estate and securities, having a tax-advantaged exit strategy can be helpful.
If you were to sell an appreciated asset, the gain would be subject to capital gains tax. By donating the appreciated asset to a charity, however, you can receive an income tax deduction equal to the fair market value of the asset and pay no capital gains tax on the increased value.
Example: Alfred purchased $25,000 of publicly-traded stock several years ago. That stock is now worth $100,000. If he sells the stock, he must pay capital gains tax on the $75,000 gain. But, Alfred can donate the stock to a qualified charity and, in turn, receive a $100,000 charitable income tax deduction. When the charity then sells the stock, no capital gains tax is due on the appreciation. How good is that?
But what happens to Alfred’s family who will be deprived of those assets that they might otherwise have received.
A popular solution: Life Insurance. Why is this popular? How do you do it? Read on…
In order to replace the value of the assets transferred to a charity, the donor establishes a second trust – an irrevocable life insurance trust (ILIT) – and the trustee acquires life insurance on the donor’s life in an amount equal to the value of the charitable gift.
Premium payments can come from the charitable deduction income tax savings and any annual cash flow from a charitable trust or charitable gift annuity. Alfred simply makes gifts to the irrevocable life insurance trust that are then used to pay the life insurance policy premiums. At Alfred’s death, the life insurance proceeds generally pass to the donor’s heirs free of income tax and estate tax, replacing the value of the assets that were given to the charity.
Not a bad deal!
Life Insurance has a number of uses; but, before shopping, it pays to know what you’re actually shopping for! To help understand life insurance design, you need to understand your priorities. You might find this simple tool helpful.
[What’s Your Focus Life Insurance Priorities Tool](https://indfin.lpages.co/leadbox/146504373f72a2%3A12a1899aa346dc/5742351410528256/)
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Life Insurance, Planning, Retirement
**Tags:** Financial planning, life insurance, Reducing Risk, term insurance, term insurance vs permanent
---
### [How to Turn a $350,000 IRA into $600,000 for Your Heirs!](https://indfin.com/rmdsforheirs/)
**Published:** April 2, 2018
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2017/10/Older-man-with-cash_gettyimages.jpg)*Getty Images*
**Jim Lorenzen, CFP®, AIF®**
**IRS mandated withdrawals from retirement accounts – required minimum distributions (RMDs) – must begin by April following the year people turn 70-1/2.**
But, if you wait until the year following that birthday, you will be required to take a double-distribution that year – two RMDs (be sure to talk to your tax-advisor). Here’s an RMD strategy you might like!
Many people, however don’t need their RMDs and don’t want them – they have to pay taxes on the distributions. They simply plan to pass the money on to their kids or grand kids.
Fred and Wilma have been retired in Bedrock for some time now. He’s 69 years old and has $350,000 in an IRA he plans to leave to his children, Pebbles and Bam-Bam.
The problem, of course – as usual, is Uncle Sam. Uncle Sam will force Fred to begin taking money from his IRA in the form of Required Minimum Distributions (RMDs).
Because they both have pensions and other sources of income, this is money they never intended to spend or use. What’s more, because the IRS uses a ‘withdrawal factor’ that changes as they age, the RMDs are calculated to deplete his IRA, thus guaranteeing the government they’ll get their cut, by the end of his life expectancy.
**To summarize:**Fred gets older, the IRA money is distributed by force, and the longer he lives, the greater the chances there will be little, if any, IRA left for the kids or grand kids.
[](https://indfin.com/wp-content/uploads/2016/11/Tax-Burden-Scale.png)The government is going to get their money – I guess we can all let that go – the only question is when, but that’s another story. The fact is, if Fred’s in the 28% tax bracket, only 72% of the money he sees on his statement is actually his. Uncle Sam is a 28% partner for the rest, unless he decides to change his percentage.
Fred could invest the after-tax withdrawal money and the kids could take advantage of the “stretch” option for the IRA, which requires non-spouse beneficiaries to take distributions over the course of the person’s life expectancy, keeping the money for the kids working for a longer period of time. Of course, as noted, there may not be much left if he’s in good health and lives a long life.
**[](https://indfin.com/wp-content/uploads/2017/05/Coffee_with_RMD_Pencil.png)The RMD**
The IRS withdrawal factor for Fred at his age is 27.4 (you can find yours on the[IRS website](https://www.irs.gov/retirement-plans/plan-participant-employee/required-minimum-distribution-worksheets)).
This means his first year RMD will be $12,773 and, of course, he’ll have to pay income taxes. At his 28% tax bracket, that would leave him with $9,196 after taxes on his first RMD.
If he invested that $9,196 every year and earned 5%, he’d have $217,554 for his children and grandchildren if he passed away at age 85. If he passed away at age 90, he’d leave $328,474 to his heirs, plus whatever pretax dollars might be left in the IRA – a balance that will likely be declining each year because the IRS withdrawal factor is based on life expectancy and computed on the balance of all IRAs a the end of the previous year.
**[](https://indfin.com/wp-content/uploads/2017/04/DiversificationPuzzle.png)There might be a better option**\[1\].
Fred’s in good health. Since he doesn’t need the money, he decides to pursue a little more sophisticated strategy.
He decides to leave the IRA where it is and use the required minimum distributions to purchase a permanent life insurance policy (since Fred can’t predict his date of death, his outliving a term policy would mean all the premiums he had paid would be lost forever with nothing to show for them).
For our example, we’ll use a no-lapse guaranteed individual universal life policy. We’ll also assume the same numbers cited above and a 28% tax bracket.
Since Fred’s a non-smoker and in good health, his $12,773 RMD, after his 28% income tax payment, means he might leverage his $9,196 after-tax withdrawal into an immediate $334,936 death benefit, which generally would pass tax-free to his heirs.\[2\]
The IRA money will still have embedded taxes, of course, and the amount of death benefit this annual premium might buy will vary by company, policy, and design. For illustration, though, this is close enough to make the point.
As you can see from our table\[3\], when added to the remaining after-tax IRA assets, the net total to the beneficiaries can be substantial, regardless of when it happens. I’ve highlighted two ages (85 and 95) to show what that $350.000 IRA could really mean if the RMDs are used for this strategy and Fred’s death should occur at those ages.
**End of****Tax-Free****End of Year****Less Tax on****Net IRA Value****Total Value****Year****Age****Life Ins. Benefit****IRA Value4****Beneficiaries (30%)****to Beneficiaries****To Beneficiaries**574$334,936$387,852$116,356$271,496$606,4321079$334,936$392,978$117,893$275,085$610,021**16****85****$334,936****$369,468****$110,840****$258,628****$593,564**2190$334,936$318,786$95,636$223,150$558,086**26****95****$334,936****$241,227****$72,368****$168,859****$503,795**All of this, of course, depends on Fred’s qualifying for a permanent policy. Since Fred isn’t dealing with any ‘high risk’ conditions, he should have no issues getting approved.
Not a bad strategy for the use of $9,196 he otherwise didn’t need during a time he’d be drawing down on his $350,000 IRA.
This was a generic hypothetical. In reality, RMDs do not remain constant; so, having a strategy properly designed can make a significant difference in outcomes.
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Life Insurance, Planning, Retirement
**Tags:** Financial planning, life insurance, Reducing Risk, term insurance, term insurance vs permanent
---
### [Your Cash Value Life Insurance Has Value!](https://indfin.com/cashvalue/)
**Published:** April 16, 2018
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2017/10/Older-man-with-cash_gettyimages.jpg)*Getty Images*
**Jim Lorenzen, CFP®, AIF®**
People often purchase cash value permanent insurance, throw the policy in a drawer or filing cabinet, and forget about it. This could be a big mistake.
Most all permanent insurance has a cash value and that cash value has real value you shouldn’t ignore! First a quick word about what permanent insurance is.
**Term vs Permanent**
The terms themselves should tell you something. Term insurance is simple: You’re renting death benefit protection from an insurance company. It’s like a lease, in a way. You’re premiums stay level until the end of the lease. You can renew your lease, but the rent will be higher. How high depends on the length of the initial lease. If you’re 40 years of age, and in good health, the purchase of a 20-year term policy means the ‘lease’ will be up when you’re age 60. If you no longer need the death benefit, you simply let the policy expire. If you do, you’ll either have to renew at what will likely be a much higher rate or buy a new policy, which means re-qualifying health-wise. You might be able to convert to a permanent policy with the same company if your term policy offers that feature, but you’d still be paying the higher premiums.
Permanent insurance isn’t a rental. This is a purchase on a sort-of installment plan. Examples are whole life, universal life, and many other iterations that are now available. In most policies, premiums do not increase and your protection doesn’t go away unless you fail to maintain the policy. These policies have cash value and that brings us back to our topic.
**Cash Value has Value!**
Someone will end-up with the policy holder’s cash value:
A)The policy holder
B)The policy holder’s beneficiaries
C)The insurance company
If the policy holder dies before accessing cash value, the answer is C! The insurance company pays out the death benefit but will keep the cash value.
What can you do to make sure you make the most of your cash value? Here are some simple strategies you might consider:
1. **Use your cash value to make premium payments**
Why not use your cash value for premium payments to keep ‘paid-up’? You’ll not only save money each year, but maintains your death benefit protection.
2. **Increase your death benefit**Use your cash value to purchase a larger death benefit! Life insurance death benefits generally go to beneficiaries income tax-free! If you have a $500,000 insurance policy with $250,000 in cash value, you might want to take your cash value to zero and increase your heirs death benefit to $750,000. Better that than your heirs getting $500,000 and the insurance company taking $250,000 (which means they had only $250,000 ‘at risk’).
3. **Take a loan**You can borrow against your policy’s cash value at rates lower than your typical bank loan. In some cases, the net loan interest rate might be close to zero (the cost of the loan could be close or equal to the policy’s interest crediting rate). Here’s the good part: You’re not obligated to pay back the loan since, in effect, you’re borrowing your own money (you should know that any amount you borrow, plus interest, will be deducted from the death benefit when you die). Here’s a smart strategy many people use: They borrow money from policy cash values to pay cash for their new car, the make ‘car payments’ back to the policy. The money they borrow is tax free. And, in many policies, the money they took out to buy the car is still ‘on the books’ in their policy for interest crediting. Every five years or so, they buy a new car almost interest free.
4. **Withdraw the money**You can withdraw your cash value–which could reduce or eliminate your death benefit. Don’t do this without checking with your agent. Calculations may not be dollar-for-dollar.
5. **Surrender the policy**No more death protection, however.
6. **Supplement retirement income**This is a 10-15 year strategy that can provide excellent benefits and protections. Talk to your advisor–preferably someone who is independent of the companies and a CFP*®* professional. Now, if we only knew where we could find one…..
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues, Life Insurance, Planning, Retirement
**Tags:** Financial planning, life insurance, Reducing Risk, term insurance, term insurance vs permanent
---
### [Here's Your 10-Point Financial Discussion Checklist!](https://indfin.com/10pointchecklist/)
**Published:** January 13, 2019
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2017/05/Coffee_with_RMD_Pencil.png)Jim Lorenzen, CFP®, AIF®**How does your financial future look? Your chances for financial freedom will depend on how well you’ve covered your bases!
Here’s a checklist for your kitchen table discussions:
1. **When do you plan to retire?** Your retirement age will impact how many years of spending your retirement assets will have to cover. It will also likely affect just how much you may spend each year.
2. **What are your retirement goals?** Get them down in writing and sort them by needs, wants, and wishes – the prioritize each goal and put a dollar amount on each of them. For those that are recurring, you’ll not only need to put a dollar amount on each event, but you’ll need to adjust for inflation, as well (car purchases are an example).
3. **When do you plan to file for and start Social Security payments?** How will this affect your tax picture when combined with other sources of income from retirement plans, etc.
4. **How will you design your investment portfolio to provide both income and inflation protection while mitigating downside risk?**
5. **Will you need to reduce living expenses?** If so, where can you cut? Not everyone will need to, but running out of money in your old age wouldn’t be a happy picture either.
6. **Should you get a reverse mortgage?** Does it really provide the security the commercials talk about or is it just a band-aid?
7. **Have you provided for the possible need for long-term care?** Long-term care policies are available, however many are concerned about not using the benefits after paying out high premiums for years. Some policies also have many restrictions. It’s worth reviewing the fine print.
8. **How will you protect yourself against financial fraud?** This can take many forms, from cyber threats to the Bernie Madoffs of the world.
9. **How can your spouse and children be protected** when the main breadwinner is gone?
10. **Is creating a financial legacy important to you?** This can be accomplished for children and grandchildren, but they’re not the only ones. Some people think giving is only for the rich; but affluent people often wish to do it, too.
Hope you find this helpful!
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Estate, Family Issues, Inflation, Investing, Planning, Retirement
**Tags:** Financial planning, life insurance, Reducing Risk, term insurance, term insurance vs permanent
---
### [Are You Managing Money? Maybe you should be managing risk.](https://indfin.com/managing-risk/)
**Published:** January 28, 2019
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b0192ac851ba2970d-320wi.jpg)Jim Lorenzen, CFP®, AIF®**Markets are sensitive to risk. We know that. According to analysts at Lockwood Advisors, only 8% of global economies are now growing above recent averages; but, the U.S. is still the best; the G10 countries are the worst. Headwinds do include politics: Many market insiders are worried about a reversal of tax cuts and the anti-business stance of many incoming members of Congress.
Just like back in 1950 (remember?) the U.S. economy has been growing above recent potential, propelled by the growth spurt from major corporate and personal tax cuts; however these cuts just might have staying power since they’re not based on wealth redistribution. The real headwinds just may be coming from two economic realities: Demographics and the large U.S. government debt.
The aging population, increasing the percentage of the population in the decumulation stage, may apply downward pressure on growth for decades. The Administration on Aging estimates that the population age 60 or older will increase by 21% between 2010 and 2020 and by 39% between 2010 and 2050.
Most people, it’s safe to say, think of future market returns using a frame of reference based on the past. Indeed, most advisors – I’m guilty too – continually put-up mountain charts to show clients what’s happened before even as we tell them it’s no guarantee it will happen again. But, the baby-boomers who remember the 1950s and 1960s – and especially the go-go 1990s – should be reminded the current is no longer flowing in the same direction. Defensive allocations just might be the best defense going forward.
Hope you find this helpful!
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Estate, Family Issues, Inflation, Investing, Planning, Retirement
**Tags:** Financial planning, life insurance, Reducing Risk, term insurance, term insurance vs permanent
---
### [Three Quick Tips for Building Family Wealth](https://indfin.com/buildingfamilywealthtips/)
**Published:** February 10, 2019
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2017/10/Older-man-with-cash_gettyimages.jpg)*Getty Images*
**Jim Lorenzen, CFP®, AIF®**
Here are three quick tips you might find helpful:
**Choose your beneficiaries wisely when allocating inheritance money.** Leave tax-deferred accounts (IRAs and non-qualified annuities, for example) to younger family members. They’re likely in a lower tax bracket and have longer life expectancies for taking the required minimum distributions, which means the distributions will be smaller, as well. Highly appreciated assets are best left to beneficiaries in higher tax brackets as long as the cost-basis can be stepped up to the current price levels. This means wealthier recipients can sell the asset with little or no tax consequences. The high-income beneficiaries would most benefit from the tax-free benefits from life insurance policies. Talk with your advisors.
**Don’t be too eager to drop older life insurance policies.** Some may wonder why keep the policy if they no longer need it. Those older policies may be paying an attractive interest rate, which is accumulating tax-deferred. Secondly, those small premiums may well be worth the much larger tax-free payoff down the road. How to tell? Start by dividing the premium into the death benefit. Got the answer? If you think you’ll pass away before that number (in years), you probably should keep paying.
**Convert Grandpa’s IRA to a Roth IRA**. When grandpa passes away, his IRA assets will likely be passed down to children and grandchildren, which means they’ll have to begin taking taxable required minimum distributions (RMDs) – which means they’ll probably be taxed at a higher rate than grandpa would have paid on his own withdrawals. If grandpa converted some or all of his traditional IRAs to Roth IRAs while alive, this problem wouldn’t happen. Smart kids might want to encourage this and even offer to pay the tax bill on the conversion now!
Hope you find this helpful!
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Estate, Family Issues, Life Insurance, Planning, Retirement
**Tags:** Financial planning, life insurance, Reducing Risk, term insurance, term insurance vs permanent
---
### [Don't Make These IRA Mistakes!](https://indfin.com/iramistakes/)
**Published:** February 24, 2019
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5118d6207970c-320wi1.jpg)*Shutterbug*
**Jim Lorenzen, CFP®, AIF®**
Have you reviewed your beneficiary forms lately? You should. IRA mistakes there can’t be fixed after the IRA or plan owner dies.
The two biggest problem areas most prone to beneficiary form: Divorce and trusts. Problems often arise when someone erroneously believes that a trust takes care of naming the beneficiary for IRAs. It doesn’t.
When someone names a trust in a will as the IRA beneficiary, a problem can arise when a new will is prepared with no trust named. Most new wills revoke the old ones – so the trust under the first will no longer exists as a beneficiary leaving no named beneficiary.
Other problems arise when a trust is created to inherit an IRA but never named on the IRA beneficiary form. The trust must be named on the IRA beneficiary form; and if a new trust is created to inherit the IRA, the IRA beneficiary form must be updated again.
Make sure your IRA beneficiary forms name the correct beneficiary – and contingent beneficiaries. And, if the trust is named, make sure it’s still accurate.
If you want to learn more about IRAs, I’m never hesitant to recommend Ed Slott’s books and DVDs. He’s one of a very minute number of ‘gurus’ (you’ll often find him on PBS) who is actually the ‘real deal’ (he’s also a CPA) when it comes to dispensing well-researched retirement and taxation knowledge.
Hope you find this helpful!
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Estate, Family Issues, Life Insurance, Planning, Retirement
**Tags:** Financial planning, life insurance, Reducing Risk, term insurance, term insurance vs permanent
---
### [Interesting Financial Statistics You May Not Know](https://indfin.com/financial-statistics/)
**Published:** March 21, 2019
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/07/Fotolia_5090081-DB-ForkInRoad.jpg)*Fotilla Images*
**Jim Lorenzen, CFP®, AIF®**
I came across some interesting stats in the most recent Journal of Financial Planning; I thought you might find a few of them interesting – I know I do.
A recent survey revealed that 65% of respondents said they mistrust the financial services industry. Only 2% said they trusted financial professionals “a lot”. Yet, 58% of those with 401(k) plans said they wanted help choosing investments.
93% of Americans think that advisors who provide retirement advice should put their clients’ interests first. 53% mistakenly believe that all financial advisors are required to do so. Only 21%, however, understand the difference between a planner who is a fiduciary and one who is not. Maybe this is what leads to the gap in trust. 50% of investors who work with a financial planner say they know for certain their advisor is a fiduciary.
It appears both investor education and advisor trust need to be improved.
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement
**Tags:** Financial planning, life insurance, Reducing Risk, term insurance, term insurance vs permanent
---
### [Retirement Withdrawal Strategy May Need a New Twist!](https://indfin.com/retirementwithdrawalstrategy/)
**Published:** April 7, 2019
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2016/11/Tax-Burden-Scale.png)Jim Lorenzen, CFP®, AIF®**The right retirement withdrawal strategy shouldn’t follow conventional wisdom blindly. What’s right for you might be very different.
Conventional wisdom says retirees should withdraw funds from taxable accounts first, tax-deferred accounts (IRAs, 401(k)s, etc.) second, and tax-free money (Roth IRAs for example) last.
But, should you do it that way?
The current tax laws aren’t permanent. These current low rates some taxpayers enjoy may not last forever. Maybe it might make sense to withdraw money from tax-deferred accounts during years when you can take full advantage of these low marginal rates.
Another idea: Convert funds from tax-deferred accounts to a Roth IRA to take full advantage of the 15% tax bracket (be sure to pay the taxes from other taxable money); or, you may want to reserve funds in a tax-deferred account to accommodate the possibility of large tax-deductible expenses, such as medical costs which can occur later in life.
These are ideas only. Your situation is unique. Don’t do anything without talking to your team: You financial, legal, and tax advisors can help you craft the strategy that’s right for you.
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement, Taxes
**Tags:** Financial planning, life insurance, Reducing Risk, term insurance, term insurance vs permanent
---
### [Ageing Issues Make Financial Planning More Important than Ever!](https://indfin.com/planningforageing/)
**Published:** April 21, 2019
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/10/20150419_094423.jpg)**Jim Lorenzen, CFP®, AIF®**
When I was a kid, no one I knew had Alzheimer’s. Heck, no one my parents knew had it. In fact, I don’t think anyone even knew what it was!
There may have been a few special-needs children around, but I never saw one in either elementary or high school. Attention deficit disorder (A.D.D.)? Never heard the term.
What a difference a generation of changes make: changes in health care advances as well as in people’s lifestyles. People are living longer – that’s a good thing; but new challenges face us all.
According to the Alzheimer’s Association, Alzheimer’s is now the 6th leading cause of death in the U.S. Between 2000 and 2016, deaths from heart disease actually declined by 11%; but deaths from Alzheimer’s increased 123%!
5.7 million Americans are living with Alzheimer’s today. One in three seniors dies with Alzheimer’s or another form of dementia. 16.1 million Americans are providing 18.4 billion hours of unpaid care for loved ones suffering from Alzheimer’s and dementia. It’s not covered by Medicare, and all those politicians who want to “reform” health care are amazingly silent about solving this problem.
Virtually every family I know has been touched by Alzheimer’s (including my own) or special needs issues affecting children or grandchildren (again, including my own).
Many ‘baby-boomer’s’ have become known as the ‘sandwich’ generation – taking care of both parents and children or even grandchildren, due to the combination of increased longevity coupled with these new medical challenges families are facing.
It’s never been more important to have a long-term multi-generational financial plan in-place. Many parents, for example, don’t realize that may have created plans for their special-needs child’s financial security that will actually disqualify the child’s eligibility for government benefits in the future… and that their plan needs to preserve that eligibility while seeing that the child will be secure all the way through the child’s own retirement. Who pays the rent and utilities when the child is older and the parents are gone? Where does the child live? Who pays the rent or mortgage.. or property and other taxes? How about transportation – for life?
Indeed, the challenges today are greater than ever before because the issues are different. When should a person begin planning? Now. It doesn’t matter your age. Do it now.
It’s not about being an investment guru; it’s about having a strategy tied to a plan – and arranging assets to accomplish long-term objectives.
Do it now. Okay, I’ll shut up.
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues, Life Insurance, Planning, Retirement, Taxes
**Tags:** Financial planning, life insurance, Reducing Risk, term insurance, term insurance vs permanent
---
### [Are All Financial Advisors "True" Fiduciaries?](https://indfin.com/fiduciaryadvisor/)
**Published:** April 29, 2019
**Author:** Jim Lorenzen
**Excerpt:** Not everyone is a true fiduciary. See what a search firm that specializes in this area has to say.
**Content:**
**Jim Lorenzen, CFP®, AIF®**The short answer is ‘no’. Mark Tibergien, CEO of Pershing Advisor Solutions, is quoted in this month’s issue of *Wealth Management*saying, “When we look at those who are breaking away \[from traditional brokerages\] and forming their own firms, we recognize that they are making a fundamental change from being an employee to being a business owner, from being a broker to being a fiduciary advisor and from being a product advocate to being a client advocate.”
According to the article, written by Mindy Diamond, president of Diamond Consultants, a nationally-recognized boutique search and consulting firm in Morristown, N.J. specializing in the financial services industry, here are just a few of the things she mentions to look for:
1. Ability to serve the client first. Captive advisors, she says, essentially serve as product advocates for the firm and are limited to the products and platforms approved by their firms. Independent advisors, on the other hand, serve as client advocates with access to the whole of the market – the ability to ‘shop the street’ for products and solutions that best serve the client.
2. Higher level of transparency. At an independent firm, safe asset custody is separate from the advisor’s business and product manufacturing, creating a process of checks and balances.
3. A clearer payment structure. Unlike the wirehouses, independent advisors aren’t paid according to a grid – a performance measurement based on selling ability and not meeting the client’s needs. Higher production levels result in a higher percentage commission payout from the firm to the advisor. Independent advisors are business owners with fully disclosed compensation that’s easy to understand.
4. Ability to select the technology and services that best suit their clients – not what the ‘house’ provides.
It’s worth noting that independent registered investment advisors (RIAs) have legal fiduciary status automatically. This may not be true in all instances when the advisor is considered an RIA representative only for the planning stage but reverts to registered representative (RR) status for product selection and implementation.
It pays to know who you’re dealing with.
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, Reducing Risk
---
### [College or Retirement: Does a 529 Plan Make Sense?](https://indfin.com/fiduciaryadvisor-2/)
**Published:** May 20, 2019
**Author:** Jim Lorenzen
**Excerpt:** Not everyone is a true fiduciary. See what a search firm that specializes in this area has to say.
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/09/Piggy_Bank_on_Side.png)Maybe there’s a better way to accomplish both!****Jim Lorenzen, CFP®, AIF®**
Can’t afford to save for retirement because you need to accumulate money for your kids’ college expenses? Sound familiar?
Most parents are willing to put their kids’ education ahead of their own retirement needs, according to a T. Rowe Price survey. In fact, their research says it’s true of 74% of parents – all willing to prioritize college saving over their own retirement needs.
But, is that the smart thing to do?
529 plans tend to be the primary college savings vehicle, but parents could be, and often are, jeopardizing their own financial security. 529 plan do offer tax breaks for their depositors; but those tend to be low dollar amounts and then often limited to only state income taxes. A 401(k) or IRA can cut their federal taxes up to 40% for every dollar they deposit! – And, it’s even more if the parent’s employer is matching contributions! This isn’t rocket science.
As for investment choices, 401(k) and IRA menus still tend to offer greater flexibility and access to thousands of mutual funds, ETFs, even individual stocks, bonds, and certificates of deposit.
**The Liquidity Issue**
While 529 plan assets can be withdrawn at any time, if it turns out you have no qualified higher education expenses to match the withdrawal amount, the earnings can be taxable income – and there could be an additional 10% penalty on the income portion.
There are, however, ways to tap retirement accounts with minimal impact from taxes, costs, or penalties: You might be able to borrow from your retirement plan at work – maybe with no application and at low interest rates – and Roth IRAs allow withdrawals of contributions at any time for any reason with no taxes or penalties. Earnings can be withdrawn after age 59-1/2 without taxes or penalties, as well. Note: Those under age 59-1/2 will be taxed on the earnings portion of a Roth IRA, or any part of a traditional IRA, as regular income. However, a pre-59-1/2 IRA or Roth IRA owner may avoid the 10% penalty if the money is used for qualified higher education expenses.
Caution: It’s worth noting that any distribution from a parent’s retirement account may be counted as income when calculating subsequent years’ financial aid and may reduce any needs-based benefits.
Speaking of needs-based awards and benefits, while no more than 5.64% of 529 plan account value will be considered each year before any needs-based money is awarded, retirement account assets usually aren’t counted at all!
Retirement should be your number one priority. Structured properly, retirement funds can be arranged to provide solutions for multiple objectives and minimize Uncle Sam’s dip into your wallet, as well.
---
Subscribe to the IFG Ezine! [ Just click here!](https://visitor.r20.constantcontact.com/manage/optin?v=001MsaghC2nU2NJckb8N0hCVabs7r2JGtIT)
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, Reducing Risk
---
### [Alternative Investments ("alts") and The Flight to Safety - Part II](https://indfin.com/fiduciaryadvisor-2-2-2/)
**Published:** June 15, 2019
**Author:** Jim Lorenzen
**Excerpt:** The financial planning profession has changed dramatically since I opened my first office in 1991; but, the financial services industry – not to be confused with the profession that operates alongside it – seems to have changed little, though it’s changed a lot. What? I’ll explain.
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5118d6207970c-320wi.jpg)Jim Lorenzen, CFP®, AIF®**In [my last post](https://indfin.com/?p=3221), a talked about how the financial planning profession has changed dramatically since I opened my first office in 1991; but, the financial services industry – not to be confused with the profession that operates alongside it – seems to have changed little, though it’s changed a lot.
I talked about how the financial product manufacturing, marketing, and sales channels represent an industry that exists alongside – not necessarily a part of – the financial planning profession. It doesn’t help, of course, that anyone can call themselves a financial planner – but I digress.
Alternative investments (alts) represent one example, which I discussed in the last post. Another alternative investment is deferred annuities.
People love guarantees. Marketers know this and the use of the word virtually always gets investors’ attention – particularly those who’ve amassed significant assets and are contemplating retirement.
The media – always on the alert for something they can hype or bash for ratings and typically lazy – find it easy to highlight high costs and shady salespeople. And, there’s some truth to that. Guaranteed income or withdrawal riders and equity indexed annuities do tend to have high costs. Often the guarantees that are less attractive than those presented.
The cost-benefit argument could, and probably will, go on forever. I have other issues. The first is, does an annuity make sense at all? – Any annuity. There’s no tax-deferral benefit if used inside an IRA and it limits your investment choices. They also often have surrender charges that enter into future decision-making; but, even when there are no surrender charges, the withdrawals can harm performance or even undermine the guarantees that were the focus of the sale.
For me, here’s the big issue: the annuity creates something most of my clients no longer want any more of – deferred income (who know what future tax rates will look like in 10-15 years as government deficits climb? Deferred income comes out first and is taxed at ordinary income tax rates.
Deferred income in non-qualified annuities (outside IRAs, etc., funded with normally taxable money) is income in respect of a decedent (IRD) and does not get a step-up in cost basis at the death of the holder – someone will pay taxes on the earnings and they may be in a higher tax bracket or the IRD may put them there.
There may be other ways to invest using alternative strategies. Options can work, but they also carry additional costs and risk.
Talk to your advisor – a real one would be a good idea – to see what your plan should be.
Jim
---
Subscribe to the IFG Ezine
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, Reducing Risk
---
### [Alternative Investments ("alts") and The Flight to Safety.](https://indfin.com/fiduciaryadvisor-2-2/)
**Published:** June 1, 2019
**Author:** Jim Lorenzen
**Excerpt:** The financial planning profession has changed dramatically since I opened my first office in 1991; but, the financial services industry – not to be confused with the profession that operates alongside it – seems to have changed little, though it’s changed a lot. What? I’ll explain.
**Content:**
[](https://indfin.com/wp-content/uploads/2014/09/iStock_62491112_XXXLARGE.jpg)iStock Images
**The more things change, the more they stay the same.**
**Jim Lorenzen, CFP®, AIF®**
The financial planning profession has changed dramatically since I opened my first office in 1991; but, the financial services industry – not to be confused with the profession that operates alongside it – seems to have changed little, though it’s changed a lot. What? I’ll explain.
The industry, comprised largely of product manufacturers and their sales arms (these days it seems anyone can say their a ‘financial advisor’), has a long track-record of constantly packaging new products to take advantage of a demand among investors that the product manufacturers create through their marketing. New ‘issues’ (created by marketing) give rise to new products to be sold to fill a marketing-driven demand. Changes in product innovation to generate new sales is the constant that never changes.
This doesn’t mean it’s all bad; it’s just that it can be difficult for spectators to recognize the game without a program.
Alternative investments get a lot of press these days – especially if there’s a perceived risk of a down or bear market… a perception that’s convenient to exploit at almost any point in time. The media likes ratings, so profiling people that called a market top or decline – and made money – is always good for attracting an audience. And, since there’s always someone on each side of a trade, finding someone on the right side isn’t difficult.
I’ve always felt that many fund managers operate like baseball free agents. Being on the right side of a call gets them on tv, which in turn attracts new assets, which in turn leads to bigger year-end bonuses. I could be wrong, or not.
Many captive “advisors” are putting their clients into “alts” these days because their employer firms (the distribution arm for the product manufacturer) are emphasizing them.
My sales pitch for alternatives: With alternatives, you can have higher costs, greater dependency on a fund manager’s clairvoyance, less transparency, low tax-efficiency, and limited access to your money! What do you think?
Don’t get me wrong. It’s not a black and white decision. They can have a place in a well-designed portfolio; and, while many endowment funds and the ultra-wealthy do tend to own alts, most of us aren’t among the ultra-wealthy and risk mitigation is important.
What can you do? What should you consider instead? Well of course that depends on your situation – everyone’s different. But, I’ll have a few thoughts you can chew on – and discuss with your advisor – in my next post.
Jim
---
Subscribe to the IFG Ezine! [ Just click here!](https://visitor.r20.constantcontact.com/manage/optin?v=001MsaghC2nU2NJckb8N0hCVabs7r2JGtIT)
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, Reducing Risk
---
### [Withdrawal Tax-Traps You Want to Avoid!](https://indfin.com/fiduciaryadvisor-2-2-2-2/)
**Published:** June 28, 2019
**Author:** Jim Lorenzen
**Excerpt:** The financial planning profession has changed dramatically since I opened my first office in 1991; but, the financial services industry – not to be confused with the profession that operates alongside it – seems to have changed little, though it’s changed a lot. What? I’ll explain.
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019b00066606970c-320wi.jpg)*iStock Images*
**Jim Lorenzen, CFP®, AIF®**
**News Flash: Baby boomers are getting older**! (film at 11). As if they didn’t have enough to worry about (i.e., parents coming home to live with them, children that can’t seem to leave home, wondering it their money will last through retirement, and an outlook that screams for increased health care costs and taxes), what if there’s an emergency that forces an early withdrawal from a retirement account? What happens if it occurs before age 59-1/2 and the IRS levies a 10% tax penalty on top of the income tax?
Not a happy situation. Someone in a 25% tax bracket who needs $10,000 will have to withdraw $13,333 plus money to cover the penalty…
… unless there’s an exception.
For example, an employee over age 50 who withdraw money from company plans after separating from service can withdraw money from his/her plan without paying the penalty – but, as highly-regarded retirement guru Ed Slott reminds us[\[1\]](#_ftn1) it’s important to know that not every exception applies to every type of plan. Some exceptions apply to company plans alright, but not all. Some apply to IRAs, but not all. Some apply to both.
Is your head spinning yet? Mr. Slott says he sees the biggest errors with first-time home buyers and people in higher education – situations where the exceptions apply only to IRAs and never to company plans. In one case a school teacher withdrew over $67,000 from her 403(b) for college education expenses only to find out (in tax court) she had to pay the 10% IRS penalty.
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01910219a734970c-320wi.jpg)*iStock Images*Here’s another from the Slott files: A Big-10 accounting firm accountant lost in tax court when he found he had to pay the 10% penalty on top of the taxes for the $30,000+ distribution he took from his 401(k) to begin his Ph.D. studies. Here’s a real shocker: Even a person who has negative income for the year and is able to withdraw funds from an IRA tax-free even after the distribution income is factored-in, will still have to pay the 10% penalty – yes, even if there’s no income tax! This one lost in tax court and again on appeal. The 10% penalty is completely independent of the level of income for the year.
Medical expenses are another possible trap, according to Mr. Slott. In one case, someone withdrew a little over $17,000 from her qualified play to pay for medical treatments that began in the same year. Payment for the treatments, however, was made the following year. The IRS assessed a 10% penalty, a little over $1,700. She lost. The expenses had to be paid in the same year the money was withdrawn. It’s important to remember that the medical expenses must qualify as deductible, meaning it must exceed the income threshold for claiming the deduction, which increased to 10% of AGI (adjusted gross income) for 2019. The exception is still available even if the taxpayer uses the standard deduction.
As you can see, there are a number of tax-traps when withdrawals from retirement plans (IRA or company plans) are used to meet emergencies.
Mr. Slott argues – and I have argued as well – this is why it’s important for advisors and their clients to set-up tax-free sources of income, such as non-IRA funds – money that’s already been taxed – so the money will be available for those emergencies when they arise.
It’s not something you can do at the last minute; but, it is something you can plan for IF you plan ahead.
Hope this helps,
Jim
```
[1] Financial Planning, June 2019. Ed Slott is a practicing CPA and a nationally recognized
retirement expert, often appearing on PBS conducting highly entertaining and informative
educational sessions.
```
---
Subscribe to the IFG Ezine
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, Reducing Risk
---
### [RMDs Rules About to Change?](https://indfin.com/fiduciaryadvisor-3/)
**Published:** July 8, 2019
**Author:** Jim Lorenzen
**Excerpt:** Not everyone is a true fiduciary. See what a search firm that specializes in this area has to say.
**Content:**
**Jim Lorenzen, CFP®, AIF®**The government is facing huge deficits and a building national debt. So, the latest bid to re-arrange deck chairs, the House recently passed *The Setting Every Community Up for Retirement Enhancement Act of 2019*. They’re calling it *The Secure Act*.
According to *Wealth Management*, it’s not law – it’s just a bill that’s passed the House and the Senate will pass its own version at some point before it goes to committee for reconciliation. Nevertheless, here’s what’s in the House bill:
1. Retirement accounts would be forced to distribute all benefits within 10 years after the employee or owner dies. This would apply whether or not the deceased had reached his/her required beginning date. What this does, of course, is reduce the value of inheritances. No special provision addresses trusts.
2. Determination of a plan’s beneficiary being an eligible designated beneficiary happens on the date of the employee’s or owner’s death.
3. Some charities will adapt to the 10-year rule by naming a charitable remainder unitrust (CRUT) as a beneficiary, permitting tax deferral over the tern of the CRUT and increasing the value realized by the non-charitable beneficiary. A present value analysis can help determine whether the benefit to the family exceeds the use of the 10-year rule. Some may adapt by making lifetime qualified charitable distributions – direct transfers of up to $100K/year from an IRA to a qualifying charity after age 70-1/2.
It’s a long way from being law yet; but, it’s good to know what they’re up to.
Jim
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, Reducing Risk
---
### [Do You REALLY Want to Invest Like Warren Buffett?](https://indfin.com/investlikebuffett/)
**Published:** July 15, 2019
**Author:** Jim Lorenzen
**Excerpt:** Not everyone is a true fiduciary. See what a search firm that specializes in this area has to say.
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a3fcbc2c3d970b-320wi.jpg)Jim Lorenzen, CFP®, AIF®**Picture this: After a long talk with your financial advisor, s/he leans back and says, “I think you should put 90% of your money into stocks and 10% into short-term government bonds.”
Your jaw drops, “What?”
Who could blame you? But, according to an excellent recent article by Craig L. Israelsen[\[1\]](#_ftn1), those were Warren Buffet’s 2013 letter to Berkshire Hathaway shareholders disclosing his instructions to a trustee for the management of the final bequest to his wife.
Retire with all your money in only two asset classes? I wonder how that would sound to the regulators if an advisor made that recommendation to clients?
Dr. Israelson decided to test this concept using a $1 million retirement portfolio with annual withdrawals determined by the required minimum distribution (RMD) over a 25-year period – and he tested four different portfolios: (1) A seven-asset portfolio[\[2\]](#_ftn2), (2) 60% large-cap US stocks and 40% aggregate bonds, (3) 90% large-cap US stocks and 10% short-term government bonds, and (4) 100% cash. His time frame was the 49-year period from 1970 to 2018, which contained 25 rolling 25-year periods.
Guess what? Buffett’s portfolio won! While all portfolios were solvent after 25 years, the Buffett model had the highest average ending balance after 25 years of withdrawals. It also provided the highest average annual withdrawal and the highest average of total withdrawals over 25 years.
The operative word, however, is *average*. The Buffett model also had the widest swings of all the other portfolios; but, when you have more than a billion dollars, who cares?
Most of us living in the real world of making our money last may love the destination; but, we may not like the ride.
Jim
—————————————–
[***\[1\]***](#_ftnref1) *Financial Planning, May 2019, p. 50. Craig L. Israelsen, Ph.D. is an executive in residence in the personal financial planning program at the Woodbury School of Business at Utah Valley University and is also the developer of the 7Twelve portfolio.*
[***\[2\]***](#_ftnref2) *Equal portions of large-cap US stocks, small-cap US stocks, non-US stocks, real estate, commodities, US bonds, and cash.*
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, Reducing Risk
---
### [Financial Literacy College Courses May Become Mandatory](https://indfin.com/financialliteracycourses/)
**Published:** July 22, 2019
**Author:** Jim Lorenzen
**Excerpt:** Not everyone is a true fiduciary. See what a search firm that specializes in this area has to say.
**Content:**
**[](https://indfin.com/wp-content/uploads/2019/07/Meeting_Notetaking.jpg)Jim Lorenzen, CFP®, AIF®**Guess what?
The government require Americans to take financial literacy courses in college. The Financial Literacy and Education Commission, chaired by U.S. Treasury Secretary Steven Mnuchin, released a report earlier this year with the recommendation that financial literacy be emphasized in school, even suggesting “mandatory financial literacy courses.” Considering how ill-prepared most people are for retirement, this may not be a bad idea!
The report also suggested providing those needing to improve their financial literacy with actionable financial information. “A body of evidence indicates that financial education alone has had a small impact on financial behaviors, in part because financial knowledge decays within two years of the lesson,” the report noted. “Behaviorally based strategies,” for example providing Social Security benefit estimates to individuals near retirement age, instead of arbitrarily providing that information, tends to be more helpful for individuals. So, relevant information – the kind they can actually use – may be just the ticket!
You can [see the report here](https://home.treasury.gov/system/files/136/Best-Practices-for-Financial-Literacy-and-Education-at-Institutions-of-Higher-Education2019.pdf).
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, Reducing Risk
---
### [Annuities Can Generate Guaranteed Income for Life! So, why do people hate them?](https://indfin.com/annuitybias/)
**Published:** August 2, 2019
**Author:** Jim Lorenzen
**Excerpt:** Not everyone is a true fiduciary. See what a search firm that specializes in this area has to say.
**Content:**
**[](https://indfin.com/wp-content/uploads/2017/05/Pension_Plan_Chart_and_Calculator.png)Jim Lorenzen, CFP®, AIF®**Many people who’ve enjoyed their employers’ guaranteed retirement pensions probably never gave much thought to the fact that some of their compensation was being diverted into an account that would fund the pension – and I’ll bet even fewer suspected that their pension was likely being funded with an annuity purchased by their employer. They would have hated purchasing an annuity themselves; but, they love the pension.
But there is an anti-annuity bias existing among many, if not most, investors. And this is despite the fact that there are certain realities we all face:
- We don’t know how long we will live – we face longevity risk, the risk of running out of money.
- When the ‘bad return years’ will occur (Murphy’s Law) – that’s called sequence of returns risk.
- If and when unexpected financial disasters might occur – health issues, roof and air/heating go kaput at the same time (Murphy’s Law again).
The good news is the use of an immediate or deferred annuity can help solve many concerns, particularly the first two above – the income is for life and market returns won’t affect that income. This is why many refer to their use as a ‘personal pension plan’.
But, there is no such thing as the perfect investment – at least I haven’t found it (and I’ve been looking on behalf of clients for more than 27 years).
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a3fd41160b970b-320wi.jpg)Every investment on the planet has a set of characteristics.** It’s generally not a question of what’s ‘good’ or ‘bad’; it’s more of a question of whether (or not) the majority of those characteristics are appropriate and beneficial – or whether the majority are inconsistent with the client’s financial situation, as well as his/her goals and desires.
- Sometimes, problems arise when people misconstrue the purpose of an annuity. Instead of focusing on the true purpose (providing an income for life), they often focus on the risk of dying before they receive all their money back. They hate the thought the insurance company might `win’. Despite the fact they hope they’ll never have a house fire (which would allow them to ‘collect’), they forget they’re really insuring against a risk (longevity) in the same way they insure their homes and cars.
- Some focus on ‘returns’, conflating an annuity purchase with a bond. The truth is they’re not purchasing a stream of dividends or interest; they’re purchasing an income stream, i.e. cash flow for life – in effect, a return of principal and interest with one difference: It’s for life; it never runs out.
- Another obstacle appears to be investors’ tendency to misprice the value of a guaranteed income for life. Few understand time-value of money and generally greatly underestimate the amount of money it takes to fund a monthly income for life. No wonder lottery winners tend to take the lump-sum and most people elect to take Social Security at 62.
Almost everyone would like a pension; but, few are willing to fund it – despite the fact that those who do have pensions and Social Security income did indeed fund those annuity payments with about 6% from each paycheck.
When one considers it takes a 25% return to buy-back a 20% loss in the markets, guaranteed income for life can sound pretty good IF there’s a willingness to fund the income stream.
[](https://indfin.com/wp-content/uploads/2014/09/Fotolia_5386670-DontSkipDetails.jpg)*Fotila Images***Are fixed annuities right for everyone?** No. Nothing is. Some academic research seems to support their use as a portfolio component for those with between $400,000 and $2 million; but, that’s academic theory, which often doesn’t translate well into the real world. Not everyone who fits this profile will have the same family situations, lifestyle requirements, health concerns, goals, yada, yada, yada.
It’s also worth remembering that annuities can be very complex products with a lot of moving parts – something that contributes to investor hesitancy. However, if you decide you want an annuity as part of your portfolio – talk this over with your advisor and be sure you understand how it will fit with your current formal retirement plan (or if it’s even needed) – a few key points are worth remembering:
**A retirement annuity is not an investment; it’s a risk-transfer tool.** You are purchasing a lifetime income stream and transferring longevity risk to the insurance company. It’s an insurance policy.
[](https://indfin.com/wp-content/uploads/2016/11/Piecing-Retirement-Puzzle-Path.png)A retirement annuity should not be your total retirement strategy – it’s a supplement to your other planning, as well as Social Security.
Do not automatically assume annuities are good. Do not assume they are automatically bad. Simply see if and how this planning component could fit (or not) with your formal plan.
**Finally, I can hear someone asking, “Do you recommend annuities to your clients?”** My use of annuities in client portfolios can best be described as extremely rare. It’s not that annuities are bad; it’s more that, for one reason or another, they either haven’t been needed or there were other overriding issues that were more important. That doesn’t mean I wouldn’t recommend a particular annuity design if circumstances warranted – it’s just been a rare occurrence up to now.
Annuities can be confusing: Variable annuities are NOTHING like fixed annuities. An annuity linked to a market index is NOT a variable annuity – it’s actually a fixed annuity and it is NOT an investment in the stock market.
If you’re not sure, the best advice is to get professional help. After all, how many of us would stand in front of a mirror with a pair of pliers when we have a toothache?
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, Reducing Risk
---
### [ROLLOVER MISTAKES CAN BE COSTLY](https://indfin.com/rollover-mistakes-can-be-costly/)
**Published:** September 12, 2019
**Author:** Jim Lorenzen
**Excerpt:** Not everyone is a true fiduciary. See what a search firm that specializes in this area has to say.
**Content:**
**[](https://indfin.com/wp-content/uploads/2017/05/Coffee_with_RMD_Pencil.png)Jim Lorenzen, CFP®, AIF®**… and mistakes are more common than you might think.
IRA mistakes generally revolve around errors associated with required minimum distributions (RMDs), hardship distributions, and distributions involving pre-tax vs. after-tax funds; but rollover errors can create special headaches. Ineligible rollovers are often taxable (unless they are after-tax funds) and could be subject to a 10% IRS penalty. Not good.
According to retirement expert Ed Slott[\[i\]](#_edn1), the biggest three ineligible rollovers are:
> Violations of the one-per-year IRA rollover rule
> Missing the 60-day rollover deadline.
> Distributions to non-spouse beneficiaries (a non-spouse beneficiary can never do a rollover. The funds must be moved as direct transfers).
Those are only the top three; but there are many other lesser-known rollover tax-traps. If you’re retiring and planning a rollover, you might consider getting professional help. You can find a *CERTIFIED FINANCIAL PLANNER®* (CFP®) professional [here](https://www.letsmakeaplan.org/choose-a-cfp-professional/find-a-cfp-professional).
Naturally, if I can help, you can get things started[ here](https://indfin.com/getting-started/).
Here’s an [IRA Rollover Checklist](https://indfin.com/wp-content/uploads/2017/05/i308a_IRA-Rollover-Checklist.pdf) you might find helpful, as well as a little insight about [How To Get Value from an Advisor Relationship](https://indfin.com/wp-content/uploads/2014/09/i109_How-To-Get-Value-from-an-Advisor-Relationship.pdf).
Jim
——————-
[***\[i\]***](#_ednref1) *El Slott is a CPA based in Rockville Centre, New York, who has appeared on PBS and is the author of several books on IRAs.*
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, Reducing Risk
---
### [Worried About the Markets? Maybe you should(n't) try alternatives - part 2.](https://indfin.com/marketworries2/)
**Published:** September 25, 2019
**Author:** Jim Lorenzen
**Excerpt:** Do annuities make sense as an alternative. It depends on what you think your postponed taxes will look like.
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017ee9006d09970d-120wi.jpg)Jim Lorenzen, CFP®, AIF®**In my last post, a talked about how the financial planning profession has changed dramatically since I opened my first office in 1991; but, the financial services industry – not to be confused with the profession that operates alongside it – seems to have changed little, though it’s changed a lot.
I talked about how the financial product manufacturing, marketing, and sales channels represent an industry that exists alongside – not necessarily a part of – the financial planning profession. It doesn’t help, of course, that anyone can call themselves a financial planner – but I digress.
Alternative investments (alts) represent one example, which I discussed in the last post. Another alternative investment is deferred annuities.
People love guarantees. Marketers know this and the use of the word virtually always gets investors’ attention – particularly those who’ve amassed significant assets and are contemplating retirement.
The media – always on the alert for something they can hype or bash for ratings and typically lazy – find it easy to highlight high costs and shady salespeople. And, there’s some truth to that. Guaranteed income or withdrawal riders and equity indexed annuities do tend to have high costs. Often the guarantees that are less attractive than those presented.
The cost-benefit argument could, and probably will, go on forever. I have other issues. The first is, does an annuity make sense at all? – Any annuity. There’s no tax-deferral benefit if used inside an IRA and it limits your investment choices. They also often have surrender charges that enter into future decision-making; but, even when there are no surrender charges, the withdrawals can harm performance or even undermine the guarantees that were the focus of the sale.
For me, here’s the big issue: the annuity creates something most of my clients no longer want any more of – deferred income (who know what future tax rates will look like in 10-15 years as government deficits climb? Deferred income comes out first and is taxed at ordinary income tax rates.
Deferred income in non-qualified annuities (outside IRAs, etc., funded with normally taxable money) is income in respect of a decedent (IRD) and does not get a step-up in cost basis at the death of the holder – someone will pay taxes on the earnings and they may be in a higher tax bracket or the IRD may put them there.
There may be other ways to invest using alternative strategies. Options can work, but they also carry additional costs and risk.
Talk to your advisor – maybe one with recognized credentials and willing to take fiduciary status might be a good idea – to see what your plan should be.
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, Reducing Risk
---
### [Worried About the Markets? Maybe you should(n't) try alternatives.](https://indfin.com/marketworries1/)
**Published:** September 21, 2019
**Author:** Jim Lorenzen
**Excerpt:** Not everyone is a true fiduciary. See what a search firm that specializes in this area has to say.
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019affbd774b970c-320wi.jpg)Jim Lorenzen, CFP®, AIF®**The financial planning profession has changed dramatically since I opened my first office in 1991; but, the financial services industry – not to be confused with the profession that operates alongside it – seems to have changed little, though it’s changed a lot. What? I’ll explain.
The industry, comprised largely of product manufacturers and their sales arms (these days it seems anyone can say they’re a ‘financial advisor’), has a long track-record of constantly packaging new products to take advantage of a demand among investors that the product manufacturers create through their marketing. New ‘issues’ (created by marketing) give rise to new products to be sold to fill a marketing-driven demand. Changes in product innovation to generate new sales is the constant that never changes.
This doesn’t mean it’s all bad; it’s just that it can be difficult for spectators to recognize the game without a program.
Alternative investments get a lot of press these days – especially if there’s a perceived risk of a down or bear market… a perception that’s convenient to exploit at almost any point in time. The media likes ratings, so profiling people that called a market top or decline – and made money – is always good for attracting an audience. And, since there’s always someone on each side of a trade, finding someone on the right side isn’t difficult.
I’ve always felt that many fund managers operate like baseball free agents. Being on the right side of a call gets them on tv, which in turn attracts new assets, which in turn leads to bigger year-end bonuses. I could be wrong, or not.
Many captive “advisors” are putting their clients into “alts” these days because their employer firms (the distribution arm for the product manufacturer) are emphasizing them.
My sales pitch for alternatives: With alternatives, you can have higher costs, greater dependency on a fund manager’s clairvoyance, less transparency, low tax-efficiency, and limited access to your money! What do you think?
Don’t get me wrong. It’s not a black and white decision. They can have a place in a well-designed portfolio; and, while many endowment funds and the ultra-wealthy do tend to own alts, most of us aren’t among the ultra-wealthy and risk mitigation is important.
More about alternatives next time.
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Investing, Planning, Retirement
**Tags:** Financial planning, Reducing Risk
---
### [I.R.S. RULING MIGHT CREATE TIMING ISSUES](https://indfin.com/irsdistributiontiming-2/)
**Published:** September 30, 2019
**Author:** Jim Lorenzen
**Excerpt:** RMDs can present a tax trap for the unwary. Here's a 4-point checklist to help you avoid the pitfalls.
**Content:**
**[](https://indfin.com/wp-content/uploads/2017/05/Crossword_RMD.png)Jim Lorenzen, CFP®, AIF®**On August 14th, the IRS ruled (Revenue Ruling 2019-19) that uncashed distribution checks from qualified retirement plans are taxable.
Oops! That means that those requesting distributions, including RMDs should do it early enough in the calendar year to avoid any year-to-year carry-over confusion. So, a distribution check issued in July, for example, will be taxed for that distribution in the year it is received, even if not cashed or rolled-over.
Those who leave companies and expect future distributions from their 401(k) from that company should update any change of address information – taxes, it appears, will be due on that money even if the check never reaches them.
Why did the IRS make this ruling? According to retirement guru and CPA Ed Slott, the ruling was intended to address a question that has long been faced by retirement plan administrators – what are their withholding and reporting obligations when a check they issued goes uncashed?
So, the distribution is recorded in the year it’s distributed…. Good to know, huh?
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement, Taxes
**Tags:** Financial planning, retirement mistakes, Retirement Planning
---
### [Changes To Medicare Plans to Begin Soon!](https://indfin.com/medicarechanges/)
**Published:** October 3, 2019
**Author:** Jim Lorenzen
**Excerpt:** RMDs can present a tax trap for the unwary. Here's a 4-point checklist to help you avoid the pitfalls.
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019aff2c523c970c-320wi.jpg)Jim Lorenzen, CFP®, AIF®**Beginning this January, Medigap plans will no longer cover the Part B deductible for those who are turning age 65. Since the deductible is only $185, it won’t be a big deal for most people.
What’s worth noting is that Plan F – the plan that covered all of Part A and Part B, including deductibles – will no longer be sold to those turning age 65 beginning January 1, 2020. Anyone who is 65 or older before that date can still apply for Plan F, but they may not want to.
Charles Paikert, writing in *Financial* *Plannng’s* September issue quoted insurance broker Stuart Millard who noted that even those who are already in Plan F, while not affected, may want to pay attention to this change. Plan G, which is nearly identical to Plan F, is still available and older clients – and they may *want* to switch! Why? Sarah Caine, a specialist quoted in the same piece, points out that since Plan F is being discontinued, no new clients are coming in. This means the pool of patients will diminish as people age out. Since no new people will be replenishing the risk-sharing pool, it’s possible that Plan F may not be as stable as it once was.
For those who can afford it, Medigap plans may be appealing because they’re not restricted to doctors in a network or geographic location whereas Medicare Advantage plans may not be as beneficial for people who split their time between two homes or are active travelers.
Medicare health planning is a highly specialized field. Too often people will simply shop online or deal with a jack-of-all-trades “financial advisor” who’s licensed to sell everything. In addition, many people are unaware that there is income testing for Medicare, going back two years. Those who have vested and restricted stocks, as well as those who are in COBRA plans may want to examine their situations carefully, including annual evaluation of their Part D prescription drug plan where prices change, as well as the offerings, each year.
Medicare has strict deadline rules, as well. Miss a deadline and you can lose important rights, such as Medigap’s guaranteed issue right.
As I said, this is a highly specialized area and the services of an experienced insurance broker who is a health care specialist just might save you thousands of dollars.
Jim
*Note: The Independent Financial Group does not sell health insurance and Jim Lorenzen is not a health insurance broker.*
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement, Taxes
**Tags:** Financial planning, retirement mistakes, Retirement Planning
---
### [Your IRA Has An Unnamed Beneficiary!](https://indfin.com/hiddenbeneficiary/)
**Published:** October 7, 2019
**Author:** Jim Lorenzen
**Excerpt:** RMDs can present a tax trap for the unwary. Here's a 4-point checklist to help you avoid the pitfalls.
**Content:**
**And, this one could end-up with the lion’s share of all you worked for.**
[](https://indfin.com/wp-content/uploads/2019/10/Fotolia_3956379-Overwhelmed.jpg)*Fotilla Images***Jim Lorenzen, CFP®, AIF®**
It’s one thing if you forget to name someone as a beneficiary – you have three kids and forgot to name one of them (oops!) – but, it’s even worse when someone you didn’t even name may end-up with the lion’s share of your retirement account!
Can’t happen? Oh yes, it can.
Let’s assume you have a 401(k) or IRA valued at $600 000. Who would you like to inherit it? Chances are it’s your loved ones/kids. So, why haven’t you given it to them already? Simple: You may need the money. But, when you do pass away, your beneficiaries must include withdrawals in their taxable income. It’s not uncommon for retirees to die sometime between ages 75 and 95… this is often the time the IRA passes to the next generation at or near their peak values.
Leaving timing and amounts aside, if you live in a high-tax state like California, the combination of other taxable income and withdrawals can easily put someone in a higher tax bracket.
Will assume the IRA is $600,000 and you have three successful kids. It wouldn’t be unrealistic for a successful two-income family to end-up in a combined state and federal tax bracket of 40%
**Here’s what each will end-up with:** $200,000 (1/3 of the IRA) less $80,000 (40% state and federal taxes) = $120,000.
###### **Oh, yeah… your 4th kid: Uncle Sam**. He received $80,000 x 3 kids = $240,000. That’s THREE TIMES what each of your kids received!
Happy now?
**How do we keep that extra $240,000 in your three kid’s pockets?** You can use a tax-offset strategy. It’s simple: You transfer the risk. Now, this isn’t something you can do with stocks, bonds, gold, or real estate. There’s only one tool in the financial toolbox I know of that can do this.
The strategy: You purchase a $600,000 survivorship life insurance policy. When the parents die, the children inherit the IRA. They also each inherit 1/3 of the life insurance proceeds ($200,000) which, by the way, comes tax-free. They can use the death benefit proceeds to pay the taxes they owe for inheriting the IRA. They keep the entire IRA (each is now $80,000 richer) and your family has retained an additional $240,000.
Each received $200,000 instead of $120,000. That’s a 70% increase!
They also now have choices. Because taxes aren’t an issue, they could liquidate the IRA and invest the money where they’ll have complete liquidity and no future required minimum distributions or explore other options available to them.
Either way, they’re better off. Thanks, mom and dad.
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Life Insurance, Planning, Retirement, Taxes
**Tags:** Financial planning, retirement mistakes, Retirement Planning
---
### [CDs, Fixed Annuities, and Indexed Annuities Share Some Common Risks- copy](https://indfin.com/cdannuityrisks/)
**Published:** October 14, 2019
**Author:** Jim Lorenzen
**Excerpt:** The most common risk associated with all fixed-rate investments is interest rate risk, but it doesn't end there.
**Content:**
**This time the unnamed beneficiary gets zero.**
[](https://indfin.com/wp-content/uploads/2016/07/Fotolia_5090081-DB-ForkInRoad.jpg)*Fotilla Images***Jim Lorenzen, CFP®, AIF®**
**The most common** risk associated with all fixed-rate investments is interest rate risk. If interest rates rise–and the fed has already sent some pretty strong signals higher rates are on the way–investors could be stuck with the old lower rates, especially if the rate hikes occur during the penalty period.
**This may not be a huge issue with CDs** most people tend to “ladder” shorter-term CDs . Missing out on a half-point increase for six months is really an opportunity cost of 0.25%. The bigger problem, of course, is the loss of purchasing power on an after-tax basis.
**Fixed annuities** tend to have surrender charges with longer time spans–and therefore have a larger interest rate risk exposure. Penalty periods of five to ten years aren’t uncommon. Waiting several years through several potential rate increases can have a larger impact. The longer surrender period usually does come with higher interest crediting rates, to be sure; but, it’s worth doing the math–it’s hard to get ‘sold’ on longer terms and accompanying surrender charges when the outlook for increases is unknown. Given how long rates have been so low, a pendulum swing isn’t hard to believe. Remember, the insurance company’s annuity products purchased today will be backed by low-yielding bonds held today for most of the penalty period.
**Fixed Indexed Annuities** offer an opportunity for higher interest based on the performance of some outside index. Despite the fact many people choose the S&P500 index as the calculation benchmark, these products are not investments in the stock market. They are still insurance company IOUs paying a fixed rate–it’s just that the fixed rate paid each year is determined by the performance of the outside index; however, they always come with some limiting factor–usually a ‘cap’ on the amount they’ll credit or crediting based on some sort of ‘spread’ factor. Many professionals figure a fixed indexed annuity might actually return 1-2% more than it’s fixed-rate guarantee. So, one that offers a fixed rate of 4% might be expected to provide a long-term return of 5-6%; however, the return could be less. It all depends on the performance of the external index chosen, so short-terms carry more risk than long term, if history is any indication.
Remember, too, that insurance companies can change their crediting rates. Nevertheless, when you compare the expected return of an FIA to a 5-year CD, it’s still a popular alternative, providing other factors meet with your needs. Remember, however, longer-term products also mean longer-term interest rate exposure, as noted above.
**Premium Bonuses**, too, may not be as good as they sound. While they provide purchasing incentives, they virtually always result in lower crediting rates, further increasing interest rate risk. It may be better to seek a shorter-term product without a bonus that allows you to move to a higher rate product sooner. Why get stuck in a long-term contract?
**Personal Take**: Generally, whatever you want to accomplish with an annuity might be better accomplished in another way, often with greater liquidity and sometimes even better benefits. In any case, it pays to do your homework. Just as all investments can’t be good, all annuities aren’t necessarily bad. For many, the peace of mind knowing income is protected is worth the trade-off. Just remember, tax-deferred means tax postponed. Do YOU know what tax rates will be when you plan to begin taxable withdrawals? Neither do I.
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Life Insurance, Planning, Retirement, Taxes
**Tags:** Financial planning, managing risk, Reducing Risk, Retirement Planning, Safe Money
---
### [How Can You Manage Your Inheritance?](https://indfin.com/inheritance/)
**Published:** October 21, 2019
**Author:** Jim Lorenzen
**Excerpt:** Coming into money can create a lot of anxiety if you don't have a plan. Here's a tip sheet and LifeGuide that might help!
**Content:**
**Here are some tips that might help!**
**[](https://indfin.com/wp-content/uploads/2016/11/Fotolia_2204049-DB-Teamwork.jpg)Jim Lorenzen, CFP®, AIF®**
For most people, there are certain times when events can feel overwhelming. For most of us, when it’s a money event (retirement plan rollover, selling property, winning the lottery, etc.) it’s usually when we think, ‘What do I do now? I don’t want to screw this up!”
Here are some tips, along with a [LifeGuide](https://indfin.com/wp-content/uploads/2019/10/i305_LifeGuide_Managing_An_Inheritance_vsa.pdf), that might help:
**Take your time.** This is an emotional time…not the best time to be making important financial decisions. Short of meeting any required tax or legal deadlines, don’t make hasty decisions concerning your inheritance.
**Identify a team of reputable, trusted advisors** (attorney, accountant, financial/insurance advisors). There are complicated tax laws and requirements related to certain inherited assets. Without accurate, reliable advice, you may find an unnecessarily large chunk of your inheritance going to pay taxes.
**Park the money.** Deposit any inherited money or investments in a bank or brokerage account until you’re in a position to make definitive decisions on what you want to do with your inheritance.
**Understand the tax consequences of inherited assets.** If your inheritance is from a spouse, there may be no estate or inheritance taxes due. Otherwise, your inheritance may be subject to federal estate tax or state inheritance tax. Income taxes are also a consideration.
**Treat inherited retirement assets with care.** The tax treatment of inherited retirement assets is a complex subject. Make sure the retirement plan administrator does not send you a check for the retirement plan proceeds until you have made a distribution decision. Get sound professional financial and tax advice before taking any money from an inherited retirement plan…otherwise you may find yourself liable for paying income taxes on the entire value of the retirement account.
**If you received an interest in a trust**, familiarize yourself with the trust document and the terms under which you receive distributions from the trust, as well as with the trustee and trust administration fees.
**Take stock.** Create a financial inventory of your assets and your debts. Start with a clean slate and reassess your financial needs, objectives and goals.
**Develop a financial plan.** No one would begin building a home (ordering out materials and beginning construction) without a well thought out plan, blueprints, and a budget; so, why build your financial future without one?
[](https://indfin.com/wp-content/uploads/2017/05/lighthouse.jpg)*Long term plans dont change just because temporary conditions do*Consider working with a financial advisor (preferably a *CERTIFIED FINANCIAL PLANNER**®*** (**CFP®)** professional to “test drive” various scenarios and determine how your funds should be invested to accomplish your financial goals. Interest rates, markets, inflation, and taxes can all change. But, your plan, if tested, is like the lighthouse in the storm – if you’re plan has been stress-tested, it’s the one thing that won’t move when everything else seems to be in turmoil.
**Evaluate your insurance needs.** If you inherited valuable personal property, you will probably need to increase your property and casualty coverage or purchase new coverage. If your inheritance is substantial, consider increasing your liability insurance to protect against lawsuits. Finally, evaluate whether your life insurance needs have changed as a result of your inheritance.
**Review your estate plan.** Your inheritance, together with your experience in managing it, may lead you to make changes in your estate plan. Your experience in receiving an inheritance may prompt you to want to do a better job of how your estate is structured and administered for the benefit [](https://indfin.com/wp-content/uploads/2019/10/i305_LifeGuide_Managing_An_Inheritance_vsa_001.jpg)of your heirs.
Don’t forget your [LifeGuide](https://indfin.com/wp-content/uploads/2019/10/i305_LifeGuide_Managing_An_Inheritance_vsa.pdf)!
Hope this helps,
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Life Insurance, Planning, Retirement, Taxes
**Tags:** Financial planning, managing inheritance, managing risk, Reducing Risk, Safe Money
---
### [When A Loved One Dies](https://indfin.com/whenalovedonedies/)
**Published:** October 24, 2019
**Author:** Jim Lorenzen
**Excerpt:** Coming into money can create a lot of anxiety if you don't have a plan. Here's a tip sheet and LifeGuide that might help!
**Content:**
**It can be helpful if you know what has to be done in advance.**
[](https://indfin.com/wp-content/uploads/2019/10/Fotolia_3956379-Overwhelmed.jpg)*fotilla images*
**Jim Lorenzen, CFP®, AIF®**
Earlier this past week I talked about [Managing an Inheritance](https://indfin.com/inheritance/) and provided a Lifeguide; but, a few readers emailed me asking if there was a checklist addressing what to do when a loved one dies.
This is a subject my wife an I can relate to, having lost both our parents between 2005 and earlier this year. So, I thought many of you might find a fillable Lifeguide Helpful.
[](https://indfin.com/wp-content/uploads/2019/10/i902_Lifeguide_When-A-Loved-One-Dies_001.jpg)
You can access it a 22-page guide [here.](https://indfin.com/wp-content/uploads/2019/10/i902_Lifeguide_When-A-Loved-One-Dies.pdf).
Hope this helps,
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Estate, Family Issues, Planning, Taxes
**Tags:** Estate Planning, Financial planning
---
### [YOU Are an Acutary!](https://indfin.com/actuary/)
**Published:** October 28, 2019
**Author:** Jim Lorenzen
**Excerpt:** Coming into money can create a lot of anxiety if you don't have a plan. Here's a tip sheet and LifeGuide that might help!
**Content:**
**Bet you didn’t know that.**
[](https://indfin.com/wp-content/uploads/2014/09/Fotolia_5386670-DontSkipDetails.jpg)*Fotila Images***Jim Lorenzen, CFP®, AIF®**
There was a time – for those of you old enough to remember – when companies would promise you a pre-determined retirement benefit, then do all the calculations required to figure out just how much they would have to fund your plan in order to achieve the promised results.
Not easy. They had to start with the ending value and work backwards, making capital markets assumptions for expected portfolio returns, based on how their investment portfolio was allocated.
Problems arose, however, when their projections were too optimistic resulting in many under-funded pension plans and an inability to pay promised benefits.
Goodbye pensions; hello 401(k). Companies decided they didn’t need the liability risk: You figure it out.
Now you get to decide how much funding is required. Can you calculate the time-value of money? Pensions promised a fixed benefit; but, in the real world, we have inflation and tax-law changes. [](https://indfin.com/wp-content/uploads/2019/10/i316b_Youre-an-Actuary_001.jpg)Pensions never even considered those factors.
Not only do you need to factor-in additional inputs; you also need know how to manage portfolio risk, too! You might find [this report ](https://indfin.com/wp-content/uploads/2019/10/i316b_Youre-an-Actuary-1.pdf)somewhat enlightening, if not helpful.
Enjoy,
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Annuities, Family Issues, Investing, Planning, Retirement
**Tags:** Estate Planning, Financial planning, managing risk, Retirement Income, Retirement Planning
---
### [The One Million Dollar Mistake.](https://indfin.com/milliondollarmistake/)
**Published:** November 4, 2019
**Author:** Jim Lorenzen
**Excerpt:** Here's a $1 million dollar mistake that many, if not most, 20-somethings make - and how it can be avoided.
**Content:**
**Most twenty-somethings fall victim to this; but it’s preventable.**
**Jim Lorenzen, CFP®, AIF®**
You’ve seen it – you may have even done it yourself: a 25-year-old who has been out of school for several years is beginning to get (somewhat) established in his/her first possible career position (which may likely be one of many before reaching age 35) and looking to enjoy the newly-found independence and early success.
A new SUV, instead of an older one (because of ‘no-down, zero percent financing’, etc.); a nice apartment in a nice area, instead of something smaller; brand-new expensive furniture instead of starting out with second-hand. In short, living month-to-month convinced they haven’t a dollar to spare – because it’s true.
What if a corner was cut here, another there – enough that allowed a savings of just $92 per week – about $400 per month… money that could be diverted to a retirement or other account?
**How much would that 25-year old have saved by age 65?**
[](https://indfin.com/wp-content/uploads/2019/11/Jim-at-Hervey-Street.jpg)*In case youre wondering this is me at age 29 in my first apartment after moving to Southern California A metal folding chair and a swap meet fold out sofa my bed were my only furniture*It depends. Let’s assume that s/he simply puts that money into a low-cost, tax-efficient fund or ETF that tracks an index of large company stocks, something like the S&P index (you can’t buy an index, only a fund that tracks it). Historically, long term returns on such an index has been somewhere around 10 percent. But even if the return were 20% less – 8% – our now 65-year-old would have (rounded-off) $1,396,408. Almost $1.4 million!
But, 25-year-olds seldom do this. They wait until they’re age 40 or 50 before they begin to get serious. Problem is, by then $400 per month savings getting the same return by age 65 will have them ending-up with just $380,410…. **More than $1 million less!**
To catch up and end-up with the same $1,396,408, our 40-year-old needs to save 266% *more* each month, $1,468.
One might respond, “Yes, but by then I’ll have more money!” True; but, things will cost more, too. Using a long-term 3.5% inflation rate (not unreasonable), that $1,468 the 40-year-old saves has the same purchasing power as $876 has for the 25-year-0ld.
**The moral**: Start early and increase your deposits as you age. Don’t wait. The biggest gift you can give your children is not their education. Maybe it’s making sure they aren’t faced with additional responsibilities in your old age.
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Investing, Planning, Retirement
**Tags:** Financial planning, Retirement Income, Retirement Planning
---
### [Is Inflation on the Horizon?](https://indfin.com/inflationrisk/)
**Published:** November 8, 2019
**Author:** Jim Lorenzen
**Excerpt:** So far, tariff-induced inflation simply hasn’t arrived. You’d think if it was going to, it would be here by now. But, are we out of the woods? And, how can you protect yourself?
**Content:**
We’ve been below 2% for a long time; but, will it continue?
**Jim Lorenzen, CFP®, AIF®**
So far, tariff-induced inflation simply hasn’t arrived. You’d think if it was going to, it would be here by now. And, the reason is simple: If inflation was in the ‘pipeline’, goods in current inventory would be marked-up in advance in order to raise cash to cover new inventory acquisition costs. [](https://indfin.com/wp-content/uploads/2016/11/Fotolia_1594119-ReadyToShip.jpg)
We’ve seen this before. When Mideast oil prices increased, prices at the local gas pumps went up immediately. But, that hasn’t happened with the trade-tariff fears.
Meanwhile, the Fed continues it’s race to the bottom. But, after the most recent cut, the dollar strengthened, making American goods more expensive and reducing demand – opposite the Fed’s intention. Weaker dollars attract foreign capital, increasing exports for American companies; so, the Fed’s losing-streak continues.
Vanguard and Wall Street Journal economists expect inflation to be closer to 2% over the next few years; but, as we know, predictions are one thing, surprises are something else. Inflation has been less than 2% over the past ten years, so it wouldn’t be surprising that the Fed would allow it to run above that number for a period.
For investors, this is where diversification can play a key role. Treasury inflation-protected securities (TIPS) are probably the best and purest form of hedging inflation. Another potential hedge is short-term corporate bonds. This is because if inflation is driven by a strong economy, consumption will increase and profits should be strong; however, it’s important to know what you’re doing: It’s important to understand credit risk – not simply trusting ratings – as well as the average duration of your bond portfolio, as well as how that duration has changed over time.
Of course, bonds can be effective as short-term inflation hedges; but a long-term time frame is another story. Nothing has outperformed stocks and bonds simply haven’t.
Remember, it’s not an either-or proposition. It’s about having a portfolio diversification design that fits your own desires and objectives – and your attitudes about risk. Best to work this out with someone who has seen it all a few hundred times and can help navigate the financial marketplace.
If you don’t know where to find professional help, you can ask your family and friends; you can also consult these resources:
[The CFP® Board](https://www.cfp.net/utility/find-a-cfp-professional)
[The Financial Planning Association](http://www.plannersearch.org/)
Of course, if you’re not a current IFG client, I hope you will consider checking out the tabs at the top of this page.
Hope this helps,
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Inflation, Investing, Planning, Retirement
**Tags:** diversification, Financial planning, Inflation, Investment Strategy, Retirement Income, Retirement Planning
---
### [Your Insurance Company Just Went Under?](https://indfin.com/insurancefailure/)
**Published:** November 15, 2019
**Author:** Jim Lorenzen
**Excerpt:** You’ve been paying on an insurance policy for years. Now, you’ve learned your insurance company – the one that top ratings from all the major ratings services - just went bust – what do you do? What could you have done to protect yourself?
**Content:**
Oops. Now what? No more protection? What happened to all those premium payments? How could you have protected yourself?
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019b00066606970c-320wi.jpg)Jim Lorenzen, CFP®, AIF®**
You’ve been paying on an insurance policy for years. Now, you’ve learned your insurance company – the one that top ratings from all the major ratings services – just went bust – what do you do? What could you have done to protect yourself?
There’s no counter for withdrawals and no ATM – and there’s no FDIC insurance. So, how are you protected?
The insurance industry is regulated state-by-state. Each state maintains its independence and operates its own system of regulation, and each is also a member of the National Association of Insurance Commissioners (NAIC), which helps provide uniformity.
It’s important to understand that an insurer may be based in one state, operate in multiple states, and still be domiciled in another. The domicile state is the lead state under normal circumstances for any regulatory actions.
While insurance companies don’t have any guaranties at the federal level, they do have state-backed insurance guaranty associations. According to Gavin Magor, Senior Financial Analyst for Weiss Ratings and oversees their ratings process, the states have established these associations to help pay claims to policyholders of failed insurance companies. However, there are several cautions which you must be aware of with respect to this coverage:
1. Most of the guaranty associations do not set aside funds in advance. Rather, states require contributions from other insurance companies after an insolvency occurs.
2.There can be an unacceptably long delay before claims are paid.
3. Each state has different levels and types of coverage, often governed by legislation. They’re unique to that state and can sometimes conflict with coverage of other states. Moreover, most state guaranty funds will not cover title, surety, credit, mortgage guarantee, or ocean marine insurance.
Bottom line: If an insurer fails, it may be awhile for you to get your claim processed and get your money to fix your home or pay bills. But just how often do insurers fail?
Since Weiss started rating insurance companies in 1989, 633 rated insurers failed. As you can see from the graph below, a majority of them were rated “D” or “E” by Weiss at the time of failure.
[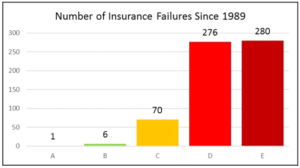](https://indfin.com/wp-content/uploads/2019/11/Ins_Failures_since_89_Weiss_GavinMagor.png)*Image provided by Weiss*The bottom line is that you can still get your claims paid even after your insurer fails, but it might take a while. So, we recommend you check an insurer’s Weiss safety rating before you start doing business with them. With only a 0.02% chance of an insurer rated “A” or “B” failing in any one year, you can see why we favor those over insurers rated “D” or “E”. In addition to our ratings, be sure to learn more about your insurer’s state guaranty funds.
Never heard of Weiss? I believe it. Virtually all insurers love to tout the other better-known companies; however, there’s a problem: Most, virtually all, of those touted rating services get paid by the insurers they rate! Weiss’ revenue is derived from those companies that subscribe to their reporting – it’s a business model similar to Consumer Reports which doesn’t accept advertising. It should be no surprise that fewer companies receive Weiss’ top ratings. It should also be no surprise that there are some ‘top rated’ companies that won’t allow Weiss to come through their doors.
I’ve encountered some insurance agents – I’ve even met some insurer’s representatives – who look at you with a blank stare when you ask about their Weiss rating. Maybe it’s because some big household names didn’t make the cut.
Worth knowing?
Jim
---
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/getting-started/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Life Insurance, Planning, Retirement
**Tags:** Financial planning, life insurance, life insurance decsions, Retirement Income, Retirement Planning
---
### [Stock Market Volatility Can Wreak Havoc on 4% Withdrawal Rates.](https://indfin.com/fourpercentrule/)
**Published:** October 12, 2020
**Author:** Jim Lorenzen
**Excerpt:** Often financial planning and wealth management is more about the unknowns in life than the knowns. After years of supporting roles on the Flintstones, Barney and Betty decided to retire from acting in cartoons (it's hard to be a cartoon character!) and enjoy life.
**Content:**
#### Financial planning is often more about what we don’t know than what we think we know.
[](https://indfin.com/wp-content/uploads/2014/09/Piggy_Bank_on_Side.png)
**Jim Lorenzen, CFP®, AIF®**
Often financial planning and wealth management is more about the unknowns in life than the knowns.
After years of supporting roles on the Flintstones, Barney and Betty decided to retire from acting in cartoons (it’s hard to be a cartoon character!) and enjoy life. Using a 4% withdrawal rate, they planned to take $40,000 a year from their $1 million retirement account which, with their Social Security, would provide them with everything they needed for life. Growth of investments would give them their inflation hedge.
*“Security is mostly a superstition: it doesn’t exist in nature” – Helen Keller*
They retired in 1999. Unfortunately, after three years his inflation-adjusted withdrawals and the market’s poor performance had eroded his portfolio to less than $540,000. At this point, his withdrawals now represented almost 8% of his portfolio value. Bad problem. Inflation made those withdrawals necessary but the 8% withdrawal rate simply wasn’t sustainable.
The market was good to him for the next five years; but, by the end of 2007, their portfolio was still less than $670,000, meaning withdrawals still amounted to more than 7% of portfolio value.
Then came 2008-9 – the melt-down. Their nest-egg plummeted to less than $400,000 and withdrawals now represented more than 12% of account value (cost of living still going up!)
4% didn’t work too well for Barney and Betty. Fred and Wilma (actually, more Wilma that Fred) had told them they needed a real plan that would be stress-tested for all the unknowns in life.
Planning isn’t about what we know; sometimes it’s knowing what we don’t know – and recognizing that often there are things we don’t know we don’t know. It’s more about managing risk than money; and planning for the unknowns.
Nothing beats experienced guidance.
Jim
————————————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a*[*proven planning process*](https://indfin.com/ifgplanningprocess/)*coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Inflation, Investing, Planning, Retirement
**Tags:** Financial planning, Investment mistakes, investment planning, investment returns
---
### [When A Loved One Dies](https://indfin.com/when-a-loved-one-dies/)
**Published:** October 27, 2020
**Author:** Jim Lorenzen
**Excerpt:** When a loved one dies, it can be a bit chaotic. I remember when my parents passed away, they had lived a very long and happy life.
**Content:**
#### It’s a confusing time; there’s a lot of emotion. Unfortunately, few people have developed a roadmap. Now, you can have one.
[](https://indfin.com/wp-content/uploads/2020/10/3986001-R1-037-17.jpg)
**Jim Lorenzen, CFP®, AIF®**
When a loved one dies, it can be a bit chaotic. I remember when my parents passed away, they had lived a very long and happy life. When the time came, it wasn’t unexpected and we had plenty of time to prepare, both emotionally and financially. This end-of-life timing scenario was predictable.
Unfortunately, that isn’t always the case. Sometimes it can happen unpredictably. When that happens, often there’s no plan in place – not even a roadmap. It can wait. We’ll do it later.
Not a good idea.
I want you to have something to work with. You don’t have to fill-out any forms; just click on the form links and you can download them immediately.
- [LifeGuide: When A Loved One Dies](https://indfin.com/wp-content/uploads/2020/10/i902_Lifeguide_When-A-Loved-One-Dies.pdf)
- [Tips for Managing an Inheritance](https://indfin.com/wp-content/uploads/2020/10/i304_TipsForManagingAnInheritance_201405.pdf)
- [LifeGuide: Managing an Inheritance](https://indfin.com/wp-content/uploads/2020/10/i305_LifeGuide_Managing_An_Inheritance_vsa.pdf)
These should provide you with the roadmap you need – you may want to print these out or save them to your hard drive – and don’t forget to get help.
Nothing beats experienced guidance.
Jim
————————————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a*[*proven planning process*](https://indfin.com/ifgplanningprocess/)*coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Family Issues, Investing, Planning, Special needs
**Tags:** death planning, End of ife, Financial planning, Investment mistakes, investment planning
---
### [Systematic Roth Conversion Strategies Can Be Powerful....](https://indfin.com/systematicrothconversions/)
**Published:** November 10, 2020
**Author:** Jim Lorenzen
**Excerpt:** Do you know what a systematic Roth conversion is? It's worth knowing!
**Content:**
#### … especially when they’re tied to a plan.
[](https://indfin.com/wp-content/uploads/2020/08/HM_Taxes.png)**Jim Lorenzen, CFP®, AIF®**
Do you know what a systematic Roth conversion is? It’s worth knowing!
Even at modest growth rates, the results of a systematic Roth conversion can be surprisingly impressive over time. Take a look at this example from Debra Taylor, a tax attorney and advisor in Franklin Lakes, New Jersey, comparing no conversion to systematic conversion. What would the traditional IRA and the Roth IRA (funded with systematic conversions) look like?
Using a modest growth rate of 5% per year over a ten-year period, here are the results beginning with a $500,000 IRA and converting just $17,500 per year.
[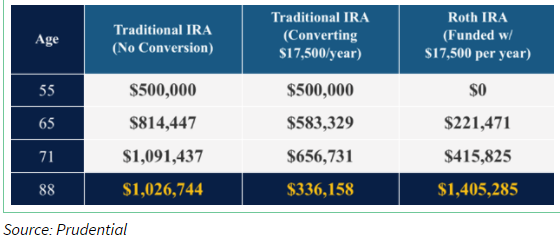](https://indfin.com/wp-content/uploads/2020/11/Roth-Conv-Outcomes-of-17500-per-yr.png)
With no conversion, the traditional IRA has grown to $1,026,744. Not bad, except that all that money doesn’t belong to the IRA owner. Some of it belongs to Uncle Sam – it’s his IRA, too. How much, of course, depends on what tax rates are in effect when withdrawals occur.
Using a ten-year systematic conversion plan instead, that $500,000 IRA ends-up with only $336,158 at the end of 10-years. That means lower required minimum distributions (which impact how much your Social Security is taxable and your Medicare premium amounts) and lower taxes, too. How much lower? Pick a bracket and do the math on both – you’ll likely be surprised.
Instead, using a systematic Roth conversion strategy, those ten annual $17,500 conversions resulted in a tax-free Roth IRA value of $1,405,285! Combined with the traditional IRA, results in two retirement accounts now worth a total of $1,741,443 – that’s $714,699 (70%) more! And, 81% of the owner’s retirement money – the money in the Roth IRA – is tax free!
The best time to begin a strategy like this is after age 59-1/2 and the age when required minimum distributions (RMDs) begin. That age depends on your birth date under the SECURE Act. The age is 72 if born on or after July 1, 1949. It’s 70-1/2 for all others. Once RMDs begin, you can’t use RMDs to fund Roth conversions; you’ll have to take your RMD first, then take the conversion amount. Secondly, the strategy works only if you convert the entire amount and pay any tax due from other funds.
It goes without saying – or maybe it doesn’t – that any strategy should be tied to a solid financial plan that can ‘stress-test’ outcomes and probabilities. Nothing beats experienced and informed guidance.
Jim
————————————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://tinyurl.com/IFGIntroCall%20 "Schedule Your IFG Intro Call!")your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-based registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a*[*proven planning process*](https://indfin.com/ifgplanningprocess/)*coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Planning, Retirement, Roth conversions, SECURE Act, Taxes
**Tags:** death planning, End of ife, Financial planning, Investment mistakes, investment planning
---
### [Medicare Advantage Plans May Come With Unpleasant Surprises.](https://indfin.com/medicareadvantage/)
**Published:** November 30, 2020
**Author:** Jim Lorenzen
**Excerpt:** Maybe you should think twice before buying a Medicare Advantage plan from a football player.
**Content:**
#### Maybe you should think twice before buying from a celebrity endorser.
**Jim Lorenzen, CFP*®*, AIF*®***
[](https://indfin.com/wp-content/uploads/2020/01/iStock-518900268.jpg)
**Let’s start with this: I’m not a Medicare expert**. My basic knowledge as a CFP® professional certainly helps when it comes to integrating health care into a financial plan, but make no mistake about it: Health insurance is a highly complex area; so, when it comes to selecting plans, including Medicare, it pays to consult an expert – someone who does *nothing but*.
That’s why I was intrigued by an article I read last April by Joanne Giardini-Russell\* entitled, “*Should You Buy a Medicare Plan from Joe Namath?*“
A few points about Medicare Advantage plans (also called “Part C” plans) that caught my eye:
- The reason private insurers can offer these plans for zero dollars per month is because the federal government actually pays them to offer Advantage plans to the public – about $1,000 per month, or more, per enrollee. In exchange, the plans administer and manage the coverage for those who sign up.
- When enrolling for a Medicare Advantage plan, you still have to pay your Medicare Part B premium. Most pay around $144 monthly for Part B coverage.
- If you see a specialist (like a cardiologist or dermatologist) you still have to pay co-pays
- Your plan can change mid-year and your physician or facility may no longer be in your network.
- Many people do not expect out-of-pocket costs – they only remember the “free” parts that were advertised in the commercials.
- Should you receive a bad diagnosis – cancer, for example – you may be surprised to find that co-pays come with chemo/radiation which can add up to $6,700 annually, and…
- If you get that bad diagnosis, you may find that if you want to return to original Medicare paired with a Medigap plan – these cost more but can provide more comprehensive coverage – you will have to go through medical underwriting and can be denied coverage.
In other words, these Advantage plans are good if you’re healthy and stay healthy. But, a bad diagnosis could leave you trapped.
Good to know, ya think?
Jim
*\*Joanne Giardini-Russell is a Medicare expert with [Giardini Medicare](https://gmedicareteam.com/).*
————————————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://indfin.com/getting-started/)your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-based registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a*[*proven planning process*](https://indfin.com/ifgplanningprocess/)*coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Medicare, Planning, Retirement
**Tags:** death planning, End of ife, Financial planning, Investment mistakes, investment planning
---
### [RMDs: We're Baaaack!](https://indfin.com/rmds-are-coming-back/)
**Published:** December 14, 2020
**Author:** Jim Lorenzen
**Excerpt:** RMDs are back for 2021! Make sure you don't get his with penalties.
**Content:**
#### The 2020 RMD waiver is coming to an end. They begin again in 2021!
**Jim Lorenzen, CFP*®*, AIF*®***
[](https://indfin.com/wp-content/uploads/2017/05/Crossword_RMD.png)**The headline says it all.**But, this is a blog; so I guess I’d better elaborate a little.
RMDs do NOT apply to Roth IRA owners, unless it’s inherited.
If you take more than the required minimum distribution, that’s not a problem; but, distributions of less than the required amount will result in a penalty: 50% of the RMD shortfall! For example, if your RMD for 2021 is $25,000 and you take only $20,000, you’ll still have to take the $5,000 remainder and the IRS will take 50% of that shortfall amount: $2,500… money you could have used to buy more masks.
There’s a new age for taking RMDs, brought on by The SECURE Act, which I’ve covered in a couple of previous posts. See [The Game Changer](https://indfin.com/secure-act-game-changer/) and this [overview](https://indfin.com/secureact/). Those two posts should bring you up to speed for most issues.
By the way, if an IRA was inherited in 2020, including a Roth IRA, an RMD must be taken for 2021 if the beneficiary is an eligible designated beneficiary is taking distribution over his/her life expectancy. There are rules and exceptions, so be sure to get professional guidance. IRAs inherited in 2021 and forward come under the 10-year rule, covered in the above previous posts.
RMD penalties are high and requesting waivers can result in headaches. It’s best to do it right instead of having to do it over.
Jim
————————————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://indfin.com/getting-started/)your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-based registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a*[*proven planning process*](https://indfin.com/ifgplanningprocess/)*coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Planning, Retirement, SECURE Act, Taxes
**Tags:** Financial planning, Required Minimum Distributions, RMDs, SECURE Act
---
### [To Roll or Not to Roll](https://indfin.com/rollover/)
**Published:** January 7, 2021
**Author:** Jim Lorenzen
**Excerpt:** Rollover advice isn't always straightforward - it's often conflicted. There are issues you should address before you act.
**Content:**
#### That’s the rollover question. Do you have the answer?
**Jim Lorenzen, CFP*®*, AIF*®***
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017c37fc6922970b-320wi.jpg)
Getting rollover advice isn’t always straightforward.
There’s a difference between a “financial advisor” or “financial planner” who really uses “planning” as a vehicle to sell products – yes, Virginia, they do exist – and a true advisor/planner who provides independent and objective analysis as a part of his or her service to clients.
Wasn’t that commercial subtle?
Nevertheless, when deciding whether or not to roll over your company retirement plan to a self-directed IRA, there are considerations and analysis to be considered before making this irrevocable decision.
Here’s a brief – read that as ‘oversimplified’ and incomplete – hint of the types of issues you should consider:
**Sample of 401(k) issues:**
- Maybe no required minimum distributions (RMDs) when you hit age 72 if you’re still working and not a 5% owner of the business you work for. Maybe. You need to check with your plan administrator – some plans still require RMDs even if still employed.
- Expenses in the 401(k) plan may be less. Maybe. This is a murky area as some plans are sold to employers as being ‘free’. It’s a myth, of course, as often costs may be hidden even from the company plan sponsor. Often plans offer a large menu of options, but not all are ‘open architecture’; many are pre-packaged. Your financial advisor should be able to provide a full independent comparison expense analysis of your plan holdings vs. the IRA holdings you’re considering.
- ERISA protections (Employment Retirement Income Security Act) protect your 401(k) assets from creditors (except IRS levies). Only qualified ERISA plans have this protection – 403(b) plans offered by state and local governments might not qualify for this protection.
**Sample of IRA issues:**
- You can contribute as long as you’re working, regardless of age.
- Unlimited menu of investment options. Many do not allow self-directed brokerage
- Not protected by ERISA but rollovers is protected under federal bankruptcy law. Amounts not rolled over (money from other sources) are protected up to $1 million, indexed for inflation every three years.
- Option to convert an IRA to a Roth IRA. You’ll need to pay taxes on the conversion – and they should be paid from other assets to capture the full advantage – and the Roth IRA will need to be funded for at least five years with the owner reaching age 59-1/2 (or disabled) when distributions are made. The current historically low income tax rates are set to expire in 2026 and could be replaced sooner. Taxes appear to be ‘on sale’ now – so this is an attractive option for many taxpayers, particularly in light of the SECURE Act, but that’s another subject (see SECURE Act under Categories on the right side panel of this blog).
Remember to plan BEFORE you act. Ready, fire, aim seldom works out well.
Jim
————————————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://indfin.com/getting-started/)your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-based registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a*[*proven planning process*](https://indfin.com/ifgplanningprocess/)*coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Planning, Retirement, Roth conversions, Taxes
**Tags:** company plan rollover, Financial planning, IRA rollover, Required Minimum Distributions, RMDs, rollover mistakes, SECURE Act
---
### [Medicare: Things May Be Worse Than You Think.](https://indfin.com/medicareproblems/)
**Published:** January 20, 2021
**Author:** Jim Lorenzen
**Excerpt:** Don’t look now, but there are major real problems ahead for Medicare.
And we’re not talking about the “down the road” distant future.
**Content:**
#### So far, no one’s talking about it, either.
**Jim Lorenzen, CFP*®*, AIF*®***
[](https://indfin.com/wp-content/uploads/2020/01/iStock-518900268.jpg)
**Don’t look now, but there are major real problems ahead for Medicare.**
And we’re not talking about the “down the road” distant future.
Medicare was signed into law fifty-five years ago and covers more than 62 million Americans. The are four parts: Part A (hospital insurance), Part B (outpatient services), and Part D (prescription drug coverage). Medicare Advantage comes under Part C, which [I wrote about earlier](https://indfin.com/2020/11/).
Parts B and D are funded through collected premiums and the government’s general revenue fund. Part A is funded by the Hospital Insurance Trust Fund (HI) and covers in-patient care. That trust fund is funded by payroll tax revenue and requires 10 years’ worth of qualified work credits. Like any other budget, income has to exceed expenses for the program to survive.
But, it hasn’t worked out that way. Income hasn’t kept up with the payouts. The depletion has been going on for years and the HI trust is expected to be exhausted by 2026. That’s only five years away. If that happens – and it just might – the HI Trust will be able to pay out only about 90% of Part A expenses.
What does that mean? It means a lot of physicians may just quit accepting Medicare insurance.
**President Biden’s plan for Medicare changes**
The President has talked about two changes he wants to make; unfortunately, neither addresses the HI Trust shortfall.
**1. Allow the federal government to negotiate drug prices with the drug companies.**
Part of the deal President George W. Bush made with the drug companies in passing the Medicare Modernization Act was that the federal government would not negotiate drug prices. This has come back to haunt the U.S, as drug prices have escalated dramatically. Higher drug prices have not only cost the Medicare program more–drug prices have increased to about $97 billion in 2019 from about $44 billion in 2006–they also cost Medicare beneficiaries thousands of dollars in out-of-pocket spending, especially for high-cost specialty drugs.
Allowing the federal government to negotiate directly with the pharmaceuticals on price would save the program an estimated $456 billion between 2023 and 2029, according to the Congressional Budget Office. The drug makers claim they need these revenues for research and clinical trials. Biden’s healthcare plan would also allow people to buy select prescription drugs from other countries. This would provide for a more competitive marketplace that should also effectively lower prescription drug pricing.
Biden’s Medicare plan would prohibit drug makers from raising the price of their prescription drugs faster than the rate of inflation as a condition of Medicare participation. Violators would face a tax penalty.
To succeed, however, the federal government needs negotiating clout – and that’s where the shell-game comes in.
**2. Lower the Medicare eligibility age to 60.**
This step would cover those between age 60 and 64, which would provide an additional 18- 25 million people the option of going on the program. Not all would enroll, of course. Of the 10-14 million who have employer coverage, some would likely keep it.
Why lower the age and add people to the program? The more people enrolled in Medicare, the more clout the federal government has in negotiating drug prices, as well as negotiating prices with hospitals and many outpatient services. Since those between ages 60-64 have less medical care costs than older patients, the average cost per patient would drop.
But, all that advantage comes with a cost: about $200 billion over the next decade, depending on what other reforms are made.
While the program is popular with many Americans, it will face an uphill battle. Hospitals stand to lose billions of dollars in revenue due to Medicare’s lower fee structure. Medicare reimbursement rates for hospital patients average about half what commercial or employer-sponsored insurance plans pay… and the American Hospital Association is one of the biggest lobbies in Congress.
**Back to the HI Trust**
There’s nothing about this in President Biden’s plan. Campaign rhetoric is always hot from the firebrands, both on the right and left. After all, it’s the base that goes out, rings the doorbells, and gets people to the polls. While the Democrats hold a majority in both chambers (the V.P. has the tie-breaking vote in the Senate), neither chamber has a 2/3 supermajority – meaning any significant legislation will have to be bipartisan in order to pass. They are also keenly aware of down-ballot results at the grass-roots level: The Republicans picked up 10 seats in the House (Democrats lost 9 along with 1 independent). In addition, Republicans picked up 1 state governorship bringing their total to 27, vs. 23 for Democrats.
After the political rhetoric dies down (yes, Virginia, I’m dreaming) the course may be more moderate than many on either side expect.
With COVID-19 on the front burner, this may take time… though not much is left.
Jim
————————————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://indfin.com/getting-started/)your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-based registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a*[*proven planning process*](https://indfin.com/ifgplanningprocess/)*coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Medicare, Planning
**Tags:** Medicare planning, Medicare surprises
---
### [Investment Strategy Is About More Than Returns.](https://indfin.com/investment-strategy/)
**Published:** February 4, 2021
**Author:** Jim Lorenzen
**Excerpt:** Investment strategy tied to a plan can be powerful. Doing things a little differently can make a big difference.
**Content:**
#### Asset Location is as important as Asset Allocation.
**Jim Lorenzen, CFP*®*, AIF*®***
[](https://indfin.com/wp-content/uploads/2014/09/iStock_64047885_SMALL.jpg)
**Investment strategy tied to a plan can be powerful. Doing things a little differently can make a big difference.**
Let’s look at a simple example using marginal tax rates of 10, 15, and 25%, and a couple that needs to live off of $65,000 annually in retirement.
If all they’re doing is contributing to a 401(k), that entire $65,000 withdrawal gets taxed at 25%. But, what if they had done some advance planning years ago. Their taxable amount could be reduced.
1. They could take a large chunk of $45,000 from the 401(k).
2. They could take the next $10,000 from a regular taxable account and pay the capital gains rate of 15 or 20%, depending on their situation.
3. They could take the remaining $10,000 from a Roth IRA and pay no taxes on the withdrawal.
They would still have $65,000 but pay far less in taxes. Add up the difference over 20 years!
Three investment buckets will do the trick:
1. Before tax: The 401(k), 403(b), or 457 accounts
2. After tax (a): Taxable accounts where withdrawals can utilize the capital gains rates.
3. After tax (b): The tax-free bucket – Roth IRAs and other tax advantaged strategies.
All you need is powerful technology, flexible solutions, access to good advice, and the right planning tools. Now, where do you suppose those could be found? Hmmmm.
Jim
————————————
**Interested in becoming an IFG client?** Why play phone tag?[Schedule](https://indfin.com/getting-started/)your 15-minute introductory phone call!
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®****Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER®professional and An Accredited Investment Fiduciary®in his 21st year of private practice as Founding Principal of*[*The Independent Financial Group*](https://indfin.com/)*,a fee-based registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a*[*proven planning process*](https://indfin.com/ifgplanningprocess/)*coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group*does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Investing, Retirement
**Tags:** investment planning, Investment Strategy, retirement decisions, Retirement Income, Retirement Planning, Tax-Free Retirement Income
---
### [Noise vs News](https://indfin.com/noise-and-news/)
**Published:** February 24, 2021
**Author:** Jim Lorenzen
**Excerpt:** In a social media world, many believe whatever they read on the internet - and accept credentials at face value. Media noise and news can be hard to differentiate.
**Content:**
#### In a social media world, many believe whatever they read on the internet – and accept credentials at face value. Media noise and news can be hard to differentiate.
**Jim Lorenzen, CFP*®*, AIF*®***
**[](https://indfin.com/wp-content/uploads/2019/07/Meeting_Notetaking.jpg)A long time** **ago** – let’s not talk about how long – I was a young intern at NBC News in Washington, D.C. Besides running a lot of errands, getting coffee, etc., I did learn how a newsroom operates and, even without realizing it at the time, I was learning the difference between news and opinion as well as when and how agendas are advanced. In those days, it was about who got the last word, who got the most film (video today). Subtle stuff.
Today it’s more difficult to differentiate because, in addition to broadcast news, we now have cable news with it’s 24-hour news cycle. Since few, if any, have real news divisions operating across the globe and have to rely on the news divisions of independent network affiliates for domestic feeds (only the major markets have real news divisions), they are forced to fill their 24-hour cycles with either repetition or analysis. News, analysis, and opinion have become intertwined so greatly it’s hard to know which is which. Financial news is no different from mainstream news.
That brings us to the profit motive. Just as newspapers have for centuries relied on increased circulation to boost ad revenue, the media relies on ratings for the same reason. In social media, it’s clicks. It’s true in financial news, as well.
**The name of the game: Clicks and eyeballs.** Sensationalism and controversy sells; ‘normal’ behavior doesn’t. The media leads, the sheep follow. As long as we’re told what to think, we don’t have to think for ourselves – convenient.
Dr. Daniel Crosby, a former clinical psychologist now researching investor behavior for Orion, suggests the following tips (comments are my own):
**Evaluate the source**: Does the individual have the appropriate credentials, and have you verified the credentials are legitimate? Many years ago I encountered a graduating high school senior who proudly announced he’d been accepted to a college I’d never heard of but had a lot of features he liked. The name just didn’t sound like a true institution of higher learning. The student said the school was ‘fully accredited’. I suggested he find out (1) the names of the accrediting organizations, then (2) look them up to see what other institutions they also accredited. He did. He found they accredited a lot of beauty schools and the like. Relief. He had excellent grades and ended-up going to an excellent university where he graduated and is now in grad school.
Reading it on the internet satisfies some – at their peril; knowing the source is critical. You must know if the source is a real ‘doctor’ and verify validity. The ‘doctor’ or ‘expert’ you’re considering could have a criminal record, adopting bogus credentials, or have a long list of negative reviews.
**Question the melodrama:** The four greatest motivators are fear, gain, pride, and imitation. Sensationalism sells and fear is the greatest motivator of all. It gets eyeballs. It gets clicks.
**Examine the tone:** Real news answers who, what, where, when, why, and sometimes how; but, if you hear loaded language or attacks, you’re more likely hearing agenda than real news. Legitimate news organizations clearly separate news from opinion and even have internal processes to ensure the separation. This doesn’t mean agenda aren’t advanced – often it can be more subtle: who gets the ‘last word’ or who gets the video coverage.
**Consider motive:** Remember, eyeballs and clicks are money. News anchor bonuses are based on both. Why do you think many newscasts begin with “Breaking News”, only to hear about a story that’s 10-15 hours old?
**Check the facts:** If something is being presented as fact, what source or research was used for validation? I was lucky enough to have some great professors during my school days. One of the best used to say, “Questions are the beginning of education”. If you don’t ask, you never get the answer. Critical thinking is how we learn. Blind acceptance of things we see or hear often takes us down the wrong path, and the wrong path never takes us where we need to go.
Caveat: Caution is good; as long as it doesn’t lead to paralysis. The right questions, however, can help point the way.
Jim
————————————
**[ Schedule](https://indfin.com/getting-started/) your complimentary “good fit” 20-minute introductory phone call [here](https://indfin.com/getting-started/)!**
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)*Jim Lorenzen CFP® AIF®*
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of* [*The Independent Financial Group*](https://indfin.com/)*, a fee-based registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a* [*proven planning process*](https://indfin.com/ifgplanningprocess/) *coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*Opinions expressed are those of the author. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Investing, Retirement
**Tags:** Investment mistakes, investment planning, Investment Strategy
---
### [Tax-Advantaged is Better than Tax-Deferred! Do you know the difference?](https://indfin.com/tax-advantaged/)
**Published:** October 27, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01910219a734970c-320wi.jpg)*iStock Images*
**Jim Lorenzen, CFP®, AIF****®**
Tax-deferred and tax-advantaged are two termsoften used interchangeably and, as a result, often lead to a lot of confusion; but, the difference can be significant in planning how you will be drawing income from your nest-egg during your retirement years. The key, of course, is to discover your options and do advance planning.
Many employers match employee contributions up to a certain dollar amount to a company-sponsored retirement account, which usually offers tax-deferred growth. Contributing to your account up to the employer match is a significant first step to retirement success.
However, many have found that their company-sponsored plan has proven inadequate due to contribution limits and other factors. Most investors would likely be well served seeking out other sources of tax-advantaged retirement funds. When used properly, tax-advantaged money is taxed up-front when earned, but not when withdrawn. This approach may seem costly; but, that view may very well be short-sighted and far more costly.
Let’s take a look at a hypothetical example of tax-deferred and tax-advantaged money at work. Our fictitious couple, Mitch and Laura, are starting retirement this year and will need $50,000 in addition to their Social Security benefits. Assuming a 28% state and federal tax rate, they’ll actually need to draw $69,444 from their retirement account to meet their needs.\*
**Tax Deferred**
Need = $50,000
Taxes = $19.444
Total Withdrawal required to meet spending need: $69,444
What if Mitch and Laura had balanced their portfolio with a tax-advantaged funding source? What if they could pull the first $30,000 from the tax-advantaged source and the rest ($27,777) from the tax-deferred source? What would that look like?
**[](https://indfin.com/wp-content/uploads/2014/09/its-about-time.jpg)Tax Deferred Combined with Tax Advantaged**
Tax-Advantaged money = $30,000
Tax-Deferred money = $20,000
Taxes = $7,777
Total Withdrawal to meet needs and taxes = $57,777
Because Mitch and Laura balanced their portfolio, **they saved $11,667 each year during retirement – almost 24% of their year’s living expenses each year!** Simple math reveals a savings of over $116,000 during ten years of retirement; and it they’re retired for 30 years, as many are, the savings is over $350,000, not counting what they could have made by leaving the money invested – which could be rather substantial: At just 3.5% annualized, the total would come to over $600,000!
**A Plan that Self-Completes**
Most savings plans, including employer-sponsored retirement plans, are dependent upon someone actually continuing to work and actively contributing to the plan. If work and contributions stop, the plan does not complete itself.
**It’s been my experience that relatively few individual investors have self-completing retirement plans, while a rather large percentage of high net-worth investors do.**
What financial tool can accomplish the goal of being self-completing? Not stocks, bonds, mutual funds, or even government-backed securities of any type. There’s only ONE I know of – and, it’s tax-advantaged, too. Believe it or not, it’s a “Swiss Army Knife” financial tool called life insurance. It’s not your father’s life insurance; it’s specially designed
It can ‘self-complete’ a retirement plan – and it doesn’t matter if the individual dies early **or lives a long life.** Few people realize they can win either way. As I said, stocks, bonds, real estate, commodities, and company retirement accounts simply can’t match it; but, the design must be customized.
If you’d like to learn more about this and other smart retirement strategies, feel free to [contact me](https://www.meetme.so/JimLorenzenCFP).
————–
*\*This has always been a source of misunderstanding for many individual investors: The fact is not all the money in Mitch and Laura’s retirement account belongs to them. Their retirement account might show a $500,000 balance, for example, leading them to believe they have $500,000. The truth is less comforting. The truth is, given a 28% tax-bracket, that $140,000 of that money belongs to the government, not Mitch and Laura. They’ll likely never see it. Their real balance – the one the statement doesn’t show them – is $360,000; and, as we’ve seen, they’ll need to draw-down $69,444 each year to meet their needs. How long do you think that money will last?*
**Disclosures**
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Life Insurance, Planning, Retirement, Taxes
**Tags:** Tax reduction, Tax-Free Retirement Income, Taxes in retirement
---
### [Tax-Advantaged or Tax-Deferred? Do you know the difference?- copy](https://indfin.com/tax-advantaged-or-tax-deferred-do-you-know-the-difference-copy/)
**Published:** June 11, 2018
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01910219a734970c-320wi.jpg)*iStock Images*
**Jim Lorenzen, CFP®, AIF****®**
Tax-deferred and tax-advantaged are two termsoften used interchangeably and, as a result, often lead to a lot of confusion; but, the difference can be significant in planning how you will be drawing income from your nest-egg during your retirement years. The key, of course, is to discover your options and do advance planning.
Tax-deferred investing is familiar to us. Many employers match employee contributions up to a certain dollar amount to a company-sponsored retirement account, which usually offers tax-deferred growth. Contributing to your account up to the employer match is a significant first step to retirement success.
However, many have found that their company-sponsored plan has proven inadequate due to contribution limits and other factors. Most investors would likely be well served seeking out other sources of tax-advantaged retirement funds. When used properly, tax-advantaged money is taxed up-front when earned, but not when withdrawn. This approach may seem costly; but, that view may very well be short-sighted and far more costly.
Let’s take a look at a hypothetical example of tax-deferred and tax-advantaged money at work. Our fictitious couple, Mitch and Laura, are starting retirement this year and will need $50,000 in addition to their Social Security benefits. Assuming a 28% state and federal tax rate, they’ll actually need to draw $69,444 from their retirement account to meet their needs.\*
**Tax Deferred**
Need = $50,000
Taxes = $19.444
Total Withdrawal required to meet spending need: $69,444
What if Mitch and Laura had balanced their portfolio with a tax-advantaged funding source? What if they could pull the first $30,000 from the tax-advantaged source and the rest ($27,777) from the tax-deferred source? What would that look like?
**[](https://indfin.com/wp-content/uploads/2014/09/its-about-time.jpg)Tax Deferred Combined with Tax Advantaged**
Tax-Advantaged money = $30,000
Tax-Deferred money = $20,000
Taxes = $7,777
Total Withdrawal to meet needs and taxes = $57,777
Because Mitch and Laura balanced their portfolio, **they saved $11,667 each year during retirement – almost 24% of their year’s living expenses each year!** Simple math reveals a savings of over $116,000 during ten years of retirement; and it they’re retired for 30 years, as many are, the savings is over $350,000, not counting what they could have made by leaving the money invested – which could be rather substantial: At just 3.5% annualized, the total would come to over $600,000!
**A Plan that Self-Completes**
Most savings plans, including employer-sponsored retirement plans, are dependent upon someone actually continuing to work and actively contributing to the plan. If work and contributions stop, the plan does not complete itself.
**It’s been my experience that relatively few individual investors have self-completing retirement plans, while a rather large percentage of high net-worth investors do.**
What financial tool can accomplish the goal of being self-completing? Not stocks, bonds, mutual funds, or even government-backed securities of any type. There’s only ONE I know of – and, it’s tax-advantaged, too. Believe it or not, it’s a “Swiss Army Knife” financial tool called life insurance. It’s not your father’s life insurance; it’s specially designed
It can ‘self-complete’ a retirement plan – and it doesn’t matter if the individual dies early **or lives a long life.** Few people realize they can win either way. As I said, stocks, bonds, real estate, commodities, and company retirement accounts simply can’t match it; but, the design must be customized.
If you’d like to learn more about this and other smart retirement strategies, feel free to [contact me](https://www.meetme.so/JimLorenzenCFP).
————–
*\*This has always been a source of misunderstanding for many individual investors: The fact is not all the money in Mitch and Laura’s retirement account belongs to them. Their retirement account might show a $500,000 balance, for example, leading them to believe they have $500,000. The truth is less comforting. The truth is, given a 28% tax-bracket, that $140,000 of that money belongs to the government, not Mitch and Laura. They’ll likely never see it. Their real balance – the one the statement doesn’t show them – is $360,000; and, as we’ve seen, they’ll need to draw-down $69,444 each year to meet their needs. How long do you think that money will last?*
**Disclosures**
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Life Insurance, Planning, Retirement, Taxes
**Tags:** Tax reduction, Tax-Free Retirement Income, Taxes in retirement
---
### [Another Way of Looking at Risk](https://indfin.com/another-way-of-looking-at-risk/)
**Published:** October 9, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01b8d073d277970c-320wi.jpg)
Ask virtually any advisor how the risk of an investment is measured, and you’ll likely hear them talk about volatility, mean variance, or [standard deviation](https://en.wikipedia.org/wiki/Standard_deviation "Standard deviation"). I know. I’ve done it myself – and still do. All those terms really refer to is simple price fluctuation around an average.
Most investors don’t like uncertainty, which is a kind of oxymoron since the very essence of investing is uncertainty. After all, if you want certainty you can buy a Treasury bill. Unfortunately, the only thing certain about the Treasury may be certain loss of purchasing power after inflation and taxes; but, I digress.
So, even though we know that price fluctuations come with the territory, instinctively, we want to reduce that volatility as much as possible. If a portfolio is expected to provide a given return over the long term, we want as little deviation from that average as possible. And, since the measure of that variance is called ‘standard deviation’, we want the lowest standard deviation we can obtain.
That’s called ‘optimizing’ a portfolio: Achieving the best return we can for the amount of risk we’re willing to take. The risk, of course, reduces return – something we all instinctively know.
Loss aversion is normally the top priority for most investors who are about to retire. Too often, however, it’s the only thing they care about; and those ‘blinders’ can cause real problems.
Is a lower standard deviation always the best choice? Suppose, given an investor’s portfolio size and spending desires, s/he really needs a higher return to achieve their goals!
Let’s take a look at my rather crude free-hand drawing of a couple of purely hypothetical bell-curves (I never did attend that art school I used to see advertised inside match books).
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01b8d073d02e970c-320wi.jpg)
These two bell-curves don’t represent any investment or portfolio. These bell curves represent two hypothetical portfolios along a return scale.
We’ll pretend tne portfolio averages a 2% return and the other averages 8%. Each curve, of course, represents the number of return observations around the average for each investment. As you can see the portfolio on the left has a narrower curve, meaning that the variance around the average is smaller. The portfolio on the right has a much wider variance, i.e. more price fluctuation around the average.
An investor focused on *only* reducing risk would rather be in the lower deviation portfolio. But, what if this investor needed a higher return to achieve his or her goals?
The investor might say, “I don’t want that much risk?” But, if the lower risk portfolio won’t allow the investor to achieve his/her goals, there are only two options: (1) take on a portfolio with increased volatility, or (2) reduce the goals in the plan.
*“I looked in the mirror and saw what I didn’t want to see. It was a bad day.”*
*– Marie Osmand*
So, how do we deal with this? Many advisors have begun touting a “bucket” strategy, which refers to earmarking certain investments for certain goals in various ‘time’ buckets (sometimes the strategy also helps sell a prepackaged investment product). The problem, of course, is that each year or so, as time goes by, dollars have to be shifted from one bucket to another simply because each given goal is now closer in time. This can create unnecessary cost and, in a taxable account, some issues at tax time.
The particular strategy chosen can vary based on an investor’s financial and personal profile and is best discussed with a qualified planner. The important point here is that the risk you assume may be the one you have to assume, if you’re not prepared to make other adjustments. By the same token, making the right adjustments may be the best first answer.
Jim
—————–
**How much risk is in YOUR current portfolio?** If your retirement portfolio is over $500,000, you can take the [first step](https://tinyurl.com/RiskNumber) in learning your risk number and [schedule](https://tinyurl.com/IFGIntroCall) a 15-minute introductory call using IFG’s convenient [scheduler](https://tinyurl.com/IFGIntroCall).
RESOURCES:
[**Jim’s Social Security Learning Center**](https://www.jlorenzen.sswise.com/ "Social Security Learning Center")[](https://www.typepad.com/site/blogs/6a017c332c5ecb970b017ee4d0333b970d/post/6a017c332c5ecb970b01a73ddd02ba970d/www.jlorenzen.sswise.com "Jim's Social Security Learning Center")
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Conversation Checklist") (does not require registration)
[Subscribe to IFG Insights ](https://tinyurl.com/IFGInsights "Subscribe to IFG Insights")
[The IFG Website](https://indfin.com/ "IFG Website")
IFG’s [Financial Resources website](https://finsecurity.com/Lorenzen "IFG Financial Resources Website").
Follow Jim on Twitter: @JimLorenzen
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [The Financial Security Gap](https://indfin.com/the-financial-security-gap/)
**Published:** October 2, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01b8d06b519e970c-320wi.jpg)**The Disconnect Between Illusion and Reality**
Helen Keller once remarked, “Security is largely superstition; it doesn’t exist in nature.” Maybe not; but, if history is any guide, “The Greatest Generation” – the Depression & World War II generation – were far more secure than their children or grandchildren.
These people were the savers. They didn’t travel extensively during their working years. Nor did they eat in expensive restaurants or buy cars they couldn’t afford. This was the generation that hated debt and paid cash for everything, save a house or maybe a car. They were happy with one tv set. That generation had long term goals and saved for them. Their most important goal was to never be dependent on anyone but themselves. Ever.
My parents were typical of their friends. They saved during their working years and retired at a lifestyle that allowed them to travel spending the “fruits” of their investing years… a far cry from many in later generations who’ve become accustomed to spending their retirement money before they get there.
A recent survey reflects the growing gap.[\[1\]](file://notebook/documents/LAPTOP%20DESKTOP/INVESTMENT%20ADVISORY/MARKETING/BLOG-EZINE-NL%20PREP/Financial%20Security%20Gap.docx#_ftn1) Here are a few interesting takeaways:
- Americans appear to believe their life insurance benefits should cover about 14 years of expenses after the loss of a breadwinner. How much protection do most Americans actually have in place? About 3 years.
- 60% of Americans believe they have enough life insurance in place. But, according to New York Life’s survey and computations, about 20% actually do.
- Today about 68% of Americans feel financially secure, down from 87% in 2008.
The last bullet point may be explained by the credit market meltdown that occurred in 2009. Nevertheless, there appears to be a huge disconnect between expectations and the realities of life likely grounded in the noticeable lack of personal financial planning education in our system; then again, maybe not. For many in the World War II generation, education came through the hard and bitter experience of the Great Depression.
While many believe their 401(k)s represent their total retirement plan, the growing reality is, especially for upper income earners, those 401(k)s and IRAs are simply and only a foundation – a starting point only, and a fact that represents another gap between illusion and reality. To understand retirement is to understand the tax code and how to create retirement ‘building blocks’.
Example: IRA guru Ed Slott[\[2\]](file://notebook/documents/LAPTOP%20DESKTOP/INVESTMENT%20ADVISORY/MARKETING/BLOG-EZINE-NL%20PREP/Financial%20Security%20Gap.docx#_ftn2) (you’ve seen his retirement tv shows, some raising money for PBS) has called cash value life insurance one of the greatest benefits in the income tax code; and, he might be right. After all, it accumulates without current taxation and can be paid out while alive without taxation – it can also be paid to heirs tax-free. And, all of this occurs while protecting your family, business, and debtors from premature death. How else could anyone create an instant estate with the stroke of a pen? Yet, many, if not most people view life insurance as little more than an expense or gamble with an insurance company. It should be noted, however, that there must be a need for the death benefit – a need for protection – for life insurance to make sense as a building block.
While many advisors, yours truly included, do go out of their way to conduct educational sessions for clients so they will understand the reasoning behind the decision-making process in mapping retirement strategies, many people find it much of the “information overload” as confusing. Adding to the confusion is the proliferation of financial infotainment masquerading as education when, sadly, real education is usually found in rather boring textbooks and seldom in glitzy packaging.
Rather than waiting for the government to provide financial education to the masses – courses they could use themselves – it’s really up to all of us to take on the responsibility to educate ourselves and secure the future to ourselves and those in our family who will remember us as someone who cared – or didn’t.
[\[1\]](file://notebook/documents/LAPTOP%20DESKTOP/INVESTMENT%20ADVISORY/MARKETING/BLOG-EZINE-NL%20PREP/Financial%20Security%20Gap.docx#_ftnref1) *Retirement Advisor*, August 2014; New York Life’s life insurance gap survey
[\[2\]](file://notebook/documents/LAPTOP%20DESKTOP/INVESTMENT%20ADVISORY/MARKETING/BLOG-EZINE-NL%20PREP/Financial%20Security%20Gap.docx#_ftnref2) It should be noted that Ed Slott is one of the few – maybe the only – gurus on television that actually is a licensed and credentialed practicing advisor – and one who actually has real clients and accountable to the regulators.
===============
**RESOURCES:**
**IFG’s Financial[ Resources website.](https://tinyurl.com/IFGSecurity%20 "Resources website")**
**Visit**[**Jim’s Social Security Learning Cen**](https://www.jlorenzen.sswise.com/ "Social Security Learning Center")**[ter](https://www.jlorenzen.sswise.com/ "Social Security Learning Center")**[](https://www.typepad.com/site/blogs/6a017c332c5ecb970b017ee4d0333b970d/post/6a017c332c5ecb970b01a73ddd02ba970d/www.jlorenzen.sswise.com "Jim's Social Security Learning Center")
**[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Conversation Checklist")** (does not require registration)
[Subscribe to IFG Insights ](https://tinyurl.com/IFGInsights "Subscribe to IFG Insights")
[The IFG Website](https://indfin.com/ "IFG Website")
Follow Jim on Twitter: @JimLorenzen
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [The Financial Tool That Solves Many of Life's Problems!](https://indfin.com/the-financial-tool-that-solves-many-of-lifes-problems-see-more-at-httpwww-jimsmoneyblog-com201408theres-more-to-retirement-planning-than-simply-saving-money-and-hoping-everything-gets-cove/)
**Published:** August 19, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a3fd41160b970b-320wi.jpg)**There’s more to retirement planning than simply saving money and hoping everything gets covered. Much more is possible if you know how to use the tools.**
Few people outside the financial industry understand the power of life insurance as a planning tool. It’s understandable: When most people think of life insurance, the (often) typical reaction is often something like, “I don’t believe in insurance. Those big insurance companies are just placing bets and making a lot of money.”
Of course, I refrain from asking them about their auto, homeowners, and health insurance – all insurance they actually *hope* they’ll never use – but, I digress.
But few people think of life insurance as a tool that actually can solve a problem! Here’s an example:
Otto Schmidlap (if you remember that name, you’re as old as I am) purchased $25,000 of publicly-traded stock several years ago. That stock is now worth $100,000. If Otto sells the stock, he’s staring a at a capital gains tax on the $75,000 gain.
But, if Otto donates the stock to his favorite qualified charity, he can get a $100,000 deduction on his tax returns. Now, the charity can sell the stock and there’s no capital gains tax is due on the appreciation.
But, wait! How about Otto’s poor heirs! They might have inherited that $100,000!
**Life Insurance: The tool that does the job**
In order to replace the value of the assets transferred to the charity, Otto establishes an irrevocable life insurance trust ([ILIT](https://en.wikipedia.org/wiki/Life_insurance_trust "Life insurance trust")) – and the trustee acquires life insurance on the Otto’s life in an amount equal to the value of the charitable gift, in this case $100,000.
How are the insurance premiums paid? Otto, using the charitable deduction income tax savings and any annual cash flow from a charitable trust (or [charitable gift annuity](https://en.wikipedia.org/wiki/Charitable_Gift_Annuity "Charitable Gift Annuity")), makes gifts to the irrevocable life insurance trust that are then used to pay the life insurance policy premiums. Sweet.
When Otto dies[\[1\]](file://notebook/documents/LAPTOP%20DESKTOP/INVESTMENT%20ADVISORY/MARKETING/BLOG-EZINE-NL%20PREP/Wealth%20Replacement%20Trusts.docx#_ftn1), the life insurance proceeds generally pass to the donor’s heirs free of income tax and estate tax, replacing the value of the assets that were given to the charity.
The charity won and the heirs were protected. Not bad.
Try doing THAT without life insurance! Sometimes, it IS the tool that does the job.
What do YOU want to accomplish? If you and your spouse haven’t had a discussion about what you want your money to accomplish, click on:[financial conversation checklist](https://indfin.com/financial-conversation-checklist "Financial Conversation Checklist"). I think you’ll find it helpful.
Jim
---
[\[1\]](file://notebook/documents/LAPTOP%20DESKTOP/INVESTMENT%20ADVISORY/MARKETING/BLOG-EZINE-NL%20PREP/Wealth%20Replacement%20Trusts.docx#_ftnref1) Unlike auto or homeowners insurance, life insurance (if kept in place) is ONE insurance policy that WILL be used. And, the return to the family, compared to how much was paid-in in premiums, can be quite high – do the math for yourself!
**RESOURCES:**
**Visit** [**Jim’s Social Security Learning Center**](https://www.jlorenzen.sswise.com/ "Social Security Learning Center")[](https://www.typepad.com/site/blogs/6a017c332c5ecb970b017ee4d0333b970d/post/6a017c332c5ecb970b01a73ddd02ba970d/www.jlorenzen.sswise.com "Jim's Social Security Learning Center")
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Conversation Checklist") (does not require registration)
[Subscribe to IFG Insights ](https://tinyurl.com/IFGInsights "Subscribe to IFG Insights")
[The IFG Website](https://indfin.com/ "IFG Website")
IFG’s [Financial Resources website](https://finsecurity.com/Lorenzen "IFG Financial Resources Website").
Follow Jim on Twitter: @JimLorenzen
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [What Will Happen To My Child If I'm No Longer Here?](https://indfin.com/what-will-happen-to-my-child-if-im-no-longer-here/)
**Published:** October 16, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01bb0794f4d3970d-320wi.jpg)**If you have a special needs child or grandchild, planning becomes especially important.**
We have special needs children in my own family; and we’re far from alone. If you’re a family dealing with this issue, there are some things that can’t be ignored.
To a large degree, the answer to the headline question will depend on the steps you begintaking today in order to arrange for your child’s future well being.
Planning for special needs children is a complex process that begins with an initialassessment. In planning for your special needs child, there are certain initial steps youshould take, such as:
1\. Assess your child’s prognosis: Will your child ever be able to earn aliving…manage assets…live independently? Your evaluation of issues such as thesewill then guide you in the type of planning you need to complete in order to provide foryour child. If you’re unsure about your child’s future prognosis, be conservative in yourassumptions. You can always change your plans in the future.
2\. Review your financial situation: What assets do you have available to provide foryour child’s future financial needs? What can you do to accumulate additional assetsfor your child’s care?
3\. Living arrangements: Where do you want your child to live after your death, or ifyou become physically unable to care for your child? Will your child need a guardian(or conservator)?
4\. Government benefits: Do you know what government benefits are available andwhat the requirements are to qualify for these benefits? Government benefits and theirrequirements can play a major role in your child’s future well being. Be aware, however,that improper or careless planning could make your child ineligible for certain benefits.
**Government benefits fall into two groups**:
**Entitlement Programs**: Eligibility for entitlement programs is based on meetingcertain requirements, such as age, disability or blindness. An individual who, forexample, meets the required definition of disability is entitled to receive benefits,regardless of that individual’s financial situation.
**Needs-Based Programs**: In order to receive benefits from a needs-basedprogram, a disabled individual cannot have income or assets above statedamounts.
Putting your child on a firm, secure footing is all about your own planning preparation. Maybe this Special Needs Life Guide will help. It’s fillable, so you can use it and save it to your own computer.
Just click on: [Download IFGi\_LifeGuide\_Planning\_Children\_Special\_Needs\_fillable\_vsa](https://jimlorenzen.typepad.com/files/ifgi_lifeguide_planning_children_special_needs_fillable_vsa-1.pdf)
Pardon the commercial; but if you’d like to learn about IFG’s planning services, you can avoid the phone tag and schedule a brief 15-minute introductory phone call by using our [convenient scheduler.](https://tinyurl.com/IFGIntroCall%20 "IFG Scheduler")
Jim
——————
**RESOURCES:**
**How much risk is in YOUR current portfolio? If your investment portfolio is over $500,000, it will help you to know** [YOUR “risk number”](https://pro.riskalyze.com/embed/e2caceca86722d4b959d)**?**
[**Jim’s Social Security Learning Center**](https://www.jlorenzen.sswise.com/ "Social Security Learning Center")[](https://www.typepad.com/site/blogs/6a017c332c5ecb970b017ee4d0333b970d/post/6a017c332c5ecb970b01a73ddd02ba970d/www.jlorenzen.sswise.com "Jim's Social Security Learning Center")
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist "Conversation Checklist") (does not require registration)
[Subscribe to IFG Insights ](https://tinyurl.com/IFGInsights "Subscribe to IFG Insights")
[The IFG Website](https://indfin.com/ "IFG Website")
IFG’s [Financial Resources website](https://finsecurity.com/Lorenzen "IFG Financial Resources Website").
Follow Jim on Twitter: @JimLorenzen
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://tinyurl.com/IFGIntroCall%20 "Schedule your 15-minute introductory call!")!
***Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of*** [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
*The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Do You Know the Value of Your Business?](https://indfin.com/do-you-know-the-value-of-your-business/)
**Published:** May 29, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73de5d743970d-320wi1.jpg)**… Why Should you care?**
You invested, probably heavily, in your American Dream; and you have a lot riding on it.
Before you can cash-in on what you’ve built, you’ll have to quantify what you’ve accomplished. That’s when you’ll be able to explore your options, choose your path, and make the moves that matter.
Years ago, when I was in the publishing business, it was before the internet era; in fact, it was even before 5-1/4-inch floppy-disk computers with A and B drives, I would have loved to not only know what my business was worth on a constant basis, but to know how each decision I was making was acutally impacting business value. Today, business owners don’t have to fly blind, unless they want to.
Business owners do make decisions every day – indeed, many have their entire net worth invested in the decisions they make – yet, few know, in advance, just how those decisions will impact business value.
According to the Small Business Administration, insufficient knowledge about business value is one of the top two challenges facing small business owners and leaders. That’s because companies that DO understand their worth are better positioned to pursue growth initiatives, attract and reward talent, and ensure proper credit and risk management.
Whether you are a sole owner, in a partnership, or part of a corporate executive team with equity in the enterprise, knowing business value can help you when you:
- Seek debt or equity financing
- Pursue new business & expansion initiatives
- Apply for a business loan
- Make a business acquisition
- Value a buy-sell agreement
- Prove you’re a reliable supplier
- Assess how you should value your business for estate planning purposes
- Determine how much insurance you need to protect your family & assets
- Gauge whether another company is a good strategic partner
- Need to know how business decisions actually impact business value
- Want to quantify business value for the sale of the business or your equity interest
Knowing your business’ valuerepresents the “on-ramp” to almost everything you need to do to accomplish a variety of objectives. It helps business owners answer the most important question they face before engaging in any financial decision-making conversation:
**What’s my business worth?**
It’s about insight: Knowing where you stand and where you may be headed.
Good luck!
—-
**Arrange a brief15-minute introductory phone call with Jim Lorenzen, CFP®, AIF®** [**here**](https://tinyurl.com/IFGIntroCall)**.**
**Social Security** – The wrong claiming strategy could conceivably cost hundreds of thousands of dollars! Knowledge is more than power; it’s real money. You can learn how to [get to the right strategy](https://tinyurl.com/SocialSecurityStrategies) with the right planning.
**College Planning and Funding Strategies** – Just like with the airlines, there are often two prices people pay for the same education: The price paid by the informed and the price paid by the uninformed. What are the projected four-year costs for the college your student desires? How much scholarship money will your student qualify for? You can see a short video, *“A Lesson in Paying for College”,* and download a free report, “*Insider Strategies and Secrets to Reducing your College Costs.”* You can learn more on the [IFG College Funding site](https://www.ifgcollegefunding.com/).
**Financial Planning and Investing:**
IFG Report:Understanding Mutual Funds
IFG Report: The Hidden Risk No One Talks About (Registration required)
Begin the discussion with your spouse with this [Financial Converstion Checklist](https://indfin.com/financial-conversation-checklist). (No registration required)
Facing financial decisions but feel you need to do some homework first? You might benefit from looking through our free [Life Guides](https://tinyurl.com/IFGLifeGuides) and using some [financial worksheets](https://tinyurl.com/IFGWorksheets)!
Visit the[IFG Website](https://indfin.com/)!
Follow Jim on Twitter: [@jimlorenzen](https://twitter.com/JimLorenzen)
and also [Jim’s MoneyBlog](https://www.jimsmoneyblog.com/)
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp)
IFG on [Facebook](https://www.facebook.com/IFGAdvisory)
Become an IFG client! [Schedule your 15-minute introductory phone call here](https://www.timetrade.com/book/F7ZPS)!
———————
Jim Lorenzen is a[ *CERTIFIED FINANCIAL PLANNER®*](https://en.wikipedia.org/wiki/Certified_Financial_Planner) professional and An Accredited Investment Fiduciary® in his 21st year of private practice.
The Independent Financial Group is a fee-only registered investment advisor with clients located across the U.S. He is also licensed for insurance as an independent agent under California license 0C00742.Jim can be reached at 805.265.5416 or (from outside California) at 800.257.6659.
**Interested in becoming an IFG client?** Why play phone-tag? You can easily [schedule your 15-minute introductoryphone call!](https://www.timetrade.com/book/F7ZPS)
The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Retirement is Different!](https://indfin.com/retirement-is-different/)
**Published:** May 27, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73de5d743970d-320wi2.jpg)**If you’re planning your retirement about now, it’s worth coming to this realization: You’re entering a new stage of life.** It’s a simple statement; but, don’t confuse it as being simplistic.
You’ve been accumulating assets up to now; and, during accumulation, negative market fluctuations are not only partially masked by your ongoing contributions, they even allow you to gather additional positions at reduced prices.
**Your new stage, however, is different**. Instead of accumulating, you’ll be entering a drawdown phase of life… a phase where negative market moves will be magnified by the fact you’ll be drawing on assets, which will further deplete your account values.
How long will your money last? It depends on how much you’re drawing; but, a number of factors impact that decision:
**Your Age and Health**
How long will you live? No one really knows, of course. Most people, in my experience, simply take a guess, usually colored by their wishes. Some are so afraid of running out of money, their knee-jerk answer is simply, “I won’t live that long.” Others will examine their parents’ lives and health issues – not a bad idea – to come up with a guesstimate.
The Social Security Administration has a number of calculators you might find useful at . Another, maybe more useful one I found is at .
**Inflation**
Every family has an economist in residence: The one who does the grocery shopping. But, anyone who fills a gas tank has seen inflation first hand, too. Money is worth only what it will purchase. And, when it purchases less, you need more of it to buy the same things.
Simple concept, I know; but, here’s the kicker: The inflation figures you see that are put out by the government are (sorry) a joke:**The government’s inflation figuresDO NOT include food or energy: The two things EVERY retiree (and every other living member of the human species) will use.**
While not all expenses will inflate (a fixed mortgage or one that’s paid-off), it’s a good bet that most expenses will – and at a rate higher than the government will admit to as they attempt to reduce what they will be required to pay out in Social Security benefits. After all, the government has a ton of debt and is running at a deficit; so, keeping outlays down (while bragging about low inflation numbers) works for them, but won’t help you (sorry, I need to enroll in a 12-step program, I know). An example of a potential hyper-inflation risk is one most retirees will need to address: Medical care. Coverage may be universal; but, deductibles above and beyond rising premiums will be an issue for many.
Many advisors are using rates between 3 and 4%; but, a number of well-respected advisors are looking back at, and using, a 30-year average, closer to 4.5%, when they plan the next thirty years with their clients. My parents retired in 1974 and soon thereafter entered a period of hyper double-digit inflation and interest rates. My dad lived 31 years in retirement and my mom passed away earlier this year at age 99. That’s a lot of inflation. Anybody remember how much a postage stamp cost in 1974?
**Variability of Investment Returns**
Here’s a statement of opinion you may find startling: There is no more meaningless statistic you’ll ever encounter than “average annual return” when you’re retired and need to make your money last. Two bigger issues are (1) variability and (2) sequence of returns. You may be able to manage one; but, you’ll have no control over the other.
For example – purely hypothetical – if a portfolio worth $500,000 incurred successive annual declines of 12% and 7%, its value would be reduced to $409,200, and it would require a gain of nearly 22% the next year to restore its value to $500,000.3 It’s a simple concept: A 20% loss on $100,000 becomes $80,000. But, it takes a 25% gain to offset that 20% loss. What if you had to take retirement income of $10,000, too? You get the idea. To get a clearer idea of how volatility can impact retirement outcomes during the “drawdown” phase of life, you may want to read my report, “[*The Hidden Risk No One Talks About*](https://tinyurl.com/TheHiddenRisk%20 "IFG Hidden Risk Report")“.
How do you counteract all this bad news? Do you stick money in the mattress? Bury it in the back yard? Maybe you pay for an expense-laden “guaranteed” packaged product that makes you feel good?
They answer is simple, but again, not simplistic: a solid financial retirement plan. Ideally, you’d begin when you’re young, in your early 30s at least; but, few do that. However, if you’re within ten years of retirement and haven’t done it yet, it’s time to start – yesterday.
There are excellent *Certified Financial Planner®* professionals everywhere (literally all over the world). You can find one on the [CFP Board website](https://www.cfp.net/utility/find-a-cfp-professional "CFP Board"). CFPs who are also members of the Financial Planning Association (FPA) can be located on [FPA’s website](https://www.plannersearch.org/Pages/home.aspx "FPA Website").
You also may like looking around [my resource site](https://finsecurity.com/Lorenzen "Jim's Financial Resource Site"). You can also learn about Social Security planning on our [Social Security Learning Center](https://tinyurl.com/IFGSSWise "IFG SS Learning"); just scroll down on the first page.
By the way, John Wasik has written an excellent article on why early retirement seminars are (his opinion) scams. You can click on the icon below to read it (you’ll have to skip past an ad – it was posted on Forbes’ website).
Enjoy!
Jim
—-

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Retirement Planning Requires Strategy](https://indfin.com/retirement-planning-requires-strategy/)
**Published:** June 3, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a3fd0c994a970b-320wi.jpg)We’re living longer. No news. During your working years you’re saving and accumulating assets. That’s not normally the case for those who retire.
Retirement is the”drawdown” phase of life: a sort of a marathon: Which will last longer – you or your money?
Just how successful your retirement is depends on how much you have at retirement and how much you spend IN retirement. Yes, achieving high returns would help; but, you can’t control interest rates, inflation, or the markets. While they can be managed to some degree, the only thing you can control is saving and spending.
**How much can you withdraw?** To a large degree, that depends on how long you live! While the [average life expectancy](https://en.wikipedia.org/wiki/Life_expectancy "Life expectancy") has risen steadily in the United States, is now reaching 78.2 years,¹ it’s worth remembering those numbers are based on full lives, counting everyone beginning at birth! – so, those numbers may have little to do with you. Your lifestyle, health, and your parents’ history all have an impact. You might want to check-out [this site](https://www.livingto100.com/) to maybe get a better idea of your own life expectancy. Today, it’s not uncommon for retirement to last three decades! If you’re married, two lives for three decades is a tall order.
**Inflation: The Invisible Danger**
Whatever drawdown rate you choose, you’d better crunch some numbers: Can you sustain that rate – with annual inflation adjustments – during the entire length of retirement without running out of money?
What inflation assumption should you use? I wouldn’t use the U.S. consumer price inflation numbers. According to government, inflation has averaged under 3% over the past 30 years.2Too bad the government numbers don’t include food or energy – people are often shocked when they find this out.
For long-term planning many top advisors assume that inflation will average in the range of 3% to 4% a year; but some of the most respected advisors are even using numbers north of 4%!
Be careful, though, of what one of America’s elite advisors, Harold Evensky, CFP®, calls “*The Retirement Income Myth[**\[\*\]**](https://www.typepad.com/site/blogs/6a017c332c5ecb970b017ee4d0333b970d/post/compose#_ftn1)”* During my twenty-three years in the financial industry, I’ve noticed that many companies are very good at identifying fears and addressing them with by creating “too good to be true” products and marketing them through dinner seminars. Fear sells – and the biggest fear most people have today is [longevity risk](https://en.wikipedia.org/wiki/Longevity_risk "Longevity risk"): fear of outliving their money; so, it’s no surprise the industry has responded by manufacturing products with guarantees to relieve those fears. The problem, of course, is there’s no free lunch – and those guarantees cost money that could otherwise be use to fund your retirement. There’s no substitute for quality planning, managing expectations, and sticking to a discipline when others are reacting from fear (a sign they DON’T have a plan).
**Hidden Risk #2: Portfolio Volatility and Sequence of Returns**
Average annual return figures may be useful during the accumulation stage of your life; but, during the drawdown phase, it may be the most worthless statistic you’ll ever be subjected to. Volatility and the sequence of returns will be far more important. For more on the ‘sequence’ risk, you may want to look at my ‘Hidden Risk” report.
A quick lesson on volatility: A $100,000 portfolio that suffers a 20% loss goes to $80,000. It would take a 25% gain from $80,000 to get back to $100,000. A 25% gain to make up for a 20% loss – that’s without withdrawals! If you’re in retirement and assuming you can withdraw 5% a year while this happens, the numbers look very different: At the end of the first year, you’d have $75,000 because of the withdrawal. Now you’d need close to a 27% return just to get to $95,000, where you thought you’d be if the market hadn’t suffered it’s decline.
As you can see, it’s about managing the downside
Jim
1Source: Center for Disease Control, March 2012 (based on 2009 data, latest available).
2Source: Bureau of Labor Statistics, January 2014.
[\[\*\]](https://www.typepad.com/site/blogs/6a017c332c5ecb970b017ee4d0333b970d/post/compose#_ftnref1) *The New Wealth Management*, Evensky, Horan, Robinson, John Wiley & Sons, Inc. 2011

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Longevity Risk Worries Investors](https://indfin.com/longevity-risk-worries-investors/)
**Published:** February 20, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a3fcbc2c3d970b-320wi.jpg)**Enter Longevity Insurance– But Look Closely Before You Buy.**You name the fear, the financial industry will come up with a solution to sell.
**These days, the fear is outliving our money.** Indeed, we are living longer… and all those extra years cost money.
**Enter longevity insurance**. Like all financial products, there are good points and others not so good. It pays examine the pros and cons in light of your own needs before you buy.
**First, what it is:** Longevity insurance is generally nothing more than a single premium deferred annuity with a specified start date for making payments. For example: A 65 year-old can purchase an annuity today; but the annuity doesn’t begin making payments until age 85. Once payments begin, they continue for life.
**Why insurance companies can do it:** Insurance companies know that because the life expectancy of a typical 65 year-old Caucasian woman is about 20 years, about half likely won’t live to collect and about half will. Those that do will diminish in numbers as each year passes.
But, it’s not all roses. It pays to know what you’re buying.
Longevity insurance is generally nothing more than a single premium deferred annuity with a specified start date for making payments. For example: A 65 year-old can purchase an annuity today; but the annuity doesn’t begin making payments until age 85. Once payments begin, they continue for life.
Of course, insurance companies know that because the life expectancy of a typical 65 year-old Caucasian woman is about 20 years, about half likely won’t live to collect and about half will.
It should come as no surprise that the payouts on longevity insurance are higher than what a purchaser would receive for a normal annuity. The reasons are simple: (1) about half will never collect, as stated above, (2) those who do collect – the other half – will be fewer and fewer as the years progress, and (3) the insurance company has many years to invest the money between the date of purchase and the date that payments begin – in our example, 20 years!
**The good news:**Longevity insurance allows retirees to plan for their later years with greater certainty. As most planners will tell you, it’s the second and third decade of retirement that can be the most dicey because of taxes and inflation.
**There are some limitations, however, worth noting:**
- Inflation will reduce the purchasing power of future payments. What may sound like a good payout today may not be so good when the day comes.
- The after-tax value of those payments may be reduced if/when tax rates increase. Because of the fixed cash flow, it will be hard to do tax planning with that income.
- The purchaser does lose control over whatever portion of the retirement portfolio that is used to contribute to the annuity. That money can’t be independently invested or easily accessed if Murphy’s Law happens. An annuity, after all, is basically an insurance company I.O.U. and the money is in the company’s control.
There is pending legislation that would allow taxpayers to purchase longevity insurance inside retirement accounts (Reg 115809-11) and also allow taxpayers over age 70-1/2 who hold those annuities in those accounts to exclude their value when calculating their required minimum distributions (RMDs).
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Is Avoiding a Down Market Smart? Maybe not.](https://indfin.com/is-avoiding-a-down-market-smart-maybe-not/)
**Published:** October 24, 2013
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019b00066606970c-320wi.jpg)Does it make sense to invest in down markets? Some people simply quit investing and avoid the market altogether. This may be the wrong decision! Here’s a little exercise might provide a clue as to why most investment experts advise consistent investing. In our example, the price of our fictitious investment begins and $50 and goes down. In fact, it takes 10 years just to get back to it’s initial price. Did systematic investing seem worthwhile? You be the judge.
**Systematic Investing During Difficult Times**
**Market**
**Year**
**Price**
**$ Amt**
**\# Shares**
**$ Amt**
**# Shares**
**Cum # Sh**
1
**$50**
$20,000
400.000
$2,000
40.000
40.000
-20%
2
$40
0
$2,000
50.000
90.000
20%
3
$48
0
$2,000
41.667
131.667
-25%
4
$36
0
$2,000
55.556
187.222
20%
5
$43
0
$2,000
46.296
233.519
-30%
6
**$30**
0
$2,000
66.138
299.656
20%
7
$36
0
$2,000
55.115
354.771
20%
8
$44
0
$2,000
45.929
400.700
-10%
9
$39
0
$2,000
51.032
451.732
28%
10
**$50**
0
$2,000
39.869
491.600
Totals
$20,000
400
$20,000
491.600
Portfolio Value
$20,066
$24,661
Average Cost per Share
$50
$40.68
Value Per Share
$50
$50
Profit Per Share
$0.16
$9.48
**Portfolio Profit**
**$66**
**$4,660.91**
Point: Our ‘systematic’ investor averaged a compounded 4.57% per year in a ‘flat’ market while the person who made a one-time purchase was virtually at a zero return ($66 over 10 years on a $20,000 investment).
If you’re young, down markets just might be good! Markets have always gone down; but, I’ve never seen one STAY down. In fact, new highs have historically been unvoidable! So, you may want to make the most of the ‘downs’ when you can.
Unfortunately, for many, retirement planning will often fail. You may be interested to learn why in this[free report](https://indfin.com/why-retirement-planning-can-often-fail "Why Most Retirement Planning Will Probably Fail").
You also may be interested in receiving my e-zine,[IFG Insights](https://tinyurl.com/IFGInsights%20 "Subscribe to IFG Insights"), that addresses retirement issues.
Jim
**RESOURCES:**
IFG Report:[The Hidden Risk No One Talks About](https://tinyurl.com/TheHiddenRisk)(registration required)
[A Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist)(does not require registration)
[Subscribe](https://tinyurl.com/IFGInsights)to IFG’s Ezine: IFG Insights
[The IFG Website](https://indfin.com/)
Follow Jim on Twitter:
Jim on[LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen's LinkedIn Profile")
IFG on[Face book](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
*This example is presented as an illustration for educational purposes only and does not represent any investment or index. No conclusions about the future of any investment or index should be drawn from this example.**Jim Lorenzenis a CERTIFIED FINANCIAL PLANNERâ„¢ and in his 22nd year of private practice as Founding Principal of The Independent Financial Group, a fee-only registered investment advisor with clients located inNew York, Florida, and California. Nothing contained in this material is intended to constitute legal, tax, securities, or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional. Nothing contained herein is an offer or recommendation to purchase any security or the services of any person or organization.*

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Ten Tips for Happiness](https://indfin.com/ten-tips-for-happiness/)
**Published:** May 2, 2013
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01901b938b2c970b-320wi.jpg)1. LOVE YOURSELF**– It is the nucleus for all motivation. You have to feel good about yourself! A good place to begin is your physical appearance. Take care of yourself! When you look good, you feel good. **2. SEEK THE LOVING LIFE**– Helping people also makes you feel good! When you can focus your attention on others, you feel better about yourself as a person. Besides, it always comes back.
**3. JOIN THE WORK WORLD**-Many people complain about work – some retirees claim they don’t miss it – but mostfeel work is essential to happiness. Money isn’t the only motivation…consider volunteer work. Here, I consider myself very fortunate: My profession is all about it. Sometimes people ask me if I’m retired; I tell them, “I don’t know!”
**4. ENJOY THE POWER OF TOUCH**– People put up a lot of barriers to touching. Some equate it to either sex or violence.Too bad.Touching helps to affirm friendship, approval, caring, etc. We too often avoid the simple acts of touching that confirm good will.
**5. LIVE ONE DAY AT A TIME**– Many of us spend much of our “today” worrying about yesterday or tomorrow. Since the past won’t change and the future may never come, forget them and enjoy the day – everyday! This is a lesson I learned from golf: Stay in the present. You can only control what you do NOW.
**6. TURN ON THE LAUGHTER**– A sense of humor is the first indicator of intelligence. If you can’t laugh, it’s time to seek help. Humor can take the sting out of failure and stupidities. It can help us overcome the worst of our experiences. We “look back and laugh” – start looking for the laughs now!
**7. MOVE YOUR MUSCLES**– Exercise can increase self esteem, relieve anxiety, improve attentiveness, dissipate stress, and elevate moods. Active people seem to be happier. Try walking more. Some people like morning walks or trips to the gym. When I play golf, I walk the course and I often feel better after the round than before I started.
**8. SEARCH FOR MEANING**– Develop a set of “guiding principles,” a “belief system,” that will help you to make sense of your life. What holds real meaning for you and what directions can you take to reach these goals?
**9. TAKE TIME TO WASTE TIME**-I read something byJack Nicklaus in the ’80s I never forgot. Lee Trevino once told him if he (Jack) had played full time, he’d have won 25 majors! Jackreplied that he won the 18 he did (plus 19 2nds) because he took time away from golf! Leisure is not a “waste of time”. It’s a way to deal with stress, increase productivity, and enhance contentment. For me, it’s golf that gets me out in fresh air and nature with exercise and recharges my batteries.
**10. GIVE TO OTHERS**– Share. Altruism can increase happiness. Being concerned about others puts youin contact with others. This type of contact will improve your outlook on life and yourself! When I wasin Vietnam, I remember an old woman who lived in a shipping crate near the docks in Saigon (now Ho Chi Minh City); despite the fact she had nothing, she invited me ‘in’ and offered me something to eat. What a lesson.
———————
Opinions expressed are those of the author and nothing contained in this material is intended to constitute legal, tax, securities, or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional. The Independent Financial Group is a Registered Investment Advisor with offices located at 11707 Blossomwood Court; Moorpark, California 93021. IFG’s Founding Principal, Jim.Lorenzen, is a Certified*Financial Planner*®and an*Accredited investment Fiduciary*®. Mr. Lorenzen is also licensed for insurance as an independent agent under California license #0C00742. Primary asset custodian is Pershing Securities, owned by Bank of New York-Mellon. IFG and Pershing/BNY are not affiliated. Jim can be reached at 805.265.5416 or by emailing info@indfin.com.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Could Your Business Run Without You?](https://indfin.com/could-your-business-run-without-you/)
**Published:** April 25, 2013
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017eea826334970d-320wi.jpg)This isthe test of whether you own*a business*or a*job*.** Back in the days when I was in publishing, I read Robert Townshend’s*Up The Organization*, which told the story about how he grew Avis from virtually nothing to becoming #2 behind Hertz. While that book was about a big corporation and my publishing enterprise was in the small business category, there were some excellent lessons that I could apply. Many small business owners assume they’ll find a ready and willing buyer – with cash – when the time comes; and it’s almost never true.
Many also never give much thought about what would happen if something bad happens beyond technical[disaster-recovery](https://en.wikipedia.org/wiki/Disaster_recovery "Disaster recovery")concerns; but, there is another ‘disaster recovery’ issue too many ignore.
Ask yourself…
- If you had retired, died or become disabled yesterday,*who would own and manage your business today?*
- Would you want your business interest*retained for a family member, sold or liquidated*?
As I indicated, the ‘cash buyer’ is a fictional character in the small business market, evenwhen the businesses are successful. If a family member wants to buy it, will it support two owners during the sale process? If an outsider is involved, who will handle the transaction? As someone who’s soldfive businesses of his own, trust me, those ‘rule of thumb’ valuations aren’t worth much, either.
It’s good to get your ducks lined-up early.
**Objective****Issues to Consider****Retain the Business Interest for Your Family**- Is there a capable and willing family member?
- Will the family member be acceptable to any other business owners?
- How will you or your surviving dependents replace the income previously provided by your business?
- Is there a need to equalize inheritances among family members?
- Will there be enough liquidity in your estate to pay taxes and other settlement costs?
**Sell the Business Interest**- To whom will your business interest be sold?
- At what price?
- And at what events (death, disability and/or retirement)?
- What is the value of your business interest?
- Will the funds be available to complete the purchase at your death, disability and/or retirement?
**Liquidate the Business Interest**- What is the value of your business as a going concern?
- How does that value compare to the liquidation value of your business?
- How will you or your surviving dependents replace the income previously provided by your business?
- Will there be sufficient funds available to allow for a planned liquidation?
The objective of business continuation planning is to assist you in evaluating which of these alternatives is most suitable for your situation and to help provide the funds that will be needed to assure that your business continuation goals become a reality.
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of The Independent Financial Group, a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent under California license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a proven planning process coupled with a cost-conscious objective and non-conflicted risk management philosophy.
The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Business Owners and Executives Face Increased Risk For Retirement Shortfall](https://indfin.com/business-owners-and-executives-face-increased-risk-for-retirement-shortfall/)
**Published:** April 23, 2013
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017c384a4369970b-320wi.jpg)Retirement planning for owner-employees, executives, and other highly-compensated employees can often fail because of one well-kept secret: These people will rarely, if ever, be able to meet their retirement income needs by simply using qualified retirement plan techniques.
Surprised?
The fact is that qualified plans are seldom sufficient for business owners or top executives if they want to maintain their lifestyle in retirement, and the reason becomes clear when the total costs (and burdens) of qualified plans are compared with their limited benefits. These top-earners are often severely limited in the amount of contributions they can make and nondiscrimination testing frequently caps at much less than the maximum, which is often less than 3% of compensation.
While it’s not unusual to find that an average wage earner in a company is able to achieve a retirement income of about 60-80% of final compensation, a highly-compensated owner, executive, or employee can often expect to achieve a retirement income of about 10-30% of final compensation. They’ll even likely face taxes on their Social Security, too.
That’s a huge gap.
This may be the reason many successful companies have adopted non-qualified plan techniques, either in addition to, or sometimes a substitute for, a qualified plan.
If the employer is willing to give up the current deduction of a qualified plan, or is already maximizing its current plan, s/he can gain flexibility to design and fund a nonqualified plan with no limits on either contributions or benefits except reasonable compensation limits.
In effect, it’s like having a “unlimited” 401(k)-like deferral option; and, the employer can choose the plan participants, as well as the employer matching and contribution guidelines. There’s more: The employer can avoid the burdens of non-discrimination, disclosure, and reporting requirements by fitting the plan into an ERISA safe harbor exemption, even though there are some additional requirements that must be met; but, now an employer can use a nonqualified plan to design[deferred compensation](https://en.wikipedia.org/wiki/Deferred_compensation "Deferred compensation")in favor of select executives, highly compensated employees, and even independent contractors!
Why would an owner or senior executive want to do this?
Besides the obvious benefit of addressing the retirement income gap for him or herself, there’s a sound business reason: Keeping top talent, not only for the foreseeable future but for future business value in case of a sale! When it’s time to make your exit, how can a potential buyer be assured that top key talent will stay on?
Proper planning will allow you to show your potential buyer that your key talent has “skin in the game” and an interest to protect – they’re unlikely to go anywhere; and, let’s face it, the biggest asset any company has is its employees, especially the key personnel that make it all work.
If you have a successful business, are concerned about your meeting your retirement income needs, and look to business value as a key component to building your net worth, you may want to talk with your financial advisor about the feasibility of adopting a non-qualified plan.
Retirement isn’t a destination; it’s a roadmap.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Do YOU Know What Provisional Income Is?](https://indfin.com/do-you-know-what-provisional-income-is/)
**Published:** August 19, 2015
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019104599445970c-320wi.jpg)If your retirement is still ten years or more in the future, NOW is the time to get your ducks lined-up. Don’t wait until you’re at the doorstep – and, here’s why:**
You may think you’ll spend less in retirement – that’s what all the experts say – but, if you’ve been a disciplined saver and investor with a nice nest-egg, you’ll probably want to enjoy life! You may travel! But, even if you don’t, here’s what you need to know:
**You’ll probably lose some deductions.**
Four deductions typically lost are:
- Mortgage interest
- Dependent Children
- Retirement Plan Contributions
- Charitable Gifts
For most retirees, that leaves them with the standard deduction and personal exemptions. Currently, for a married couple filing jointly, the standard deduction is $12,600. Personal exemptions for each are $4,000; so, that gives a couple a total of $20,600 in deductions they can take when they’re no longer itemizing. Historically, these have been adjusted for inflation, so you can do the same as you estimate what they’ll be in retirement.
So, any income below that number won’t be taxed. But, what if income is higher? – and it probably will be.
**The IRS looks at Provisional Income.**And, here’s what’s counted:
- 1/2 of Social Security income
- Distributions from tax-deferred accounts (your retirement accounts)
- 1099 interest from taxable accounts
- Employment income
- Rental income
- Interest from municipal bonds
Did you notice? Municipal bond interest, which is normally tax-free, is counted!
**What’s the significance of provisional income?**The total determines how much of your Social Security benefit gets taxed! Here are the brackets:
**Married Couples**
**Single People****% of Social Security Subject to Income Taxation**< $32K<$25K0$32 – $44K$25 -$34K50> $44K> 34K85
**Here’s the kicker:**These brackets were created by President Reagan and House Speaker “Tip” O’Neil back in the early 1980s in an effort to save Social Security. But, just a swith the Alternative Minimum Tax (AMT), they made no provisions for inflation adjustment.
That means inflation alone may force many into the higher brackets by the time they retire… a land-mine you need to be aware of.
**What does all this mean for your advance planning?**It means you need to understand two things:
1. Asset allocation decisions – the arrangement of assets – shouldn’t be limited to simply choosing a risk-adjusted allocation of asset classes and picking investments. Before that stage, you must***arrange***assets – well in advance of retirement – into the right tax buckets.
2. You (your advisor) will need to do some “reverse engineering” to guard against your provisional income in retirement exceeding your standard deduction and personal exemptions. Example: if you plan to retire ten years from now, those deductions should total about $27,700, using a 3% inflation factor. So, for planning purposes, we’ll want to arrange assets into the right tax buckets well in advance to keep provisional income below that number.
How you should approach this strategy depends on too many variables to go into here – but, it should be a component of an overall financial plan for your life.
If you’d like help, feel free to contact me – there’s information below.
Hope this helps!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Life Insurance, Retirement
**Tags:** Retirement Income, Tax-Free Retirement Income
---
### [Did You Think Trusts Were Only for the Wealthy?](https://indfin.com/did-you-think-trusts-were-only-for-the-wealthy/)
**Published:** May 6, 2015
**Author:** Jim Lorenzen
**Content:**
Jim Lorenzen, CFP®, AIF®
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi3.jpg)When most people think about estate planning, they think about protecting assets from estate taxation. But, most people aren’t worried about that liability.
You may be surprised to learn that the upper middle class, defined as clients with between $500,000 and $5 million in investable assets can also benefit from estate planning. There are other issues, many never think about.
If you are concerned with any of the issues on this checklist below you may need an estate plan:
See if any of these are of concern to you:
- Do you have concerns about family members or beneficiaries that cannot manage their financial affairs? In this case the estate plan can contain a trust to prevent these beneficiaries from squandering their inheritance, protect them from creditors, predators, lawsuits, and divorces.
- Are you recently divorced, or your spouse has recently died?
- Are you in a second (or later) marriage and/or have a blended family?
- Do you have a disabled child or beneficiary? In this case the plan needs to be carefully structured to be sure that your disabled child or beneficiary continues to receive their crucial governmental benefits, because even a modest inheritance can cause loss of important benefits such as health care and housing.
- Do you have a family or closely held business or hold an interest in such a business?
- Do you want to minimize the costs of administration of your estate (financial affairs) if you should become disabled or pass away unexpectedly?
- Do you want to leave money and things of value to people you care about?
- Are you looking to benefit charities or causes that matter to you?
It is possible to create an estate plan using trusts affordable for middle class families dealing with the issues mentioned above. If these issues are of interest and you don’t have a written plan in place, I may be able to provide you some guidance and assistance. Just call my office at 802-265-5416, extension #1.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Estate
---
### [Does Time REALLY Reduce Risk? Don't bet on it.](https://indfin.com/does-time-really-reduce-risk-dont-bet-on-it/)
**Published:** May 6, 2015
**Author:** Jim Lorenzen
**Content:**
**You’ve seen this chart. Advisors have been using it – or something like it – with clients and prospective clients for years. It’s supposed to educate you.**It doesn’t.
[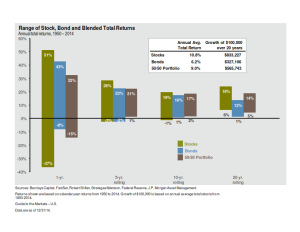](https://indfin.com/wp-content/uploads/2015/05/Image_Rolling-Period-Returns_001.png)
The chart is designed to address the issue of risk by showing that it’s time, not timing, that reduces risk for the investor. After all, as you can see, a 50-50 stock and bond portfolio might go down 15% if held over one year; but, should expect a ‘downside’ risk of +5% if held twenty years.
While it may be true that the volatility of long-term outcomes may be reduced, it actually means little in the real world.
Patrick Kelly, in his book *The Retirement Miracle*, talks about the story of Tom who had been contributing to his 401(k) plan for years, riding the market ups and downs, and finally feeling good about the $2.5 million he’d accumulated in November, 2007 on his 64th birthday as he looked forward to retiring the following year.
On the day he planned to retire in November 2008, he walked into the office finding a lot of commotion. During the next three days his $2.5 million was at $2.2 million. By October 7th, it was down to $1.5 million – down about $1 million in 12 months. His dreams of traveling with his wife had gone up in smoke.
The chart above didn’t let him know that when you’re one year away from retirement, you aren’t looking at the 20-year data anymore; it’s the one-year data that may be more relevant.
Now, obviously, the 2008 market meltdown was an extremely rare occurrence, and one arguably caused as much by (and that’s being generous) elected officials as anything Wall Street did; but, the lesson is no less worth learning: Managing the downside becomes critical as time passes and we get closer to the time we begin to draw-down on assets.
‘Nuff said.
You can begin your planning [here](https://indfin.com/?p=9)! [Let me know](https://indfin.com/contact/) if I can help.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
---
### [Need to Manage an Inheritance? Here's Your Checklist!](https://indfin.com/need-to-manage-an-inheritance-heres-your-checklist/)
**Published:** June 3, 2015
**Author:** Jim Lorenzen
**Content:**
Jim Lorenzen, CFP®, AIF®
For some, managing a large inheritance can be as daunting as winning the lottery; the windfall may sound good initially, but the money can disappear quickly if not managed properly.
What needs to be considered? What needs to be done? What comes first? What’s been overlooked or forgotten? Who should I be talking to and what should I ask?
Lots of questions…
Here are some answers. As part of our IFG LifeGuides series, we’ve created a LifeGuide for Managing an Inheritance. I hope you find it helpful.
[](https://indfin.com/wp-content/uploads/2015/06/IFGi_LifeGuide_Managing_An_Inheritance_vsa_001.png)
[Get Your Inheritance LifeGuide here!](https://indfin.leadpages.net/leadbox/147bc2c73f72a2%3A12a1899aa346dc/5662543133540352/)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Is Your Indexed Annuity a Stock, a Bond, or Something Else?](https://indfin.com/fia/)
**Published:** July 22, 2015
**Author:** Jim Lorenzen
**Content:**
Jim Lorenzen, CFP®, AIF®
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b0192ac851ba2970d-320wi.jpg)Good question, ya’ think?[\[1\]](#_ftn1) Maybe we should begin with what a fixed annuity is; then move to an indexed annuity.
**Fixed Annuity (FA**
When you loan your money to a bank, they give you a CD that pays a fixed rate until the CD matures and then return your money, paying off the loan.
When you loan your money to a government or corporate entity, they give you a bond that pays a fixed rate until maturity and then they return your money, paying off the loan.
Both of the above scenarios are basically bond scenarios: A bank bond, a government bond, a corporate bond. All three are I.O.U.s.
When you loan your money to an insurance company, you get an I.O.U. from them, too. They pay a fixed rate – sometimes even a bonus on top the first year – with one extra benefit: As long as the interest accumulates inside the annuity, it’s tax-deferred. The benefit of tax-deferral, of course, comes with a price: You might have tax issues if you ‘cash-in’ before age 59-1/2. That’s an I.R.S. requirement, not the insurance company’s – but, I digress. At its core, a fixed annuity is essentially a loan to an insurance company in exchange for a tax-deferred fixed rate of interest, paid by the company – it’s an insurance company I.O.U. Annuitizing, a separate discussion, is an option, not generally required.
**An Indexed Annuity (IA)**
This is a fixed annuity, too. It pays a fixed rate of interest for a term chosen by the annuity holder.
What’s the fixed rate? It depends on what it’s “pegged” to. Most people seem to like the S&P 500 Index. They don’t’ own the index – which is impossible, anyway – they simply receive a rate of interest determined by the performance of the index.
What is the term? It depends on the crediting option chosen. Annual point-to-point (comparing only two index values – beginning date and anniversary date – has a one year term. Others could be monthly, etc. Companies are also beginning to use a volatility control index, as well.
The point: It’s still a fixed annuity with the insurance company resetting the interest rate according to the performance of an outside index.
**What do you own?**
Is this a stock? No. There’s no equity ownership in any company, either directly or indirectly.
Is this a bond? Well, yes BUT. It is a bond in the sense it’s an insurance company I.O.U. The fact that the interest rate will move up or down based on the performance of some outside index is immaterial.
The BUT is this – and it’s a good one: These can be used to supplement the bond portion of a portfolio but will often outperform bonds. The reason is simple: The rate credited, tied to an outside index, can rise with that index (often up to a ‘cap’). When they do, those gains are ‘locked-in’ on the anniversary date. They never go back down! You never lose money. Those gains are also tax-deferred, which is better than paying taxes on CD money you’re not touching or bond interest you’re not using.
**Are FIAs right for everyone?**
No. Nothing is. They certainly shouldn’t be purchased al-a-carte; they’re complex products and should be installed into a portfolio as part of an integrated financial plan. While FIAs carry no annual fees, unless you attach riders, they do carry surrender charges if funds are accessed in greater amounts than the contract provides. Even though many contracts allow 10% free liquidity provisions, it’s still worth noting. This may not be an issue for those who do not need to touch the money; but, it’s another reason they should be part of an integrated financial plan that has planned for liquidity contingencies.
Someone who’s looking for guaranteed income as the main focus – not focused on liquidity or needing to walk away with a giant lump-sum at a future date – FIAs can be an excellent portfolio supplement. The combination of (1) no downside risk, (2) tax-deferral, and (3) returns that will probably outpace bonds (due to equity upside participation with no downside risk), make FIAs pretty attractive. For those under age 55, there are other insured options that might be considered before settling on an FIA. Many experts believe that taxes will rise and it might make more sense to reposition assets early to arrange a tax-free retirement. IRA guru Ed Slott, a CPA, and David M. Walker, former U.S. Comptroller General, are big proponents of this. If you’d like a free report on this, you can get it here.
**Why the surrender charge and how does the insurance company make equity-related payouts?**
These two issues are related.
Insurance companies may be the best risk managers on the planet, which may explain why so many of them went through the Great Depression never missing a claim payment while Wall Street was watching people jump out of windows.
Their process for meeting index-related obligations is pretty simple, really (though not simplistic). The vast majority of premiums are generally invested in long-term bonds.
But, with rates so low, how do they earn enough money to make higher payouts when an index goes up? Just for the sake of illustration, I’ll use simple numbers. An insurance company might invest, for example, 95% of its FIA premiums in long-term bonds, in order to get a decent bond market return. The other 5% would go to buy call options on the index – a ‘call’ is the right to purchase at a specified price if the market rises. If the index goes up the company executes the option to purchase. If not, the company lets the option expire. Naturally, some options are paid-for and never executed.
As for the surrender charges, there’s not only the cost of unexecuted options – a relatively small piece of the puzzle – but, there’s also the long-term bonds that must be sold in order to meet a redemption request. The company not only may face a loss on those bonds – maybe not, it depends on interest rates and price movements – but must also forgo the interest they would have received on those bonds as part of their total portfolio in order to meet all outstanding obligations to policyholders. The surrender charges also serve to help reimburse the company for the marketing costs they had originally paid out of their general account.
**Potential problems in sales situations**
Because FIAs can be sold by insurance agents who have no securities license – it’s not a securities sale – they can easily be either misrepresented or, more often, even misunderstood by the agent making the sale. One area has to do with a working knowledge of the underlying indices from which a client must select. The biggest issue, however, may be the solvency of the issuer. As I said, FIAs are really insurance company I.O.U.s. The risk of performance may be on the insurance company, but the risk of an insolvent carrier may be another issue. It’s worth noting that most of the ratings from agencies cited in their ads are actually paid for by the carriers being rated. Ideally, the person recommending the annuity issuer would be someone who can get “under the hood” of the insurance company financials and not rely on paid-for company ratings. This would call for, at a minimum, someone who’s securities licensed or preferably a Registered Investment Advisor with additional recognized credentials.
**The Outlook**
There was a time when companies in America provided pensions to their retired workers. These defined-benefit plans have all but disappeared, which is why income-replacement has become a huge issue as boomers face retirement.
Some are even wondering if it’s time to dump the 401(k) altogether. Take a look at this:
The argument in favor of income replacement tools is simple: You insure your house, your car, your health, and some even their dental visits; why wouldn’t you insure your future income. Many people who pride themselves in paying cash for everything else still find it difficult to pay cash for an income they can’t outlive; but, as I said earlier, it must be done carefully and as part of an overall plan because income isn’t the only factor in everyone’s lives.
Jim
[\[1\]](#_ftnref1) This excellent question was posed by Ben Mattlin in the June issue of *Financial Advisor Magazine.*
[Sign-up For Jim’s Ezine!](https://visitor.r20.constantcontact.com/d.jsp?llr=fdk6idhab&p=oi&m=1107137833061&sit=icdtuhhgb&f=752ea908-2c06-442f-b9b9-905991d9ae0a)
For Email Newsletters you can trust.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
**Tags:** Retirement Income, Retirement Planning, Retirement Strategy
---
### [Enjoy the 4th!](https://indfin.com/enjoy-the-4th/)
**Published:** July 1, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi3.jpg)
Jim Lorenzen, CFP®, AIF®
One of my hobbies, if you can call it that, is American history – particularly the period between 1765 and 1800.
It was during that 35-year period that the colonies declared their independence, and began a rebellion that morphed into a full-fledged revolution (which had NO chance of success) that defeated the largest and best-equipped fighting force on earth.
During the summer of 1787, the best minds the colonies could produce met in Philadelphia to hammer-out a framework of government. While Adams and Madison had performed extensive research on the history of republics, they had to make adjustments because few lasted very long and all had failed.
The resulting constitution provided the framework of government that became a reality in 1789 when George Washington took office as the first President of the United States. The new government was funded by a financial genius Secretary of the Treasury, Alexander Hamilton. The funding came from a bank he founded: The Bank of New York (now BNY Mellon, which owns Pershing).
The Constitution they created that summer, that we still have today, is – are you ready? – the oldest functioning constitution in the world today. No country anywhere on our planet is operating under a constitution older than ours…. Not Greece, not France, not Italy, no one.
It says something about the minds that met in Philadelphia that summer. Each of them brought something unique and brilliant to the table. Few people realize that the banking system, credit and stock markets, our system of trade, including the customs service, were all designed by Alexander Hamilton. He’s one founding father that could walk into our financial system today and recognize all of it, maybe except the machines, because he created it all.
James Madison, the father of the Constitution, would probably be amazed to see that the constitution still lives, albeit with expected amendments since that process was provided for in the original document. All other constitutions in existence around the world at that time are no longer around.
Enjoy the holiday! This one is one of the great birthdays we celebrate.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Will the Fed Act To Raise Rates Today?](https://indfin.com/will-the-fed-act-to-raise-rates-today/)
**Published:** September 17, 2015
**Author:** Jim Lorenzen
**Content:**
A slim majority of economists don’t believe they will. We’ll soon see if these ‘experts’ are right.
[](https://indfin.com/wp-content/uploads/2015/09/WSJ-economists.jpg)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [What Happens to Your Business if Something Happens to YOU?](https://indfin.com/what-happens-to-your-business-if-something-happens-to-you/)
**Published:** October 27, 2015
**Author:** Jim Lorenzen
**Content:**
Jim Lorenzen, CFP®, AIF®
[](https://indfin.com/wp-content/uploads/2014/09/multitasker_male.jpg)*Fotila Images*I can speak from personal experience on this one. I’ve been a business owner for thirty-seven years, owning seven different businesses in three different industries; and my wife’s former husband passed away (unexpectedly) after building a chain of seven quality restaurants that stretched from El Paso, Texas to Northern California.
Experience teaches preparation.
If you’re a business owner or a partner in a business, have you asked yourself what would happen to your business if something should happen to you? Death and disability, are possibilities even if we want to avoid the thought. And, of course, some want to retire.
Does the business simply stop? If so, that may cause a lot of equity to simply be flushed away.
Does your partner’s spouse inherit your partner’s share? Do you want that?
Every objective brings with it issues you should consider:
**Retain the Business for Your Family**
“¢ Is there a capable and willing family member?
“¢ Will the family member be acceptable to any other business owners?
“¢ How will you or your surviving dependents replace the income previously provided by your business?
“¢ Is there a need to equalize inheritances among family members?
“¢ Will there be enough liquidity in your estate to pay taxes and other settlement costs?
**Sell the Business**
- To whom will your business interest be sold?
- At what price?
- What is the value of your business as a going concern?
- How does that value compare to the liquidation value of your business?
- How will you or your surviving dependents replace the income previously provided by your business?
Will there be sufficient funds available to allow for a planned liquidation?
- And at what events (death, disability and/or retirement)?
- What is the value of your business interest?
- Will the funds be available to complete the purchase at your death, disability and/or retirement?
**Liquidatethe Business**
- What is the value of your business as a going concern?
- How does that value compare to the liquidation value of your business?
- How will you or your surviving dependents replace the income previously provided by your business.
- Will there be sufficient funds available to allow for a planned liquidation?
The objective of business continuation planning is to assist in evaluating which of these alternatives is most suitable for your situation and to help provide the funds that will be needed to assure that your business continuation goals become a reality.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Business Owners, Family Issues
---
### [Happy Thanksgiving!](https://indfin.com/happy-thanksgiving/)
**Published:** November 24, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a00d83451c82369e201b8d0769f84970c-600wi.jpg) 
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Is Your Income/Tax Picture Common or Uncommon?](https://indfin.com/is-your-incometax-picture-common-or-uncommon/)
**Published:** November 17, 2015
**Author:** Jim Lorenzen
**Content:**
Jim Lorenzen, CFP®, AIF®
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b0192ac851ba2970d-320wi.jpg)**Is your income common or uncommon?**
Most of us think our income is pretty normal, according to most of the studies I’ve seen. That may be because we see our neighbors living in the same neighborhood we do; driving the same type of car; and probably making similar incomes. The people we hang out with are probably similar to us, too. Sure, we know there are people who are poor and others who are filthy-rich; but, that doesn’t mean our incomes are uncommon…. or does it?
How much money do you have to make to be in the top 1%? – the 1-percenters we all hear about. How about the top 10% or even the top half of all Americans? And, how much of the total tax revenue do people who are like you contribute?
According to MoneyTrax®, Inc., these are the numbers (rounded-off):
The Top\_\_%
Total HH Income% of Total Tax Revenue Paid1
$369K+375
$161K+5910
$116K+71
25$69K+87
50$34K+97
So, not only are those who’s combined household income totals $69,000 or more in the top 25% of all households, they’re also paying 87% of tall the income taxes paid.
With our national debt now over $18 trillion and with the handwriting on the wall – have you ever seen Congress *lower* the debt ceiling? – there may be a message for the Baby-Boomers who are getting within ten years of retirement: It just might (I’m being kind) get worse.
Do you have a plan? It might be a good time to [start](https://indfin.com/video-library-2/).
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Taxes
---
### [Inflation (for YOU) May Be Less Than You Think](https://indfin.com/inflation-for-you-may-be-less-than-you-think/)
**Published:** November 3, 2015
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73de5d743970d-320wi.jpg)Jim Lorenzen, CFP®, AIF® While historic inflation rates average a bit over 4% and many people doing their own calculations may be using figures in the 2-3.5% range, the actual numbers may – just may – be far less – maybe as low as 1%!
Why? Because inflation doesn’t apply to ALL of your spending. Many people are paying on a fixed mortgage – those payments won’t increase. Granted, other outlays (food, energy, and products) may increase; but, the total may be less than you think.
If 70% of your spending increases at an average rate of 3% annually, but 25% of your expenditures remain constant, you’re actual realized increase is more like 2.25%.
But, what if you’re retired an your spending decreases? That’s when your overall cost increases may be closer to 1%… maybe.
It’s important that your planning reflect these realities, as well as others. There are other considerations, to be sure. A bad (or no) plan can be the most expensive of all.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
---
### [Big Changes in Social Security Claiming](https://indfin.com/big-changes-in-social-security-claiming/)
**Published:** December 2, 2015
**Author:** Jim Lorenzen
**Content:**
Jim Lorenzen, CFP®, AIF®
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019b00066606970c-320wi.jpg)The Bipartisan Budget Act of 2015, passed by Congress and signed into law by President Obama on October 30, 2015, will dramatically impact two Social Security claiming strategies: restricted application benefits and voluntary suspension benefits.
Passed in order to eliminate unintended loopholes in Social Security verbiage, Section 831(a) and 831(b) of the Bipartisan Budget Act of 2015 effectively make dramatic changes to restricted application benefits and voluntary suspension benefits. These benefits, partnered with file-and-suspend claims, allowed retirees to earn an additional $35,000 to $60,000 over the course of their retirement and can make a significant difference in retirees’ future retirement income.
**Section 831(a): Restricted application**
Up to now restricted applications allow those people who are full retirement age (FRA), to file a restricted application on their spouse’s record, allowing them to collect half of their spouse’s payment, while their own benefits continue to accumulate. That was then. No longer.
After April 30, when a retiree files, they will receive the highest benefit they are entitled to and will not have the flexibility of choosing between receiving benefits based upon their own record or their spouse’s record. This means once a retiree reaches full retirement age (FRA), s/he will solely receive the highest benefit available to them. So now, in order to receive delayed retirement credits, they will simply have to wait to file for benefits. This is a concept is known as “deemed filing,” and was previously applicable only for those who had not yet reached FRA, but will now apply to those reaching FRA and beyond.
There’s more.
Retirees can no longer elect to use a restricted application to draw upon spousal benefits while their benefits continue to grow.
The restricted application strategy for only spousal benefits, with ability to switch to their own benefits after they’ve accumulated further, will now be an option only for those people born January 1, 1954 or earlier. As long as a retiree is 62 by December 31, 2015, they can utilize restricted applications. However, if they don’t fall into this category, they will have to consider other options.
**831(b): Voluntary suspension or “file and suspend”**
Voluntary suspensions allow the lower-earning spouse, spouse A, to draw benefits based upon spouse B’s record while spouse B’s record is suspended. This allows spouse B’s benefits to grow by 8 percent until age 70. No more.
Under the new law, spouse A will no longer be able to receive benefits on spouse B’s record while it is suspended, and conversely, if spouse A files for benefits and suspends, he/she will not be able to receive benefits on anyone else’s work record. In short, if a retiree suspends their benefits, he or she cannot draw off of anyone else’s record and no one will be able to draw off of his or hers.
That’s not all. The law effectively eliminates the ability of individuals to request a retroactive lump sum for all benefits between the date of filing and the date of suspension. Up to now, retirees could “file and suspend”, and then elect for a lump sum of the benefits that would have been paid if the record had not been suspended until age 70 – an especially attractive feature for those people who have had poor health and would benefit from enjoying the present value of their money, rather than receiving it over the course of many years (in the form of the 8 percent higher valued payment).
Under the new law, people who have reached FRA and suspend benefits within the first 180 days of enactment of the new law will be able to take advantage of the old “file-and-suspend” rules. Those filing more than 180 days after enactment of the bill will not, and will have to utilize alternative Social Security strategies.
**Who do these changes affect?**
These changes primarily affect married couples, but do in fact have some implications for those filing as single and divorced.
- Single people will no longer be able to file-and-suspend at FRA, and then collect a retroactive lump sum. They will now have to take the highest benefit available to them at the time of filing.
- Divorced persons will now be able to draw off their ex-spouse’s account only for “spousal benefits” if the ex-spouse has an active Social Security account. This means if their ex-spouse suspends their benefits, the divorcee filing will be left without that source of income until their ex-spouse chooses to make it active again.
- Widows or widowers planning for retirement will not be affected and can continue to take advantage of restricted applications for survivor’s benefits. Additionally, those who have already executed a file-and suspend strategy or a restricted application will continue to receive those benefits.
It’s important to remember Social Security *optimization* is different from ‘maximization’. It’s not how much you receive; it’s how much you get to keep after taxes that counts.
If you’d like to get started on your planning, your first step can [begin here!](https://indfin.com/getting-started/)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues, Retirement, Taxes
---
### [ROLLOVER MISTAKES ARE OFTEN IRREVOCABLE](https://indfin.com/rollovermistakes/)
**Published:** January 19, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017c384ba1fa970b-320wi.jpg)**Jim Lorenzen, CFP®, AIF®**
Believe it or not, over the years I’ve had many new clients come to their first planning meeting having already made bad, and often irrevocable, choices on their own – yes, even prior to planning; and, I’m sure I’m not the only financial planner who’s seen this. Most often, the mistakes are made in Social Security claiming elections, often based on pre-conceived internal bias and no calculations; but, sometimes the decisions involved their 401(k) plans.
According to Cerulli Associates, rollovers from 401(k)s and other retirement plans will cause IRA assets to reach $12 trillion by 2020.
According to retirement expert, Ed Slott, who also happens to be a practicing CPA, it’s worth understanding that every time IRA or 401(k) money is touched, it’s a gamble for those who don’t know what they’re doing. Hesays it’s like an eggshell – break it, and it’s over.
Here’s something few people really get: If you make a mistake on the rollover, it’s possible you could lose the IRA entirely! Boom! It’s irrevocable.
A number of years ago, I wrote a report, *[Six Best and Worst IRA Rollover Decisions,](https://tinyurl.com/IRARolloverDecisions)*and one of the mistakes I mentioned was in not recognizing you probably shouldn’t do a rollover at all!
Why? First, you have to understand what a rollover is – as the well as the difference between a rollover and an custodian-to-custodian transfer. A rollover happens when money has been withdrawn from a 401(k) and deposited into an IRA. When that happens, the client is required to do the necessary withholding, pay the tax and wait for a refund the following year. A transfer of the account directly between custodians avoids that problem; but, there’s a potentially bigger one.
Example: If a rollover has been previously rolled over in the past 12 months, the entire account now becomes taxable, and there’s no fix to correct the error. Someone with a $500,000 or $1 million (or any other size) IRA could be in for a big shock. Taxes will be due at their new rate – this withdrawal likely puts them in a new bracket – and the money left is no longer tax-deferred!
A direct transfer would have avoided this problem.
**Keep Up with New Rules**
A lot of seniors have CDs and IRAs at banks. Last year, you could do one rollover per year for each of your IRA accounts. No more. Now, the law is one rollover per year for ALL IRA accounts – and that includes Roth IRAs. Two rollovers means that one of them will be no good.
**Inherited IRAs**
Here’s where mistakes can, and do, happen far too often; because the rules are different – and stiffer.
Did you know a non-spouse beneficiary can NOT do a rollover? A child who inherits a parent’s IRA must be careful. Often , because the child wants to access the money right away, an attorney will put the child’s name on it. When that happens, that’s the end of the account. It just became a taxable distribution. It should have been set up as a properly titled and inherited IRA. Putting the money into the beneficiary’s IRA is a terrible mistake.
**Beneficiary Designation**
Too often, problems happen because people fill-out the beneficiary forms and forget them – never reviewing them. Failure to do this only puts off the day when siblings get “lawyered-up” because the investor didn’t understand the true meaning of the distribution designations.
There’s more to know, of course; but, hopefully this will get you thinking… and doing your homework before making mistakes that can’t be changed. Working with a professional who’s been down the path before can’t hurt, either.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Taxes
---
### [LOOK FOR LOWER PAYOUTS ON GUARANTEED INSURANCE LIFETIME PAYOUTS](https://indfin.com/lowerpayouts/)
**Published:** January 26, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a3fd0c994a970b-320wi.jpg)Jim Lorenzen, CFP®, AIF® Virtually all insurance companies will be using the newer 2012 mortality tables in 2016. Why is that important? The answer is simple: The difference in payouts is significant when our lives are measured by the new tables!
According to the new tables to be used in 2016, the male life expectancy is now 88.5 years versus 85.4 years under the old tables. This 3.1 years represents over 37 months of additional income that will have to be generated from an annuity. For this reason, you can expect to see ALL companies that offer guaranteed income riders and annuities to lower their roll up rates and/or their income payments.
How much lower will the payments be? That depends on who you ask, but many believe the payouts will be about 10% lower. That means if the payout rate for a particular age would have been 5.5%, the new payout rate could be under 5%!

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Should Investing Be Fun?](https://indfin.com/should-investing-be-fun/)
**Published:** February 1, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017c37dfb72e970b-120wi.jpg)*iStock Images*
*Jim Lorenzen, CFP®, AIF®*
*“If you think investing is fun, you’re doing something wrong.” – Warren Buffett*
I’ll never forget visiting with a nice couple who was seeking advice on planning and investing. All of a sudden one of them piped-up and said, “I really like trading; it’s fun, and I’ve been pretty good at it.”
When I asked how they did during the market meltdown, I was told they broke even. I guess they were like everyone you know who just returned from Las Vegas.
I guess there must be a lot of people who do, considering all the active trading commercials you see on television, despite all the educational resources available that debunk it’s effectiveness on a consistent basis. If Warren Buffett won’t do it, why should I?
One colleague tells his clients that pain in a strong indicator of good investing. In other words, if a potential buy feels right, it’s probably best to hold off.
Studies seem to prove reveal that the human mind is often disconnected from reality. If their feelings toward an activity are positive, they are naturally moved to judging the risk as low. This explains why so many tend to buy when the market’s good and sell when it goes down. Not surprisingly, awhole new field of behavioral finance has emerged that explains how we can think we’re being logical even as we do illogical things:
**Data mining**: We tend to look for patterns that validate our beliefs.
**Recency bias**: If stocks fall, we expect it will continue. When they go up, we think that will continue, as well. The most recent events are more important than an event that happened three months – or years – ago.
**Confirmation bias:** When stocks go down, our belief is confirmed that stocks are high risk and low reward – which is why so many move to cash until the market comes back (buying high).
**Herd effect**: While many investors believe they’re contrarians, research shows the human animal is more likely to follow the herd. – because we believe the herd is led by experts.
The fact is there are many other risks out there, often ignored by those trying to build their retirement asset base. I even recorded a [webinar](https://attendee.gotowebinar.com/recording/3582652353068760321) about why many retirement plans are doomed to failure. The important note is sometimes lost: Those who begin early – and do it right – virtually always outperform those who do it wrong until they’re 65 and worried.
When it comes to trading, maybe Warren Buffett just might know something our nice couple didn’t.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
**Tags:** Retirement Strategy
---
### [HAVE YOU CALLED A FAMILY MEETING?](https://indfin.com/have-you-called-a-family-meeting/)
**Published:** February 15, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/have-you-had-the-talk/6a017c332c5ecb970b019aff2c523c970c-320wi/)**No? You’re not alone.**Very few families ever sit down together and talk over important issues. Too bad; it’s important. It should be considered an integral component in “the business of living”.
According to an excellent article in the current issue of the *Journal of Financial Planning*, there are four key areas every family should discuss:
1. **Legal issues**: Who has the durable power? Who will be executor for the wills? Do they have trusts?
2. **Health care**: What happens if mom and dad get sick? Who takes care of them? Where are they going to live and how are they going to pay for their care?
3. **Financial**: Are the parents financially secure? Will they need help from the children? It’s a tough conversation to have, but children need to know this stuff in advance.
4. **Legacy**: More than who gets what; it’s about what you want your children and grandchildren to remember about you.
Ideally, the meeting should have a good facilitator. Your financial advisor, if s/he’s been at the center of your financial planning – which should be the case – might be the perfect person. The facilitator doesn’t control or direct; but, can provide an objective and worthwhile service. In addition, you may want to include your family attorney in the meeting to address legal issues and provide valuable input. And, one of the adult children should be the note-taker to follow up on who is to do what and by when.
One meeting isn’t a magic pill, and it won’t correct all past problems; but it’s a start. After all, it’s about helping parents when they’ll need it most.
Jim
————–
*Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [*The Independent Financial Group*](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Estate, Family Issues, Retirement
---
### [Danger in Future Inflation, Interest Rate, and Tax-Law Changes.](https://indfin.com/danger-in-future-inflation-interest-rate-and-tax-law-changes/)
**Published:** April 27, 2016
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/does-the-4-rule-still-work/6a017c332c5ecb970b01a5116fb332970c-320wi/)Jim Lorenzen, CFP®, AIF®** Back during the 1990s, many Americans, particularly baby-boomers, were focusing on accumulation. Many of us can remember the focus on mutual funds and a rising stock market. Today, these same boomers are thinking more about protecting what they’ve saved.
The problem, as is often the case, is Uncle Sam.
**For years I’ve believed that our 401(k) and other tax-deferred account statements are misleading.** Someone who’s successful and in his/her 50’s might open their retirement account statement and see a balance of $600,000, for example, and believe they actually have $600,000!
Not likely. For someone in a 28% federal bracket, for example (we’ll ignore state taxes for now, but you shouldn’t), the statement should read:
**Your money: $432,000**
[](https://indfin.com/a-zero-percent-return-can-be-powerful/istock_unclesamliftingwallet_medium/)**The Federal Government’s money: $168,000**, unless your tax bracket changes and unless the federal government decides to change how much will be required to fund government operations. If more is required, the government can increase it’s share of your retirement account without your consent.
And, there lies the problem.
According to this chart, federal finances may experience a bleak future.
[](https://indfin.com/danger-in-future-inflation-interest-rate-and-tax-law-changes/201603i_federal-finances-2/)
I aplogize for the poor image quality, but the upper-left depicts the annual deficits both past and projected, while the lower left chart shows the effect of these accumulated deficits
There’s more you should know about this and how this issue, combined with a few others, has important implications for baby boomers who need to navigate the retirement maze in the face of potential rising interest rates, inflation, and tax-increases – all during the years when they’ll be tapping into their nest-eggs. I’ve included this and a few other charts – all much more legible – and additional information you might find interesting, as well.
[Click Here!](https://indfin.leadpages.co/leadbox/14134b073f72a2%3A12a1899aa346dc/5724681378201600/)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Taxes
**Tags:** Financial Security, Retirement Income, Retirement Planning, Retirement Strategy
---
### [Tips for Managing an Inheritance](https://indfin.com/tips-for-managing-an-inheritance/)
**Published:** September 7, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73de5d743970d-320wi4.jpg)**Receiving an inheritance?**
**Not sure how to manage it?**
Before you make decision, it’s good to do your homework. You might find our report on managing inheritance money helpful. You can access it below.
[Get Your Inheritance LifeGuide here!](https://indfin.leadpages.co/leadbox/147bc2c73f72a2%3A12a1899aa346dc/5662543133540352/)
—————————-
Visit the [IFG Website](https://indfin.com/)!
**Arrange a brief15-minute introductory phone call with Jim Lorenzen, CFP®, AIF®** [**here**](https://www.meetme.so/JimLorenzenCFP)**.**
Follow Jim on Twitter: [@jimlorenzen](https://twitter.com/JimLorenzen)
and also [Jim’s MoneyBlog](https://www.jimsmoneyblog.com/)
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp)
IFG on [Facebook](https://www.facebook.com/IFGAdvisory)
Become an IFG client! [Schedule your 15-minute introductory phone call here](https://www.meetme.so/JimLorenzenCFP)!
———————
Jim Lorenzen is a[ *CERTIFIED FINANCIAL PLANNER®*](https://en.wikipedia.org/wiki/Certified_Financial_Planner) professional and An Accredited Investment Fiduciary® in his 21st year of private practice.
The Independent Financial Group is a fee-only registered investment advisor with clients located across the U.S. He is also licensed for insurance as an independent agent under California license 0C00742.Jim can be reached at 805.265.5416 or (from outside California) at 800.257.6659.
**Interested in becoming an IFG client?** Why play phone-tag? You can easily [schedule your 15-minute introductoryphone call!](https://www.meetme.so/JimLorenzenCFP)
The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Estate, Family Issues, Investing, Planning
**Tags:** Inheritance, managing a windfall, managing inheritance
---
### [THE MARKET IS AT ALL-TIME HIGHS! Corrections, however, are a fact of life.](https://indfin.com/time-to-rethink-401k/)
**Published:** November 18, 2019
**Author:** Jim Lorenzen
**Content:**
For workers in their 40s and 50s facing massive government debt and retirement 15-20 years off, it’s worth asking: Is it time to (Dump) THE 401(K)?
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi3.jpg)Many Believe It Is…. including some well-known experts**
Jim Lorenzen, CFP®, AIF®
In his book, The Retirement Miracle, Patrick Kelly writes about a man who had built-up a 401(k) balance of over $2 million over his career. Then, on the brink of retirement, his world was shattered. It was a September day in 2008. He’d lost about 10% of his nest-egg in a single trading day. By October 7th, he found his balance was down to $1.5 million! By the time he reached his last day of work, his account was down to $1.2 million – actually about $1 million less than what it had been before all this happened.
And, just as an aside, if that wasn’t bad enough, that $1.2 million had an embedded tax liability. If this man was in the 30% combined federal and state tax brackets, $360,000 of that belonged to the state and federal government, leaving him with only $840,000 to retire on – and THAT’s only if taxes don’t go up while he’s in retirement.
Is the 401(k) really an answer to America’s growing retirement crisis? After all, 401(k)-type plans are a little less than 40 years old in this country, created when most people were accumulating assets. They haven’t been around long enough to see what happens when the ‘baby-boom bubble’ begins to drain them.
More than a few experts believe it’s time to shake things up, as you’ll see in this video (there’s a very brief ad in front – it’s quick). There’s also another video (scroll down below this one) I think you’ll find very interesting.
A recent article by Wealth Management Systems, writing for the FPA noted the following:
“Recent research indicated that a third of retirement plan participants were “not at all familiar” or “not that familiar” with the investment options offered by their employer’s plan. The study went on to reveal that individuals who were familiar with their retirement plan investments were nearly twice as likely to save 10% or more of their annual income, compared with those who report having little-to-no knowledge about such investments. Understanding your investment options is essential when building a portfolio that matches your risk tolerance and time horizon. Generally speaking, the shorter your time horizon, the more conservative you may want your investments to be, while a longer time horizon may enable you to take on slightly more risk.”
Here’s another one I think you’ll find very interesting.
**The 401k Failure**
**Howfamiliar with their options are 401(k) investors?** Not very, apparently. Many now believe it’s time to move from a stock market-based system to something that’s insurance-based. While this may not be the right path for everyone, it certainly appears it is for most, as the following clips from FrontLine, 60-Minutes, and others.
According to *The Power of Zero*, by David McKnight (with a forward by Ed Slott, a CPA and well-known retirement expert, and a back cover endorsement by David Walker, former Comptroller General of the United States), an insurance-based approach makes far more sense, particularly if properly designed. And, there are a number of advantages.
Theinsurance-based approach to funding retirement you saw in the video clips, does seem to have it’s benefits.
**Indexed Universal Life:** A Life Insurance Retirement Plan is one401k Alternative.
“¢ No contribution limits
“¢ No Pre-59-1/2 withdrawal penalties AND no mandatory distributions
“¢ Tax Free Income at retirement
“¢ Zero Loss From Market Crashes – with annual reset locking-in gains!
“¢ Tax Free to heirs
“¢ Self-funding option in case of disability
“¢ Protection from market loss – You never lose money
It also doesn’t create or increase taxation of Social Security benefits, provides protection from lawsuits in many states, has no minimum age or income requirement, avoids probate, and – this is a big one – provides accurate return figures, an issue I’ve discussed in other writings.
Not bad.
There’s a lot more to this,of course. And, it pays to do your homework. Talk to your advisor – or talk with me! You can [schedule your introductory phone call](https://www.meetme.so/JimLorenzenCFP) and begin now.
Jim
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Life Insurance, Retirement
**Tags:** 401(k) planning, 401k decisions, retirement decisions, Retirement Planning
---
### [Webinar Announcement: NEW DATE FOR WEBINAR - Planning Retirement in an Unpredictable World](https://indfin.com/webinar-announcement-planning-retirement-in-an-unpredictable-world/)
**Published:** May 25, 2016
**Author:** Jim Lorenzen
**Content:**
******DATE CHANGE: The webinar will be held on June 4th!**
**Uncle Sam (translation: elected politicians) will likely need more moneyin coming years.**
They’ll need it to fund all their promises – and it wouldn’t be surprising to see their demand for your money rise over the coming 2-3 decades just as aging ‘baby-boomers’ – the largest of the demographic bubbles – will be retiring while others in that group are trying to survive their second and third decade in retirement.
Rising taxes and prices, coupled with a potential health-care crisis – that problem still isn’t solved – all spell possible problems.
Easy answers are easy to find. Too bad those often fall short of matching real life needs.
Too often, we focus on trying to find those easy answers instead of focusing on the right questions.
I’ll be conducting a webinar on **Saturday, June 4th, at 9 a.m**. Pacific (noon Eastern) discussing these issues. You can [register for it here ](https://indfin.com/retirementwebinar)and also receive our free LifeGuide, ***So You’re Thinking About Retirement***.
This LifeGuide contains tips, checklists, tools, and other helpful ideas to get you started on your journey. And, of course, both the LifeGuide and webinar are free.
[Register for the webinar](https://indfin.com/retirementwebinar) and get your LifeGuide – and I’ll see you on the 4th!
Jim
**Your webinar host:**
**James Lorenzen, CFP®, AIF®**
Background:
**Retirement Planning & Wealth Management**(1991-present) serving selected private clients. Founding Principal of The Independent Financial Group, a Registered Investment Advisor. Jim is a CERTIFIED FINANCIAL PLANNER**®** professional and an ACCREDITED INVESTMENT FIDUCIARY**®**, earned through the Center for Fiduciary Studies in conjunction with the Joseph M. Katz Graduate School of Business, University of Pittsburgh.
Interviewed for American Airlines *Sky Radio*, heard on more than 19,000 flights, and by *The Wall Street Journal* for *Smart Money*. Articles published in *Insights* by the Profit Sharing Council of America and the *Journal of Compensation and Benefits*, as well as in numerous newspapers locally and nationally.
**International speaking and management consulting** (1984-1996). Headline speaker at more than 500 conventions throughout the U.S., Canada, and the U.K. Clients included Foster Grant, Hobie Cat, CapCities/ABC, Hearst Corp., Independence Bank, Val-Pak, Dial-One, Inc., and scores of others. Contributing author to more than 25 national and international publications.
**Business owner** – Founded, built, and sold five businesses in the publishing industry (1978-86) in Simi Valley, California. Prior experience includes senior executive positions in consumer and commercial finance overseeing 65 offices throughout the United States and Canada.
—————
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
**Tags:** Investment Strategy, Reducing Risk, Retirement Planning, Retirement Strategy
---
### [Final Opportunity To Register](https://indfin.com/final-opportunity-to-register/)
**Published:** June 3, 2016
**Author:** Jim Lorenzen
**Content:**
*iStock Images*
LAST CHANCE TO REGISTER THIS WEBINAR:
**PLANNING RETIREMENT IN AN UNCERTAIN WORLD**
Tomorrow, June 4th: 9 a.m. Pacific, noon Eastern
[Register here](https://indfin.com/retirementwebinar) and receive our complimentary LifeGuide: ***So You’re Thinking About Retirement***. It’s filled with tips, checklists, and other information you might find helpful. **So [register today](https://indfin.com/retirementwebinar)!**
**Your webinar host:**
**James Lorenzen, CFP®, AIF®**
Background:
**Retirement Planning & Wealth Management**(1991-present) serving selected private clients. Founding Principal of The Independent Financial Group, a Registered Investment Advisor. Jim is a CERTIFIED FINANCIAL PLANNER**®** professional and an ACCREDITED INVESTMENT FIDUCIARY**®**, earned through the Center for Fiduciary Studies in conjunction with the Joseph M. Katz Graduate School of Business, University of Pittsburgh.
Interviewed for American Airlines *Sky Radio*, heard on more than 19,000 flights, and by *The Wall Street Journal* for *Smart Money*. Articles published in *Insights* by the Profit Sharing Council of America and the *Journal of Compensation and Benefits*, as well as in numerous newspapers locally and nationally.
**International speaking and management consulting** (1984-1996). Headline speaker at more than 500 conventions throughout the U.S., Canada, and the U.K. Clients included Foster Grant, Hobie Cat, CapCities/ABC, Hearst Corp., Independence Bank, Val-Pak, Dial-One, Inc., and scores of others. Contributing author to more than 25 national and international publications.
**Business owner** – Founded, built, and sold five businesses in the publishing industry (1978-86) in Simi Valley, California. Prior experience includes senior executive positions in consumer and commercial finance overseeing 65 offices throughout the United States and Canada.
—————
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement
**Tags:** Retirement Planning, Retirement Strategy
---
### [A "Safe" Route to Higher Income in a Rising Rate Environment](https://indfin.com/a-safe-route-to-higher-income-in-a-rising-rate-environment/)
**Published:** June 7, 2016
**Author:** Jim Lorenzen
**Content:**
**Jim Lorenzen, CFP®, AIF®**
Think interest rates may be headed up in the future?
Looking for a “safe” way to produce a rising income if that happens?
**First, the good news:** It’s pretty simple to do. It’s called a bond ladder, but it can be accomplished using bank CDs or virtually any other fixed-rate instrument that has a maturity date.
You simply divide your money into time frames or baskets, i.e., 1 year, 3, year, 5, year, 10 years. As each basket matures, you simply buy another basket with the same time frame.
It looks something like this:
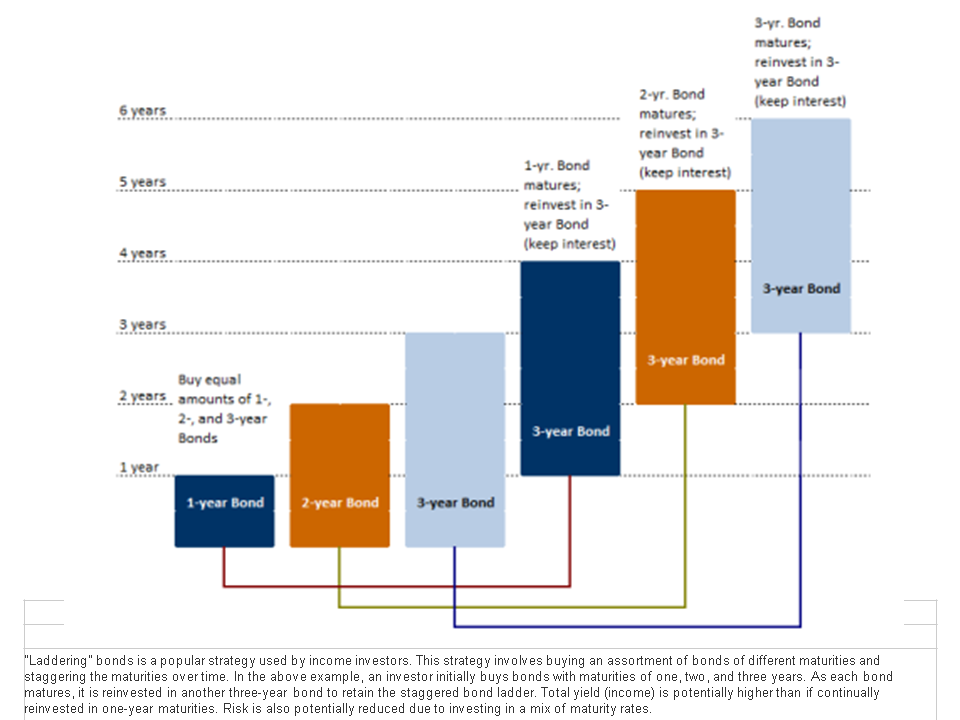
**Now the bad news:** The rates may or may not keep up with inflation. And, unless held in a long-term tax-deferred account – and many aren’t because people consider this money to be ‘liquid’ emergency money – the interest is also taxable.
For example, as I write this, according to [bankrate](https://www.bankrate.com/), a 5-year CD is currently paying around 1.67%. Someone in the 30% combined state and federal tax bracket would realize only 1.17% while inflation, according to the [government calculations](https://www.usinflationcalculator.com/inflation/current-inflation-rates/), is 1.1%. In other words, you’re treading water. And, while most people like liquidity and safety, they also don’t generally want to have a lot of money going nowhere.
There’s something else to consider, too. Given the current U.S. [government debt level ](https://www.usdebtclock.org/)and the state of the U.S. economy, there is pressure to keep rates low (it’s in the government’s interest as long as heavy borrowing continues); so, rising rates may be a ways off and slow in coming at that, while inflation – and higher taxes – just could arrive first!
**If you’re stuck in low interest rate accounts**, there are other options available. Whether they are right for you would depend on a number of factors, which I’ll cover in an upcoming webinar entitled, ***Marooned With Low Rates?*** It’ll be held on Saturday morning, June 18th andwill be accessible to all of our ezine subscribers. If you subscribe to our ezine (see side panel), you’ll be receiving an invitation soon.
Jim
---
**Become an IFG client!** Don’t play phone-tag; schedule your 15-minute introductory phone call using [this convenient scheduler](https://www.meetme.so/JimLorenzenCFP "Schedule your 15-minute introductory call!")!
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing
**Tags:** Financial Security, Guaranteed Income, Interest rates, Liquidity and Safety, Rising income, Safe Money
---
### [How to Plan for a "Late Life" Income Without Giving Up Control](https://indfin.com/how-to-plan-for-a-late-life-income-without-giving-up-control/)
**Published:** June 15, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/latelifeincome)*iStock Images*
Jim Lorenzen, CFP®, AIF®
Scott and Linda (not their real names) have done everything right: They’ve worked hard, saved and invested wisely, and did all the right things.
But now, as they head toward retirement (he’s in his mid-fifties) he’s concerned about:
- What the federal debt means for income taxes during what could be three decades of retirement.
- Just what it would mean if they’d need long-term elder care later.
- What would happen if they had a major unexpected financial set-back or outlay at a time when the markets could ‘melt-down’ again.
- Whether all their assets will provide them with cost-of-living increases should the above happen.
They have a comfortable retirement planned and they have adequate assets, but the tax and inflation questions are enough to make them consider a further diversification approach that might help them ‘cover their bases’ without giving up control of their money.
[](https://indfin.com/latelifeincome)If you have over $500,000 in taxable investments (outside your 401(k) or IRAs) and are in your mid-50s, this case study might be of interest to you.
You can learn more and access it[ here](https://indfin.com/latelifeincome).
While I hope you find it informative, I would caution that no strategy should be implemented unless it’s part of a comprehensive financial plan; so, this is information you may find interesting, but not advice to be acted upon.
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Life Insurance, Planning, Retirement, Taxes
**Tags:** diversification, Reducing Risk, Retirement Income, Retirement Strategy, Tax-Free Retirement Income
---
### [Pension Plan Retirement Options](https://indfin.com/pension-plan-retirement-options/)
**Published:** July 13, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/07/Fotolia_5090081-DB-ForkInRoad.jpg)*Fotilla Images*
Jim Lorenzen, CFP®, AIF®
Choosing between pension options can be a difficult task. Choosing an option that guarantees your spouse pension benefits after your death means extra security but also lower monthly benefits.
On the other hand, choosing a pension option that only pays through your lifetime can provide larger monthly payments, but requires a lump sum to protect your spouse if your spouse outlives you. So, what’s the best choice? You need to get some numbers.
If you’d like see a calculation to help decide which pension option works best for your particular retirement needs, this is the information you will need to conduct an analysis.
**The input regarding your pension and plan retirement options information you’ll need to provide:**
- Your current age
- Retirement age
- Your health status and life expectancy
- Spouse’s current age
- Spouse’s health status and life expectancy
- Single monthly pension amount at retirement
- Joint monthly pension amount at retirement
- Rate of return on your investments (be careful, many miscalculate and overestimate this because they fail to include all their financial assets)
I’ve put together a series of concept pages onRetirement Pension Decisions you might find helpful. Just click on this link: [Retirement Pension Decisions Guide](https://indfin.leadpages.co/leadbox/141b9f073f72a2%3A12a1899aa346dc/5666644290437120/)
**If you need help putting an analysis together**, you can [schedule an introductory phone call](https://www.meetme.so/JimLorenzenCFP) with me. A reminder: You will need the above information for our call.
Jim
---
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi3.jpg)
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991.*
*Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement
**Tags:** pension decisions, pension options, retirement mistakes, Retirement Planning
---
### [TO ROLL? OR, NOT TO ROLL....](https://indfin.com/to-roll-or-not-to-roll/)
**Published:** October 20, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b0192ac05f306970d-320wi.jpg)*iStock Images*
Jim Lorenzen, CFP®, AIF®
Getting ready to pull the retirement cord? In a previous[post](https://indfin.com/pension-plan-retirement-options/), I had talked about pension options – worth reviewing if that’s an issue for you. I also recently provided an IRA[ rollover checklist](https://indfin.com/IRArolloverchecklist)for those evaluating the pros and cons of such a decision.
Whether or not to to do a rollover is not a simple ‘yes’ or ‘no’ question. It depends on your particular situation. There are good reasons both for and against rolling over your retirement plan to an IRA – the checklist can help sort those out.
**Believe it or not, there may be a reason to take some of your retirement out in cash and pay taxes right now!** How can that be?
If you’re on of those now doing your homework – good for you – you may enjoy reading this report, ***Six Best and Worst IRA Rollover Decisions***. This report not only discusses those decisions, it will also provide some insight on additional issues worth considering.
I hope you find it worthwhile. You can download it here> [Click here for your report!](https://indfin.leadpages.co/leadbox/147676173f72a2%3A12a1899aa346dc/5672463165816832/)
Before you get to the report, however, here’s a bit of news I came across fromMark Dreschler, the president and founder of Premier Trust. His words:
> The US Supreme court ruled this past June, in Clark v. Rameker, that inherited IRAs are NOT protected from a beneficiaries’ bankruptcy. Previously, this was an open issue. Now, the only way to protect an inherited IRA from inclusion in the beneficiaries’ bankruptcy, is to have a correctly worded IRA Inheritance Trust named as the beneficiary. This will also protect the IRA principal from other creditors, or divorce proceedings.
>
> However, if the distributions are paid directly to the beneficiary, they are NOT protected from bankruptcy or even attack in the event of a divorce. An IRA Inheritance Trust which also protects distributions from attack is called an “accumulation trust.” The trustee cannot be the child. The trustee has full discretion to hold distributions from the IRA in trust to protect the child or pass them out, depending on the circumstances. The child beneficiary may benefit from the distributed assets that the trust holds, but does not own them individually. Obviously, if the child-beneficiary has no title or control of the IRA distributions, they cannot be taken by a charging order or other legal means of attack.
Hope you find that helpful. And, don’t forget to [download your report](https://indfin.leadpages.co/leadbox/147676173f72a2%3A12a1899aa346dc/5672463165816832/).
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement, Taxes
**Tags:** company plan rollover, IRA rollover, retirement decisions, retirement mistakes, Retirement Planning, rollover mistakes
---
### [Investment Return Figures Can Take Many Forms](https://indfin.com/investmentreturns/)
**Published:** October 5, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/09/iStock_62491112_XXXLARGE.jpg)*iStock Images*
Jim Lorenzen, CFP®, AIF®
Many years ago a prospective client told me his investment returnshad averaged 25% per year over the past ten years. This was back in the ’90s when the markets were going strong and everyone (it seems) was watching ‘talking heads’ give their ratings of mutual funds on the various tv business channels.
He was sure he was earning 25% per year because his $100,000 had grown to $250,000, a 250% increase he said. And, as everyone knows, 250% divided by 10 years is 25% per year.
I didn’t bother asking him if he’d also been adding deposits to his account during that ten year period, in which case dollar-weighted returns would be different from time-weighted returns. But, even without additions, his real return was more like 9.6% – not bad (remember, it was a bull market), but a far cry from 25%.
But, that 9.6% was his compound return – and that’s different from his average return.
If you’d like to learn more about deciphering investment returns, you may enjoy this special report. You can access it by clicking the button below.
Enjoy!
[Special Report: Understanding Investment Returns](https://indfin.leadpages.co/leadbox/1412b3673f72a2%3A12a1899aa346dc/5651757665353728/)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** investment returns, understanding investment returns
---
### [17 Unexpected Retirement Expenses](https://indfin.com/17-unexpected-retirement-expenses/)
**Published:** October 12, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/10/Checkbook-Pen.jpg)**Jim Lorenzen, CFP®, AIF®**
The Society of Actuaries outlined 17 unexpected or shocking expenses during retirement in its 2015 Risks and Process of Retirement Survey. I’ve put those into a small report that explains why two in particular happen to too many retirees.
I hope you enjoy it. You can get yours by simply clicking on the button below.
[Click Here for your report](https://indfin.leadpages.co/leadbox/1430ef673f72a2%3A12a1899aa346dc/5665054615666688/)
—————–
Jim Lorenzen is a*[ CERTIFIED FINANCIAL PLANNER®](https://en.wikipedia.org/wiki/Certified_Financial_Planner)* professional and An Accredited Investment Fiduciary® providing private client wealth management services since 1991.
The Independent Financial Group is a registered investment advisor with clients located across the U.S. He is also licensed for insurance as an independent agent under California license 0C00742.Jim can be reached at 805.265.5416 or (from outside California) at 800.257.6659.
**Interested in becoming an IFG client?** Why play phone-tag? You can easily [schedule your 15-minute introductoryphone call!](https://www.timetrade.com/book/F7ZPS)
The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** Investment mistakes, Investment Strategy, retirement decisions, retirement mistakes, Retirement Planning
---
### [Thinking of Rolling your 401(k)? This checklist may help!](https://indfin.com/irarolloverchecklist/)
**Published:** October 18, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/09/iStock_62491112_XXXLARGE.jpg)*iStock Images*
Jim Lorenzen, CFP®, AIF®
Getting ready to leave your company? Considering doing a rollover? This isn’t a decision to be taken lightly. While rolling over your 401(k) or other qualified retirement plan to an IRA makes perfect sense for many people, it’s not an “automatic” decision.
I’ve put together a little checklist that may provide some help. I hope you feel it’s helpful for you.
Jim
[Click Here for your checklist!](https://indfin.leadpages.co/leadbox/141e8f273f72a2%3A12a1899aa346dc/5761253830033408/)
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an Accredited Investment Fiduciary® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of **The Independent Financial Group**, a Registered Investment Advisor providing retirement planning and investment advisory services on a fee-only basis. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriately licensed professional. All images used in this communication are in public domain unless otherwise noted.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement, Taxes
**Tags:** company plan rollover, IRA rollover, retirement decisions, retirement mistakes
---
### [Caring for a Loved One at Home? Here are some tips!](https://indfin.com/homecareresources/)
**Published:** October 25, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/10/20150419_094423.jpg)*Sunday Brunch at home*
Jim Lorenzen, CFP®, AIF®
Taking care of family does present its challenges; but, it can extremely rewarding – and a lot of fun!
If you’re one of those who’s embarking on this journey, there are a lot of resources available to you; but, there’s also a lot you’ll want to know.
My wife and I cared for my mom for nine years, and we’re now caring for her mom. As I said, there are challenges, but it can be a time you’ll never, or want to, forget.
The buttonbelow will get you to some tips you might find helpful, as well as some personal experiences that you may find worth knowing.
Enjoy!
[Home Care Resources and Tips You Can Use!](https://indfin.leadpages.co/leadbox/144da7673f72a2%3A12a1899aa346dc/5752142325350400/)
—————-
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues, Planning
**Tags:** Home care, Resources for helping an aging parent, Resoures for home care, Tips about home care
---
### [Looking for an Easy Bonus Plan for Your Key Employees?](https://indfin.com/looking-for-an-easy-bonus-plan-for-your-key-employees/)
**Published:** November 1, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017eea826334970d-320wi.jpg)*iStock Images*
**Jim Lorenzen, CFP®, AIF®**
Executive Bonus plans are a little different from Non-Qualified Deferred Compensation Plans (NQDC), which we talked about in another short paper. But, these types of plans are very popular!
The employee (or a third party, such as an irrevocable trust designated by the employee) purchases and owns the policy and even names the beneficiary.
The employee-policy owner has all the rights in the policy. The corporation never has any right to any part of the policy cash values, dividends, or death benefit. In fact, the corporation never has any incident of ownership in the policy.
Basically, it involves the purchase of a life insurance policy on the life of one or more employees, chosen by the employer. The employer pays the premium on the policy but charges the employee with a bonus with an amount equal to the payment. Under other arrangements, the employee can pay the premium and the employer adds the amount of the premium to the employees paycheck.
[](https://indfin.com/wp-content/uploads/2015/03/iStock_000003860264-FemaleLeader.jpg)*iStock Images***Why does a corporation do this?**
- Unlike the NQDC, the corporation, under IRS Section 162, can take an immediate tax deduction for the amount of the bonus.
- It provides valuable life insurance for key employees at little or no-out-of-pocket costs. The corporation has a great deal of freedom in deciding just who will be covered and has considerable flexibility, depending on the product type, regarding how much premium to pay. If cost is an issue, a permanent universal life product can provide essentially a term insurance equivalent.
- It’s completely confidential. No one other than covered employees need know about the plan
- It can be terminated by the employer at any time for any reason without justification to the IRS or the Department of Labor. There’s no termination penalty, as is the case with a qualified plan.
- It may be the most inexpensive and easy plan to implement and maintain.
- It’s appreciated because these plans provide real benefits for the chosen employees – and the benefits cannot be forfeited. Unlike a NQDC plan, assets in a Section 162 plan belong to the employee and cannot be reached by the employer’s creditors.
- The policy is portable. Termination of employment has no impact on policy values.
- Present or future management may discontinue premium payments, but the employee will not lose anything if the business is subsequently sold or there is a corporate takeover.
- Premiums payments may self-complete if the selected employee becomes sick or suffers an accident, if there is a disability waiver of premium rider. Cash values will continue to grow.
- Cash values, which accumulate income tax deferred, can be turned into tax-free supplemental retirement income, cash for an education, or any other need, in the form of policy loans.\\
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73d75677c970d-320wi.jpg)*Fotilla Images***Disadvantages:**
- Once the premium is paid, the employer generally has no control over either the employee or the policy. This can be somewhat controlled using a “Controlled Executive Bonus arrangement”, however, the employer bonus is generally enough of an incentive for the employee.
- Cash values are controlled by the employee; but then, it is a bonus plan and the employer did receive a tax-deduction for it.
- None of the cost of the plan will ever be recovered by the employer, compared to a split-dollar plan, which allows recovery of employer costs. However, bonus payments are seldom recoverable anyway; and, as stated earlier, this is one of the easiest and least expensive plans to set-up and maintain.
**Tax implications:**
- Bonus payments made, whether to the employee to pay the insurer or directly to the insurance company, are deductible by the employer.
- The bonus (premium) is reportable as income by the employee
- It’s likely that the payments will be considered a non-cash fringe benefit for withholding purposes, meaning that premium amounts should be added to regular cash wages and subject to appropriate withholding.
- Since the employee has already paid tax on the full cost of the policy, the employee’s cost basis is equal to the sum of the all premiums paid by the employer. This basis can be used to offset income tax as amounts are withdrawn when the policy is surrendered.
If you’d like to see how it works, the click the button below and I’ll send you our concept sheet that shows how anExecutive Bonus Plan looks “in action”.
[Get Your Executive Bonus Roadmap!](https://indfin.leadpages.co/leadbox/1451e0573f72a2%3A12a1899aa346dc/5651276360581120/)
[](https://indfin.com/wp-content/uploads/2014/03/6a017c332c5ecb970b01a51174caed970c-120wi.jpg)To learn more, talk with your advisor, or seek out an independent insurance professional. Look for credentials such as CFP, ChFC, or CLU. An independent will not only know the ins-and-outs of the ratings agencies (some highly-rated companies have failed during past melt-downs, remember?), as well as which companies stand-out in this part of the market. The right advisor should be able to bring the right experts to the table for you. Of course (shameless promotion), you can[ contact me!](https://www.meetme.so/JimLorenzenCFP)
Jim
---
***[](https://indfin.com/wp-content/uploads/2014/03/6a017c332c5ecb970b01a51174cbb0970c-120wi.jpg)Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and an Accredited Investment Fiduciary® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of **The Independent Financial Group**, a Registered Investment Advisor providing retirement planning and investment advisory services on a fee-only basis. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriately licensed professional. All images used in this communication are in public domain unless otherwise noted.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Business Owners, Executive Compensation, Planning, Retirement
**Tags:** Bonus plans, Executive Benefits, Executive Bonus
---
### [Will Your Retirement Money last? Maybe - with the right 'Late Life Income' strategy.](https://indfin.com/latelifeincomestrategy/)
**Published:** November 15, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/06/iStock_44633966_SMALL.jpg)iStock Images
Jim Lorenzen, CFP®, AIF®
This past Monday, I retweeted a Fox Business post, [*Why Your Retirement Savings May Be a Pipedream.*](https://www.foxbusiness.com/features/2016/11/14/why-your-retirement-savings-may-be-pipe-dream.html)
A number of my clients, deciding to help ensure their late-life income needs will be met, have in the past elected to execute a “late life income” strategy – however, they wanted one that would not lock them in to the low rates and liquidity issues that come with annuities.
I created a hypothetical – translate *fictitious* – [Late Life Income “case study”](https://indfin.com/latelifeincome) of what such a strategy might look like for the right candidate couple (this may not be right for everyone). You can learn more by getting it [here](https://indfin.com/latelifeincome).
Enjoy,
Jim
————
[](https://indfin.com/wp-content/uploads/2014/09/Resized-CFP_Logo_Gold.jpg)Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an Accredited Investment Fiduciary® serving private clients providing retirement planning and wealth management services since 1991. Jim is Founding Principal of The Independent Financial Group, a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.[](https://indfin.com/wp-content/uploads/2014/03/6a017c332c5ecb970b01a51174cbb0970c-120wi.jpg)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Life Insurance, Planning, Retirement
**Tags:** retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy
---
### [Planning to Roll Your 401(k) to Your Own IRA?](https://indfin.com/planning-to-roll-your-401k-to-your-own-ira/)
**Published:** November 29, 2016
**Author:** Jim Lorenzen
**Content:**
**Jim Lorenzen, CFP®, AIF****®** Getting ready to retire? Planning to roll your 401(k) into your own IRA? It will pay to do your homework first.
To help you get started, you might find our 401(k) Rollover Reviewhelpful. It contains information on changing jobs, retiring, methods, rollover taxation issues, and more.
[](https://indfin.com/wp-content/uploads/2016/11/i303a_IRA-Rollover-Review_Overview-Report_vsa_001.png)[Click Here for your 401(k) Rollover Review!](https://indfin.leadpages.co/leadbox/142e92773f72a2%3A12a1899aa346dc/5646392177459200/)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement, Taxes
**Tags:** 401k decisions, company plan rollover, IRA rollover, retirement decisions, retirement mistakes, Retirement Strategy, Retirement tax strategies, rollover mistakes
---
### [Department of Labor Wants Consumers To Know Their Advisor's Fiduciary Status](https://indfin.com/dolconsumer/)
**Published:** January 17, 2017
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b019aff2c9b18970d-320wi.jpg)*Fotilla Images*
**Jim Lorenzen, CFP®, AIF®**
The DOL wants investors to know who their “advisors” are and just how they operate when giving advice to consumers regarding their retirement accounts, i.e., 401(k)s, IRAs, etc.
Under the new rules, which are scheduled to be phased-in over time beginning in April, any financial advisor providing advice on retirement accounts must act as a fiduciary – clients’ best interest must be the sole consideration – as opposed to operating under the old “suitability” standard – as long as the investments recommended are suitable, they pass the test, i.e., the recommendation doesn’t have to be in the client’s best interest.
RIAs (Registered Investment Advisors) have been operating under that standard for all client accounts for years; but “dually-registered” financial advisors – those selling securities as registered representatives of broker-dealers who are also registered as RIAs – have been utilizing two different standards, thus providing a confusing landscape for many investors who may find it difficult to determine just when their advisor is wearing which hat.
Commissions aren’t really the issue; however, because of the conflicts commissions can create, any advisor who provides advice or recommendations on retirement account investments for commission compensation will be required to provide the client with a Best Interest Contract Exemption (BICE) agreement.
The DOL has posted a consumer protection piece on their website, containing a more complete explanation, as well as a list of questions consumers should ask their advisor. See[DOL Consumer Protection Rights](https://indfin.com/wp-content/uploads/2017/01/DOL-Consumer-Protection-Rights.pdf).
Hope you find this helpful.
Jim
---
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi2.jpg)Opinions expressed are solely those of the author. The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.[](https://indfin.com/wp-content/uploads/2014/03/6a017c332c5ecb970b01a51174caed970c-120wi.jpg)James Lorenzen is a *Certified Financial Planner®* professional and an *Accredited Investment Fiduciary*® in independent practice since 1991. The Independent Financial Group is a fee-based registered investment advisor with clients located across the U.S. Jim is also licensed for insurance as an independent agent under California license 0C00742.Jim can be reached at 805.265.5416 or (from outside California) at 800.257.6659.[](https://indfin.com/wp-content/uploads/2014/03/6a017c332c5ecb970b01a51174cbb0970c-120wi.jpg)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Retirement
---
### [Will My Money Last?](https://indfin.com/will-my-money-last/)
**Published:** January 31, 2017
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/11/Piecing-Retirement-Puzzle-Path.png)**Jim Lorenzen, CFP®, AIF®**Scott and Linda (not their real names) are in their 50s and have done a lot of things right: They’ve worked hard, saved and invested, and they’ve been practical in their spending.
They feel like they’re well on-track to a secure retirement; but, a few “wild cards” do have them concerned:
- **Inflation and longevity**: They know what’s happened to their purchasing power over the last 30 years. They’re concerned about the next 30+ (maybe 40) when they’re living off their investments.
- **Taxes**: While there may be a temporary reduction coming now, they also know the U.S. is facing a $20 trillion debt and there will be 7 or more presidential elections – not to mention 15 congressional elections – that will take place in the next 30 years. That spells a lot of potential changes and changes in tax laws. They want old-age income that will be protected from the politicians.
- **Health costs**: A huge wild-card. They know the odds are about 50% one of them will need it, but they don’t want to see long-term-care insurance money going down the drain if they don’t need it. They also want money available if they do have a chronic illness.
- **Liquidity**: They want money available for emergencies during retirement without having to jump through a ton of hoops.
I thought you might like seeing a [sample case study](https://indfin.leadpages.co/leadbox/14076cc73f72a2%3A12a1899aa346dc/5734616174428160/) about how one couple addressed this issue.
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Life Insurance, Planning, Retirement, Taxes
**Tags:** Retirement Income, secure retirement, Tax-Free Retirement Income, Taxes in retirement
---
### [Can You Reduce Risk By Adding To It?](https://indfin.com/riskreport/)
**Published:** February 7, 2017
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/09/iStock_62491112_XXXLARGE.jpg)*iStock Images***Jim Lorenzen, CFP®, AIF®**
Ever wonder why so many “off-the-shelf” allocation engines available today tend to look so much alike? The reason is pretty straightforward: The investor’s menu of choices is limited by the engine provider based on similar sets of data inputs and a short risk questionnaire. When you couple that sameness with a fear of placing “risky” investments in the hands of the general public in a litigious culture, you get what you’d expect: Off-the-shelf tends to look a lot alike with limited ‘plain vanilla’ investment options and sometimes, if not often, a proprietary product line.
“Plain vanilla” isn’t bad! However, there are ways a little pinch of something can actually enhance the flavor without causing stomach upset.
You might find this risk report interesting, if not helpful.
[Risk Report](https://indfin.leadpages.co/leadbox/14327a573f72a2%3A12a1899aa346dc/5747976207073280/)
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** Retirement Income, secure retirement, Tax-Free Retirement Income, Taxes in retirement
---
### [Trying to Keep Top Talent? This could be your roadmap](https://indfin.com/rebareport/)
**Published:** February 21, 2017
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2015/03/YoungExecSmilingAtMeeting.jpg)*iStock Images***Jim Lorenzen, CFP®, AIF®**
No, that’s no my picture – I wish I were that young and good looking; but he does look like a happy executive who’s worth keeping…. a key employee!
Key employees don’t have to be executives. It can be anyone who is valuable to a business, particularly a small business that has to compete to attract top talent – and keep them from jumping ship to joina larger competitor or to start their own business in competition with you (trying to enforce non-compete agreements is no fun and costs far too much time and money, not to mention lost opportunities).
Small business owners often aren’t established enough to offer expensive benefit packages, but they want to find a way they can offer the right incentives to benefit their top people.
You might be interested in learning about the REBA, or GEBA, as some call it. It’s a Restrictive Executive Bonus Arrangment, or Golden Executive Bonus Arrangement.
They’re pretty simple to set-up and can be designed to provide flexibility for the owner.
You can get a copy of the REBA Report by using the button below. Hope you find it helpful.
[Get My REBA Report!](https://indfin.leadpages.co/leadbox/143f3e773f72a2%3A12a1899aa346dc/5698497110081536/)
Enjoy,
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Business Owners, Executive Compensation
**Tags:** business owners, business owners retirement, selling closely-held business, Selling your business
---
### [Is Your Business A Ticking Grenade?](https://indfin.com/tickinggrenade/)
**Published:** February 28, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2016/11/Transferring-Business.png)Jim Lorenzen, CFP®, AIF®**Did you know that as much as 80% to 90% of many business owner’s net worth is tied-up in their businesses?
According to the Exit Planning Institute’s State of Owner Readiness survey, 83% of business owners do not have a plan for how they will leave their business.
It’s interesting when you consider the number one reason a business owner sells is to fund retirement. The stats above are even more alarming when you consider that 70% of those doing over $1 million in revenue are 54 years old or older; and many businesses distribute all their cash flow to their owners with little in the way of cash reserves set aside.
[](https://indfin.com/wp-content/uploads/2016/07/Fotolia_5090081-DB-ForkInRoad.jpg)*Fotilla Images*Businesses like these are called “lifestyle’ businesses; and many experts agree that up to 90% of all closely-held businesses operate just this way: They are simply operated until they shut the doors. This being the case, it’s no wonder that 50% of all businesses end-up closing their doors unexpectedly.
When this happens, the only thing the business owner can fall back on is retirement savings, if there are any, including the business’ 401(k), which often proves insufficient simply because it’s funding limitations often can fall short of what an owner will need in retirement to preserve his/her pre-retirement lifestyle.
Many business owners intuitively understand that there business either does or should have resale value allowing them to cash-out their equity. The problem arises, if they’ve waited too long to address this issue, is not only the ability to find a viable buyer with money, but even one that’s ‘bankable’ – one able to arrange financing outside of the selling owner; after all, no seller wants to have to come back in and retake control of a now failing business.
[](https://indfin.com/wp-content/uploads/2016/11/Solution-Puzzle-Piece-2.png)There are a number of solutions available to an owner who begins planning early – the earlier the better. Just to provide one example, one solution is called the “**One-Way Buy-Sell**“.
It’s just one possible option among many, but you may find it interesting. I caution, however, not to assume it’s the right solution for you. The best solution is one that’s tailored to the business owner’s unique circumstances; but, FYI, you may enjoy learning about this one. You can get a copy of our One-Way Buy Sell Report by using the link below:
[One-Way Buy-Sell Report](https://indfin.leadpages.co/leadbox/14764a473f72a2%3A12a1899aa346dc/5761493274460160/)
Enjoy,
Jim
---
***[](https://indfin.com/wp-content/uploads/2014/09/Resized-CFP_Logo_Gold.jpg)Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
*Jim’s background includes founding, building, and selling five successful businesses and international consulting. He has been the headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications, as well as scores of state, regional, and national conventions. Jim has also been featured on American Airlines’ Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights, and has been published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.*

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Business Owners, Life Insurance, Planning, Retirement
**Tags:** business owners, business owners retirement, selling closely-held business, Selling your business
---
### [What's Your Focus?](https://indfin.com/whatsyourfocus/)
**Published:** March 14, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/09/Fotolia_7236556-MakingPiecesFit.jpg)Jim Lorenzen, CFP®, AIF®**Most people buy life insurance based on the same outdated advice they’ve been given for years. It’s predictable: buy term – and, for many people term insurance makes the most sense! Others have been told they should buy “whole life” because it’s permanent and comes with the most guarantees; and, for many people that probably is the best choice – and it does come with the most guarantees.
All generally agree they should buy the most amount of death benefit for the least amount of money – and in some cases, that’s true as well – but, not in all cases.
Different strategies and case designs are possible to achieve a wide variety of objectives and all can make sense for some people and not for others. This should be no surprise. There are people who are allergic to foods other people love – my dad, for example, couldn’t eat peanuts, but I could munch on them all afternoon.
If you’re wondering what kind of life insurance strategy makes the most sense for you, the first thing to do is to identify your focus – your priorities. Life insurance can be simple death protection or it can function as a highly versatile financial tool accomplishing a number of objectives.
What’s your focus? What do you want life insurance to accomplish for you? Here’s a little tool you can use to help identify your focus; so, when you talk to an advisor (naturally I hope it’s me, but it can be anyone you trust), you’ll be able to more clearly communicate just what your needs really are.
Hope you find this helpful.
[What’s Your Focus Life Insurance Priorities Tool](https://indfin.leadpages.co/leadbox/146504373f72a2%3A12a1899aa346dc/5742351410528256/)
By the way, when you request this tool, you’ll also receive future issues of my ezine. I hope you find that helpful, as well; but, you can unsubscribe at any time and be removed from the list immediately.
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Life Insurance, Planning, Retirement
**Tags:** life insurance, life insurance decsions, Retirement Income, secure retirement, Tax-Free Retirement Income, Taxes in retirement
---
### [Someone else likes your key employee - Your competition!](https://indfin.com/easybonusplan/)
**Published:** March 28, 2017
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2015/03/YoungExecSmilingAtMeeting.jpg)*iStock Images***Jim Lorenzen, CFP®, AIF®**
Successful business owners know they’re successful because of their people. Within that group there’s usually one or two key people that either seem to make everything run well or, without their presence, the business would suffer a significant loss of revenue. Sometimes they have special vendor or banking relationships, which means the banker’s terms may not be as good if those key people left, until the business could ‘prove itself’ again.
**You value your key people. So do your competitors.**
How does the small business owner compete with competitors who can offer hefty benefit packages – or keep key employee(s) fromstriking out on their own?
This report shows one easy way small business can compete! You can access it [here](https://indfin.com/easybonus).
Hope you find it helpful.
Enjoy,
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Business Owners, Executive Compensation
**Tags:** business owners, business owners retirement, selling closely-held business, Selling your business
---
### [A Slick 2017 Market Outlook Infographic!](https://indfin.com/2017vgoutlook/)
**Published:** April 4, 2017
**Author:** Jim Lorenzen
**Content:**
**Jim Lorenzen, CFP®, AIF®**[](https://indfin.com/wp-content/uploads/2017/04/Vanguard_InfoGraphic_20172Q-2.png)Jim Lorenzen, CFP®, AIF®
Here’s an interesting market outlook infographic from Vanguard! Thought you might enjoy seeing it!
Just click on the image; you can enlarge it.
The White Paper referenced was written at the end of last year, but you may still find it interesting. You can get it[here.](https://indfin.com/wp-content/uploads/2017/04/Vanguard-White-Paper17.pdf)
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Economy
**Tags:** life insurance, life insurance decsions, term insurance vs permanent
---
### [Business Owners Face Potential Tax Law Changes](https://indfin.com/business-owner-tax-law-changes/)
**Published:** October 16, 2017
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b0192ac05f306970d-320wi.jpg)iStock Images
**Jim Lorenzen, CFP®, AIF®**
**1954**
**1986**
**2017**
**What do those years have in common?** If you guessed those were the years of major tax reform, you’d be right–at least about the first two. 2017 is still a question mark.
While tax law changes can occur quite often, major reforms appear to come around about every thirty years. Business owners, unlike the rest of America, will have to deal with the impact of any changes on both the personal and business front.
Most Americans don’t own businesses and can be excused for not understanding many of the issues business owners face. First, most businesses tend to be small – proprietor-owned – and are therefore taxed at individual rates; and that includes partnerships. They don’t get taxed at the lower corporate rate; yet, these owners represent most of the job creation. Those who are successful, pay at high rates – and even more if they’re in a high tax state! It’s not uncommon for a successful small business owner in a high-tax state, like California or New York, to be faced with having to make $300,000 in pretax profit, only to see half of it go to federal, state, and local government, leaving about $150,000. Sound like a lot? Not if you’re in one of those high cost-of-living states, which usually happen to be the same ones, in which case $150,000 is often just middle-income. Makes it pretty hard to create jobs for other people – often the reason many of these businesses often relocate to low-tax states (with a lower cost of living) to grow their businesses, where they find it easier to create jobs.
How about corporations? Most Americans don’t realize that those who incorporate their businesses are taxed twice. Their business pays a tax on profits BEFORE the business pays a salary to the business owner, who then must pay a second income tax! And, of course, we’re back to the high income-tax state issue.
The government drains money from the people who create the jobs; so, no wonder – as people want to see more jobs in the economy – tax reform is such a big issue.
**Proposed Changes for Business**
Under the proposed tax bill, which still faces much debate, the corporate tax rate would be reduced to 20% – a substantial cut. S-Corps would see their rate drop to 25%. Well, maybe not – what day is it? This all changes with the wind until it’s law.
One of the proposed changes, favored by many business owners, would allow for the expensing of capital expenditures–no doubt in an effort to spur growth. However, there could be a fly in the ointment for many business owners in a provision no one’s talking about.
You’ve heard about the ‘border tax’. Under this provision, there would be no cost-of-goods deduction on imported goods–a potential problem for many retailers, as well as manufacturers who outsource some or all of their supply chain.[](https://indfin.com/wp-content/uploads/2016/02/iStock_UncleSamLiftingWallet_Medium.jpg)
Many businesses that have spent years researching and developing their supply chains may face some formidable challenges. There would be a deduction for the cost of goods exported.
Finally, there would be no deduction for business loan interest under the proposed plan. This may not be a big issue now, given today’s low interest rates; but, it could become a major issue if we should ever experience the double-digit interest rates similar to those of the late 1970s.
**[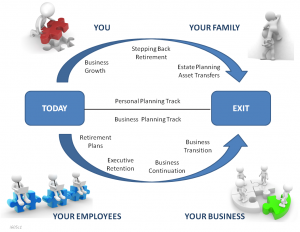](https://indfin.com/wp-content/uploads/2016/11/i605c1_BO_Lifecycle_slide_201611.png)Business owners are individuals, too.**
As if dealing with all a business owner faces isn’t enough, there’s also the personal side. There are some potential changes looming on the horizon there worth knowing about.
Individual tax rates would come down and reduced to three brackets.
The elimination of all itemized deductions except for mortgages and charitable contributions is also popular with many, but not everyone. The proposed change for charitable deductions limits those deductions to $100,000 for a single payer and $200,000 for a married couple. It may become difficult for a charity toconvince a multi-millionaire to donate that $1 million work of art !
And, while there’s talk of repealing the estate tax, it doesn’t appear to be a complete repeal. The government still wants that unrealized appreciation taxed! The talk is about going to a system similar to what they have in Canada.
The idea would be to tax unrealized appreciation over $5 million at a capital gains rate. Taxes on gifts would correspond to eliminate people using gifting to avoid the estate tax.
Finally, the newest proposal would also do away with deductions for medical expenses–or at least have a very high threshold.
All these are proposed–not passed. But, it’s good to be aware
[](https://indfin.com/wp-content/uploads/2016/07/Fotolia_5090081-DB-ForkInRoad.jpg)*Fotilla Images*of what could be on the horizon.
**What Should Business Owners Do?**
You might discuss these points with your tax advisor–I am not a CPA. I am a CFP®, AIF®,,,, EIEIO.
***Planning Point***
If you don’t have an executive bonus plan, you may want to consider starting one and paying the bonus before March 15, 1018. Same if you do have one. Your business gets the 2017 deduction while the employee may be paying tax on the bonus received at lower tax rates. If you’re `grossing up’ the bonus to cover the employee’s tax payment, that would be under the 2018 rates, as well–remember, talk to your tax advisor. If you want to learn more about these plans,you can access my [special report here](https://indfin.com/easybonus).
***Planning Point***
Don’t neglect what is probably the most versatile financial tool available today: cash value life insurance–it has tax benefits that no other financial vehicle can provide and is an ideal retirement supplement–especially for high-earning executives and owners who are limited in what they can put away in qualified tax-deferred vehicles. Quite often, these executives are stunned to find out those limits simply will not allow the account to provide enough capital at retirement for them to preserve their desired lifestyle.
[](https://indfin.com/wp-content/uploads/2016/11/Solution-Puzzle-Piece-2.png)As David McKnight points out in his book, *Tax Free Retirement*, life insurance is used as a key retirement strategy by more than 85% of Fortune 500 CEOs and many members of Congress. The book was also endorsed by retirement guru and CPA Ed Slott, as well as David M. Walker, former Comptroller General of the United States.
Sometimes, I will see arguments against this approach in the media – arguments that are little short of idiotic – but, the simple truth is that insurance, including indexed universal life (IUL) in particular, is becoming widely accepted among leading experts in the profession as a true asset class (in addition to cash, stocks, bonds, real estate, and commodities), probably as a result of an aging population with changing priorities and increasing economic uncertainty (where the government’s future need for tax revenue is concerned).
- Your tax advisor can provide the best insight regarding tax strategy;
- your estate planning attorney can help you make sure your documents are updated and in order; and
- your financial advisor should be able to help you arrange assets to fit your needs.
Never use a podiatrist for dental advice.
I hope you found this helpful.
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Business Owners, Executive Compensation, Investing, Planning
**Tags:** business owner tax planning, business owners retirement, Investment Strategy
---
### [MONEY OR INCOME: Which is most important to you?](https://indfin.com/incomeormoney/)
**Published:** August 1, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/09/Piggy_Bank_on_Side.png)Jim Lorenzen, CFP®, AIF®****Which goal is most important to you?**
– Never running out of retirement money
– Never running out of retirement income
– Both
**Sure, you said both**. And, maybe that’s possible!
The problem for many is that not only are substantial assets required to provide a comfortable retirement income – you also have to live a lifestyle below what many would believe you could afford.
I have a client couple who have done just that. They’ve worked hard, invested responsibly, and lived well within their means allowing them to save at a rate greater than what would appeal to many others. The result: They’ve been able to retire in their late ’50s in a beautiful area – and doing it at a time their son graduated from college and is now entering grad school. How many parents could afford to retire with a child entering grad school? In short, they’re set! They’ve taken all the right steps to insure their future, even into their 80’s and 90s… and even if everything in “the markets” went south on them.
I’ve also seen others who have amassed ten times that couple’s assets, but are living at a lifestyle that keeps them in perpetual jeopardy. They’re constantly in danger of running out of money. Their lives are like a hamster running on the spinning wheel, constantly chasing the cheese. The lesson: Even people with$30 million dollars canstill be on the edge of disaster. Think of all the multi-million dollar sports and entertainment figures who’ve ended-up broke, sometimes due to poor management, sometimes due to overspending, sometimes both, virtually always because of ignorance…. either on their part or the part of their ‘managers’, or both.
**[](https://indfin.com/wp-content/uploads/2014/09/Solution-Puzzle-Piece.png)Choosing the right strategy**
What kind of retirement income or wealth management strategy makes senseany given investor? Naturally, it depends on age, goals, asset level and lifestyle. It also depends upon what type of strategy the individualis open to considering – most of us have built-in biases based on how we’ve been programmed.
Given the level of financial literacy in America today, it’s a real concern. Most of what people know about financial instruments they’ve learned from entertainment gurus, their parents, or their friends. I saw a recent study that revealed more than 31% of Americans didn’t know they could lose money in fixed income investments; and 68% thought rising interest rates would be good for bonds… all while 60% said they don’t consider themselves knowledgeable regarding fixed income, the market, or economic forces that drive bond pricing.
Generalizations are always dangerous; but hey, you’ve have to start somewhere, right? So, let’s begin, as a starting point, with this basic admittedly oversimplified outline of what an overall retirement strategy might be:
[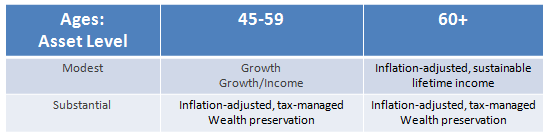](https://indfin.com/wp-content/uploads/2017/05/Retirement_Strategy_Grid.png)
You might be wondering why those below age 45 aren’t included in my little over-generalized grid. The answer is simple: In 25 years’ of practice, only ONCE has someone below age 45 come to my office. That was almost 20 years ago and I haven’t seen anyone in their 40s come to my office since – they’re still watching Kramer- but, I’ll see them after they turn 50 and finally figured something out they don’t know today.
Back to our grid:
The definitions of “modest” and “substantial” are somewhat squishy. It’s like trying to define what a ‘middle-market’ company is – you can ask a hundred people and get a hundred different answers. So, let’s just say the definition is whatever you think it is.
If you’re worried about running out of money, you might consider yourself to be a “constrained investor” – and you probably shouldn’t be trying to ‘make up for lost time’ by making risky bets.
If you’re like the couple who’s sitting pretty and just doesn’t want to blow it, you might be preservation minded – someone who wants to maintain their lifestyle after inflation and taxes and not do anything stupid. \[See my blog post, “***Inflation and Stocks***” [here.](https://indfin.com/inflationandstocks/)\]
**Back to our initial quiz:**
Which worries you most: Running out of money or running out of income?
[](https://indfin.com/wp-content/uploads/2017/05/lighthouse.jpg)*Long term plans dont change just because temporary conditions do*You can have an income forever; but, it may not be enough to even pay your utility bill if the asset base is too small; and, if you
run out of money, there’s no income.
Navigating it all is much like navigating a ship at sea, surrounded by all sorts of potential hazards.
Too much to cover in a single post, as you might imagine; so, we’ll be covering the issues and strategies you can use in upcoming installments. I hope you’ll find them helpful.
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** investment returns, Investment Strategy, managing risk, Reducing Risk, retirement decisions, Retirement Income
---
### [Old-Age Financial Security: Silence is NOT Golden, yet Some aren't talking!](https://indfin.com/canwetalk/)
**Published:** July 17, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2016/11/Fotolia_2204049-DB-Teamwork.jpg)Jim Lorenzen, CFP®, AIF®****Generational planning didn’t seem**important for old age financial security in my grandparent’s day. They were living at a time when Social Security was passed and designed to last for a lifetime beginning at age 65. Of course, life expectancy back then was around age 68! Who needed to worry about generational issues? Longevity wasn’t a risk.
My generation–the baby boomerss–became the first to experience the ‘sandwich’ effect: Taking care of aging parents and children at the same time. And, as that was unfolding, people were beginning to realize they were living longer, too!
**The cultural quicksand** began to materialize, but few have recognized it. It’s like glaucoma: You don’t see it coming; but, all of a sudden, it’s there. It’s silence. In a recent online survey (cited below), over half of GenX respondents and 60% of baby boomers indicated they’ve never had a conversation about planning for retirement or financial security in their old age, yet their fears were the same.
[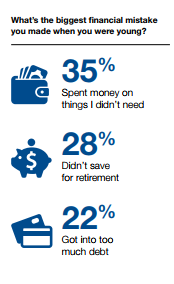](https://indfin.com/wp-content/uploads/2017/07/Financial_Mistakes.png)The reasons tend to tell is why. They’re repeating the same mistakes their parents made.
Why do we study history? Because we know human nature doesn’t change–it hasn’t changed for thousands of years. Studying history allows us to learn the mistakes human nature, unencumbered by knowledge, tends to make. But, knowledge helps us prevent a repetition!
When parents and children don’t talk about finances, guess what…
Why do they feel they’re not making enough money? Why do they have too many other expenses and are paying off debt? The answer is simple.
**They’re repeating mistakes.** But, the GenX group seems to be making more of them. Are the boomers not talking to their kids? Are their kids not involved in their parent’s ownplanning? Maybe they should be.
[](https://indfin.com/wp-content/uploads/2017/07/5_-_Supporting_Others.png)As parents are living longer–longevity risk– they run a very real risk of needing long-term care. If ever there was a threat to old age financial security, this may be it; yet, relatively few address that issue usually because of cost or for fear of losing all that money paid in premiums if they don’t use it. However if they do need it, and the kids end up having to pay some or all of the ultimate cost for that and their parents’ support, it also could eat-up their inheritance!
**What we don’t know can cause financial hurt**. Perhaps they don’t know that a professionally-designed life insurance policy might provide tax-free money that could be used to cover long-term care if needed and yet preserves cash if it isn’t–and still maintain the children’s inheritance! It’s a financial ‘Swiss Army Knife” type tool that can solve a lot of issues at once.
Unfortunately, few people take the time to have a generational financial planning session either on their own or – maybe better–facilitated with a family financial advisor acting as a guide and facilitator. Some advance planning can make a big difference. Here’s an example:
***Real Life Case History****(Names changed)*
*Fred and Wilma never discussed their finances with Pebbles or Bam Bam. As Fred and Wilma grew into their 90s, it became evident they could no longer live on their own. Fred was diagnosed with a terminal disease and Wilma, at 90, was diagnosed with Alzheimer’s. They could no longer function and it was now Pebbles’ and Bam Bam’s turn to take care of their parents. Fred lived for eight more months, but Wilma continued living for nine more years. Despite the fact they did have some retirement savings, it was no where near enough to cover the more than $600,000 in costs that were incurred by Pebbles and Bam Bam during that 9-year period.*
Had Fred and Wilma taken the right steps sooner, those costs threatening the old age financial security of Pebbles and Bam Bam might have been covered, or–at the very least–Pebbles and Bam Bam would have been reimbursed, protecting their inheritance … and all of the money might have been provided tax-free! Unfortunately, their attitudes about various financial solutions available to them were colored by what they’ve heard from parents, friends, and even entertainment media, including television gurus selling DVDs. Not surprising. Some people even get their medical advice that way.
Old strategies simply don’t address today’s longevity and ageing issues. Different strategies are required. How can it be possible to make sure the parents have a lifetime of inflation-adjusted income and still provide an inheritance for the kids?
[](https://indfin.com/wp-content/uploads/2014/09/LTop_Maintain_Purchasing_Power.png)You might enjoy viewing this educational [20-minute video](https://www.ifg.incomeforlifemodel.com/) that shows one strategy that likely makes sense for many people. While the tools used to implement it might vary, it’s still worth a view. So, grab some coffee and [see for yourself.](https://www.ifg.incomeforlifemodel.com/)
If you haven’t had a generational meeting with your family financial advisor, maybe it’s time you did. Like Mark Cuban’s dad once told him: ***This is as young as you’re ever going to be*.**
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
Enjoy!
Jim
[](https://indfin.com/wp-content/uploads/2017/07/Not_Talking_Methodology_Disclosure.png)
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues, Investing, Life Insurance, Planning, Retirement
**Tags:** investment returns, Investment Strategy, managing risk, Reducing Risk, retirement decisions, Retirement Income
---
### [Beware of Mortgage Loan Scams](https://indfin.com/mortgageloanscams/)
**Published:** September 5, 2017
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2017/05/Older-man-with-cash_gettyimages.jpg)*Getty Images*
**Jim Lorenzen, CFP®, AIF®**
First I want to point out that this post is really courtesy of Senior Deputy Becky Purnell of the Moorpark Police who provided this information in the City of Moorpark Guide; but, I thought it was so worthwhile I wanted to relay the information here.
According to Deputy Purnell, you should be aware that **scammers are targeting email accounts of realtors and escrow and title companies in order to steal your money!**
So, if you are buying a home or refinancing, you should be alert to what could be happening and how to protect yourself.
- The scammer hacks into the email account of a real estate agent or escrow officer and monitors correspondence between that person and the home buyer. The scammer then creates an email that is nearly identical to the agent or officer’s email, including their writing style, logos, and signatures.
- About the time the home buyer would expect to receive instructions on how to wire the money, the scammer sends instructions to wire the money to a specified account which goes to the scammer. The agent or escrow officer is unaware this is happening
This scam targets people who are in the refinancing process and any other transactions that include the wiring of money. Here are some ways Deputy Purnell recommends for protecting yourself:
- Before you wire money, speak with the realtor/escrow officer by phone or in person to get wiring instructions and confirm the account number is legitimate.
- Do not email financial information. It isn’t secure. Many financial firms do what I do: they provide secure vault access to their clients so that documents never go through an email system.
- Look for web addresses that begin with https (the s stands for secure). Don’t click on email links that come in emails – it’s always safer to look up the website’s real URL and type in the address yourself.
- Be cautious about opening email attachments. Those files could contain malware.
- Be sure your browser and software are up to date.
Especially if you’re getting emails from someone you don’t know, never click on the link. Even when I get a link from my own bank, I never click on it. I always enter the correct URL manually to gain access.
You can set-up a spreadsheet with columns for website names, URL, ID, Username, Passwords, and security questions and answers; but, make sure you spreadsheet is password protected and not accessible to others (you may want to store the data on an external drive, or example).
Hope this helps! If you’d like to learn more about IFG,we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP) You can click on that link (if you feel confident), or you can simply go to the IFG website and contact me through the site. www.indfin.com.
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues
**Tags:** investment returns, Investment Strategy, managing risk, Reducing Risk
---
### [What To Do With Business Sale Proceeds](https://indfin.com/businesssaleproceeds/)
**Published:** October 30, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2017/10/Older-man-with-cash_gettyimages.jpg)Jim Lorenzen, CFP®, AIF®**When you receive business sale proceeds, you’ll likely pay a capital gains tax; but, that may not be the end of the story.
Suppose you have $1 million or more after the sale – money you’d like to put somewhere for future use – but you also want growth with safety and tax-deferral, too!
You could use our 401(k); however, there are funding limits in any given year and those limits don’t carry over. Besides, the safety issue could be problematic.
Bank certificates of deposit can provide safety, but not growth or tax-deferral.
If you’re selling your business next year, you’ve waited too long to plan. However, if your sale is scheduled for ten, fifteen, or twenty years from now, this IS the time to get your ducks lined-up – and this report might help.
[Click Here!](https://indfin.lpages.co/leadbox/141be9d73f72a2%3A12a1899aa346dc/5697070107197440/)
By the way, when you get the report, you’ll also be subscribed to our free ezine. If you decide you don’t want it, simply unsubscribe at any time – your name will be removed immediately. IFG will never share your email address with anyone for any reason.
If you would like help, of course, we can always [visit by phone.](https://www.meetme.so/JimLorenzenCFP)
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Business Owners, Investing, Life Insurance, Planning, Retirement
**Tags:** business owner tax planning, business owners retirement, Investment Strategy
---
### [Managing Retirement Income Decisions During Retirement](https://indfin.com/managingretirementincome/)
**Published:** November 27, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2016/11/Fotolia_4812344-DB-wDollarSign.jpg)Jim Lorenzen, CFP®, AIF®**Managing retirement income has never been easy. Those who retired in the early 1970s saw interest rates rise dramatically, then fall the same way – all within about a 15-year period. When interest rates were going up, it made them feel good; but, few paid attention to inflation or tax implications. During one period, interest rates were in the double-digits, but so was inflation, which meant their “increased” income wasn’t really increasing at all. Money is worth only what it buys at the checkout counter.
So, the retiree who felt great about a 15% interest rate during 15% inflation (yes, it really happened and could happen again, blindsiding people who didn’t live through it before), weren’t really getting a raise at all – and that was *before* taxes!
The real problem, of course, came when interest rates began to fall. During the period that interest rates (and inflation) dropped to 12% from 15%, retirees were seeing their incomes drop by 20% (a 3% drop in rates from 15%) while still seeing prices rise by 12%.
How do you manage income in retirement? It ain’t easy.
Naturally, you could consider a basic withdrawal sequence using a straightforward strategy to take money in the following order:
1. Required minimum distributions (RMDs) from IRAs, 401(k), or other qualified retirement accounts.
2. Taxable accounts, such as brokerage and bank accounts.
3. Tax-deferred traditional IRAs, 401(k), and other similar accounts
4. Tax-free money – from Roth IRAs for example
This sequence can provide an order of withdrawals; but, other than the RMDs, it doesn’t tell you how much!
But wait! (as they say on tv).
How much? And, how can you be sure you won’t run out of money?
RMD can provide a clue!
The RMD calculations can provide sound guidance for your entire portfolio! Using the IRS formulas, Craig Iraelson, executive-in-residence in the financial planning program at Utah Valley University, did some back-testing with hypothetical portfolios invested in different investment allocations with RMD withdrawals starting in 1970 (the beginning of a relatively flat ten-year stock market). Using beginning values, and even with a portfolio invested in 100% cash, there was still $850,000 left after 25 years! And, a portfolio that was 25% stocks had $2 million left.
RMDs appear to address longevity risk pretty well; but, there’s another question. Is the income level provided by the RMDs enough to preserve the pre-retirement lifestyle – or anything close?
There’s the rub. In the back-tested portfolios, the initial RMD was 3.65% of assets… and that falls within the widely-accepted 4% rule… but, that’s only $36,500 of pre-tax income. Even if the retiree family has an additional $30,000 from Social Security, that’s still just $66,500 before taxes; and, for many successful individuals, that isn’t enough.
So, there’s the trade-off: Sacrifice income for longevity, or accept longevity risk in order to take increased income.
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73d6e4d94970d-320wi.jpg)Fotilla ImagesMaybe there’s another way. How can a couple have more freedom to take greater income early while still addressing the risk of running out of “late-life income”?
My “Late Life Income”reportshows how many couples have addressed this issue. [You can access it here!](https://indfin.leadpages.co/leadbox/14076cc73f72a2%3A12a1899aa346dc/5734616174428160/)
By the way, when you get my report, you’ll also receive a subscription to my ezine. If you decide you don’t want the ezine when you receive it, you’ll be able to unsubscribe immediately with a single click and, of course, your email is never shared with anyone.
Enjoy the report! Hope you find it helpful.
Enjoy!
Jim
---
***[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi.jpg)Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Inflation, Life Insurance, Planning, Retirement
**Tags:** retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy, secure retirement
---
### [How To Avoid the Family Business Wealth Evaporation Trap](https://indfin.com/familybusinesswealthevaporation/)
**Published:** December 11, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2017/12/iStock_000005627655-DemandsOnYourDollar.jpg)Jim Lorenzen, CFP®, AIF®**Family business owners face wealth evaporation daily. It’s like glaucoma. You can’t tell it’s happening on a daily basis, but the cumulative results can be costly.
Many years ago – before the internet – I was in thebusiness of publishing weekly newspapers and shopping guides. It was a business that included advertising sales, ad layouts and graphic design, production and composition, printing and distribution, and (of course) all the financial disciplines of managing cash flow and credit lines.
I mention this simply to point out that I know the challenges the owners of closely-held businesses face… and also to point out that there are some common mistakes many such owners have in common.
It was during this period I remember reading an interview with Jack Nicklaus, who was then at the top of his game and was THE golfer that “moved the needle”, as they even said back then. It was in that interview he pointed out one of the biggest mistakes he made had to do with his approach to cash management, pointing out just how costly his mistakes were – until he corrected them.
I learned from that article and it made a huge difference in mylife. That article, however, didn’t provide much detail; it was, after all, a golf magazine and didn’t have a financial focus.
Santa Barbara-based business expert George Issac, however, has written an excellent piece, entitled, ***Avoiding the Family Business Wealth Evaporation Trap.*** If you own a family business, you just might find this information highly valuable.
I recommend it highly; and you can get your own copy when you subscribe to my ezine – If you decide later you don’t want the ezine, you can unsubscribe immediately with a single click. By the way, IFG never shares your email address with anyone.
I recommend this piece by George Issac. I think you’ll be happy you read it.
[Click Here](https://indfin.lpages.co/leadbox/14788e673f72a2%3A12a1899aa346dc/5731972085186560/)
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Business Owners, Estate, Planning, Retirement
**Tags:** business owners, business owners retirement
---
### [A Long Life Is Wonderful When You Can Enjoy It!](https://indfin.com/familybusinesswealthevaporation-2/)
**Published:** December 20, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2017/12/iStock_000005627655-DemandsOnYourDollar.jpg)Jim Lorenzen, CFP®, AIF®**We know we’re living longer; a long life can be wonderful… and some of us get to live better, too.
I think you’ll enjoy this little one-minute video – [Say “Hi” to Ida](https://player.vimeo.com/video/117588730?color=cc002).
….and, enjoy the Holidays!
Enjoy!
Jim
---
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement
**Tags:** business owners, business owners retirement
---
### [Thinking of Giving to Charity? Here are some options for giving!](https://indfin.com/tax-advantaged-or-tax-deferred-do-you-know-the-difference-copy-2/)
**Published:** September 26, 2018
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01910219a734970c-320wi.jpg)*iStock Images*
**Jim Lorenzen, CFP®, AIF****®**
Giving to charity? While most anything can be given to charity, these are the more common forms of donated property:
**Cash:**Cash gifts are the easiest to give to a charity, both in terms of substantiating the deduction and in determining the value of the gift. But, cash may be your most expensive option.
**Real Estate:**Real estate that is owned outright and which has appreciated in value can be given to a charity. The donor can generally deduct the fair market value of the property, up to an adjusted gross income (AGI) percentage limitation. When a charity sells donated appreciated property, the capital gain then escapes taxation, up to AGI percentage limits.
**Securities:**The best securities to donate tend to be those that have increased substantially in value. As with real estate, the donor can generally deduct the fair market value of the security and the capital gain escapes taxation when the security is sold by the charity.
**Charitable Gift Tax Implications:**
- Gifts of cash and ordinary income property are generally deductible up to 50% of the donor’s adjusted gross income (AGI).
- The fair market value of gifts of long-term capital gains property (e.g., real estate, stock) is deductible up to 30% of AGI. There is, however, a special election through which a donor may deduct up to 50% of AGI if the donor values the property at the lesser of fair market value or adjusted cost basis.
- Charitable contributions in excess of the percentage limitations can be carried over and deducted for up to five succeeding years.
- The donor must itemize income tax deductions in order to claim a charitable deduction. A portion of itemized deductions is phased out for taxpayers with an AGI above certain limits.
**Life Insurance:**If a charitable organization is made the owner and beneficiary of an existing life insurance policy, the donor can deduct the value of the policy as of the date of the transfer of ownership. The donor may then deduct all future amounts given to the charity to pay the premiums. If a charity is named just the beneficiary of an insurance policy on the donor’s life, no current income tax deduction is available. At the donor’s death, however, the donor’s estate receives an estate tax charitable deduction for the full amount of the policy death benefit.
**Disclosures**
***Jim Lorenzen** is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal of* [***The Independent Financial Group***](https://indfin.com/)***,*** *a fee-only registered investment advisor with clients located across the U.S.. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Group* does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Charitable Giving, Life Insurance, Planning, Retirement, Taxes
**Tags:** Tax reduction, Tax-Free Retirement Income, Taxes in retirement
---
### [Are Risk Questionnaires Meaningless?](https://indfin.com/riskquestionnaires-2/)
**Published:** November 22, 2019
**Author:** Jim Lorenzen
**Excerpt:** Risk questionnaires have played a major role in retirement and investment planning for as long as I can remember; and I’ve used them no less religiously than any other advisor. Frankly, I’ve always felt they were a little stupid.
**Content:**
**Do they really add value?**
**[](https://indfin.com/wp-content/uploads/2019/07/Meeting_Notetaking.jpg)Jim Lorenzen, CFP®, AIF®**
Risk questionnaires have played a major role in retirement and investment planning for as long as I can remember; and I’ve used them no less religiously than any other advisor. Frankly, I’ve always felt they were a little stupid.
Elmer Duckhunter walks into Brainy Smartsuit’s office at Behemoth Securities. It’s a beautiful place, full of mahogany with lots of beautiful brochures in the lobby. Brainy has been successful at Behemoth, gaining promotion to Sr. Vice President after selling more Secure Your Future product than anyone else in the office using the “Secret in a Box” software supplied by the product wholesaler.
“How can I help you?”, Brainy asks.
“Well,” says Elmer, “I have a lot of money from all those Tractor Pulls I won and I think it’s time I began investing for my future. What should I invest in?”
“I think I can help you, but first I have to know more about you!”
“Makes sense. What do you want to know?”
Brainy pulls out the Behemoth Risk Assessment questionnaire. “First, I’d like to know a little about how you feel about investing.”
“Okay.” Elmer settles in. “How many questions are there?”
Brainy smiles, “Just six.”
“Six? You can learn everything you need to know about me with just six questions?”
“Trust me. This is very scientific, “says Brainy.
“Okay.”
Brainy begins. “On a scale of zero to 10, how much risk do you feel you can handle?”
“I don’t know. What would a ‘five’ feel like?”, asks Elmer.
“Just pick one that you feel comfortable with, says Brainy. “The people who prepare these know what they’re doing.”
Elmer thinks for a second. “Well, back in 2007 I was a 9, but after the crash I was a 2. Now, I don’t know what I am. That’s why I’m here!”
“Well, I can’t tell you how much risk to take until you tell me how much risk you want; then, I can tell you what you told me and we’ll have the answer!”
“Huh?”
They both look at each other, then Elmer continues, “How much risk do I want? Seems to me you should be telling me how much risk I need or don’t need!”
“But what if it’s more than you want?”, asks Brainy.
“I don’t know how much I want. I need to know how much I should or should not have?
Brainy perks up. “Now we’re getting somewhere. What are your goals?”
“Simple”, says Elmer, “to retire with as much money as possible with as little risk as necessary.”
“How much is that?”
“How should I know? You tell me.”
Brainy senses a lack of forward progress. “Let’s come back to that. Try this one: If your portfolio went down, what would you do?”
“I’d probably ask you for advice! Isn’t that your job?” Elmer’s beginning to wonder if Brainy Smartsuit is so smart after all. “Why are you asking me all this. I just want to know what I should be doing!”
Brainy comes clean. “We have regulatory compliance concerns. We have to make sure what we recommend is consistent with how you feel about investing.”
“I’d rather have advice that’s consistent with what I need,” says Elmer. Are you protecting me or your firm?”
“Well, actually, both…”
“There are six of these?” Elmer’s fed up. He puts on his duck hunter cap with earflaps, and stomps out of the office.
Maybe these questionnaires can shed some light about attitudes; but, they don’t tell Elmer what he needs to know. Elmer just wants to know what he should be doing and why. Once he understands what and why, the rest gets easier. Fear can exist only where there’s a knowledge vacuum. When knowledge replaces ignorance, fear dissipates and understanding prevails. Maybe questionnaires have zero to do with long term success for the client; but, they maybe do help sell more Secure Your Future product.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Family Issues, Investing, Planning, Retirement
**Tags:** Financial planning, investment planning, managing risk, retirement decisions, Retirement Planning
---
### [What Will "Medicare for All" Really Cost?](https://indfin.com/healthcareforall/)
**Published:** December 2, 2019
**Author:** Jim Lorenzen
**Excerpt:** I’m not sure how many of the candidates who are running on government supported Medicare for everyone majored in economics or finance – it maybe explains the obvious their all to obvious failure to address the question directly.
Elizabeth Warren, for example, promised that it won’t cost the middle class “one penny” – a feat that hasn’t been accomplished by any country now offering universal health care. According to an inciteful Advisor Perspectives article by Rick Kahler, CFP and registered investment advisor based in Rapid City, S.D., the middle class in those countries pay income taxes of up to 40% and a national sales tax equivalent to 15-25% of income.
While Senator Warren estimates the cost over a decade at $20 trillion in new federal spending – a cost the middle class is somehow to avoid – Estimates from six independent financial organizations put the figure in the $28-36 trillion range.
Link: http://www.crfb.org/blogs/how-much-will-medicare-all-cost
A Forbes article describes the tax increases aimed at wealthy individuals. Included are:
Eliminating the favorable tax rate on capital gains
Increasing the “Obamacare” tax from 3.8% to 14.8% on investment income over $250,000
Eliminating the step-up in basis for inheritors
Establishing a financial transaction tax of 0.10%
The capital gains tax increase, the step-up in basis, and the financial transaction tax will all affect middle class investors – potentially anyone with a 401(k) or an IRA. Rick Kahler points out that the American Retirement Association estimates that the financial transaction tax alone will cost the average 401(k) and IRA investor over $1,500 a year.
The 0.10% financial transaction tax, for example, would apply to all securities sold and purchased within a mutual fund or ETF, in addition to any purchases and sales of the funds themselves by investors. Mr. Kahler estimates these costs can run 0.20% to 0.30% a year to fund investors. When you consider some index funds charge only 0.10% in total expenses, the increase comes to 200% or more.
Eliminating the step-up in basis and the favorable capital gains treatment will certainly cost middle class investors more than a penny. A retiree leaving an heir $200,000 with $100,000 in cost basis, could easily cost the middle class inheritor $10,000 to $20,000 or more in taxes.
Forbes link: https://www.forbes.com/sites/howardgleckman/2019/11/07/warrens-plan-to-double-tax-wealth-is-unrealistic/#4444076e4aaf
Candidates can promise – that doesn’t cost anything – but it’s the electorate who needs to do the math. After all, our elected representatives don’t live in the same health care world the rest of us do.
**Content:**
**Politicians don’t live under the same health care or retirement systems the rest of us do – so promises, for them, are easy to make.**
[](https://indfin.com/wp-content/uploads/2014/09/Fotolia_5386670-DontSkipDetails.jpg)*Fotila Images***Jim Lorenzen, CFP®, AIF®**
I’m not sure how many of the candidates who are running on government supported Medicare for everyone majored in economics or finance – it maybe explains the obvious their all-to-obvious failure to address the question directly.
Sen. Elizabeth Warren, for example, promised that it won’t cost the middle class “one penny” – a feat that hasn’t been accomplished by any country now offering universal health care. According to an inciteful Advisor Perspectives article by Rick Kahler, CFP® and registered investment advisor based in Rapid City, S.D., the middle class in those countries pay income taxes of up to 40% and a national sales tax equivalent to 15-25% of income.
While Senator Warren estimates the cost over a decade at $20 trillion in new federal spending – a cost the middle class is somehow to avoid – Estimates from [six independent financial organizations](http://www.crfb.org/blogs/how-much-will-medicare-all-cost) put the figure in the $28-36 trillion range.
A [Forbes article](https://www.forbes.com/sites/howardgleckman/2019/11/07/warrens-plan-to-double-tax-wealth-is-unrealistic/#4444076e4aaf) describes the tax increases aimed at wealthy individuals. Included are:
- Eliminating the favorable tax rate on capital gains
- Increasing the “Obamacare” tax from 3.8% to 14.8% on investment income over $250,000
- Eliminating the step-up in basis for inheritors
- Establishing a financial transaction tax of 0.10%
The capital gains tax increase, the step-up in basis, and the financial transaction tax will all affect middle class investors – potentially anyone with a 401(k) or an IRA. Rick Kahler points out that the American Retirement Association estimates that the financial transaction tax alone will cost the average 401(k) and IRA investor over $1,500 a year.
The 0.10% financial transaction tax, for example, would apply to all securities sold and purchased within a mutual fund or ETF, in addition to any purchases and sales of the funds themselves by investors. Mr. Kahler estimates these costs can run 0.20% to 0.30% a year to fund investors. When you consider some index funds charge only 0.10% in total expenses, the increase comes to 200% or more.
Eliminating the step-up in basis and the favorable capital gains treatment will certainly cost middle class investors more than a penny. A retiree leaving an heir $200,000 with $100,000 in cost basis, could easily cost the middle class inheritor $10,000 to $20,000 or more in taxes.
Candidates can promise – that doesn’t cost anything – but it’s the electorate who needs to do the math. After all, our elected representatives don’t live in the same health care world the rest of us do.
Jim
———————————————————————————–
Jim Lorenzenis a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Jim is Founding Principal ofThe Independent Financial Group. He is also licensed for insurance as an independent agent under California license 0C00742. The Independent Financial Groupdoes not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Economy, Family Issues, IFG Viewpoint & Outlook, Investing, Planning, Retirement, Taxes
**Tags:** Financial planning, health care, health care for all, investment planning, managing risk, retirement decisions, Retirement Planning
---
### [Women and Social Security Land Mines](https://indfin.com/women-and-social-security-land-mines/)
**Published:** May 20, 2021
**Author:** Jim Lorenzen
**Excerpt:** Bad decisions can create time bombs, and few decisions can be as disastrous as those that result from the mistakes many women make when it comes to claiming Social Security benefits. This is particularly true for widows, divorced spouses, and stay-at-home parents.
**Content:**
A few Social Security claiming decisions that can cause nightmares:
[](https://indfin.com/wp-content/uploads/2021/05/Fotolia_3956379-Overwhelmed.jpg)
**Not thinking about taxes.** Many fail to realize that benefits can be taxable – and the thresholds are low – at ordinary income tax rates. Many would be wise to have withholding tax taken out of their benefits every month.
**The tax-bracket trap**: A widow’s tax bracket will likely change in the year after her husband’s death. Going from joint filing to single filing can provide the first shock. The second comes when their standard deduction has been cut in half.
[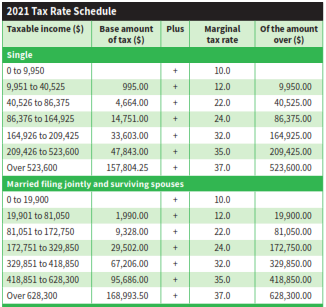](https://indfin.com/wp-content/uploads/2021/05/2021-Tax-Tables.png)
**Getting blind-sided by Medicare**. Believe it or not, Medicare has it’s own tax brackets. Besides having to pay Medicare Part B premiums, the move from a joint return to filing single means her Part B premiums could jump dramatically. This could be a big deal for widows, especially when added to all the other surprises.
[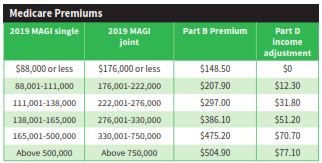](https://indfin.com/wp-content/uploads/2021/05/2021-Medicare-Premiums.png)
**Quarterly taxes?** You read that correctly. How many widows, or retirees for that matter, don’t’ know how often they have to pay quarterly estimates on their income in retirement? Even if simply living off investment income, it’s still income. Failing to do so can result in penalties and interest. Not good.
**Claiming early while planning to ‘bump-up’ the benefit later**. Sorry. Once you’ve made a claim at age 62, you’re stuck. You can’t increase it later.
**Widows often don’t realize one check is going away**. Often women who are below age 60 with grown children think they can begin collecting benefits as soon as they become widows. The gap, however can be longer, not realizing they have to wait until age 60 to begin collecting benefits. Many also fail to realize that the spouses check will stop coming. The loss can be from 1/3 to 1/2, depending on her career earnings.
This isn’t an exhaustive list; there’s more to know. However, it should serve as a wake-up call that professional help could prove beneficial.
Jim
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Planning, Retirement, Social Security
**Tags:** social security
---
### [Should You ALWAYS Wait to Claim Social Security Benefits?](https://indfin.com/social-security-claiming/)
**Published:** July 15, 2021
**Author:** Jim Lorenzen
**Excerpt:** There may be times when you might decide it's worth claiming your Social Security benefits early!
**Content:**
There may be times when you might decide it’s worth claiming your Social Security benefits early!
Here’s a hypothetical possibility: Margaret is 62 years of age, married, and has about $5 million in retirement assets from her recently sold business with all taxes paid. Her monthly expenses are about $8,000 monthly and has no other income. Her expenses are reasonable, given her asset level.
She doesn’t need her Social Security income. Should she claim early or late? Consultant’s answer: it depends.
Her benefit at full retirement age would be $2,800. If she claims early, at 62, she would receive only $2,007; but if she waits until age 70, she would receive $3,547 monthly! Big difference! So, what’s best? Again, it depends. On what?
What does she want the money to accomplish? She doesn’t need the money; so what does she intend to do with it?
She ways she wants the money to leave a legacy for her children and grandchildren. That’s a long time! If we were to compare beginning now at age 62 with waiting until age 70 with all the income invested for a long-term goal of a 7% return, would the increased income by waiting to age 70 make up for the the eight years of time lost investing the lesser amount? If 7% is assumed, it may pay to begin now.
[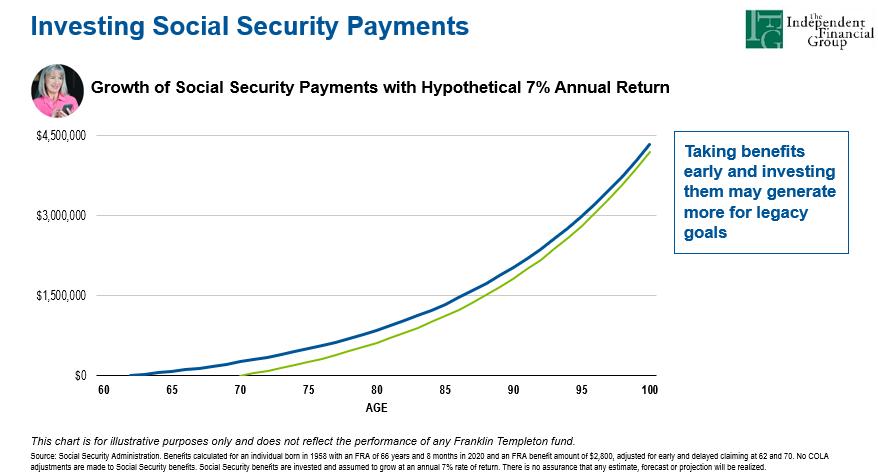](https://indfin.com/wp-content/uploads/2021/07/Investing-SS-Payments.png)As you can see, if investing the money for legacy is the objective, maybe claiming early and aggressively investing over the long term may be the ideal choice! Social Security planning should be integrated with your total financial plan; after all, benefits can be subject to income taxation and beginning early to lay plans for minimizing those can critical to long term success.
If you’d like to find out if IFG is the right fit for you, just go to the Getting Started tab above, [or click here](https://indfin.com/getting-started/), to arrange your ‘right fit’ introductory phone call!
Food for thought.
Jim
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Investing, Planning, Retirement, Social Security
**Tags:** social security, social security claiming, when to claim social security
---
### [Social Security Report Indicates Benefit Cuts May Be On The Way.](https://indfin.com/social-security-report-on-benefit-cuts/)
**Published:** September 2, 2021
**Author:** Jim Lorenzen
**Excerpt:** The Social Security Board of Trustees released its annual report on the long-term financial status of the Social Security Trust Funds.
**Content:**
You can [see their report here](https://indfin.com/wp-content/uploads/2021/09/SSA-News-Release_20210831.pdf).
The combined asset reserves of the Old-Age and Survivors Insurance and Disability Insurance (OASI and DI) Trust Funds are projected to become depleted in 2034, one year earlier than projected last year, with 78 percent of benefits payable at that time.
The OASI Trust Fund is projected to become depleted in 2033, one year sooner than last year’s estimate, with 76 percent of benefits payable at that time. The DI Trust Fund is estimated to become depleted in 2057, eight years earlier than last year’s estimate, with 91 percent of benefits still payable. The Center for Retirement Research at Boston College has provided an initial analysis, which [you can see here.](https://indfin.com/wp-content/uploads/2021/09/Impact-of-Inflation-on-Benefits_BostonCollege.pdf)
I’ll have more on this in our Q4 letter in October.
Jim
(If you’re not a subscriber and would like to receive the IFG letter, you can [subscribe here](https://visitor.r20.constantcontact.com/manage/optin?v=001MsaghC2nU2NJckb8N0hCVabs7r2JGtIT). IFG will not sell your information and you can unsubscribe anytime.)
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Retirement, Social Security
**Tags:** social security
---
### [Social Security Claiming Mistakes Mean Retirees Set To Lose $3.4 Trillion in Retirement Income.](https://indfin.com/social-security-claiming-mistakes-mean-retirees-set-to-lose-3-4-trillion-in-retirement-income/)
**Published:** September 14, 2021
**Author:** Jim Lorenzen
**Excerpt:** Over half of all Americans expect to live a comfortable retirement and only one third think Social Security will be important to them.
**Content:**
Could this be the reason for so many faulty claiming strategies?
That’s according to a report from United Income researchers. In short, bad assumptions often lead to bad decisions. It’s even worse when those false assumptions are grounded more in cultural beliefs than in empirical evidence.
Believe it or not, only 4% of retirees make the optimal claiming decision. In fact the study found that a claiming age of 62-64 is optimal for only about 8% of adults – primarily those with a short life expectancy.
There’s more. You might find [this article](https://indfin.com/wp-content/uploads/2021/09/i425a_Americans-Lose-Trillions-in-Social-Security-3.pdf) by Elaine Floyd, CFP***®*** interesting.
If you’d like help, you can set-up your “Right Fit” introductory call [here](https://indfin.com/getting-started/).
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Retirement, Social Security
**Tags:** social security, social security claiming, when to claim social security
---
### [7% Return? From the U.S. Treasury?](https://indfin.com/7-percent-from-the-us-treasury/)
**Published:** April 26, 2022
**Author:** Jim Lorenzen
**Excerpt:** Yes, Virginia, Series I bonds sold from November 2021 through April 2022 earn interest at 7.12%. Oops.
**Content:**
[](https://indfin.com/wp-content/uploads/2022/04/Series-I-Bonds_WM-2.png)These bonds earn interest for 30 years or until you decide to return them. If you redeem them before five years, you’ll lose interest on the previous three months. After five years, you can cash them in without penalty. By the way, **you cannot redeem these bonds before one year.**
If you have excess cash just sitting someplace, these may make sense.
Oh, yeah, the bad news: there is a limit per taxpayer of $10,000 worth of Series I bonds per year.
The income you earn is subject to federal income tax, but not subject to state or local taxes – how about that?
Possible good news? There’s talk the administration could raise the annual cap for Series I bonds fro $10,000 to $100,000 – we’ll follow this.
Where can you buy these? Alas, not even yours truly, with all my magical powers, can provide these. You must buy these directly from the treasury using the [TreasuryDirect](https://www.treasurydirect.gov/indiv/research/indepth/ibonds/res_ibonds_ibuy.htm) website.
Enjoy!
Jim
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Uncategorized
---
### [Tax Planning for Retirement Income](https://indfin.com/tax-planning-for-retirement-income/)
**Published:** May 23, 2022
**Author:** Jim Lorenzen
**Excerpt:** Tax Planning doesn't stop at retirement. In fact, tax planning is important for optimizing retirement income - and it changes during all four stages of retirement.
**Content:**
Retirement often contains surprises. All you have to do is turn on the news to see what’s happening today; and here’s more bad news: the only change will be more change. It’s been going on since our first truly contested election back in 1800 when Thomas Jefferson had to fend-off Aaron Burr to see who would face John Adams in his bid for re-election. Anyone who thinks politics is divisive today should see what it was like then – or sixty years later when states were leaving the union. But, I digress.
**There are generally four stages to retirement:**
> > Pre-retirement – working and saving
> > Early retirement – “Go-go” years
> > Mid-retirement – Go-slow years
> > Late retirement – No-go years
And, the surprises will continue through all the stages. How to address it all? Well, there are four basic keys, which [you can have by clicking here.](https://indfin.com/wp-content/uploads/2022/05/IFG_How-Tax-Planning-Changes-HO.pdf)
For those interested in learning more about tax planning in retirement, attend my free webinar! I think you’ll find it helpful. You can [learn more here](https://event.webinarjam.com/register/5/pgyy8f5).
Enjoy!
Jim
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Planning, Retirement, Taxes
---
### [Remember 1966? How About 1967?](https://indfin.com/remember-1966/)
**Published:** June 28, 2022
**Author:** Jim Lorenzen
**Excerpt:** Retirement decisions can be momentous. Which year you would have remembered would depend on if you retired back then... and which year!
**Content:**
If you had retired with $1 million and invested in a typical 60% stock, 40% bond allocation, withdrawing 5% each year with a 3% cost-of-living increase, how would you have ended up 30 years later?
Thirty years sounds like a long time, but many people do outlive that… and their money.
The folks at Franklin Templeton ran an analysis of two hypothetical investors. One retiring in 1966 and the other in 1967 – both with the numbers outlined above.
The [results were quite different](https://indfin.com/wp-content/uploads/2022/06/1966.png)! Our 1966 retiree ended up broke, while the one who retired in 1967 ended up with more than $2 million, even after all the withdrawals!
So, how do you predict which is the best year to retire? Well, you can’t. But, you can install some guardrails for your retirement nest egg. You might find my webinar on this subject helpful. You can [register here](https://event.webinarjam.com/register/2/ky66zsz).
Enjoy!
Jim
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Planning, Retirement, Rollovers
**Tags:** Financial planning, Investment Strategy, managing risk, retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy
---
### [Managing an Inheritance](https://indfin.com/managing-an-inheritance/)
**Published:** July 11, 2022
**Author:** Jim Lorenzen
**Excerpt:** Managing inherited money isn't as simple as depositing the check and picking some sure-fire investments.
**Content:**
There are a number of challenges that come with managing inherited money. Maybe this Life Guide will help.
[This Life Guide](https://indfin.com/wp-content/uploads/2022/07/IFGi_LifeGuide_Managing_An_Inheritance_vsa.pdf) will help you sort through the maze of issues you’ll face.
You’ll also need to establish, if you haven’t done so already, a financial plan that takes into account not only how to locate assets for future growth, but how to locate them in a manner that’s both tax efficient and inflation protected.
Also, don’t assume what made sense for the deceased will automatically make sense for you.
There’s a lot to consider. You can[ access your inheritance Life Guide here.](https://indfin.com/wp-content/uploads/2022/07/IFGi_LifeGuide_Managing_An_Inheritance_vsa.pdf)
Enjoy!
Jim
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Family Issues, Inflation, Inheritance, Investing, Planning
---
### [When Should You Apply for Social Security Benefits?](https://indfin.com/when-should-you-apply-for-social-security-benefits/)
**Published:** December 13, 2022
**Author:** Jim Lorenzen
**Excerpt:** Mistakes can be costly - and may be permanent!
**Content:**
With the demise of guaranteed pensions (not to mention the risks you face in managing your own retirement assets) knowing when to claim,, and how to maximize the value of, your Social Security benefits has become a critical part of retirement planning.
Step one is knowing when to apply and how your claiming ae affects your income stream.
You can [read about it here](https://indfin.com/wp-content/uploads/2022/12/i430a_When-to-Apply-for-SS-Benefits-6.pdf)**!**
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Retirement, Social Security
**Tags:** social security, social security claiming, social security help, when to claim social security
---
### [Thinking About a Rollover?](https://indfin.com/thinking-about-a-rollover/)
**Published:** January 16, 2023
**Author:** Jim Lorenzen
**Excerpt:** No, we're not training your dog. But, if you're nearing retirement, you know exactly what a rollover is - and you know it's a big decision.
**Content:**
*When you leave your employer, you have the opportunity to rollover your qualified retirement plan – a 401(k) for most people – into either an IRA or a new employer’s plan. Many people make the ‘automatic’ decision to roll their plan into an IRA – and, for many, it may be the best option – but, the decision shouldn’t be automatic.*
There’s more to consider than you might think. And you can [learn more about it here](https://indfin.com/wp-content/uploads/2023/01/i308a_IRA-Rollover-Checklist.pdf).
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** IRAs, Retirement, Rollovers
---
### [The Big (Expensive) Rollover Mistake Some People Make](https://indfin.com/bigrollovermistake/)
**Published:** March 14, 2023
**Author:** Jim Lorenzen
**Excerpt:** At retirement, some people receive a check from their employer for their 401(k) balance and write a check for deposit into their IRA before the 60-day deadline, just like they were told, to avoid any problems with the IRS. They’ve met the deadline. The money is now in their IRA. They’re clear and the rollover is complete…. or is it?
**Content:**
No. The rollover isn’t complete. It’s a rollover mistake that happens too often.
They may have been given a ‘heads up’ that their employer would be withholding 20% for the amount of the check; but they didn’t know they’d have to make it up themselves!
True. Imagine. You have $300,000 in your 401(k) and you receive a check from your employer for $240,000 after withholding $60,000 for the I.R.S. You deposit the check and, within 60 days, you write a check for $240,000 for deposit into your IRA. But, the rollover still isn’t complete and the 60-day clock is still ticking!
Why? Believe it or not you have to make up that $60,000 from your own funds and deposit that money into your IRA before the 60-day clock runs out – hopefully you didn’t wait until 59 days had run out before you acted. It’s only after that final deposit brings the balance to the original amount, $300,000, that the rollover is complete.
How do you avoid this dilemma? You make sure your rollover is DIRECT. Make sure the money goes directly from your 401(k) custodian to the IRA custodian without you ever taking possession of the funds. Now, some employers will insist the check be sent to you. Okay. Have the check made out to the custodian for your benefit. Pay to (example) *XYZ Company FBO Jim Lorenzen IRA.* Your employer can give you the physical check but you’re not taking possession of the funds. In the memo space on the check you write your account number and provide it to your IRA custodian. The funds go directly into your IRA.
Oh, and guess what? On a direct rollover there’s NO 60-day clock and there’s NO withholding. And, using our example, you just saved $60,000 of other funds. Not bad.
If you’re making a rollover decision [you may find this checklist helpful.](https://indfin.com/wp-content/uploads/2017/05/i308a_IRA-Rollover-Checklist.pdf)
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** IRAs, Planning, Retirement, Rollovers
**Tags:** 401(k) rollovers, company plan rollover, IRA rollover, retirement decisions, Retirement Planning, rollover mistakes
---
### [Uncle Sam’s Greed and Your Retirement: Should You Go All-In on Your 401(k)?](https://indfin.com/uncle-sams-greed-and-your-retirement-should-you-go-all-in-on-your-401k/)
**Published:** May 19, 2023
**Author:** Jim Lorenzen
**Excerpt:** Given the size of our growing national debt it’s no wonder so many people believe taxes will be higher in the future. We have an ageing population and there are a number of factors at work: There’s the annual deficit plus money needed to fund Medicare and Social Security, just to mention a few.
**Content:**
You can [see the debt ](https://www.usdebtclock.org/index.html?taxpayer)[clock in real time here](https://www.usdebtclock.org/index.html?taxpayer)
**With taxes likely going up in the future and a huge baby-boom population going into retirement – the government does expect to cash-in.**
And with the passage of so-called SECURE Act 2.0, most non-spouse inheritors of those retirement accounts will be forced to empty them out – at the then current tax rates – within ten years. At that time, they’ll likely be in their highest earning years and already in high tax brackets, maybe being forced into even higher ones.
This probably has you wondering if maxing out your 401(k) is still a smart move. Money matters can be confusing, and the thought of giving more of your hard-earned cash to the government might make you cringe. Let’s break it down to help you decide if going all-in on your 401(k) is still the way to go. I don’t have a crystal ball; but then, financial planning isn’t always about what we know – it’s often about what we don’t know, as well.
**Understanding your 401(k)**
Let’s start with the basics. A 401(k) is simply an account where you can stash your money for later in life – a time when you’d like work to be an option instead of a requirement. The good news is that you get to contribute to it with your pre-tax income, which means you’re reducing the amount of money the taxman can get his grubby paws on right now. Plus, your employer might even throw in some extra dough to sweeten the deal. Free money! – a good reason right there to max out contributions. So far so good: you stash the cash and don’t pay taxes (yet) on the income that money represents.
**Oh, yeah – It Can Grow Too!**
The very fact you’re reading this – a financial blog – means you very likely know about the power of time and compound interest. When you max out your 401(k) consistently, you’re giving your money the opportunity to grow like a wild weed. It’s like planting a seed and watching it sprout into a money tree. Even if taxes go up, the compounded growth within your tax-deferred 401(k) account could be juicier than the extra taxes you’ll pay later. Obviously, this may or may not happen, but that employer match sure helps.
But, be sure to remember the definition of tax-deferred: it means tax-delayed. Hmmm. This is where things can get dicey. Note: The IRS has a claim on part of your balance; but, it has a claim on part of your losses, too! [See why here](https://indfin.com/did-you-know-the-government-subsidizes-market-losses-in-traditional-ira-and-401k-accounts/).
**Evaluating Potential Tax Increases**
Then there’s the elephant in the room: higher taxes. As we said at the top, this can be a potential time-bomb for many. Some think, not without good reason, that The SECURE Act is really about making the government more secure.
One thing to keep in mind: tax rates are about as predictable as a soap opera plot. They go up, they go down, they change more often than your favorite pair of socks. Trying to time your retirement savings based on potential tax changes is like trying to predict the next viral cat video–it’s a risky game.
What to do? Focus on the long-term. Your retirement goals shouldn’t be swayed by short-term tax rate wobbles any more than you’d gamble on short-term market moves based on what traders are doing. Dumb, but people do it.
**Diversification**
This may be one of the most misunderstood areas of investing. Warren Buffet once said diversification is protection against ignorance. I won’t argue the point, but for most of us mortals there are some things worth diversifying. Risks come in many forms: inflation, tax-law changes, economic conditions, etc.
One of the most misunderstood is market risk. People believe you can reduce market risk through diversification. Think about this: if you purchased every single stock in the stock market (in the name of diversification), would you have diversified away your market risk? Of course not. You would have only *replicated* the market’s risk. So you can’t diversify away market risk. But, you can minimize business risk! There’s more to learn about diversification. You might like my report, which [you can access here](https://indfin.com/wp-content/uploads/2014/09/i306_Understanding-The-Diversification-Puzzle.pdf).
Then, there’s tax law changes – legislative risk: if you believe taxes will be higher in the future, as discussed at the top, you may want to consider concentrating your stock holdings in regular taxable accounts while keeping your bond holdings in tax-delayed accounts. Bonds are less likely to grow as much as stocks, but the interest isn’t immediately taxed. Stocks in the taxable accounts may pay capital gains taxes, which are generally lower, when they are sold. It sounds counterintuitive; but the math often makes sense.
Now, here’s where people can often fool themselves. As a planner and advisor, I’ve seen it many times: the failure to understand what diversification really means. I’ve seen cases where one person would hold the same investments in five different IRA accounts believing that approach constituted diversification in their eyes.
The fact is an account is like a drawer in a desk. Drawers are simply places to hold things. The drawers simply hold investments. Whether you split an investment into five drawers or only one, the rewards are the same and the risks are the same.
**Did you know there are four stages of retirement**?
And, did you know that each stage is unique from a tax standpoint? Ready to invest about 45 minutes in some learning? Grab some coffee. [You may find this video enlightening.](https://vimeo.com/jimlorenzen/taxplanniingforretirement2023)
If you’re in or nearing retirement – or even approaching that age where sound financial decisions have become increasingly important – you may find an introductory call worthwhile. You [can learn more here.](https://indfin.com/getting-started/)
Enjoy the video!
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Uncategorized
**Tags:** Investment Strategy, managing risk, retirement decisions, Retirement Planning, Retirement Strategy, Retirement tax strategies, tax law changes
---
### [Want to Defer RMD Taxable Income? Try a QLAC!](https://indfin.com/want-to-defer-rmd-taxable-income-try-a-qlac/)
**Published:** June 3, 2024
**Author:** Jim Lorenzen
**Excerpt:** Why are QLACs getting a attention now? Two reasons: (1) SECURE Act 2.0, and (2) rising interest rates.
**Content:**
QLACs (Qualified Longevity Annuity Contracts) may help you defer RMD taxable income. QLACs have been around since 2014, but there’s been no rush by investors to jump on the bandwagon – and for good reason: they’re hard to understand and investors are limited to the lesser of 25% of aggregated IRA balances or $145,000. They’re also a fixed return, thus traditionally offering little chance for growth.
There are two reasons QLACs are getting a second look: (1) SECURE Act 2.0, and (2) rising interest rates. According to Kiplinger’s, QLACs re offering 100% to 250% more income than they did just three years ago.
**How it works**
A QLAC is technically a deferred income annuity purchased by your traditional retirement account. The tax-free transfer not only purchases a QLAC but it also reduces your retirement income balances, which ultimately reduces your taxable RMDs!
Now, because of [SECURE Act 2.0](https://indfin.com/wp-content/uploads/2024/06/What-Important-Issues-Changes-Made-By-The-Secure-Act-2.0-2024-1.pdf), individuals can contribute up to $200,000 into a QLAC during life (there is no percentage limit regarding the IRA balance). This could be huge for married couples if both partners take advantage of increased contribution limit. In addition, because of SECURE Act 2.0, you can also include a “return of premium” feature in your QLAC so that the purchase amount, less any payouts, goes to a beneficiary at your passing.
QLACs are fixed annuities, so their return is reliant on interest rates. Current higher rates have made these attractive. QLAC withdrawals are required to begin at age 85, so this strategy provides a way to (1) reduce taxes on early RMDs while (2) providing a ‘late life’ income solution that’s guaranteed, (3) provide a nice add-on to Social Security or provide for long-term care, and (4) protecting your heirs.
The QLAC strategy is just one for late life income (there are others that provide other tax advantages), but this one allows you to reposition IRA money without current taxes and reduce your RMDs when they come due. One drawback: income from the QLAC will be taxable and no one knows what taxes will be at that time.
**There’s one hint that makes one suspect it may be a good idea:** the government limits how much your able to convert. Usually if the government limits something, it makes me suspect it’s a good thing.
SECURE Act 2.0 also raises other issues. [Here’s a checklist](https://indfin.com/wp-content/uploads/2024/06/What-Important-Issues-Changes-Made-By-The-Secure-Act-2.0-2024-1.pdf) you might find helpful.
Jim
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Annuities, Annuities, IRAs, Retirement, SECURE Act, Taxes
---
### [Key Retirement Milestones](https://indfin.com/key-retirement-milestones/)
**Published:** June 25, 2024
**Author:** Jim Lorenzen
**Excerpt:** Retirement milestones should actually begin the day you leave school and enter the workforce; but few people think about retirement at that age. They’re too busy starting careers. If they achieve early success, they won’t even be worried about retirement. It’s been my experience that it’s after age 50 they come through my door. By that time they’re done with stock tips and chasing rainbows. Age 50 has a way of making all of us start thinking.
**Content:**
**So, what are some of the things we should be doing at different ages?**
Let’s take a look at some of the things we should be thinking about as we move past age 50:
**Ages 50-60**
**Final Preparation and Risk Management**
- **Refine Retirement Budget**: Develop a detailed retirement budget that includes anticipated living expenses, healthcare costs, and discretionary spending. Even companies like Microsoft operate with budgets; why shouldn’t you?
- **Adjust Investment Strategy**: It’s a common practice to shift investment strategy to become more conservative as retirement approaches. The idea is that it helps protect accumulated savings from market volatility. However, you still may have thirty more years of inflation and tax law changes ahead of you. A billionaire like Warren Buffett may have 95% of his money in stocks while someone on welfare can’t do that. What *you* should do should be dictated by a lot of factors all integrated into your own personal financial plan. Don’t get sucked-in to a blanket target-date fund – they’re nothing but balanced funds that change allocations over time – not all people the same age are alike, have the same financial assets or experience the same circumstances.
- **Maximize Social Security Benefits**: Plan when to start taking Social Security benefits. Delaying benefits can result in higher monthly payments. Here, a financial plan that incorporates your future Social Security strategy can be worth hundreds of thousands of dollars.
- **Explore Healthcare Options**: Research healthcare options, including Medicare and supplemental insurance, to ensure adequate coverage in retirement.
- **Downsize if Necessary**: Consider downsizing to a smaller home or relocating to reduce living expenses and free up additional funds for retirement.
**Pre-Retirement: Ages 60-65**
**Transition and Final Adjustments**
- **Finalize Retirement Date**: Determine your exact retirement date and inform the employer. Ensure all necessary paperwork and benefits are in order.
- **Create a Withdrawal Strategy**: Talk with your financial advisor. It’s not as simple as just withdrawing funds from retirement accounts. Consider tax implications and required minimum distributions (RMDs). The size of your future RMDs will impact taxation on your Social Security benefits and the size of your Medicare premiums.
- **Review Estate Plan**: Yes, Virginia, you don’t have to be rich to have an estate plan. In fact, EVERYONE already has one! That’s right. The problem is, of course, is if people don’t create their own, the government has a default estate plan already in-place for them – and it can be expensive and time consuming. Better to update estate planning documents such as wills, trusts, and power of attorney to reflect current wishes. Talk with your attorney or get guidance from your financial advisor on how to access the right help.
- **Evaluate Income Sources**: Assess all potential sources of retirement income, including pensions, annuities, and rental properties. Naturally, these are all components of your financial plan.
- **Conduct a Retirement Trial Run**: Try living on the projected retirement budget for a few months to identify any adjustments that may be needed.
**Retirement: Ages 65 and Beyond**
**Enjoy Retirement and Stay Financially Healthy**
- **Monitor Spending and Investments**: Regularly review spending and adjust the budget as needed. Monitor investment performance and make necessary adjustments to ensure funds last throughout retirement.
- **Stay Informed About Benefits**: Keep up-to-date with changes in Social Security, Medicare, and other benefits.
- **Consider Part-Time Work**: Some individuals may choose to work part-time or engage in freelance work to supplement retirement income.
- **Stay Active and Engaged**: Maintain an active lifestyle and stay socially engaged to enhance overall well-being in retirement.
**Want more information?**
Retirement planning is a multi-stage process that requires careful consideration and regular adjustments. Here are a couple of tools to help you:
**[Important Milestones](https://indfin.com/wp-content/uploads/2024/06/Important-Milestones-2024.pdf)**: Dates you need to know
**[Retirement Issues:](https://indfin.com/wp-content/uploads/2024/06/What-Issues-Should-I-Consider-Before-I-Retire-2024.pdf)** A 2-page retirement checklist covering areas like cash flow, healthcare and insurance, assets & debt, tax planning, long-term care and other issues.
Enjoy!
Jim
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Uncategorized
---
### [Get Ready for Some Possible Tax Increases!](https://indfin.com/taxincreases/)
**Published:** August 5, 2024
**Author:** Jim Lorenzen
**Excerpt:** As you may or may not know, the Tax Cuts and Jobs Act is due to expire at the end of next year – just 16 months from now. The Biden Administration has proposed new tax increases worth knowing about.
**Content:**
1. **Capital gains tax increase:** The current top rate is 20%; the Biden plan would nearly double it to 39.6% for individuals making more than $1 million annually. There’s also a separate proposal creating a 44.6% capital gains rate for those with high net investment and taxable income. This rate hike, combined with the plan to largely eliminate the ‘stepped-up basis’ loophole (we’ll get to that) will be a major blow to some investors
2. **Top marginal income tax rate increase**: This would go from 37% to 39.6% (a 7% increase in taxes) for those individuals earning over $400,000.
3. **Medicare tax increase** (the Net Investment Income Tax (NIIT)):The Medicare tax rate will go from 3.8% to 5% for individuals earning over $400,000 annually. This basically closes the loophole on those business owners with pass-through entities who have avoided the tax.
4. **Corporate tax increase:** This would jump from 21% to 28%. It’s interesting that the TCJA made corporate tax cuts permanent while individual cuts sunset next year. Some business owner will be seriously impacted. By the way, the corporate alternative minimum tax (CAMT) would increase from 15% to 21%.
5. **Repeal of like-kind exchanges**: The Biden plan would repeal Section 1031 of the tax code which currently allows for tax-deferred ‘like kind exchanges’ of real estate. Note Section 1035, which allows like-kind exchanges of insurance and annuities, does not seem to be under attack.
6. **Carried interest loophole closure:** Certain types of carried interest would be treated as ordinary income rather than capital gains. This will likely impact taxes paid by private equity and hedge fund managers.
7. **Billionaire minimum tax:** A new minimum tax would be imposed on households with a net worth exceeding $100 million. The Supreme Court’s recent ruling shows they’re less than enthusiastic about this provision and administration of this provision would be a nightmare.
8. **Elimination of stepped-up basis:** As mentioned earlier, the Biden plan would largely eliminate this provision where capital gains are not taxed when assets are transferred at death or by gift. This has bi-partisan opposition, however due to the damage it would do to family farms and family businesses.
9. **Increased limit on deducting employee compensation:** The $1 million cap would be expanded to apply to all employees of publicly and privately held C corporations. This would be good for business owners.
10. **Higher excise tax on stock buybacks:** This would increase from 1% to 4%, which could impact some investors’ investment strategies. This will also likely face strong opposition from large corporations.
The nearly $3 trillion in projected deficit reduction over 10 years (provided no new spending is added) signals the administration’s intent to raise revenue; but, you can expect a healthy debate in Congress.
By the way, even if none of these proposals are enacted, the TCJA still expires at the end of next year and taxes for most everyone will go up anyway. You can [see a comparison here.](https://indfin.com/wp-content/uploads/2024/08/2024_TCJA-Sunset-Provision-Comparison-Guide.pdf)
Enjoy,
Jim
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** Investing, Taxes
**Tags:** tax hikes, tax law changes, tax management
---
### [No Tax on Social Security Benefits?](https://indfin.com/no-tax-on-social-security-benefits/)
**Published:** January 27, 2025
**Author:** Jim Lorenzen
**Excerpt:** We all love free money; and no taxes on Social Security sounds good! Hey, Social Security benefits weren’t taxed for many years!
**Content:**
But, as we began to see an aging population, more people retiring, and a lesser percentage of population paying in, a source of revenue became necessary to preserve benefits for both current and future retirees. It was part of tax reform in 1986, hammered out by both parties, led by President Reagan and House Speaker “Tip” O’Neil. They created a framework for taxing ‘provisional income’. But (here it comes) those brackets weren’t indexed for inflation. Bingo. Inflation carried more people into those brackets as the years went by without either party having to raise taxes.
What is ‘Provisional Income”? It includes adjusted gross income, plus one-half of the Social Security benefit plus any tax-exempt interest. So, the brackets apply to 1/2 of the Social Security benefits received. Did you notice that even tax-free municipal bond interest is included for this computation? Let’s take a look at the brackets.
[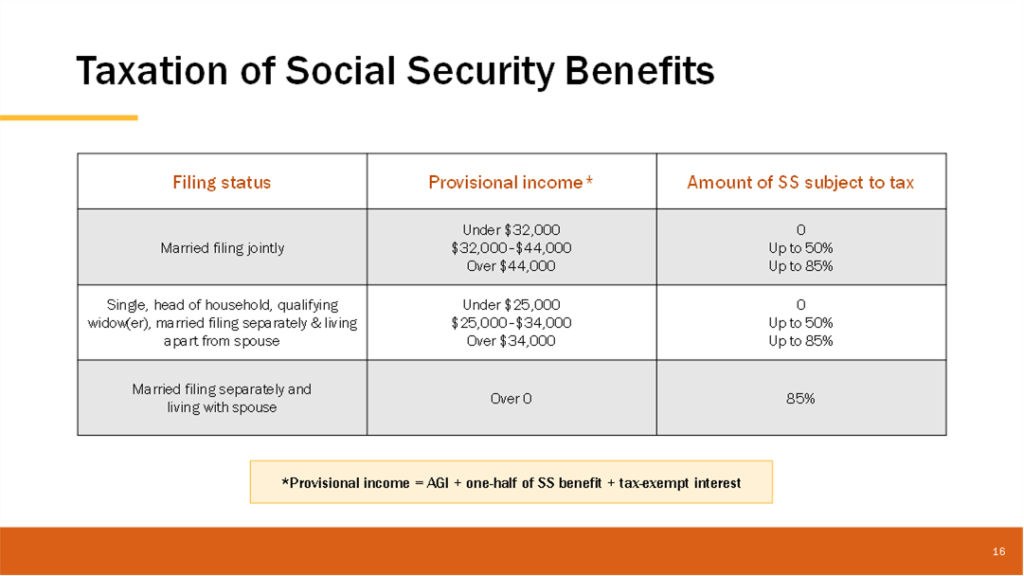](https://indfin.com/wp-content/uploads/2025/01/Provisional-Income-Brackets.png)As you can see, it doesn’t take much for a married couple to see their Social Security benefits get taxed. A married couple filing jointly and with only $75,000 in provisional income will see at 85% of their benefit included in taxable income.
What if their were no taxes on benefits? According to the Committee for a Responsible Federal Budget (CRFB), it would increase Social Security’s 10-year cash shortfall by $2.3 trillion through FY 2035, and advance insolvency by three years from FY 2034 to FY 2031. The across-the-board benefit reductiions in 2035 would go from 23% to 33%, according to the Congressional Budget Office (CBO). There’s more, but you get the idea: no free lunch. It basically eliminates a revenue stream now being used to fund current benefits, which puts stress on the trust fund.
**What can Congress do to save Social Security?** It’s simple math, really. There are reform proposals now circulating on Capitol Hill. The answer to come from any one or a combination of these options:
[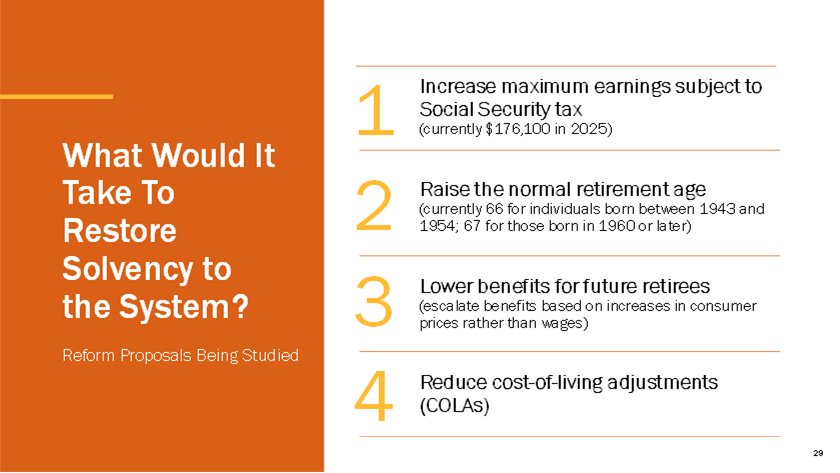](https://indfin.com/wp-content/uploads/2025/01/Fixing-SS.png)\#1 may be the easiest to get passed.
\#2 may be more difficult since working in a coal mine is different than working in an office.
\#3 may not be required if #1 is adequately adjusted.
\#4 may not be required for the same reason. They also could adjust provisional brackets.
We’ll see what congress does; but, as for taxes, be careful what you wish for.
Jim
Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications.
See Full Bio
**Categories:** IFG Viewpoint & Outlook, Retirement, Social Security, Taxes, Uncategorized
**Tags:** social security, social security outlook, tax law changes, Taxes in retirement
---
### [Will My Money Last?](https://indfin.com/will-my-money-last-2/)
**Published:** August 2, 2024
**Author:** Jim Lorenzen
**Excerpt:** If you are one of those asking the 'will my money last' question, there's a way you can find out just what your probabilities are!
**Content:**
**I’d like to make you a special offer:** A complete needs-analysis report and additional resources of appropriate checklists and flowcharts to help you on your way – including two meetings, either online or in-office – for just $600. The offer is good through August 9th.
Would you like the answer to the will my money last question? Your report will show you:
- A Summary of your prioritized Financial Goals
- A Summary of your Financial Resources
- A View of your Investment Assets by Asset Class and by Tax Category
- Net Worth Summary – All Resources
- Net Worth Detail – All Resources
- Your Current Portfolio Allocation by style and asset class
- Probability of Success by Importance based on your resources, life expectancy, tax situation, and your prioritized goals
- Your personal Worksheet Detail – Retirement Distribution Cash Flow Chart – This can be an eye-opener.
- Your personal Worksheet Detail – An “Inside the Numbers” Final Result
- Additional appropriate flowcharts and checklists
There’s nothing to buy – I don’t sell investments – and there’s no obligation. This is a straightforward $600 offer. **You can get started by [submitting this priority review](https://indfin.com/retirement-priority-planning-review/).** **At the bottom be sure to mention you want to take advantage of the $600 Needs Analysis offer.**
Why not [**get started today**](https://indfin.com/retirement-priority-planning-review/)? Remember, the offer ends August 9th.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Inflation, Investing, Planning, Retirement, Retirement Income
**Tags:** longevity, retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy
---
### [Protecting Wealth from Inflation](https://indfin.com/protecting-wealth-from-inflation/)
**Published:** July 15, 2024
**Author:** Jim Lorenzen
**Excerpt:** We all know the Fed target is 2% inflation; but, since COVID-19 and all the accompanying spending, it’s been tough going for the Fed. While the rate of inflation has been slowly declining, it’s still stubbornly around 3% - and with people living longer, it can still spell disaster for those facing retirement, especially with longer life expectancies.
**Content:**
Someone age 40 today may think that continuing to live on a $100,000 income in retirement might be just fine; however, assuming retirement at age 65 and a 3% inflation rate, it will take an annual income of over $209,000 to provide the same purchasing power.
Now, obviously, Social Security will provide a portion of that requirement, but it will likely be a minority portion. Let’s say Social Security provides $50,000 (coughing, maybe some chuckles), $159,000+ will still have to come from investments. How much will be needed? Rough guess: close to $4 million!
Oops. Better start saving.
How about those getting ready to retire? What should they do? At the risk of sounding self-serving, get an advisor. **Generic information isn’t advice**; but, here are some ideas you and your advisor should discuss.
**Understanding Inflation**
Remember money is not about how many pictures of Presidents you have. Money is worth only what it purchases.
Inflation rates can vary widely from year to year and are influenced by factors such as government policies, economic growth, and global events. While moderate inflation is considered healthy for economic growth, too much inflation can wreak havoc on savings and investments if not properly managed.
**Strategies to Protect Wealth Against Inflation**
There are only three things you can do with money:
> > - you can loan (bonds, cds, savings, etc) – a strategy that historically doesn’t hedge inflation especially after taxes
> > - you can own, or
> > - you can bury it in your back yard (or some other convenient location) – a guaranteed loss to inflation)
Two out of those three will lose to inflation. Ownership of assets always seems to do better – go figure.
**1. Real Assets**
Real assets are tangible assets that tend to retain or increase in value over time, keeping pace with or outpacing inflation. Examples include:
Real Estate: Property values generally rise with inflation, making real estate a popular inflation hedge.
Commodities: Precious metals like gold and silver, as well as other commodities like oil and agricultural products, often maintain their value during inflationary periods.
Infrastructure: Investments in infrastructure projects such as toll roads or renewable energy facilities can provide stable returns that adjust for inflation.
Diversifying into these real assets can help cushion your portfolio against the erosive effects of inflation.
**2. Stocks** – equity in the companies that sell products
Have you been at the grocery checkout lately? Upset about the prices? Do you own equity in any of the companies that are selling all those products at higher prices? Hmmm. These are consumer staples: Companies that produce essential goods like food, household products, and pharmaceuticals often see increased revenues during inflation. Other equity ownership options include:
Natural Resources: Companies involved in mining, energy production, and agriculture can benefit from rising commodity prices.
Utilities: Utility companies typically pass on increased costs to consumers, maintaining their profit margins during inflation.
But, Jim! Stocks are risky. They go up and down!
Yes, but inflation seems to go up more consistently. By the way, your house goes up and down, too. Did you sell at the last price decline? Your car *always* goes down, but you still like it.
**3. Inflation-Indexed Bonds**
Governments issue inflation-indexed bonds (like TIPS in the United States) that adjust their principal and interest payments based on inflation rates. These bonds guarantee that your investment keeps pace with inflation, offering a reliable way to preserve purchasing power. Of course, as I said, there are taxes. What if you hold TIPS inside an IRA? You still have taxes – tax deferred means tax delayed. Do you know what your tax bracket will be in 20 years? Trusting Congress to spend less may not be a good plan.
**4. Diversify Globally**
Inflation rates vary by country and region, so diversifying your investments globally can help mitigate inflation risks. By spreading your assets across different economies, currencies, and markets, you reduce the impact of inflation in any one region.
**5. Focus on Income-Generating Investments**
Investments that generate a steady income, such as dividend-paying stocks, rental properties, or bonds, can be effective against inflation. Regular income streams adjust with inflation and provide stability during economic uncertainty. The lessons of Warren Buffett should not be lost on a forty-year-old: it’s not share price that matters, it’s the accumulation of shares over time that counts. The price of quality companies will take care of itself over time. Notice the long-term trend of the large indexes lately?
**6. Avoid Long-Term Fixed-Rate Debt**
During inflationary periods, the real value of debt decreases because you are paying back loans with less valuable currency over time. However, it’s crucial to distinguish between good and bad debt. While manageable mortgage debt on appreciating real estate can be beneficial, high-interest consumer debt can quickly erode wealth. And, don’t forget interest rate risk. A 1% rate hike and do a lot of damage to a 30-year bond.
**How much should you own of any of the above?** Consultant’s answer: it depends. It’s not as simple as picking a retirement date and choosing an allocation (target-date funds seem to assume that everyone 10 years from retirement with the same risk profile has the same income, spending needs, obligations, even number of children, I guess. Not every investment option, no matter how good for one person, may not be right for another. Remember: penicillin is a miracle drug, but some people are allergic to it.
**7. Monitor and Adjust**
Economic conditions and inflation rates change over time. Regularly review your investments and financial strategies to ensure they remain aligned with your goals and current economic trends. Adjust your portfolio as needed to maximize protection against inflation.
**Practical Steps to Implement These Strategies**
Educate Yourself: Stay informed about economic indicators, inflation rates, and market trends.
Consult Professionals: Never get neuro surgery advice from a podiatrist. Don’t get financial advice from your hairdresser. Never get legal advice from me – or even hair care, for that matter. The financial services industry is filled with meaningless credentials obtained at weekend hotel seminars – they make good marketing but are of little value. Make sure your ‘advisor’ – everyone seems to use that title these days – is the real deal.
Stay Disciplined: Stick to your long-term financial plan and avoid emotional reactions to short-term market fluctuations. That’s why it’s call investment discipline. People who have a real plan not only know *what* they’re doing, but *why* they’re doing it. Short term surprises don’t surprise.
*“The only thing that surprises me is that we continue to be surprised when surprise happens.”*
*– Donald Rumsfeld, former Secretary of Defense*
*Known and Unknown*
Review Regularly: Schedule periodic reviews of your portfolio and financial goals to make necessary adjustments. Remember, investments aren’t the only things that change. You’ll change, too! In addition to constant ageing, there are other issues: future purchases, births, deaths, college, vacations, – the list is long, but they’ll all impact your plan, particularly 20+ years out from now.
**Conclusion**
Protecting wealth against inflation requires foresight, diversification, and informed decision-making. You wouldn’t build a house without a blueprint; your financial future should be no different. By staying disciplined and regularly reviewing your financial strategies will ensure that your wealth continues to grow and preserve its purchasing power over time. Remember: think long-term.
Planning your retirement? [This little tool](https://www.calcxml.com/do/ret05?teaser&c=4a4a4a) may help you measure the impact of inflation on *your* retirement, and here’s[ a good place to get your ducks lined-up](https://indfin.com/all-about-you/).
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [What Does the Future Hold for Social Security?](https://indfin.com/what-does-the-future-hold-for-social-security/)
**Published:** April 3, 2024
**Author:** Jim Lorenzen
**Excerpt:** It’s an election year, and while the headline topics dwell on the border, January 6th, the age of the candidates, and all the rest, few are talking about the “3rd rail” of politics: social security.
You can expect a few politicians will come up with innovative approaches (they know will never reach the floor for a vote), but it does make for good campaign sound bites. It can be confusing.
**Content:**
Some political influencers have made the claim that Social Security is basically a bait-and-switch shell game. Matt Bruenig at the People’s Policy Project makes a good case.
> [What Does It Mean to Increase the Social Security Retirement Age?](https://www.peoplespolicyproject.org/2022/10/26/what-does-it-mean-to-increase-the-social-security-retirement-age/)
How Social Security calculates retirement benefits:
Note: How benefits are calculated:
Politicians love to say the system is nothing but a bunch of IOUs that add to the debt, but like most things politicians say – they are in the reelection business, after all – it’s actually a half-truth.
The Trust fund *is* full of I.O.U.s – and it should be. If you managed a trust fund that had to provide safety for other people, what would you invest in? Most trust funds place an emphasis on Treasury bonds. And, the Social Security system is no different. The trust fund buys special-issue Treasuries (special issue because they’re redeemed at par, which removes interest rate risk). Treasuries are a form of government debt – If you own government bonds, whether directly or through a fund, you’re part of the debt, too).
Some politicians want to see partial privatization of Social Security, but that’s discussion for another time. Just read the fine print (a town full of lawyer-politicians acting like economic experts is never comforting.
Whether any solution makes things better for recipients is the subject for further analysis; however, there are a number of ways Social Security can be saved. Basically, it’s a math problem.
Here’s a 13-minute video that will hopefully provide some clarity for you. You may also There are four possible solutions. You might find this helpful. You may also like visiting my [Social Security page](https://indfin.com/socialsecurity/) for more information.
Enjoy! Jim.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
**Tags:** Retirement Income, Retirement Planning, social security, social security outlook, Will Social Security be there for me
---
### [Facing Retirement Account Rollover Decisions?](https://indfin.com/facing-retirement-account-rollover-decisions/)
**Published:** March 13, 2024
**Author:** Jim Lorenzen
**Excerpt:** Believe it or not, you'll have a number of options available to you - and it pays to do your homework before making decisions that could be irrevocable - and costly.
**Content:**
You have retirement and rollover decisions to make; and each of your options comes with upsides and downsides. What are your options? You can
1. [Leave the money in your plan!](https://vimeo.com/919700051/7b737bab00?share=copy) Basically, do nothing!
2. [Move the money to your new employer’s plan](https://vimeo.com/920114129/0c2b47679f?share=copy) if you’re changing jobs.
3. [Roll your money into an IRA](https://vimeo.com/920143551/d626474dc1?share=copy) – a popular rollover decision for many.
4. [Take the money and run ](https://vimeo.com/920518130/bc3869cfd0?share=copy)– cash out!
5. [Convert your employer plan assets into a Roth IRA](https://vimeo.com/920533438/7ec240929c?share=copy)
6. [Make a Roth conversion inside your company’s plan](https://vimeo.com/920545311/9ac36bd94d?share=copy), if your company allows Roth 401(k)s.
Each of these options comes with it’s own set of pros and cons; so it pays to do your homework first. [You can begin here](https://indfin.com/retirementdecisions/)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Retirement, Rollovers, Roth conversions, Taxes
**Tags:** 401(k) rollovers, company plan rollover, IRA rollover, retirement decisions, Retirement Planning, Retirement Strategy, rollover mistakes
---
### [Tax-Delayed Isn’t Tax-Free](https://indfin.com/tax-delayed-isnt-tax-free/)
**Published:** February 5, 2024
**Author:** Jim Lorenzen
**Excerpt:** Believe it or not, investing during working years was the easy part. Just keep accumulating! Even better, the money you put aside wasn’t taxable. Such a deal! Tax-delayed doesn't mean tax-free however.
**Content:**
Ideally, you’d retire tax-free, too – disinheriting Uncle Sam! Nice thought; but when you retire, investing isn’t so easy. There’s more to think about.
First, that tax-deferred retirement account has been growing for decades. At retirement, it might be quite large and at some point Uncle Sam (your business partner in life – the one that can make up the rules beyond your control) will force you to begin taking distributions, whether you need them or not. These required minimum distributions (RMDs) each year will be based on your account value. Obviously, the higher the account value, the higher the RMD.
Do you know what tax brackets will look like when you turn 70? Of course not, but given our nation’s debt (see it in real time at ) , you might be able to assume a direction (pick up or down). But, unknown taxes on your RMDs are only one factor. The size of your RMD will impact how much of your Social Security is taxable and, oh yes, the size of your RMD will also impact your Medicare premiums.
**Instead of Tax-Delayed, wouldn’t Tax-Free be better?**
There are two options you can use to help minimize taxes: you can either withdraw funds to complete a Roth conversion or use an over-funded permanent life insurance policy. – both will allow you to grow and access money on a tax-free basis. Each has it’s benefits worth considering.
**How much to withdraw?**
Our tax code is progressive. Part of your income is taxed at one rate and other portions are taxed at another. For example, you may have one portion of income taxed at 12% with money above that bracket being taxed at 22%. The highest bracket you’re in is your marginal tax bracket. Since current tax law is due to sunset at the end of next year, taxes now are ‘on sale’. It may make sense to convert whatever you can that will keep you in your current bracket; however, you will pay taxes at current rates on that withdrawal you use for conversion. Another point: make sure you can pay those taxes from other funds – paying from converted funds defeats the purpose of the conversion – you want to convert the full amount.
**Other options**.
There are other avenues available to mitigate taxes, but nothing is perfect for everyone. Whether they make sense for you is something you should discuss with your tax and CFP® professional.
- Donor-advised funds (DAF): You contribute charitable donations to a fund you control when distributions are made and receive the tax benefit in the year you make the contribution to the fund. Making multiple donations in a single year can provide offsetting taxable distributions from your retirement account in that same year.
- Charitable remainder trust (CRT): You contribute future charitable donations into the trust that you control when distributions are ultimately made (usually at death); however you receive the tax benefit of the donation the year you make the contribution. You can also receive income from the trust while you’re alive (within IRS limits). Again, making multiple donations in a single year can offset taable RMDs from your retirement accounts. You should talk with your estate planning attorney.
- Qualified charitable donations ( QCD): Anyone over age 70-1/2 can make a direct donation from a qualified account to a charity – this bypasses the standard deduction limits which means the donation becomes a tax-free transfer. You should talk with your tax advisor and CFP® professional.
Food for thought….
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
**Tags:** retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy, tax management, Tax reduction, Tax-Free Retirement Income
---
### [Bad Financial Behavior and How to Avoid It!](https://indfin.com/bad-financial-behavior-and-how-to-avoid-it/)
**Published:** October 20, 2023
**Author:** Jim Lorenzen
**Excerpt:** Rollercoasters are fun – at the amusement park. Not so much in your retirement account. And that’s where bad financial behavior gets costly.
**Content:**
You’ve probably heard tales of folks making a fortune in the blink of an eye – probably at some downtown investment seminar where they’re selling their system in the back of the room. Financial behavior is often our worst enemy. Some people decide they can get rich by trading options. Hey, the seminar speaker said you can do it safely!
The temptation to jump on the money train is strong. But, before you start dreaming about yachts and mansions, let’s talk about why your financial behavior in the real world can sting you worse than that one time you tried to eat ghost peppers on a dare.
**I. The Thrill of Chasing Big Bucks**
Sure, the idea of striking it rich is as exciting as discovering a hidden treasure chest. But the problem is that gambling isn’t investing. When the two get confused, is when things can get a little dicey. It ain’t Vegas.
But, it can be an emotional rollercoaster. If you’ve ever been on a rollercoaster, you know the highs and lows. This is especially true for those (not so bright) who are continually check their phones to see how their stocks are doing.
Warren Buffett is amazing for a laundry list of reasons. One of them is the fact he never watches the stock market and freely tells people he hasn’t the slightest idea what ‘the market’ is doing – he pays little or no attention to price – yet, so many people watch little else (his writings are worth reading).
**II. The Real Cost of Risky Business**
Okay, let’s talk about the dark side of risky financial behavior and investments. It’s not just about losing money; it’s about what it does to you, as a person, and your family.
Stress and Anxiety. Constantly watching your investments can make you as anxious as a cat in a room full of rocking chairs. Stress can lead to health problems. Who needs that?
Relationship Drama. Your money habits can also strain your relationships. Money can be a touchy subject, and when your investments go south, your family and friends might start to feel the heat.
**III. Forget About Perfect Timing**
Talk about bad financial behavior. Thinking you can time the market perfectly is like believing you’ll win the lottery if you keep buying tickets. It’s just not likely.
Market Predictions Are Tricky. Yogi Berra once said that predictions are hard, especially when they’re about the future. The truth: no one knows what the market will do. Maybe that’s why Mr. Buffett doesn’t worry about price.
Some people seem to have missed the tale of the hare and the tortoise.
**IV. Diversification: Not Putting All Your Eggs in One Basket**
Diversification is a somewhat overused word – I say that because most people regard it as simply spreading money around different investments. I’ve seen people buy four different growth mutual funds thinking they were diversifying their risk when all they were doing was constantly *replicating* it. There’s more to it than that. You can [learn ](https://indfin.com/asset-diversification-report/)[more ](https://indfin.com/asset-diversification-report/)[here](https://indfin.com/asset-diversification-report/) if you’re interested.
Diversifying your investments in the right way can help protect you from major losses. Just like a zombie apocalypse plan, it’s always good to have a backup.
Diversified portfolios often provide steady returns over time. Think of it like slow-cooking a stew rather than microwaving a hot pocket – it might take longer, but it’s worth the wait.
**V. The Magic of Patience**
In the world of finance, patience is the opposite of bad financial behavior. Patience can make a huge difference in your financial success.
Forget the phone quotes. Think long-term. It can get to 30-below in Minnesota in winter, but they all know the sun will come back out in the spring – no one panics.
**VI. Discipline and Learning**
Discipline Is Key. Discipline is far easier when you have a plan. The reason is simple: a retirement plan has already factored-in the periods of crisis. Those with plans not only know *what* they are doing; they also know *why* they’re doing it and *aren’t surprised* by the detours.
So, sticking to a plan – good financial behavior – and not going off the rails when things get bumpy becomes much easier.
Keep Learning. My dad used to say, “If you think knowledge is expensive, try ignorance.”
Education is like your secret weapon in the financial world. The more you know, the better equipped you are to make smart choices and avoid financial pitfalls. Caveat: don’t confuse entertainment with education. Little – virtually none – of what you see on tv or on your phone is education. Always consider the source but remember, true education is more likely to be found in educational books. Read one lately?
**VII. Real-Life Examples: The Consequences of bad financial behavior.**
Let’s look at a couple of stories that show what can happen when financial behavior can go a little wild resulting in bad investment decisions.
The Dot-Com Bubble
Back in the late ’90s and early 2000s, it seemed like everyone was jumping on the dot-com companies. People poured their money into these stocks, thinking they’d get rich quick. When the bubble burst, many lost their life savings. Fad chasing seldom works. Kind of like all the buffalo going over the cliff.
The Housing Market Crash
During the housing boom, many folks were buying properties left and right, thinking it was a surefire way to get rich. When the market crashed in 2008, many found themselves drowning in mortgage debt. It’s like thinking you’ll get rich by collecting Beanie Babies, only to realize they’re not worth much after all. The main reason people think real estate is less risky than stocks is simply because they don’t see a daily price quote. No wonder Mr. Buffett doesn’t check prices. Investments are investments. Financial behavior is often what makes the difference.
**VIII. Conclusion: The Tortoise was right – Steady Wins the Race**
In the end, it’s all about staying cool, calm, and collected in the financial world. Chasing quick riches is a bit like trying to win the lottery – it’s fun to dream, but it’s not a solid plan. To truly succeed, focus on being sensible, [diversify your investments](https://indfin.com/asset-diversification-report/), be patient, stay disciplined, and never stop learning. In a world full of financial storms, the smart financial behavior is being the calm and collected. You wouldn’t build a house without a blueprint; why should your financial house be any different.
The plan is the key.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
**Tags:** Financial planning, Investment Strategy, managing risk, Reducing Risk, retirement decisions, Retirement Planning, Retirement Strategy
---
### [Older Variable Annuities Can Be Expensive!](https://indfin.com/older-variable-annuities-can-be-expensive/)
**Published:** August 3, 2023
**Author:** Jim Lorenzen
**Excerpt:** Older annuities have grown – and so have their expenses. They may be worth a review.
**Content:**
A $500,000 annuity growing at 7.17% can double in value in only 10 years. That’s the good news. The bad news: it’s likely the expenses in these older variable annuities have doubled as well.
People purchase annuities usually for their tax-deferral feature. The growth isn’t taxed until the money is taken out. Makes sense. Variable annuities have sub-accounts which are similar to mutual funds and it’s the insurance wrapper that buys the tax-deferral feature. This wrapper, of course, comes at a cost (what doesn’t?) for mortality and administration expenses.
Many of the annuities that were available years ago – and still today – charge a percentage of account value to cover those costs; but, as the account value increases, so do the expenses. There’s more: these insurance expenses are in addition to the expenses for the underlying investments.
Here’s a hypothetical example: it’s not uncommon for the ‘insurance wrapper’, especially in older annuities, to come in at around 1.4%. So, the cost of a $500,000 variable annuity at 1.4% would be $7,000. It that annuity doubles to $1 million in value over ten years, the wrapper would cost just over $13,000. Did the annuity’s cost really grow that much?
How much would that wrapper cost over a ten-year period? A little calculation shows that the total cost would come to $97,495 – and that’s if the money grew by 7.17% annually. Obviously, the expenses for a 9% or 10% growth rate would have been much higher.
Nevertheless, paying almost $100,000 in administration for $500,000 worth of growth, even with tax deferral, can look pretty steep.
Those with older variable annuities, especially those with low or no surrender charges may want to review them.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Annuities, Annuities, Retirement
**Tags:** annuity review, Investment Strategy, Retirement Annuities, retirement decisions, Retirement Planning
---
### [How Can You Make Your Retirement Money Last?](https://indfin.com/how-to-make-your-retirement-money-last/)
**Published:** May 4, 2023
**Author:** Jim Lorenzen
**Excerpt:** Making your retirement nest-egg last through retirement isn’t easy. Company pension plans have all but disappeared, which means it’s now up to you to be your own actuary. Unfortunately, it’s not something many are equipped to do.
**Content:**
How can you make retirement money last? Let’s begin with one that gets a lot of heavy industry promotion. Some firms promote them as being the answer to all your prayers while other disparage them as evil, hateful, and to be avoided at all costs.
Both are wrong – big surprise. Absolutes seldom prove credible.
Let’s start with fixed annuities. Fixed annuities with yields tied to a stock index – indexed annuities – have become hot in recent years, much of it due to an aging population increasingly wary of volatile stocks. The rise of annuity sales is great. Fear of stock market volatility has affected variable annuity sales, as well.
One of the reasons index annuity sales are up is partly due to more consumer friendly product designs that have made the product more acceptable to the industry (and their compliance departments) and, as noted, partly due to demographic trends, i.e., baby boomers’ changing priorities. Making retirement money last has become a priority and annuities do speak to a need.
Remember, though, the financial industry is famous for responding to trends (and fears) with saleable solutions designed to generate revenue for the distribution channel. If you’re considering purchasing an annuity, here are a few guidelines you may want to consider.
Index-linked annuities are NOT a substitute for equities.
If you want to compare them to something, they should be compared to other investments designed to protect your money, i.e., CDs, treasuries, etc. The reason for this is simple: Annuities are not stock market investments; they are fixed-return investments that pay an unpredictable rate of return each year – the rate applied is dependent upon the return of an outside index. While you can’t lose, the upside is generally capped. A little math tells you that if the market is up 2 out of every 3 years, the best you’ll make is the cap rate for two of the three years and one will be 0. So even if you have a cap rate of, say 10% and you earn 10%, 10% then 0%, your compounded rate of return for the three years is 6.56%. While the return is tax-deferred, you still have a tax issue: If your combined federal and state tax bracket is 30%, it means, in reality, you’re making 4.59% – the rest is Uncle Sam’s money that’s growing…. and Uncle Sam can (probably will) change his mind about how much of it is his when the time comes you decide to withdraw your money. He could decide he wants more.
So, return is unpredictable, though tax-deferred, and it’s capped. In exchange for giving up a guaranteed return, you might get 1%–2% more per year over the long run, depending on what future interest rates and the stock market does. If interest rates move up and the market is flat, results could be problematic. My own take is that one should expect a return similar to short-to-intermediate bonds.
If you are considering an index annuity with a living benefit, realize that the income guarantees on the date of issue are the most you will likely ever receive.
**Do Annuities make sense for Lifetime income?**
It’s a strategy for making your retirement money last. The premiums you pay go into the insurance company’s general account, which is then invested heavily in bonds. Outlays are then matched to the length of time they are needed.
The growth potential for stocks is greater, of course, and individual bonds can support an income for a fixed period, but they do not offer longevity protection. You can create a bond ladder, but, the longevity protection won’t exceed the last bond in the ladder, so it may not be the best way to make sure your retirement money lasts.
And, contrary to what many may believe, bond funds can be quite volatile. Funds with long bonds can be as volatile as the stock market, exposing retirees to both potential losses *and* sequence risk while still not providing the long-term inflation hedge required to support maybe 30 years of spending during retirement.
One thing an annuity provider can offer: risk pooling. This allows an income annuity to support a higher level of lifetime spending compared to bonds. Stocks have proven to provide that long-term inflation hedge; but short-term risk. A downturn in the market during the early years of retirement, while a retiree is withdrawing money, can create a hole that’s very difficult to dig out of. So, we have sequence-of-returns risk on the short end of the time frame and longevity risk – outliving your money – on the long end.
Think about annuities as income bonds of a different type: The length of payments are for life with no maturity date. The flip side is the principal value is not repaid upon death. You’re trading principal (which you hope you don’t have to spend anyway) for security, which was the whole point of investing in the first place. And, even though they may appear to make retirement money last, their value as an inflation hedge is problematic.
When you think about it, [Social Security](https://indfin.com/socialsecurity/) is a form of annuity – you’ve been paying premiums all your working career that goes into pooled money sharing the risk – providing an income you can’t outlive with no return of principal. Ask some seniors if they like their Social Security – I’ll bet the answer will be unanimous. And, Social Security DOES provide inflation adjustments – key to making retirement money last.
So, we do know an income annuity can be a great tool for managing longevity risk. The payout rates for an income annuity assume bond-like returns and longevity is further supported through risk pooling and mortality credits, rather than by seeking outsized stock market returns.
Risk pooling is the ‘secret sauce’. While you may think it counterintuitive to subsidize payments to others, this act can allow all owners in the risk pool to enjoy a higher standard of living than bonds could support. All annuity owners know that the mortality credits will be waiting for them if they do end up living beyond life expectancy.
An income annuity not only provides longevity risk protection, it also avoids sequence risk. The annuity provider invests the pooled money mostly into individual bonds which create income that matches the company’s obligations for covering its promised annuity payments.
**So, someone near or in retirement has some choices**; but, it’s not an all-or-nothing proposition. There are stocks, bonds, annuities, or they can self-annuitize. Do you want to make retirement money last – or do you wan to make your *income* last? Or, can you do both?
**Bonds**: One could spread the money over a bond ladder of 20 years or so; but, history tells us spend rates over that period wouldn’t be sustainable, especially with taxes and inflation. In short, you could still expect to be taking longevity risk and a danger of no late-life income.
**Income annuities:** With risk pooling, longevity risk is eliminated, no matter how long the annuitant survives.
**“Self-annuitizing”**: Now suppose the retiree “self-annuitizes” instead by managing this longevity risk without insurance. Suppose we assume a retirement of thirty years. Note that there is a direct relationship between a longer life and a lower rate of spending. Retirees who plan to self-annuitize are forced to spend less to the extent they worry about outliving their money. For those with substantial portfolios and responsible spending habits, this is an option – as it is for most of my clients.
**Stocks**: I saved stocks for last. Stocks create risk. No news there. The greater the stock exposure, the greater the exposure to volatility. And, as we’ve noted, spending from investments further heightens sequence risk. A few poor returns early on could easily derail retirement outcomes for years, even permanently.
It seems life is full of trade-offs. Annuitized assets do not provide upside stock market potential or a legacy for heirs, but spending (longevity) risk is also eliminated.
One problem with “Self-annuitizing” is that it requires lower spending, and stocks could support higher spending with upside growth – and both options have their risks, as we’ve seen.
Bonds? The question is why would anyone want to hold bonds to meet spending obligations, given what we’ve noted above? After all, an income annuity invests in bonds and provides payments precisely matched to the length of retirement, while bonds alone hold no advantage.
So, the income annuity provider’s risk pooling allows us to spend more in the early years when sequence of return risk is greatest and addresses longevity risk as well. Again, remember, their value as a long-term inflation hedge – money is worth only what it can purchase – might be problematic.
Sequence risk has another wrinkle. Many people are faced with spending less in the early years in the hopes that values will increase so that they can spend more later. But, in fact, most people spend more in retirement’s early ‘go-go’ years, compounding sequence risk, and may be forced to reduce their standard of living later. This can be disastrous because inflation compounds, too!
Now, after reading all this, you might think I’m a huge promoter of annuities. Well, yes and no. The fact is while I am licensed for annuities, I have not placed one with a client for over ten years. Now, this could change, of course – they’ll need to come up with a low-cost long-term inflation solution – but, while I think they can be a fine tool for many people, I just haven’t found them the right ‘fit’ for anyone I work with. After all, penicillin is a miracle drug, but some people are allergic to it. Doctors don’t go around selling penicillin and advisors shouldn’t be just be prescribing annuities either. Annuities can be very complex and contain a lot of hidden levers under the hood. I’ve always believed that anything a client invests in should be simple, clear, and easy to understand. The more complex something is, the less I like it. There are a lot of good, clean, simple annuities out there (without the bells and whistles that can make them both highly marketable and dangerous); I just haven’t found the right fit yet – but, I’m sure at some point I will. There’s more at stake than simply making retirement money last.
Back to our retirement income issue, how does a retiree prepare? Like building a house, it begins with a blueprint. However, understanding: how to address retirement income and portfolio construction begins with understanding there’s usually a combination of tactics required to create a strategy. And, it helps to have some [guardrails](https://vimeo.com/635459466/282eb2c845) built in.
If you’d like some help getting your planning started, I hope you’ll [reach out](https://indfin.com/getting-started/).
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Annuities, Retirement, Retirement Income
**Tags:** Income Annuities, Reducing Risk, Retirement Annuities, retirement decisions, Retirement Income, Retirement Planning, secure retirement
---
### [Social Security Answers to The Most Pressing - Questions.](https://indfin.com/socialsecurityquestions/)
**Published:** July 6, 2023
**Author:** Jim Lorenzen
**Excerpt:** Social Security decision-making isn’t as easy as it was for our parents and grandparents. When they became eligible, they simply went downtown (remember those places?) and simply filed.
Not so easy today. Social Security decision-making has become more complex and, unfortunately, because of that, there are few ‘simple’ answers.
**Content:**
One of the biggest Social Security answers people want to know is simple: **When should I start claiming Social Security benefits?**
That depends on various factors, such as life expectancy, health factors, financial needs, and other sources of retirement income. While you can claim benefits as early as age 62, doing so will result in a reduced monthly benefit. On the other hand, delaying your claim beyond your full retirement age (FRA) can lead to increased benefits. What’s right for you?
The answer, again unfortunately, is more complex. The people who work at your local Social Security office (or on the other end of the phone) are hard-working and well-meaning; but, they are not financial planners and often – again, thinking they are helping – provide the wrong advice. For that reason, it’s best to get your Social Security answers from fiduciary advisors who can integrate all of your planning. One client of mine, a widow who had not reached full retirement age, was told to claim her deceased husband’s benefit now because it would be much higher. The advice was correct, but it was also wrong. She didn’t need the income now. She could claim her reduced benefit now and allow her husband’s benefit to continue growing until full retirement age later. The difference would be significant. If she had followed the well-intentioned advice of the Social Security worker, she would have been frozen into a benefit that would have been much lower than she could have received for many years.
**How is my Social Security benefit amount calculated?**
The Social Security Administration (SSA) calculates your benefit amount based on your average indexed monthly earnings (AIME). The AIME is determined by adjusting your lifetime earnings for inflation and considering your highest-earning years.
The SSA applies a formula to your AIME to calculate your primary insurance amount (PIA), which is the monthly benefit you would receive if you claimed benefits at your FRA. The PIA is subject to adjustments based on the age at which you claim benefits (reductions for early claiming or increases for delaying).
**Can I work and receive Social Security benefits at the same time?**
This is one of those Social Security answers that often surprises. Yes, you can work and receive Social Security benefits simultaneously. However, if you claim benefits before reaching your FRA and earn above the annual earnings limit, your benefits may be temporarily reduced. Once you reach your FRA, there is no earnings limit, and you can work and receive your full Social Security benefits without any reduction.
Here’s something few people realize: if your benefits were reduced due to early claiming and excess earnings, the SSA will recalculate your benefits at your FRA to account for the reduction. This means your monthly benefit will increase to make up for the withheld amounts. So, don’t let this concern keep you from working.
**What happens if I continue working after claiming Social Security benefits?**
If you continue working after claiming Social Security benefits, your earnings may affect the taxation of your benefits. You see, depending on your total income, a portion of your benefits may become subject to federal income tax. It’s based on something called provisional income. The exact calculation can be complex. You may want to talk to your tax professional. If you are working with a *CERTIFIED FINANCIAL PLANNER*® professional, s/he can be of help here, as well.
Again, if you continue working and earning a higher income, your future Social Security benefits may be recalculated. The SSA reviews your earnings record annually and adjusts your benefits accordingly, potentially increasing your future benefits if your new earnings replace lower-earning years from the past.
**What happens to my Social Security benefits if I divorce?**
If you are divorced, you may still be eligible for Social Security benefits based on your ex-spouse’s earnings record. To qualify, you must have been married for at least ten years, be currently unmarried, and be at least 62 years old. Additionally, your ex-spouse must be eligible for or already receiving Social Security retirement or disability benefits.
If you meet these requirements, you may be entitled to claim either your own benefits or a spousal benefit, whichever is higher. Claiming benefits based on your ex-spouse’s earnings record will not affect their benefits or their current spouse’s benefits. Like I said, Social Security answers can often be surprising.
**What happens to my Social Security benefits if I remarry?**
If you remarry, you generally cannot continue to receive Social Security benefits based on your former spouse’s earnings record, unless your subsequent marriage ends either by death, divorce, or annulment. However, if you are eligible for benefits based on your new spouse’s earnings record, you may be able to claim benefits as a spouse.
This is one of those Social Security answers people seek that can be costly without proper planning. It is important to review the specific rules and regulations surrounding Social Security benefits for divorced individuals and those who remarry to understand how your benefits may be affected.
**Is Social Security financially stable for the future?**
There’s probably more misinformation surrounding this issue than any other. Much of it because of the ambitions of politicians. Concerns about the long-term financial stability of Social Security are widespread. While the program faces challenges due to demographic shifts and an aging population, it remains a vital safety net for retirees and individuals with disabilities.
The Social Security Trustees regularly review the program’s financial status and make projections about its future. Currently, the Trustees’ reports indicate that Social Security has sufficient reserves to pay full benefits until 2034. Beyond that point, if no changes are made to the program, it is estimated that incoming revenue will be able to cover around 76% of scheduled benefits.
Efforts are being made at the legislative level to address the long-term sustainability of Social Security. However, it is important to stay informed about potential changes and consider them in your retirement planning.
**Are you ready to do your homework?**
If so, you can [begin here](https://indfin.com/socialsecurity/), where you’ll find a brief discussion and links to some education. Grab some coffee and get ready to take some notes. Many of the Social Security answers you seek can be found here. I think you’ll find this will be a worthwhile [one-hour classro](//vimeo.com/816255781/6a62bbd7bf)[o](https://vimeo.com/816255781/6a62bbd7bf)[m](https://vimeo.com/687190688). The notes you take will give you an excellent list of ‘conversation starters’ when you meet with your CFP® professional or tax advisor.
Enjoy!

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Social Security
**Tags:** retirement decisions, Retirement Income, Retirement Strategy, social security claiming, social security help, social security outlook, when to claim social security
---
### [Planning Your Future Without a Roadmap?](https://indfin.com/planning-your-future-without-a-roadmap/)
**Published:** September 14, 2023
**Author:** Jim Lorenzen
**Excerpt:** You want to begin planning your future life, but aren't sure how. You want help but don't know how to get stareted. Sound familiar? It should.
**Content:**
Despite the fact that the overwhelming majority of people who have advisors are happy with them, it’s not a majority of people that hire an advisor. Those that do tend to be high net worth families, which means that many who are among the so-called mass-affluent want help but are either unconvinced or don’t know how to begin. Planning your future without an experienced guide can be expensive.
Here’s a good way to begin your journey. Learn about MyBlocks. It’s an easy way for you to get started on your own and lay financial groundwork for all your tomorrows. Learn more here:
So, how do you get started? You can learn how here:
Concerned about security? I am. Being a Registered Investment Advisor, *[ CERTIFIED FINANCIAL PLANNER®](http://en.wikipedia.org/wiki/Certified_Financial_Planner)* professional and an *Accredited Investment Fiduciary*®, security is critical to both my practice and my clients – and has been for more than thirty years. As you’ll see, the MyBlocks platform considers security important, too.
Ready? You can begin here or go to my [Getting Started page](https://indfin.com/getting-started/).
[Financial Goal Plan](https://www.moneyguidepro.com/fpa/Guests.aspx?gst=7D2BF5831D4A12A652761D84AD4ED7F849CD29F9040B5B8FD4949DA05352CA57&ent=49CAD448DD6351AE7DC397EE433CE623DE65DD57E4A18D65A70D8CA5968C29BC)You can get your journey started today!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement
**Tags:** Financial planning, retirement decisions, Retirement Planning, Retirement Strategy
---
### [Do Roth Conversions Make Sense if You're in a High Tax Bracket?](https://indfin.com/do-roth-conversions-make-sense-if-youre-in-a-high-tax-bracket/)
**Published:** September 5, 2023
**Author:** Jim Lorenzen
**Excerpt:** There are a lot of myths surrounding Roth conversions and this one might rank near the top, and you should know why. It’s important to have some historical perspective.
**Content:**
Do you think your tax bracket is too high for a Roth conversion? First, believe it or not, we are currently in one of the lowest tax regimes since the tax code was created back in 1913! Actually, from the mid-1940s until the mid 1960s, the top bracket was north of 80%! Our top tax bracket today is near historic lows – but, that will very likely change soon.
Our current national debt is over $31 trillion and with higher interest rates, carrying that debt becomes even more costly. Significant? You bet, because it’s individual income taxes that supply about 70% of the government’s revenue.
Second, the land mine ahead: the Tax Cut and Jobs Act of 2017 expires in 2025, which means the current top rate of 37% goes back to 39.6% – but, that’s just part of the story. Congress can easily raise taxes without changing the top bracket by simply assigning higher rates to lower income levels. In fact, that will happen to some people even with no changes.
Here’s how: a married couple making $160,000 is in the 22% bracket; but after the current law sunsets, that same couple will find themselves in the 28% tax bracket automatically – even if congress does nothing.
So, if you’re in the 37% bracket, don’t automatically dismiss a Roth conversion. In fact, any married couple making over $480,050 will likely find themselves moving from 35% to 39.6 overnight.
There’s more. As the years go by and your tax-deferred accounts grow, they will not only later move you into those higher tax brackets when the time comes to begin taking those required minimum distributions, but those may very well affect your Medicare premiums and even how much of your Social Security will be subject to income tax. What’s more: the Social Security tax regime is based on a calculation that was put in place back in 1986 and – wait for it – it wasn’t indexed for inflation. which means it will get easier and easier to move up those brackets. Of course, high earners are already there, but the dollar amounts will only increase.
Doing some tax planning for your retirement income is important, and it’s a good idea to start early. [You can learn more here.](https://vimeo.com/696150730/d5a8274b6a?share=copyncome/ "You can learn more here.")
The current tax law expiring isn’t the only tax trap. Did you it’s possible to be smack in the middle of the 22% tax bracket, yet taking an additional $1,000 in income could make that additional money taxable at 40%? It can happen to some taxpayers. In fact, there are other pitfalls many aren’t aware of, as well. Ever hear of the tax torpedo? [Check out the “Brain Teaser”](https://indfin.com/video-library/ "Check out the "Brain Teaser"") in my video library.
Talk to your tax advisor and talk to your financial planner. Don’t have a financial planner? Sign up for my newsletter – maybe I can help.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Roth Accounts Provide Many Advantages - But Congress Could Provide the Wild Card.](https://indfin.com/roth-accounts-provide-many-advantages-but-congress-could-provide-the-wild-card/)
**Published:** August 7, 2023
**Author:** Jim Lorenzen
**Excerpt:** But Congress Could Provide the Wild Card. Roth accounts can be attractive, especially when viewed through the lens of our national debt and the possibility (probability?) of higher taxes in the future to fund that debt.
**Content:**
Roth distributions may very well remain untaxable, but that doesn’t mean Congress couldn’t create reforms that would make these accounts less attractive, thus reducing their inflows.
Here are a couple of changes Congress could make:
(1) adding a required minimum distribution requirement, which would bring money back into taxable accounts, and/or
(2) including these distributions in measures of modified adjusted gross income or provisional income for determining other taxes such as on Social Security or triggering higher Medicare premiums.
The answer, if there is such a thing, might be prudent asset location.
Tax-deferred accounts should probably hold tax inefficient investments, which usually means lower returns, i.e. bond holdings. Tax-exempt accounts should likely hold tax-inefficient, higher return, investments, i.e., stocks and stock funds. Tax-efficient holdings may be best held taxable accounts.
Broad guidelines are good, but personalized advice is better. Talk with your advisor – or feel free to get in touch with me. See our [“Getting Started” page](https://indfin.com/getting-started/)!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Retirement, Roth conversions, Taxes
**Tags:** IRAs, Roth conversions, Roth IRA, taxes
---
### [The Intersection of Current Events, Banking Crises, and Financial Planning: Navigating Uncertainty with Prudence](https://indfin.com/bank-crisis-and-safe-money/)
**Published:** June 15, 2023
**Author:** Jim Lorenzen
**Excerpt:** It’s been said that the only constant is change and lately it’s been the banking crisis. Financial planning is often more about what we don’t know than what we do know. Lately, we’ve been through COVID, supply chain issues and (ongoing) issues with some of our country’s financial institutions.
**Content:**
So, what is the critical relationship between banking crises, current events, and financial planning. And what are the key considerations for individuals and businesses to navigate uncertainty and safeguard their financial well-being.
**Banking Crises: Causes and Consequences**
Obviously, the banking crises, characterized by financial distress and instability in the banking sector, can have far-reaching implications for individuals, businesses, and the overall economy. This particular problem seems to have been triggered by factors such as excessive risk-taking combined with weak regulatory oversight and further magnified by economic issues, including those within the financial system itself. The consequences of banking crises usually include credit crunches, liquidity constraints, loss of investor confidence, and economic recessions – and this time around was no different.
**Impact on Investment Portfolios and Asset Allocation**
During a banking crisis, financial markets often experience significant volatility and disruptions. Asset prices often plummet as investors flee to safety, liquidity may dry up, and credit availability may shrink. And it happened again this time around, too.
The typical line goes like this: when there’s a banking crisis, individuals and businesses need to reassess their investment portfolios and asset allocation strategies. Diversification becomes crucial to mitigate risk, as investments that seemed stable during normal market conditions may become highly vulnerable during a crisis. Financial planners, too, need to carefully analyze the impact of a banking crisis on different asset classes, such as equities, bonds, real estate, and commodities, to guide clients in making informed decisions and adjusting their investment strategies.
A lot of intelligent sounding guidance? Translation: react to the news and make changes in your long-term portfolio so you can be in the wrong allocation the next time you have to react to new news. Hey, that’s what keeps Wall Street ticking.
**Reevaluating Risk Tolerance and Emergency Funds**
One thing worth doing: reevaluate your risk tolerance. It’s easy to say you can accept risk when markets are going up. But, if you feel you have to adjust your portfolio (see ‘intelligent guidance’ above) because of short-term events, it’s proof your initial plan was flawed – and that’s often the result of a flawed initial risk assessment. It’s true crisis may necessitate a more conservative approach to investments, with a focus on preserving capital rather than pursuing higher returns. Additionally, building and maintaining an adequate emergency fund becomes even more critical during periods of banking crises. But, again, all of that should have been part of the initial plan.
I remember 2008-9 credit meltdown very well. What I remember most – and was most happy about – is that my phone never rang once. No one had to make adjustments in their portfolio because their initial plans had anticipated Murphy’s Law and ‘stress tests’ were run in advance to make sure their investments were in line with a well-designed risk assessment.
**Financial Advice is About More than Investments**
During my initial introductory call with clients, I make it clear what’s controllable and what isn’t. It’s been my experience – a little over thirty years now – that failure for many people is usually less about the investments they’ve chosen (though, sometimes that has been somewhat eye-opening – performance-chasing is a losers game) but more about their expectations and behavior if and when those expectations turned out to be unrealistic. That’s why the understanding of what’s controllable and what isn’t is so important.
**Social Security is an Asset Class**
Few people recognize the true value of their Social Security checks. Where else can you get an income for life with cost-of-living increases? There are some annuity products that provide COLAs, but I haven’t found any outside the variable type and those come with a lot of moving parts and some other issues that are outside the scope of this post. Back to our Social Security check….
If you expect your Social Security benefit to be $3,000 monthly, for example, that $36,000 annual benefit is more valuable than you might think. How much additional money would you have to have invested in your retirement portfolio to provide that $36,000 annual benefit with cost of living increases – for life?
Most planners would probably tell you – and they might be right – that it would take somewhere between $900,000 and $1,200,000 in additional investment money to provide the same benefit (between 3%-4% of assets as a withdrawal rate). There are, of course, a number of factors that can affect that number, but you get the idea. That’s why making the decision about when you claim can be very important. [You can learn more about that here](https://indfin.com/what-baby-boomers-need-to-know-about-social-security-in-2023/).
If I can be of help to you, [let me know](https://indfin.com/getting-started/)!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Economy, Inflation
**Tags:** Banking Crisis, Financial planning, financial risk, Inflation, Investment Strategy, Safe Money
---
### [Which is Better: An IUL or a Roth IRA? ](https://indfin.com/iulorroth/)
**Published:** June 6, 2023
**Author:** Jim Lorenzen
**Excerpt:** When it comes to building a solid financial future, finding the right investment vehicle can be a daunting task. Comparisons are often made between an IUL (Indexed Universal Life Insurance) and a Roth IRA (Individual Retirement Account) as a choice between getting life insurance or investing in the stock market. While an IUL can give the appearance of doing both; however that’s not really the case – and, often, this can lead to unrealistic expectations.
**Content:**
But, is it a real either/or decision? Let’s review each.
**Features and Benefits**:
**The IUL**, a hybrid product that combines life insurance with an investment component – or so it seems. In fact, it’s returns come in the form of credits to cash value paid by the insurance company – the size of which can vary from year to year. How much the insurance company credits is usually tied to the performance of some outside index and comes with limitations to the upside, called a ‘cap’, and, in many cases, protection against loss on the downside, called a ‘floor’. So, typically, an IUL offers the potential for tax-deferred growth up to the cap and limits loss often to 0. There’s also a death benefit, which is generally tax-free.
**The Roth IRA** comes with a straightforward approach: You contribute after-tax dollars, and your investment grows tax-free. It offers flexibility, allowing you to withdraw your contributions at any time after five years without penalty (there are holding requirements and earnings may be subject to taxes and penalties if withdrawn before age 59½). So, no limits on the upside – but also the same holds true for the downside and any ‘death benefit’ is simply whatever’s left in the account. They have some limitations, too. You can’t contribute if your income is too high. For example, someone filing single on their taxes must earn less than $153,000 in 2023 to contribute to an IRA, while married joint filers lose the ability with an income of $228,000.
There’s more: both traditional and Roth IRAs have annual contribution limits if you have $6,500 or $7,500 per year to invest. As a result, you must put money into another account type if you have more than $6,500 or $7,500 per year to invest.
**Performance and Returns:**
Many IUL marketers claim the IUL will provide the best of both worlds: the potential for market gains and a safety net during market downturns. This isn’t really a realistic depiction, though. The reason is simple. IUL premiums, after the cost of insurance, are typically invested by the insurance company in government treasury bonds and other safe investments, with a small portion used to purchase options on the stock market. This combination, along with risk pooling, allows the insurance company to protect policyholders against loss. The trade-off for the safety is the cap on gains. As a result, I tell clients that their long-term return will likely be closer to those of intermediate bonds, and you’ll have a tax-free death benefit for your heirs. [I’ve written about tax planning before](https://indfin.com/tax-planning/).
On the other hand, the Roth IRA is really a ‘drawer’ in which investments are held, so you have wider flexibility. The return realized depends on the investments held inside. If the investment is, for example, an index fund, you’ll receive whatever returns the index fund generates. No cap. No floor. At death, heirs get what’s left.
**Flexibility and Access:**
For the IUL, this can vary from company to company – and depends on the policy design. There are some designs that provide for early cash build-up with more available liquidity than many people need. Other designs place more emphasis on legacy build-up (for heirs). Liquidity is usually achieved by withdrawals (up to the deposit level) then through policy loans, which are also tax free. Money can be withdrawn for any reason and there’s no legislative holding requirement and no age 59-1/2 penalty issue. Different companies have different designs and limitations. It’s wise to have an independent professional guide help you with this.
The Roth IRA allows you to withdraw your contributions without penalty as long as the account holder has held the account for five years and has turned 59-1/2.. It’s like having a genie in a bottle, granting your financial wishes whenever you need them. Just be cautious not to abuse this power, or your retirement dreams might vanish as quickly as the genie itself.
**It’s Not Either/Or**
Here’s something to consider: for the long-term investor with a sizable bond allocation, an IUL can make sense for a portion of these long term assets. In terms of funding order, it might make sense to (1) fund retirement accounts up to the maximum allowable amount, then (2) fund an IUL for late-life income (with an added legacy benefit). The IUL portion of the portfolio could be considered part of the long-term bond allocation of the portfolio. [Here’s more information for making your money last](https://indfin.com/how-to-make-your-retirement-money-last/).
**Conclusion:**
Is this right for you? Maybe. Maybe not. You wouldn’t build a house without a blueprint; your financial house should be no different.
You might want to sit down with a CFP® professional to develop a plan. Decisions in one area can affect others. Coordination is critical for avoiding expensive mistakes, like [decisions involving Social Security](https://indfin.com/what-baby-boomers-need-to-know-about-social-security-in-2023/), for example.
I hope this has opened the door for you to begin asking questions and doing your homework.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, IRAs, Life Insurance, Retirement, Retirement Income, Roth conversions, Taxes
**Tags:** IRAs, life insurance decsions, retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy, Retirement tax strategies, Roth IRA
---
### [How Long Will Your Retirement Money Last?](https://indfin.com/makingmymoneylast/)
**Published:** October 21, 2021
**Author:** Jim Lorenzen
**Excerpt:** Longevity risk is real. Accumulating assets for retirement was a lot easier than managing retirement income. Now you practically have to be an actuary to make sure your money doesn't run out before you do!
**Content:**
During your working career, you simply put money into your retirement account and watched the market climb for two to three decades (not in a straight line, of course; but, it still went up over time).
The accumulation phase was a lot easier than the distribution phase. In retirement you’re drawing down assets – and doing it during two or three decades of inflation and tax-law changes, not to mention those untimely market declines that always seem to take place just when you need your money the most!
**Do you remember 1966?**
There was no recession or depression. No dot-com bust or credit melt-down; no market crash. It was a pretty unremarkable year except – it was a bad year to retire.
No one want to see their retirement plans go ‘off the road’ – especially when already in retirement. Maybe installing some ‘guardrails’ might help.
I’m doing a short webinar on how you can adopt a “Guardrails” strategy for your own retirement. I think you’ll find it helpful.
You can [see it here!](https://vimeo.com/635459466/282eb2c845)
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Retirement, Rollovers
**Tags:** Investment Strategy, making money last, managing retirement savings, managing risk, Retirement Income, Retirement Planning, Retirement Strategy
---
### [A Tax Trap That Catches Many By Surprise](https://indfin.com/tax-planning/)
**Published:** April 17, 2023
**Author:** Jim Lorenzen
**Excerpt:** Tax planning through retirement is important; and failing to do it through all four stages of retirement can prove costly because some of the tax traps are permanent. Here’s an example:
**Content:**
Bill is single and retired with a taxable income of $46,138, which puts him right in the middle of the 22% tax bracket. His income includes $38,000 from his IRA plus $37,500 from Social Security. He decides he’d like to take a trip and withdraws an additional $1,000 from his IRA.
How much will Bill owe in federal taxes on that extra $1,000? You’d think it would be $220 since he’s in the 22% tax bracket, right?
Nope. Bill will owe $407 in tax – a 40.7% federal tax rate – on that income.
What?
Why? That’s just one tax trap. There are a few others, but it’s just one example of why it’s important to do tax planning through all four stages of retirement. And, it’s important to do your homework.
I’ve created an on-demand video that will take you through it. So, grab some coffee and get ready to arm yourself with some information that could save you tens of thousands of dollars. [You can see it here.](https://vimeo.com/jimlorenzen/taxplanniingforretirement2023)
Enjoy!

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Retirement Income, Taxes
---
### [What Baby Boomers Need to Know About Social Security in 2023!](https://indfin.com/what-baby-boomers-need-to-know-about-social-security-in-2023/)
**Published:** April 11, 2023
**Author:** Jim Lorenzen
**Excerpt:** Social Security claiming decisions aren't as simple as they may appear. The decisions you make for yourself can impact your spouse, your future taxes, and even the bite Medicare premiums take from your Social Security benefits.
**Content:**
Did you know that one couple could have up to 18,000 ways to claim? And, most decisions are irreversible after 12 months. And, there’s more at stake than individual benefits!
Is Social Security *really* going bankrupt? Will it be there for you when you need it? What is the outlook for Social Security? What factors should you consider when you claim?
Are you really penalized for working when you receive Social Security? The answer may surprise you!
Do you know what *provisional income* is… and how it affects your tax bill in retirement?
Ready to do some homework BEFORE you make your decisions? You’re in the right place! I’ve created an on-demand webinar, *[What Baby Boomers Need to Know About Their Retirement Income](https://vimeo.com/jimlorenzen/socialsecurity2023)*. It’s all about Social Security and the changes for 2023.
Invest an hour now; it may be one of the best investments you’ve made.
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Social Security
**Tags:** retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy, retirement webinar, social security, social security claiming, social security help, social security outlook, when to claim social security
---
### [SECURE Act 2.0 and How Tax Law Changes Might Change Your Plans.](https://indfin.com/secure-act-2-0-and-how-tax-law-changes-might-change-your-plans/)
**Published:** March 31, 2023
**Author:** Jim Lorenzen
**Excerpt:** The SECURE Act includes roughly 100 new rules for retirement affecting both individuals and businesses - all with tax implications and various effective dates. These are the most expansive changes to retirement rules in 40 years.
**Content:**
Obviously, current financial plans need to be reviewed for these changes to see how these new rules affect family outcomes in a shifting tax landscape. There are 4 keys to understanding SECURE Act 2.0. You can [learn about those keys in my 30-minute video](https://vimeo.com/812870514/251d75cc8b). Grab some coffee!

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Retirement, SECURE Act, Taxes
**Tags:** retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy, SECURE Act, taxes
---
### [Should You Take Social Security Early and Continue to Grow your IRA?](https://indfin.com/should-you-take-social-security-early-and-continue-to-grow-your-ira/)
**Published:** March 20, 2023
**Author:** Jim Lorenzen
**Excerpt:** Many people believe they should take Social Security early in order to keep from drawing down IRA assets, believing that the longer they can grow the IRA tax-deferred, the better off they’ll be.
Are they wrong? Maybe. Maybe not. Different people are in different circumstances.
**Content:**
Should you claim Social Security early?
Let’s start with health. Generally – and that is the operative word – the longer someone lives, the better off they’ll be drawing down their IRA leaving their Social Security in order to max out benefits. Not only do Social Security benefits increase significantly by delaying – and they’ll still get the cost-of-living adjustments, too – but, by drawing down IRA assets first, later required minimum distributions (RMDs) will be lower. It’s worth remembering RMDs are recognized as taxable income which is one factor in the calculation of any taxes on total income, Social Security, as well as impacting Medicare Part B premiums.
Each person should have a Social Security analysis created as part of a comprehensive financial plan. As you can see, there are a number of moving parts and each can impact other issues.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Social Security
**Tags:** social security, social security claiming, when to claim social security
---
### [What's New for Social Security in 2023?](https://indfin.com/whats-new-for-social-security-in-2023/)
**Published:** March 16, 2023
**Author:** Jim Lorenzen
**Excerpt:** There have been some changes to Social Security this year.
**Content:**
Grab some coffee and see what they are in this short 30-minute webinar. [You can get to it here. ](https://indfin.com/socialsecurity/)
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Social Security
**Tags:** social security, social security outlook, when to claim social security
---
### [What People Get Wrong About Retirement Rollovers](https://indfin.com/rollovermistakes-2/)
**Published:** February 27, 2023
**Author:** Jim Lorenzen
**Excerpt:** Here’s what people get wrong when making rollover decisions.
**Content:**
Most people think the rollover decision is simple – an easy ‘should I or shouldn’t I’ decision. The decision isn’t as simple as many believe due more to bias than fact – and it can be costly because they could have up to SIX different options available! Too bad few realize this.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Retirement, Rollovers
**Tags:** 401(k) rollovers, IRA rollover, retirement decisions, Retirement Planning, Retirement Strategy, rollover mistakes
---
### [Retirees' Biggest Decision? It's Still When to Claim Social Security.](https://indfin.com/retirees-biggest-decision-its-still-when-to-claim-social-security/)
**Published:** February 15, 2023
**Author:** Jim Lorenzen
**Excerpt:** Too many seniors still take the Social Security claiming decision too lightly – it’s a mistake that can cost them tens, if not hundreds, of thousands of dollars of retirement income during their lifetimes. And, often, the decision is made based on false bias or assumptions rather than a solid planning strategy.
**Content:**
Many will want to claim their Social Security benefits early this year simply because they want to claim the high cost-of-living (COLA) adjustment. The reality: they don’t have to claim early to get the benefit of this, or any other year’s, benefit. Social Security applies all annual COLAs by simply accumulation between the ages of 63 and 70 for those waiting to claim, so the adjustment is already built-in to the formula.
There may be legitimate financial reasons for some people to claim early – but, when you build your financial house, it’s good to have a blueprint first. Houses built without blueprints generally don’t turn out too well. It’s all about optimizing your claiming strategy; unfortunately, few Americans are making optimized decisions. ([There’s a lot to know about claiming strategies; learn more here](https://vimeo.com/jimlorenzen/boomers).)
The National Bureau of Economic Research (NBER) study in 2022 found that virtually all American workers ages 45-62 should wait beyond 65 to begin collecting Social Security and more than 9 out of 10 should wait until age 70, yet just 10.2% of Americans seem to do so. The median loss for this age group in the present value of household lifetime discretionary spending is in excess of $180,000.
Those with health issues or little faith in Social Security solvency – a major driver of claiming mistakes – may be convinced they should claim early, even where there might be a younger and healthier spouse who would benefit by delaying. Others may have an emotional fear of spending down their retirement savings before Social Security kicks in. Few of these people, however, have seen the math or considered the consequences of their decision.
The present value calculations indicate that getting the claiming decision right can add the equivalent of a six-figure windfall to the retiree’s balance sheet.
One size does not fit all. That’s why plans have to be individual, not boiler plate. It pays – literally – to get your ducks lined up before making decisions. [Learn more about Social Security claiming here.](https://vimeo.com/jimlorenzen/boomers)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Social Security
**Tags:** retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy, social security claiming, when to claim social security
---
### [Does SECURE Act 2.0 Create a Stealth Tax?](https://indfin.com/secure-act-stealth-tax/)
**Published:** January 23, 2023
**Author:** Jim Lorenzen
**Excerpt:** The SECURE Act 2.0 may do a lot to help secure Uncle Sam, but I’m not so sure about the rest of us.
**Content:**
President Joe Biden signed legislation last month that pushes the age retirees must start taking required minimum distributions (RMDs) from IRAs, 401(k)s, and 403(b) plans, to 73 this year (up from 72). And, the age will actually bump up even higher to age 75 in 2033. Does that make you feel more secure?
People typically like the idea of putting off RMDs to get tax-deferred growth as long as possible. But, maybe that’s what the green eye shades in Washington want you to believe.
Putting off the time you begin withdrawals may NOT be so good. The more you delay the retirement age, the greater your RMD will likely have to be. You see, your RMD is calculated by dividing your tax-deferred retirement account balance as of December 31st of the preceding year by a life expectancy factor that corresponds to your age in the IRS Uniform Lifetime Table.
Put simply, as your life expectancy goes down, the percentage of assets that must be withdrawn goes up.
Higher RMDs later just might force you into a higher tax bracket – don’t forget, current tax brackets sunset in 2025, so tax brackets will be higher in just three years even if Congress does nothing.
More stealth? If you have higher taxable income, it may affect the taxation of your Social Security benefits, as well as your Medicare premiums for Part B (based on modified adjusted gross income) – even without the current tax law expiring.
There are many people who don’t need the money think they’re saving something by putting off RMDs as long as possible; but, they may end up paying more – in more than one way.
Oh, yes, your heirs may take a hit, too. The new SECURE Act 2.0 requires that most non-spouse beneficiaries to empty out their inherited IRAs within ten years… which may be when they’re in their highest earning years anyway.
The SECURE Act 2.0 may do a lot to help secure Uncle Sam, but I’m not so sure about the rest of us. Roth conversions – paying taxes now while they’re on sale – may be worth considering more now than ever.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Roth conversions, SECURE Act, Taxes
**Tags:** Retirement Income, retirement mistakes, Retirement Strategy, Retirement tax strategies, SECURE Act, tax hikes, Tax reduction, Taxes in retirement
---
### [IRAs With Excess Assets Impact Family Members Too!](https://indfin.com/iras-with-excess-assets-impact-family-members-too/)
**Published:** January 9, 2023
**Author:** Jim Lorenzen
**Excerpt:** After passage of the SECURE Act of 2019, non-spouse IRA beneficiaries are now required to liquidate their inherited IRAs by the end of the 10th year. Often, that means they’ll be withdrawing taxable income from the inherited IRAs during their peak earning years – great gift for Uncle Sam, but not so good for the kids.
**Content:**
How about a spouse who inherits the IRA. No ten-year rule, but there are still required RMDs. Not so bad? Think again: the surviving spouse is now a single return filer – not joint – and guess what that does: it halves the available deductions and tax brackets. Maybe the only one more ‘secure’ is Uncle Sam.
You [can learn more about the SECURE Act ](https://vimeo.com/jimlorenzen/secureact) in my video.
What can you do? Start your income planning before you need to withdraw income.
One possible strategy is to think about accelerating your IRA withdrawals when taxable income is generally reduced early in retirement. It would be taxable income, but maybe better now than later (talk with your advisor). This may also allow you to defer Social Security benefits to age 70 to maximize them. A series of Roth conversions would allow the money to grow tax-free, too!
How about beneficiary planning? Maybe you don’t want to simply divide all accounts evenly. Again, why include Uncle Sam among your heirs? You may, for example, give the child with the lower taxable income the IRA, while giving the higher tax child your other taxable accounts or Roth IRAs.
You’ve been accumulating for years – that strategy was easy: keep saving and socking it away. The decumulation phase requires a more sophisticated planning strategy – unless you really like Uncle Sam and want to make him a favored beneficiary.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues, Inheritance, IRAs, Planning, Retirement, SECURE Act
**Tags:** Financial planning, retirement decisions, Retirement Planning, Retirement Strategy
---
### [ESG Investing: Really Worthwhile or Just Another Wall Street Gimmick?](https://indfin.com/esg-investing-really-worthwhile-or-just-another-wall-street-gimmick/)
**Published:** November 27, 2022
**Author:** Jim Lorenzen
**Excerpt:** The value of ESG – or even what it is – hasn’t been defined. So, it depends on who you ask, how the law is interpreted, and apparently, who’s doing the packaging. Oh, yes, it also depends on how you quantify it.
**Content:**
According to a Bloomberg report appearing in the November 22 issue of Wealth Management, Goldman Sachs settled a $4 million case with the SEC over Goldman’s ESG research process used to select and monitor securities. Apparently the SEC felt they weren’t properly weighing environmental, social, and governance factors in some of it’s investment products.
The Department of Labor recently announced a new ruling that reverses prior regulations approved under the former Trump administration. In late 2020, the DOL required retirement plan managers to make investment policy on solely on “pecuniary factors”. The final version adds a provision that fiduciaries do not violate their duty of loyalty ‘solely because they take participants’ preferences into account’ when constructing investment plans. The new rule eliminates the ‘pecuniary’ terminology and permits fiduciaries to factor ESG and the economic effects of climate change into the risk and return analysis.
Wall Street, of course, had opposed the old rule and like the new one – they get to create and market new products to the public. The final rule, according to Brian Graff, chief executive of the American Retirement Association, makes it clear that ESG factors do not have to be considered; but that they “may” be considered if they’re considered to be relevant as part of a principles-based fiduciary analysis.
But how?
A November 2nd Forbes article*, Is ESG Really a Sham*, notes that while many of the ESG funds that retail investors expect to be green are really far from it. One problem, he notes, is that so many investors are so focused on low-cost indexing that they have no choice but to include the Coca-Colas and Metas of the world. Retail investors often want solutions-based, positive impact portfolios. To them, an ESG index that has exposure to oil companies is less bad and a portfolio that eliminates oil entirely is better; but one that replaces oil with solar is the best – it’s what they want.
But, ESG indexes typically have minimal exposure to such solutions-based investments as clean energy, green transportation, sustainable real estate, and all the rest. But, the ESG acronym does sell well.
One problem, according to Marc Shoffman of Financial Advisor IQ, is that there are no standardized rules in the U.S. governing what constitutes an ESG fund. ESG is simply not well defined. That’s one of the reasons it has become a political football, as well. Florida and Texas, for example, have banned the use of ESG by state pension funds.
As Pete Krull at Forbes states, retail investors need to understand the difference between ESG investing and sustainable investing. There’s a big difference. I might add that investment outcomes just might be very different, as well.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Retirement
**Tags:** investment returns, Investment Strategy, retirement decisions
---
### [Looking for a Riskless Alternative to Risky Investments?](https://indfin.com/alternative2risk/)
**Published:** November 14, 2022
**Author:** Jim Lorenzen
**Excerpt:** How about an asset class that doesn’t have the risks of stocks or bonds? One that can provide stability and peace of mind.
**Content:**
What if you could even access earnings or growth without income tax consequences? Sound good?
It should. Too good to be true? Nope.
It’s probably the last asset people ever think of (you included?), yet one used to great effect by many of America’s wealthiest families. And, it has a hidden benefit most people never think about.
Give up? Life insurance. WHAT?
It’s been my experience that no one wants to buy life insurance; but the ones who have it love what it does – and they later find they’re glad they have it. And, I’m not talking about the death benefit, which everyone knows about.
Permanent insurance has something temporary insurance doesn’t have: cash value build-up. Retirees who were forward thinking enough to have an advisor create a long-term strategy for them are now finding out how handy it is.
Why? Because when markets go through their down cycles, as they do from time to time – like now, retirees with permanent insurance policies are generally able to access their cash value for tax-free income (yes, tax-free) during the downturn, leaving their retirement assets invested to ride out the downturn and in-place for the recovery. No one likes to draw down money when markets are down.
Pretty good, huh?

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Life Insurance, Planning, Retirement, Taxes
---
### [Did You Know the Government Subsidizes Market Losses in Traditional IRA and 401K accounts?](https://indfin.com/did-you-know-the-government-subsidizes-market-losses-in-traditional-ira-and-401k-accounts/)
**Published:** October 28, 2022
**Author:** Jim Lorenzen
**Excerpt:** True! Market losses aren't all yours. The IRS subsidizes part of them.
**Content:**
I guess I always knew it, but I sure wasn’t thinking about the real effects of market losses before reading a trade publication article by Allan Roth.
For example, suppose your statement showed you have $100,000 in an IRA at the beginning of the year and you’re in the 25% tax bracket. What the statement isn’t telling you is that $25,000 of that money doesn’t belong to you. Your real balance is $75,000.
Now suppose your account took a 20% market loss in value. Your balance is now $80,000, but did YOU lose $20,000? Nope. Your balance, because of your 25% tax bracket, is now $60,000, because the I.R.S. owns it’s 25%, or $20,000.
So, while your statement shows a drop of $20,000 from $100,000 to $80,000, the fact is your loss was $15,000 – a drop from $75,000 to $60,000. The other $5,000 is the government’s loss.
But, of course, it’s all on paper. Losses don’t really get realized until they’re, well, realized… only when you sell. And, historically, markets have always seemed to come back to reach new highs. We don’t know when it will happen again; but, I wouldn’t bet against it.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, IRAs, Retirement, Taxes
---
### [Planning for Retirement? Here are a few tips!](https://indfin.com/planning-for-retirement/)
**Published:** September 29, 2022
**Author:** Jim Lorenzen
**Excerpt:** For some people, planning for retirement can feel like trying to eat an elephant; but, it doesn't have to be that way. Before making big decisions, it's always important to get the ducks lined-up first.
**Content:**
Retirement planning is like building a house. You don’t want to order out all your materials until you have a blueprint. And, you don’t begin the blueprint until you have a vision (artist’s rendering) of what you want the finished product to look like.
And, of course, there’s the budget.
What do you want your retirement to look like? What will it take to do it? How close are you to realizing that goal? And, how did you arrive at that conclusion?
Tough questions, yes. But, as someone once said to me: if you think education is expensive, try ignorance.
Okay, here are some tips:
1. **Talk with your financial advisor.** Your financial advisor has been through this many times before. You haven’t been through it yet. Experience and education do make a difference. The biggest concern is finding a good one. These days it seems everyone is calling him/herself a financial planner. Check credentials and experience. Are they truly independent planners or simply disguised brokers? [Check the CFP Board’s website!](https://www.letsmakeaplan.org/?gclid=EAIaIQobChMIrvKJkba6-gIVZciUCR0NPQ1OEAAYASAAEgKG1fD_BwE&gclsrc=aw.ds) Remember, too, you want to find a planner that best fits your needs. It’s not like finding someone you’ll see once every five years; it’s almost a marriage. A good advisor will be screening you, too.
2. **Make your Social Security decision**. This isn’t done in a vacuum. This is an integral component of your total financial plan; and, because these benefits can be taxable, how other assets are arranged can affect the degree to which these benefits are taxed, or not at all. There are a lot of myths surrounding claiming options. Don’t be too quick to choose an option simply because someone you know made a (possibly bad) decision.
3. **Review how your current assets are arranged now.** Has your current arrangement been ‘stress-tested’ for a down market? Or, is the market doing it for you for the first time now? Think about this: An asset that drops from 100 to 80 has experienced a 20% loss; but, for that asset to get back from 80 to 100 requires a 25% gain…. just to get back to even. You don’t want to be drawing down on retirement money when markets turn against you. Murphy’s Law does happen.
4. **How much income will you need in retirement?** Don’t forget inflation (how can we?) and tax law changes (inevitable). Have you ever created a projection and done a probability analysis (inflation, taxes, and markets never seem to move in a straight line).
5. **Planning a major purchase?** When should you do it – now or later? How will that purchase impact your lifestyle years from now if that same money had been redeployed? Maybe not at all… or, it might be regrettable later. Did you plan before or after you took action?
6. **Medicare decisions:** Did you get your advice from Joe Namath or did you make a deep dive to find out where the money comes from to pay for all those ‘free’ benefits? Do you know when your enrollment period is?
7. **Are your assets properly placed and titled?** Are your beneficiaries updated? Did you name a grandchild for your IRA in a will but name your spouse in the IRA document? It will go to your spouse. Do your will and trust contradict each other?
8. **Do you have updated estate documents?** If you have moved to another state, you probably should have everything updated. Do you have a designated general power of attorney, a healthcare power of attorney, etc.
9. **Do you have a trust?** A will is a public document that can be contested and takes affect only after your death. There are many kinds of trusts and may help saving taxes or simply help you maintain control. While living trusts generally don’t save on taxes, but they can be simple to set up and they do save a lot of headaches for your heirs by avoiding probate.
10. **Do you have all your documents in one place?** Is it fireproof, earthquake proof, flood proof? You might consider digitizing them and storing them in an independent, secure, vault. Documents such as employer plans, health savings accounts, medical plans, etc., that may become harder to obtain once you leave your company.
These are just a few tips. Talk with your advisor. Don’t have one? Gee, I wonder who you could get…..
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Estate, Inflation, Investing, IRAs, Planning, Retirement, Social Security
**Tags:** Financial planning, managing risk, retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy
---
### [Customer Service is a Problem at Social Security](https://indfin.com/social-security-customer-service-problems/)
**Published:** August 22, 2022
**Author:** Jim Lorenzen
**Excerpt:** Have you tried to call Social Security lately? If so, this won’t come as much of a surprise – customer service is all but non-existent.
**Content:**
Social Security pays out about $1 trillion in annual benefits to beneficiaries; but those who need help typically find that the telephone system doesn’t work – often even disconnecting people after 15 minutes on hold. Some people spend hours on hold without anyone ever picking up!
This isn’t new. The problem has been growing. Social Security has acquired 21% more beneficiaries since 2010 – a rise from 54 million to 65 million, according to Alison Weir, a staff attorney and policy advocate at Greater Hartford Legal Aid in New Haven, Connecticut who spoke at a hearing of the U.S. House of Representatives’ Ways and Means Committee on May 17th. What’s more, approximately 10,000 baby boomers become eligible for retirement benefits every day.
According to Weir, between 2008 and 2021, more than 100,000 people died while awaiting decisions on disability benefits.
Ingrid Case, writing for *Financial Planning*, notes that Social Security now has 60,000 workers – it’s lowest staff level in 25 years. Part of the reason is the closing of 67 field offices during the pandemic. Nearly all are open again; however only about half of the workforce is physically present.
Typical of government, of course, it’s hard to fire poor performers – that can require years of documentation. That’s compounded by hiring freezes and limited budgets.
There is proposed legislation to address many of these issues, according to Case; however, a budget watchdog group dropped its support, so that may not be going anywhere until the group feels the proposed fixes get more serious.
Does this mean Social Security will be going broke? Not likely. But, [that’s another story](https://indfin.com/social-security-trustee-report/).
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Social Security
**Tags:** social security, social security outlook
---
### [Annual Social Security Trustee Report Urges Reform](https://indfin.com/social-security-trustee-report/)
**Published:** June 14, 2022
**Author:** Jim Lorenzen
**Excerpt:** The annual Social Security trustees' report is to advise Congress on the financial condition of the Social Security system over the next 75 years. If they project that 100% of benefits will be paid, it's said to be in balance and no action will be needed. If they project a shortfall, they call on Congress to fix the problem by either raising taxes, cutting benefits, or some combination of the two.
**Content:**
Don’t expect much help from Capitol Hill.
T[he annual Social Security trustees’ report](https://www.ssa.gov/OACT/TR/2022/) is to advise Congress on the financial condition of the Social Security system over the next 75 years. If they project that 100% of benefits will be paid, it’s said to be in balance and no action will be needed. If they project a shortfall, they [call on Congress to fix the problem](https://www.ssa.gov/OACT/solvency/provisions/index.html) by either raising taxes, cutting benefits, or some combination of the two.
Congress, of course, is in an election year. Democrats, right now, have the [only proposal on the table](https://larson.house.gov/issues/social-security-2100-sacred-trust), although it doesn’t address solvency of the system, knowing full well – it’s an election year – they can beat a drum knowing it won’t pass without Republican votes; and Republicans, in an election year, are silent on the issue. Any solution is bound to hurt someone and everyone on Capitol Hill wants votes in November.
The time between now and projected insolvency is thirteen years – that’s six congressional terms and two senate terms. Most in power now know they won’t be facing voters then.
The last major reform was in 1983 when brackets were created for the taxation of Social Security benefits. Those brackets weren’t indexed for inflation; so, with inflation increasing, tax revenue from this source is increasing as well, giving Congress another reason to kick the can.
But, don’t let the solvency issue change your claiming timing. You might be tempted to claim early because you think the system is going broke; but, think again. Even if you believe you’ll see a 20% benefit cut and you think you can capture it by claiming ahead of time, remember that 80% of a higher benefit is more than 80% of a lower benefit realized because it was tempting to ‘game’ the system.
Any strategy, of course, should be determined after a careful analysis that takes many other factors into account. Talk to an advisor. Don’t have one? Hmmmm.[ I wonder who you could get…..](https://indfin.com/your-advisor-jim-lorenzen-cfp-aif/)
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Social Security, Taxes
**Tags:** social security, social security claiming, social security help, when to claim social security
---
### [SECURE Act 2.0: RMD Age Hikes Coming?](https://indfin.com/secure-act-and-rmd-age-hikes/)
**Published:** August 8, 2022
**Author:** Jim Lorenzen
**Excerpt:** RMD age hikes may not be the blessing you think. The question just might be who is more secure? Retirees or future government spending?
**Content:**
As you may already know, the House of Representatives recently passed the SECURE Act 2.0. And, the RMD changes will be good news for late retirees.
The SECURE Act passed in 2019 (Securing a Strong Retirement Act) is expanded under the “2.0” bill, which I’ve talked about before (see and ), in a number of areas. Of particular interest to late and wealthy retirees will be the required minimum distribution (RMD) hikes. How?
SECURE Act 2.0 raises the RMD beginning dates. Tax-advantaged retirement accounts (think 401(k)s, traditional IRAs and the like, come with a rule called required minimum distributions – the amount of money that must be withdrawn from the account each year – and that rule also tells the account owner when distributions MUST begin.
The first SECURE Act raised the age from 70-1/2 to 72. The newest version will raise the age from 72 to 75. Note: Roth IRAs do not have required beginning dates because there is no RMD requirement. Taxes on that money was paid before money entered the account, so that money grows tax-free.
For workers who choose to retire later or those retirees who choose to delay withdrawals, the increased RMD could – repeat, COULD – be a significant advantage.
Some critics have even argued that this increase in the age limit advantages the wealthy because they can afford to wait. They also argue that this would cost the government significantly because of all those uncollected taxes.
My own opinion is just the opposite. The only thing really being secured is the government’s future revenue stream. Retirees may be on the wrong side of a shell game.
Follow.
- The government is faced with a huge debt – no news there.
- Faced with this debt, the government needs to raise revenue.
- Debt incurred during periods of low inflation is more easily paid back with cheaper dollars during periods of high inflation.
- A combination of higher taxes and inflation virtually compounds the government’s ability to raise money.
- By delaying RMDs three more years, the annual payouts will be increased, and, my guess…
- Tax rates will be higher. Even without new legislation, the current tax law sunsets in 2025, meaning tax rates go back to the Obama-era tax laws.
- Higher tax rates combined with higher payouts just may force many into higher tax brackets.
Is it any wonder why Roth conversions are becoming so popular?
The Senate is expected to pass a comparable version. When that happens, the two bills will go to reconciliation before being returned to the respective houses for final passage.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IFG Viewpoint & Outlook, Inflation, Retirement, Roth conversions, SECURE Act, Taxes
**Tags:** Financial planning, retirement decisions, Retirement Planning, Retirement Strategy, RMDs, SECURE Act, taxes
---
### [Two Interesting Investment Strategies - But No Free Lunch.](https://indfin.com/investment-stratey/)
**Published:** June 20, 2022
**Author:** Jim Lorenzen
**Excerpt:** No investment strategy is without some kind of risk; but, I think this comes close. Take a look:
**Content:**
According to Annuity.org, a typical rate for a 10-year annuity right now is about 3.7%. That means, if you were to put $100,000 into this hypothetical annuity, you’d end up with $143,809 in ten years.
According to ycharts.com the 10-year U.S. Treasury note currently yields 3.25%. That’s not as much as the annuity, so your $100,000 investment wouldn’t do quite as well. But, what if you’d be happy with taking a risk that you wouldn’t gain as much as long as you wouldn’t lose anything? At 3.25%, you could deposit $72,627 into our hypothetical treasury note and it would be guaranteed to grow to $100,000, thus guaranteeing your principal. Since you deposited only $72,627, you have $27,373 left to invest in stocks for a 10-year period.
If your stocks averaged 8% (below the historic long-term average annual growth rate of 10%), your stocks would grow to $59,096, giving you a total return of 4.75% on your combined $100,000 investment. If your stocks grew by 9%, they would end up at $64,801, giving you a combined return of 5.10%.
So, you can have a guarantee of $143,809 in ten years with an annuity; or you can take door #2 that guarantees you against loss, but could provide you with an unknown gain.
Both are taxable at the end, though stocks are more likely to enjoy some capital gains treatment when sold. And, both strategies must battle inflation.
No free lunch.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Annuities, Investing
**Tags:** investment returns, Investment Strategy, managing risk, Reducing Risk
---
### [A SECURE Act Defense Strategy](https://indfin.com/a-secure-act-defense-strategy/)
**Published:** June 6, 2022
**Author:** Jim Lorenzen
**Excerpt:** Congress labeled it the SECURE Act, because it’s a better sell to the public. But, what Uncle Sam really wanted to do was make their spending programs more secure – hence, securing reelection.
**Content:**
For some background on the SECURE Act, you can learn more about it from [my webinar](https://event.webinarjam.com/register/6/mgll9fk). It’s most important impact was the elimination of the stretch IRA.
By eliminating the stretch IRA and requiring distribution of inherited IRAs to most non-spouse beneficiaries within a ten-year period ([my webinar has more on this aspect](https://event.webinarjam.com/register/6/mgll9fk)), the government can get their hands on your beneficiaries’ money sooner.
What does all this mean? Frankly, it raises the point that traditional IRAs and other tax-deferred retirement plans may no longer be the best option for leaving funds to beneficiaries.
IRA guru Ed Slott, a CPA and frequent PBS contributor, says many people should consider replacing their IRAs (a poor estate planning asset) with life insurance (an excellent estate-planning asset that has become even more valuable), since the single biggest benefit in the tax code is the income tax exemption for life insurance. He calls life insurance the best, most cost effective yet amazingly underutilized strategy for protecting large retirement account balances.
No wonder. It’s not subject to any post-death SECURE Act limitations; proceeds generally flow income tax free, and it’s more flexible if utilizing a trust. It can simulate the aspects of a stretch IRA without the tax complications of an IRA trust.
Interesting? Worth learning about. This strategy isn’t appropriate for everyone. You should talk with an advisor about your specific situation – that happens best by completing a formal financial plan, preferably with a CFP® professional – to see if this, or maybe some other, strategy might be right for you.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
**Tags:** Financial planning, retirement decisions, Retirement Planning, Retirement Strategy, SECURE Act, secure retirement
---
### [To Roll or Not to Roll](https://indfin.com/irarollovers/)
**Published:** May 13, 2022
**Author:** Jim Lorenzen
**Excerpt:** Good question. Whether or not you should roll-over your retirement funds to an IRA..... it depends (#1 in the consultant’s handbook of responses).
**Content:**
Let’s face it: your rollover check may be the biggest one you receive in your entire life – and it comes with a lot of decisions that can have far-reaching consequences, maybe even irrevocable!
**Basically, you have four options:**
- Stay put. Leave it in the company plan, if allowed and for as long as allowed, or roll it over to a new employer’s plan if you’re changing jobs.
- Roll the money over to an IRA
- Convert to a Roth IRA or Roth 401(k)
- Take a lump-sum distribution and pay the tax now.
Your choice will depend on when you’ll need the money, your retirement tax bracket, the size of your distribution, your age, health, life expectancy, your tax bracket, your plans for work, your income needs, whether creditor protection is important, and how it fits with your estate plan, just to name a few issues you’ll need to address.
**To Roll: Advantages of Rolling to an IRA**
- **Flexibility re withholding**. Usually plans are required to withhold 20% of an eligible rollover distribution paid to an employee. This doesn’t apply to IRAs. Owners can choose their withholding percentage, even if it’s zero.
- **RMDs are simpler**. IRA balances are aggregated for RMD calculation and the distribution can come from one or any combination of IRAs
- **More investment choices.** You’re no longer restricted to one ‘department store’. Now you have the entire mall to shop in – the whole universe of investments, plus the ability to customize. This can be important when planning in a volatile environment.
- **Roth conversions possible**. You can convert company plan funds directly to a Roth IRA, or leave the door open for future eligibility for converting from a traditional IRA to a Roth IRA later. One caveat: some company plans may not allow a distribution that you can convert to a Roth IRA; but, using an IRA rollover, you can convert to a Roth IRA at any time.
- **Estate planning is easier.** Coordination between your IRA and estate plan is easier than coordinating an estate plan with a company plan, like a 401(k).
- **Withdrawal flexibility**. IRAs have no withdrawal restrictions, which may not be the case with company plans. Some plans may not allow a distribution, even for personal hardship, if you’re under age 59-1/2.
- **Less paper and greater portability**. You can consolidate IRAs into one account and simplify paperwork. If you plan to keep working, you can roll the taxable money in your IRA back into your new company’s plan if you wish.
- **Professional advice** from a credentialed advisor well-versed in distribution issues and financial planning. Management of company plans, such as 401(k)s it typically outsourced to clerical staff.
**Not to Roll: Advantages of Staying In Your Company Pan**
- **Creditor protection**. Federal protection against personal bankruptcy, law suits, malpractice, and other actions. Note this is protection on the federal level; IRAs receive creditor protection on the state level. Also, under Federal Bankruptcy Law virtually all IRA funds are creditor protected from bankruptcy, but not other civil judgments.
- **Borrowing ability**. Many company plans have loan provisions. You can’t borrow from your IRA.
- **Still working** – you can delay the mandatory age 72 deadline for required minimum distributions (RMDs). You can’t do that with an IRA.
There are other advantages and disadvantages; but, these are the key issues that could affect most people. Each individual’s situation is different and a reputable advisor can provide valuable assistance.
Hope you found this helpful.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, IRAs, Planning, Retirement, Rollovers
---
### [Does The SECURE Act Make You More Secure?](https://indfin.com/retirement-security/)
**Published:** April 29, 2022
**Author:** Jim Lorenzen
**Excerpt:** Looking for retirement security?
Government spending has been out of control for decades and Congress needs to raise revenue. So, they passed The SECURE (Setting Every Community Up for Retirement Enhancement) Act in December 2019. It may secure the government’s future; but, one provision may make your heir’s retirement a little less secure.
**Content:**
Here are some key points:
The stretch-IRA has been eliminated and replaced with a 10-year mandatory payout for beneficiaries, except for certain ‘Eligible Designated Beneficiaries” (effective for 2020). This could provide a financial ‘time-bomb’ for the children of baby-boomers who stand to inherit during their prime earning years – what will tax brackets look like then? How will this affect their retirement security?
How will the new post IRA rules would work? Which IRAs will be most affected?
My 25-minute webinar will guide you through the key issues of The SECURE Act with what you need to know. Hope you find it helpful. [You can register to attend here](https://event.webinarjam.com/register/6/mgll9fk).
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Retirement, SECURE Act, Taxes
**Tags:** higher taxes, retirement decisions, Retirement Planning, Retirement Strategy, tax law changes, Tax reduction, Taxes in retirement
---
### [2022 Decisions Can Affect 2024 Taxes for Some!](https://indfin.com/irmaa/)
**Published:** April 18, 2022
**Author:** Jim Lorenzen
**Excerpt:** Expecting a big capital gains or other tax event this year? It might mean an unexpected tax surprise that can affect your Medicare premiums two years from now!
**Content:**
Ever hear of IRMAA? It’s the Medicare income-related monthly adjustment amount. It’s a test, devised as a means test for recipients of the federal program. Some think it’s only fair; others call it a cliff-tax for the rich. Many, if not most, people don’t even know about it.
While it kicks-in at incomes over $91.000 for singles and $182,000 for marrieds and who are in Medicare Part B or Part D (or both), these surcharges can be significant.
Many people aren’t worried feeling they won’t be affected – and, maybe they’re right. The most common trigger event is the sale of a home. In that case, it’s likely their Medicare premium will go up for one year, then drop the following year. It’s important to remember, there’s a two-year ‘look-back’.
How to mitigate this? Sell at age 63! It won’t affect IRMMA.
There are other strategies you might consider, too. Tax planning should be ongoing – now and all the way through retirement. Congress won’t stop tinkering with the tax laws just because you’re retiring.
[Register for my webinar](https://event.webinarjam.com/register/5/pgyy8f5), then grab some coffee and learn what you might be able to do to keep more of your hard-earned money from going to Washington.
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Planning, Retirement, Social Security, Taxes
---
### [Beware of Tax Torpedoes and the IRMAA Cliff](https://indfin.com/beware-of-tax-torpedoes-and-the-irmaa-cliff/)
**Published:** April 11, 2022
**Author:** Jim Lorenzen
**Excerpt:** Tax traps are waiting. Did you it's possible to be smack in the middle of the 22% tax bracket, yet taking an additional $1,000 in income could make that additional money taxable at 40%? It can happen to some taxpayers. In fact, there are other pitfalls many aren't aware of, as well.
**Content:**
Tax planning doesn’t stop because things change – stuff happens – in all four stages!
Planning is about preparing ahead of time to avoid unpleasant surprises. [My webinar](https://event.webinarjam.com/register/5/pgyy8f5) covers these and other issues. You can learn more [here](https://event.webinarjam.com/register/5/pgyy8f5)!
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Planning, Retirement, Rollovers, Roth conversions, Social Security, Taxes
**Tags:** Financial planning, retirement decisions, Retirement Planning, Retirement Strategy
---
### [Planning Retirement? Think Hard. Stuff Happens.](https://indfin.com/guardrails/)
**Published:** March 28, 2022
**Author:** Jim Lorenzen
**Excerpt:** Remember 1966? What if you retired then? Would it have made a difference if you retired in 1967 instead? Can you time retirement? If not, how do you reduce your risk when there's no time to rebuild all over again?
**Content:**
1966 was the year the American public was introduced to Doritos; Chevrolet released the first Camero; Star Trek hit the tv screens and the top song that year was “I’m a Believer” by the Monkees.
It was also the year that William Bengen discovered in his research that 1966 was the worst year for someone to retire!
No one can know when a bad, let alone a “worst”, year will happen. What we do know is we don’t want to outlive our money and end-up broke in our old age.
Is there a way to protect against this? Why not attend my short 22-minute webinar that just might make a world of difference in you planning? [You’ll find it here.](https://event.webinarjam.com/register/2/ky66zsz)
Enjoy!

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, Planning, Retirement
**Tags:** managing risk, Reducing Risk, retirement decisions, Retirement Planning, Retirement Strategy
---
### [New Social Security Statements Available](https://indfin.com/social-security-2/)
**Published:** March 24, 2022
**Author:** Jim Lorenzen
**Excerpt:** Have you checked your Social Security statement on the SSA's website? You should; there's a lot of good information there!
**Content:**
Your Social Security statement is critical to smart Social Security Planning. This is where you find your primary insurance amount (PIA), which is the monthly amount SSA estimates you will receive if you apply for benefits at full retirement age.
The statement presumes continued earnings to full retirement age (FRA) and is stated in today’s dollars. Since many will not apply for benefits at their exact full retirement age, the calculators I use in planning adjust the PIA for early or delayed claiming and apply projected cost-of-living adjustments. The calculators then show the income stream and total lifetime benefits for each claiming scenario using the life expectancies you enter. For many, seeing their claiming options in terms of lifetime benefits, including survivor income over the life expectancy of the surviving spouse, is essential to understanding the full impact of clients’ Social Security claiming decisions. It generally leads to a claim age of 70 for the higher-earning spouse, which is great.
Ever since statements were instituted by SSA in 1999, they have shown the benefit estimate at three different claiming ages: 62, FRA, and 70. These estimates take into account the reductions or credits for early or delayed claiming as well as the (generally small) impact of earnings to age 62, FRA, or 70.
The SSA has played around with different ways of presenting the estimates, mainly to discourage early claiming. Rather than showing the age-62 benefit first, it started showing the FRA-age benefit in large type on the front and listed it ahead of the age-62 benefit estimate. Different explanations in the body copy likewise sought to help people understand that starting benefits early would give them permanently lower income.
All of this is good, but the statements do lack the one piece of data that is needed to make the optimal decision on when to claim Social Security: total lifetime benefits under the various claiming scenarios taking into account life expectancies and COLAs. Thankfully, our planning platform takes care of this.
Between the Social Security statements and the calculators used in planning, incorporating Social Security benefits into retirement income planning has never been easier or led to better decisions about when to retire and when to start benefits. A whole generation of retirees will have more Social Security income because of this, especially the many widows-to-be who in 10 to 30 years won’t even realize how much better off they are because a spouse claimed at 70 instead of 62.
Want to learn more about this?
I’ve created a short 23-minute webinar you might find helpful. You can [find it here.](https://event.webinarjam.com/register/3/wgyymf7)
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Social Security
**Tags:** social security, social security claiming, social security help, when to claim social security
---
### [Are You A "Baby Boomer" Getting Ready for Social Security?](https://indfin.com/social-security-for-baby-boomers/)
**Published:** March 18, 2022
**Author:** Jim Lorenzen
**Excerpt:** If you're a baby boomer, you may want to begin your Social Security planning early - and it's especially true when it comes to claiming Social Security! Today it's different from when your parents filed their claims: they just went down to the Social Security office and put in the paperwork! Today, it's far more complicated.
**Content:**
Unfortunately, many, if not most, people get this wrong. They find out too late their friends weren’t experts – and their mistakes can cost tens, even hundreds of thousands of dollars. And, those mistakes can be irrevocable!
Those claiming mistakes can impact the taxes you pay later, including those on your IRA required minimum distributions and even your Medicare premiums. Widows, widowers, and even divorcees can be impacted, as well.
Retiring early and plan to work too? You may have heard your benefits will be impacted – your friends probably told you you’d be penalized! The truth is your benefits are adjusted; but you may be surprised to learn they’re not really lost. All of these issues need to be included in your overall planning. After all, living is a business, and every business should have a plan.
I’ve created a [short program](https://event.webinarjam.com/register/3/wgyymf7) – only about 23 minutes – that you might find helpful. It won’t make you a Social Security expert; but, it will get you started on the right track and help bring to the forefront some of the things you might want to know before making any mistakes.
You can[ register and access it here](https://event.webinarjam.com/register/3/wgyymf7).

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Social Security
**Tags:** social security, social security claiming, social security help, when to claim social security
---
### [Retirement Planning with Rising Rates and Inflation](https://indfin.com/retirement-planning-with-rising-rates-and-inflation/)
**Published:** February 22, 2022
**Author:** Jim Lorenzen
**Excerpt:** Retirement planning was much easier during working years than the challenge of managing after retirement. During the working years it’s relatively simple: just keep stashing money into your retirement plan and let the markets, over decades, do the rest!
**Content:**
While many people continue to work during the so-called retirement years, many others can’t – or would rather not – work. They’d rather enjoy other pursuits. The problem during ‘retirement’ is much more complicated, though. It’s not about simply stashing money anymore.
Now, there’s a new problem: how to be a actuary! Now, you have to face the challenges pension managers face: how to fund your own ‘pension’ liability for an indeterminant period of unpredictable changes in inflation, interest rates, and tax legislation. Not easy.
How do you do that? A look back might be of help. Those who retired during the early-to-mid 1970s were doing so at a time when interest rates were heading higher, as was inflation, while the markets were stagnant. Not a bad model to review, whether or not the markets repeat.
It was a time when many new retirees began to experience interest rates and inflation that grew in tandem up to double digits, about 15-17%. They loved the fact they were getting ‘pay raises’ by simply rolling 6-month CDs! Few considered that after taxes, they were actually losing purchasing power, but that wasn’t what undid many of their retirement plans.
No, it was the problem created when they began rolling CDs as interest rates and inflation both trended down. Let’s look at a simplified hypothetical example of the kind of situation that was common during that double-digit period:
Fred and Mary are retired. Inflation is 15% and their 6-month CD is paying 16% – no not an exaggeration – and they’re happy. Never mind that even in a 25% tax bracket, they’re really earning only 12% and losing 3% to inflation.
The next year, inflation and interest rates start down. Suppose inflation drops to 12% and, when they go to roll their CD, the new rate is now 13%. That 3-point drop in interest puts them in an uncomfortable situation. When they go to the grocery store, prices are still 12% higher, but their income has dropped 19% (3 points off 16% to 13% is 3/16 = 19%).
Yup, the next year, even with another drop, prices are still higher and their income dropped again. Not good. Too bad their assets weren’t arranged to preserve value.
Mark Twain once said, “History doesn’t repeat; but it rhymes.” Cycles happen and stuff happens. Planning isn’t about what we know; it’s about what we don’t know. And, often, the arrangement of assets can be more important than being clairvoyant.
Guardrails can help! You might enjoy our webinar on how to install them into your plan! You can [register here.](https://event.webinarjam.com/register/2/ky66zsz)
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Inflation, Investing, Planning, Retirement
**Tags:** Financial planning, managing risk, retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy
---
### [529 vs Roth IRA: Which is Better for College Savings?](https://indfin.com/college-planning/)
**Published:** January 27, 2022
**Author:** Jim Lorenzen
**Excerpt:** We’ve all been conditioned to believe the well-known 529 plan is the “designated” college savings vehicle – people tend to think of it automatically when planning.
**Content:**
But should they? Maybe… maybe not.
We all know what’s happened with college costs. The government has thrown money (college loans, grants, etc.) at students and colleges, in an attempt to recruit, have put much of that money into student unions, high-end dorm rooms, and a lot of other bells and whistles driving the cost of college sky high. I’m not sure if academic proficiency has kept pace with the improvement of infrastructure, but it has made saving for college more of a challenge for parents who are looking for new ways to save.
Families can seek student aid and file a Free Application for Federal Student Aid (FAFSA). With more than 100 questions on the form – many are financial – it helps those friendly folks in Washington decide just how much a student should pay for their own education. It’s calculated, in part, based on the assets of both the student and parents. Yes, *529 plan assets are included in the calculation*.
So, if you save through the “designated” vehicle expressly created for that purpose, it actually works against the student, reducing or even eliminating the amount of financial aid for which the student would otherwise qualify.
But wait! (I love it when they say that in those infomercials)
**There may be another way!**
Yes, 529 plans allow some tax breaks as long as 529 plan money is used to pay for qualified higher education expenses, like tuition. Those distribution are tax-free at the federal level and some states may even allow a state income tax deduction.
But what if things change? What if the student decides to go to a trade school or do something else? What if your child gets a full scholarship? What happens then? That money you’ve been saving in a 529 plan isn’t tax free anymore and may even be subject to a 10% penalty.
Not good.
**So what’s another possible strategy? The Roth IRA!** What if the money had been saved in a Roth IRA?
The Roth also allows for tax-free distributions as long as the Roth IRA owner is over age 59-1/2 and they’ve had any Roth IRA for five years or longer. People have been waiting longer to get married in recent years, making both thresholds easier to meet. But even if the owner hasn’t reached age 59-1/2 or met the holding period requirement, Roth IRA contributions can be distributed at any age – at any time tax-free and penalty-free. So, contributions over ten years, for example, can be withdrawn at any time for any reason, tax-free and penalty-free.
Oh yes, money converted to a Roth IRA from a traditional IRA might possibly also be distributed tax and penalty free, as long as the conversion took place five years ago, or longer.
How do Roth IRA distributions to pay for college impact the child’s chances for aid in future years? It could. It depends. (consultants always like to say that.)
The child or parent can take out loans for education expenses as needed, then use Roth IRA funds to pay off the debt. Note: The parents’ Roth IRA isn’t counted as an asset for FAFSA. That’s good. Distributions, however, are counted as income for FAFSA purposes, even if those distributions are tax free. This means the parents are okay the first year they fill-out the FAFSA form, because there’s been no distribution to pay for college costs as yet. If they do take a Roth IRA distribution to pay for college related expense, it might reduce or eliminate their eligibility in future years.
However, if they use student loans to pay for education expenses, they can wait until they no longer need to file a FAFSA form for aid and then use the Roth IRA to repay the loans. By the way, interest paid on the student loans is a deductible expense.
Taking out student loans and making timely repayments (even from funds taken from the Roth IRA) can be used to build credit… not just average credit, either, when the amounts can be many thousands of dollars.
Not bad.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues, Investing, Planning
**Tags:** college planning
---
### [Roth Conversions Can Be Advantageous, but Not for Everyone.](https://indfin.com/roth-conversions-can-be-advantageous/)
**Published:** January 4, 2022
**Author:** Jim Lorenzen
**Excerpt:** There may be times when a Roth conversion may be advantageous; but there are others when it may not be your best move.
**Content:**
**There may be times when a Roth conversion may not be your best move.**
Here are some examples:
**You don’t have the cash to pay the tax.** The conversion amount is considered taxable income. If you pay the taxes from the conversion, your Roth will have less money which destroys any advantage a conversion provides. Besides, if you’re under 59-1/2 any money withheld from the conversion counts as a distribution and you’ll owe a 10% penalty to the IRS.
**You might need the money within 5 years**. There are a couple of 5-year rules that can be ‘gotchas’ that generate additional taxes or penalties. The important thing to remember is that each conversion starts a 5-year holding requirement. Talk with your advisor.
**You expect your tax bracket to be lower in future years**. This one may be difficult to believe, given the increasing government debt and need for revenue; however, there are considerations worth mentioning: the state of your retirement is one. If you’re in a high tax state and plan to retire in a state that has no state income tax – Florida, for example – you may want to crunch some numbers first. But, even some high-tax states have some advantages. New Jersey, for example excludes the first $100,000 from retirement income. Talk to your tax advisor. Also, if you plan to work in retirement, that may change or calculations.
**Your IRA beneficiary will be in a lower tax bracket**. If your IRA is large enough and you have other money to live on, it’s very likely your IRA will be inherited by someone else. If it’s a non-spouse (think children or grandchildren), they’ll have to withdraw all the funds within a 10-year period. Will your beneficiary be a low income earner or a high-earning professional? Some advance planning can provide some answers.
**You are expecting large medical expenses.** Converting all your IRA money to Roth IRAs means there would be no traditional IRA money left to use for medical expenses to take advantage of any deductions that might be available. You’d be paying taxes and wasting the deduction!
**You own a business**. Any future losses could be used against IRA distributions! If your business is profitable, it’s a better situation and you might want to disregard this one.
The Roth conversion isn’t right for everyone; but, it’s a powerful tool for many, if not most. It’s worth having a plan.
Now, if only I knew where you could find an advisor to help…….

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Retirement, Roth conversions, Taxes
**Tags:** retirement decisions, Retirement Planning, Retirement Strategy, Roth conversions
---
### [Good News: Social Security Isn't Going Broke.](https://indfin.com/socialsecurityoutlook/)
**Published:** November 29, 2021
**Author:** Jim Lorenzen
**Excerpt:** However we're not out of the woods....
**Content:**
**The Bad News: Some benefit cuts may be on the way!**
The headlines aren’t new. People have been talking about Social Security going broke for decades. Now with added inflation concerns and the impact of future budget deficits on the outlook for both inflation and taxes, it’s no surprise that more people are concerned about their own retirement plans.
This, of course, is especially important to baby boomers who are nearing what could be thirty years of retirement punctuated with inflation, tax law changes, and uncertain – as if they were ever anything else – markets.
I’ll be addressing those issues in my webinar, ***What Baby Boomers Need To Know About Retirement Income***. You can **[reserve your spot here](https://event.webinarjam.com/register/1/1vnnycp).**
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Inflation, Retirement, Social Security
**Tags:** retirement decisions, Retirement Income, Retirement Strategy, social security, social security claiming, social security help, social security outlook
---
### [Social Security Claiming can be Confusing.](https://indfin.com/social-security/)
**Published:** November 15, 2021
**Author:** Jim Lorenzen
**Excerpt:** Social Security can be confusing; even the hard-working people working in Social Security offices don't always get it right. Here are the two questions advisors often get asked.
**Content:**
**I applied for early benefits and now wish I hadn’t. What can I do?**
It depends. If it’s been less than 12 months since you first applied, you can withdraw your application and repay your benefits. You can then reapply at any time in the future.
However, if it’s been more than 12 months, **and** you are now over full retirement age (FRA, which ranges between 66 and 67 depending on your birthday), you can suspend your benefit and earn the 8% annual delayed credits on the current amount.
**Example:** Fred applied for Social Security at 62. His primary insurance amount (PIA) is $2,000. (The PIA is the amount he would receive if he claimed his benefit at FRA.) Because he claimed at 62, his benefit is 70% of $2,000, or $1,400. When he turns 67 he can suspend his benefit and earn 8% annual delayed credits on the $1,400. When he turns 70 he can claim his benefit and raise his permanent benefit to $1,736 ($1,400 x 1.24 = $1,980). Note that if Fred suspends, no spousal or dependent benefits can be paid on his record while it is in suspension. If you are under full retirement age you may not voluntarily suspend your benefit. However, you can achieve the same result by going back to work. And, that’s not bad, as you’ll see.
**Don’t I lose money if I go back to work after starting Social Security?**
If you are under full retirement age, some or all of your benefits may be withheld. That’s ‘withheld’, not lost.
$1 will be withheld for every $2 that you earn over the earnings test threshold, which is $18,960 in 2021. Sounds bad, but read on. Those benefits aren’t lost. In fact, it may be a good reason to go back to work, because your benefit will be recomputed at FRA to remove the actuarial reduction for those months in which your benefit was withheld. In other words, it will raise your benefit going forward. True!
Let’s say your PIA is $2,000 and you applied for benefits at 62. Your reduced benefit is $1,400 (70% of $2,000). At age 64, you go back to work and earn enough so that all of your benefits are withheld. When you turn FRA (67), your benefit will be recomputed to make it as if you had applied at age 64! Going forward you will get 80% of $2,000, which comes to $1,600. Then, if you were to suspend your benefit at FRA, you can earn 8% annual delayed credits on the $1,600. When you claim your benefit at 70, it will be $1,984 (not counting cost-of-living adjustments or the effect of additional earnings). Going back to work is a great way to increase your Social Security benefit, and benefit from the earnings themselves.
How about that, sports fans?

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Planning, Retirement, Social Security
---
### [Social Security Claiming Mistakes Can Be Expensive.](https://indfin.com/socialsecurity4boomers/)
**Published:** November 8, 2021
**Author:** Jim Lorenzen
**Excerpt:** Social Security claiming mistakes can result in more than just lost income; you might end-up paying thousands in extra taxes later!
**Content:**
**If you’re a baby boomer thinking you might need help making Social Security decisions, you’re not alone.**
When should you claim? How much will you receive? Will Social Security be there for me when I retire? Can I continue working and will I really be penalized? How can a claiming mistake today cost me even more later?
T**here’s a lot to know about Social Security**, especially when it comes to making decisions that can affect you and your spouse for decades to come. Your decisions will impact your tax bill for many years to come.
Do you know how your IRS-mandated required minimum distributions at age 72 will impact the taxes you pay on Social Security? Your Medicare premiums? Do you know what ‘provisional income’ is and how it affects the taxes you’ll pay in retirement?
**If you’re someone with a nest-egg over $500,000 and thinking about when or whether you should claim your Social Security benefit early or wait,** I would suggest it’s best to do your planning BEFORE you act. But, even before you plan, you might want to get your knowledge ducks lined-up.
Consider this your invitation to a webinar especially designed for Baby Boomers: ***What Baby Boomers Need to Know About Retirement Income***. The emphasis is on Social Security strategy and the importance of coordinating your strategy with a comprehensive retirement plan.
**[You can register for an upcoming webinar here](https://event.webinarjam.com/register/1/1vnnycp).**
This webinar will cover a LOT of material; so, be sure to have your coffee and be ready to take a lot of notes.
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Social Security
**Tags:** social security, social security claiming, social security help, when to claim social security
---
### [Do You Have A System for Managing Retirement Income?](https://indfin.com/makingmymoneylast-2/)
**Published:** October 22, 2021
**Author:** Jim Lorenzen
**Excerpt:** Longevity risk is real. Accumulating assets for retirement was a lot easier than managing retirement income. Now you practically have to be an actuary to make sure your money doesn't run out before you do!
**Content:**
It**‘s a different skill set. Do you have a strategy?**
During your working career, you simply put money into your retirement account and watched the market climb for two to three decades (not in a straight line, of course; but, it still went up over time).
The accumulation phase was a lot easier than the distribution phase. In retirement you’re drawing down assets – and doing it during two or three decades of inflation and tax-law changes, not to mention those untimely market declines that always seem to take place just when you need your money the most!
**Do you remember 1966?**
There was no recession or depression. No dot-com bust or credit melt-down; no market crash. It was a pretty unremarkable year except – it was a bad year to retire.
No one want to see their retirement plans go ‘off the road’ – especially when already in retirement. Maybe installing some ‘guardrails’ might help.
I’m doing a short webinar on how you can adopt a “Guardrails” strategy for your own retirement. I think you’ll find it helpful.
You can[ register here!](https://event.webinarjam.com/register/2/ky66zsz)
Enjoy!

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Retirement, Rollovers
**Tags:** Financial planning, retirement decisions, Retirement Income, Retirement Planning, Retirement Strategy
---
### [Can Your IRA Grow Too Big?](https://indfin.com/can-your-ira-grow-too-big/)
**Published:** September 28, 2021
**Author:** Jim Lorenzen
**Excerpt:** A Roth conversion for some IRA assets may provide more tax savings than you realize.
**Content:**
The Tax Cuts and Jobs Act eliminated the ability to undo a Roth conversion from your IRA. Big deal. Even when you could undo a Roth conversion, it was for a limited time; after that, they were permanent anyway.
A smart strategy may not be to convert your entire IRA all at once, anyway. Odds are that move will put you into a higher tax bracket. Better to make a series of smaller conversions over a number of years. IFG’s planning software does all these computations for you, however, contrary to conventional wisdom of stashing away as much as you can in your retirement account, you may NOT want your IRA to grow too large.
Really?
Think about it: at age 70 you’ll be required to take distributions from your IRA. The minimum amount you’ll be required to take (your RMDs) very well could put you into a higher tax bracket; and, if taxes go up, it could be even worse than we think. So, how do you keep your RMD below that threshold? Here’s a good way to begin using a little back-of-the-envelope calculation I learned from Ed Slott[\[1\]](#_ftn1):
1\. Your marginal tax bracket: Let’s assume you want to be in 12% marginal tax bracket in retirement. A look at the tax tables shows you that a couple would require a taxable income of $81,050 or less to be in that bracket.
2\. Multiply that amount by the life expectancy for a 70-year-old using the IRS uniform table. Currently it’s 27.4 years. $81,050 x 27.4 = $2,220,770. IRAs exceeding that amount would have RMDs forcing you into a higher tax bracket. Naturally you’ll want to monitor both the tax brackets and IRS tables as time passes – planning never ends.
Note: If you and your spouse want to be in the 10% bracket, the amount changes drastically. Now it’s $19,900 \* 27.4 = $545,260. Oops! Big difference.
Your retirement income not only impacts your income taxes directly; it also impacts the taxes you pay on your Social Security income as well as your Medicare premiums.
What if you wanted to have a completely tax-free income in retirement? Talk about fewer headaches, huh? It may be possible if you plan early. Start arranging assets in your mid-50s. Those who begin early enough can potentially create a tax-free retirement—which could virtually take Congressional tax bills out of your financial future.
That would be a good thing.
Jim
---
[***\[1\]***](#_ftnref1) *Ed Slott is a practicing CPA and a recognized IRA expert.*

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Retirement, Rollovers
**Tags:** RMDs, Roth conversions, Roth IRA
---
### [17 Unexpected Retirement Expenses](https://indfin.com/17-unexpected-retirement-expenses-2/)
**Published:** July 23, 2021
**Author:** Jim Lorenzen
**Excerpt:** I wish I could take credit for this list, but I can’t. This is from the Society of Actuaries who outlined these unexpected or shocking expenses in its 2015 Risks and Process of Retirement Survey. I doubt it’s changed much since. Here they’re ranked by the likelihood of it happening.
**Content:**
How many of these unexpected retirement expenses can you cross off?
*17. Loss of capacity requiring someone outside the household to manage your money.*
*16. Divorce during retirement*
*15. Significant damage to or loss of home due to fire or natural disaster*
*14. Loss of home through foreclosure*
*13. Bankruptcy*
*12. Victimization by fraud or scam*
*11. Loss in total value of savings of 10% or more due to poor investment decisions*
*10. Death of spouse or long-term partner*
*9. Family emergency that impacted the ability to spend on other things or used 10% or more of savings*
*8. Going on Medi-Cal/Medicaid*
*7. Sudden loss of total value of savings of 25% or more due to a drop in the market*
*6. Running out of assets*
*5. Illness or disability that limited the retiree’s ability to take care of him/herself*
*4. Drop in home value of 25% or more*
*3. Significant out-of-pocket medical or prescription expenses from a chronic health condition or disability that did not limit the retiree’s ability to take care for him/herself.*
*2. Major dental expenses*
*1. Major home repair or upgrades*
Believe it or not, virtually all of these can be planned for and eliminated or mitigated, which can help lessen the shock. What have *you* done?
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Family Issues, Planning
---
### [Higher Taxes Ahead?](https://indfin.com/higher-taxes-ahead/)
**Published:** July 10, 2021
**Author:** Jim Lorenzen
**Excerpt:** What could those tax hikes look like? Let’s consider the possibilities.
**Content:**
### More spending = higher taxes?
That seems likely with a $2 trillion American Jobs Plan (that could eventually cost trillions more) on the table to bolster America’s crumbling infrastructure and invest in R&D.
Though President Biden committed to not raising taxes on folks earning less than $400,000 per year, it seems hard to believe that he’ll be able to keep that promise with such a massive jobs bill to cover.
**Watch out for a new auto mileage tax**, which would raise money for highway infrastructure.
**Another is higher fuel taxes,** which could increase what Americans pay at the pump.3 However, both proposals would be difficult to get through Congress, so they seem unlikely to come to fruition.
Some economists favor funding long-term infrastructure spending with **ultra-long bonds** and it’s possible Treasury Secretary Yellen will consider issuing 50-year bonds for the first time since 1911 to take advantage of low interest rates.4 Be careful about buying one, however – a slight increase in interest rates could make those bond values plummet.
**Bottom line: we don’t know exactly what will ultimately come out of Congressional haggling; however, it’s smart to prepare ourselves for potentially higher tax rates in 2022.** Actually, even beyond.
**Even if NO bill passes**, the current tax law will expire in five years taking us back to the Obama era tax brackets – and those will affect most everyone.
What could 2022 taxes look like? While I don’t have a crystal ball (well, I do, but it’s in the shop), the following changes seem very possible:
- A higher top income tax rate
- A higher capital gains tax rate (Some want to eliminate capital gains and tax it all at the higher income rates. Others, including President Biden, favor eliminating the step-up at death and taxing inherited wealth, beyond a certain threshold, as income whether the inherited assets are sold or not.)
- A higher corporate tax rate
- A lower estate tax exemption amount
We’ll know more as the final deal shakes out, but it’s clear these possibilities make 2021 even more critical for tax and estate planning, especially since the SECURE Act all but eliminated the stretch IRA for nonspouse beneficiaries – which would force liquidation within ten years when the beneficiaires are in their peak earning years and likely in higher tax brackets (with the double-whammy of tax increases).
Good planning can mitigate – maybe even eliminate – some of these concerns.
It’s all about the plan. Without that, it’s all about Washington. Take your pick!
Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Economy, Taxes
**Tags:** higher taxes, tax hikes, tax law changes, taxes
---
### [When to Name a Trust as your IRA Beneficiary](https://indfin.com/when-to-name-a-trust-as-your-ira-beneficiary/)
**Published:** June 24, 2021
**Author:** Jim Lorenzen
**Excerpt:** IRAs are popular choices as a retirement vehicle, today holding over $11 trillion in assets, estimated to comprise more than one-third of all retirement assets. What’s interesting is that naming trusts as IRA beneficiaries has become more common.
**Content:**
**Jim Lorenzen, CFP®, AIF®**
Most everyone knows required minimum distributions (RMDs) must begin at age 72. The size of each year’s RMD is based on an age and life expectancy factor shown in tables published by the IRS (Roth IRAs are not subject to the RMD requirement). What few realize is that the way the tables are calculated, there will be money over in the IRA at death if only RMDs are withdrawn each year. In fact, if the IRA has a high rate of return, it’s even possible for the IRA to have actually grown in value. So far, not bad.
IRA assets, of course, do not pass under the terms of your will or trust – they pass to whoever is named as beneficiary. But, a trust can be named as beneficiary, then the assets are maintained in a separate account; and, there may be times when this makes sense:
**Your beneficiary is a minor or someone with special needs** – A minor cannot legally own an IRA. Someone with special needs maybe shouldn’t be a beneficiary if they’re likely to lose access to government benefits if s/he owns assets in his/her own name.
**Second marriages** – An IRA owner may wish to benefit a surviving spouse during his/her lifetime and have the remainder pass to the owner’s own children.
**Successive beneficiaries** – When your beneficiary inherits your IRA, s/he can name his/her own beneficiaries. These may or may not be the successors the original owner intended.
**Limiting/controlling access to funds** – Beneficiaries can decide how much they want to take without regard to their purpose. An IRA owned by a trust will be subject to the terms of the trust.
**Creditor protection** – While a regular IRA does have some degree of creditor protection, those protections don’t always carry over to an inherited IRA, according to a 2014 Supreme Court ruling in Clark v. Rameker, 134 S. Ct. 2242. The court ruled that inherited IRAs do not qualify as exempt from claims of creditors as “retirement funds” under the Federal Bankruptcy Code. An IRA owned by a trust, however, is not considered to be owned by the beneficiary and does have some protection.
**Loss of the “Stretch”** – The SECURE Act has all but eliminated the stretch IRA for non-spouse beneficiaries. They’re now faced with the 10-year rule, which [we’ve talked about before](https://indfin.com/secure-act-2-0/). Post-death RMDs for a trust named as beneficiary will be calculated under either the stretch, 10-year, or 5-year rule, depending on the trust and beneficiary characteristics. It depends on whether the trust qualifies as a conduit trust, an accumulation trust, a see-through trust and whether the beneficiaries are non-individuals, regular beneficiaries, or part of what’s now called “eligible designated beneficiaries”. Be sure to talk with your estate planning attorney – which rule applies is not always clear.
As you can see, the beneficiary choices can be important considerations. It’s good to talk with your team of professionals.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Retirement, SECURE Act, Special needs
**Tags:** ira beneficiaries, SECURE Act, trusts
---
### [SECURE Act 2.0?](https://indfin.com/secure-act-2-0/)
**Published:** June 9, 2021
**Author:** Jim Lorenzen
**Excerpt:** Remember when we heard the SECURE Act eliminated the stretch IRA for most all non-spouse beneficiaries?
**Content:**
Remember when we heard the SECURE Act eliminated the stretch IRA for most all non-spouse beneficiaries? The SECURE Act said those IRA beneficiaries had to liquidate the IRA by the end of the tenth year.
But, wait! [The IRS in Publication 590-B](https://www.irs.gov/pub/irs-pdf/p590b.pdf) has issued new guidance that seems to indicate RMDs will be required in EACH of those ten years… no waiting until the end of the tenth year (the government is in debt and needs money, you know). Eligible beneficiaries – spouses and a few other classes – can still stretch payouts over their life expectancy; but, most non-spouse beneficiaries may have to take RMDs liquidating the inherited IRAs that liquidate the accounts within ten years.
But, wait! (yes, again). The house Ways and Means Committee unanimously passed H.R. 2954 on May May 5th. What’s been called Secure Act 2.0 now goes to the full house before moving on to the Senate and a likely presidential signature. There are a number of changes, but the top 4 may be these:
1. The RMD age has been increased to 73 starting on January 1, 2022, then to 74 starting on January 1, 2029, and to 75 starting on January 1, 2032.
2. 401(k) and 403(b) plans will be required to automatically enroll workers when they become eligible. They can opt-out, but the initial enrollment will be automatic.
3. IRA catch-up contributions are currently increased by $1,000 (not indexed) for individuals who’ve reached age 50. The bill indexes the limits starting in 2023.
4. There will be higher catch-up limits at ae 62, 63, and 64. The act increases limits on catch-up contributions to $10,000 ($5,000 for SIMPLE PLANS) for individuals who have reached ages 62, 63, and 64, but not age 65.
The dust hasn’t settled yet.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Retirement, SECURE Act, Uncategorized
**Tags:** Retirement Income, Retirement Planning, Retirement tax strategies, RMDs, SECURE Act
---
### [Retirement Income Planning Gains Importance.](https://indfin.com/retirementincome/)
**Published:** May 7, 2021
**Author:** Jim Lorenzen
**Excerpt:** Retirement Income Planning Gains Importance.
**Content:**
**Boomers Getting Older; Tax Laws Changing; IRAs Changing. So, What else is new?**
**Boomers are getting older.** According to a Pew Research Center study, *four times* as many boomers retired between February and September of last year than did during the same period the year before. That’s 11 million boomers who retired last year vs 250,000 the year before.
And, retirement income is getting more complicated. Today a coordinated, tax-smart asset location (not just allocation) is becoming more important than ever – not just for those who are still in the accumulation stage, but also for those in retirement who need an optimal sequence of withdrawal strategy from Social Security, annuities, investment accounts, and other sources of income.
**Social Security saw three big changes arrive in 2021.** In addition to a 1.3% increase – a $20 monthly increase for the average recipient (party time!) – more earnings are now subject to Social Security taxation. Beginning this year taxpayers will pay a 6.2% Social Security tax and a 1.45% tax for Medicare (known together as FICA) on the first $142,800 they earn (up by $5,100 from the year before. Unfortunately, prices for goods and services have been rising even more, particularly food and utilities. And, of course, the Social Security earnings limit will be higher. But, so much for the weeds
**The SECURE Act** came along in December 2019. It had five big IRA changes many find advantageous.
1\. It repealed the age limitation for IRA contributions. Now any individual can contribute to an IRA regardless of age, as long as that individual has eligible compensation.
2\. Eligible compensation not only includes wages, salaries, tips, and self-employment income, it now includes non-tuition fellowship and stipend payments included in gross income and paid to aid in the IRAs pursuit of graduate or postdoctoral study. In addition, home health care workers who receive foster care payments are included.
3\. The beginning date for RMDs is now April 1st of the year that follows the year in which the participant reached age 72 (applies to those who reached 70-1/2 after December 31, 2019; those reaching 70-1/2 earlier are not affected and the CARES Act waived the RMD requirement for 2020).
4\. Penalty-free withdrawals from retirement plans are now allowed for individuals in case of birth of a child or adoption – for both traditional and Roth IRAs (limits apply).
5\. The distribution period has changed for certain beneficiaries – for both traditional and Roth IRAs. Now, most beneficiaries must take full distribution of inherited IRA assets within a ten-year period. This affect all those who inherited retirement accounts after December 31, 1019. This is a game-changer for most non-spouse beneficiaries.
As I indicated earlier, *asset location*, not just allocation, has become more important than ever. A retirement income strategy that’s tax-efficient will be key, unless you want Uncle Sam as an inheritor. That might be okay if your children really do see him as big brother.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** IRAs, Planning, Retirement, Rollovers, Roth conversions, SECURE Act, Taxes
---
### [IRA Rollover Mistakes Can Be Irrevocable](https://indfin.com/ira-rollover-mistakes-can-be-irrevocable/)
**Published:** April 20, 2021
**Author:** Jim Lorenzen
**Excerpt:** IRA rollover mistakes are easy to make and could be impossible to correct. It’s worth understanding that every time IRA or 401(k) money is touched, it’s a gamble for those who don’t know what they’re doing.
**Content:**
IRA rollover mistakes are easy to make and could be impossible to correct. It’s worth understanding that every time IRA or 401(k) money is touched, it’s a gamble for those who don’t know what they’re doing. IRA expert and CPA Ed Slott says it’s like an eggshell – he’s good at metaphors – break it, and it’s over. He’s right.
Few people realize that if they make a mistake on the rollover, they could lose the IRA entirely – and it’s irrevocable!
A number of years ago, I wrote a report, Six Best and Worst IRA Rollover Decisions, which is available on the IFG website. One of the mistakes I mentioned was in not recognizing you probably shouldn’t do a rollover at all!
Why? First, you have to understand what a rollover is – as the well as the difference between a rollover and an custodian-to-custodian transfer. A rollover happens when money has been withdrawn from a 401(k) and deposited into an IRA. When that happens, the client is required to do the necessary withholding, pay the tax and wait for a refund the following year. A transfer of the account directly between custodians avoids that problem; but, there’s a potentially bigger one.
**Here’s an example scenario**: If a rollover has been previously rolled over in the past 12 months, the entire account now becomes taxable, and there’s no fix to correct the error. Someone with a $500,000 or $1 million (or any other size) IRA could be in for a big shock. Taxes will be due at their new rate – this withdrawal likely puts them in a new bracket – and the money left is no longer tax-deferred!
A direct transfer would have avoided this problem.
**Keep up with the latest rules**
A lot of seniors have CDs and IRAs at banks. There was a time when you could do one rollover per year for each of your IRA accounts. The law these days is one rollover per year for ALL IRA accounts – and that includes Roth IRAs. Two rollovers means that one of them will be no good.
**Inherited IRAs**
Here’s where mistakes can, and do, happen far too often; because the rules are different – and stiffer.
Did you know a non-spouse beneficiary can NOT do a rollover? A child who inherits a parent’s IRA must be careful. Often , because the child wants to access the money right away, an attorney will put the child’s name on it. When that happens, that’s the end of the account. It just became a taxable distribution. It should have been set up as a properly titled and inherited IRA. Putting the money into the beneficiary’s IRA is a terrible mistake.
**Beneficiary Designation**
Too often, problems happen because people fill-out the beneficiary forms and forget them – never reviewing them. Failure to do this only puts off the day when siblings get “lawyered-up” because the investor didn’t understand the true meaning of the distribution designations.
There’s more to know, of course; but, hopefully this will get you thinking… and doing your homework before making mistakes that can’t be changed. Working with a professional who’s been down the path before can’t hurt, either.
Jim
---
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® serving private clients since 1991. Opinions expressed are those of the author and do not represent the opinions of IFG any IFG affiliate or associated entity.The Independent Financial Group is a fee-only registered investment advisor with clients located across the U.S. He is also licensed for insurance as an independent agent under California license 0C00742. Jim can be reached at 805.265.5416 or (from outside California) at 800.257.6659. The Independent Financial Group does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.
Interested in becoming an IFG client? Why play phone-tag? You can easily schedule your 15-minute introductory phone call!

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Investing, IRAs, Planning, Retirement, Rollovers
**Tags:** IRA rollover, retirement decisions, Retirement Planning
---
### [What Does A Tax Strategy Look Like?](https://indfin.com/what-does-a-tax-strategy-look-like/)
**Published:** March 11, 2021
**Author:** Jim Lorenzen
**Excerpt:** There are many possible tax strategies available. The question, of course, is which, if any, are appropriate for you.
**Content:**
There are many possible tax strategies available. The question, of course, is which, if any, are appropriate for you. To give you an idea of one strategy, it might be best to see an example. Remember, however, to talk with an advisor before acting. They say a picture is worth a thousand words.
[Take a look at this!](https://indfin.com/video-library/) Enjoy!
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
**Tags:** Retirement tax strategies, Tax reduction, Tax-Free Retirement Income, Taxes in retirement
---
### [Insurance Company Ratings May Not Be What They Seem!](https://indfin.com/insurance-company-ratings-may-not-be-what-they-seem/)
**Published:** October 21, 2015
**Author:** Jim Lorenzen
**Content:**
**Jim Lorenzen, CFP®, AIF®**
Don’t believe beautiful illustrations. They’re based on assumptions that can change. Unless you know the probability of success in advance – not an easy thing to do – you may be buying a “pig-in-a-polk”, as we used say when I was in college back in Virginia.
Example: Before Executive Life of New York went under, they had over 50% of their portfolio invested in less than investment grade ‘junk’ bonds, despite the fact that in June 1987, the New York legislature had mandated that insurance companies licensed to business in that state were to limit their general portfolios to no more than a 20% allocation to such bonds. Remember, there are no guarantees; there are only guarantors. \[Source: The New Insurance Investment Advisor, Ben G. Baldwin, McGraw-Hill 2002, p. 37.\]. Is your insurance agent a qualified investment advisor who knows what to look for “under the hood”?
Most of the well-known rating agencies we’re familiar with are actually paid by the insurance companies they rate.
Yes, you should read that again.
Little wonder many insurance companies that failed actually had good ratings when they went under. My personal favorite rating agency is Weiss. They receive no money from the insurance companies they rate – they’re paid by customers who access the ratings. Their ratings are called ‘safety ratings’ and they seem to be a little more stringent. For example, according to the September 2002 Insurance Forum, of 1221 life and health companies rated by Weiss, only 3.9% of companies made it into the ‘A’ category. Compare that with the 54.9% rated ‘A’ by Standard and Poor’s. At Moody’s, 90% of their list made it to ‘A’ that year. A.M. Best gave ‘A’ to 56.3% of the companies they rated.
The takeaway: You may want to be sure your agent is not only independent, but understands whether and how life insurance fits into your overall financial plan. Your agent/advisor should also khow the difference between a “highly-rated” company and an “investment grade” company.
Thought you might be interested.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Life Insurance, Retirement
---
### [Are YOU a Target in the Green Book?](https://indfin.com/are-you-a-target-in-the-green-book/)
**Published:** May 20, 2015
**Author:** Jim Lorenzen
**Content:**
Last week we heard from many experts who believe it may be time to dump the 401(k).
Two weeks ago we discovered that many experts, like retirement guru and CPA, Ed Slott and former US Comptroller General David M. Walker, believe income taxes are going up – I even conducted my first-ever webinar on how you might be able to plan for an income tax-free retirement.
(You can access a[ recorded version here](https://attendee.gotowebinar.com/recording/1183711495198713857). Be aware: There’s a lot of information, so it lasts about an hour).
This week, I want to tell you about the Green Book. The Green Book is what the administration releases every year, detailing budget and tax proposals for the coming year. The Obama Administration released their latest version in February, detailing their proposals for the fiscal year beginning this October.
**Surprise: Many of the Green Book retirement planning proposals are aimed at limiting taxpayer use of tax-advantaged qualified retirement plans and IRAs.**
Maybe you’d like to view that [recorded webinar](https://attendee.gotowebinar.com/recording/1183711495198713857), after all.
This proposal should cause some concern because many who have contributed to retirement plans throughout their working lifetime and hit the proposed “retirement savings cap” will lose the ability to make future contributions and lose matching contributions provided by an employer.
By the way, under the Green Book proposals, *after-tax* contributions to an IRA could not be converted to a Roth IRA.
As many experts recommended in the second video featured in [last week’s post](https://indfin.com/time-to-rethink-401k), the current system might be better replaced with an insured solution, taking market-risk off the table and potentially removing much of the legislative risk, as well.
**What the Green Book proposals would do.**
According to David Cordell, PhD, CFP®, CFA, CLU®, and Thomas Langdon, J.D., LL.M., CFA, writing for the *Journal of Financial Planning*, these are some of the key proposals:
- Raise the capital gains rate from 20% to 28%
- Treating gifts of appreciated property (this would include your investments) as realized gain, requiring the payment of capital gains tax
- Reducing the estate and generation-skipping transfer tax exemptions from their current level of $5.43 million to $3.5 million with (ready?) no inflation indexing
- Reducing the lifetime gift tax annual exclusion from $5.43 million to $1 million. Eliminating the IRC Sec. 1014 “step-to” basis provision and replacing it with a $100,000 per person exclusion at death – the “steps” can be down, as well as up.
**How this might impact your planning:**
The “insured solution” may be where much planning is headed. The Green Book proposals might make life insurance policies designed for cash accumulation even more attractive than they already are, for both individuals and businesses.
The most significant changes in the Green Book include:
- Eliminating “stretch” IRAs by requiring non-spouses to distribute inherited IRA funds within five years.
- Depriving individuals with more than a specified amount in their retirement accounts from making contributions to retirement accounts – they’re currently projecting this figure to be about $3.4 million, which could be expected to produce an annual income of $119,000 before taxes with a comfortable margin of safety using a 3.5% withdrawal rate while allowing for inflation adjustments. The figure, however, could vary – the government will let you know.
- Repealing the special exclusion for net unrealized appreciation for lump-sum distributions of employer securities from employer plans.
- Requiring plans to expand eligibility requirements to include part-time employees who worked at least 500 hours per year in three consecutive years, and
- Limiting Roth conversions to pre-tax dollars
*\[Source: Journal of Financial Planning, May 2015\]*
If you missed my webinar, you might want to [take a look now](https://attendee.gotowebinar.com/recording/1183711495198713857). Grab a cup of coffee, a pad and pen – you’ll be taking notes – and see what you might be able to do to secure your future and remove, as much as possible, government intervention from the picture you have of your 30+ year retirement.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Retirement, Uncategorized
---
### [Bull or Bubble?](https://indfin.com/bull-or-bubble/)
**Published:** March 7, 2013
**Author:** Jim Lorenzen
**Content:**
[](https://jimlorenzen.typepad.com/.a/6a017c332c5ecb970b017d418c2c9e970c-120wi)Financial planning is about preserving purchasing power for retirement and beyond. It may not be as easy as it looks, especially for those close to or in retirement.
Few of these folks have overweighted stock allocations. In the meantime, bonds have likely hit their highs and their yields are low; so, even a 40% increase in stock prices, for example, would result in only an 8% increase in portfoliio value for someone who’s had just 20% of his portfolio in stocks, assuming bond values didn’t change. When you add factors like inflation, and taxes on required minimum distributions for tax-deferred accounts, etc., one can see why investors are concerned.
The stock market has had a big run over the past five years; but, it’s been five years of drastically increased borrowing on top of a decade-old policy of pursuing a weak dollar policy. So, prices may be higher, is the value really preserved?
Many believe, as [this article](https://www.economist.com/blogs/schumpeter/2013/03/america%E2%80%99s-stockmarket "Economist") in The Economist indicates, that the current U.S. stock market, recently closing at its all-time highs, is better than all the other alternatives out there.
This may be true; many feel the recent run-ups we’ve been seeing are simply the result of cost-cutting. Maybe, however, there’s more at play. Maybe the rising prices we’re seeing on our month-end statements, just like those we see at the gas pump and the grocery store, are also the result of an inflated currency.
The U.S. has been pursuing a weak-dollar policy for more than a decade in an effort to spur foreign demand for American products, hoping to help American industry by increasing exports. This, in combination with increased borrowing to fund an ever-increasing debt, has lead to inflation numbers that could be far different from what we’re told. While most of us see prices going up at the gas pump and grocery store, the inflation rate many retirees see in their Social Security checks doesn’t seem to keep pace. This is because the inflation rate most of us experience is reflected by the CPI-U index, reflecting prices in urban areas, while the government computes inflation using the CPI-W index, which places an emphasis on wage inflation – something that doesn’t rise much during a recession and also doesn’t include food or energy numbers. It’s a convenient way to keep government outlays down, too.
However, markets know different. Markets know that record borrowing and historically-high debt levels will likely lead to printing money, in order to repay the debt, at some point.
*U.S. to China: Don’t worry. We’ll repay you dollar-for-dollar.*
*China to U.S.: That’s what we’re afraid of.*
A sea of debt inevitably leading to a sea of currency printing, coupled with a decade-old in-place weak dollar policy brings us back to the inflated currency discussion. If it takes more dollars to buy a gallon of gas or a box of cereal, it will take more to buy the same share of stock; but, will that share of stock be worth more in[ REAL dollars](https://en.wikipedia.org/wiki/Real_versus_nominal_value_%28economics%29 "Real Dollars")?
It probably depends on the index you’re using, especially after taxes. The government is no doubt hoping you’re using the index they like. It’s what gets them re-elected.
Jim
——
Resources:
*Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and An Accredited Investment Fiduciary® in his 21st year of private practice as Founding Principal of* [*The Independent Financial Group*](https://www.jimsmoneyblog.com/page/4/ "IFG Website")*, a fee-only registered investment advisor with clients located in New York, Florida, and California. He is also licensed for insurance as an independent agent underCalifornia license 0C00742. IFG helps specializes in crafting wealth design strategies around life goals by using a* *proven planning process* *coupled with a cost-conscious objective and non-conflicted risk management philosophy.*
**Additional IFG Links:**
Follow Jim on Twitter: @JimLorenzen
[Jim’s MoneyBlog](https://indfin.com/jim-blog/)
Jim on [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim on LinkedIn")
IFG on [Facebook](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
*The Independent Financial Group is a Registered Investment Advisor providing fee-only financial planning and investment advisory services with a focus on retirement.* IFG does not provide legal or tax advice and nothing contained herein should be construed as securities or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Fraudsters Targeting Seniors Chasing Yield](https://indfin.com/fraudsters-targeting-seniors-chasing-yield/)
**Published:** September 9, 2014
**Author:** Jim Lorenzen
**Content:**
Whenever there’s a crowd chasing a solution, there’s a fraudster willing to take their money.
While inflation has found people at the gas pump and the grocery line, the increased income inflation is supposed to provide has not found its way into Social Security payouts. This has resulted in many seniors searching desperately for high yield; and, the more desperate they are, the more the fraudsters like it.
The August issue of Retirement Advisor magazine cited a new investor alert from The Financial Industry Regulatory Authority (FINRA) that lists some “red flags” worth noting:
Watch out for CD offers that may be fraudulent. Some examples:
- Interest rates are significantly higher than average. Remember, CDs are from banks and all banks operate in the same economy everyone else does. In addition, they have to meet stringent [reserve requirements](https://en.wikipedia.org/wiki/Reserve_requirement "Reserve requirement") and are subject to audit. There’s no free lunch.
- Emails coming to you with an originating address not from the institution cited in the promotion.
- Emails that contain misspellings or grammatical errors;
- Promotions from a U.S. financial institution claiming to be affiliated with an international bank;
- Promotions that are good “for a limited time only”; and
- Promotions that claim to be directed at “best customers” and that require extremely high minimum investments.
In addition, watch out for the phone scammers, as well. While many may be selling “too good to be true” investments – a huge red flag all by itself – there are others that aren’t selling anything.
My wife, for example, has family in Mexico. She recently received a call from someone claiming to be her nephew. He was being held by a Mexican gang demanding ransom! While he was on the phone with my wife, his cohort was on the phone with my wife’s mother (in her 90s) obtaining all kinds of personal information that could be used to verify his identity to my wife! It almost worked until my wife began asking questions that stumped him – he was calling from Mexico, so there was little our local police could do.
It’s good to be wary.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [The Federal Debt Solution](https://indfin.com/the-federal-debt-solution/)
**Published:** October 16, 2012
**Author:** Jim Lorenzen
**Content:**
**If history is any guide, we may already know the answer.** **Politicians will take the easy way out.**
Given the increasing deficits, the outlook for growth is problematic. It would appear there are three available options. Which one do you think the politicians will choose?
(1) Reduce the level of debt, i.e., reduce spending; or
(2) A combination of higher taxes and reduced spending; or
(3) inflation.
Since politicians can’t seem to get agreement on either of the first two, don’t be surprised if inflation will be the “solution” – the one that will bear no one’s finger prints and allow everyone to blame the other in their next re-election campaign… it’s always good to have another issue in your back pocket, you know.
**Inflation is a common solution**. One study has found that in the past 400 years, inflation has been the most common way that governments have dealt with excessively high levels of debt.[\[1\]](https://jimlorenzen.wordpress.com/wp-admin/post-new.php#_ftn1) The reasons stated above help explain why. Those of you who’ve been following my pontifications over recent years may remember my going on about this issue before. The short version: Look for the U.S. to simply print money and inflate the currency to repay the debt – and taxpayers will be left paying for their spending to buy re-election. While the Main Stage debate will be over tax brackets and deductions, who pays, etc., the real action will be off to the side out of sight: Hidden taxes through higher prices, taxes buried inside the higher prices, fees we don’t know we’re being charged.
**My guess:** Expect average growth and above average inflation as countries around the globe attempt to deleverage by engaging in competitive devaluation to rebuild their economies. The U.S. may be attempting to win that race. This could be a five-year window – maybe more; I doubt it will be less.
Jim
—————-
[1] Carmen Reinhardt and Ken Rogoff paper, *“Debt Overhangs: Past and Present”*

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [The Benchmark Myth](https://indfin.com/the-benchmark-myth/)
**Published:** November 6, 2012
**Author:** Jim Lorenzen
**Content:**
We’ve all heard it. We’ve all read it. Most managers fail to match, let alone beat, the market. Actually, it makes sense! And, there’s a very simple reason for this, which comes in two parts.
First, if you believe – probably rightly so – that institutional managers of giant pension plans, mutual funds, etc., actually comprise most of the trading volume, then you begin to realize the managers ARE the market.
So, if they ARE the market, why is it half of them don’t perform above the average and half below? That brings us to the second reason: Expenses.
Indexes don’t have expenses. You can’t even buy an index. You can buy An index mutual fund or exchange-traded fund (ETF) that replicates an index, but not the index.\\
Managers, however, are judged on portfolio net-asset-value (NAV) – the value after expenses.
Let’s use an example you experience every day: Your house.
Suppose you bought a house for $250,000 and it appreciated in value right along with the overall housing market at 5% per year for 13 years. Did you tie the market?
Now, let’s use some assumptions you would have to take into account to report YOUR performance:
1. Property taxes are and remain at 1% per year
2. Insurance is only 0.5% of value each year
3. Maintenance is less than 1% and rises at 3% per year
4. Final selling costs are only 3%
5. Moving costs, loan interest expenses, and cash flow loss is ignored.
What does your performance look like?
Year**$250,000**Prop TxsIns. Exp.Maint.**Sell****Value**1$262,500$2,500$1,313$2,400$256,2882$275,625$2,500$1,378$2,472$269,2753$289,406$2,500$1,447$2,546$282,9134$303,877$2,500$1,519$2,623$297,2355$319,070$2,500$1,595$2,701$312,2746$335,024$2,500$1,675$2,782$328,0677$351,775$2,500$1,759$2,866$344,6518$369,364$2,500$1,847$2,952$362,0659$387,832$2,500$1,939$3,040$380,35310$407,224$2,500$2,036$3,131$399,55611$427,585$2,500$2,138$3,225$419,72212$448,964$2,500$2,245$3,322$440,89713**$471,412**$2,500$2,357$3,422$14,142**$448,991** The market did 5% per year; but YOUR record was 4.6% per year.
Your record looks like it’s 0.4% below market, right? It’s actually 8% below the market performance (5% – 8% of 5% = 4.6%).
Your house tied – you didn’t.
Now you know why my most managers don’t outperform the index. Collectively, they are the index; but they have expenses, too.
Jim

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Are Risk Questionnaires A Waste of Time?](https://indfin.com/are-risk-questionnaires-a-waste-of-time/)
**Published:** November 8, 2012
**Author:** Jim Lorenzen
**Content:**
**Are these things worth anything? … or nothing.**
Risk questionnaires have played a major role in retirement and investment planning for as long as I can remember; and I’ve used them no less religiously than any other advisor. Frankly, I’ve always felt they were a little stupid.
Elmer Duckhunter walks into Brainy Smartsuit’s office at Behemoth Securities. It’s a beautiful place, full of mahogany with lots of beautiful brochures in the lobby. Brainy has been successful at Behemoth, gaining promotion to Sr. Vice President after selling more Secure Your Future product than anyone else in the office using the “Secret in a Box” software supplied by the product wholesaler.
“How can I help you?”, Brainy asks.
“Well,” says Elmer, “I have a lot of money from all those Tractor Pulls I won and I think it’s time I began investing for my future. What should I invest in?”
“I think I can help you, but first I have to know more about you!”
“Makes sense. What do you want to know?”
Brainy pulls out the Behemoth Risk Assessment questionnaire. “First, I’d like to know a little about how you feel about investing.”
“Okay.” Elmer settles in. “How many questions are there?”
Brainy smiles, “Just six.”
“Six? You can learn everything you need to know about me with just six questions?”
“Trust me. This is very scientific, “says Brainy.
“Okay.”
Brainy begins. “On a scale of zero to 10, how much risk do you feel you can handle?”
“I don’t know. What would a ‘five’ feel like?”, asks Elmer.
“Just pick one that you feel comfortable with, says Brainy. “The people who prepare these know what they’re doing.”
Elmer thinks for a second. “Well, back in 2007 I was a 9, but after the crash I was a 2. Now, I don’t know what I am. That’s why I’m here!”
“Well, I can’t tell you how much risk to take until you tell me how much risk you want; then, I can tell you what you told me and we’ll have the answer!”
“Huh?”
They both look at each other, then Elmer continues, “How much risk do I want? Seems to me you should be telling me how much risk I need or don’t need!”
“But what if it’s more than you want?”, asks Brainy.
“I don’t know how much I want. I need to know how much I should or should not have?
Brainy perks up. “Now we’re getting somewhere. What are your goals?”
“Simple”, says Elmer, “to retire with as much money as possible with as little risk as necessary.”
“How much is that?”
“How should I know? You tell me.”
Brainy senses a lack of forward progress. “Let’s come back to that. Try this one: If your portfolio went down, what would you do?”
“I’d probably ask you for advice! Isn’t that your job?” Elmer’s beginning to wonder if Brainy Smartsuit is so smart after all. “Why are you asking me all this. I just want to know what I should be doing!”
Brainy comes clean. “We have regulatory compliance concerns. We have to make sure what we recommend is consistent with how you feel about investing.”
“I’d rather have advice that’s consistent with what I need,” says Elmer. Are you protecting me or your firm?”
“Well, actually, both…”
“There are six of these?” Elmer’s fed up. He puts on his duck hunter cap with earflaps, and stomps out of the office.
Maybe these questionnaires can shed some light about attitudes; but, they don’t tell Elmer what he needs to know. Elmer just wants to know what he should be doing and why. Once he understands what and why, the rest gets easier. Fear can exist only where there’s a knowledge vacuum. When knowledge replaces ignorance, fear dissipates and understanding prevails. Maybe questionnaires have zero to do with long term success for the client; but, they maybe do help sell more Secure Your Future product.
———————————
– See more at: https://www.jimsmoneyblog.com/2012/11/are-risk-questionnaires-a-waste-of-time.html#sthash.UkHUmfR1.dpuf

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Company Stock and NUA](https://indfin.com/company-stock-and-nua/)
**Published:** November 12, 2012
**Author:** Jim Lorenzen
**Content:**
**Getting ready to retire?** **Leaving your company?** Wondering whether you should sell or roll-over your company stock? That’s really a tax-treatment question, which means you should consult with your tax professional; but, here’s a little information you may want to review.
**What you should know:** Shares of employer stock get special tax treatment, and in many cases, it may be fine to ignore this special status and roll the shares to an IRA. This would be true when the amount of employer stock is small, or the basis of the shares is high relative to the current market value. However, if you have large amounts of shares or low basis, it might be a very costly mistake not to use the Net Unrealized Appreciation (NUA) Rules.[\[1\]](https://jimlorenzen.wordpress.com/wp-admin/post-new.php#_ftn1)
If your company retirement account includes highly appreciated company stock, one option is to withdraw the stock, pay tax on it now, and roll the balance of the plan assets to an IRA. This way you will pay no current tax on the Net Unrealized Appreciation (NUA), or on the amount rolled over to the IRA. The only tax you pay now would be on the cost of the stock (the basis) when acquired by the plan. By the way, if you withdraw the stock and are under 55 years old, you have to pay a 10% penalty (the penalty is applied only to the amount that is taxable). So, you can then defer the tax on the NUA until you sell the stock. When you do sell, you will only pay tax at the current capital gains rate, whatever it is at that time. To qualify for the tax deferral on NUA, the distribution must be a lump-sum distribution, meaning that all of the employer’s stock in your plan account must be distributed.
**Hypothetical Example:** Jackie just retired and has company stock in her profit sharing plan. The cost of the stock was $200,000 when acquired in her account, and is now worth $1 million.
- **The Rollover Option**: If she were to rollover the $1 million to her IRA, the money would grow tax-deferred until she took distributions. At that time, the withdrawals would be taxed as ordinary income – for this hypothetical, let’s assume 35% federal. When Jackie dies, her beneficiaries would pay ordinary income tax on all of the money they receive.
- **Withdrawing the Stock**: But if Jackie withdrew the stock from the plan rather than rolling it into her IRA, her tax situation would be different. She would have to pay ordinary income tax on the $200,000 basis. However, the $800,000 would not be currently taxable. And she would not have to worry about required minimum distributions on the shares. If she eventually sells the stock, she would pay the lower capital gains tax on the NUA and any additional appreciation.
Jackie’s beneficiaries would not receive a step-up-in-basis for the NUA. However, they would only pay at the capital gains rate. Appreciation between the distribution date and the date of death would receive a step-up-in-basis (we’ll assume a 15% capital gains rate); therefore would pass income tax-free.
**With NUA****Without NUA**35% Tax on $200,000$70,00035% Tax on $1 million$350,00015% Tax on $800,000$120,000Total Tax$190,000$350,000
Let’s assume the stock value increases to $1.5 million in five years, and she decides to sell.
**With NUA****Without NUA**Taxable Amount$1.3 million$1.5 millionTax Rate15%35%Potential Income Tax to Jackie$195,000Plus Amount Previously Paid$70,000Total Tax$265,000$525,000
Finally, assume that Jackie died in five years after the stock increased to $1.5 million. What would her beneficiaries have to pay?
**With NUA****Without NUA**Taxable Amount$800,000$1.5 millionTax Rate15%35%Income Tax$120,000$525,000Amount Receiving Step-Up in Basis$500,000\*0
\*Because 2010 is a transition year with estate taxes, there is a limit on the step up in basis of $1.3 million for capital gains.
Okay, now you know enough to be dangerous. Next step: Meet with your tax professional to (1) check for any possible tax law changes, and (2) plug-in your own numbers and tax rates, and (3) discuss any complicating issues this piece isn’t considering. I have a report, entitled *“Six Best and Worst Rollover Decisions”* available and there’s a link to it in our ezine that covers this topic. You’ll find it in our *Insights* archive. You might want to [subscribe](https://tinyurl.com/IFGInsights)

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Three Retirement Rollover Mistakes to Avoid](https://indfin.com/three-retirement-rollover-mistakes-to-avoid/)
**Published:** November 12, 2012
**Author:** Jim Lorenzen
**Content:**
**Planning to retire? Contemplating a rollover?** Here are three ways NOT to do it.
**1. Get a check from the company**
Of course, this is just foolish. The company must withhold 20% from the payment, so that a person with a $100,000 account will have $20,000 withheld, and will receive a check for $80,000. In order to complete a tax-free rollover, the taxpayer must deposit that $80,000 in an IRA plus $20,000 from their pocket to complete a tax-free $100,000 rollover. The taxpayer may eventually get the $20,000 withheld as a tax refund the following year, but that will not help their cash flow, as they need to complete their IRA rollover within 60 days of receiving the check from their qualified plan. The bottom line is that people should never touch their qualified funds. The only sensible way to move funds is a direct transfer from the qualified plan to the IRA custodian and avoid withholding.
**2. Rollover company stock**
Shares of employer stock get special tax treatment, and in many cases, it may be fine to ignore this special status and roll the shares to an IRA. This would be true when the amount of employer stock is small, or the basis of the shares is high relative to the current market value. However, in the case of large amounts of shares or low basis, it would be a very costly mistake not to use the Net Unrealized Appreciation (NUA) Rules.[\[1\]](https://jimlorenzen.wordpress.com/wp-admin/post-new.php#_ftn1)
If your company retirement account includes highly appreciated company stock, an option is to withdraw the stock, pay tax on it now, and roll the balance of the plan assets to an IRA. This way you will pay no current tax on the Net Unrealized Appreciation (NUA), or on the amount rolled over to the IRA. The only tax you pay now would be on the cost of the stock (the basis) when acquired by the plan. If you withdraw the stock and are under 55 years old, you have to pay a 10% penalty (the penalty is only applied to the amount that is taxable). IRA owners can then defer the tax on the NUA until they sell the stock. When you do sell, you will only pay tax at the current capital gains rate. To qualify for the tax deferral on NUA, the distribution must be a lump-sum distribution, meaning that all of the employer’s stock in your plan account must be distributed.
**3. Rollover after-tax dollars**
Sometimes, qualified plan accounts contain after-tax dollars. At the time of rollover, it is preferable to remove these after-tax dollars, and not roll them to an IRA. That way, if the account owner chooses to use the after-tax dollars, he will have total liquidity to do so. You can take out all of the after-tax contributions, tax-free, before rolling the qualified plan dollars to an IRA. You also have the option to rollover pre-tax and after-tax funds from a qualified plan to an IRA and allow all the money to continue to grow tax-deferred. The big question is, “will you need the money soon?” If so, it probably will not pay to rollover the after-tax money to an IRA, because once you roll over after-tax money to an IRA, you cannot withdraw it tax-free. The after-tax funds become part of the IRA, and any withdrawals from the IRA are subject to the “Pro Rata Rule.”
The Pro Rata Rule requires that each distribution from an IRA contain a proportionate amount of both the taxable and non-taxable amounts in the account. The non-taxable amounts are called “basis.” In an IRA, the basis is the amount of non-deductible contributions made to the IRA.
————–

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [How Much Is That $1 Coupon Really Worth?](https://indfin.com/how-much-is-that-1-coupon-really-worth/)
**Published:** November 14, 2012
**Author:** Jim Lorenzen
**Content:**
Retirement success may not be as easy to achieve as many think. I attended a conference and heard one speaker relay a story about one company’s 401(k) enrollment meeting where 100% – yes, everyone – said they wanted to enroll in the company’s 401(k) plan. They all were going through the materials and even choosing allocations they felt were appropriate – and all them were excited about starting to save for their retirement!
Would you like to guess how many actually followed through and actually participated? 3%. That’s right; only three in one hundred actually did it.
Education didn’t seem to help, at least in that particular case, despite all the glowing post-meeting comments. Benjamin Graham, the ‘dean’ of value investing who taught Warren Buffett at Columbia University, once said that behavior, more than investment choices, represent the largest impediment to financial success for most Americans; and the data seems to bear that out. Poor savings habits, poor investor performance due to behavior, and paralysis often due to too many choices create roadblocks many have trouble overcoming.
Maybe the best gauge of investor success (or failure) might be whether they are ‘on track’ to a successful retirement, which some define as replacing 75% of preretirement income at age 67.
According to one study – I think it was conducted by Mass Mutual – revealed that *only 15%* of American workers are ‘on track’. Even without my HP12-C, it’s obvious it obvious then that 85% are not.
It’s not rocket science. It’s about three simple components: time, savings rates, and return. But, time is the only component that constantly declines; and, as it does, it creates pressure on the other two to outperform. That’s when mistakes are likely to happen.
When procrastination behavior reduces the available time, most of the pressure then falls on investment return, simply because most people feel limited regarding how much they can save.
This may be why some people reach a point where they begin making the risky choices they soon live to regret. Investment mistakes can be committed by anyone – I even once met a CPA who didn’t know the difference between gain and yield.
But then, you wouldn’t want me doing your taxes, either.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [New Tax Rates - New Game Plan for 2013](https://indfin.com/new-tax-rates-new-game-plan-for-2013/)
**Published:** February 14, 2013
**Author:** Jim Lorenzen
**Content:**
**Higher Tax Rates**
You probably know we now have a new restored 39.6% top marginal tax bracket for high earners. Those people will also be paying a 20% rate on both capital gains and dividends; but, there’s more: These are the people who very likely will be paying an additional 3.8% Medicare tax on investment income.
I’ll spare you all the details on this – you should talk to your CPA – but, the big change may be in the estate tax threshold – potentially $10.24 million for a couple, and inflation indexed for future years.
What this means is that while life insurance, long offered as a tax-favored envelope to protect investment dollars, substantially enhances the benefit of investment buildup inside an insurance wrapper. With the estate tax threshold so much higher than before, the estate tax rationale for insurance trusts now doesn’t seem to apply to most people today.
A technique previously frowned upon by most estate planners now may be worth a look: Purchasing life insurance inside a retirement plan. This allows pre-tax dollars to fund premiums. Previously, estate planners were worried about the inclusion of life insurance proceeds in the insured’s estate. This is no longer an issue for those under the exemption amounts.
Another technique, bypass trusts, may also introduce more complexity – titling assets, dealing with a trustee, filing trust income tax returns, etc. – than most will want or need going forward, especially since the threshold is now indexed for inflation. There are still state estate tax issues, as well as divorce/marriage risk and other issues that estate planners feel should be addressed, and rightly so; but, given the fact that many high-net-worth individuals who gifted most or all of their exemption amounts in 2012, setting up trust for modest assets may or may not be cost effective.
To know where you stand, talk to your estate attorney and CPA.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Commissions or Fees: Which is Cheaper](https://indfin.com/commissions-or-fees-which-is-cheaper/)
**Published:** February 21, 2013
**Author:** Jim Lorenzen
**Content:**
**You guessed it: It depends**.
You can ask ten people and get ten different opinions about this issue; but, after more than twenty years in this business – having begun in a Wall Street big name `wire house’ and gradually changing my business model from stockbroker to independent broker to independent planner/broker to independent planner/broker/advisor to independent planner/advisor and having spoken with hundreds of other advisors over the years at scores of industry conferences and conventions – this is my own humble opinion**:**
**There’s no one right answer. There’s only the one that’s best for YOU.**
You have to do some analysis – and it helps if you can use a computer spreadsheet. But, it might be worth remembering what your parents probably told you many years ago: There is no free lunch.
If you’re thinking of using a financial advisor to get investment help, it should come as no surprise they will be compensated. Typically, this is what you can expect to find:
- **Registered investment advisors (RIAs)** charge fees and have fiduciary status, so must perform to a fiduciary standard, i.e., recommendations must be in the best interest of the client.
- **Registered representatives (RRs)** – You know them as stockbrokers and others who may be independent ‘advisors’ or ‘consultants’ – sell investment products and earn commissions. They use a ‘suitability’ standard, i.e., as long as the recommendation is suitable, it passes the test.
- **Dually-registered as both RIAs and RRs**. Typically, they tout the fiduciary ‘standard’ during the planning stage, but often switch to the ‘suitability’ standard during the recommendation and implementation stage.
What’s best? Hype and arguments aside, I personally don’t believe most advisors’ integrity is dictated by the form of their compensation. It’s a factor to consider, of course, but I wouldn’t make it a deciding factor. There are many quality competent advisors operating within each of these business models.
Each model has its advantages and disadvantages. While I believe the fee model may present fewer obstacles to portfolio rebalancing, the commission model often makes it possible for smaller investors – people who may be less likely to pay fees – to get the help they want.
Back to our original question: Which model is most cost effective when using an investment advisor.
Take a look at your portfolio size and compare what the fee advisor is charging against what the commissioned rep is selling.
**Example #1: Suppose you have only $50,000 and you want a growth fund.**
- **The commission approach:** It wouldn’t be uncommon or surprising to see a load of between 3-5% for this sale. So, if the load were 4%, the client would be paying a $2,000 commission up front. It wouldn’t be a surprise to see ongoing 12b-1 fees of 0.25% annually ($125, assuming no growth) which, frankly, is pretty reasonable annual compensation to have a rep answering questions and servicing the account. The upfront commission provides compensation for all the up-front work, including the account opening.
- **The fee option:** It’s become common for many, certainly not all, advisors to charge somewhere in the neighborhood of 1% of assets annually – this usually depends on the size of the portfolio – and then go DOWN as the asset levels increase.Back to our $50,000 client: I think it’s fair to say few fee-only advisors would look forward to doing all the initial planning and research – and paperwork, including compliance issues – for $500, and then have to wait a full year to be paid in full. This is the reason many fee-only advisors charge planning fees; but how many people with $50,000 would pay the freight? Not many I think.
**Example #2: Suppose you have $600,000 in your nest-egg and need help**
- **The commission approach.** This can get dicey. In the commissioned world, it wouldn’t be surprising to see `free’ planning services result in a recommendation of fully-disclosed low-cost investment products mixed with some undisclosed (hidden) high-cost products. I know people personally who, in their past, had invested as much as $1 million with a commissioned broker, having no idea they’d actually paid as much as $40,000 in hidden commissions up front – in the first 90 days – simply because many of the products looked ‘free’ to them! There was no charge for planning. Yes, unfortunately, this does happen.I doubt the above experience is the `norm’ but, let’s face it: If only 20% of your $600,000 account is placed in products with undisclosed hidden costs and paying 6% commissions, you’ve paid $7,200 in front on just 20% of your assets… that’s 1.2% of all of your invested assets right there! Even if the balance of the portfolio carried only a 1% charge, you’re still paying a total of $12,000 in the first year on your $600,000 portfolio – about 2% of assets.**Is all this bad? It depends.** The investment products you receive just may be worth it! And, let’s face it, quality planning for that size portfolio, even with sophisticated software, still takes time simply because the investment screening requires more than simple button-pushing.
The point is you should KNOW what you’re paying and what you’re getting so you can make an informed decision. It’s also important – I think – to know if the products and managers involved are proprietary (in house) or from third-parties. It’s also good to know what other products and managers were screened-out by the advisor and why. Remember: Two identical products might pay two different commissions.
- **The fee approach.** Generally not as dicey because of the straightforward service agreement with fully-disclosed charges with no product sales. But, still, RIAs differ in their charges and services. Some will charge a one-time retainer to do your plan as well as an annual advisory fees for ongoing management oversight and portfolio consulting. Others may not charge for the plan but will likely require a higher asset minimum to justify the time and may require that assets be placed on deposit before any work begins.
If there’s a planning retainer required, the amount will often depend on the complexity of the plan and the time involved. Annual advisory fees can also vary, depending on the firm’s asset minimum. Wherever they begin, the annual fee generally goes down as assets increase.
Each RIA sets its own fee schedule, but you will find that most RIAs take pride in providing complete transparency and full disclosure. Since they’re not compensated by commissions, they use non-commission investments and also like to use institutional money managers for the value they can often add. One of the benefits of institutional management is that their charges typically go down (as a percentage of assets) as portfolio value increases – something that doesn’t occur in mutual funds. If you’d like to learn more about mutual fund costs, you can [download our report here](https://jimlorenzen.advisorwebsite.com/understanding-mutual-fund-landscape "IFG Mutual Fund Report").
Any questions? Use the email link!
[](https://jimlorenzen.typepad.com/.a/6a017c332c5ecb970b017d412f115e970c-pi)
Follow Jim and IFG on
- [Twitter](https://twitter.com/JimLorenzen "Jim Lorenzen on Twitter")
- [Facebook](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® and an ACCREDITED INVESTMENT FIDUCIARY® in his 21st year of private practice as Founding Principal of THE INDEPENDENT FINANCIAL GROUP, a fee-only registered investment advisor with clients located in New York, Florida, and California. IFG provides fee-only financial and retirement planning, as well as investment advisory and wealth management services for individual investors. IFG also does not provide tax or legal advice. Content contained herein represents the author’s opinion and should not be regarded as investment advice which is provided only to IFG clients upon completion of a written plan.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Inflation Is Sneaky; The Hazards Can Be Significant!](https://indfin.com/inflation-is-sneaky-the-hazards-can-be-significant/)
**Published:** February 26, 2013
**Author:** Jim Lorenzen
**Content:**
**Inflation is like glaucoma**.
You can’t see it on a day-to-day basis, but the erosion of purchasing power is still there. Do you remember when $50,000 a year was a lot of money and $5,000 would buy a luxury car? I do (okay, I also remember double-knits).
**My dad retired in 1974 and lived 32 years in retirement!** Suppose he had $800,000 on the day he retired and someone had sold him a guaranteed 5% investment that would pay him $40,000 annually for the rest of his life. That would have looked pretty good to many people in 1974 – $40,000 wasn’t peanuts back then – but after 20 years of inflation, that $3,333 per month BEFORE taxes, wouldn’t have looked so good – even at only a 3% rate, the purchasing power by 1994 would have dropped to $1,845 per month – and he would STILL go on to live more than another decade! More on that later.
Consider a 54-year-old widow who puts $2,500,000 into a guaranteed fixed-income investment yielding 4%. A $100,000 a year income sounds pretty good and the money is considered safe! But, let’s examine the situation in the real world.
**The Impact of Inflation**
Widow, age 54, 30-year life expectancy
Assumptions:
- 4% Interest Rate
- 3% Inflation Rate
- $2,500,000 invested
(A)(B)(C) = A x BCapitalInterestRealYearPurchasing PowerRateYieldNow$2,500,0004%$100,00010$1.860,2354%$74,40911$1,384,1894%$55,36812$1,029,9674%$41,199*Source: Asset Allocation, Roger C. Gibson, McGraw Hill, 4th Edition.*
The chart above shows what really would have happened. As you can see, our widow’s `safe’ money was worth less and less – and the same thing happened to the purchasing power of her income from interest. At twenty years – by the way, have you noticed people are living longer? – with maybe still a decade ahead of her, her income was worth just over half what it used to purchase; and the same was true for her principal.
And, we didn’t even factor-in taxes. That would be too scary.
What if this widow experienced what my dad did: *Hyper-inflation* with rising interest rates, which we experienced in the late 1970s. Many may not remember when money market accounts were paying 17% in some places and inflation was running in the teens; not a good time to be stuck in a guaranteed 4%.
**Back to our widow:**
Was her income certain? Yes.
Was the outcome certain? Yes, that too.
Does this mean no one should buy annuities? Of course not. Annuities can and do serve a valuable function in a retirement mix; but, remember, they should serve as a *component* of the solution, not the answer.
**How about stocks?**
It also depends because it seems quite often investors seem to be their own worst enemy – hurt more by their behavior than their investments.
DALBAR, Inc., a Boston-based firm that provides research to the financial industry published an often-cited study entitled, “*Quantitative Analysis of Investor Behavior*”, which compared the track-record of the average investor in equity mutual funds to that of the S&P Index of U.S. large company stocks for the 20-year period between 1986 and 2005. Based on the timing of contributions to and withdrawals from equity mutual funds, the average equity mutual fund investor earned just 3.9% while the S&P Index had an average annual return for the same period of 11.9%.
That 8-point spread represents a 67.23% under-performance – they did only 1/3 as well as the index! The major reason: The study found that investors tend to chase performance, which by definition is always past – but it’s good for the tv ratings of the investment gurus. But, look on the bright side, they apparently saved a point or two by not getting help.
So, how does the average investor protect against inflation and taxes while still not exposing his/her portfolio to an unacceptable level of volatility… and still maintain the level of liquidity required to live comfortably and remain prepared for emergencies?
The easy answer doesn’t exist; but, a workable solution likely does. My recommendation: Locate and talk with a *CERTIFIED FINANCIAL PLANNER*® professional. If you want to work with one that’s local to you, you can [find one here](https://www.cfp.net/utility/find-a-cfp-professional "CFP Board CFP Locator"). You may also be interested in our report, ***[Why Most Retirement Planning Often Fails](https://jimlorenzen.advisorwebsite.com/why-retirement-planning-can-often-fail%20 "IFG Report: Why Retirement Planning Often Fails")***.
Jim
[](https://jimlorenzen.typepad.com/.a/6a017c332c5ecb970b017d412f0dac970c-pi)
Follow Jim and IFG on
- [Twitter](https://twitter.com/JimLorenzen "Jim Lorenzen on Twitter")
- [Facebook](https://www.facebook.com/IFGAdvisory "IFG on Facebook")
*Nothing contained in this material is intended to constitute legal, tax, securities, or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional. Nothing contained herein is an offer or recommendation to purchase any security or the services of any person or organization.*

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [Ten Tips for Retiring Rich](https://indfin.com/ten-tips-for-retiring-rich/)
**Published:** February 28, 2013
**Author:** Jim Lorenzen
**Content:**
***“Money may not be too important to you, pal; but, to me, it ranks right up there with oxygen.***
***Ruth Gordon***
***Former Actress***
It’s a funny line – and there’s a certain ring of truth to it; after all, no one wants to live a life of worry and insecurity in their later years; But, rich and wealthy are two different things. While both are possible, I think most people would say that freedom from worry, coupled with living a full and rich life, would rank pretty high.
So, what does constitute success? Based on my noticing what smart people do, here are my *Ten Tips*:
**\#1 – Money really doesn’t buy happiness.**
Most young people don’t buy into this but most of the rest of us begin to understand it more as time goes by. You really don’t need $50 gazillion! In fact, many people begin to get rid of a lot of ‘baggage’ as they get older. There’s nothing wrong with simplifying your life and many are indeed happier!
**\#2 – Wealth accumulation is more a result of your choices than your investments.**
W. Clement Stone started out as a 7-year-old selling newspapers on a street corner to help support his single mother and younger brothers. He ended-up as Chairman of Combined Insurance Companies of America and gave millions to charity from his own pocket. He once said, “Successful people are those who’ve acquired the habit of doing the things unsuccessful people don’t like to do.”
He knew that luck was the result of hard work. Most successful people know it’s not how much you make; but how much you KEEP that makes you wealthy. While others spend lavishly on cars and vacations, the key to true riches is to pay yourself first and make your money work for you.
**\#3 – Plan for success or plan for failure – There’s no third choice.**
Those who fail to plan are planning for failure. Every successful business owner or executive knows that a plan kept in your head is worthless. Plans must be in writing. Not that paper makes it work; but, it’s a reflection of the person who is serious enough to actually complete the process. Good plans identify where you are, where you want to go, and how you want to get there. It’s no different for individuals. You are the President and CEO of YOU, Inc. Success or failure depends on your planning and your management.
**\#4 – Begin saving early.**
My dad told me when I was ten, “Jim, I know you won’t do this; but if you save just 10% of everything you ever earn, you’ll never have to worry about money as long as you live. He was right twice.
**\#5 – You can’t enjoy retirement if you’re dead.**
Take care of yourself. Live a balanced lifestyle with time for exercise and fresh air. Don’t neglect medical check-ups! Jack Nicklaus won 18 professional majors and finished second 19 times; that’s 37 times being 1st or 2nd in majors!!! – Match THAT, Tiger! But, that’s only half the story. He did it playing a limited schedule for most of his career, playing as few as 15 events in some years! While other golfers, like Lee Trevino who was in the field almost every week, would question how many he would have won if he’d played full time, Nicklaus always answered by saying it was the time-off that kept him fresh, up, and wanting to play! He said that each year he’d block-out his calendar in this order: Family time got blocked first. Then, the remaining time was blocked for business and golf, prioritizing the events and projects. That way, he said, he never got `burnt out’. Not a bad lesson.
**\#6 – A quality life is surrounded by quality people.**
If your parents were like mine, they said, “If you want to know who you are, just look around and see who you’re with.” Positive people don’t hang around with negative people. Honest people don’t associate with dishonest people. In short, quality people enhance your life with interests, ideas, and positive attitudes and influences. Negative people only sap your strength; and do little to enhance your well-being.
**\#7 – Invest like a millionaire**
Ask any 10-year old, “Would you like to invest like a millionaire or a poor person. Don’t worry, you’ll get the correct answer. Unfortunately, the parents all too often continue to invest like poor people. What’s the difference? A millionaire will carefully choose an advisor who has no conflict of interest, then, with the advisor, create a `business plan’ and hire institutional managers to follow a strict investment discipline, always taking a long term view keeping costs low and expectations realistic. The poor person is likely to find a broker and buy some “hot” individual stocks, thinking the broker has some special insight that everybody else on Wall Street is too dumb to recognize. Even worse, the poor person might think HE has some special sight Wall Street lacks and does his own trading, hoping to hit the jackpot. I actually know of a family that lost their life savings and their home because the husband was convinced the system he’d picked up in a seminar would work. Even after losing everything, he told me, “Jim, I was just getting it! If I only had a little more money to work with, it would have worked.” I could only shake my head. Who did he think he was talking to?
**\#8 – Keep active – Mentally and physically**
Those who stay mentally and physically active – and around people who do the same (see #6) – live longer and stay healthier. Whether it’s a hobby – or three – or reading and socializing while taking walks, the more active your mind and body are, the greater your quality of life.
**\#9 – Forget the word `retirement’**
Some of the happiest people I know may have quit their formal jobs; but virtually all would have little trouble making a list of 100 things they would love to do if they had the time: Books to read, places to go, people to see, etc. They know tomorrow is promised to nobody. My dad and all his friends `retired’ to Florida back in the early 1970s; but none of them actually retired. All of them were busier down there than they ever were during their ‘working’ years. One of them, a `retired’ prominent radiologist from Johns Hopkins, even continued reading x-rays that were sent overnight to him on a daily basis! My dad, a `retired’ electrical engineer, began writing articles for dozens of industry publications. Even Warren Buffett, who just turned 80, can’t see himself doing nothing.
**\#10 – Giving back**
Smart people already know this: You probably have something to give you haven’t given yet! It might be money. It might be time or volunteer work. It might be a helping hand. One of my dad’s fellow `retirees’ got involved with *Meals on Wheels* and truly enjoyed it! You might enjoy being around young people through little league baseball or helping area youth through involvement in a civic organization. It might be as simple as the gift of listening.
[](https://jimlorenzen.typepad.com/.a/6a017c332c5ecb970b017d412f1e79970c-pi)Jim Lorenzen is a *CERTIFIED FINANCIAL PLANNER*® and an *ACCREDITED INVESTMENT FIDUCIARY*® in his 21st year of private practice as Founding Principal of The Independent Financial Group , a fee-only registered investment advisor with clients located in New York, Florida, and California. IFG provides fee-only financial and retirement planning, as well as investment advisory and wealth management services for individual investors. IFG also does not provide tax or legal advice. Content contained herein represents the author’s opinion and should not be regarded as investment advice which is provided only to IFG clients upon completion of a written plan.
Follow Jim on:
- [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp "Jim Lorenzen LinkedIn Profile")
- [Twitter](https://twitter.com/JimLorenzen "Jim Lorenzen on Twitter")
- [Facebook](https://www.facebook.com/IFGAdvisory "IFG Facebook Page")

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
### [The Government May Be Your Partner!](https://indfin.com/the-government-may-be-your-partner/)
**Published:** April 30, 2013
**Author:** Jim Lorenzen
**Content:**
*“A taxpayer is someone who works for the government, but doesn’t have to take the Civil Service Exam.” – Ronald Reagan*
Is the government your partner? If so, wealth preservation may be an issue… expect Uncle Sam to want part of all you worked for when you die.
If you own raw land, a farm, a successsful business, or rental property, be careful; a portion of your estate may be siphoned off to pay federal and state death taxes, as well as fees and final expenses required to administer your estate. Your family then receives what is remaining after these estate settlement costs have been paid. Here’s an illustration of the situation your heirs could face:
**The high cost of dying:**
Federal and State Death Taxes
**<$$$**
**YOUR ESTATE:**
Personal Property
Real Estate
Business Interests
Employer/Government Benefits
Life Insurance
**$$$>**
Estate Administrative Costs
**$$$**
v
**YOUR FAMILY**
**The good news is that with proper advance planning, you can make sure that more of your estate ultimately passes to your family!**
It might be a good time to talk with your financial advisor.
—————–
Opinions expressed are those of the author and nothing contained in this material is intended to constitute legal, tax, securities, or investment advice, nor an opinion regarding the appropriateness of any investment to the individual reader. The general information provided should not be acted upon without obtaining specific legal, tax, and investment advice from an appropriate licensed professional. The Independent Financial Group is a Registered Investment Advisor with offices located at 11707 Blossomwood Court; Moorpark, California 93021. IFG’s Founding Principal, Jim.Lorenzen, is a Certified *Financial Planner*® and an *Accredited investment Fiduciary*®. Mr. Lorenzen is also licensed for insurance as an independent agent under California license #0C00742. Primary asset custodian is Pershing Securities, owned by Bank of New York-Mellon. IFG and Pershing/BNY are not affiliated. Jim can be reached at 805.265.5416 or by emailing info@indfin.com.

Jim Lorenzen
Jim Lorenzen is a CERTIFIED FINANCIAL PLANNER® professional and an ACCREDITED INVESTMENT FIDUCIARY® serving private clients’ wealth management needs since 1991. Jim is Founding Principal of The Independent Financial Group, a Registered Investment Advisor providing wealth management, retirement planning and investment advisory services. Jim's background includes founding, building, and selling five successful businesses and international consulting. He has been headline speaker at more than 500 national and international association and corporate conventions for clients such as Foster Grant, Hobie Cat, CapCities/ABC, H.R. Textron, Hearst Corporation, The National Management Association, the National Newspaper Association, and Cox Communications and has been featured on American Airlines' Sky Radio heard on more than 19,000 flights, as well as in The Wall Street Journal’s SmartMoney magazine, The Profit Sharing Council of America’s Insights; also published in the Journal of Compensation and Benefits, NASDAQ, and in scores of national and international association trade publications. [See Full Bio](https://indfin.com/author/jim_oss/) [ ](https://indfin.com/author/jim_oss/)
**Categories:** Uncategorized
---
## Pages
### [Certified Financial Planner and Fiduciary Advisor](https://indfin.com/)
**Published:** February 25, 2021
**Author:** Jim Lorenzen
**Content:**
### *CERTIFIED FINANCIAL PLANNER® (CFP®) professional*
*and an ACCREDITED INVESTMENT FIDUCIARY® (AIF®)*
*serving pre-retirees and retirees managing the transition to retirement since 1991.*

[ ](https://indfin.com/ifgplanningprocess/)
### [Managing the Transition to Retirement](https://indfin.com/ifgplanningprocess/)
Wealth planning and tax-managed strategies for pre-retirees and retirees.
[ ](https://indfin.com/all-about-ifg/)
### [Independent Fiduciary Advice](https://indfin.com/all-about-ifg/)
All about your fiduciary advisor
Jim Lorenzen, CFP®, AIF®, and the IFG philosophy including answers to most frequently asked questions.
[ ](https://indfin.com/all-about-you/)
### [What are Your Priorities?](https://indfin.com/retirement-priority-planning-review/)
Building an attractive financial future begins with a blueprint.
Let’s begin designing your financial future today!
## Plan with a
*CERTIFIED FINANCIAL PLANNER®* Professional
## Who is *also* a Fiduciary Advisor
 James Lorenzen, CFP®, AIF®
The withdrawal phase in retirement is different from the accumulation phase. During your working years, you just socked money away. But, during retirement there are decisions to make and tax traps to avoid – some of which can not only be unwelcome surprises, but irrevocable, as well. Getting your ducks lined up well in advance can make a big difference in later years.
Whether you’re a pre-retiree or already retired, you can get started today. [Tell me your priorities here](https://indfin.com/retirement-priority-planning-review/) then schedule your introductory call.
**You can begin planning your tomorrows right now!**
[ Schedule Your Introductory Call ](https://go.oncehub.com/JimLorenzenCFP)
## Concerned about navigating the risks in life?
### [Download our
FREE REPORT](https://indfin.com/asset-diversification-report/)
Understanding the Diversification Puzzle
[  ](https://indfin.com/asset-diversification-report/)
### IFG RESOURCES
## Recent Posts
#### [ Don’t Need a Financial Advisor? ](https://indfin.com/dont-need-a-financial-advisor/)
September 9, 2026
Maybe having an independent fiduciary financial advisor is worth having anyway!
[ Read More » ](https://indfin.com/dont-need-a-financial-advisor/)
#### [ When to Claim Social Security? Here’s a Guide! ](https://indfin.com/when-to-claim-social-security-heres-a-guide/)
August 19, 2026
The Decision Is Bigger Than Age 62, 67, or 70.
[ Read More » ](https://indfin.com/when-to-claim-social-security-heres-a-guide/)
## Connect
#### Schedule Your
20-Minute “Right Fit” Introductory Call Now!
[ Schedule Your Call Today! ](https://go.oncehub.com/JimLorenzenCFP)
[ ](https://tinyurl.com/IFGInsights)
[ Join Our Newsletter! ](https://visitor.r20.constantcontact.com/manage/optin?v=001MsaghC2nU2NJckb8N0hCVSZJKePtwK7ckaFMLZWDlZeu36gUwtjYrny9vHm_5tu8jQKSMkEU7tY%3D)
## Tools & Strategies

See our latest industry reports and blog articles! [Click to get started.](https://indfin.com/ifg-resources/)
---
### [Frequently Asked Questions](https://indfin.com/faqs/)
**Published:** September 8, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/09/Z-090521-Lorenzen-0081-cropped-tight.jpg)Jim Lorenzen CFP® AIF®
Welcome to my site!
**My clients value straight talk and clear communications; so, here are some of the questions I hear asked most often – along with the answers – by those thinking of choosing me as their advisor. along with the answers!**
Many people understandably confuse advice with custody. An advisor can choose to be an employee of a large custodial firm – or – an advisor can choose to be a true independent advisor who is free to use any custodial firm s/he choses. The capabilities are the same, however, independent advisors arguably have access to the entire universe of investment options – not simply those an employer provides.
**“What are the services IFG provides?”**
IFG’s focus is on families who want and need long-term planning and advice. Some are working, some retired – or business owners seeking to preserve and monetize the value they’ve created – all families have long-term goals they want to achieve with available resources. That’s where a good financial advisor can be of help.
1. **Retirement income planning:** A focused planning approach for those who’s main concern is outliving their money. Longevity risk, combined with market risk, inflation risk, and legislative (taxation) risk over the next 20-30 years creates a very real concern among many at or nearing retirement: “Will my money last?” Planning can help answer that question and, help guide you to a more secure solution.
2. **Financial/retirement/wealth management planning**: This is a more holistic/comprehensive planning assignment encompassing a variety of issues, such as Social Security optimization/maximization, wealth management, estate planning and charitable giving, as examples.
3. **Investment advisory services:** The implementation stage following the planning process. Implementation can take many forms, depending on the plan adopted and could involve a variety or combination of a number of financial tools, including investments and insurance. You can learn more about the IFG investment philosophy [here](https://indfin.com/wp-content/uploads/2014/09/i206_Investment-Philosophy.pdf).
4. **Insurance services**: Insurance is often a component in planning both as a risk management/transfer tool, but also (for some) a mechanism that provides a tax-advantaged way to engage in estate wealth transfer and charitable giving.
**“What reporting will I receive on my investment accounts?”**
Virtually everyone today offers (or should offer) robust individual and aggregated account reporting.
IFG provides two levels of reporting available. The first is the traditional level most people will find familiar.
**[](https://indfin.com/wp-content/uploads/2014/09/Internet_Image_Global_Waves.jpg)1 – Custodian-level Reporting.**
All investment performance reporting is provided by independent third-party reporting entities. Just as I believe the advisor should be independent of the managers and the managers should be independent of the custodian to avoid potential conflicts of interest, the reporting entity should likewise be independent of the managers they cover as well as the advisor! And no one should be receiving any form of `under the table’ incentives from anyone else.
Your `checks-and-balances should look like this.
- Independent advisor – not affiliated with the custodian or the reporting entity (advisor works for the client, not the firm)
- Independent management – not affiliated with the advisor (objective analysis)
- Independent custodian – no advisor access to client funds (no hands in the cookie jar)
- Independent reporting – not affiliated with the advisor (no opportunity to doctor the books)
IFG utilizes the services of two such independent reporting entities, the choice of which depending on the types of accounts and investment approaches we both agree is most appropriate to fulfill your plan.
You’ll also have[ 24/7 on-demand independent reporting](https://www.seic.com/rias-independent-advisors/investor-portal-investor?_gl=1*oorp12*_gcl_au*MTgzMjk3NTU0OS4xNzIxOTI2Mzkx*_ga*MTc0NjMyMTE2LjE3MTI2OTQxMTM.*_ga_MT7NE92F3W*MTcyNTU2NTA5OC4zNy4xLjE3MjU1NjU1NTcuMTkuMC4w) on your accounts. You’ll be able to access complete performance and tax reporting, including the required filled-out forms, and have all the sophisticated analysis you’ll need for ‘on-demand’ year-to-date, or any time-frame you wish to analyze. You will get more than enough data to feel comfortable that you are receiving better information than the vast majority of your actively invested peers.
Level #2 may have more meaning for someone who wants to meet their own objectives.
[](https://indfin.com/wp-content/uploads/2014/09/iStock_62491112_XXXLARGE.jpg)*iStock Images*
**Level #2 – Personal Goals-Based Reporting**
While custodians can tell you how well your investments are doing, that’s only part of the story – and not very meaningful.
What people really need to know is how well THEY are doing! Most people never realize, until they enter formal planning, that they may have seven or more goals they want to meet. Some are needs, some are wants, some are wishes. And, each category may have three or more goals, all of which may need to be prioritized.
[](https://indfin.com/wp-content/uploads/2014/09/IFG-MGP_Retirement_Lifestyle_Workbook_Employed_001.png)A financial plan for your future is much like a blueprint for your dream home. You wouldn’t just run out and order materials and tools! You’d first want an artist’s rendering of the final result. Once you have a picture of the future, you begin to take stock of your resources and prepare a budget before beginning a blueprint.
You’ll have 24/7 access to your financial plan – which you’re free to download and save on your own computer anytime –
**“Once a client, what comes next?”**
[](https://indfin.com/wp-content/uploads/2016/06/iStock_44633966_SMALL.jpg)We’ll go through a [Seven Step Process.](https://indfin.com/ifgplanningprocess/) We’ll being by discussing your goals and by reviewing your current assets. Out of this process will come a documented financial plan that will incorporate your short, medium, and long term needs. Wealth preservation, tax minimization, and multi-generational issues will be discussed and resolved if these are relevant.
All of these discussions, reflected in your financial plan, will become the framework for the portfolio modeling we’ll create for your current assets.
The implementation stage comes next, which will involve transitioning assets from your current custodian to SEI Private Trust Company.
SEI, founded in 1968, is one of the world’s largest providers of wealth management solutions, with over 5,000 employees and $1.3 trillion in assets (as of September 30, 2023) and offices in the U.S., Canada, Ireland, India, Luxembourg, South Africa, and United Kingdom. SEI’s platform powers eight of the 20 largest banks and 43 of the 100 largest money managers on earth, according to Wealth Management magazine.
Through times of radical change, SEI has been a constant in the financial services industry. SEI has never been bought or sold, and, despite their growth, has been at the forefront of innovation. They’ve been able to take a complex business model and make the processes simple for the end-investor. SEI also has an impressive stable of well-known institutional and corporate clients with which they work closely, in the same fiduciary capacity that I serve you.
You’ll also have [24/7 secure access to your account](https://www.seic.com/rias-independent-advisors/investor-portal-investor?_gl=1*oorp12*_gcl_au*MTgzMjk3NTU0OS4xNzIxOTI2Mzkx*_ga*MTc0NjMyMTE2LjE3MTI2OTQxMTM.*_ga_MT7NE92F3W*MTcyNTU2NTA5OC4zNy4xLjE3MjU1NjU1NTcuMTkuMC4w) so you’ll be able to see all deposits as they arrive. It’s important to note that your assets will be in your account in your name. IFG never takes custody of your assets at any time.
Naturally, I’ll be available during and after this process to answer your questions, which we know you will have. It’s normal to expect that the first year will be the most time-intensive as we get to know one another.
**“How do I become an IFG client? What is the process?”**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73de5d743970d-320wi2.jpg)The process is easier than you might think. Just click on the Getting Started tab above. That will take you through the steps.
**“Can we meet in person prior to my becoming a client?”**
Absolutely! At the conclusion of our introductory call (see Getting Started tab, above) we can schedule the initial consultation and I’ll forward a Welcome Kit outlining what you should bring with you to this first meeting. I always advise people to make the most of it.
My office is easy to locate; see the **[Contact](https://indfin.com/contact/)** tab. To get started, go the the Getting Started tab above!
**“What are your fees?”**
The IFG compensation model looks like this:
- - **Initial on-boarding financial planning fee:** This is a one-time flat fee for creating your initial plan – quoted in advance at our second meeting based on the scope and complexity of the plan that’s required.
- **Plan implementation, reviews and Investment Advisory Fees:** Financial plan updates and investment advisory services go hand-in-hand at IFG. Advisory fees are fully transparent: IFG does better as you do better. **IFG investment advisory fees:**
**Assets**
**Annual**
**Quarterly**
On the first $500,000
1.20%
0.30%
On the next $500,000
0.70%
0.175%
On assets over $1,000,000
0.50%
0.125%
**Emerging Investor: Below $500k**
- Needs Analysis $750
- Planning fee (quoted after Needs Analysis)
- Investment Advisory schedule (above) plus $600 quarterly
**Wealth Management Client $500K+**
- Needs Analysis $750
- Planning Fee (quoted after Needs Analysis)
- Investment Advisory Schedule
**“Is there an account minimum?”**
- **Financial Planning:** There is no mandatory minimum for financial planning services and the fee will vary based on the scope and complexity of the plan and quoted at our second meeting (there is no charge for the initial meeting).
- **[](https://indfin.com/wp-content/uploads/2019/06/i202a_Compensation-Policy_2018_001.jpg)Investment Advisory Services:** Our clients don’t like surprises; neither do I. You can see [IFG’s Compensation Policy here. ](https://indfin.com/wp-content/uploads/2023/08/C100F_-Compensation-Policy-2023.pdf) While there is no hard rule on minimums, IFG planning and investment advisory services are most appropriate for those with portfolios above $500,000. A typical client might have a number of taxable and tax-deferred accounts aggregated to arrive at the total account value. Overall portfolio size will impact the type and scope of services offered; strategies appropriate for some clients may not be appropriate for others. The investment advisory services utilized will vary based on the individual circumstances and needs of each client, given the client’s desires and investment/risk profile.
[](https://indfin.com/wp-content/uploads/2014/09/Home_Office_Woman_On_Phone.jpg)*Fotilla Images*
An brief introductory call should help us both determine if IFG’s services will fit your needs. Just head for my Getting Started page.
**“Do you receive commissions from brokerages or mutual fund providers?”**
No. All investment services are fee only. IFG does not accept any incentives or compensation from any investment brokerage, mutual fund, or investment product provider. Planning and advisory services are fee only.
There are times when another financial tool is required to meet a client’s objectives, such as insurance which does not require ongoing oversight, etc., as indicated above. In those cases, IFG’s compensation is provided from the insurer’s general account rather than collecting ongoing fees from the client. .
**“What is your investment philosophy?”**
[It’s here.](https://indfin.com/investment-philosophy/)
**“Do you offer estate or tax planning, real estate advice, or insurance advice in addition to financial planning?”**
These subjects are incorporated into the financial planning process from a strategic prospective. IFG’s insurance services are limited to retirement, estate, and wealth management fixed products, which includes life insurance. IFG does not provide health or property and casualty insurance.
You should think of your CFP® professional as your financial ‘general practitioner’ who can coordinate and integrate the various specialists in your planning and able to make the appropriate referrals if needed. IFG, as a matter of principal, as well as to fulfill fiduciary standards, does not accept third party compensation or incentives for making referrals.
**“Don’t many firms tout their fiduciary standard?”**
The SEC ruled on June 5, 2019 that brokerage firms are now held to a ‘best interest’ standard; however, they may have just re-arranged the deck chairs to preserve the Wall Street business model: no where in the ruling is ‘best interest’ defined and the word ‘fiduciary’ doesn’t even appear. SEC Commissioner Robert J. Jackson, Jr. issued this statement.
**The Acid Test:** **Ask a ‘best interest’ broker if s/he will accept fiduciary status for all services in writing.**
Here’s a report on [The Fiduciary Standard ](https://indfin.com/wp-content/uploads/2014/09/IFGi-The-Fiduciary-Standard.pdf)you can download.
Many firms, and virtually all of the major ‘big-name’ firms, are ‘dually registered’ as investment brokers as well as Registered Investment Advisors. This allows them to act as a fiduciary in the planning process, thus the fiduciary ‘standard’, while adopting a ‘best interest’ standard when it comes to investment selection. Since it isn’t defined, we still don’t know what it means.
**“Are there a lot of fees involved?”**
The media has virtually ‘brainwashed’ the public into believing fees are bad. Why not? Who likes fees?
Fact is, no one works for free; it’s ***excessive*** fees that ARE bad; but, cost is a function of value, and all assets have a cost connected to maintenance and management, including homes and cars.
**“What separates IFG from other financial advisors?”**
I guess that depends on who IFG is being compared to. You can [see my background here.](https://indfin.com/your-advisor-jim-lorenzen-cfp-aif/)
IFG a small, independent, client-centered private-client boutique consultancy which began in late 1991. Working with an independent practitioner offers some unique advantages: Objectivity, independence in the selection of investments, managers, platforms, and other service providers, as well as no proprietary product. IFG is also a registered investment advisor, held to a fiduciary standard. It’s about planning, advice, and financial and investment guidance.
Financial advisors at major firms, as I learned first-hand early in my career, can be limited to only those offerings their firm provides. Today, all firms, including independent practices like mine, are able to offer a vast array of services and a variety of providers – and may of them are the same. The real hidden issue that might be of concern to many involves the hidden “back-door” revenue sharing arrangements that may exist between the firm and the product providers. Clients should know who the advisor really works for – and sometimes a ‘captive’ advisor-employee of a firm may not really know what’s going on ‘under the hood’.
**While major firms today provide a vast array of services, there’s a bigger question a potential client should ask:**
“Do I want my advisor to be an employee of a firm that has month-end numbers they must meet, or would I rather have an independent advisor who can access major `brand-name’ custodians and offerings without the need to achieve employer-mandated month-end numbers?”
As I said, clients shouldn’t have to wonder who is really compensating the advisor.
[](https://indfin.com/wp-content/uploads/2014/09/Resized-CFP_Logo_Gold.jpg)**Credentials:**
I am a *CERTIFIED FINANCIAL PLANNER®* professional and an *Accredited Investment Fiduciary®*a certification earned from the Center for Fiduciary Studies in association with the Joseph M. Katz Graduate School of Business at the University of Pittsburgh. I’m also a member of the Financial Planning Association.
I think [my business experience](https://indfin.com/your-advisor-jim-lorenzen-cfp-aif/) may be of some value here, as well. Not many financial advisors have created and built businesses outside of this industry; few have ever had to make a payroll and grow a business. Anyone who’s been either a business owner or senior corporate executive will relate to the financial planning process, as well as the investment process, and will likely appreciate the help I can provide in other areas of their financial and business lives. You can download theIFG Philosophy and Profile.
**The IFG approach begins with the IFG Credo:**
Every client deserves, and has the right to expect, an objective and unbiased advisor who is fully aligned with the client’s goals, possesses a moral compass with strict standards of accountability, and who takes a straightforward, common sense collaborative approach, putting the client in control of a hassle-free process incorporating breakthrough technology and unparalleled flexibility… all with openness and transparency.
**I don’t see any client reviews on your website. Why not?**
THANK YOU! I’m glad you asked. The giant custodial firms have reviews. But, in California (and nine other states), the solo independent advisors registered in the state ARE NOT ALLOWED to post testimonials or reviews. Doctors, dentists, attorneys, and virtually everyone else can post reviews.
[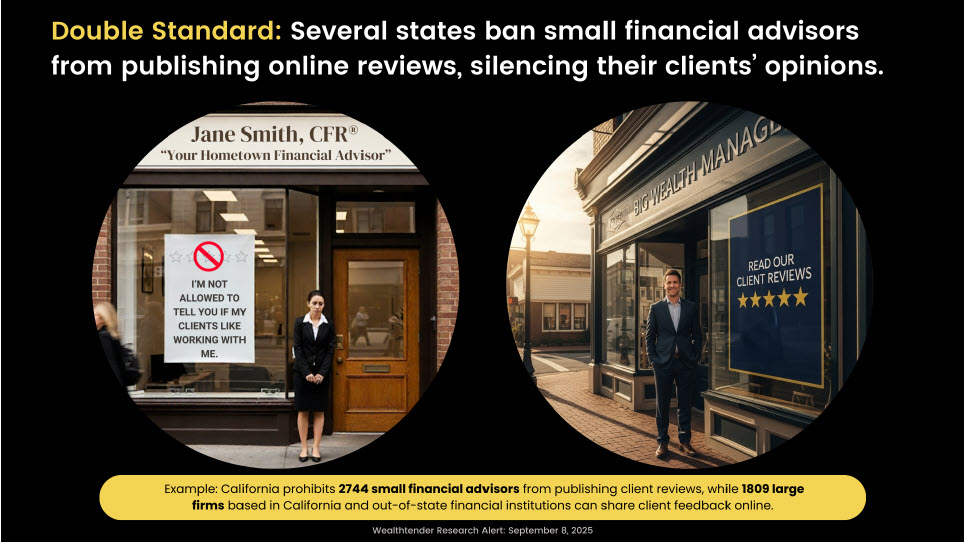](https://indfin.com/wp-content/uploads/2026/09/Double-Standard_-Image.jpg)Smaller independent practices are allowed to post reviews in forty of the fifty states. Ten states, including California, haven’t joined the 21st century on this issue, putting the smaller independent advisory practices at a disadvantage. – which is no doubt just fine with the larger custodial firms with large sales forces (they CAN advertise in California due to their SEC registration. Brian Thorp, CEO of Wealthtender, has [**written about this double-standard**](https://indfin.com/wp-content/uploads/2026/07/Double-Standard_-These-States-Dont-Want-You-to-Read-Online-Reviews-About-Some-Financial-Advisors-2.pdf). Unfortunately, California doesn’t seem to plan on any changes.
---
### [The Planning Process](https://indfin.com/ifgplanningprocess/)
**Published:** October 21, 2015
**Author:** Jim Lorenzen
**Content:**
### The Seven-Step Financial Planning Process
Are you over age 50 and concerned about your future? Do you need help? The financial planning process is really a road map designed to help you on the way to your goals.
Planning for retirement income and wealth preservation in the face of inflation and taxes requires some thought. You can begin your planning process easily. Just go to the [GETTING STARTED tab!](https://indfin.com/getting-started/)
#### **Here are some questions worth pondering:**
- Will your retirement income last to life expectancy for two people?
- How will your next major purchase or repair impact your retirement planning for two decades from now?
- Does your financial plan include an investment policy statement that provides a roadmap for your long-term investments?
- Was your retirement plan the result of a collaboration with a CERTIFIED FINANCIAL PLANNER® professional, or a “boiler plate” presentation from a product salesperson?
- Are you getting your advice from a broker or a Registered Investment Advisor
Technology today has leveled the playing field for investors. While access to sophisticated planning and institutional management – once was the exclusive domain of the old `big-name’ bricks-and-mortar firms – technology has leveled the playing field, allowing investors greater access while still utilizing the guidance of independent, non-conflicted service providers who don’t operate in a sales environment.
**The Planning Process – How it works:**
[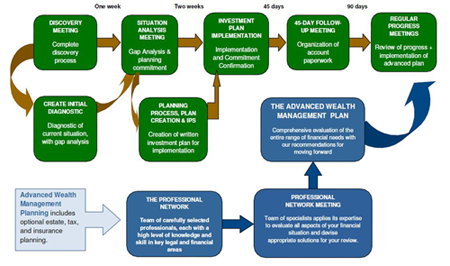](https://indfin.com/wp-content/uploads/2014/09/T3-Planning-Process-Graphic.pdf)
[Click on the graphic above to see the PDF](https://indfin.com/wp-content/uploads/2014/09/T3-Planning-Process-Graphic.pdf)
**[](https://indfin.com/wp-content/uploads/2014/09/Resized-CFP_Logo_Gold.jpg)**
**The CFP® Board’s Seven-Step Planning Process:**
**1. Understanding Your Personal and Financial Circumstances**
Any plan is only as good as its input. We begin with gathering all relevant information required to help you meet your goals. In addition to your financial information, we also work with you to analyze your current situation and address incomplete information.
**2. Identifying, Selecting and Prioritizing your Goals**
We all have needs, wants, and wishes. “Getting the ducks lined-up” helps when it comes to making sure the important things don’t get neglected.
**3. Situation/Needs Gap Analysis**
Your current portfolio is analyzed for risk and a `stress test’ analysis is performed to see how a similar asset allocation would have performed during different historical periods revealing best/worst case scenarios which help calculate success probabilities, taking taxes, inflation, portfolio inflows and outflows. We’ll also analyze potential alternate courses of action.
**4. Data Review and Construction of a Financial Action Plan**
We then review our findings with you and discuss alternative approaches for fulfilling the Action Plan. Review/Refinement of Action-Plan.
**5. Review/Refinement of Action Plan**
This is the search, screening, and selection process to refine the investment/manager mix to fulfill your objectives in a manner consistent with your profile, gap analysis, and plan criteria.
**6. Plan Implementation**
Once you’ve approved the plan and selections have been finalized, implementation is largely an administrative process. We prepare and process the appropriate paperwork, facilitate asset transfers, set-up monitoring procedures, and coordinate efforts with your accountant, attorney, and other advisors as necessary
**7. Monitoring with Reviews and Revisions**
In addition to regularly scheduled review meetings, plan performance is routinely monitored and you can expect communication from IFG throughout the year, including performance, updates, newsletters, etc. Complete information is also available 24/7 via the “Clients Only” portal of our website.
Jim Lorenzen is a *CERTIFIED FINANCIAL* *PLANNER*® and an *ACCREDITED INVESTMENT FIDUCIARY*® based in Simi Valley, California, also serving clients across the United States. To arrange an introductory phone call, just use our convenient [scheduler](https://www.meetme.so/JimLorenzenCFP)!
---
### [Getting Started with IFG.](https://indfin.com/getting-started/)
**Published:** September 8, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi1-e1449855032742.jpg)
**Jim Lorenzen, CFP®, AIF®**
## Ready to begin?
#### Getting your planning started is easy!
#### If your portfolio is over $500,000 and are seeking truly independent fiduciary advice, **you can get started in just 2 easy steps:**
### ****Step #1 – Complete the Retirement Planning Priority Review.****
Complete the [**Personal Planning Priority Review**](https://indfin.com/retirement-priority-planning-review/ "Retirement Priority Planning Review") form. This will give me an overview to help me understand your current situation, priorities, and goals. Don’t worry, the form doesn’t require any sensitive identifying information – no Social Security, driver’s license, etc. Once completed, just fire it off to me!
[Retirement Planning Priority Review](https://indfin.com/retirement-priority-planning-review/)
### **Step #2 – Click here > [Schedule your introductory call.](https://www.meetme.so/JimLorenzenCFP)**
Actually, it’s an online meeting. During our meeting you’ll learn about my practice and have an opportunity to ask any questions about how IFG serves clients.
**Once you’ve scheduled our meeting and submitted your Priority Review, you’ll be provided with a meeting link!** Important: **Your Priority Review must be received at least 48 hours before our meeting.**
Also see [*How to Get Value from an Advisor Relationship*](https://indfin.com/wp-content/uploads/2014/09/i109_How-To-Get-Value-from-an-Advisor-Relationship-1.pdf). You might find it helpful.
### **After our introductory meeting….**
If we both feel we have a good fit, we can schedule a meeting to begin your planning journey. This meeting – by appointment only – can take place **either online or in person at my office**. The office is [easy to find](https://indfin.com/contact/), just north of the #118 at First Street in Simi Valley.
### **Step #4 – Prepare for our first meeting.**
You’ll need to gather the information necessary for our first meeting. Here’s the [agenda and list](https://indfin.com/wp-content/uploads/2014/09/i110_First-Meeting-Agenda-2.pdf) of items you’ll need.
**The First Meeting.** The initial analysis typically requires two meetings – This is where we learn about each other and I will learn about your current situation – financially and personally – and what goals you want to achieve. This information will allow me to create a needs analysis for a second meeting. This analysis will show you where you stand today in relation to your life goals. You will also see what you can do to improve your outlook.
**As noted above, it all begins with a call.** We can do a screen share call – about 20 minutes – which will help you understand the entire process and give you a chance to ask any questions you might have.
So, do step #1, then [Schedule your call](https://www.meetme.so/JimLorenzenCFP) today! It’s easy!… and it may be the best decision you’ve made in a long time.
**Items for your information:**
- [IFG’s Privacy Policy](https://indfin.com/wp-content/uploads/2014/09/IFG-Privacy-Policy.pdf)
- [The Seven-Step Planning Process](https://indfin.com/wp-content/uploads/2019/07/i207_CFP_7-Step-Advisory-Process.pdf)– describes the planning steps from the *CERTIFIED FINANCIAL PLANNER*® Board of Standards.
- [The Planning Process](https://indfin.com/wp-content/uploads/2014/09/IFG-Planning-Process-Graphic_onsitealready.pdf) – charts the work flow and expected timelines. Not all steps apply to every situation.
- You also might want to visit the “All About You” tab above for topics you may want to consider. If you’re married, they might be good topics of conversation with your spouse.
Jim
###### **\* IFG services are most appropriate for households with $1M+ investable assets.**
---
### [The Social Security "Elephant In the Room"](https://indfin.com/the-social-security-elephant-in-the-room/)
**Published:** August 17, 2026
**Author:** Jim Lorenzen
**Excerpt:** "When should I claim Social Security based on my income needs, taxes, life expectancy, spouse, and overall retirement plan?"
**Content:**
“**When should I claim Social Security based on my income needs, taxes, life expectancy, spouse, and overall retirement plan?**“
You’ve come to the right place!
Get your **“The Social Security Elephant in the Room,”** practical Social Security claiming guide that walks through the major considerations and includes a **simple decision flowchart you can complete in about five minutes.**
[Get your Guide here!](https://indfin.com/wp-content/uploads/2026/08/i430k_Social-Secuity-Elephant-2.pdf)
You also may like learning about *[What Baby Boomers Need to Know](https://indfin.com/socialsecurity/)*!
Enjoy!
Jim
---
### ["Can I Retire?"](https://indfin.com/howdoibegin/)
**Published:** September 12, 2023
**Author:** Jim Lorenzen
**Excerpt:** One of the most common questions asked is "Can I retire?" That's probably because for the first time, a retiree has to live off assets instead of earned income.
**Content:**
**You’ve been socking-away money into your retirement plan for years and accumulated a sizable nest-egg. Now the decisions become more connected – and mistakes become more expensive. No wonder “can I retire” is a common question.**
The decumulation stage is different from the accumulation stage. Now you need clear coordination of retirement income, taxes, Social Security, Medicare, and what happens to your surviving spouse.
AI can answer questions by mining internet sources (with varying degrees of accuracy); but it only answers the questions that are asked. Where are the answers to the questions that aren’t asked?
**AI won’t think of the questions that need asking. That comes from experience.**
**Retirement isn’t one decision. It is a series of tax, investment, income, and family decisions that must work together.** That’s where professional help brings value:
- Thirty-plus years of experience
- CFP*®* certification
- *Accredited Investment Fiduciary®*
- Independent, objective advice
- Direct relationship with the advisor doing the work
- Retirement specialization
- Tax-advantaged planning strategies
- Local knowledge
- No large-team handoff after becoming a client
A common misconception among many investors is that a solo, independent practitioner doesn’t have the available resources of a large institution with a well-known brand. The fact is it’s often just the opposite.
For example, an airline or hotel employee won’t have access to all the airlines and hotels in the world – but an independent travel agent does! And, one with thirty-plus years’ experience also knows what questions to ask.
**As a solo, independent professional, your advantage is continuity: the person you meet is the one who will know your family and answer your call.**
**How can you know if you and IFG might be a good fit?**
- **You are likely a good fit if you are:**
- Age 55+ (nearing or in retirement)
- NOT interested in chasing investment tips and stories or trying to “beat the market” (a long-term thinker who plans for the long-term – able to maintain investment discipline according to your long-term plan when all of your friends are chasing investment short-term headlines, tips or fads.
- Minimum $500,000+ portfolio – significant IRA, 401(k), 403(b) or taxable account balances (where asset arrangement and tax-advantaged strategies can have significant impact on long-term outcomes).
- Someone with a sense of humor. You may see your doctor or accountant once a year; but, an advisory relationship is just that – an ongoing relationship. It’s important we actually enjoy working together. That’s how long-term relationships get to be long-term. Integrity, trust, and fun are all two-way streets.
**If you’re someone with ‘scattered assets’** (multiple IRAs or multiple investments purchased without a plan over many years) it might be a good time to get your financial house in order. Many years ago, a corporate CEO came into my office (it was before Zoom meetings) with a milk crate filled with folders. He said, “Jim, I don’t have a portfolio. I have a collection of stuff I’ve accumulated. It’s time I had a portfolio.” I couldn’t have said it better.
### **Ready for professional help? Get the answer to the ‘can I retire’ question.**
1. **Decide on your priorities –** you can do this in one of two ways:
1. User this [online form](https://indfin.com/retirement-priority-planning-review/) – simple, easy, no personal information required.
2. Use this [fillable PDF](https://indfin.com/wp-content/uploads/2023/12/C100H2_RetirementPriorityReview_vsa.pdf) and forward it to me at your convenience.
2. **[Schedule your introductory call](https://go.oncehub.com/JimLorenzenCFP)**
### [Getting Started](https://indfin.com/getting-started)
Want help from Jim Lorenzen, CFP? Here’s how you can [get started with IFG!](https://indfin.com/getting-started)
---
### [Organizing Your Life](https://indfin.com/your-life-data-file/)
**Published:** September 15, 2014
**Author:** Jim Lorenzen
**Excerpt:** Organizing your life information may seem daunting; but, it's about just getting started.
**Content:**
Organizing your life is simple. We’ll just take it one step at a time. [ Let’s get organized!](https://indfin.com/wp-content/uploads/2025/09/Legacy-Planning-Assessment.pdf)[](https://indfin.com/wp-content/uploads/2014/10/Life-Data-File.pdf)
## [Want a copy of this info?](https://indfin.com/wp-content/uploads/2014/10/Life-Data-File.pdf)
[Download our free PDF](https://indfin.com/wp-content/uploads/2014/10/Life-Data-File.pdf)
### Life Data File
Here’s a basic “Bare-Bones” list you can use. For a complete list, download the free PDF file!
**Give location of this information to executor, spouse, anyone with power of attorney.**
- Social Security #
- Spouse Social Security #
- Beneficiary Names, Addresses, Social Security #, Birthdates
- Military ID #
- Account Numbers and Locations
- Will/Trus(s) Location
- Life Insurance Policy #s and carriers
- Annuity Contract #s and carriers
- Credit Card #s
- Checking Accounts and checkbook locations
- Accountant name and phone
- Attorney name and phone
- Insurance Agent name and phone
- Company Benefits Administrator name and phone
- Planner name and phone
- Other Advisor/Family Member/Friend name and phone
- Who will pay immediate bills if you can’t? Ongoing?
### Notification List
**Name and contact # of the following:**
- Family Member/Friend (Help and Support)
- Memorial Society/Church (Help Organize Memorial Arrangements, 946-6822)
- Attorney (Legal Notifications and Filings)
- Executor (See Executor Duties List Attached)
- Accountant (Identify Required Valuations and Tax Filings)
- Planner
- Employer
- Organizations
- Children/Relatives
- Close Friends
- Benefits Admin at Work (Explain Benefits and Necessary Paperwork)
- Insurance Agent/Company (Assist to File Claim)
- Social Security Admin (Disability/Survivor Benefits, 800-772-1213)
- Dept. of Defense (Benefits, 800-321-1080)
**Additional download:** [ **Financial Fitness Checklist**](https://indfin.com/wp-content/uploads/2026/08/IFG-Financial-Fitness-Checklist.pdf)
Here are [six tips for organizing your records.](https://indfin.com/wp-content/uploads/2025/09/NL_Six-Tips-for-Organizing-Your-Records.pdf)
**Don’t forget your heirs! They’ll never forget you!**
Generational Planning is important, too. You might find [this checklist ](https://indfin.com/wp-content/uploads/2025/09/HO_Generational-Planning-Checklist.pdf)helpful. Wondering where you stand? Take this [short assessment](https://indfin.com/wp-content/uploads/2025/09/Legacy-Planning-Assessment.pdf) yourself!
Ready to get started? [ Let’s do it!](https://indfin.com/getting-started/)
Jim
---
### [Your Goals and Priorities](https://indfin.com/your-goals/)
**Published:** September 15, 2014
**Author:** Jim Lorenzen
**Content:**
## **What do you still want to do?**
Directions: Rank each of the following values 1-13 (or more). Remember, you must rank each one; no ties!
\_\_\_\_ FINANCE CHILDREN’S/GRAND CHILDREN’S EDUCATION
\_\_\_\_ BUY A NEW HOME (PRIMARY/VACATION)
\_\_\_\_ BUY A NEW CAR/BOAT/THING
\_\_\_\_ TRAVEL EXTENSIVELY
\_\_\_\_ SAVE FOR RETIREMENT
\_\_\_\_ REDUCE/ELIMINATE DEBT
\_\_\_\_ SET UP A RESERVE/EMERGENCY FUND
\_\_\_\_ CREATE FINANCIAL INDEPENDENCE
\_\_\_\_ SUPPORT ELDERLY/ANY RELATIVES
\_\_\_\_ CONTRIBUTE TO FAVORITE CHARITY/CAUSE
\_\_\_\_ START/BUY/EXPAND OWN BUSINESS
\_\_\_\_ CREATE/LEAVE LARGE ESTATE FOR HEIRS
\_\_\_\_ PROVIDE FOR DEPENDENT’S SPECIAL NEEDS
### **Here’s a good place to start!** Use this handy [Priority Review.](https://indfin.com/wp-content/uploads/2023/12/C100H2_RetirementPriorityReview_vsa.pdf)
**Prefer an [easier online form](https://indfin.com/retirement-priority-planning-review/)?** Don’t worry, No personal sensitive information is required and I won’t see anything unless you give permission.
Or, you can get started by laying the groundwork for your planning [right here](https://www.moneyguidepro.com/fpa/Guests.aspx?gst=7D2BF5831D4A12A652761D84AD4ED7F849CD29F9040B5B8FD4949DA05352CA57&ent=2042797253AD6124C99A85CFF2F9302F5472443908D91D78B7DA6179F0ACA7AF)!
Jim
---
### [Rank Your Priorities](https://indfin.com/your-values/)
**Published:** September 15, 2014
**Author:** Jim Lorenzen
**Content:**
## What’s important to you?
## [Want a copy of this info?](https://indfin.com/wp-content/uploads/2014/10/Values-Exercise.pdf)
[Download our free PDF](https://indfin.com/wp-content/uploads/2014/10/Values-Exercise.pdf)
**Values Exercise**
**What’s important to you?**
**Directions: Rank each of the following values 1-16 (or more). You must ‘Rank’ each one, i.e., NO ties!**
(Drawn from Ken Rouse, Putting Money in its Place)
\_\_\_\_ **ACHIEVEMENT**: To accomplish something important in life, to succeed at what I am doing
\_\_\_\_ **AESTHETICS**: To be able to appreciate beauty and be creative
\_\_\_\_ **AUTHORITY/POWER**: To be a key decision maker and direct other’s activities
\_\_\_\_ **ADVENTURE**: To experience variety and excitement, and to respond to challenging opportunities
\_\_\_\_ **AUTONOMY**: To be independent, to have freedom and do what I want to do
\_\_\_\_ **HEALTH**: To be physically, mentally and emotionally well, to feel energetic and to have a sense of well being
\_\_\_\_ **INTEGRITY**: To have close personal relationships, to share love with family and friends
\_\_\_\_ **PLEASURE**: To experience enjoyment and satisfaction from activities in which I participate
\_\_\_\_ **RECOGNITION**: To be seen as successful, receive acknowledgement for achievement
\_\_\_\_ **SECURITY**: To feel stable and comfortable with few changes or anxieties in my life
\_\_\_\_ **SENSE OF HUMOR**: To keep life experiences in perspective through appropriate use of humor
\_\_\_\_ **SERVICE**: To provide for the community through contributing time, money, or skills
\_\_\_\_ **SPIRITUAL GROWTH**: To have harmony with the infinite source of life
\_\_\_\_ **FINANCIAL WEALTH**: To acquire enough money to be financially independent
\_\_\_\_ **WISDOM**: To have insight, to be able to pursue new knowledge and have clear judgment
\_\_\_\_ **OTHER**
\_\_\_\_\_\_\_\_\_\_
\_\_\_\_ **OTHER**
---
### [The IFG Services Menu](https://indfin.com/ifg-services-investment-advisor-moorpark-ca-planning-retirement-moorpark-2/)
**Published:** September 15, 2014
**Author:** Jim Lorenzen
**Content:**
Welcome to IFG!
IFG is a Simi Valley-based fully independent financial planning and wealth management advisor. IFG founding principal **Jim Lorenzen** is a fee-based *CERTIFIED FINANCIAL PLANNER*® (CFP®) professional, an *ACCREDITED INVESTMENT FIDUCIARY*® (AIF®) and a registered investment advisor serving eastern Ventura county pre-retirees and retirees navigating the transition from corporate careers since 1991 with a focus on retirement and Social Security income planning including tax management strategies.
You can learn [more about IFG here](https://indfin.com/wp-content/uploads/2015/01/Ifgdifference-1.mp4) and Jim Lorenzen’s background [here](https://indfin.com/your-advisor-jim-lorenzen-cfp-aif/).
## IFG services include:
**Financial and Wealth Management Planning**
Pre- and post-retirement planning requires the ability to navigate Social Security timing, withdrawal strategies, healthcare costs, and longevity risk – areas that no longer feel abstract; they’re now immediate and personal.
The process of navigating a course to achieve your financial goals is similar to that of a ship’s captain navigating a ship across a vast ocean.
Just as the ship’s captain must navigate currents and weather, investors must contend with their own set of external risks: Inflation, interest rates, legislative (tax), market, and various business risks. These can be navigated with a long-term focus, discipline, and an understanding of the things that can be managed: Risk, taxes, and costs.
Tax-efficiency, liquidity needs, estate planning and wealth transfer issues can be important issues for many investors. The solution often resides in the proper location and arrangement of assets – and the ability to mitigate or transfer risk.
**Social Security Planning**
This is an area where costly mistakes are often made and can prove irreversible. It’s also an integral part of, and should be coordinated with, retirement income planning. You can [learn more about it here.](https://indfin.com/socialsecurity/)
**Retirement Income Planning**
For many, this is the most important of all IFG services. Retirement planning is about more than simply saving – having the right Social Security strategy is critical – and it can mean the difference of possibly hundreds of thousands of dollars over a lifetime. It can also affect your RMDs and Medicare. It’s about [optimizing retirement income](https://indfin.com/retirementplanning/) to last a lifetime; in fact, for couples, the income must last for two or more lifetimes, depending on the existence of any special needs.
IFG planning is collaborative. You will be involved in every step of the financial planning process to ensure your plan is one you can embrace. Your plan is the blueprint for reaching long-term financial goals. The IFG planning platform, powered by PIE Technologies, is considered industry-wide, as one of the most robust and sophisticated tools available today. Clients have full access to their plans 24/7. They can test, save, and even download.
**Tax Planning**
Tax planning isn’t the same as doing taxes. [Tax planning is proactive](https://indfin.com/tax-planning-the-smart-way/). It’s not about “tax advice.” That’s the accountant’s job. Planning is about recognizing tax liabilities and other hidden tax penalties embedded in the way financial assets are arranged that many accountants may not know or don’t understand. It’s about [planning the arrangement of financial assets](https://indfin.com/tax-planning-the-smart-way/) in order to pay the lowest tax rate allowed by law.
**Investment Advisory**
Using your plan as the blueprint, IFG will develop asset allocation strategy and investment policy statement (IPS), which outlines the criteria and master plan for the investment process which can include developing tax efficient investment strategies, analyzing the impact of concentrated positions on overall portfolio, searching, screening, and selecting investment managers or appropriate investments, providing for independent reporting, and a process for ongoing monitoring of investment performance.
The process of navigating a course to achieve your financial goals is similar to that of a ship’s captain navigating a ship across a vast ocean. Just as the ship’s captain must navigate currents and weather, investors must contend with their own set of external risks: Inflation, interest rates, legislative (tax), market, and various business risks. No one can control the stock or credit markets. The same is true of the economic environment, let alone government monetary or fiscal policy and legislation; but all those changes can be navigated with a long-term focus, discipline, and an understanding of the things that can be controlled: Risk, taxes, and costs.
**Beyond Estate Planning: Generational Planning**
Deciding who gets what is fine; protecting against excessive taxes and costs is another. But, how many people engage in generational planning – coordinating planning to achieve generational wealth?
Answer: the wealthy.
You can [learn more about estate planning and generational planning here.](https://indfin.com/beyond-estate-planning-generational-planning/)
**Risk Management and Mitigation**
Whether it is protecting against an unforeseen loss of income or replacing wealth earmarked for charitable giving for wealth transfer, IFG has the resources to help clients put tax-efficient financial strategies in-place to achieve financial objectives and sleep at night. [Asset protection](https://indfin.com/asset-protection-a-common-sense-primer-to-get-you-started/) is a must.
## State of the Art Technology and Tools
IFG utilizes some of the most sophisticated tools available in the financial industry. Dynamic data feeds keep a wide variety of inputs constantly updated and IFG clients have 24/7/365 access as well as complete control.
## Sophisticated, Prudent, Investment Management
IFG clients have access to virtually the entire investment universe of investment choices, including institutional-level asset management in separately managed accounts, including tax-managed institutional managers and/or direct indexing solutions. For some accounts, low-cost index mutual or exchange-traded funds (ETFs) are recommended.
IFG utilizes only no-load, no-commission investment solutions and does not receive commissions or any other compensation of any description from third party investment product or service providers.
Where insurance tools or solutions are required by the client, compensation is derived from the insurer’s general account rather than collecting ongoing annual advisory fees on those assets.
Clients have 24/7/365 access to their financial plans and all investment accounts in both individual and consolidated formats, as well as up-to-date tax and performance reporting direct from their custodial institution.
---
### [Getting Started with IFG - IRMAA Concerns](https://indfin.com/getting-started-with-ifg-irmaa-concerns/)
**Published:** March 3, 2026
**Author:** Jim Lorenzen
**Excerpt:** Avoid the Medicare Premium Surprise!
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi1-e1449855032742.jpg)
**Jim Lorenzen, CFP®, AIF®**
**You’ve come to the right place!**
**Avoid the Medicare Premium Surprise.**
Here’s where you can get the quick PDF for executives nearing retirement. Spot the bonus, severance, and stock years that can raise Medicare costs later.
[Access Your IRMAA Tripwire Kit](https://indfin.com/wp-content/uploads/2026/02/IRMAA-Tripwire-Kit_202602.pdf "IRMAA Tripwire Kit_202602")
**What’s in the Kit:**
> The 10 most common IRMAA tripwires that catch executives off-guard
> A simple 2-year lookback planner
> What to do if income drops after retirement – how the Social Security Administration process works
**Optional: If you want to move faster with professional help, getting started is easy.**
## If you’re an executive nearing retirement and want to avoid Medicare surprises, here are the two easiest ways to begin.
**Right-fit minimum:** typically $1 million+ in investable assets. If you are below that threshold, you’re still welcome to our newsletter. Ongoing advisory work is typically reserved for $1M+ households.
#### ****Step #1 – Complete the Retirement Planning Priority Review.****
**I’ll need some information, of course; but, you don’t need to provide any sensitive info – just enough to help me understand how I can be of help. Naturally, you’ll have some questions, too. That’s what the introductory process is all about.**You can do it one of two ways:
**(a)** Complete the [**Personal Planning Priority Review**](https://indfin.com/retirement-priority-planning-review/ "Retirement Priority Planning Review") form. This will give me an overview to help me understand your current situation, priorities, and goals. You can [fill out the form](https://indfin.com/wp-content/uploads/2023/12/C100H2_RetirementPriorityReview_vsa.pdf) here. Once completed just fire it off to me!
[Retirement Planning Priority Review](https://indfin.com/retirement-priority-planning-review/)
**(b)** **Or**, you can start with MyBlocks. It’s a fun way for you and your spouse to begin with building blocks. You can start here. By the way, just like the Priority Review form above, I won’t see any of your information unless you decide to share it.
[MyBlocks Menu](https://www.moneyguidepro.com/fpa/Guests.aspx?gst=7D2BF5831D4A12A652761D84AD4ED7F849CD29F9040B5B8FD4949DA05352CA57&ent=2042797253AD6124C99A85CFF2F9302F5472443908D91D78B7DA6179F0ACA7AF)
### **Step #2 – [Schedule your introductory call. ](https://www.meetme.so/JimLorenzenCFP)**
No telephone tag; just use this handy scheduler to choose a time! During this call you’ll learn about my practice and have an opportunity to ask any questions about how IFG serves clients.
**At the end of the call, you can decide if you would like to schedule a meeting.** See [*How to Get Value from an Advisor Relationship*](https://indfin.com/wp-content/uploads/2014/09/i109_How-To-Get-Value-from-an-Advisor-Relationship-1.pdf). If you decide to move forward, we will……
### **If we both feel we have a ‘fit’, you can schedule your first meeting.**
This meeting – by appointment only – can take place **either online or in person at my office**. The office is [easy to find](https://indfin.com/contact/): Note, the office is on First Street, just **north** the #118, (Google Maps is sometimes in error) in Simi Valley.
### **Prepare for our first meeting.**
You’ll need to gather the information necessary for our first meeting. Here’s the [agenda and list](https://indfin.com/wp-content/uploads/2014/09/i110_First-Meeting-Agenda-2.pdf) of items you’ll need.
**The Beginning:** The initial analysis typically requires two meetings – This is where we learn about each other and I will learn about your current situation – financially and personally – and what goals you want to achieve. This information will allow me to create a needs analysis for a second meeting. This analysis will show you where you stand today in relation to your life goals. You will also see what you can do to improve your outlook.
**As noted above, it all begins with a call.** We can do a screen share call – about 20 minutes – which will help you understand the entire process and give you a chance to ask any questions you might have.
**So, do step #1**, then [Schedule your call](https://www.meetme.so/JimLorenzenCFP) today! It’s easy!… and it may be the best decision you’ve made in a long time.
**Items for your information:**
- [IFG’s Privacy Policy](https://indfin.com/wp-content/uploads/2014/09/IFG-Privacy-Policy.pdf)
- [The Seven-Step Planning Process](https://indfin.com/wp-content/uploads/2019/07/i207_CFP_7-Step-Advisory-Process.pdf)– describes the planning steps from the *CERTIFIED FINANCIAL PLANNER*® Board of Standards.
- [The Planning Process](https://indfin.com/wp-content/uploads/2014/09/IFG-Planning-Process-Graphic_onsitealready.pdf) – charts the work flow and expected timelines. Not all steps apply to every situation.
- You also might want to visit the “All About You” tab above for topics you may want to consider. If you’re married, they might be good topics of conversation with your spouse.
Jim
---
### [Asset Diversification Report](https://indfin.com/asset-diversification-report/)
**Published:** May 29, 2019
**Author:** Jim Lorenzen
**Content:**
Below is your FREE copy of the Asset Diversification Report which details diversity in the Asset Allocation Process.
[i306\_Understanding The Diversification Puzzle](https://indfin.com/wp-content/uploads/2026/05/i306_Understanding-The-Diversification-Puzzle.pdf)
---
### **Sign-up for IFG Newsletters!**
Email (required) \*
First Name \*
Select list(s) to subscribe toI am currently retired
I am a Business Owner
I am a pre-retiree corporate executive
Sign me up for all IFG Insights subject areas!
Example: Yes, I would like to receive emails from The Independent Financial Group. (You can unsubscribe anytime)
Constant Contact Use. Please leave this field blank.
---
By submitting this form, you are consenting to receive marketing emails from: . You can revoke your consent to receive emails at any time by using the SafeUnsubscribe® link, found at the bottom of every email. [Emails are serviced by Constant Contact](https://www.constantcontact.com/legal/about-constant-contact)
---
### [Jim Lorenzen, CFP®, AIF®](https://indfin.com/your-advisor-jim-lorenzen-cfp-aif/)
**Published:** September 15, 2014
**Author:** Jim Lorenzen
**Content:**
**Your Fiduciary Advisor**

***Jim Lorenzen, CFP®, AIF®
THE INDEPENDENT FINANCIAL GROUP
Registered Investment Advisor***
Phone: 805-265-5416
Fax: 805-830-1138
Toll Free: 800-257-6659
E-mail:
***[](https://indfin.com/wp-content/uploads/2014/09/Resized-CFP_Logo_Gold.jpg)***
Jim Lorenzen is a Simi Valley-based fully independent financial planning and wealth management advisor. Jim is a fee-based *CERTIFIED FINANCIAL PLANNER*® (CFP®) professional, an *ACCREDITED INVESTMENT FIDUCIARY*® (AIF®) and a registered investment advisor serving eastern Ventura county pre-retirees and retirees navigating the transition from corporate careers since 1991 with a focus on retirement and Social Security income planning including tax management strategies.
***CERTIFIED FINANCIAL PLANNER*®** professional specializing in retirement income planning in Simi Valley. Jim began his wealth management career in 1991.
**ACCREDITED INVESTMENT FIDUCIARY (AIF®)**
Many call themselves fiduciary advisors; Jim Lorenzen is received is accreditation from The Center for Fiduciary Studies in association with the Joseph M. Katz Graduate School of Business, University of Pittsburgh. As a Registered Investment Advisor (RIA), your interests must come first as a matter of law; however, accreditation is evidence of successful completion of a formal course of study encompassing retirement plans and their regulatory requirements.
**Arrange an introductory call with Jim by using our convenient [scheduler](https://www.meetme.so/JimLorenzenCFP)!**
### Education
- Emory & Henry (Virginia), B.A., Economics
- The American College – Financial planning curriculum for CFP®
- Center for Fiduciary Studies in association with the Joseph M. Katz Graduate School of Business, University of Pittsburgh – Accredited Investment Fiduciary (AIF®)
### **Business background:**
**Founded, built, and successfully sold five businesses**
Weekly entertainment magazines, shopping guides, and weekly papers–a business model combining a number of functions: sales, materials sourcing, manufacturing, assembly, distribution, finance, human resource management, and service. (Prior background had included broadcast news and advertising, as well as several national and international corporate positions in consumer and commercial finance.)
**Professional speaker and management consultant**
During the 1980s: headline speaker at more than 500 national and international conventions throughout the United States, Canada, and the U.K. for clients such as Hearst Corporation, CapCities/ABC, Foster Grant, Hobie Cat, Independence Bank, H.R. Textron, Orlando Sentinel, Val-Pak, The Los Angeles Daily News, The National Association of Advertising Publishers, National Association of General Merchandise Representatives, National Association of Music Merchants, National Newspaper Association, National Management Association, Manufacturer’s Reps of America, California State University Northridge, New York State Publisher’s Council, Union Ice Company, Cox Communications, and many others. Articles published in scores of national trade and other publications of organizations cited above and others.
**Media coverage**
As a financial advisor in Simi Valley, CA, published in ***NASDAQ*** , the ***Journal of Compensation and Benefits***, and Profit Sharing Council of America’s ***Insights.*** He has also appeared on American Airlines’ ***Sky Radio***, heard on more than 19,000 flights. Also has been interviewed by *The Wall Street Journal* for ***Smart Money*** magazine.
**What is a CERTIFIED FINANCIAL PLANNER?**
To earn the CFP® certification from the CFP Board, candidates must meet requirements for education, work experience, and ethics. To fulfill the educational requirement, candidates must have a bachelor’s degree or higher from an accredited college or university and also master a list of nearly 100 topics on integrated financial planning through a CFP Board-Registered program. Topics cover major planning areas, such as:
- Estate Tax, Gift Tax, and Transfer Tax Planning
- Asset Protection Planning
- Retirement Planning
- Estate Planning
- General Principles of Finance and Financial Planning
- Insurance Planning
- Employee Benefits Planning
- Investment and Securities Planning
- State and Federal Income Tax Planning
- Asset Protection Planning
The time it takes to complete the requirements depends heavily on the candidates study schedule – two to three years is not uncommon. There are more than 300 colleges and universities offering a CFP Board-Registered course of study within their graduate MBA programs. Upon completion, CFP candidates must pass a ten-hour, 2-day, exam, conducted twice each year on the same dates at specific selected testing locations across the United States.
---
### [Retirement Income Planning](https://indfin.com/retirementplanning/)
**Published:** September 20, 2014
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017c384ba1fa970b-320wi.jpg)Most of us tend to think of retirement planning as simply having enough money to quit working.** But, retirement income planning takes on [many new dimensions](https://indfin.com/retirement-planning-unplugged-how-to-stop-losing-sleep-over-money-markets-and-the-irs/) that never had to be considered by earlier generations. Retirement income planning should begin long before you retire – and it doesn’t stop at retirement.
**Retirement income planning is a key component of wealth preservation** simply because there’s more involved than simply achieving a decent return. Tax law changes, inflation, as well as unexpected expenses can wipe out years’ of savings. Many people fail to consider how retirement income coming from [tax deferred accounts can impact their Medicare premiums](https://indfin.com/tax-planning-the-smart-way/) – a good reason to plan for minimizing the amount of your taxable retirement plan distributions well in advance of those distributions becoming mandatory later. The most common concerns, of course, are:
- How much can I safely spend?
- [What tax issues should I know about?](https://vimeo.com/jimlorenzen/taxplanniingforretirement2023)
- [What tax planning should I do?](https://indfin.com/tax-planning-the-smart-way/)
- How much risk should I take?
- What investments should I choose?
- How does the distribution phase of my life differ from the accumulation phase?
## **How does tax planning change during the 4 stages of retirement?**
Enjoy this video – and you can download this handout: [IFG\_How-Tax-Planning-Changes-HO2026](https://indfin.com/wp-content/uploads/2026/05/IFG_How-Tax-Planning-Changes-HO2026.pdf)
Knowing how to turn savings into retirement income that lasts and keeps pace with inflation requires a skill set not all who call themselves advisors possess. It’s not simply about where to invest, it’s also about how to ‘locate’ your money. In December 2022, congress passed a second version of The SECURE Act, dubbed SECURE Act 2.0, and it made some changes both to retirement savings and retirement income taxation. While there are over 100 provisions – yes, it can be rather confusing – there are FOUR key areas that most people need to be aware of.
SECURE Act 2.0 changed the rules, too. It doesn’t matter if you’re in Simi Valley, Moorpark, or Thousand Oaks, CA. Grab some coffee: [**here’s a 30-minute video**](https://vimeo.com/812870514/251d75cc8b) that will walk you through the 4 key areas of SECURE Act 2.0 you might find helpful. You can download a fact sheet and [see some short videos about the Act here.](https://indfin.com/how-the-secure-act-changes-retirement-planning/)
**Do you remember 1966?** **There was no recession or depression. No dot-com bust. No credit melt-down; yet, it turned out for many to be a terrible year to retire.** Why? You might like this short video to learn why “Guardrails” are important in your retirement income planning – particularly for those years when you’re drawing down assets. You can [view my video here](https://vimeo.com/635459466/282eb2c845)
### The Lifetime Retirement Income Need is larger than most believe.
As noted above, it takes a lot of money to support two people for thirty years of inflation and tax law changes. Retirees need to be concerned with maintaining their lifestyle by building a rising stream of income.
It’s about more than choosing the right investments, strategy is important, too. No one can control the markets or politicians; but, external forces can be managed.
### Social Security
**When should you claim your Social Security benefits?** Choosing the correct claiming strategy can mean hundreds of thousands of dollars over a lifetime – and choosing the wrong one can result in *life-long* penalties and can impact your loved ones, as well. You can learn more on IFG’s[ Social Security page.](https://indfin.com/socialsecurity/)
### Your 401(k)
What should you do with your 401(k)? Should you stay or go? It’s not the simple decision many believe. Depending on your situation, you can have up to six options available to you – and all come with their own advantages and disadvantages. I created a series of videos that goes through all six options – I think you’ll find it well worth your while to do your homework before you make your decision. [You can find them here](https://indfin.com/retirementdecisions/). Enjoy!
### Understanding Investments and Diversification
Investment management requires a basic understanding of the principles of diversification and knowing how investment returns are computed. In addition, it’s important to understand the costs of various investment options. The most popular investment option in most retirement plans is the mutual fund.
Here’s some reading on all three you might find helpful:
- [Understanding Diversification](https://indfin.com/wp-content/uploads/2014/09/i306_Understanding-The-Diversification-Puzzle.pdf)
- [Understanding Investment Returns](https://indfin.com/wp-content/uploads/2014/09/i307_RPT-Understanding-Investment-Returns.pdf)
- [Understanding the Mutual Fund Landscape](https://indfin.com/wp-content/uploads/2014/09/i309_WP-Understanding_Mutual_Fund_Landscape.pdf)
IFG has been helping people plan retirement for more than 22 years. For more information on retirement income needs and income sources, I’m here to help. You can[ get started here!](https://indfin.com/getting-started/)
---
### [Video Library](https://indfin.com/video-library/)
**Published:** September 20, 2014
**Author:** Jim Lorenzen
**Content:**
You can schedule your introductory phone call with Jim [here](https://www.meetme.so/JimLorenzenCFP)!
###
Accumulating money during your working years was simple: sock it away and grow! The distribution phase is different. This video begins with a brain-teaser you might find eye-opening!
### 2026 Tax Planning Through the Four Stages of Retirement
### Six Retirement Account Options Every Retiree Must Know. Each has it’s own advantages and disadvantages:
**1 – Leave your money in your employer’s plan**
**2 – Move your money to your new employer’s plan.**
**3 – Roll your money into an IRA.**
**4 – Take a Lump Sum Distribution**
**5 – Convert your plan assets to a Roth IRA**
**6 – Make an in-plan Roth conversion**
[How the SECURE Act Changes Retirement](https://indfin.com/how-the-secure-act-changes-retirement-planning/)
**Secure Act 2.0 Short Videos**
1. [More Time to Save](https://vimeo.com/938718223/4d4a984cab?share=copy)
2. [More Ways to Save](https://vimeo.com/943298819/89be5b4c66?share=copy)
3. [New Ways to Use Your Money](https://vimeo.com/948381967/7ae99a24d0?share=copy)
4. [Death of the “stretch”](https://vimeo.com/948781448/7f4e6bf795?share=copy)
---
### [Video Library](https://indfin.com/video-library-2-2/)
**Published:** April 29, 2015
**Author:** Jim Lorenzen
**Content:**
**By Appointment Only**
[Schedule your introductory phone call here!](https://www.meetme.so/JimLorenzenCFP)
### Jim Lorenzen, CFP®, AIF®
### *THE INDEPENDENT FINANCIAL GROUP*
### *A Registered Investment Advisor*
**Phone: 805-265-5416**
Fax: 805-830-1138
Toll Free: 800-257-6659
E-mail:
Ca. Ins. Lic. 0C00742
2655 First Street, Suite 250; Simi Valley, California 93065

# [Join Our Newsletter](https://tinyurl.com/IFGInsights)
Can You Tell the Difference Between a “Financial Advisor” and a…

---
### [How to Create A Tax-Managed Investment Strategy](https://indfin.com/investment-philosophy/)
**Published:** September 15, 2014
**Author:** Jim Lorenzen
**Excerpt:** Tax managed investment strategy is important - even for tax-deferred accounts!
**Content:**
It’s simple, but not simplistic.
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi2.jpg)Jim Lorenzen CFP® AIF®**Is tax-managed investment management, even for ‘tax-delayed’ accounts, like your 401(k) and IRAs, etc., important?**
**Yes, but probably not the way you think.**
You’re probably wondering why you would need tax-managed investment management inside a tax-deferred account.
Well, you don’t. Actually, it’s more about asset location.
Remember, the size of your 401(k) someday will determine the size of your required minimum distributions (RMDs) – do you know what tax brackets will look like when you retire? You not only may not like your new tax bracket; but, you may get a surprise when you find the size of your RMD also impacts how much of your Social Security is taxed, as well as your Medicare premiums. Hmmm. You may want to grab some coffee and take a look at [this video](https://indfin.com/asset-custody/) about how tax planning changes during the four stages of retirement.
All good financial planning begins with these basic pillars:
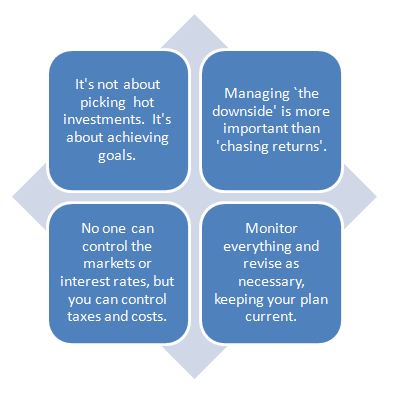
Inflation, interest rates, and the markets are all concerns; but these concerns, while not in our control, can be managed. One thing we do have some control over taxes and costs. It comes down to a sound strategy tied to a solid plan. You can’t manage taxes with funds or ETFs: they’re both baskets of pooled money. But, you CAN replicate an index in a cost-efficient and tax-efficient way.
**Tax optimization – one controllable – is key.**
For tax-deferred accounts, a strategy for controlling future account balances is important before being forced to take required minimum distributions (RMDs) in the future. Those distribution levels will impact taxes on Social Security benefits and also Medicare premiums.
For table accounts, investors need a strategy that goes beyond mutual funds and ETFs – one that allows for a more customized investment experience that mirrors the attributes of a selected index while providing enhanced transparency and a more individualized approach to the investment process.
[](https://indfin.com/wp-content/uploads/2025/09/Strategies-vs-Funds.png)Core tax strategies vs pooled investmentsAnd, it makes sense: Core tax strategy vs. pooled investments
[](https://indfin.com/wp-content/uploads/2025/09/Strategies-vs-Funds_grid.png)A core tax strategy compared to pooled investments**This approach delivers a range of potential benefits, including:**
- **Cost efficiency** (the other controllable variable) – Do not incur commission fees at the manager level. It’s passively managed with respect to an index rather than picking stocks.
- **Transparency and direct ownership** – Instead of owning a share in a pooled vehicle, like a mutual fund or ETF, investors actually own the individual stocks and bonds in their accounts. Note: bond funds and bond ETFs do not have a maturity date. When you own bonds, you know they will mature at face value on their maturity dates, regardless of market gyrations in the meantime. Stocks, of course, can be managed for tax-harvesting.
- **Personalization** – The ability to personalize all aspects of a portfolio to truly align with an investor’s priorities and needs.
**Building your financial future?** It’s like building your dream home. Hire an an experienced architect. Building your dream future? Well, you know. You need a good blueprint, either way. Otherwise, you might not like the outcome.
**What does the basic process look like?**
[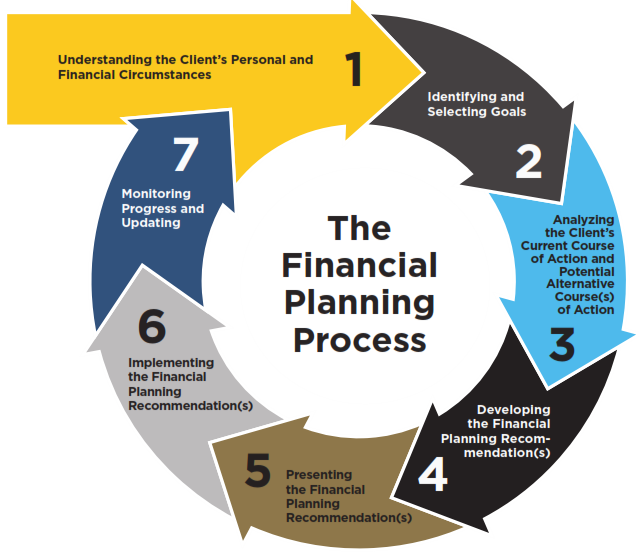](https://indfin.com/wp-content/uploads/2023/05/CFP_Financial_Planning_Process.png)
1. It begins with you. You can’t find the store you want in the mall until you find that X on the mall directory that says ‘you are here’. You wouldn’t want your doctor to prescribe a treatment without conducting an examination and providing a diagnosis. This step should be no surprise to anyone.
2. It’s best to know what you want your house to look like before we begin ordering out materials.
3. Has what you’ve been doing so far been working? Can it be improved?
4. A preliminary plan is developed, however….
5. Planning is a collaborative process. This is where your input and tweaking may be necessary to arrive at the final approach everyone is comfortable pursuing: you have to be comfortable knowing it’s exactly what you want and I have to be comfortable it’s in your best interest and we’re not doing anything stupid.
6. The plan is implemented, and…
7. We have regularly scheduled meetings to monitor your progress and make sure we’re on-track. Remember Pillar #1 at the top of this page: we don’t care if we beat indexes – the only index that matters is if you’re achieving your financial goals.
**So, why would you consider working with an independent fiduciary advisor?**
- **Independent and Objective.** Financial planning and investment advisory services are provided on a fee-only basis. IFG does not accept commissions or third party compensation for these services. Insurance products, which do not require ongoing management oversight, are not included on the annual fee structure. Compensation for the use of these products, where desired, is derived from the insurance carrier..[\[1\]](https://jimlorenzen.advisorwebsite.com/user/login?destination=/node/26988/edit?destination=content-manager#_ftn1)
- **Minimize expenses.** Use passive low-cost investments wherever feasible. Use active institutional management when value can be added to reduce volatility, increase predictability, and/or increase tax efficiency.
- **Clear Responsibilities and Limits.** A fiduciary advisor is just that – an *advisor*. IFG does not take custody of, or have access to, client assets at any time. Client assets are held in the client’s name at an approved independent third-party custodian. [Learn more here](https://indfin.com/asset-custody/).
- **Clear compensation.** Planning fees are quoted in advance on a defined-project basis. As for investment management and oversight, it’s simple: IFG does better when clients do better. All fees are clear and fully disclosed.
- **Fiduciary Status.** As a Registered Investment Advisor, IFG embraces fiduciary status on all client investment accounts. This means a client’s best interest can be the only consideration. I am willing to put my fiduciary status in writing. Learn more about the fiduciary standard Download the [The Fiduciary Standard](https://indfin.com/wp-content/uploads/2014/09/IFGi-The-Fiduciary-Standard.pdf).
Every client deserves, and has the right to expect, an objective and unbiased advisor who is fully aligned with the client’s goals, possesses a moral compass with strict standards of accountability, and who takes a straightforward, common sense collaborative approach, putting the client in control of a hassle-free process incorporating state-of-the-art technology with unparalleled flexibility, openness, and transparency.
Service is paramount: extraordinary service with no surprises, no excuses, and no worries, coupled with independent thinking and lasting solutions to help clients achieve the security, stability, predictability, and peace of mind they seek.
Would you like to have a fiduciary advisor help you navigate the financial marketplace? I’d be happy to help!
1. [Tell me your priorities here](https://indfin.com/asset-custody/), then
2. Arrange your introductory ‘right fit’ phone call today using our [convenient scheduler!](https://indfin.com/asset-custody/)
It’s easy, and of course, you’re under no obligation.
Jim
###### ***[\[1\]](https://jimlorenzen.advisorwebsite.com/user/login?destination=/node/26988/edit?destination=content-manager#_ftn1) IFG Founding Principal Jim Lorenzen,CFP®, AIF®, is able to provide insurance products independently under Ca. Lic.#0C00742.***
---
### [Social Security Decisions Can Be Costly... and irrevocable](https://indfin.com/socialsecurity/)
**Published:** October 7, 2021
**Author:** Jim Lorenzen
**Excerpt:** Here's what Baby Boomers need to know for 2026.
**Content:**
**For Baby Boomers**
When your parents retired, it was simple – just go down to the Social Security office and sign up! It’s different for you. There are more decisions to make: the video above will help you understand how benefits are calculated, when to apply, pitfalls to avoid, 5 strategies for maximizing benefits, and more.
But there’s even more you should understand: Did you know a couple could conceivably have up to 18,000 claiming options? How will those decisions impact your future taxes and even your spouse later in life?
**[Issues facing ‘baby boomers ](http://view.vzaar.com/11305923/player)include:**
- What Social Security is and isn’t
- How much will you receive – how benefits are calculated
- Factors to consider deciding when you should claim
- When to apply: Effects of claiming early or late
- How working impacts benefits – separating more fact from gossip
- How to strategize to optimize (different from maximize)
- Provisional income: What it is and how it affects your tax bill in retirement
- How IRS required minimum distributions (RMDs) will impact your Social Security
- The importance of strategizing your retirement income years in advance
- Strategies to minimize taxes on your benefits
- How Medicare impacts your Social Security check
- For couples: There’s more at stake than individual benefits
- Key factors for widows and divorcees – More flexibility than you might think
You would never build a house without a blueprint. Why would you make a decision without [advance planning](https://indfin.com/retirementplanning/)?
The Center for Retirement Research at Boston College published a report on ***The Impact of inflation on Social Security Benefits**.* You can [access it here](https://indfin.com/wp-content/uploads/2021/10/Impact-of-Inflation-on-Benefits_BostonCollege.pdf).
**Wondering when you should claim? What’s YOUR break-even age between 62 and 70?**
Want your breakeven, survivor, and after-tax comparison in writing? **I’ll prepare a personalized report for you with your exact figures including an analysis.** [You can request it here](https://lp.constantcontactpages.com/sl/9Al940w). Your personalized report
- Will run through all possible claiming scenarios, whether you’re single, divorced, married, widowed – even for families with minor or disabled adult children
- Shows detailed breakdown of lifetime benefits under virtually any scenario.
- Incorporates cost-of-living adjustments – again, the SSA doesn’t provide this – they’re helpful (and overworked), but they’re not in the business of either providing predictions or financial planning.
- Shows first-year survivor income
- Is updated for the Social Security Fairness Act signed into law January 5, 2025
The complimentary report you receive shows the benefit estimate based on the age when you claim Social Security. Each scenario shows both the benefit stream and cumulative benefits over your life expectancy. All that’s needed is each spouse’s birthdate and primary insurance amount.
**Want help with your planning?**
1. You can [begin by telling me your priorities](https://indfin.com/retirement-priority-planning-review/). Then,
2. schedule a “Right Fit” introductory phone call with me. The call will take about 20 minutes. You’ll be able to share my screen and learn about what IFG is all about and see if IFG is right for you. [Schedule your “Right Fit” call here.](https://go.oncehub.com/JimLorenzenCFP)
See you soon!
Jim
---
### [You're in the right place!](https://indfin.com/irmaa-kit-thank-you/)
**Published:** February 19, 2026
**Author:** Jim Lorenzen
**Excerpt:** Thank you! Here's your IRMAA Tripwire kit!
**Content:**
## **Thank you! Here’s your IRMAA Tripwire kit!**
**[You can download your kit here!](https://indfin.com/wp-content/uploads/2026/02/IRMAA-Tripwire-Kit_202602.pdf "IRMAA Tripwire Kit_202602")**
If you’d like help in applying this, [here’s how to get started!](https://indfin.com/getting-started/)
Enjoy!
Jim Lorenzen, CFP®, AIF®
---
### [Generational Planning: Getting Estate Planning Ducks Lined Up.](https://indfin.com/beyond-estate-planning-generational-planning/)
**Published:** February 17, 2025
**Author:** Jim Lorenzen
**Excerpt:** Money matters don’t happen in a vacuum—what you do with your finances can affect your whole family, from your kids to your aging parents. Even if your bank accounts stay separate, it makes sense for your and your family to look at estate planning as a team effort across generations.
**Content:**
**Smart Financial Planning Goes Beyond Estate Planning**
Money matters don’t happen in a vacuum—what you do with your finances can impact your entire family, from your children to your aging parents. Even if your bank accounts remain separate, it makes sense for you and your family to approach **estate planning** as a collaborative effort **across generations**. By aligning financial goals and responsibilities, you can ensure that your family’s future is secure, and that the wealth you’ve built is passed down smoothly to the next generation.
Most people focus on their own needs when working with an advisor—issues like retirement savings, investments, or budgeting for major purchases. For **baby boomers**, estate planning and **Social Security** are top priorities, while younger generations are focused on saving for their first home or paying off student loans. However, taking a step back to consider the bigger picture can help families make smarter financial decisions together. By incorporating **estate planning** into your family’s broader financial strategy, everyone—across generations—can align their goals for a more secure future.
**Maybe We Should Think About Family Finances as a Whole?**
Families often share financial responsibilities, whether it’s grandparents helping with college tuition, parents caring for aging relatives, or adult children moving back home. Our lives are financially intertwined, making **estate planning** a crucial conversation for families. Having open discussions about money not only makes sense but can also help avoid surprises and ensure everyone is on the same page. Even if each family member’s finances remain separate, coordinating financial plans can lead to smarter choices and fewer headaches, especially when it comes to managing **retirement savings**, **healthcare costs**, and passing down wealth across generations.
**Key Topics to Consider**
**Bringing Family into Financial Discussions**
At your next financial check-in, think about these questions:
- Are your kids or grandkids getting ready for college?
- Are your adult children looking to buy a home?
- Do your parents need help with caregiving or medical expenses?
**Keeping Up with Family Changes**
This generational planning checklist can also help you cover all the bases.
[HO\_Generational Planning Checklist](https://indfin.com/wp-content/uploads/2025/09/HO_Generational-Planning-Checklist-1.pdf)[Download](https://indfin.com/wp-content/uploads/2025/09/HO_Generational-Planning-Checklist-1.pdf)
Life changes fast—marriages, divorces, new babies, adoptions, or even kids moving back home can all have financial implications. Keeping track of these changes – and planning ahead – can prevent a lot of financial stress down the road. And, don’t forget aging parents’ financial well-being. An ounce of prevention (you know the rest) can help avoid last-minute decisions in times of crisis.
**Aligning Financial Goals Across Generations**
Different family members often have different goals—some want to buy a home, others may be starting a business, and some are focused on retirement. Even if your finances aren’t combined, discussing these goals openly can be helpful. Do you have strategies to support different family members in reaching their financial milestones?
[HO\_Family Guide to Savvy Generational Planning](https://indfin.com/wp-content/uploads/2025/09/HO_Family-Guide-to-Savvy-Generational-Planning.pdf)[Download](https://indfin.com/wp-content/uploads/2025/09/HO_Family-Guide-to-Savvy-Generational-Planning.pdf)
**Planning for Business Succession**
Do you own a business and want to pass it down to your kids? What’s the plan. It needs to be more than ‘they’ll just take over’. You’ll need an income for retirement while they’ll need an income to live! Will it support both? What if they don’t want the business? Good advice: start planning early. A well-structured exit or succession plan ensures a smooth transition while also handling any tax or legal concerns that might come up.
**Career and Work Planning**
Still working? Helping to provide financial support for a younger generation? Delaying retirement? Having career conversations with younger family members can also help guide them toward financial independence.
**Health and Medical Costs**
You know about this one. Healthcare expenses can be a major financial strain. Do you have a formal written plan that integrates these issues into your retirement?
**Managing Investments and Wealth**
Financial planning isn’t just about saving money—it’s about smart investing, minimizing taxes, and managing cash flow. There’s an old saying that people are seldom hurt by their investments; they’re usually hurt by their behavior. It’s also important that both spouses or partners are on the same page and stay informed about financial matters in case of unexpected life changes.
*The only thing that surprises me is that we continue to be surprised when surprise happens. – Donald Rumsfeld, former Secretary of Defense.*
**Estate Planning and Passing on Wealth**
Estate planning is more than simply making a will—it’s about ensuring your family is financially prepared for the future. Beyond just passing down assets, it’s important to prepare beneficiaries to manage their inheritance wisely. Discussions now can prevent confusion and conflict later on.
**Retirement Planning for the Whole Family**
Planning for your own retirement is crucial, but it’s equally important to consider how your retirement planning affects your family. With estate planning in Simi Valley, ensure that your retirement accounts are set up properly and that your loved ones understand key aspects like required minimum distributions (RMDs) and inherited IRAs, including the tax consequences of your financial decisions. By addressing these factors, you can help your family avoid unexpected tax burdens and ensure a smooth transition of wealth. If the wealthiest families receive financial guidance to navigate these complexities, it only makes sense for the rest of us to take the same approach with estate planning.
[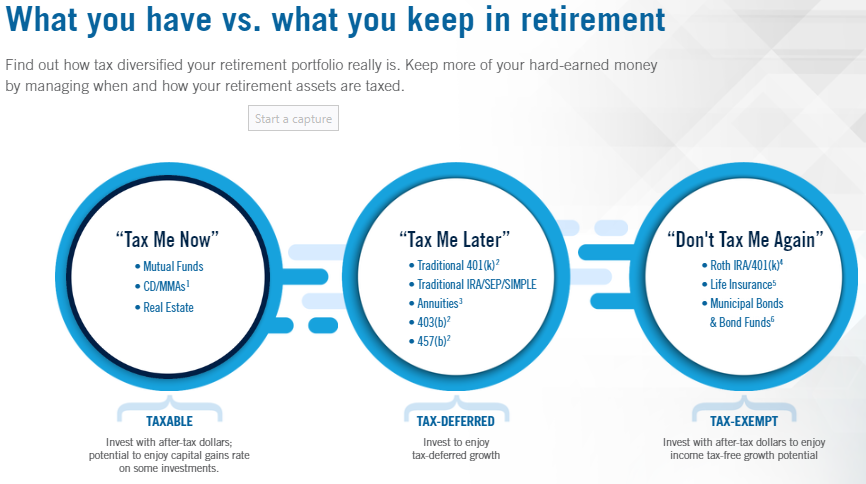](https://indfin.com/wp-content/uploads/2025/02/Tax-Challenge.png)*Estate planning for generational benefit***Preparing for Future Financial Changes**
Change is the only constant, and many changes can be anticipated. As part of estate planning in Simi Valley, it’s important to think ahead—what big changes might happen in the next five years? Does your family have enough savings to handle unexpected expenses without dipping into long-term investments? How do you know? Have your assumptions been tested? Ensuring everyone’s financial stability through proper estate planning can prevent last-minute financial scrambles and provide peace of mind for the future.
**Why a Multi-Generational Approach Makes Sense**
Money decisions have a rippling effect. They don’t just affect one person—consequences ripple across the family. Looking at financial planning as a shared effort can help ensure everyone is on solid ground, from young adults just starting out to retirees enjoying their golden years.
What are your priorities? You can [use this form](https://indfin.com/wp-content/uploads/2023/12/C100H2_RetirementPriorityReview_vsa.pdf) or you can[ tell me ](https://indfin.com/retirement-priority-planning-review/)[here](https://indfin.com/retirement-priority-planning-review/)!
If I can help, the place to begin is on the [Getting Started page.](https://indfin.com/getting-started/)
Jim
---
### [Why Choose an Independent Fiduciary Advisor?](https://indfin.com/all-about-ifg/)
**Published:** September 8, 2014
**Author:** Jim Lorenzen
**Excerpt:** Are you seeking a fiduciary advisor? If so, you've found one! Of course, you're probably wondering if you've found the right one... an advisor with long experience and respected credentials,
**Content:**
In a sea of high-powered marketers and investment product sellers, an independent fiduciary advisor is special. Problem is, the term ‘fiduciary’ has become a marketing tag many firms use too loosely. A ‘pure’ registered investment advisor is a fiduciary by law, not rhetoric.
Here’s one of the best kept secrets in the financial services business: An independent fiduciary advisor, not being a ‘captive’ employee of a single firm, has access to the entire financial marketplace and, in many cases, has greater access and flexibility than those working at the ‘household name’ companies.
My philosophy is simple: Every client deserves, and has the right to expect, an objective and unbiased advisor who is fully aligned with the client’s goals, possesses a moral compass with strict standards of accountability, and who takes a straightforward, common sense collaborative approach.
Here, you are in control of a hassle-free process incorporating state-of-the-art technology with unparalleled flexibility, openness, and transparency.
Why choose IFG? Service is paramount: extraordinary service with no surprises, no excuses, and no worries, coupled with independent thinking and lasting solutions to help clients achieve the security, stability, predictability, and peace of mind they seek.
One of my early mentors was international management consultant, Don Butler. He used to say, “People never have time to do it right, but they find time to do it over.”
You’ve probably spent your entire career laying the groundwork for a stress-free life; but, you probably won’t have time to do it over. It makes sense to hire a guide – someone who’s ‘made the trip’ before – many times. I’d like to help.
**Jim Lorenzen, CFP®, AIF®**
**Are you seeking a fiduciary advisor?** If so, you’ve found one! I am an independent *CERTIFIED FINANCIAL PLANNER®* professional and a fiduciary advisor. In fact, I’m an *ACCREDITED INVESTMENT FIDUCIARY.®* [You can see more about my background here.](https://indfin.com/your-advisor-jim-lorenzen-cfp-aif/)
Of course, you’re probably wondering if you’ve found the *right* advisor for you… an advisor with long experience and respected credentials,
I’m Jim Lorenzen. Retirement has been specialty since I first hung out my shingle back in 1991. Since then, I’ve been helping people nearing or in retirement with their planning and execution of investment and tax strategies designed to preserve wealth so they can sleep at night not having to wonder where there money is.
One place it ISN’T is in any IFG account. I do not have access to, nor do I take custody of, client funds at any time. Your investments are held in YOUR name at an independent third-party custodian.
**An extra level of protection:** While most firms hold client assets in “street name” (meaning they’re held in the firm’s name as an attachable asset on their balance sheet – which means if they go bankrupt, your only protection is the insurance coverage). As an independent fiduciary advisor, I’ve chosen a different model: your investments are not held in “street” name; your money is held in YOUR name in an independent third-party trust account – NOT as an asset on the custodian’s balance sheet making them subject to seizure. It’s about SAFETY!
Whether you’ve saved one or ten million dollars, turning your life savings into a stable tax-efficient retirement income is one of the most consequential financial decisions you will ever make.
**Why work with an independent solo practitioner?** **Simple: Independence, objectivity**. I function as your advisor. I do not take custody of client assets. (remember Bernie?). Clients shouldn’t have to wonder who their advisor really works for or who pays them. Another word you may have heard before: fiduciary – one that gets a lot of use these days. As a registered investment advisor, I’m a fiduciary by law. More on my fiduciary status below.
**IFG is an independently-owned financial planning and registered investment advisor specializing in retirement and retirement income planning,** serving private clients seeking quality fiduciary advice. IFG does not sell investment products and is proud of the lasting client relationships formed since IFGs formation in 1991. I am a *Certified Financial Planner®* professional and an *Accredited Investment Fiduciary*® with a focus on retirement planning since I first opened my doors in 1991. You can learn more by viewing the video on my [Home Page](https://indfin.com).
**All Financial Credentials Aren’t Created Equal**
There’s a distinct difference between a certification and a designation, though many use the terms interchangeably. Certification is accredited: it requires impartial, third-party validation from a credentialing program – the certifying body cannot be affiliated with the education provider and therefore conveys a higher standard.[](https://indfin.com/wp-content/uploads/2014/03/6a017c332c5ecb970b01a51174caed970c-120wi.jpg)For example, the CFP® Board certified financial planning curriculum is now offered in both undergraduate and postgraduate degree programs at more than 300 accredited colleges and universities across the United States. Graduates planning to become CFP® professionals must sit for the CFP® Board exam, given twice a year on the same date in selected locations across the United States.
**Putting this in perspective:** An advisor with a designation tailored to a specialty can’t effectively plan a client’s retirement unless s/he knows how it affects other areas of the financial plan. An analogy: If someone wants to become an anesthesiologist, s/he doesn’t simply go to anesthesiology school. The first stop is medical school learn how each part of the body interacts with the others. Once they have a medical degree, then they go to anesthesiology school. So, if someone specializes in a narrow area and is not a board-certified CFP®, some unintended consequences may bring unhappy surprises down the road.
**[](https://indfin.com/wp-content/uploads/2022/06/Office-Lg-Conf-Rm.png)The “Fiduciary” Handle Can Be Confusing**
Maybe you’ve heard of “the F word”: Fiduciary. Many people are becoming aware that all advisors aren’t alike, though a lot of misinformation, some even coming from lawmakers, and tv advertising is blurring this important distinction. Talking about “best interests” and accepting true fiduciary status are two very different things.
## **The operative question: Will your advisor accept fiduciary status *for all services* in writing?**
Many advisors working for broker-dealers talk about working in the their clients’ “best interest”, even pointing to recent SEC rulings; however they do not – in fact, may not even be *allowed* to – accept fiduciary status for all advice and transactions for client accounts… *and certainly not in writing.* Nowhere in the new regulations is the word ‘fiduciary’ used and ‘best interest’ isn’t defined. And, since many major firms register as both “advisors” and brokers, they can still change hats. it’s still business as usual, it seems.
Those who are ‘pure’ Registered Investment Advisors (RIAs) are held to a fiduciary standard by law; and independent RIAs work for only one employer: The client. Acid test: Is the advisor willing to sign a document acknowledging fiduciary status?
How about conflicts of interest. The fact is every advisor, no matter how packaged, has a conflict of interest. Conflicts can not be avoided, but they can be managed. Want to learn more about conflicts? [Here’s my take.](https://indfin.com/crs-conflicts/)
**At IFG, you get an independent advisor embracing fiduciary status, experience, and credentials. IFG clients work directly with me.**You can learn more about my background [here](https://indfin.com/your-advisor-jim-lorenzen-cfp-aif/).
**Is my practice the right fit for you?**
My services are designed for people who value independent, objective advice. They’re focus is on the serious issues of longevity, taxation, inflation, etc., and still manage to keep a sense of humor.
My services are NOT ideal for people who react to daily headlines, are trying to ‘beat the markets’, emotionally invested in theories and myths, and don’t have a sense of humor.
Although there is no minimum requirement, IFG’ services are most appropriate for clients with $500,000 or more to invest and who are seeking qualified, independent and objective comprehensive planning and advice from a fee-based fiduciary advisor, with a[fee structure that is clear](https://indfin.com/wp-content/uploads/2023/08/C100F_-Compensation-Policy-2023.pdf) and easy to understand. To learn more, [arrange your introductory call today!](https://meetme.so/JimLorenzenCFP)
**Your advisorshould act as an educator and coach**. And, coaching DOES make a difference! See **[*How to Get Value from an Advisor Relationship.*](https://indfin.com/wp-content/uploads/2014/09/i109_How-To-Get-Value-from-an-Advisor-Relationship-1.pdf)**
Studies have shown that most Americans are woefully unprepared for retirement. Indeed, many wait until they’re about to retire before beginning to plan for the very first time!
[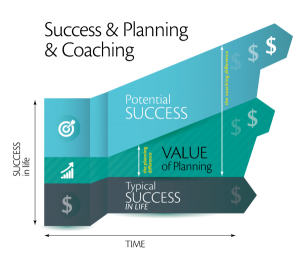](https://indfin.com/wp-content/uploads/2014/09/PlanningCoaching_Graphic.png)
**Thereal value of an advisor may be due to theeducation and coaching process a client receives**. **This is this has been shown to help advisory clients reach theirfull financial potential.**
**Those who do plan in advance do better!** How much? According to an independent research study by Vanguard Funds, a company with a long-established reputation for low expenses and consumer advocacy, published a paper for the profession regarding the long-term value of using a retirement planning advisor for planning, implementation, and followup and found it does outweigh the so-called ‘costs’, and by more than most would suspect! A study by both Envestnet and Vanguard came to the same conclusions. The Envestnet study can be found [here](https://indfin.com/wp-content/uploads/2014/09/i209e_Advisor-Value_env.pdf). (In case some of the terminology may be unfamiliar, 100 basis points (bps) = 1.00%.)
**Financial Planning and Investment Advisory Practice Profile**
[](https://indfin.com/wp-content/uploads/2016/06/IFGi-Philosophy_and_Profile-201606_001.png)IFG is a Registered Investment Advisor provides independent retirement income planning and wealth management advice to serious clients seeking objective help from a qualified retirement planning advisor. You can learn more by downloading IFG’s [Practice Philosophy and Profile.](https://indfin.com/wp-content/uploads/2014/09/i205_Philosophy_and_Profile-201707.pdf)
Founding principal Jim Lorenzen is a *CERTIFIED FINANCIAL PLANNER*® professional, as well as an *ACCREDITED INVESTMENT FIDUCIARY*® who began independent practice in 1991 and now serves clients both within and outside California. You can learn more about Jim [here](https://indfin.com/your-advisor-jim-lorenzen-cfp-aif/).
IFG believes in straight talk. If you would like to arrange a short introductory phone call with Founding Principal Jim Lorenzen, here’s how you can [get started](https://indfin.com/getting-started/).
**The IFG Client Profile**
Since 1991, IFG has been serving private clients andtheir families, who are concerned about future taxes and inflation and want greater predictability fortheir financial futures by establishing strategies and ‘auto-pilot’ solutionsrequiring less effort.
[](https://indfin.com/wp-content/uploads/2014/09/Key_Success.png)
**People preparing for retirement:**
- - - - **Private clients preparing for retirement.** Often they are executives and business ownersfor whom 401(k) contributions are not enough and are seeking greater tax-efficiency, or simply those nearing retirement and concerned about wealth preservation.
- - **Conservative** – Not interested in stock tips, trends, or the latest investment fad.
- - **Focused** – Knows the difference between education and financial entertainment; does not get advice from television gurus.
- - **Long-Term Oriented** – Does not let daily news (financial, economic, or any other) impact decision-making.
- - **Willing to learn** – Education plays a large part in the IFG service process. Clients should understand the “why” behind their plan and its components; and, quite often, real education can be in conflict with the ‘sound bite entertainment’ put forward by the media, whose only concern is ratings.
- - **Understand the value of professional guidance**. It’s not about ‘beating the markets’ or overcoming an annual expense ratio, as the consumer media would have people believe. Most often, the value is achieved through tax reduction, risk mitigation, or simply avoiding mistakes. Value provided in those areas often dwarf their attendant costs.
- **Appreciate “straight talk”** – Straight talk can sometimes be in conflict with what people want to hear or expect, based on something they’ve heard or seen. Helping clients achieve their long-term goals is something IFG takes seriously. It’s simply about doing what’s right and makes sense.
**What IFG Provides**
Not all planning assignments are alike; but the types of services that are typical in many planning projects include:
- - - Situation analysis
- Goal setting and prioritization
- Assessment and analysis of risk profile
- Budgeting and cash flow analysis
- Analyzing the impact of concentrated positions on overall portfolio
- Developing asset allocation strategy and investment policy
- Developing tax-advantaged and efficientwealth management strategies including optimized Social Security and retirement draw-down strategies with capital needs vs market-exposure stress-testing
- Searching and selecting appropriate portfolio components and investment managers
- “Safe money” options that provide a competitive return with no downside risk while maintaining liquidity and building security
- Tax-advantaged strategies for wealth building and preservationwhile providing for future security
- Independent third party reporting – unrelated to IFG or the managers and/or investments they cover.
- Monitoring investment performance
- Coordination of estate and tax planning
- Consulting on current and post-career business interests, including transition strategies.
How to get value from yourrelationship with a qualified retirement planning advisor? – [See our guide.](https://indfin.com/wp-content/uploads/2017/02/i109_How-To-Get-Value-from-an-Advisor-Relationship.pdf)
**Minimizing Uncertainty**
While certain components of the wealth management process can feature guaranteed solutions, it’s important to understand that, more often than not, the planning and management process is about probabilities arrived at through extensive back-testing and ‘stress-tests’ using sophisticated technology combined with common sense.
You can learn more about the IFG approach to asset management by downloading the [IFG Investment Philosophy](https://indfin.com/wp-content/uploads/2014/09/i206_Investment-Philosophy.pdf). You’ll find it straightforward.
**[](https://indfin.com/wp-content/uploads/2022/06/Office-Exterior.png)Investment Management**
All financial and retirement planning, as well as all investment advisory services, are provided on a fee-only basis.
IFG clients have access to virtually the entire investment universe of investment choices, including institutional-level asset management in separately managed accounts optimized for tax efficiency. You can learn more about IFG’s screening and selection process [here](https://indfin.com/wp-content/uploads/2014/09/i208_Manager-Screening-and-Selection-Process.pdf).
For some accounts, low-cost index mutual or exchange-traded funds (ETFs) are recommended. IFG utilizes only no-load, no-commission, and no surrender charge investment solutions. IFG does not receive commissions or any other compensation of any description from third party investment service providers. In addition, clients have 24/7/365 access to their accounts, as well as up-to-date tax and performance reporting direct from the asset custodian.
**Insurance Solutions**
Insurance is not a priority at IFG. I don’t go out looking to sell insurance. In fact, it’s rarely used; but sometimes insurance is the tool in the toolbox that’s needed. In those cases where insurance is a desired solution component, our screening begins with only “investment grade” carriers. While virtually every company touts high ratings, it’s worth noting that almost all the rating agencies are paid by the carriers they rate. Knowing what’s ‘under the hood’ in the company’s investment portfolio is important. Some very highly-rated companies have gone under simply because the rating agencies didn’t know(?) what was happening.
It’s also important to understand how the companies treat existing policyholders vs. new sales.
Insurance-based solutions, normally not requiring continuous ongoing management oversight, so ongoing advisory fees would seem inappropriate. Therefore, insurance services are provided on a commission basis under California license 0C00742. IFG is independent of all carriers. Solutions chosen, when required, are chosen based on both the carrier’s track-record, financial stability, and ‘best fit’ for meeting the client’s objectives.
**Who is The Independent Financial Group?**
**The Independent Financial Group isn’t a group of people** working for IFG; the name depicts what IFG provides for clients. Too often, investors are steered to “bundled” solutions packed with hidden fees and back-door compensation arrangements. As you’ll see below, IFG unbundles these services, and their providers, to create a custom-tailored, transparent solution. This puts the client in control, not the providers.
**The Independent Financial Group name refers to YOUR group** of independent financial resources – not IFGs – chosen and custom-tailored to meet YOUR specific needs and to meet YOUR specific goals… all with the help of a qualified, experienced [advisor](https://indfin.com/your-advisor-jim-lorenzen-cfp-aif/).
- - - **Independent advice from a qualified advisor**
Financial Planning: *CERTIFIED FINANCIAL PLANNER*® professional
Investment advice: *ACCREDITED INVESTMENT FIDUCIARY®.*
Insurance: Non-captive independent agent (California license #0C00742.
Learn more about IFG’s Founding Principal, [Jim Lorenzen](https://indfin.com/your-advisor-jim-lorenzen-cfp-aif/)
- **Major independent custodian**– **IFG does not take custody of client assets at any time.** Client assets are held in trust in the client’s name – not “street name” – they are not held as an asset of the custodian subject to creditors and limited insurance coverage. Technology is [state-of-the-art with easy access.](https://www.seic.com/rias-independent-advisors/investor-portal-investor?_gl=1*oorp12*_gcl_au*MTgzMjk3NTU0OS4xNzIxOTI2Mzkx*_ga*MTc0NjMyMTE2LjE3MTI2OTQxMTM.*_ga_MT7NE92F3W*MTcyNTU2NTA5OC4zNy4xLjE3MjU1NjU1NTcuMTkuMC4w)
- **Independent due-diligence: 2 layers**
(a) independent third-party due-diligence at the institutional level plus – not related to the managers and institutions they cover.
(b) at the advisory/client level utilizing a ‘best interests’ fiduciary standard vs. a suitability standard. Note: The Independent Financial Group is a Registered Investment Advisor bound to a fiduciary standard of client care.
- **Independent third-party institutional reporting:** Unrelated to the managers they cover.
- **Independent investment selection and management** – unrelated to the parties conducting due-diligence.
- **State-of-the-art industry-leading technology** – independent and unaffiliated with institutional custodians or investment providers. Our planning platform, created by PIE tech, enhances the client-advisor collaborative effort and provides an easy/intuitive client interface. One of the reasons IFG can collaborate with clients in Florida as easily as with clients in California. And, your investment [collaboration becomes easier than ever.](https://www.seic.com/rias-independent-advisors/investor-portal-investor?_gl=1*oorp12*_gcl_au*MTgzMjk3NTU0OS4xNzIxOTI2Mzkx*_ga*MTc0NjMyMTE2LjE3MTI2OTQxMTM.*_ga_MT7NE92F3W*MTcyNTU2NTA5OC4zNy4xLjE3MjU1NjU1NTcuMTkuMC4w)
[](https://indfin.com/wp-content/uploads/2014/03/6a017c332c5ecb970b01a51174caed970c-120wi.jpg)
**Transparency. This puts the client in control.**
- - 1. An experienced and credentialed *Certified Financial Planner®* professional and an *Accredited Investment Fiduciary*®
2. Independent [advisory services ](https://indfin.com/ifg-services-investment-advisor-moorpark-ca-planning-retirement-moorpark-2)grounded in a sound[ investment philosophy.](https://indfin.com/wp-content/uploads/2014/09/i206_Investment-Philosophy-1.pdf)
3. [Custodial services ](https://indfin.com/asset-custody)independent of the advisor
4. Reporting services independent of the advisor and the custodian
5. Account management independent of the advisor, the custodian, and the reporting entity
### **Are You STILL Working with a retail broker?**
The creation of IFG meant moving away from the old paradigm (the advisor working as a captive rep for a firm)….
**The Old Organization Paradigm**

**…To a New Paradigm****The advisor is independent** of all the firms and product providers, **working only for the client.**
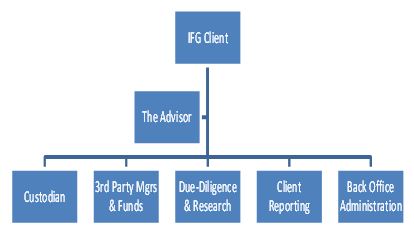The **New Paradigm** investing structure features an independent advisor working solely for the client in an ‘unbundled’ environment without hidden compensation. Investment service providers serve the client independently avoiding revenue sharing and other conflicts of interest. The result: YOUR independent financial group dedicated to putting YOUR interests first. You are the CEO, and the advisor acts as your personal CFO. You can access IFG’s [Privacy Policy here.](https://indfin.com/wp-content/uploads/2025/09/C100A_Privacy-Policy.pdf)
**You can hear Jim Lorenzen talk about The IFG Difference [here](https://indfin.com/video-library-2/)!**
*iStock images*### **Become an IFG client!**
#### **You can arrange an introductory phone call with Jim Lorenzen, CFP by using our convenient scheduler! You can do it [here](https://www.meetme.so/JimLorenzenCFP)!**
---
### [How to Contact IFG!](https://indfin.com/contact/)
**Published:** September 8, 2014
**Author:** Jim Lorenzen
**Content:**

### Jim Lorenzen, CFP®, AIF®
### *THE INDEPENDENT FINANCIAL GROUP*
### *A Registered Investment Advisor*
**By Appointment Only**
[Schedule your introductory phone call here!](https://www.meetme.so/JimLorenzenCFP)
[**Phone: 805-265-5416**](https://www.meetme.so/JimLorenzenCFP)
Fax: 805-830-1138
Toll Free: 800-257-6659
E-mail:
Ca. Ins. Lic. 0C00742
2655 First Street, Suite 250; Simi Valley, California 93065
---
### [Retirement Rollover Decisions and Your 401(k)](https://indfin.com/retirementdecisions/)
**Published:** May 31, 2017
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b017c384ba1fa970b-320wi.jpg)**
### 401(k) Retirement Rollover Decisions
Your 401(k) [retirement rollover decisions](https://indfin.com/retirement-planning-unplugged-how-to-stop-losing-sleep-over-money-markets-and-the-irs/) impact your retirement planning process because the decisions you make can have a major impact on your future. [Should you roll over your 401(K) or not?](https://indfin.com/irarollovers/)
[Get IFG’s IRA Rollover Checklist](https://lp.constantcontactpages.com/sl/DGaznSe): It’s a handy tool to help your decision making.
Did you know there are [five things you can do with an IRA you can’t with a 401(k)?](https://indfin.com/wp-content/uploads/2022/05/5-Things-You-Can-Do-with-an-IRA-You-Cant-With-401k.pdf)
**But, should YOU roll over your 401(k) to an IRA?** Many people think this is a simple decision; but this decision isn’t as simple as it sounds. Believe it or not, **depending on your situation, you may have up to SIX different options available to you!** And, some retirement rollover decisions you make can come with unintended tax consequences due to their relationship with other legislation.
Want to know more? You’re smart. I’ve created a video series that will review all six of your potential options, *including the advantages and disadvantages* of each. So, grab some coffee! I hope you find These helpful. Here are your six options:
1. [Leave your money in your current plan](https://vimeo.com/919700051/7b737bab00?share=copy)
2. [Move your money to your new employer’s plan](https://vimeo.com/920114129/0c2b47679f?share=copy)
3. [Roll your money into an IRA](https://vimeo.com/920143551/d626474dc1?share=copy)
4. [Take a lump-sum distribution of all your money](https://vimeo.com/920518130/bc3869cfd0?share=copy)
5. [Convert plan assets to a Roth IRA](https://vimeo.com/920533438/7ec240929c?share=copy)
6. [Make an in-plan Roth conversion](https://vimeo.com/920545311/9ac36bd94d?share=copy)
###
### Understanding Investments, Diversification and the 401(k) Retirement Rollover Decision.
Investment management requires a basic understanding of the principles of diversification and knowing how investment returns are computed. In addition, it’s important to understand the costs of various investment options. The most popular investment option in most retirement plans is the mutual fund. Of course, whether to rollover your 401(k) to an IRA should be evaluated, as well.
Here’s some reading you might find helpful:
- - [Understanding Diversification](https://indfin.com/wp-content/uploads/2014/09/i306_Understanding-The-Diversification-Puzzle.pdf)
- [Understanding Investment Returns](https://indfin.com/wp-content/uploads/2014/09/i307_RPT-Understanding-Investment-Returns.pdf)
- [Understanding the Mutual Fund Landscape](https://indfin.com/wp-content/uploads/2014/09/i309_WP-Understanding_Mutual_Fund_Landscape.pdf)
IFG has been helping people plan retirement for more than 30 years. For more information on retirement income needs and income sources, please [contact IFG today.](https://indfin.com/contact)
---
### [How The SECURE Act Changes Retirement Planning](https://indfin.com/how-the-secure-act-changes-retirement-planning/)
**Published:** May 3, 2024
**Author:** Jim Lorenzen
**Content:**
[IFG-SECURE-Act2.0-HO\_New-Retirement-Rules-4](https://indfin.com/wp-content/uploads/2024/05/IFG-SECURE-Act2.0-HO_New-Retirement-Rules-4.pdf)[Download](https://indfin.com/wp-content/uploads/2024/05/IFG-SECURE-Act2.0-HO_New-Retirement-Rules-4.pdf)
How the SECURE Act changes retirement planning for you and your children and grandchildren is worth knowing. Here’s a handout you might enjoy as you view the videos below about the SECURE Act.
The SECURE Act (Setting Every Community Up for Retirement Enhancement – they had a government committee up all night working on that one) was passed in December 2019 and and the 2.0 add-on was passed in December 2022. With roughly 100 provisions, mostly around retirement plans, you can imagine there’s both good news and bad news. Despite it’s title, there are some provisions that do more to secure the government and the I.R.S. than the tax payers.
However, there is some good news, too: more time to save, more ways to save, new ways to use your money, etc., but the death of the stretch will provide a lot of payback for the government.
Most of these provisions are effective 2024, but others are pushed out to 2028 – and the impact is far-reaching, all the way from the silent generation to the Gen-Z’ers who will be the recipients of a great wealth transfer in the coming decades.
The benefits that come today, however, do carry a price tag that may very well be paid by our children and grandchildren – securing the government’s income rather than their own.
I’m posting a series of short videos about how the SECURE Act changes retirement planning. Also, [here’s a handout](https://indfin.com/wp-content/uploads/2024/05/IFG-SECURE-Act2.0_4KeysHO.pdf) for easy reference. I hope you’ll find them helpful.
Enjoy! And, if you’d like some help with your retirement planning, Just click on the Getting Started tab or [go here!](https://indfin.com/getting-started/ "Start my retirement plan")
1. **Video #1:** [More Time to Save](https://vimeo.com/938718223/4d4a984cab?share=copy "SECURE Act 2.0 gives you more time to save") (11:11)
2. **Video #2:** [More Ways to Save](https://vimeo.com/943298819/89be5b4c66?share=copy) (13:51)
3. **Video #3:** [More Ways to Use your Money](https://vimeo.com/948381967/7ae99a24d0?share=copy) (11:16)
4. **Video #4:** [Death of the Stretch!](https://vimeo.com/948781448/7f4e6bf795?share=copy) Not good news for your kids and grandkids who may be in their peak earning years when they inherit. (11:18). If you are a non-spouse IRA beneficiary, you will find [this special roadmap](https://lp.constantcontactpages.com/sl/8iYWYlN "Non-Spouse IRA Beneficiary Roadmap") helpful. Just tell me where to send it! You’ll also get regular updates on usable financial information – no worries, you can cancel easily anytime.
Hope you find these helpful. There are more videos in the Video Library under the Resources tab.
Jim
---
### [Tax Planning the Smart Way](https://indfin.com/tax-planning-the-smart-way/)
**Published:** February 13, 2025
**Author:** Jim Lorenzen
**Excerpt:** If you have $500,000 in your 401(k) or IRA, it’s not really $500.000. If you’re married and filing jointly, it’s more likely you could have $325,000 (35% tax bracket) or just $315,000 (37% tax bracket).
**Content:**
**Bad Tax Planning begins when you believe your 401(k)/IRA statements**
Effective tax planning is essential for reducing tax liabilities, especially when it comes to **retirement accounts** and **Medicare premiums**. Whether you live in Simi Valley or Florida, smart tax planning is critical to retirement success.
You might like my report, ***Four Steps to a Tax Free Retirement***! **Just [tell me where to send it!](https://lp.constantcontactpages.com/sl/1nfZSzD/4StepsTaxFreeRetirement)**
With rising tax rates and unpredictable costs in retirement, **tax planning** requires a careful, forward-thinking approach. Our team helps you plan for **RMDs** (Required Minimum Distributions) and capital gains tax to ensure you aren’t caught off guard by increased **Medicare premiums** and **IRMAA surcharges**
If you have $500,000 in your 401(k) or IRA, it’s not really $500.000. If you’re married and filing jointly, it’s more likely you could have $325,000 (35% tax bracket) or just $315,000 (37% tax bracket).
Tax deferred should read ‘tax delayed’. Do you know what taxes will be when you’re 73/75 and required by the I.R.S. to take distributions? Would you like to [take](https://www.usdebtclock.org/)[ a guess](https://www.usdebtclock.org/)? Tax planning begins with understanding your situation – not just now, but 5, 10, 20+ years down the road!
[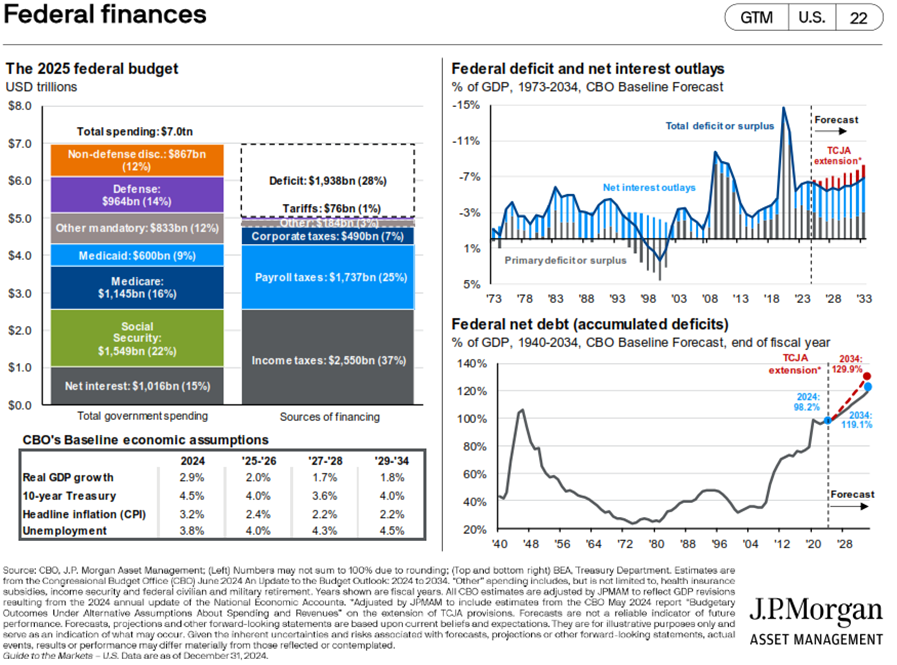](https://indfin.com/wp-content/uploads/2025/02/image.png)It’s not only highly likely your accounts (and therefore your RMDs) will be much larger, but the tax rates may be much higher, too. And, of course, all this will impact the tax rates on your Social Security benefits – and those brackets aren’t adjusted for inflation; so, inflation alone will push many into higher Social Security tax brackets.
Oh yes, tax planning can’t ignore Medicare – those premiums are impacted, too.
**Have You Met IRMAA? Understand How it Affects Your Tax Planning**
IRMAA, or “Income-Related Monthly Adjustment Amount,” is a monthly surcharge added to your **Medicare Parts B and D premiums** based on your income. This surcharge acts like a tax and only applies if your income exceeds $103,000 for single filers or $206,000 for married couples filing jointly.
Let’s break down what this means for you and how **tax planning** can help you avoid unexpected charges.
George and Martha, a high-earning married couple, are participants in **Medicare Parts B and D**. As part of their **tax planning**, it’s crucial to understand that **IRMAA surcharges** are based on income from two years prior. In their case, their **modified adjusted gross income (MAGI)** for the year was projected to reach $322,000, which triggers the IRMAA surcharge on their Medicare premiums.
For couples like George and Martha, **strategic tax planning** is essential to managing IRMAA and minimizing unexpected costs. Understanding how your income impacts your **Medicare premiums** can be a key part of smart financial planning.
On December 1, George, a high-earning individual, decided to sell a stock he had purchased in 2007 for $10,000. He sold it for $11,000, resulting in a $1,000 capital gain. This gain was taxed at the **15% long-term capital gains rate**, along with an additional **3.8% net investment income surtax**. The total federal tax bill for George was 18.8%.
This 3.8% surtax is another crucial factor in **tax planning** for individuals whose **modified adjusted gross income (MAGI)** exceeds $200,000 for singles or $250,000 for married couples. With effective **tax planning**, George could have better managed these taxes, ensuring that the impact on his finances was minimized.
So, George and Martha owe $188 of tax on the gain from their sale of the stock, right – 18.8% of $1,000.
Nope.
If a good definition of a tax is any cost that increases as your income increases, then George and Martha will owe more tax than $188 because the gain from the sale of stock pushed them off the Medicare IRMAA cliff, into paying higher Medicare premiums.
[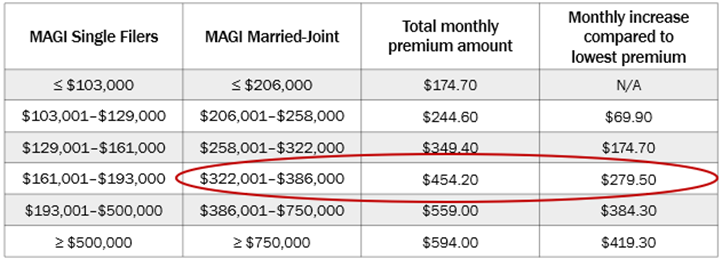](https://indfin.com/wp-content/uploads/2025/02/image-1.png)Look at this Part B IRMAA chart. That extra $1,000 gain pushed their AGI into the next premium tier that starts with $322,001.
So now, instead of owing $349.40 each for their monthly Medicare Part B premiums, George and Martha will owe $454.20 per month, an extra $104.80 per month, times two ($209.60), for an annual total in additional income-related monthly adjusted Medicare Part B premiums of $2,515.20.
But it’s not over. Remember my mentioning Medicare Part D IRMAA charges are also impacted. George and Martha will each another $20.5 per month for their drug plans – an extra $492 for the couple over the course of a year. Adding all the IRMAA surcharges together for the year, George and Martha will each owe an extra $125.30 a month, or more than $3,000 of combined additional charges for the year!
All because of that $1,000 capital gain on the stock sale. Add the $188 they thought they’d pay and the total comes to $3,195.20. That’s a tax rate of 319.5% Yes, you read that right.
[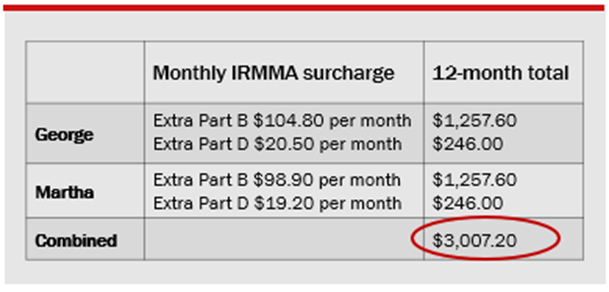](https://indfin.com/wp-content/uploads/2025/02/image-2.png)Let’s do a quick review:
- They sold stock for a $1,000 income gain
- The stock sale tax was: $188 (15% for long-term capital gains and 3.8% for the net investment income tax for high earners, for a 18.8% rate)
- The extra income from the stock sale triggers new IRMAA tiers
- The total IRMAA surcharges amounts for the year to $3,007.20 for George and Martha.
- So, the $1,000 extra income triggers taxes of $3,195.20—319.5% real tax rate!
So, is there a moral here?
Waiting to the end of the year to have your taxes “done” for you isn’t tax planning – it’s after-the-fact cleaning out the barn after the mess has been made.
Tax planning in Simi Valley, CA has to do with the **arrangement of assets BEFORE you add-up the results for the I.R.S.** That’s what financial planning is all about. Common sense stuff: getting ahead of things instead of waiting for the damage.
Need help? [Tell me your priorities](https://indfin.com/retirement-priority-planning-review/) and [arrange an online introductory call](https://go.oncehub.com/JimLorenzenCFP)!
Let’s get your ducks lined-up!
Jim
---
### [Calculator Library](https://indfin.com/calculator-library/)
**Published:** September 23, 2014
**Author:** Jim Lorenzen
**Content:**
**Link Disclosure:** The information being provided is strictly as a courtesy. When you click on any of the links provided here, you are leaving this website and viewing information provided by a third party. We make no representation as to the completeness or accuracy of information provided by any third-party website. Nor is the company liable for any direct or indirect technical or system issues or any consequences arising out of your access to or your use of third-party technologies, websites, information and programs made available through this website. By accessing these calculators, you assume total responsibility and risk for your use of the third-party website.
Retirement:
- [Social security retirement income estimator](https://www.calcxml.com/do/ret04?teaser&c=4a4a4a)
- [How does inflation impact my retirement income needs?](https://www.calcxml.com/do/ret05?teaser&c=4a4a4a)
- [Convert discretionary expenses to savings](https://www.calcxml.com/do/ret08?teaser&c=4a4a4a)
Savings:
- [Becoming a millionaire](https://www.calcxml.com/do/sav01?teaser&c=4a4a4a)
- [How long will it take to double my money?](https://www.calcxml.com/do/sav03?teaser&c=4a4a4a)
- [How long until my savings reach my goal?](https://www.calcxml.com/do/sav04?teaser&c=4a4a4a)
- [Save now vs. save later](https://www.calcxml.com/do/sav05?teaser&c=4a4a4a)
- [How much should I save to reach my goal?](https://www.calcxml.com/do/sav06?teaser&c=4a4a4a)
- [What will my current savings grow to?](https://www.calcxml.com/do/sav07?teaser&c=4a4a4a)
- [Calculate rate of return](https://www.calcxml.com/do/sav08?teaser&c=4a4a4a)
- [How do taxes and inflation impact my return?](https://www.calcxml.com/do/sav09?teaser&c=4a4a4a)
Insurance
- [What is my life expectancy?](https://www.calcxml.com/do/ins02?teaser&c=4a4a4a)
- [What are the chances of becoming disabled?](https://www.calcxml.com/do/ins05?teaser&c=4a4a4a)
- [How much will I earn in my lifetime?](https://www.calcxml.com/do/ins07?teaser&c=4a4a4a)
- [What are the tax advantages of an annuity?](https://www.calcxml.com/do/ins08?teaser&c=4a4a4a)
- [How long will my current life insurance proceeds last?](https://www.calcxml.com/do/ins09?teaser&c=4a4a4a)
Taxation:
- [Federal income tax calculator ](https://www.calcxml.com/do/inc02?teaser&c=4a4a4a)
- [How much self-employment tax will I pay?](https://www.calcxml.com/do/inc05?teaser&c=4a4a4a)
- [What is my tax-equivalent yield?](https://www.calcxml.com/do/inc11?teaser&c=4a4a4a)
- [Tax refund estimator](https://www.calcxml.com/do/inc12?teaser&c=4a4a4a)
- [Tax freedom day](https://www.calcxml.com/do/inc13?teaser&c=4a4a4a)
Home & Mortgage:
- [Comprehensive mortgage calculator ](https://www.calcxml.com/do/hom03?teaser&c=4a4a4a)
- [Should I convert to a bi-weekly payment schedule?](https://www.calcxml.com/do/hom07?teaser&c=4a4a4a)
- [What are the tax savings generated by my mortgage?](https://www.calcxml.com/do/hom09?teaser&c=4a4a4a)
- [Compare an interest-only versus traditional mortgage](https://www.calcxml.com/do/hom13?teaser&c=4a4a4a)
College:
- [Will I be able to pay back my student loans?](https://www.calcxml.com/do/col02?teaser&c=4a4a4a)
- [Advantages of the Coverdell ESA.](https://www.calcxml.com/do/col03?teaser&c=4a4a4a)
- [Advantages of a 529 College Savings Plan](https://www.calcxml.com/do/col04?teaser&c=4a4a4a)
- [What is the value of a college education?](https://www.calcxml.com/do/col05?teaser&c=4a4a4a)
- [What are the payments on a parental (PLUS) loan?](https://www.calcxml.com/do/col06?teaser&c=4a4a4a)
Cash Flow:
- [Should I pay down debt or invest more?](https://www.calcxml.com/do/bud04?teaser&c=4a4a4a)
- [How long will my money last?](https://www.calcxml.com/do/bud05?teaser&c=4a4a4a)
- [Historical inflation – Compare purchasing power](https://www.calcxml.com/do/bud12?teaser&c=4a4a4a)
Credit:
- [How long will it take to pay off my credit card(s)?](https://www.calcxml.com/do/det01?teaser&c=4a4a4a)
- [How long until my loan is paid off?](https://www.calcxml.com/do/det02?teaser&c=4a4a4a)
- [What would my loan payments be?](https://www.calcxml.com/do/det03?teaser&c=4a4a4a)
- [What is the balance owing on my loan?](https://www.calcxml.com/do/det05?teaser&c=4a4a4a)
- [Which is better, cash up front or payments over time?](https://www.calcxml.com/do/det08?teaser&c=4a4a4a)
- [What is the impact of making extra debt payments?](https://www.calcxml.com/do/det09?teaser&c=4a4a4a)
- [Should I pay off debts or invest the money?](https://www.calcxml.com/do/det10?teaser&c=4a4a4a)
Paycheck & Benefits:
- [Convert my salary to an equivalent hourly wage.](https://www.calcxml.com/do/pay03?teaser&c=4a4a4a)
- [Convert my hourly wage to an equivalent salary.](https://www.calcxml.com/do/pay04?teaser&c=4a4a4a)
Auto:
- [Auto purchase – Loan vs. 0% dealer financing?](https://www.calcxml.com/do/aut02?teaser&c=4a4a4a)
- [What would my auto payments be?](https://www.calcxml.com/do/aut03?teaser&c=4a4a4a)
- [Auto loan – Accelerated payoff](https://www.calcxml.com/do/aut05?teaser&c=4a4a4a)
FINRA Calculators:
- [Smart Bond Investing Accrued Interest Calculator](https://www.finra.org/accruedinterest)
- [Retirement Calculator](https://apps.finra.org/Investor_Information/Calculators/1/RetirementCalc.aspx)
- [College Savings Calculator](https://www.finra.org/collegecalculator)
- [Savings Calculator](https://www.finra.org/savingscalculator)
- [401(k) and IRA Minimum Required Distribution Calculator](https://www.finra.org/rmdcalculator)
---
### [Sitemap](https://indfin.com/sitemap/)
**Published:** September 26, 2014
**Author:** Jim Lorenzen
**Content:**
### Primary links
- [Home](https://indfin.com/)
- [All About IFG](https://indfin.com/all-about-ifg/)
- [Jim Lorenzen, CFP®, AIF®](https://indfin.com/your-advisor-jim-lorenzen-cfp-aif/)
- [IFG Services](https://indfin.com/your-advisor-jim-lorenzen-cfp-aif/)
- Investment Philosophy
- [Asset Custody](https://indfin.com/asset-custody/)
- [ All About YOU](https://indfin.com/all-about-you/)
- [ Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist/)
- [Your Values](https://indfin.com/your-values/)
- [Your Goals](https://indfin.com/your-goals/)
- [Your Life Data File](https://indfin.com/your-life-data-file/)
- [The Process](https://indfin.com/ifgplanningprocess/)
- [FAQs](https://indfin.com/faqs/)
- [Getting Started](https://indfin.com/getting-started/)
- [ Contact](https://indfin.com/contact/)
- [Resources](https://indfin.com/resources/)
- [Calculator Library](https://indfin.com/calculator-library/)
- [Video Library](https://indfin.com/video-library/)
- [Articles Library](https://indfin.com/articles-library/)
- [ Whitepaper & Reports](https://indfin.com/ifg-resources/)
- [Jim’s Blog](https://indfin.com/jims-blog/)
### Secondary links
- [Sitemap](https://indfin.com/sitemap/)
- [Privacy Policy](https://indfin.com/wp-content/uploads/2014/09/IFG-Privacy-Policy.pdf)
- [Terms & Conditions](https://indfin.com/terms-conditions)
- [Executive Compensation for Business Owners](https://indfin.com/executive-compensation-for-business-owners/)
---
### [White Papers & Reports](https://indfin.com/ifg-resources/)
**Published:** September 23, 2014
**Author:** Jim Lorenzen
**Content:**
# IFG Resources
### [](https://indfin.com/wp-content/uploads/2014/09/iStock_64047885_SMALL.jpg)White Papers & Reports
[Understanding\_Mutual\_Fund\_Landscape](https://indfin.com/wp-content/uploads/2014/09/i309_WP-Understanding_Mutual_Fund_Landscape.pdf)
[Understanding Investment Returns](https://indfin.com/wp-content/uploads/2014/09/i307_RPT-Understanding-Investment-Returns.pdf)
[IRA Rollover Checklist](https://indfin.com/wp-content/uploads/2017/05/i308a_IRA-Rollover-Checklist.pdf)
[The Fatal Rollover Oversight](https://indfin.com/wp-content/uploads/2019/06/i308b_The-Fatal-Rollover-Oversight.pdf)
[IRA Beneficiary Designations Matter](https://indfin.com/wp-content/uploads/2019/06/i308c_IRA-Designations-Matter.pdf)
[17 Unexpected Retirement Expenses](https://indfin.com/wp-content/uploads/2019/06/i310_17-Unexpected-Retirement-Expenses.pdf)
### [](https://indfin.com/wp-content/uploads/2014/09/its-about-time.jpg)Time & Money
[Learn more](https://indfin.com/time-money/)
### Tools and Strategies
Some useful [Life Guides](https://tinyurl.com/IFGLifeGuides/) and [Worksheets](https://tinyurl.com/IFGWorksheets)
### IFG Blog
[Visit Jim’s Money Blog](https://indfin.com/jim-blog/)
### Tell a Friend
Spread the word about IFG by telling a friend! [Click here to do so.](https://indfin.com/tell-a-friend/)
---
### [Executive Compensation for Business Owners](https://indfin.com/business/executive-compensation-for-business-owners/)
**Published:** September 20, 2014
**Author:** Jim Lorenzen
**Content:**
### Why Install an Executive Compensation Plan?
Simple. Quite often qualified plan contributions, even at the limits, will be inadequate to meet the retirement income needs of highly compensated employees.
Executives at companies with 401(k) plans actually often find they’re severely limited by plan limits as to how much they can contribute; and, that severely limits their ability to achieve the necessary levels of retirement income to continue their pre-retirement standard of living, even when coupled with Social Security.
For example, it’s not uncommon to find that a typical wage earner will achieve about 60-80% of final compensation from a combination of Social Security and qualified plan distributions. But, a highly-compensated executive (HCE) may only achieve retirement income of about 10-30% of final compensation.
### Will Your Top Executives Exercise “Free Agency”?
It’s no secret: It can take years to find or develop the executive talent needed to build the business to the next level. Not only is executive talent is hard to come by, it is even more difficult to replace when it walks out the door.
What keeps a key executive? There are many reasons, of course; but, a strong monetary incentive package is likely a bedrock requirement. People tend to stay where they feel appreciated and appropriately rewarded. Structured incentive plans can help keep key executives in place and motivate them to higher levels of performance.
Plans such as Nonqualified Deferred Compensation, Executive Bonus, and Split Dollar Life Insurance are quite often life insurance-based plans utilized by business owners because they enable the business to offer current and future benefits to their key executives in exchange for their continued service for a specified period of time. 1
### Nonqualified Deferred Compensation Plan
A nonqualified deferred compensation (NQDC) plan is an arrangement between an employer and a key employee whereby the employer agrees to pay additional compensation for a specified period of time in exchange for the continued service of the employee. When certain tax code requirements are met, this arrangement allows the employer to single out highly compensated employees for the purpose of rewarding them for their contributions to the company, and as an incentive for the employee to stay with the company.2
The amount of compensation to be deferred is agreed upon by the employer and the employee. The plan can be funded or unfunded. If it is funded the employee must be at risk to forfeit his rights to the compensation or else it will be currently taxable. In other words, the money becomes taxable once ‘vested’. As long as the compensation is beyond the control of the employee, it isn’t currently taxable; so, the key is to avoid “constructive receipt” by the key executive. An unfunded plan, of course, allows for the taxation of compensation to be deferred until it is actually received.
Many plans are informally funded through the use of life insurance which is owned by the employer on the life of the employee. The accumulated cash value funds the plan and is distributed as compensation over a specified period of time. The death benefit paid to the company is available to compensate the family of the employee if death occurs prior to the planned distribution. The employer may also use the death benefit proceeds to offset the cost of funding the plan. The distributions are taxable to the employee when they are received and the employer receives a tax deduction as the benefits are paid.
### Executive Bonus Plan
Another way an employer can reward selected key employees is through an Executive Bonus Plan (IRC Sec. 162). Under this approach, the employer bonuses the employee for the premium paid by the employee for a life insurance policy owned by the employee. The policy, including the cash values, belongs to the employee who can maintain the coverage on his own if he were to leave the employer.
The bonus which equals the amount of the net premium payment is considered to be additional compensation to the employee and is taxed currently. In some cases, an employer will bonus an extra amount to offset the employees tax on the premium. The bonuses are tax deductible to the employer.
Executive compensation plans such as nonqualified deferred compensation and executive bonus plans involve legal, tax and insurance issues. The guidance of a qualified tax or financial professional is strongly recommended.
For more information on executive compensation plans for business owners, please [contact us today.](https://indfin.com/contact/)
*1 Nonqualified deferred compensation arrangements may be funded, unfunded, or informally funded with the use of life insurance policy.*
---
### [Articles Library](https://indfin.com/articles-library/)
**Published:** September 19, 2014
**Author:** Jim Lorenzen
**Content:**
For Business Owners
- Planning for Business Owners
- [ Executive Compensation for Business Owners ](https://indfin.com/executive-compensation-for-business-owners)
- Business Succession Planning
For Wealth Management
- [Retirement Planning](https://indfin.com/retirement-planning)
- [Charitable Giving](https://indfin.com/charitable-giving)
Planning to Roll-Over your 401(k)? You may want to do some homework first. See our IRA Rollover Checklist to see if the rollover decision is the right one for you.
[Click Here for your checklist!](https://indfin.leadpages.co/leadbox/141e8f273f72a2%3A12a1899aa346dc/5761253830033408/)
---
### [Time & Money](https://indfin.com/time-money-2/)
**Published:** September 25, 2014
**Author:** Jim Lorenzen
**Content:**
It’s about time!
There are three factors that will affect your future financial success:
1. How much you set aside for your future
2. The rate at which your money grows, after taxes and inflation
3. How long do your saving before you retire
#### These three factors are related!
For example, if you achieve a higher rate of growth than you expected, you probably won’t have to save as much to reach your goals. However, if your returns are less than you expected, you either won’t reach your goals or you’ll have to save more money than you had planned. It’s worth noting that many pension plans, both private and public, throughout the U.S. are having trouble meeting their obligations because they didn’t set-aside enough money based on projected rates of return that didn’t materialize. As the Chief Executive Officer of your own individual investment company trying to achieve a secure retirement income for yourself, you don’t want to fall into this trap.
While these factors are related, they’re not alike!
**How much you save:** This can be adjusted up or down, though most people do feel limited due to other obligations, i.e., saving for college, paying a mortgage, property taxes, medical bills, and all the other things that place demands on income and assets. But you do have some control over this factor.
**Rate of return:** This can be adjusted up or down, as well; but you have little to no control since the marketplace determines the value of assets, including even the interest you receive on bank accounts. Even as interest rates rise, achieving a positive real return – after taxes and inflation – can often prove problematic. Even a ‘guaranteed’ rate that may look good today could look bad tomorrow in a high-inflation environment, especially if governments (national, state, and local) find additional ways to take your money, whether at the gas pump, the checkout, or through other assessments.
**Time:** This is the ONLY factor YOU can control. There’s a catch: It’s also the ONLY factor that doesn’t expand. Time only decreases. Yes, you can work longer provided your health continues to be good and you’re able to either find work or start a business; but, it’s worth noting a lot of Harvard MBAs are out of work and the odds of making a business succeed are against you at any age, let alone post retirement. Even if you work past 65, how far past 65 can you work? While some work even to age 80, you may not want to count on it.
---
### [Tell a Friend](https://indfin.com/tell-a-friend/)
**Published:** September 25, 2014
**Author:** Jim Lorenzen
**Content:**
We grow our business through client referrals. If you’ve been happy with our services and our work together, please tell a friend!
Filling out the following form is a quick and easy way to let others know about our services. The mandatory fields are denoted with an asterisk (\*).
Note that your friend’s e-mail address and name will not be sent to us and will not be used for any purpose other than to send him/her your message. All information is confidential. Remember that e-mail is not a secure medium, and so personal information should be transmitted by more secure means.
\[contact-form-7 id=”311″ title=”Tell a Friend”\]
---
### [Tell a Friend](https://indfin.com/thank-you/)
**Published:** September 25, 2014
**Author:** Jim Lorenzen
**Content:**
Thank you! Your submission has been received.
Click [here](https://indfin.com/) to return to the home page.
[Go back to the form](https://indfin.com/tell-a-friend/)
---
### [Resources](https://indfin.com/resources/)
**Published:** September 8, 2014
**Author:** Jim Lorenzen
**Content:**
Here are some useful resources you might like:
#### Social Media Pages
- [LinkedIn](https://www.linkedin.com/in/jimlorenzencfp)
- [Twitter](https://twitter.com/JimLorenzen)
- [Facebook](https://www.facebook.com/IFGAdvisory)
#### Resource Links
- - [Watch House & Senate Live on CSPAN](https://www.c-span.org)
- [The Conference Board](https://www.conference-board.org)
- [The IRS](https://www.irs.gov)
- [The Federal Reserve](https://www.federalreserve.gov)
- [Social Security Administration](https://www.ssa.gov)
#### More resources:
- [ Calculator Library](https://indfin.com/all-about-you/)
- [Are You On Track](https://indfin.com/all-about-you/)? Will you achieve your goals? This exercise may help you see if you’re on your way!
**Link Disclosure:** The information being provided is strictly as a courtesy. When you link to any of the websites provided here, you are leaving this website. We make no representation as to the completeness or accuracy of information provided at these websites. Nor is the company liable for any direct or indirect technical or system issues or any consequences arising out of your access to or your use of third-party technologies, websites, information and programs made available through this website. When you access one of these websites, you are leaving our website and assume total responsibility and risk for your use of the websites you are linking to.
---
### [Get My Retirement Plan Started](https://indfin.com/getmyplanstarted/)
**Published:** April 16, 2015
**Author:** Jim Lorenzen
**Content:**
**Want to get started on getting retirement planning help?** The first step is to recognizeall the issues involved and review your priorities! Here are two helpful pieces to get you started. Just click on the titles to open and download.
[](https://indfin.com/wp-content/uploads/2015/04/IFGi_LifeGuide_Thinking_About_Retirement_vsa_001.png)
The[IFGi\_LifeGuide\_Thinking\_About\_Retirement](https://indfin.com/wp-content/uploads/2015/04/IFGi_LifeGuide_Thinking_About_Retirement_vsa.pdf)will help you go through the checklist of important issues to consider.
Are you considering whether to spend or rollover your 401(k) to an IRA. You might find this short video worth viewing:
[](https://indfin.com/wp-content/uploads/2015/04/IFGi_RetirementPriorityReview_vsa_0011.png)The [IFGi\_RetirementPriorityReview](https://indfin.com/wp-content/uploads/2015/04/IFGi_RetirementPriorityReview_vsa.pdf)will help you organize your priorities. You can download this form to your hard-drive and fill it in at your convenience!
[](https://indfin.com/wp-content/uploads/2014/09/Home_Office_Woman_On_Phone.jpg)*Fotilla Images*Once you’ve collected your thoughts and priorities, you might want to [schedule an introductory phone call](https://www.meetme.so/JimLorenzenCFP) with Jim Lorenzen, CFP®. You can avoid phone tag by using IFG’s convenient scheduler. You can arrange your call [here](https://www.meetme.so/JimLorenzenCFP).
---
### [Financial Conversation Checklist](https://indfin.com/financial-conversation-checklist/)
**Published:** September 15, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a5116fb332970c-320wi3.jpg)Jim Lorenzen CFP® AIF®Planning your retirement success is like building a home: it takes some advance planning. Checklists are useful tools.
**Here’s a financial planning conversation checklist you might helpful before you call me** (or any other advisor – Naturally, calls are always welcome, but preparation is always better, I’m sure you would agree.)
**The first step** is to determine what’s important to you (and your spouse). Here’s a [Financial Conversation Checklist ](https://indfin.com/wp-content/uploads/2014/10/Financial-Conversation-Checklist1.pdf)that’s worth downloading and reviewing together with your spouse.
**Then, you might find these helpful** before picking-up the phone .
- **How do you get value from a relationship with an advisor?** You might want to [download this](https://indfin.com/wp-content/uploads/2014/09/i109_How-To-Get-Value-from-an-Advisor-Relationship.pdf)!
- **What will the first meeting look like?** Here’s a [sample agenda](https://indfin.com/wp-content/uploads/2014/09/i110_First-Meeting-Agenda-1.pdf).
- **What should you bring to the meeting?** Here’s a [sample checklist](https://indfin.com/wp-content/uploads/2014/09/i108_First-Meeting-Checklist.pdf).
[](https://indfin.com/wp-content/uploads/2014/10/6a017c332c5ecb970b01a73dd6f67e970d-320wi1.jpg)*iStock Images***Ready to arrange a call with me?** Before you do, just follow these steps:
1. Use this tool to [review your priorities](https://indfin.com/wp-content/uploads/2023/12/C100H2_RetirementPriorityReview_vsa.pdf). You can save it to your hard drive, fill-it out, then forward it to me (instructions are on the form). This will help me address your issues during our call.
2. Arrange your introductory phone call with me by using our convenient scheduler! It’s easy, avoids phone-tag, and you can pick a time that’s convenient for you! Just click [here](https://www.meetme.so/JimLorenzenCFP).
I look forward to talking with you!
Jim
---
### [CRS Additional Information -Conflicts](https://indfin.com/crs-conflicts/)
**Published:** June 26, 2020
**Author:** Jim Lorenzen
**Content:**
 **When I act as your investment advisor, I have to act in your best interest and not put my interest ahead of yours.** At the same time, the fact is conflicts are unavoidable, no matter how much we like to pretend they don’t exist. The way I make money – the way anyone makes money – creates some conflicts with your interests. All compensation forms contain some inherent conflict:
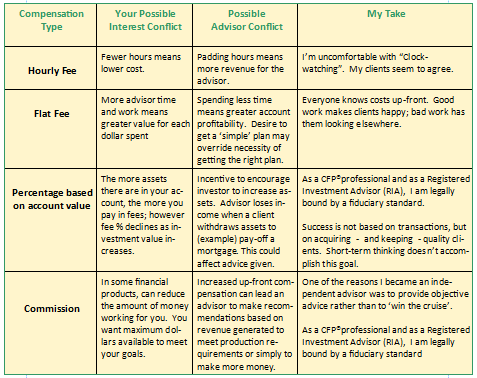My **financial planning services** are under a flat-fee arrangement, quoted in advance and investment advisory services are based on a percentage of account value. See my compensation structure at [indfin.com/CRS/fees](https://indfin.com/crs/fees).
**I routinely offer a written Fiduciary Oath to my clients**. You should ask any advisor you are considering if they’re willing to sign a fiduciary oath pledging to act in your best interest.
Research any firm you are considering. Go to [FINRA’s Broker Check](https://brokercheck.finra.org/) site to check any firm you’re considering. Just type the name into the second box to see if there are any regulatory histories.
Note: I am not a broker; I am a Registered Investment Advisor (RIA). Unfortunately, by lumping broker and RIA regulatory information onto a single website still labeled “broker check”, it’s just one more example of why many investors don’t understand the difference. Who can blame them?
---
### [Charitable Giving](https://indfin.com/charitable-giving/)
**Published:** September 20, 2014
**Author:** Jim Lorenzen
**Content:**
You don’t have to be Warren Buffett or Bill Gates to leave a legacy to a charity; and, you don’t have to forsake your heirs, either. Want to help support art, science, or education? Everyone has their own reason for gifting their assets or a portion of their income to charitable organizations. Some find comfort in helping others who are less fortunate, while others simply want to share their good fortune. Many of the institutions are supported in large part by those who want to give something back in appreciation for their contributions to the community or the individuals themselves.
Currently, the tax code offers incentives for gifting of one’s assets or incomes. Tax deductions are given for current contributions and, for estate owners, charitable gifts can reduce the size of the estate to help minimize estate taxes.
Usually, an individual will designate a charitable beneficiary in their will to benefit the organization after the individual dies. By using charitable gifting techniques, a donor may be able to benefit the charity while living without having to sacrifice the income that those assets can generate. Understanding how properly structured charitable gifts can provide current benefits for both the donor and the charity could be important for the charitably inclined.
### Charitable Remainder Trust
A charitable remainder trust (CRT) enables the donor to transfer an asset while retaining the right to the income it generates. The asset itself becomes the “remainder” which is owned by the charity. Remainder trusts, if properly structured, can qualify for a current tax deduction. Not bad: The donor can donate, receive a tax deduction, and still live off the income the asset generates! There are three types of remainder trusts:
**Unitrust:** A charitable remainder unitrust (CRUT) is calculated so that the income the donor receives is based on a percentage of the current fair market valuation of a trust asset. Each year, as the asset is valued, the income is adjusted based on the new valuation. Of course, asset values can fluctuate, meaning the income can fluctuate, too.
**Annuity Trust:** Instead of a percentage of the asset value, the donor is paid a fixed amount annually from a charitable remainder annuity trust (CRAT). So, this one’s like an annuity. The income is fixed.
**Pooled Income Fund:** Donors can pool their donated assets in a fund that is operated by the charitable organization. The donors then receive a proportionate share of income from the fund that is paid throughout their lifetime. Payments can vary each year based on the valuation of the underlying assets in the fund.
### Charitable Lead Trust
This operates as the reverse of a remainder trust. Also known as an Income Trust this vehicle transfers the income rights to the charitable organization. Generally, the income rights are assigned for a specified period of time after which the remainder passes to the donor.
Charitable planning involves tax issues that should be discussed with a qualified tax or financial professional.
For more information of charitable planning, please [contact us today.](https://indfin.com/contact)
---
### [Business Owner Issues](https://indfin.com/business/)
**Published:** November 18, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/11/JL-HR-0092-cropped-tight.jpg)Jim Lorenzen CFP® AIF®
**Business owners aren’t all alike.** Neither are financial advisors.
Unlike many financial advisors or many other *CERTIFIED FINANCIAL PLANNER®professionals*, I’ve actually owned businesses; not just one, but several outside the financial profession – and all going full-cycle from founding to exit. I know what it’s like to work with suppliers, employees, and customers – and what it’s like to make a payroll.
My businesses were in publishing weekly papers and shoppers – a business that combines the elements of a service business with those of manufacturing and distribution – so, I can relate to the central issues business owners face every day.
**Business owners live in a world a bit different from everyone else.**
While most people work at their careers and need to budget their spending and saving to navigate a path to a successful retirement, business owners must deal with a myriad of additional complex financial decisions not required of others.
**Business owners navigate two tracks instead of one:** Personal and business; and the integration of these two tracks in a business owner’s planning are critical to the business owner’s ultimate success.
**[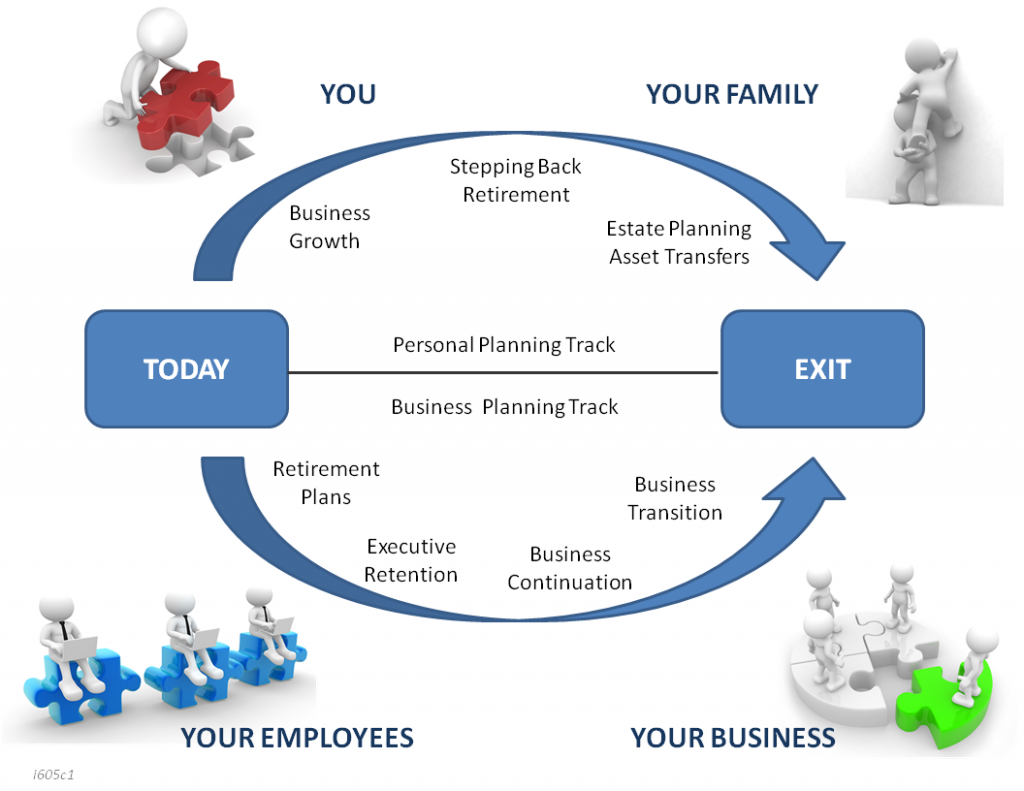](https://indfin.com/wp-content/uploads/2016/11/i605c1_BO_Lifecycle_slide_201611.png)**
What are YOUR PRIORITIES?
[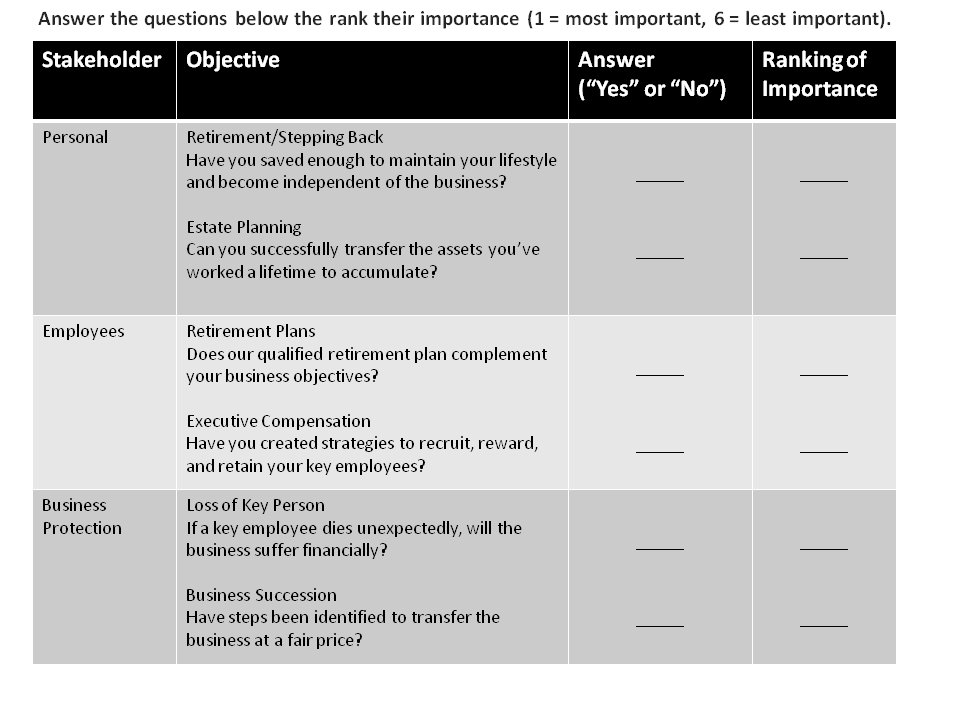](https://indfin.com/wp-content/uploads/2016/11/i605d_BOLD-Q-Priorities_Initial.png)
**Personal: Strategies addressing personal concerns:**
**Retirement/Stepping back**
Successful business owners often find 401(k) and similar plans simply aren’t enough – too restrictive – and seek solutions that will provide them with the retirement income they desire without the contribution limits and [](https://indfin.com/wp-content/uploads/2016/11/Tax-Burden-Scale.png)administrative headaches they want to avoid.
Your retirement strategy should reflect your vision for retirement: will you retire completely, or simply step back from actively managing your business?
By limiting the amount of taxes you pay in retirement, the less likely future tax law changes will impact your planning and the more comfortable your retirement will likely be. The added benefit, of course, is the I.R.S. has less chance of becoming an heir. [More on business owner retirement planning](https://indfin.com/ownerretirement).
**[](https://indfin.com/wp-content/uploads/2016/11/Business-Owners-Puzzle.png)Estate planning – Transferring assets**
Traditional estate planning focuses on what happens to assets at a business owner’s death. What many don’t realize is that estate planning also provides the opportunity to focus on assets while the business owner is alive.
A business-owner centered estate plan can maximize how you can **enjoy life today and in retirement,** and also maximize the assets you pass on to your family.
**Strategies addressing business concerns:**
**Executive retention – Keeping Key People**
Key employees make critical contributions to a company’s profitability. Selective executive compensation benefits reward those employees most responsible for company growth and allow key employees to share in business accomplishments. Often business owners use supplemental retirement plans and strategic compensation designs to create “Golden Handcuffs”, which can provide a strong incentive for one or more key people to remain with the business long-term, rather than accept an attractive offer from a competitor. The type of design chosen depends upon the business’ unique characteristics. [More on executive retention here](https://indfin.com/executivecompensation).
**Key person protection**
The death of a key employee could cause serious problems for a business, such as lost sales, lower earnings and loss of intellectual capital. It could even affect supplier and banking relationships.
The cost of hiring and training a replacement could negatively impact the business. Successfully dealing with issues like this require a strategy to help cover those costs and to help the business continue to operate smoothly after losing a key employee. [More on business continuity.](https://indfin.com/businesscontinuity)
**[](https://indfin.com/wp-content/uploads/2016/11/Dollar-Sign-and-characters-surrounding.png)Business Continuation & Succession**
A business succession strategy is a key to a company’s success and survival. Having a ‘ready-made’ buyer in-place with secured funding can solve a lot of problems BEFORE they occur. Strategies such as buy-sell arrangements can successfully transfer a business interest on the business owners’ terms. The key is advance planning and a valuation everyone can agree on.
An informal business valuation can avoid the cost of a formal appraisal, yet provide the means for establishing value when the time for transfer arrives. [More on business succession](https://indfin.com/businesssuccession)
See IFG’s [menu of business services](https://indfin.com/business/ownerservices/).
**How to Begin**
The first step is an introductory phone call. You can arrange a call with me at a time that’s convenient for you by simply using our [convenient scheduler](https://www.meetme.so/JimLorenzenCFP).
I hope we have a chance to talk and maybe meet. I look forward to helping you reach your goals as your unofficial CFO.
Jim
[](https://indfin.com/wp-content/uploads/2014/09/Resized-CFP_Logo_Gold.jpg)
[](https://indfin.com/wp-content/uploads/2014/03/6a017c332c5ecb970b01a51174cbb0970c-120wi.jpg)
**Areas of expertise include:**
- Non-qualified deferred compensation plans including Supplemental Executive Retirement Plans (SERPs)
- Individually-owned supplemental savings and benefits arrangement
- Corporate-owned life insurance (COLI) informal funding arrangements
- Corporate-sponsored annuity options
- Executive bonus programs
- Life insurance plans (including; various forms of split-dollar, carve-outs, etc.)
---
### [CRS and ADV Disclosures](https://indfin.com/crs/)
**Published:** June 26, 2020
**Author:** Jim Lorenzen
**Content:**
**Customer Relationship Summary and Additional Information**
**Jim Lorenzen, CFP®, AIF®**
 **Welcome to the IFG Disclosures page**!
Here you’ll be able to easily access disclosures for The Independent Financial Group. Much of the language is mandated, including the questions, form, and length; however, since mine is a solo private practice, you should find my business model and much of the language comparatively easy to understand. Naturally there are links to additional information and you’ll find even more here on my website, including links that will enable you to check on the disciplinary history of any advisor you are considering.
You can access my Customer Relationship Summary (CRS) [here](https://indfin.com/wp-content/uploads/2023/08/C100L_IFG_CRS.pdf).
You can access The Independent Financial Group’s ADV filing [here](https://indfin.com/wp-content/uploads/2023/08/C100L2IFG-ADV-2A-2B_2-2023.pdf).
If you have any questions, feel free to call me at 805.265.5416 or email me: .
Happy reading!
Jim
---
### [CRS Additional Information: IFG Services](https://indfin.com/crs-services/)
**Published:** June 26, 2020
**Author:** Jim Lorenzen
**Content:**
**Information: Services**
**What investment services will you provide me?**
 **Services I provide for individual private clients fall into three broad categories:**
**Phase One:** **Financial Planning Services**
- Process following the CFP® Board’s 7-Step process and fiduciary guidelines.
- Organizing your current investment and insurance information to help you understand how they interrelate and to identify your current needs.
- Setting long-term goals and intermediate-term objectives and prioritizing what’s important to you.
- Identifying available strategies for wealth accumulation, preservation, distribution, and legacy strategies.
- How/when it’s best for you to begin taking Social Security
- Identifying the most efficient ways of arranging assets in order to reduce risk, taxes, and investment costs.
- Plans are continually updated and reviews are arranged according to a schedule convenient for you.
**Phase Two:** **Investment Advisory Services**
- At the end of your financial plan I will create an Investment Policy Statement (IPS) for your review.
- I will also tailor, for your approval, the selection of the investment puzzle pieces that meets your needs, including providers for investment due-diligence, asset custody (I do not take custody of your assets at any time), investments including ETFs, mutual funds, and institutional wrap-fee programs for investment management and reporting.
- If you are a conservative investor, you may be happy to know I do not provide advisory services regarding private placements, limited partnerships, or initial public offerings (IPOs). I do provide access to institutional money managers and various wrap-free programs including third party money managers and investment models, if you should so desire and where appropriate.
**Phase Three: Financial Plan and Investment Plan Reviews:**
Reviews will be conducted on a schedule appropriate and convenient for you. In addition, you will have 24/7/365 direct access to your financial plan and investment accounts. In addition, your financial plan will be automatically updated daily to reflect any changes in value for the assets you’ve placed through my services.
**Life Insurance**
This area generally comes into play for legacy, estate, wealth replacement protection, charitable giving and tax-advantaged/supplemental retirement strategies.
**More Information**
Free and simple tools are available to research firms and financial professionals at , which also provides educational materials about brokers, investment advisors, and investing. Unfortunately, the videos seem to convey the impression that all “advisors” are brokers and investment advice is the only service offered and never considers financial planning, how registered investment advisors differ from brokers, and other technical services as part of the value mix.
The fiduciary standard has been ‘watered-down’ as of late; however, I routinely offer my clients a written and signed Fiduciary Oath.
Jim
---
### [CRS Additional Information - Fees](https://indfin.com/fees/)
**Published:** June 26, 2020
**Author:** Jim Lorenzen
**Content:**
 **Additional Information: What fees will I pay?**
All IFG planning and investment advisory fees are fully disclosed and explained in writing with all questions answered before you enter into a planning or advisory agreement. You will also be given a copy of my privacy policy and my written Fiduciary Oath.
**The concept behind the IFG fee structure is simple:** Ongoing services, i.e., financial planning and investment advisory services, use an ongoing compensation model. Processes requiring few or no ongoing services, i.e., life insurance, are not charged ongoing fees and use a single compensation model. All fees are clearly explained in all IFG proposals and are mutually agreed upon prior to you becoming a client.
**Compensation Breakdown:**
**Financial Planning and Investment Advisory Fees:**
I.**Your Initial Financial Plan:**
(a) The first step: Learning about you. The formal term is “Gap Analysis”, but it amounts to the same thing. This is where we gather all information about your current situation, as well as your priorities, views, and goals. Retainer: $750.
(b) The second step: Financial Planning. This is a collaborative process and could take several meetings, either in-office or online (your choice). **A completed financial plan is a requirement for becoming an IFG investment advisory client**, this initial planning fee is quoted on a defined-project basis. You will receive a written proposal with everything clearly spelled-out.
II.**Ongoing investment advisory services with financial plan reviews and updates.**
**The two components of financial planning and investment advisory services go hand-in-hand at IFG** and compensation for each depends on the size and complexity of each case and is based as follows:
- **Assets Under Advisement (AUA) – $500,000 minimum.** Family accounts are aggregated for fee computation.
**Plan review component:** A separate fee for subsequent financial planning review and update services is charged for **‘held-away’ assets only** (those not covered by an IFG investment advisory agreement) with IFG’s planning fee discounted equal to the percentage of the client’s total financial assets placed through the services of IFG. Example: If 75% of your financial assets are placed through IFG, your fee for the ongoing planning reviews concerning ‘held-away’ assets is discounted at 75%. Obviously, if 100% of assets are placed through IFG, there is no separate fee for reviews and updates. This structure ties IFG’s compensation not only to portfolio performance, but also to cost efficiency.
**Investment advisory component**: Advisory fees are paid according to the investment advisory fee schedule (below) which encompasses all ongoing financial planning review and update meetings and services for assets placed through IFG, including investment advisory services, encompassing ongoing due-diligence, monitoring, and client education. The investment advisory fee is asset-based and automatically deducted on a quarterly basis in accordance with IFG’s investment advisory fee schedule by the custodial firm and fully disclosed. Advisory fees typically range from 0.55% to 1.20%.
****IFG’s investment advisory fee schedule\*\*****
Annual investment advisory fees are computed based on asset balances and deducted on a quarterly schedule by the asset custodian (IFG does not take custody of client assets). Quarterly fee deductions are fully-disclosed in advance and on client statements. IFG does reserve the right to waive the $500,000 asset minimum in certain instances. Accounts falling below the minimum are charged an additional quarterly fee of $450.
**Investment Management Advisory Asset Based Fees1** On the first $500,000 1.20% On the next $500,000 0.70% On assets above $1 million 0.50% As you can see, as your asset size increases, the fee percentage declines.
[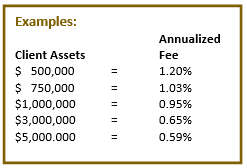](https://indfin.com/wp-content/uploads/2021/04/Fee-Examples-1.png)**Points worth noting:**
- **Please keep in mind that all fees are subject to adjustment based on each client’s unique circumstances and goals. IFG’s working arrangement will be provided to you in writing after a needs/gap analysis has been completed.**
- **Asset Custody:** IFG does NOT take custody of client assets. Accounts will be in your name (or trustee you designate) at an independent third-party custodian, most often Pershing/Bank of New York-Mellon. IFG has no access to client funds. All fee billing services are provided by independent third-party providers in accordance with clients’ written instructions contained in IFG’s investment advisory agreement.
- **Referral Compensation Arrangements**: IFG does not pay or receive compensation, or any other material economic benefit, either directly or indirectly, involving any third party professional or individual for recommending the selection or retention of professional services for a client. IFG may, from time to time, utilize the services of a third-party referral service who is paid in order to provide compensation for marketing expenditures.
- **Insurance services**: There are some instances, as noted above, where ongoing advisory fees would seem inadvisable. For example: “fixed” insurance products generally do not require continuous or ongoing manager due-diligence, oversight, and portfolio review – therefore it would seem inconsistent to charge ongoing advisory fees. Examples would include the placement of life insurance or fixed annuities, generally used when estate protection, charitable giving, or other needs when insurance products are either the only logical tool or an appropriate supplement available in the “financial toolbox”. Insurance is provided under California license #0C00742. In California, licensed agents are not allowed to charge fees for insurance placement and non-licensed professionals are not allowed to provide guidance on specific policies.
**Financial planning fees can be paid by bank ACH or credit card and monthly or quarterly subscription fees can be arranged for certain services.**
All fee arrangements, however, do contain inherent conflicts of interest. [I’ve addressed ](https://indfin.com/crs-conflicts)[these ](https://indfin.com/crs-conflicts)[here](https://indfin.com/crs-conflicts). Of course, if you have any questions, you can [arrange a call with me here](https://indfin.com/getting-started/) or email me at info@indfin.com.
\_\_\_\_\_\_\_\_\_\_\_\_\_\_\_\_\_\_\_\_\_\_\_\_\_\_\_
*\*Generally limited to children and grandchildren of current IFG clients.*
*\*\*Applies to IFG planning and advisory services only. Fees do not include advice on assets not covered under an advisory agreement, or third party fees or expenses which may be charged for custodial, management, or reporting by other third party providers. This schedule does not include or apply to compensation for assets placed in insurance products required to fulfill a plan. Annual fees are deducted on a quarterly basis by the asset custodian according to the schedule(s) outlined in the proposal and platform provider’s fee agreement(s). Clients engaged prior to January 2, 2021 may be paying fees that differ from this schedule for the same services. IFG’s ADV filing is available upon request. All fees are subject to change without prior notice. However, clients must sign amendments to any agreements impacted by the fee changes.*
---
### [Safe Money: Asset Custody and Strategic Partners](https://indfin.com/asset-custody/)
**Published:** September 15, 2014
**Author:** Jim Lorenzen
**Content:**
Safe money is important. **The Independent Financial Group does not take custody of client assets at any time**; nor does IFG have access to client assets; nor does IFG receive any compensation or incentives of any description from the custodians selected. Client accounts are opened in the client’s name at an independent third-party custodial firm which takes physical custody of client assets.
### SEI Private Trust Company
**Safety First**: Have you ever asked yourself why your bank carries FDIC insurance? Why virtually all investment firms carry SIPC plus additional insurance? The simple answer is they have to. You see, the money – your money – is held in the institution’s name, not yours.
It’s referred to as holding assets in “street name”. The money is actually an asset of the firm that can be attached by creditors if the institution should fail, leaving insurance to cover, up to a limit, investor losses. Remember the 2008-9 credit melt-down when banks and firms that were too big to fail actually did? Insurers were unable to cover all investor losses because the institutions were using client money for leverage while using insurance to protect the clients.
**At SEI, assets are *not* held in street name.** They are not an asset of the firm because the investments are held at an independent trust company **in the investor’s name,** and subject to more regulatory scrutiny than the typical brokerage/custodian firm. If the firm goes bankrupt, creditors have no claim on the investments–they’re owned by the investors in trust, not as assets of the custodian firm. That alone is worth some thought.
**SEI**
SEI, founded in 1968, is one of the world’s largest providers of wealth management solutions, with over 5,000 employees and $1.3 trillion in assets (as of September 30, 2023) and offices in the U.S., Canada, Ireland, India, Luxembourg, South Africa, and United Kingdom. Through times of radical change, SEI has been a constant in the financial services industry. SEI has never been bought or sold, and, despite their growth, has been at the forefront of innovation. They’ve been able to take a complex business model and make the processes simple for the end-investor. SEI also has an impressive stable of well-known institutional and corporate clients with which they work closely, in the same fiduciary capacity that I serve you.
And, you’ll love[ SEI’s ](https://www.seic.com/rias-independent-advisors/investor-portal-investor?_gl=1*oorp12*_gcl_au*MTgzMjk3NTU0OS4xNzIxOTI2Mzkx*_ga*MTc0NjMyMTE2LjE3MTI2OTQxMTM.*_ga_MT7NE92F3W*MTcyNTU2NTA5OC4zNy4xLjE3MjU1NjU1NTcuMTkuMC4w)[technology](https://www.seic.com/rias-independent-advisors/investor-portal-investor?_gl=1*oorp12*_gcl_au*MTgzMjk3NTU0OS4xNzIxOTI2Mzkx*_ga*MTc0NjMyMTE2LjE3MTI2OTQxMTM.*_ga_MT7NE92F3W*MTcyNTU2NTA5OC4zNy4xLjE3MjU1NjU1NTcuMTkuMC4w)[.](https://www.seic.com/rias-independent-advisors/investor-portal-investor?_gl=1*oorp12*_gcl_au*MTgzMjk3NTU0OS4xNzIxOTI2Mzkx*_ga*MTc0NjMyMTE2LjE3MTI2OTQxMTM.*_ga_MT7NE92F3W*MTcyNTU2NTA5OC4zNy4xLjE3MjU1NjU1NTcuMTkuMC4w)
### The smart way to manage:
- **Your advisor is independent of the asset custodian**. IFG receives no compensation from Pershing.
- Your **reporting** is objective, **provided by independent third parties** not related to IFG.
- There are no ‘revenue-sharing’ or ‘back-door’ compensation arrangements.
- **All charges and compensation are transparent.**
To put it bluntly: IFG is not in a position to “cook the books” or put it’s hand in the cookie jar. [The independent model simply makes sense.](https://indfin.com/wp-content/uploads/2015/01/Ifgdifference-1.mp4)
If this all makes sense to you, IFG may provide the ‘right-fit’ advisory model to help plan your future.
Ready to get started! You can [get the ball rolling here](https://indfin.com/getting-started/)!
---
### [Asset Protection Planning - A Common-Sense Primer to Get You Started.](https://indfin.com/asset-protection-a-common-sense-primer-to-get-you-started/)
**Published:** February 17, 2025
**Author:** Jim Lorenzen
**Excerpt:** Money doesn’t just grow on trees. No news there. Once you've worked hard to build your wealth, you want to make sure it stays safe – that’s what asset protection is all about.
**Content:**
Money doesn’t just grow on trees. Once you’ve worked hard to build your wealth, you want to make sure it stays safe—that’s where **asset protection planning** comes in.
Life can throw curveballs—lawsuits, economic downturns, unexpected emergencies—and without the right protections in place, your hard-earned assets could be at risk. **Asset protection planning** helps you create strategies to shield your wealth from these unpredictable challenges, ensuring your assets remain secure no matter what life throws your way.
The good news? With a little foresight and some common-sense strategies, you can shield your finances from many threats. **Asset protection planning** helps you take proactive steps to safeguard your wealth. Here’s a practical ‘primer’ to walk you through no-nonsense, effective ways to protect your financial future from unexpected challenges.
[](https://indfin.com/wp-content/uploads/2025/02/Couple_in_car.png)**Understanding the Risks to Your Assets**
Before we dive into asset protection planning in Simi Valley, let’s first understand what you’re up against. Your assets—whether cash, property, investments, or business holdings—can be vulnerable to several threats. Effective asset protection planning helps you identify and guard against these risks, ensuring your wealth remains secure in the face of unexpected challenges.
1. **Lawsuits** – Whether from business disputes, accidents, or even personal liabilities, lawsuits can drain your wealth quickly if you’re not prepared.
2. **Economic Downturns** – Market fluctuations, recessions, or industry collapses can devalue your investments.
3. **Debt and Creditors** – If you owe money, creditors can seize assets to satisfy debts.
4. **Medical Expenses** – A serious health issue without proper insurance can wipe out savings fast.
5. **Divorce** – A messy separation can mean splitting assets, sometimes unfairly.
6. **Fraud and Identity Theft** – Cybercrimes and scams are increasing, and without proper precautions, you could be left with financial losses.
Understanding these risks is the first step in securing your financial future. Now, let’s look at what you can do to protect yourself.
**Establish a Solid Legal Framework**
**1. Choose the Right Legal Structure**
If you own a business or have significant assets, your personal wealth should be separate from your business holdings. Consider setting up a **Limited Liability Company (LLC)** or a **corporation** to protect personal assets from business liabilities. These structures create a legal barrier between you and potential creditors.
**2. Utilize Trusts for Asset Protection**
A **trust** is a legal entity that can hold assets on your behalf, shielding them from creditors, lawsuits, and even estate taxes. Some options include:
- **Revocable Trusts** – Useful for estate planning but don’t provide strong protection against creditors.
- **Irrevocable Trusts** – More robust protection, since assets in these trusts legally no longer belong to you, making them harder to seize.
**3. Properly Structure Ownership**
Consider joint ownership structures, such as **tenancy by the entirety** (available in some states for married couples), which can protect assets from creditors targeting just one spouse.
**Insure Yourself Against Major Risks**
Insurance may not be exciting, but it’s one of the easiest and most effective ways to protect your wealth. Some key policies include:
**1. Liability Insurance**
If you own a home, a business, or even just drive a car, **liability insurance** is crucial. It protects you in case someone sues you for injury or damages. Consider an **umbrella policy** to provide extra coverage beyond your standard policies.
**2. Health and Disability Insurance**
Medical bills are a leading cause of bankruptcy. **Health insurance** helps mitigate those costs, and **disability insurance** ensures you have income if an injury or illness prevents you from working.
**3. Long-Term Care Insurance**
Nursing home and assisted living costs are skyrocketing. **Long-term care insurance** is one way and can help prevent these expenses from depleting your assets. Believe it or not, **cash value life insurance** can be designed to provide the same benefits, and often with more advantages, i.e., you don’t lose it if you don’t use it, for example. In addition, policies can be designed to provide far easier access to benefits.
[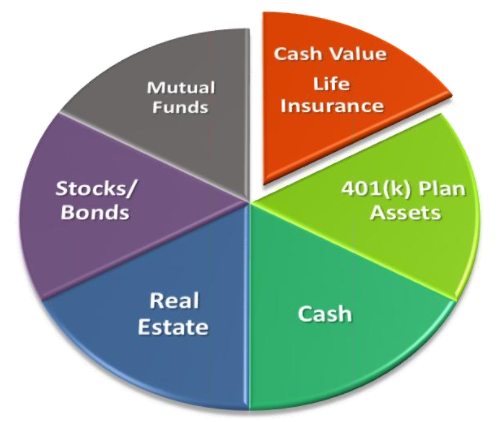](https://indfin.com/wp-content/uploads/2025/02/Life_Insurance_as_an_asset.png)*The right asset mix can mitigate many risks***4. Business Insurance**
If you own a business, protect it (and yourself) with **business liability insurance**, **workers’ compensation**, and **key person insurance** (which covers financial losses if a vital employee or partner passes away).
**Diversify and Secure Your Investments**
**1. Don’t Put All Your Eggs in One Basket**
A diverse portfolio can help protect against stock market downturns. The key to effective diversification is something called reduced correlation, which can be achieved by spreading assets across different asset classes, such as:
- Stocks and bonds
- Real estate
- Precious metals and other hard assets
- Mutual funds and ETFs
- International markets
**2. Be Cautious With High-Risk Investments**
It’s tempting to chase high returns, but risky ventures can wipe out your savings. If you’re going to invest in volatile assets like cryptocurrency, speculative stocks, or startups, limit your exposure and balance it with safer investments.
**Protect Your Digital and Physical Assets**
**1. Cybersecurity Measures**
Identity theft and cyber fraud are growing concerns. Take these steps to protect yourself:
- Use strong, unique passwords for financial accounts.
- Enable **two-factor authentication**.
- Monitor your credit reports for unauthorized activity.
- Use encrypted digital wallets for online transactions.
**2. Physical Security**
For tangible assets like cash, gold, or important documents, consider:
- **Home safes** for smaller valuables.
- **Bank safe deposit boxes** for important papers and heirlooms.
- Keeping physical asset locations confidential from all but trusted family members.
**Plan for the Unexpected**
**1. Estate Planning**
Yes, asset protection also includes your estate! If something happens to you, what happens to your assets? Without proper estate planning, your wealth could end up in probate court, eaten away by taxes and legal fees. Key steps include:
- Drafting a **will**.
- Establishing **power of attorney** for financial and medical decisions.
- Setting up **trusts** for heirs.
- Reviewing **beneficiary designations** on retirement accounts and life insurance policies.
**2. Emergency Fund**
Unexpected expenses happen—job loss, medical bills, home repairs. Having an emergency fund with **3-6 months of living expenses** in a liquid, easily accessible account can keep you from dipping into long-term savings.
**Avoid Common Pitfalls**
**1. Ignoring Legal and Financial Advice**
You don’t have to be an expert in law or finance, but having a **trusted attorney and financial advisor** can save you from costly mistakes.
**2. Making Emotional Financial Decisions**
Fear and greed can lead to poor investment choices. Avoid panic-selling during downturns or chasing get-rich-quick schemes.
[](https://indfin.com/wp-content/uploads/2025/02/Fotolia_3956379-Overwhelmed-C2.jpg)**3. Failing to Update Plans**
Your financial situation changes over time. Regularly **review and update** your estate plan, insurance policies, and asset protection strategies.
**Final Thoughts: Be Proactive, Not Reactive**
Asset protection isn’t about being paranoid – although a little paranoia made be a good thing – it’s about being prepared. By taking common-sense steps—like structuring assets wisely, using the right insurance, diversifying investments, and keeping a security-first mindset—you can safeguard your financial future. The key is to **act now**, before problems arise. A little effort today can save you a lot of stress and money down the road.
What are your priorities? [Let me know](https://indfin.com/retirement-priority-planning-review/)! I’ll be happy to help.
Jim
---
### [Business Continuity](https://indfin.com/business/businesscontinuity/)
**Published:** November 18, 2016
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2016/11/Fotolia_2204049-DB-Teamwork.jpg)The loss of a key executive** or other employee can change the trajectory of a business’ growth for months, if not years. A key executive might be one who has relationships with key customers, bankers, suppliers, and/or industry contacts. This is the reason many realize Loss = Cost = Reason to Insure. After all, it’s the reason businesses carry fire, as well as other types of insurance: Protection against loss.
The loss of a key executive can impact a business’ bottom line in many ways:
1. Cost to locate, recruit and train a replacement – all three are separate with their own time lines.
2. Loss of the executive’s contribution to earnings – Which means the costs in #1 are being absorbed with reduced cash flow.
3. Present value of lost business earnings until #1 and #2 have been completed and replaced.
**Locating and hiring**: Executives and high-performers – those that can impact the business growth trajectory – are hard, and expensive, to locate and hire. Executive search firms’ costs vary considerably; it would not be unusual for the fee to equal 50% of the executive’s first-year compensation.
**Training:** Getting a new executive ‘up to speed’ includes not only training costs, but costs to compensate for the mistakes the replacement might make before being able to function at the same level as the former executive.
**How to Value a Key Executive**
Revenue has two sources: Money working and people working. The necessity for putting a value on an executive’s ability has given rise to different methods of valuation:
- **Contribution to Earnings**
Typically, the 5-year average return on assets at book value is subtracted from the business’ 5-year average pretax earnings. The result provides the level of earnings based on management skill, which in turn are assigned to each member of the management team and multiplied by the time required to get up t speed.
- **Key Executive Salary:**
Under this method, the executive’s duties are grouped into two categories: (1) routine, and (2) duties that require special talent or expertise. The steps are as follows:
1. Begin with the key executive’s salary
2. Identify routine tasks performed by the key executive
3. Determine the annual salary that would be to hire a replacement for performing only those routine tasks
4. Key executive’s value would be determined by subtracting the results in Step 3 from Step 1.
- **Present Value of Lost Business Earnings**
This method is simply estimating the anticipated lost earnings resulting from the loss of the key executive. The present value of those lost earnings is then added to recruiting and training.
- **One Year’s Business Earnings**
This method has less credibility simply because it’s not based on any actual or perceived value the key executive might have to the business.
Remember to add executive search and training costs to any valuation method you use.
**Funding Search, Replacement, and Training with Life Insurance**
[](https://indfin.com/wp-content/uploads/2016/11/Solution-Puzzle-Piece-2.png)Typically, businesses don’t have a non-working capital set aside in a sinking fund in order to self-insure the loss of a key executive. This is why insurance is frequently the choice as a funding mechanism. It’s a ‘risk-transfer’ vehicle: Employers pay insurance companies to take the risk.
In typical arrangements, the employer is the:
- policy applicant, and owner
- premium payer
- beneficiary of the death benefit
The key executive is simply the insured and has no rights in the policy. The death benefit is tax-free to the employer provided notice and consent requirements have been met AND the key executive dies during the period of employment (or within 12 months of such employment), OR the key executive was a director or highly compensated employee when the policy was issued, even if no longer an employee at the time of death.
**What Kind of Insurance**
Where affordability is an issue: Term life, but with the understanding that a subsequent conversion to permanent life insurance will be done if possible. Reason: Term insurance has an expiration date, while the term of employment does not and the executive may no longer be insurable at that time. In addition, renewing the term insurance would result in higher rates.
Where seasonal or unexpected cash flow changes are an issue, whole life should be avoided in favor of universal life insurance, which allows for flexible premiums and can be designed with cost structures similar to term.
Where supplemental retirement benefits are desired, permanent insurance may be the best choice. Under this arrangement, key executive life insurance does ‘double-duty’ as a supplemental employee retirement plan (SERP) arrangement. You can learn more [**here**](https://indfin.com/wp-content/uploads/2016/11/i706_SERP-In-Action.pdf).
While whole life insurance generally has the strongest guarantees, it’s also not as flexible and therefore less attractive to most business owners who tend to favor universal life insurance, which allows the employer to:
- increase or reduce premium payments – or pay none at all – depending on the business’ cash flow at the time the premium is due and its interest in increasing the policy’s cash value.
- Take cash withdrawals on a favorable FIFO tax basis under which all cost is withdrawn tax-free before any taxable gain is taken.
- Increase (with evidence of insurability) or decrease the policy’s death benefit to meet business needs.
Premium payments for life insurance are not tax deductible to the employer if the business is a beneficiary under the policy, either directly or indirectly.
Disability insurance premiums are not deductible either, but for a different reason: Since the benefits received under a key executive disability policy are not taxable, no deduction is allowed for premium payments.
Important: No level of premium payments to a universal life policy (unless there’s a secondary no-lapse guarantee) will ensure the policy will remain in force for the insured’s entire life. Insurers do have the legal ability to increase insurance rates and expense deductions, which could have an effect on policy cash values. If minimum premium payments are made for a short time and cash values are relied on to keep the insurance in force, insurance costs could use up the cash value over time.
---
### [Executive Retention: Keeping Key People](https://indfin.com/business/executivecompensation/)
**Published:** November 18, 2016
**Author:** Jim Lorenzen
**Content:**
**Business success** is often – if not always – the result of having the right people… and keeping them! The loss of the intellectual and entrepreneurial skills of a key person may be even more important than protecting against the loss of physical property. Most business owners have fire insurance, but the building doesn’t make money – people do; and losses there can be far more expensive.
[](https://indfin.com/wp-content/uploads/2016/11/Fotolia_4812281-DB-StandingOut.jpg)
**Key people** are often those who
- possess extraordinary administrative ability
- have critical information or knowledge
- maintain and nourish key contacts and relationships with important customers, suppliers, industry contacts, and/or banking relationships
- have the ability to identify target markets and mount powerful campaigns that consistently produce profitable results
- are reliable financial professionals who ensure sufficient operating funds are available despite seasonal cash flow concerns
**How do you keep Key People?**
It’s possible to put bonus and retirement options in-place that aren’t subject to the restrictions of qualified retirement plans under ERISA. Plans that are intentionally designed to fall outside ERISA guidelines are called non-qualified plans. See [*When Qualified Plans Are Not Enough*.](https://indfin.com/wp-content/uploads/2016/11/i705c1_NQDC_Memo_WhenQualPlansNotEnough.pdf)
Non-qualified plans do not have to include everyone; indeed, in many companies that utilize these plans, non-key employees may not even know they exist because the business owners are not required to include them. You can see how a non-qualified deferred compensation plan works [here.](https://indfin.com/wp-content/uploads/2016/11/i705a_NQDC-In-Action.pdf)
A key determinant in choosing the right plan is the business’ potential for survival, since the business must be in existence in order to pay the promised benefits.
- Is the business likely to survive the owner’s death, disability, or retirement?
- Is it desirable for assets purchased by the business to fund future executive benefits to be accessible by the business’ creditors.
If the answer to both of the above questions is YES, then a Supplemental Employee Retirement Plan (SERP) may be just the answer. You can see a SERP in action[ **here**](https://indfin.com/wp-content/uploads/2016/11/i706_SERP-In-Action.pdf).
If the answer to either of these questions is NO, then a selective executive benefit plan owned by the key employee may be a better choice.
- **Executive Bonus Plan**: The corporation pays a bonus to the selected key employee in the form of insurance premiums. The bonus is deductible to the business and taxable to the executive, who receives cash value life insurance for the cost of the taxes only and, in a properly designed policy, cash values can grow substantially to supplement retirement or for any other purpose.
You can learn more about Executive Bonus Plans [**here**](https://indfin.com/wp-content/uploads/2016/11/i701a1_Looking-For-An-Easy-Bonus-Plan.pdf) and see how a basic Executive Bonus Plan works by seeing one in action,[ **here**](https://indfin.com/wp-content/uploads/2016/11/i701a2_Executive-Bonus-in-Action_vsa.pdf).
[](https://indfin.com/wp-content/uploads/2016/11/Dollar-Sign-and-characters-surrounding.png)In order to guard against an executive deciding to retire early or to start a competing company, many business owners have opted for a Restricted Executive Bonus Arrangement (REBA). These arrangements provide wide flexibility and they can even be terminated without IRS notification, approval, or restrictions. [Learn more about REBAs here](https://indfin.com/wp-content/uploads/2016/11/i704a_REBA-Report.pdf).
- **Split Dollar Plans**: In a split-dollar arrangement, since the employer pays part of the cost, selected key executives are able to purchase cash value life insurance at a reduced cost to them. The executive owns the contract, making it safe from the business’ creditors. These can be designed in a way that allows the employee to obtain permanent cash value insurance at a reduced cost while the employer eventually recovers its share of premium costs from the policy’s cash value or death benefit. These arrangements can also be designed as equity or non-equity plans. You can [see what a split-dollar plan looks like here](https://indfin.com/wp-content/uploads/2016/11/i707_Split-Dollar-In-Action.pdf).
There are a number of uses for split-dollar plans. If you’d like to learn more, feel free to schedule an introductory phone call [**here**](https://www.meetme.so/JimLorenzenCFP).
- **Group Carve-Out Plans**
Employer-provided group term life insurance is common today. Typical, employee coverage is equal to some percentage of salary, i.e., 2 or 3 times annual salary, for example. The cost of the first $50,000 of coverage is typically paid by the employer and not taxable to the employee; however, coverage in excess of $50,000 is taxable to the employee.
[](https://indfin.com/wp-content/uploads/2016/11/Image_Carve-Out-1.png)A group carve-out plan is a nonqualified plan under which insurance coverage in excess of $50,000 is replaced by life insurance owned by the employee, usually an officer or other key executive. By ‘carving out’ this coverage, it becomes unassociated with the group term plan. The employer makes minimum premium payments but either the employer or employee can make additional premium contributions to grow cash values.
[](https://indfin.com/wp-content/uploads/2016/11/Image_Carve-Out-2.png)
“Selectivity” or “discrimination” is a distinct benefit of non-qualified plans. In practice, a group carve-out plan may actually reduce the employer’s overall benefit costs. The reason is that senior executives – the ones usually covered – usually have the highest level of group term insurance. They are usually the oldest covered employees with the highest mortality cost. The ability to reduce overall group term life insurance rates by removing older participants’ excess coverage can result in significant savings.
Most employer-provided nonqualified compensation and protection plans can be provided under a number of designs, including cost and benefit sharing with the executive, called ‘split-dollar’. In addition, business owners often choose to ‘carve-out’ a particular group for inclusion; which means they can exclude certain groups of employees.
There’s more to know; but, the real concern is choosing the right strategy and design that fits your needs.
If you would like to arrange a brief introductory call in advance of a meeting, you can schedule a time convenient for you **[here](https://www.meetme.so/JimLorenzenCFP)**!
[](https://indfin.com/wp-content/uploads/2014/09/Resized-CFP_Logo_Gold.jpg)
---
### [Video Library](https://indfin.com/video-library-2/)
**Published:** January 24, 2015
**Author:** Jim Lorenzen
**Content:**
**Start Today! It’s as simple as 1-2-3!**
1. Provide us with some [basic information](https://app.advizr.com/guest/expresswizard?ctaEmail=info@indfin.com).
2. [Schedule your introductory phone call here!](https://www.meetme.so/JimLorenzenCFP) Pick a time that’s convenient for you!
3. Complete and return your [IFGi\_RetirementPriorityReview](https://indfin.com/wp-content/uploads/2015/04/IFGi_RetirementPriorityReview_vsa.pdf)!
(You can download and save it to your computer before completing. Return it to Jim prior to the Introductory Call. Send it to cfp@indfin.com.
### Jim Lorenzen, CFP®, AIF®
### *THE INDEPENDENT FINANCIAL GROUP*
### *A Registered Investment Advisor*
**Phone: 805-265-5416**
Fax: 805-830-1138
Toll Free: 800-257-6659
E-mail:
Ca. Ins. Lic. 0C00742
2655 First Street, Suite 250; Simi Valley, California 93065

# [Join Our Newsletter](https://tinyurl.com/IFGInsights)

Can You Tell the Difference Between a “Financial Advisor” and a…

---
### [Financial Planning for Business Owners](https://indfin.com/financial-planning-for-business-owners/)
**Published:** September 19, 2014
**Author:** Jim Lorenzen
**Content:**
Financial planning forbusiness owners is more complex only because independent business owners must confront a myriad of tax laws and regulations while trying to effectively create products or services, manage their employees, develop and cultivate clients, and do so profitably. It can be challenging, to say the least.
[](https://indfin.com/wp-content/uploads/2016/11/i605c1_BO_Lifecycle_slide_201611.png)Quite often, owners are so absorbed in day-to-day operations and profitability issues that there’s little time tend to their own financial needs; and this also means they can easily overlook key planning considerations that could help their business grow and prosper. If that isn’t enough, the owner’s very business survival can be imperiled when unexpected events occur, even outside the owner’s control, that adversely affect the bottom line of the business.
### Business Owner Needs
**Retirement**
For many business owners, the business is their primary retirement asset; and after many years of building a successful business they expect to convert it to an income for retirement by selling it. When you think about it, they’re staking their entire future on the price of a single stock! But, what if the value they need to produce the income they desire isn’t there when the time comes? Bad timing (Murphy’s Law) can happen due to circumstances beyond the owner’s control when it’s least expected… remember the melt-down?
Businesses can fail, of course. Economic cycles play a role, as well. The timing is not always right to sell a business. And, business owners who are highly ‘hands-on’ may have additional problems: A potential buyer may be wary of an investment when the true value of the business lies in the talents and good will of the business owner who won’t be around to run the business after he retires.
The takeaway: Business owners today must prepare for retirement with the same level of diversification recommended for any retirement plan. Business owners have access to a number of qualified and non-qualified retirement plan options that can provide a cornerstone for their retirement income needs. In other words, it might be smart to use the business as a cash-flow generator in order to build net worth outside the business itself. If you can sell later, great; but, if something goes wrong, you still have a cash-flow generator.
**Business Valuation**
Before you can realize your rewards fully, you’ll have to quantify what you’ve accomplished. Only then will you be able to explore your options, choose your path, and make the moves that matter.
Business owners make decisions every day – indeed, many have their entire net worth invested in the decisions they make – yet, few know, in advance, just how those decisions will impact business value. According to the Small Business Administration, insufficient knowledge about business value is one of the top two challenges facing small business owners and leaders. That’s because companies that DO understand their worth are better positioned to pursue growth initiatives, attract and reward talent, and ensure proper credit and risk management.
[](https://indfin.com/wp-content/uploads/2015/03/iStock_000005551048-SmallBusinessOwner.jpg)*iStock Images*IFG is able to help, as part of our financial planning process, through the use of an innovative, patented online business valuator system that provides IFG clients with access to real-time business valuation knowledge. This resource represents the “on-ramp” to almost everything you need to do to accomplish a variety of objectives. It helps business owners answer the most important question they face before engaging in any financial decision-making conversation: [What’s my business worth?](https://indfin.com/what-your-business-worth)
**It’s about insight: Knowing where you stand and where you may be headed.**
There are seven simple steps in the process; and the system continually updates your valuation as you go through the steps. The result: A customized 24-page Business Valuation Report. And, you’ll have access to the online system for ongoing strategic decision making for a full year.
**Business Succession**
When a business partner dies, the business loses a valuable asset and could suffer in the short term. The long term issue for surviving business owners is whether the business can survive when the partner’s family members show up for their interest in the business.
[](https://indfin.com/wp-content/uploads/2014/09/Transferring-Business.png)For the families of business partners, the business interest is often their biggest asset and they become the rightful owner of that interest at the death of the partner. They will want to receive their share of the business, either in direct compensation or through their participation as an active partner in the business. Quite often, the surviving partner would rather not have the heirs of the deceased partner as new business partners. That can lead to problems, as you might suspect.
But if the surviving partner doesn’t have the capital to compensate the heirs for their share of the business, options are limited and not very attractive. A business succession plan can provide for the orderly transfer of the business interest from the deceased’s family to the business.
**Key Employee Protection**
[](https://indfin.com/wp-content/uploads/2014/09/Solution-Puzzle-Piece.png)One of the more devastating events a small business can suffer is the loss of a key employee. Often times it’s a key employee who brings a special talent to the business and is responsible for much of the success of the business owner. The loss of such a valuable asset could set the business back for a period of time, and at tremendous cost, while the business owner seeks to find a replacement, if one can be found at all.
Most of us know that our most valuable assets – our home, our ability to earn income, our cars – should be insured against an unexpected loss. It’s no different for business owners as the loss of a valuable business asset could imperil the business.
Buying life insurance coverage on a key employee makes good business sense. The amount of coverage should be enough to cover the costs of recruiting and paying a replacement, loss of earnings to the company to get through the adjustment period, and any redemption of stock or a salary continuation plan arrangement with the surviving family.
**Executive Compensation**
Finding good talent isn’t easy; it probably won’t happen overnight. In fact, it could take years to find or develop the executive talent needed to build the business to the next level. Executive talent is hard to come by, and it is even more difficult on the business when it walks out the door in pursuit of another opportunity.
[](https://indfin.com/wp-content/uploads/2014/09/Working-Planning-Retirement-Puzzle.png)When key executives are presented with a strong monetary incentive package, they are more likely to stay and utilize their talents where they feel appreciated and appropriately rewarded. Structured incentive plans can help keep key executives in place and motivate them to higher levels of performance.
Plans such as Non-qualified Deferred Compensation, Executive Bonus, and Split Dollar Life Insurance are life insurance based plans that enable the business to offer current and future benefits to their key executives in exchange for their continued service for a specified period of time.
Here’s IFG’scomplete [menu of business services](https://indfin.com/business/ownerservices/).
For more information on Business Owner Planning, please [contact us today.](https://indfin.com/contact)
---
### [What Is Your Business Worth](https://indfin.com/what-your-business-worth/)
**Published:** September 15, 2014
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2017/05/Older-man-with-cash_gettyimages.jpg)*Getty Images*
**… and why should you care?**
You invested, probably heavily, in your American Dream; and you have a lot riding on it.
Before you can realize your rewards fully, you’ll have to quantify what you’ve accomplished. Only then will you be able to explore your options, choose your path, and make the moves that matter.
Business owners make decisions every day – indeed, many have their entire net worth invested in the decisions they make – yet, few know, in advance, just how those decisions will impact business value.
According to the Small Business Administration, insufficient knowledge about business value is one of the top two challenges facing small business owners and leaders. That’s because companies that DO understand their worth are better positioned to pursue growth initiatives, attract and reward talent, and ensure proper credit and risk management.
Whether you are a sole owner, in a partnership, or part of a corporate executive team with equity in the enterprise, knowing business value can help you when you:
- Seek debt or equity financing
- Pursue new business & expansion initiatives
- Apply for a business loan
- Make a business acquisition
- Value a buy-sell agreement
- Prove you’re a reliable supplier
- Assess how you should value your business for estate planning purposes
- Determine how much insurance you need to protect your family & assets
- Gauge whether another company is a good strategic partner
- Need to know how business decisions actually impact business value
- Want to quantify business value for the sale of the business or your equity interest
IFG is able to help, as part of our financial planning process, through the use of an innovative, patented online business valuator system that provides IFG clients with access to real-time business valuation knowledge. This resource represents the “on-ramp” to almost everything you need to do to accomplish a variety of objectives. It helps business owners answer the most important question they face before engaging in any financial decision-making conversation: What’s my business worth?
It’s about insight: Knowing where you stand and where you may be headed.
Jim Lorenzen, CFP®
---
### [Business Succession](https://indfin.com/business/businesssuccession/)
**Published:** November 18, 2016
**Author:** Jim Lorenzen
**Content:**
[](https://indfin.com/wp-content/uploads/2016/11/Transferring-Business.png)Business Succession planning isn’t something you put-off! A buy-sell agreement should be at the top of your list!
**If your business partner should die tomorrow, would you be happy if your partner’s spouse became your new partner?**
Would the spouse earn his/her percentage? Would all surviving partners be happy?
**If you plan to sell your business, who will you sell it to? Have you identified a buyer? Have you a plan to secure your buyer’s funding to protect yourself in case of future business downturns?**
All valid questions, I’m sure you would agree.
**Whether your business will realizes growth in the years to come depends, in part, on your written succession plan**.
If you have not formalized one for your business yet, here are questions to consider:
> Who will take over your business when you retire, become disabled, or unexpectedly die?
> Is this person properly equipped and experienced to do the job?
> Will your employees,board members, customers, suppliers, and bankers support this person or will relationships and terms change?
> How will the tranfer be funded that secures your future and the future of your dependents and heirs?
**If you have already begun a succession plan, did you ask these questions?**
> Does your identified successor have the required skills, knowledge and experience?
> Have you communicated the plan to all relevant parties?
> Have you made arrangements for dealing with key employees involved with your business to gain their support for your choice successor?
Ever hear of a one-way buy-sell agreement? If you know who you’d like to have take over, you may be interested in[ learning more ](https://indfin.com/wp-content/uploads/2016/11/i806a_One-Way-Buy-Sell-Agreements.pdf)about this strategy. Here’s a hypothetical [case study](https://indfin.com/wp-content/uploads/2016/11/i806b_Case-Study_Buy-Sell.pdf), as well.
[](https://indfin.com/wp-content/uploads/2016/11/i806c_LLC-Buy-Sell-Strategy_001.png)[](https://indfin.com/wp-content/uploads/2016/11/i806c_LLC-Buy-Sell-Strategy_001.png)[](https://indfin.com/wp-content/uploads/2016/11/i806c_LLC-Buy-Sell-Strategy_001-3.png)If you’re operating an LLC, you may be interested in [this report](https://indfin.com/wp-content/uploads/2016/11/i806c_LLC-Buy-Sell-Strategy.pdf) on buy-sell strategies for LLCs.
**Business succession planning is a process, not an event**.
Over time, it can provide you with the ability to accomplish specificgoals. We know business succession planning and how to apply theuse of appropriate tools, including life insurance. As an independent advisor, The Independent Financial Group can work with you to develop the strategies that maximize control if you wish, while still allowing the business to smoothly transition whenever you choose. One important component: Putting a funding mechanism in-place in advance. You can [schedule an introductory call here.](https://www.meetme.so/JimLorenzenCFP)
**You can’t pass it on without knowing it’s value**
It’s the rare business owner who spends a lifetime building a successful business only to walk away. The vast majority of owners hope to monetize what they’ve built; indeed, for many, their business value may represent their retirement!
[](https://indfin.com/wp-content/uploads/2016/11/Fotolia_4812344-DB-wDollarSign.jpg)Whether you plan to pass your business on to an outside buyer, inside buyer (employee or family member), or just leave it to the kids, you still need to know what your business is worth.
While many transactions might require a formal valuation, such as a certified appraisal, many other applications do not, including informal valuations conducted for planning purposes. You might be interested in the IFG report, How to Establish Business Value, which you can access here:
[How To Establish Business Value Report](https://indfin.leadpages.co/leadbox/145a6f273f72a2%3A12a1899aa346dc/5746569068412928/)
Real problems can arise, however, when there’s a premature death of the owner or a partner. A buy-sell agreement that’s been created in advance, with a funding mechanism in-place, can save survivors a lot of headaches, and secure the retirement for the deceased owner’s heirs.
Buy-sell agreements can be created for a partnership buy-out or a pre-arranged business sale to an employee or even a competitor or supplier. The key is to secure the business value so that the deceased owner’s heirs aren’t at risk of a subsequent business failure destroying the retirement income they counted on receiving.
**There are four ways to fund a Buy-Sell agreement:**
**Cash –**The buyer might be able to make an all-cash purchase on the spot, but that’s unlikely. Businesses seldom find an all cash buyer, especially when the owner is deceased.
**Installments –**They buyer could make installment payments from business cash flow; but, that would represent a strain on the business’ bottom-line for years. In addition, as noted, the business may not survive or be later sold to an incompetent or unscrupulous buyer. The heirs future would not be secure.
**Loan –**Assuming the new owner could obtain a loan, but the situation would be the same as under the installment method.
**Insured –**There’s only ONE financial tool that can guarantee that the cash needed to monetize business value will be available to fund the buy-out, removing the deceased partner’s heirs from the business (freeing the new owners to operate without added purchase costs) while helping to secure the surviving heirs future, assuming the business has been accurately valued and the value is sufficient to accomplish the intended objective.
[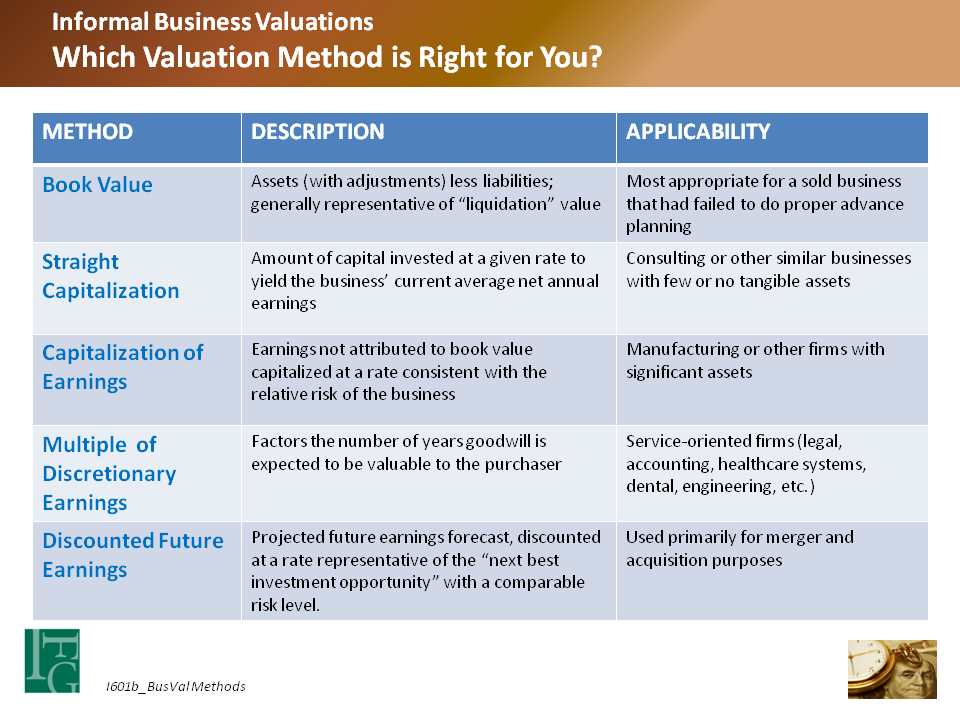](https://indfin.com/wp-content/uploads/2016/11/i601b_Businss-Valuation-Methods_slide-1.png)
**How to Value Your Business**
There are four basic methods for obtaining an informal business valuation. You can see them compared below.
There are a number of advantages to knowing your business’ value:
- **For estate planning**: In addition to knowing whether an owner’s total assets might result in an estate tax exposure, the value of the business in relation to other assets can determine whether a deceased owner’s estate is eligible for certain tax-relief provisions, such as Section 303.
- **Business continuation planning**: Closely-held businesses do not have a secondary market to determine the value of ownership shares.
- **Gift tax purposes:** Owners who plan to gift all or a portion of business interest will need to justify their valuation to the I.R.S.
- **Obtaining business loans**
- **Justifying ‘reasonable compensation’** paid to owner-employees in case the I.R.S. asks.
- **Understanding the impact of financial decisions** on business value.
If you’d like to learn more about how a buy-sell arrangement might look for your business, you schedule a brief phone interview with IFG founding principal Jim Lorenzen, CFP, AIF, **[here](https://www.meetme.so/JimLorenzenCFP)**. Just answer some basic questions about your business andyou’ll receive a overview showinghow a buy-sell structure might look for your business.
[](https://indfin.com/wp-content/uploads/2014/09/Resized-CFP_Logo_Gold.jpg)
---
### [Retirement Planning for Business Owners](https://indfin.com/business/ownerretirement/)
**Published:** November 18, 2016
**Author:** Jim Lorenzen
**Content:**
**[](https://indfin.com/wp-content/uploads/2016/11/Piecing-Retirement-Puzzle-Path.png)Business owners** must not only wear many hats, often they are: - the active managers of the business
- heavily invested in the business
- running a privately-held business that has no secondary market for the sale of ownership interests
- relying on a small number of important key accounts and suppliers
- relying on a single ongoing source of business credit that is vital to continuing business operations
- limited in the resources that are available to provide employee benefits
While many who are not business owners often fail to do any formal advance planning before actually approaching retirement, successful business owners are usually comfortable with the planning process as an integral component of their business operations.
Integrating business and personal planning, however, is often overlooked. For example, how does a business expenditure impact the value of the business and how will that impact the owner’s retirement plans, access to credit and financing, or the valuation of the business for a future sale?
**A couple of tools you might find helpful in beginning your planning are:**
- [Retirement Planning Priority Review](https://indfin.com/wp-content/uploads/2016/11/i500_RetirementPriorityReview_fill_vsa-1.pdf)
- [Business Priority Planning Review](https://indfin.com/wp-content/uploads/2016/11/i605_Business-Priority-Planning-Review_vsa.pdf)
Knowing the value of your business can be quite helpful and an informal valuation need not be expensive. There are a number of methods available:
[](https://indfin.com/wp-content/uploads/2016/11/i601b_Businss-Valuation-Methods_slide-1.png)
You might check out our short report, ***What’s Your Business Worth*?** You can also obtain a **sample valuation report** by clicking below.
[Click Here to get your Sample Business Valuation Report](https://indfin.leadpages.co/leadbox/1464bce73f72a2%3A12a1899aa346dc/5714142736416768/)
If you’d like to schedule an introductory call with me, you can do that [here](https://www.meetme.so/JimLorenzenCFP).
---
### [Retirement Priority Planning Review](https://indfin.com/retirement-priority-planning-review/)
**Published:** April 7, 2024
**Author:** Jim Lorenzen
**Content:**
# Retirement Priority Planning Review
Please enable JavaScript in your browser to complete this form.
## Personal Information
Please complete only the information that may not be in our current records.
Name \*First
Last
Phone \*
Cell
Business Phone
Email \*
Business Email
Spouse NameFirst
Last
Spouse Phone
Spouse Email
## Personal Planning Profile
Please check the boxes that reflect your current planning.
I know how long my retirement income will last.- Yes
- No
- Unsure
I am concerned about the risk of outliving my retirement income.- Yes
- No
- Unsure
I am pleased with the returns on my retirement and investment programs.- Yes
- No
- Unsure
I understand the impact of inflation on my retirement plan.- Yes
- No
- Unsure
I pay taxes on my Social Security benefits.- Yes
- No
- Unsure
I am fully covered for health care costs: Medicare A and B as well as “Med Sup.”- Yes
- No
- Unsure
I am familiar with costs of long-term care and nursing home costs.- Yes
- No
- Unsure
I have reviewed my life insurance program in the last two years.- Yes
- No
- Unsure
I have a current will consistent with my estate distribution wishes.- Yes
- No
- Unsure
I have advance directives (living will, medical power of attorney) consistent with my wishes.- Yes
- No
- Unsure
I am concerned about estate taxes.- Yes
- No
- Unsure
I am concerned about my final expenses.- Yes
- No
- Unsure
I want to leave something to my: children, grandchildren, church, alma mater, charity.- Yes
- No
- Unsure
### Financial Statement
Please check the boxes of that best reflect you current situation.
## Financial Statement
Please check the boxes that best reflect your current situation.
Your Annual Income \*- Less than $50,000
- $50,000 to $100,000
- $100,000 to $250,000
- More than $250,000
Your Spouse's Annual Income- Less than $50,000
- $50,000 to $100,000
- $100,000 to $250,000
- More than $250,000
Assets (excluding home) \*- Less than $50,000
- $50,000 to $150,000
- $150,000 to $250,000
- $250,000 to $500,000
- $500,000 to $1,000,000
- More than $1,000,000
Value of Home
Liabilities (excluding home mortgage) \*- Less than $50,000
- $50,000 to $150,000
- $150,000 to $250,000
- $250,000 to $500,000
- $500,000 to $1,000,000
- More than $1,000,000
Home Mortgage
Current Savings and Investments \*- Savings and CDs
- Money Market Fund
- Mutual Funds
- Stocks
- Bonds
- Life Insurance Cash Value
- Tax-Deferred Annuity
- IRA or SEPP
- 401(k) Salary Deferral
- Pension/Profit Sharing Plan
Other Savings and Investments
Current Life Insurance- Less than $50,000
- $50,000 to $150,000
- $150,000 to $500,000
- More than $500,000
- Long Term Care Insurance
Your Spouse's Current Life Insurance- Less than $50,000
- $50,000 to $150,000
- $150,000 to $500,000
- More than $500,000
- Long Term Care Insurance
## Financial Planning Priorities
Please check the boxes that most closely reflect your financial priorities.
Returns made on my retirement assets are a…- High Priority
- Medium Priority
- Low Priority
- Not Applicable
Effect of inflation on my assets is a…- High Priority
- Medium Priority
- Low Priority
- Not Applicable
Risk of outliving my retirement income is a…- High Priority
- Medium Priority
- Low Priority
- Not Applicable
Providing funds to pay my mortgage and debts in the event of death is a...- High Priority
- Medium Priority
- Low Priority
- Not Applicable
Protecting against the costs of long-term health care is a...- High Priority
- Medium Priority
- Low Priority
- Not Applicable
Investing money in tax-favored plans is a...- High Priority
- Medium Priority
- Low Priority
- Not Applicable
Low risk investments are a...- High Priority
- Medium Priority
- Low Priority
- Not Applicable
Investments that offer high growth potential are a...- High Priority
- Medium Priority
- Low Priority
- Not Applicable
An overall financial plan is a...- High Priority
- Medium Priority
- Low Priority
- Not Applicable
Review of all my insurance policies is a…- High Priority
- Medium Priority
- Low Priority
- Not Applicable
Availability of additional health care coverage is a…- High Priority
- Medium Priority
- Low Priority
- Not Applicable
Income from real estate including residence is a…- High Priority
- Medium Priority
- Low Priority
- Not Applicable
Involvement of my spouse in our financial planning is a...- High Priority
- Medium Priority
- Low Priority
- Not Applicable
## Current Priorities
Please check all items you are interested in discussing:
Current Priorities \*- A complete financial analysis
- Better return on retirement assets
- Guaranteed lifetime income.
- Insurance on myself
- Insurance on my spouse
- Insurance on children/grandchildren
- Converting temporary insurance
- Mortgage protection coverage
- Supplemental health insurance
- Income from real estate including residence
- Protecting against the costs of long-term health care
- Methods of charitable giving
- How to pay estate taxes
- Existing policy review
Other pertinent information about Priorities:
## Future Plans
Please check all items that may apply within the next two years:
Future Plans- New home
- Charitable gifts
- Relocation
- Vacations
- Sell property
- Inheritance
- Retirement
Submit
---
### [Will My Money Last? Common Question for those Facing Retirement.](https://indfin.com/willmymoneylast/)
**Published:** September 19, 2023
**Author:** Jim Lorenzen
**Excerpt:** Planning your financial future is like planning a journey - so you can end-up at a destination you'll like - doesn't have to feel like work. In fact, it can be fun! But, you don't want to be like he Griswalds who travelled 2,000 miles to find Wally World closed.
**Content:**
“Will my money last?” is a common question. Retirement requires decision-making – and decision-making requires answers to questions those facing retirement need to answer. The best first step is a retirement needs analysis to begin the journey.
**Do these questions sound familiar?**
- Do I have enough money to retire?
- Will my money last? How long?
- Under different inflation rates?
- Under different tax rates?
- How will the sunsetting of current tax law the end of next year affect me?
- How will unforeseen emergencies (roof replacement, medical, etc.) even five or ten years from now affect my future security?
- When should I apply for Social Security? Medicare? How do I choose a plan?
- What will my required minimum distributions (RMDs) be and when will they begin?
- How will my RMDs affect my Medicare premiums
- What will taxes be on my Social Security benefits and how can they be reduced?
- How can I protect against future tax increases during my later retirement years?
**Planning your financial future is like planning a journey** – so you can end-up at a destination you’ll like – doesn’t have to feel like work. In fact, it can be fun! But, you don’t want to be like he Griswalds who travelled 2,000 miles to find Wally World closed.
**Would you like to know where you are today – and if you’re on-track to reach your goals?**
**Is it worth $600 to you to find out?** You can have an objective, straightforward, needs analysis – something that shows you where you are today and where you’re headed.
There’s nothing to buy. Once it’s completed and you have your full report, you can decide – on your own – if you would like to collaborate with me on the creation of your own life financial plan. There’s no obligation and no pressure (I don’t work that way).
**Your Needs Analysis will show you a formal look at your:**
- Your Current Personal Information and a Summary of Financial Goals
- Summary of all Resources available to meet your Goals and a Retirement Time-Line
- Investment Assets by Asset Class and Tax Category – important to asset location strategies
- Summary and Detail of Net Worth from All Resources
- Current Portfolio Allocation with details about ‘under the hood’ characteristics, including risk
- Probability of Success based on your Prioritized Goals and Resources
- Complete Worksheet Detail showing your Retirement Distribution Cash Flow Chart – this can be an eye-opener.
- Worksheet Detail – Inside the Numbers Final Results with a Probabilities Analysis
You’ll also be provided with relevant checklists and flow charts to help you on your way. So, if you’re asking, “Will my money last?”, here’s where you can get started.
**There are two ways to get started:** Pick the one you like best!
1. **[Tell me your priorities](https://indfin.com/retirement-priority-planning-review/)** and **book your [Introductory Call](https://go.oncehub.com/JimLorenzenCFP)** and the next step will be an office appointment where we can meet to assemble the needed information, or
2. **Email me: Jim@indfin.com** and tell me you want the $600 Needs Analysis offer and I’ll get you set-up to provide the initial inputs yourself! Check out this video:
Are you and your spouse on the same page? You might be surprised! Finding out can be fun. MyBlocks helps make a game out of it! Here’s how it works!
Begin your financial journey today! It’s safe and secure – no need to enter sensitive identifying information – and you’ll be on your way! Enjoy!
[Tell Me Your Priorities!](https://indfin.com/retirement-priority-planning-review/)
---
### [IFG Services for Business Owners](https://indfin.com/business/ownerservices/)
**Published:** January 9, 2017
**Author:** Jim Lorenzen
**Content:**
### Business Solutions
- **Executive compensation**
Executive bonus
- **Key person protection**
Protecting the business from loss of a key employee
- **Supplemental Executive Retirement Plans**
When 401(k)s are not enough
- **Business Continuation**
One-Way, family, and third-party Buy-Sell solutions
- **Informal Business Valuation**
For strategic planning, financial decisions and retirement planning
- **Business Succession**
Transferring the business at a fair price
### Exit and Retirement Planning
- Discovery, goal definition and prioritization, risk assessment
- Wealth accumulation, preservation and dis-tribution strategies
- Retirement planning accumulation and tax-free income strategies
- Social Security optimization
- Situation needs analysis
- 24/7/365 Plan access with auto external data updates.
- Asset allocation review with risk and prob-abilities analysis
- Insurance review
- Plan creation working with a CERTIFIED FINANCIAL PLANNER®(CFP®) professional
### Investment Advisory
- Investment Policy Statement (IPS) construction – based on a formalized plan
- Independent/objective investment and management due-diligence, screening, and selection
- Advisory and oversight services provided by an ACCREDITED INVESTMENT FIDUCIARY® (AIF®).
- Independent and objective third-party reporting
- Secure 24/7 account access
- Institutional management available for selected accounts
---
### [Terms & Conditions](https://indfin.com/terms-conditions/)
**Published:** September 26, 2014
**Author:** Jim Lorenzen
**Content:**
**The following terms and conditions of use (“terms and conditions”) govern your use of, and access to, The Independent Financial Group (IFG) website.** By accessing, using, printing or downloading anything from this Website, you agree to use the Website in accordance with, and be bound by, the terms and conditions stated below. You may use and access this Website only in accordance with such terms and conditions.
**PLEASE READ THE TERMS AND CONDITIONS CAREFULLY.** This Website is made available to all persons who agree to be bound by the terms and conditions set forth herein. If you do not agree with such terms and conditions, you must exit this Website immediately and may not use or access the Website or print or download anything from it. IFG reserves the right to modify or discontinue, temporarily or permanently, all or any portion of this Website with or without notice. You agree that IFG will not be liable to you or to any third party for any such modification, suspension or discontinuance.
**No Offer, Investment Advice or Performance Guarantees.** This Website is for
informational and educational purposes only. Despite the efforts of IFG to provide useful and accurate information, errors may occur. Neither the information nor any opinion expressed on this Website constitutes an offer by IFG to buy or sell any securities or financial instruments, or to provide any investment advice or service, nor should any information or opinion on this Website be construed as legal or investment recommendations or endorsements coming from IFG. In exchange for using this Website, you agree not to hold IFG liable for any possible claim for any damages arising from any decision you make based on such information. Before you act on information you have found on this Website, you should confirm any facts that are important to your decision. You alone will need to evaluate the merits and risks associated with the use of this Website. The services, securities and financial instruments described on this Website may not be available to or suitable for you, and not all strategies are appropriate at all times. The value and income of any of the securities or financial instruments mentioned on this Website can fall as well as rise, and an investor may get back less than he or she invested. Foreign-currency denominated securities and financial instruments are subject to fluctuations in exchange rates that could have a positive or adverse affect on the value, price or income of such securities and financial instruments. Past performance is not necessarily a guide to future performance. Independent advice should be sought in all cases.
**Tax Consequences.** Any investment products and services that may be mentioned on this Website may have tax consequences. It is important to bear in mind that IFG does not provide tax advice. The levels and bases of taxation can change. Your tax affairs are your own responsibility and you should consult your own attorneys or other tax advisors in order to understand the tax consequences of any investment products and services mentioned on this Website.
**Links to Third Party Websites.** This Website may contain links to other third party websites, including links to the websites of companies that provide related information, products and services. IFG does not control such linked websites and is not responsible for the content of them or any link contained within them. These links are solely for the convenience of visitors to this Website, and the inclusion of such links does not necessarily imply an affiliation, sponsorship or endorsement. IFG makes no representations whatsoever
regarding such third party websites. You should review the privacy policies of other websites carefully before providing any information to such websites. IFG is not responsible for the content or availability of third party websites, and shall not be responsible or liable for any information, opinions, advice, products, or services available on or through such third party websites. If you decide to access any of the third party websites linked to this Website, you do so entirely at your own risk.
**Links to this Website.** We ask that you notify us in advance of your intention to link to the public portion of this Website by emailing us at info@indfin.com. You may not (i) display this Website in frames, or (ii) display any of the content found on this Website via inline links, without express written permission from an authorized representative of IFG.
**Trademark and Service Mark Information.** Nothing contained on this Website should be construed as granting, by implication, estoppel, or otherwise, any license or right to use any trademark or service mark displayed on the Website without the written permission of IFG or such third party that may own the trademarks or service marks displayed on this Website. Your use of the trademarks or service marks displayed on this Website, or any other content on the Website, except as provided herein, is strictly prohibited. Images displayed on this Website are either the property of, or used with permission by, IFG. The use of these images by you, or anyone else authorized by you, is prohibited unless specifically permitted under these terms and conditions. Any unauthorized use of the images may violate copyright laws, trademark laws, service mark laws, the laws of privacy and publicity, or other regulations and statutes. No mark of IFG may be used in any manner that is likely to cause confusion among consumers or in any manner disparages, harms or discredits IFG.
**Responsible Behavior.** In addition to the obligations set forth above, you agree not to
access or use this Website to:
1. reproduce, duplicate, copy, sell, trade, resell or exploit for any commercial purposes, any portion of this Website, use of this Website, or access to this Website;
2. impersonate any person or entity or falsely state or otherwise misrepresent your affiliation with a person or entity;
3. forge headers or otherwise manipulate identifiers in order to disguise the origin of any content transmitted on this Website;
4. make available any content that you do not have a right to make available under any law or under contractual or fiduciary relationships;
5. make available any content that infringes any patent, trademark, service mark, trade secret, copyright or other proprietary rights of any party;
6. make available any content that is unlawful, harmful, threatening, tortious, defamatory, obscene, invasive of another’s privacy, or otherwise objectionable;
7. make available any unsolicited or unauthorized advertising, promotional materials, “junk mail,” “spam,” “chain letters,” “pyramid schemes,” or any other form of solicitation;
8. make available any material that contains software viruses or any other computer code, files or programs designed to interrupt, destroy or limit the functionality of any computer software or hardware or telecommunications equipment;
9. interfere with or disrupt this Website or servers or networks connected to this Website, or disobey any requirements, procedures, policies or regulations of networks connected to this Website; or
10. violate any applicable local, state, national or international laws or regulations.
**Disclaimer of Warranties.** YOU EXPRESSLY AGREE THAT USE OF THIS WEBSITE IS AT YOUR OWN AND SOLE RISK. THE WEBSITE IS PROVIDED ON AN “AS IS” And “AS AVAILABLE” BASIS WITHOUT WARRANTY OF ANY KIND, EITHER EXPRESS OR IMPLIED. NEITHER PIA NOR ANY OF IT AFFILIATES OR SUBSIDIARIES MAKES ANY WARRANTY, INCLUDING BUT NOT LIMITED TO, ANY IMPLIED WARRANTIES OF MERCHANTABILITY, FITNESS FOR A PARTICULAR PURPOSE OR USE, TITLE, NON-INFRINGEMENT, ACCURACY, ADEQUACY OR COMPLETENESS OF THE INFORMATION CONTAINED IN THIS WEBSITE. THERE IS NO OTHER WARRANTY OF ANY KIND, EXPRESS OR IMPLIED, REGARDING THIS WEBSITE. IFG MAKES NO REPRESENTATIONS OR WARRANTIES THAT THIS WEBSITE WILL BE UNINTERRUPTED, TIMELY, SECURE, OR ERROR FREE; NOR DOES IFG MAKE ANY REPRESENTATIONS OR WARRANTIES AS TO THE QUALITY, SUITABILITY, TRUTH, ACCURACY OR COMPLETENESS OF THE WEBSITE. IFG MAKES NO COMMITMENT TO UPDATE ANY INFORMATION ON THIS WEBSITE. SOME JURISDICTIONS DO NOT ALLOW THE EXCLUSION OF CERTAIN WARRANTIES, SO SOME OF THE ABOVE EXCLUSIONS MAY NOT APPLY TO YOU.
**Indemnification.** You agree to indemnify, defend and hold harmless IFG, its affiliates, officers, directors, members, managers, employees, consultants, shareholders, independent contractors, parents, subsidiaries, licensors and agents, from and against any and all claims, actions, demands, liability, damages and/or costs (including, but not limited to, reasonable legal and accounting fees), resulting or allegedly resulting from your use of this Website or your breach or threatened breach of any of the terms and conditions described herein, or from your violation of any applicable law, including your infringement or violation of any intellectual property or other right of a third party.
**Limitation of Liability.** YOU UNDERSTAND THAT UNDER NO CIRCUMSTANCES WILL IFG
OR ITS AFFILIATES, OFFICERS, DIRECTORS, MEMBERS, MANAGERS, EMPLOYEES,
CONSULTANTS, SHAREHOLDERS, INDEPENDENT CONTRACTORS, PARENTS, SUBSIDIARIES, LICENSORS AND AGENTS BE LIABLE FOR ANY DAMAGES OF ANY KIND INCLUDING, WITHOUT LIMITATION, DIRECT, CONSEQUENTIAL, INDIRECT, EXEMPLARY, INCIDENTAL, SPECIAL OR PUNITIVE DAMAGES, LOSSES OR EXPENSES, WHETHER IN AN ACTION UNDER CONTRACT, NEGLIGENCE, TORT, STRICT LIABILITY OR ANY OTHER THEORY, ARISING OUT OF YOUR USE OF, OR INABILITY TO USE, ANY PORTION OF THIS WEBSITE, EVEN IF IFG OR ANY RELATED PARTY HAS BEEN ADVISED OF THE POSSIBILITY OF SUCH DAMAGES. YOU UNDERSTAND AND AGREE THAT ANYTHING DOWNLOADED OR OTHERWISE OBTAINED THROUGH THE USE OF THIS WEBSITE IS DONE AT YOUR OWN DISCRETION AND RISK AND THAT YOU WILL BE SOLELY RESPONSIBLE FOR ANY DAMAGE TO YOUR COMPUTER SYSTEM OR LOSS OF DATA THAT RESULTS FROM THE DOWNLOAD OF ANY SUCH MATERIAL AND/OR DATA. SOME JURISDICTIONS DO NOT ALLOW THE EXCLUSION OR LIMITATION OF LIABILITY FOR CONSEQUENTIAL OR INCIDENTAL DAMAGES, SO THE ABOVE LIMITATIONS MAY NOT APPLY TO YOU.
**Applicable Laws.** The validity and enforcement of these terms and conditions and the relationship between you and us relating to your use of this Website shall be governed by, and construed in accordance with, the laws of the state of California, without regard to any conflict of laws provisions that would require the application of the laws of a different jurisdiction. If any part of these terms and conditions is deemed unlawful, void or unenforceable, that part will be deemed severable and will not affect the validity and
enforceability of any remaining provisions. In the event of any dispute between you and IFG in connection with this Website, you agree to submit to the exclusive and personal jurisdiction of the state and federal courts located in Ventura, California for any dispute, claim or action arising out of or related to your use of this Website or these terms and conditions of use, and you hereby waive any objections to the jurisdiction or venue of such courts. IFG makes no representation that this Website is appropriate or available for use in other locations, and forbids access to the Website from locations where the content may be illegal or is otherwise prohibited.
**Assignments.** You may not assign or delegate any right or duty under these terms of use or related to this Website without the prior written consent of an authorized officer of IFG. Any attempted assignment or delegation without such consent will be null and void from the beginning and without further effect. IFG may assign any right or duty under these terms of use or related to this Website with or without notice to you. Subject to the foregoing, these terms of use will be binding upon and will inure to the benefit of you and us, and each of our respective representatives, heirs, administrators, successors and permitted assigns. **Waiver.** No duty or breach of these terms and conditions of use may be waived by any act, omission or knowledge by IFG, except by an instrument in writing expressly waiving the duty or breach and signed by an authorized representative of IFG. Any waiver (express or implied) by us of any duty or breach will no constitute a waiver of any other or subsequent duty or breach.
**Entire Agreement.** These terms of use constitute the entire agreement between you and IFG with regard to your access to and use of this Website, and supersede all prior and contemporaneous negotiations, statements and agreements, whether written or oral, relating to the subject matter hereof, except that, in the case of any IFG client, this Agreement does not supersede any Investment Advisory Agreement or Service Agreement. To the extent the provisions of any Investment Advisory Agreement or Service Agreement conflicts with these terms and conditions of use, the provisions of the Investment Advisory
**Agreement or Service Agreement will control.** In the event any provision of these terms of use is judicially determined to be invalid or unenforceable, such provision will be changed and interpreted t accomplish the objectives of such provision to the greatest extent permitted under applicable law, and the remaining provisions will continue in full force and effect.
---
### [IFG Blog](https://indfin.com/jims-blog/)
**Published:** September 8, 2014
**Author:** Jim Lorenzen
**Content:**
Trouble viewing this page? [Click here](https://www.jimsmoneyblog.com/).
---
## Categories
### [Uncategorized](https://indfin.com/category/uncategorized/)
**Description:** Uncategorized Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [IFG Viewpoint & Outlook](https://indfin.com/category/ifg-viewpoint-outlook/)
**Description:** IFG Viewpoint & Outlook Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Family Issues](https://indfin.com/category/family-issues/)
**Description:** Family Issues Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Life Insurance](https://indfin.com/category/life-insurance/)
**Description:** Life Insurance Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Estate](https://indfin.com/category/estate/)
**Description:** Estate Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Retirement](https://indfin.com/category/retirement/)
**Description:** Retirement Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Business Owners](https://indfin.com/category/business-owners/)
**Description:** Business Owners Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Taxes](https://indfin.com/category/taxes/)
**Description:** Taxes Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Planning](https://indfin.com/category/planning/)
**Description:** Planning Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Investing](https://indfin.com/category/investing/)
**Description:** Investing Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Executive Compensation](https://indfin.com/category/executive-compensation/)
**Description:** Executive Compensation Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Economy](https://indfin.com/category/economy/)
**Description:** Economy Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Inflation](https://indfin.com/category/inflation/)
**Description:** Inflation Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Annuities](https://indfin.com/category/annuities/)
**Description:** Annuities Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Charitable Giving](https://indfin.com/category/charitable-giving/)
**Description:** Charitable Giving Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Special needs](https://indfin.com/category/special-needs/)
**Description:** Special needs Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Business Succession](https://indfin.com/category/business-owners/business-succession/)
**Description:** Business Succession Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Health](https://indfin.com/category/health/)
**Description:** Health Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [SECURE Act](https://indfin.com/category/secure-act/)
**Description:** SECURE Act Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Roth conversions](https://indfin.com/category/roth-conversions/)
**Description:** Roth conversions Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Medicare](https://indfin.com/category/medicare/)
**Description:** Medicare Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [IRAs](https://indfin.com/category/retirement/iras/)
**Description:** IRAs Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Rollovers](https://indfin.com/category/retirement/rollovers/)
**Description:** Rollovers Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Social Security](https://indfin.com/category/retirement/social-security/)
**Description:** Social Security Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Inheritance](https://indfin.com/category/planning/inheritance/)
**Description:** Inheritance Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Retirement Income](https://indfin.com/category/retirement/retirement-income/)
**Description:** Retirement Income Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [Annuities](https://indfin.com/category/retirement/annuities-retirement/)
**Description:** Annuities Retirement Planning and Wealth Management Solutions https://indfin.com/
---
### [AI - Artificial Intelligence](https://indfin.com/category/ai-artificial-intelligence/)
**Description:** AI - Artificial Intelligence Retirement Planning and Wealth Management Solutions https://indfin.com/
---
## Tags
### [Retirement Planning](https://indfin.com/tag/retirement-planning/)
**Description:** Articles about planning for retirement and the planning process.
---
### [Retirement Income](https://indfin.com/tag/retirement-income/)
**Description:** Articles about producing income in retirement
---
### [Retirement Strategy](https://indfin.com/tag/retirement-strategy/)
**Description:** Articles about creating a sound retirement strategy
---
### [Guaranteed Income](https://indfin.com/tag/guaranteed-income/)
**Description:** Articles about guaranteed income strategies
---
### [Retirement Annuities](https://indfin.com/tag/retirement-annuities/)
**Description:** Articles about using annuities for retirement or as retirement supplements.
---
### [Income Annuities](https://indfin.com/tag/income-annuities/)
**Description:** Articles about immediate and deferred income annuities.
---
### [Tax-Free Retirement Income](https://indfin.com/tag/tax-free-retirement-income/)
**Description:** Articles about creating a tax-free income during retirement.
---
### [Inheritance](https://indfin.com/tag/inheritance/)
**Description:** Articles about inheritance issues.
---
### [Investment Strategy](https://indfin.com/tag/investment-strategy/)
**Description:** Portfolio management, asset allocation, and investment strategy articles.
---
### [Financial Security](https://indfin.com/tag/financial-security/)
**Description:** Articles about achieving financial security
---
### [Reducing Risk](https://indfin.com/tag/reducing-risk/)
**Description:** Articles about risk reduction and mitigation
---
### [Safe Money](https://indfin.com/tag/safe-money/)
**Description:** Articles about money that must be kept liquid and safe
---
### [IRAs](https://indfin.com/tag/ira/)
**Description:** Articles about IRAs and IRA strategies
---
### [Inflation](https://indfin.com/tag/inflation/)
---
### [Interest rates](https://indfin.com/tag/interest-rates/)
---
### [Rising income](https://indfin.com/tag/rising-income/)
---
### [Liquidity and Safety](https://indfin.com/tag/liquidity-and-safety/)
---
### [Required Minimum Distributions](https://indfin.com/tag/required-minimum-distributions/)
---
### [RMDs](https://indfin.com/tag/rmds/)
---
### [Taxes in retirement](https://indfin.com/tag/taxes-in-retirement/)
---
### [diversification](https://indfin.com/tag/diversification/)
---
### [rollover mistakes](https://indfin.com/tag/rollover-mistakes/)
---
### [retirement mistakes](https://indfin.com/tag/retirement-mistakes/)
---
### [pension decisions](https://indfin.com/tag/pension-decisions/)
---
### [pension options](https://indfin.com/tag/pension-options/)
---
### [retirement decisions](https://indfin.com/tag/retirement-decisions/)
---
### [IRA rollover](https://indfin.com/tag/ira-rollover/)
---
### [company plan rollover](https://indfin.com/tag/company-plan-rollover/)
---
### [Retirement tax strategies](https://indfin.com/tag/retirement-tax-strategies/)
---
### [Annuity](https://indfin.com/tag/annuity/)
---
### [Annuity income](https://indfin.com/tag/annuity-income/)
---
### [401(k) planning](https://indfin.com/tag/401k-planning/)
---
### [401k decisions](https://indfin.com/tag/401k-decisions/)
---
### [managing inheritance](https://indfin.com/tag/managing-inheritance/)
---
### [managing a windfall](https://indfin.com/tag/managing-a-windfall/)
---
### [Tax reduction](https://indfin.com/tag/tax-reduction/)
---
### [retirement webinar](https://indfin.com/tag/retirement-webinar/)
---
### [investment returns](https://indfin.com/tag/investment-returns/)
---
### [understanding investment returns](https://indfin.com/tag/understanding-investment-returns/)
---
### [Investment mistakes](https://indfin.com/tag/investment-mistakes/)
---
### [Home care](https://indfin.com/tag/home-care/)
---
### [Resoures for home care](https://indfin.com/tag/resoures-for-home-care/)
---
### [Tips about home care](https://indfin.com/tag/tips-about-home-care/)
---
### [Resources for helping an aging parent](https://indfin.com/tag/resources-for-helping-an-aging-parent/)
---
### [Executive Benefits](https://indfin.com/tag/executive-benefits/)
---
### [Executive Bonus](https://indfin.com/tag/executive-bonus/)
---
### [Bonus plans](https://indfin.com/tag/bonus-plans/)
---
### [electoral college](https://indfin.com/tag/electoral-college/)
---
### [Thanksgiving](https://indfin.com/tag/thanksgiving/)
---
### [business value](https://indfin.com/tag/business-value/)
---
### [business decisions](https://indfin.com/tag/business-decisions/)
---
### [business owners](https://indfin.com/tag/business-owners/)
---
### [Selling your business](https://indfin.com/tag/selling-your-business/)
---
### [selling closely-held business](https://indfin.com/tag/selling-closely-held-business/)
---
### [business owners retirement](https://indfin.com/tag/business-owners-retirement/)
---
### [secure retirement](https://indfin.com/tag/secure-retirement/)
---
### [life insurance](https://indfin.com/tag/life-insurance/)
---
### [life insurance decsions](https://indfin.com/tag/life-insurance-decsions/)
---
### [term insurance vs permanent](https://indfin.com/tag/term-insurance-vs-permanent/)
---
### [calculating returns](https://indfin.com/tag/calculating-returns/)
---
### [managing risk](https://indfin.com/tag/managing-risk/)
---
### [management](https://indfin.com/tag/management/)
---
### [business owner tax planning](https://indfin.com/tag/business-owner-tax-planning/)
---
### [Financial planning](https://indfin.com/tag/financial-planning/)
---
### [Estate Planning](https://indfin.com/tag/estate-planning/)
---
### [term insurance](https://indfin.com/tag/term-insurance/)
---
### [investment planning](https://indfin.com/tag/investment-planning/)
---
### [health care](https://indfin.com/tag/health-care/)
---
### [health care for all](https://indfin.com/tag/health-care-for-all/)
---
### [Medicare planning](https://indfin.com/tag/medicare-planning/)
---
### [Medicare surprises](https://indfin.com/tag/medicare-surprises/)
---
### [charitable giving](https://indfin.com/tag/charitable-giving/)
---
### [wealth replacement](https://indfin.com/tag/wealth-replacement/)
---
### [trusts](https://indfin.com/tag/trusts/)
---
### [SECURE Act](https://indfin.com/tag/secure-act/)
---
### [Coronavirus](https://indfin.com/tag/coronavirus/)
---
### [social security](https://indfin.com/tag/social-security/)
---
### [Roth IRA](https://indfin.com/tag/roth-ira/)
---
### [Roth conversions](https://indfin.com/tag/roth-conversions/)
---
### [death planning](https://indfin.com/tag/death-planning/)
---
### [End of ife](https://indfin.com/tag/end-of-ife/)
---
### [ira beneficiaries](https://indfin.com/tag/ira-beneficiaries/)
---
### [taxes](https://indfin.com/tag/taxes/)
---
### [higher taxes](https://indfin.com/tag/higher-taxes/)
---
### [tax hikes](https://indfin.com/tag/tax-hikes/)
---
### [tax law changes](https://indfin.com/tag/tax-law-changes/)
---
### [social security claiming](https://indfin.com/tag/social-security-claiming/)
---
### [when to claim social security](https://indfin.com/tag/when-to-claim-social-security/)
---
### [social security help](https://indfin.com/tag/social-security-help/)
---
### [making money last](https://indfin.com/tag/making-money-last/)
---
### [managing retirement savings](https://indfin.com/tag/managing-retirement-savings/)
---
### [social security outlook](https://indfin.com/tag/social-security-outlook/)
---
### [college planning](https://indfin.com/tag/college-planning/)
---
### [ira rollovers](https://indfin.com/tag/ira-rollovers/)
---
### [401(k) rollovers](https://indfin.com/tag/401k-rollovers/)
---
### [Banking Crisis](https://indfin.com/tag/banking-crisis/)
---
### [financial risk](https://indfin.com/tag/financial-risk/)
---
### [annuity review](https://indfin.com/tag/annuity-review/)
---
### [tax management](https://indfin.com/tag/tax-management/)
---
### [Will Social Security be there for me](https://indfin.com/tag/will-social-security-be-there-for-me/)
---
### [longevity](https://indfin.com/tag/longevity/)
---
### [tax planning](https://indfin.com/tag/tax-planning/)
---
### [Tariffs](https://indfin.com/tag/tariffs/)
---
### [Trade wars](https://indfin.com/tag/trade-wars/)
---
### [economy](https://indfin.com/tag/economy/)
---
### [special needs](https://indfin.com/tag/special-needs/)
---
### [special needs trusts](https://indfin.com/tag/special-needs-trusts/)
---
### [cognitive decline](https://indfin.com/tag/cognitive-decline/)
---
### [Alzheimers](https://indfin.com/tag/alzheimers/)
---
### [Dementia](https://indfin.com/tag/dementia/)
---
### [generational planning](https://indfin.com/tag/generational-planning/)
---
### [AI](https://indfin.com/tag/ai/)
---
### [Medicare](https://indfin.com/tag/medicare/)
---
### [tax traps](https://indfin.com/tag/tax-traps/)
---
### [spousal ira](https://indfin.com/tag/spousal-ira/)
---
### [investment decisions](https://indfin.com/tag/investment-decisions/)
---